
 Europe Ski Gear and Equipment Market | 2026-2036
Europe Ski Gear and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ski Gear and Equipment Market Foresight
Smart-mold shell construction with integrated gaiter systems is reconfiguring how alpine boots achieve precision fit without traditional overlap designs. Fischer Sports GmbH leverages its Austrian manufacturing base to sustain vertical integration across binding-to-boot systems. Decathlon S.A. anchors its European market presence through controlled private-label distribution spanning rental partnerships and direct retail. Amer Sports, Inc. competes across multiple price tiers through distinct brand architectures that separate performance from entry-level positioning.
Europe ski gear and equipment encompasses technical alpine apparatus engineered to ISO 9465 ski-binding release standards and EN 1077 helmet impact specifications, with carbon-reinforced polymer laminates and titanal sandwich constructions defining performance-tier product architecture. The primary commercial purpose centers on delivering controlled descent capability across variable snow conditions while managing kinetic energy transfer and protecting against torsional injury. Ski boots and skis together occupy the dominant margin pool as these categories command the highest replacement frequency and technical upgrade cycles among recreational users. Specialty stores and online retail channels are diverging in function, with brick-and-mortar locations concentrating on boot fitting services while digital platforms capture standardized hardware transactions.
CE marking under the EU Personal Protective Equipment Regulation and REACH chemical compliance through ECHA govern material composition and safety certification for equipment sold across member states. The EU Green Deal and F-Gas Regulation are reshaping manufacturing inputs by restricting fluorinated wax compounds and mandating recycled content thresholds in base materials. Stakeholders must monitor how France's ANSM and Germany's KBA extend product safety frameworks into environmental performance standards that will determine market access for non-compliant suppliers.
Market Dynamics
The EU Green Deal and F-Gas Regulation are forcing manufacturers to abandon fluorinated wax compounds and retool production lines for bio-based composites, reshaping competitive positioning across Alpine supply chains. Recreational skiers in France, Austria, and Switzerland now demand circular-certified equipment, pressuring incumbents to absorb compliance costs while defending margin structures.
Growth Catalysts
- REACH chemical compliance:Mandatory ECHA registration for base material formulations creates barrier-to-entry advantages for established European compounders with dedicated regulatory affairs teams.
- Resort infrastructure investment:French and Swiss Alpine municipalities are expanding snowmaking capacity and lift systems, directly stimulating replacement demand for performance-tier ski boots and bindings.
- Carbon-reinforced polymer laminates:Advanced composite manufacturing is reducing shell weight while maintaining torsional rigidity, enabling technical upgrades among weight-conscious recreational users.
Market Restraints
- Titanal supply concentration:Austrian and German smelters control premium aluminum-titanium alloy output, exposing boot and ski manufacturers to input cost volatility and allocation risk during peak production seasons.
- CE marking complexity:Evolving EU Personal Protective Equipment Regulation interpretation by France's ANSM extends certification timelines for new helmet designs, compressing product launch windows.
- Climate-induced season compression:Shorter reliable snow periods in lower-elevation Alpine zones are reducing rental fleet utilization rates and deferring consumer purchase decisions.
Strategic Opportunities
- Eastern European market development:Poland and Czech Republic ski participation rates trail Western Alpine averages by significant margins, presenting white-space expansion for entry-to-mid tier equipment distribution.
- Binding-to-boot system integration:Convergence of release-mechanism electronics with pressure-mapping insoles enables premium pricing for coordinated safety systems among technical skiers.
- EU circular economy action plan:Mandated recycled content thresholds in base materials favor manufacturers with established polymer recovery partnerships and closed-loop production capabilities.
Industry Challenges
- Master boot-fitter talent scarcity:Technical fitting expertise required for precision shell molding is concentrating among aging specialists in Austria and France, constraining specialty retail service capacity expansion.
- Legacy binding inventory reconciliation:ISO 9465 standard revisions force simultaneous engineering redesign and channel clearance of prior-generation release mechanisms, complicating working capital management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ski Gear and Equipment Market |
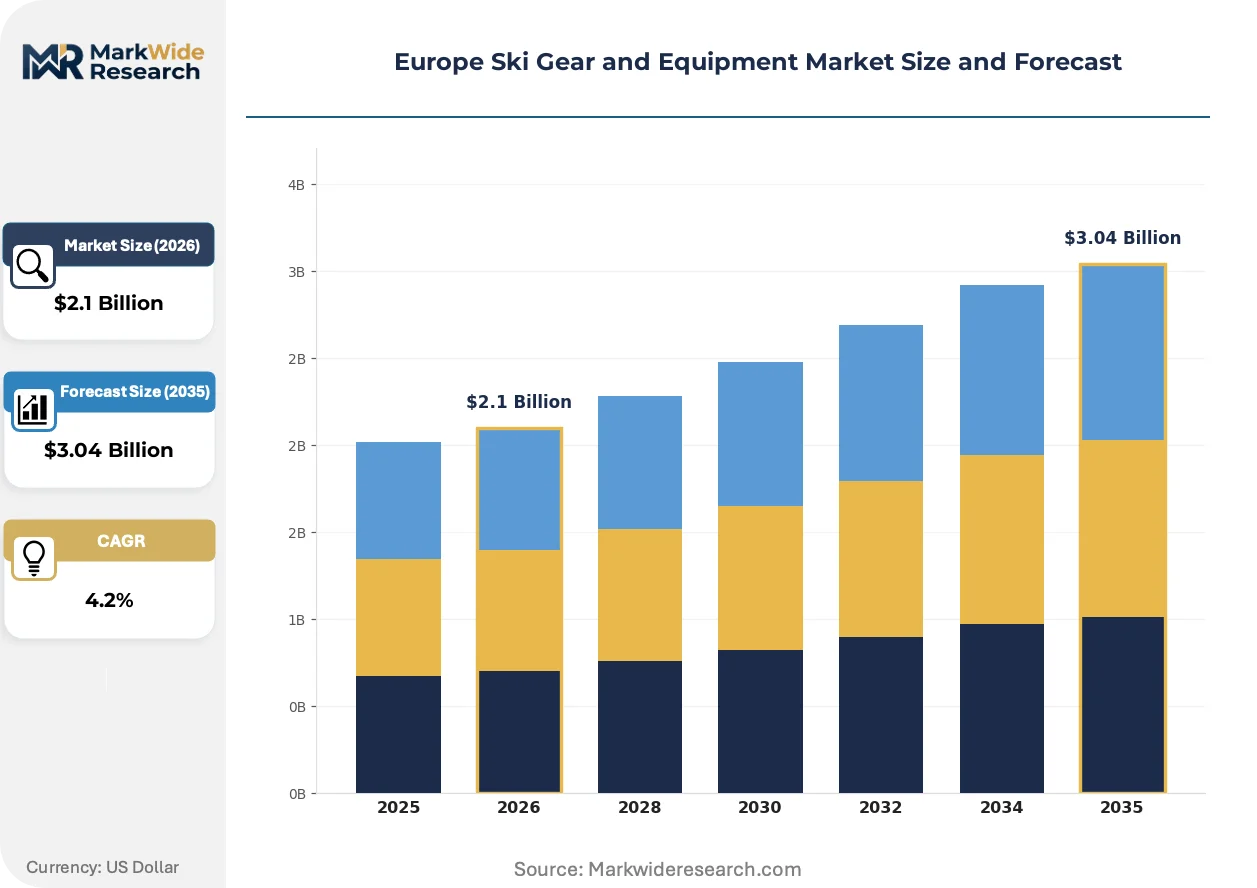
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ski Boots, Ski Poles, Skis, Snowboards End User: Recreational Skiers, Professional Athletes, Ski Instructors, Beginners Distribution Channel: Online Retail, Specialty Stores, Department Stores, Rental Shops Price Tier: Premium, Mid-Range, Budget, Discounts |
| Companies Covered | Head Sport GmbH, Marker Dalbello Volkl GmbH, Fischer Sports GmbH, Scott Sports SA, UVEX Group, Skis Rossignol S.A., Amer Sports, Inc., Decathlon S.A., Tecnica Group S.p.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ski Gear and Equipment Market Shifts & Advancements
Equipment architecture is hybridizing across material science, digital integration, and circular design principles. Manufacturers now compete on integrated system performance rather than isolated component specifications.
Smart-mold shell construction with integrated gaiter systems is hybridizing traditional overlap and three-piece boot architectures into unified precision-fit platforms. Performance-tier recreational skiers in Austria and Switzerland are adopting these configurations at accelerated replacement cycles. The technology is compressing aftermarket customization demand while elevating factory-direct specification importance.
F-Gas Regulation prohibitions on perfluorinated compounds are forcing base material suppliers to reformulate glide coatings around hydrocarbon and plant-derived alternatives. German chemical compounders are scaling bio-wax production capacity ahead of 2025 enforcement deadlines. Race-oriented ski segments face the steepest performance transition costs as fluorinated wax historically dominated FIS-compliant competition standards.
Rental fleet procurement is consolidating around multi-season durability specifications and digital inventory tracking systems. French resort operators are displacing single-season hardware commitments with five-year total-cost-of-ownership contracts. This behavioral shift is most visible in Les Trois Vallées and Portes du Soleil clusters, where centralized purchasing now favors suppliers with integrated binding-boot service networks.
Europe Ski Gear and Equipment Market Segmentation
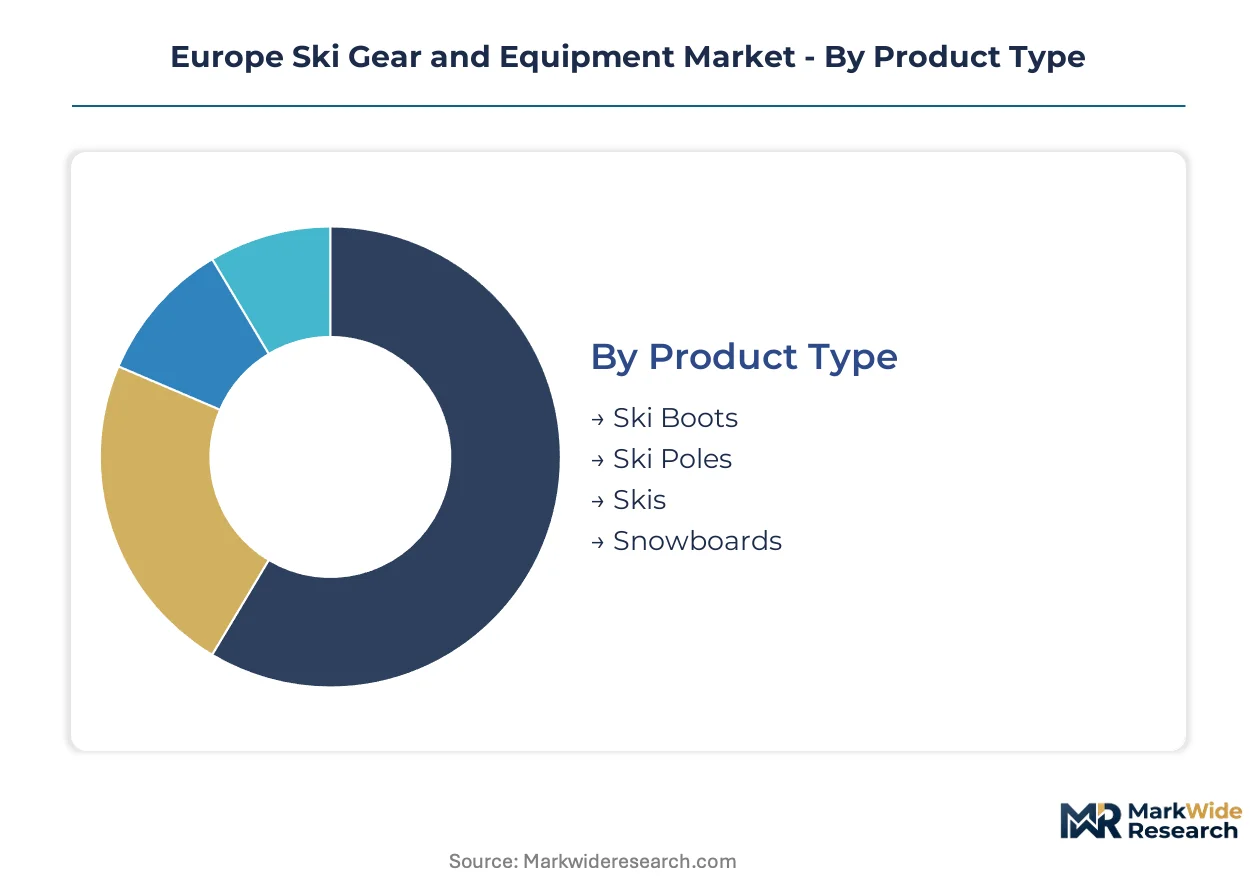
Equipment architecture varies sharply across user sophistication and purchase context. Segmentation reveals how technical specifications, distribution access, and price positioning fragment demand across Alpine markets.
Product Type:
Recreational skiers in France, Austria, and Switzerland select equipment based on descent control requirements and snow condition variability.
- Ski Boots:Precision-molded shells with integrated gaiter systems dominate technical specifications. French and Austrian specialty retailers concentrate fitting services around these high-margin items, where replacement cycles compress with smart-mold adoption.
- Skis:Carbon-reinforced polymer laminates and titanal sandwich constructions define performance-tier architecture. Demand clusters among weight-conscious recreational users in Swiss Alpine zones seeking technical upgrades without torsional rigidity loss.
- Ski Poles:Lightweight aluminum and carbon fiber shafts serve balance and propulsion functions across all skill tiers.
- Snowboards:Directional and twin-tip geometries capture freestyle and freeride disciplines, with softer flex patterns dominating beginner rental fleets.
The dominant share belongs to Ski Boots, while Skis is closing the gap fastest.
End User:
Skill-based segmentation determines equipment complexity and service intensity requirements.
- Recreational Skiers:Performance-tier users in Alpine destinations drive replacement demand through accelerated upgrade cycles and circular-certified equipment preferences.
- Professional Athletes:FIS-compliant race segments face steepest fluorinated wax transition costs under F-Gas Regulation enforcement.
- Ski Instructors:Multi-season durability specifications dominate procurement, with five-year total-cost-of-ownership contracts displacing single-season commitments.
- Beginners:Rental fleet utilization concentrates demand in Les Trois Vallées and Portes du Soleil clusters, where centralized purchasing favors integrated binding-boot service networks.
Recreational Skiers commands the largest participant base, though Beginners is expanding most quickly through resort infrastructure investment.
Distribution Channel:
Channel function is diverging between technical service delivery and transactional efficiency.
- Specialty Stores:Master boot-fitter expertise in Austria and France constrains service capacity expansion while defending margin structures through precision fitting.
- Online Retail:Standardized hardware transactions capture skis and poles where sizing complexity remains low.
- Department Stores:Entry-to-mid tier equipment reaches casual participants through seasonal merchandise rotations.
- Rental Shops:Digital inventory tracking systems and multi-season durability specifications reshape procurement in French resort municipalities expanding snowmaking capacity.
Specialty Stores retains the highest value per transaction, yet Online Retail is gaining share fastest among replacement purchases.
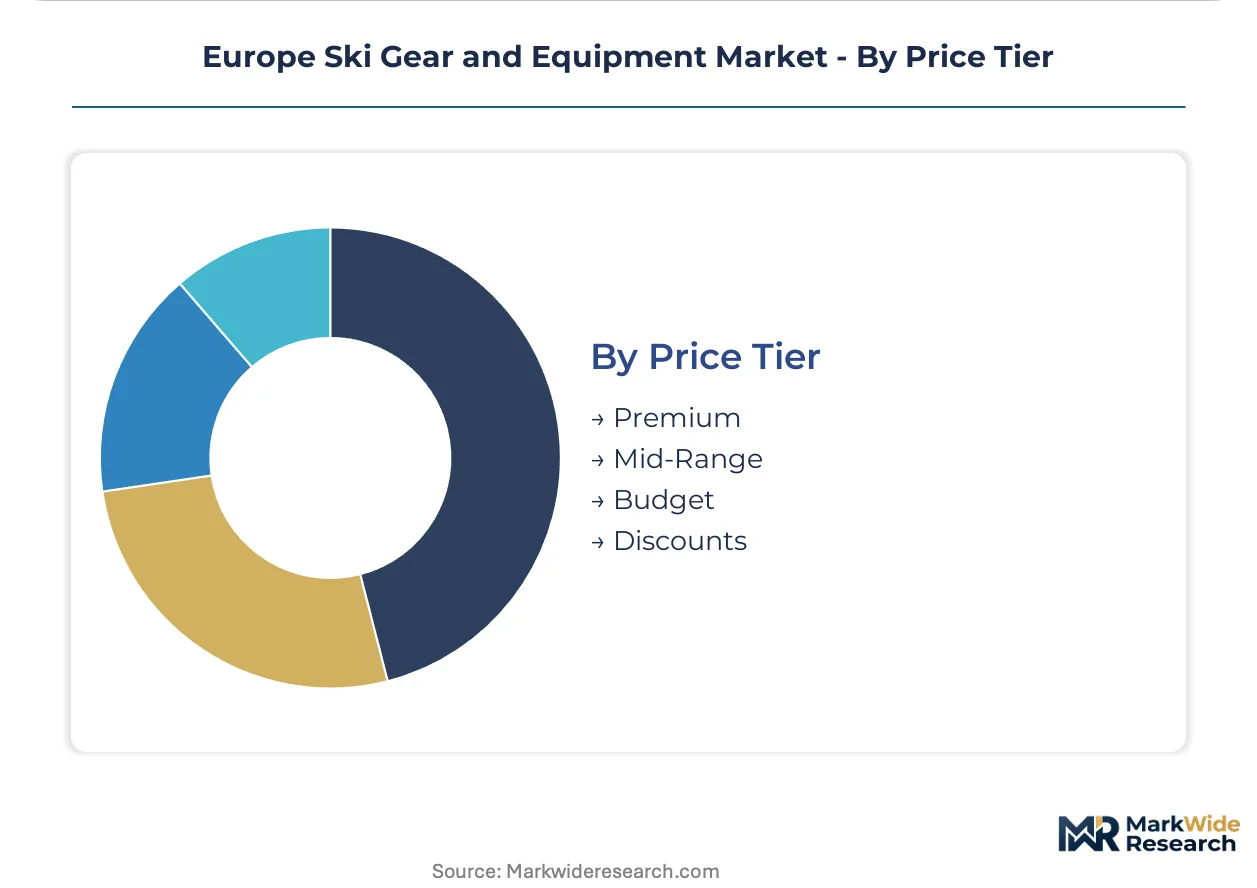
Price Tier:
Cost stratification aligns with technical certification tiers and material input quality.
- Premium:CE marking under EU Personal Protective Equipment Regulation and REACH compliance through ECHA govern safety certification, with bio-based composites and recycled content thresholds elevating input costs.
- Mid-Range:Carbon-reinforced polymer laminates penetrate this tier as manufacturing scale reduces composite cost premiums.
- Budget:Hydrocarbon and plant-derived wax alternatives displace fluorinated compounds ahead of regulatory deadlines.
- Discounts:Legacy binding inventory clearance accelerates through channel partnerships as ISO 9465 standard revisions force engineering redesign.
Premium captures the dominant margin pool, while Mid-Range shows the steepest expansion trajectory as technical features cascade downward.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alpine manufacturing clusters dominate European ski gear production, with specialized component suppliers concentrated in Austria and Switzerland balancing equipment imports from Asian polymer fabricators. France and Germany anchor downstream distribution through resort-adjacent retail networks and digital fulfillment hubs.
France
Resort infrastructure investment in Les Trois Vallées and Portes du Soleil clusters is accelerating rental fleet procurement cycles for integrated binding-boot systems. ANSM enforcement of EU Personal Protective Equipment Regulation extends certification timelines for helmet designs entering the French market. Auvergne-Rhône-Alpes municipalities are expanding snowmaking capacity, directly stimulating replacement demand for performance-tier equipment.
Austria
Master boot-fitter expertise concentrates among aging specialists in Tyrol and Salzburg, constraining specialty retail service capacity expansion. REACH chemical compliance through ECHA governs base material formulations for Austrian compounders with dedicated regulatory affairs teams. Fischer Sports GmbH leverages its domestic manufacturing base to sustain in-house production across binding-to-boot systems.
Switzerland
Weight-conscious recreational users in Swiss Alpine zones are adopting carbon-reinforced polymer laminates for technical upgrades without torsional rigidity loss. Swissmedic coordinates with EU regulators on CE marking alignment for protective equipment crossing into member states. Zurich and Geneva serve as logistics hubs for premium-tier distribution across Western Alpine markets.
Germany
German chemical compounders are scaling bio-wax production capacity ahead of F-Gas Regulation enforcement deadlines for fluorinated compound prohibitions. KBA interpretation of safety frameworks extends into environmental performance standards determining market access. Bavarian and Baden-Württemberg industrial zones host precision molding operations for shell construction components.
Italy
Multi-season durability specifications are displacing single-season hardware commitments among Italian resort operators in Dolomiti Superski and Via Lattea clusters. EU Green Deal recycled content thresholds favor manufacturers with established polymer recovery partnerships in Northern Italy. Tecnica Group S.p.A. anchors domestic production of precision-molded boot architectures for export across Alpine markets.
Europe Ski Gear and Equipment Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated specialists with captive control over critical alloy and composite inputs. Tiered competitive dynamics separate premium performance architects from mid-range volume fabricators and private-label distributors. Strategic archetypes include Austrian-German integrated system builders, French multi-brand portfolio holders, and mass-market sporting goods retailers. Dominant competitive moves encompass binding-to-boot technology convergence and circular production certification acquisition.
Among Austrian-German integrated specialists, Head Sport GmbH, Marker Dalbello Volkl GmbH, and Fischer Sports GmbH exemplify the vertically integrated archetype with in-house production spanning alloy sourcing to finished equipment assembly. These GmbH-structured entities occupy positions where titanal supply relationships and ISO 9465 certification capabilities create defensive moats. Decathlon S.A. represents the mass-market distribution archetype, anchoring European presence through controlled private-label networks. Amer Sports, Inc. sits within the multi-brand portfolio tier, competing across price segments through distinct brand architectures that separate performance from entry-level positioning.
| Leading Market Players |
|---|
| Head Sport GmbH |
| Marker Dalbello Volkl GmbH |
| Fischer Sports GmbH |
| Scott Sports SA |
| UVEX Group |
| Skis Rossignol S.A. |
| Amer Sports, Inc. |
| Decathlon S.A. |
| Tecnica Group S.p.A. |
| Others |
Supply & Pricing Matrix
Titanal supply concentration among Austrian and German smelters determines both pricing tier spreads and supply chain shape across European ski gear manufacturing. This alloy dependency compresses margin structures for boot and ski producers while forcing geographic clustering of premium-tier assembly operations around Alpine metalworking zones.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across premium and mid-range equipment tiers. Price differentiation rests on CE certification grade and carbon-reinforced polymer laminate quality, with REACH-compliant bio-based composites commanding material premiums. Cost compression in budget tiers is intensifying because F-Gas Regulation compliance forces hydrocarbon wax reformulation. Rental fleet operators show highest price sensitivity due to five-year total-cost-of-ownership procurement models, while technical recreational skiers in Swiss Alpine zones demonstrate lowest sensitivity to factory-direct smart-mold specifications.
Supply Chain Analysis
Contract manufacturing capacity concentrates among Austrian vertically integrated specialists and Northern Italian polymer fabricators serving precision-molded shell production. Raw material flows draw from German chemical compounders for bio-wax formulations, Austrian titanal smelters for aluminum-titanium alloys, and Asian carbon fiber weavers for reinforced laminates. Single-source vulnerability runs through titanal allocation during peak production seasons. Distribution feeds from Tyrol and Salzburg manufacturing clusters through French resort-adjacent specialty retail networks and Zurich-Geneva logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master boot-fitter expertise scarcity in aging Austrian and French specialist pools constrains service capacity expansion across Alpine retail networks. This capability gap rewards incumbents who lock in technical talent while exposing new entrants to quality-control risks in precision fitting.
For Market Incumbents: Insulate margin structures by securing captive titanal supply agreements with Austrian smelters ahead of allocation bottlenecks. Deepen backward integration into bio-based composite formulation to deflect F-Gas Regulation compliance cost shocks. Priority investment targets smart-mold manufacturing scale-up in Tyrol to compress replacement cycle capture. For New Entrants and Emerging Players: Establish a beachhead in Polish and Czech Republic distribution white-space where ski participation rates trail Western Alpine benchmarks. Target entry-to-mid tier equipment through digital-first rental fleet partnerships bypassing specialty retail service constraints. Go-to-market angle emphasizes multi-season durability specifications aligned with centralized French resort procurement. For Investors and Strategic Acquirers: F-Gas Regulation enforcement milestones reshape the acquisition landscape toward bio-wax compounders and circular-certified polymer recovery specialists. Five-to-ten year viability favors manufacturers with closed-loop production capabilities and ECHA-registered formulation portfolios. Signal to watch is ANSM extension of CE marking timelines into environmental performance standards that will filter non-compliant suppliers from French market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanal Supply | Austrian smelter relationships secure alloy allocation priority during peak production seasons. |
| Bio-Based Composite Manufacturing Scale-Up | German chemical compounder partnerships position ahead of F-Gas Regulation wax prohibitions. |
| Smart-Mold Shell Technology Acquisition | Precision-fit platforms compress aftermarket customization demand among technical recreational skiers. |
| Circular Certification Program Implementation | EU Green Deal recycled content thresholds favor polymer recovery partnership integration. |
| Eastern European Distribution Expansion | Poland and Czech Republic white-space access bypasses saturated French-Austrian-Swiss retail clusters. |
Research Methodology
Initial hypotheses were tested against primary input from ski manufacturing executives, specialty retail buyers, resort procurement managers, and master boot-fitter specialists and refined through secondary validation. Stakeholder interviews combined with customs trade data, ECHA chemical registration databases, EU Green Deal policy filings, and SEC disclosures from listed sporting goods conglomerates. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled encompass product type, end-user sophistication tier, distribution channel function, and price-positioning band. CAGRs derived from replacement cycle velocity analysis, regulatory compliance cost absorption rates, and resort infrastructure investment flow-through effects. Industry-specific forecast inputs included snowmaking capacity expansion timelines and ISO 9465 standard revision implementation schedules.
Stress conditions across titanal price volatility, F-Gas Regulation enforcement timing, and climate-induced season compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Alpine resort investment continuity and REACH chemical compliance trajectory. Quarterly review of ANSM certification timeline extensions and Austrian smelter allocation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Tennis Pole Market
Sports Equipment
Boxing Gear Market
Sports Equipment
UAE Horse Riding Equipment Market
Sports Equipment
Global Weighted Hula Hoop Market
Sports Equipment
Archery Equipment Market
Sports Equipment
Backboard Market
Sports Equipment
Gym Rubber Flooring Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Cycling Helmet Market
Sports Equipment
Golf Shoes Market
Sports Equipment
Squash Equipment Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
Football Equipment Market
Sports Equipment
Fresh Water Rowing Boats Market
Sports Equipment
Winter Sporting Goods Market