
 Curling Equipment Market | 2026-2036
Curling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Curling Equipment Market Outlook
Scottish granite quarries is restructuring output schedules to balance heritage extraction against modern volume needs. Kays of Scotland leverages centuries-old Ailsa Craig granite access to sustain premium stone positioning. Hardline Curling competes through carbon fiber broom technology leadership. Goldline Curling Supplies Ltd anchors North American distribution through direct club partnerships.
Curling equipment encompasses stones, brooms, footwear, and target mats engineered to precise weight, balance, and friction specifications for ice sheet competition. Granite stones require 38-44 pound mass tolerance and running band curvature within 3 millimeters for championship play. The product type dimension shows curling stones commanding the highest value per unit while brooms generate recurring replacement revenue from competitive wear. Material segmentation reveals composite broom heads displacing traditional hair blends among professional teams seeking reduced stone surface abrasion.
Health Canada and the country's national sports safety regulator oversee equipment standards for participant protection in organized play. ISO standards for sporting goods durability apply to international championship certification requirements. Forward-looking stakeholders must monitor synthetic material regulations and ice facility energy efficiency mandates as these forces reshape procurement criteria and product specifications.
Market Dynamics
Synthetic brush head technology is compressing replacement cycles while heritage granite extraction constraints concentrate premium stone supply in Scotland. Municipal rink expansion across Canada sustains baseline equipment procurement volume.
Growth Catalysts
- Club-level program expansion:Municipal rink investments across Canada drive systematic equipment procurement as membership rolls expand at community facilities.
- Composite material innovation:Carbon fiber broom technology reduces stone surface abrasion and extends playing surface life, lowering total facility maintenance cost.
- REACH compliance alignment:European chemical safety standards for sporting goods materials open certification pathways for synthetic brush head exports into EU member states.
Market Restraints
- Ailsa Craig granite depletion risk:Single-source heritage quarry concentration creates supply vulnerability for championship-grade stone production.
- Ice facility energy cost volatility:Natural gas and electricity price swings compress municipal rink operating budgets and delay equipment refresh cycles.
- ISO durability certification timelines:Extended testing protocols for international championship approval slow new product market entry.
Strategic Opportunities
- Synthetic surface adoption:Artificial ice sheet technology creates equipment demand in non-traditional climates where natural ice formation is unreliable.
- Health Canada safety framework expansion:Updated participant protection standards mandate equipment upgrades across registered provincial leagues.
- Direct-to-club digital distribution:Bypassing traditional retail channels captures margin and accelerates replacement part fulfillment timelines.
Industry Challenges
- Granite craftsperson pipeline:Master stone finishing expertise concentrates among aging Scottish artisans with limited apprenticeship program scale.
- Multi-standard compliance complexity:Simultaneous Health Canada, ISO, and national federation certification requirements fragment testing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Curling Equipment Market |
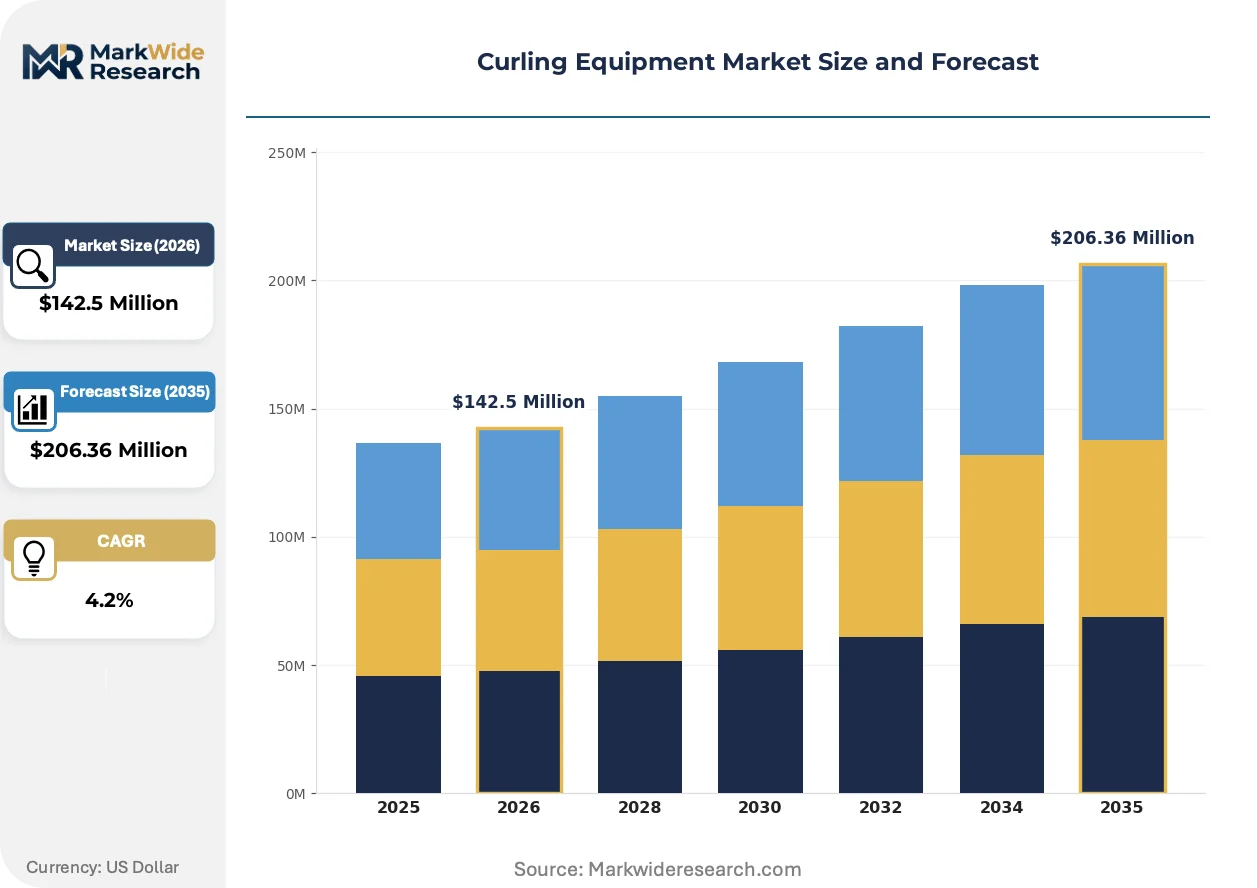
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $206.36 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Curling Stones, Brooms, Shoes, Target Mats Material: Granite, Composite, Plastic, Wood End User: Professional Teams, Recreational Players, Schools, Clubs Distribution Channel: Online Retail, Specialty Stores, Sports Outlets, Direct Sales |
| Companies Covered | Hardline Curling, Canada Curling Stone Co, Goldline Curling Supplies Ltd, Performance Brush Co, Olson Curling, Balance Plus, Kays of Scotland, Shooters Curling Supply, Asham Curling Supplies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Curling Equipment Market Strategic Shifts
Equipment specification convergence between recreational and competitive tiers is compressing product line differentiation. Manufacturers face pressure to unify production runs while preserving performance tier signaling.
Carbon fiber composite broom shafts are integrating with precision-molded brush heads to reduce weight variance below 15 grams across production batches. Competitive teams in Scotland and Canada adopt these configurations fastest, forcing mid-tier suppliers to match specification tolerance or exit championship certification markets. The technology is integrating formerly separate component supply chains into unified manufacturing cells.
Health Canada's updated sporting goods safety framework mandates impact resistance testing for brush handles and stone collision scenarios. Equipment distributors must now maintain third-party laboratory relationships and documentation systems. Club procurement committees in Ontario and Alberta prioritize Health Canada-compliant suppliers in competitive bidding processes.
After-sales service unbundling is separating stone reconditioning, running band refurbishment, and handle replacement into discrete purchase decisions. Curling clubs in Scotland negotiate component-level contracts rather than full equipment packages. This pattern concentrates in heritage-rich markets where stone longevity traditions support refurbishment economics over replacement cycles.
Curling Equipment Market Segmentation
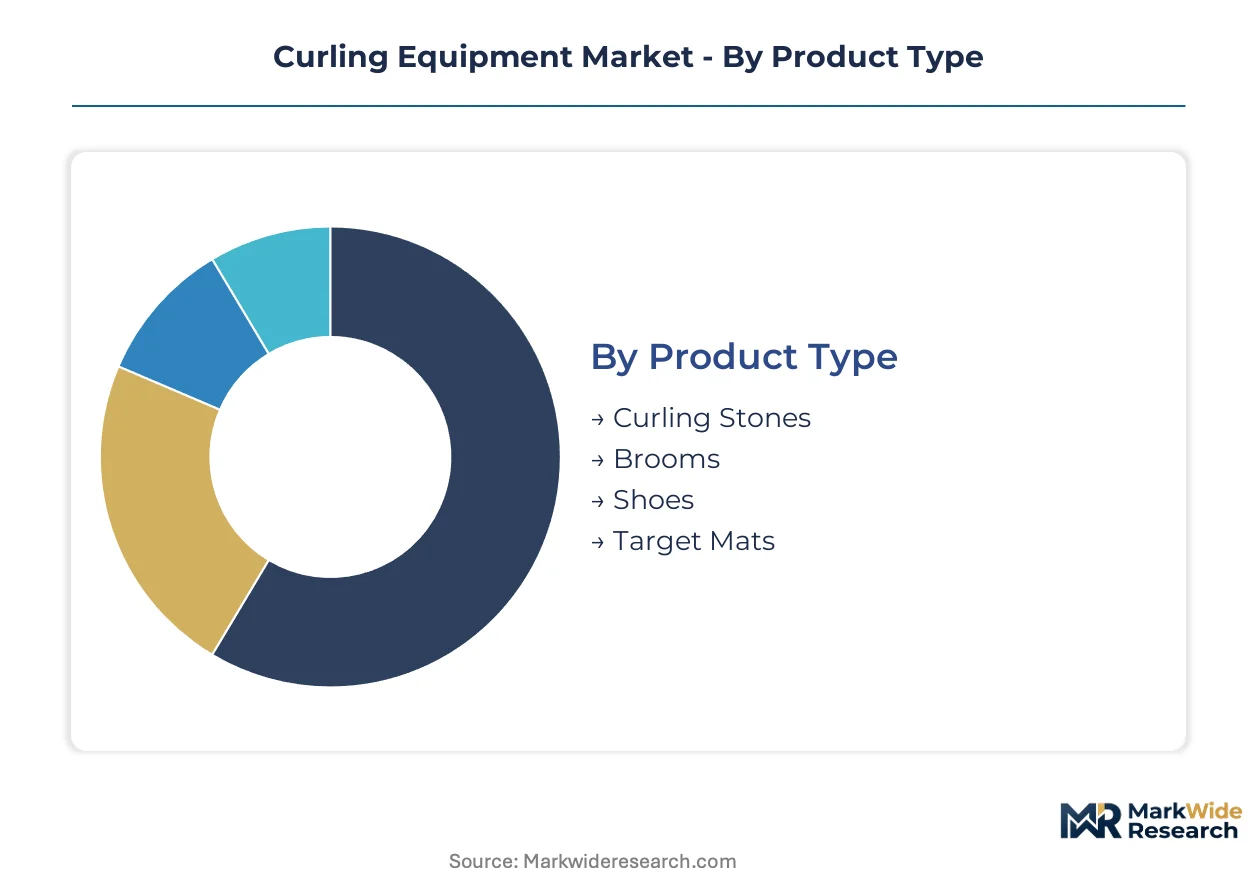
Curling equipment segmentation reflects divergent procurement economics between heritage stone craftsmanship and high-frequency consumable replacement. Understanding these splits enables suppliers to align production capacity with actual demand concentration across competitive and recreational tiers.
Product Type:
Volume concentrates in brooms and shoes while premium value pools in championship-grade stones with multi-decade replacement cycles.
- Curling Stones:Granite blocks precision-machined to 38-44 pound mass tolerance with running band curvature within 3 millimeters for regulation play. Scottish quarries supply championship-grade material while Canadian distributors dominate North American procurement through club direct relationships. Today's leader: Curling Stones. Tomorrow's challenger: Brooms.
- Brooms:Carbon fiber shafts paired with composite or hair brush heads generate recurring replacement revenue from competitive wear and surface abrasion protocols. Canadian club expansion drives systematic refresh cycles as municipal rinks proliferate across Ontario and Alberta.
- Shoes:Specialized sliding soles with Teflon or stainless steel inserts balance grip and glide for delivery mechanics.
- Target Mats:Vinyl or rubber house and button markers for practice facilities and non-standard ice configurations.
Revenue concentration favors stones on a per-unit basis while brooms dominate transaction frequency across institutional accounts.
Material:
Heritage extraction constraints in Scotland concentrate premium granite supply while synthetic alternatives capture recreational and practice segments.
- Granite:Ailsa Craig and Trefor quarry outputs supply championship-grade stone density and thermal stability requirements. Scottish heritage extraction faces volume limits against rising international club demand from Canada and emerging Asian markets.
- Composite:Carbon fiber and polymer matrix materials displace traditional hair blends in professional broom heads to reduce stone surface abrasion and extend playing surface life. REACH compliance alignment opens EU certification pathways for synthetic brush exports.
- Plastic:Injection-molded components for target mats, practice stones, and entry-level footwear soles.
- Wood:Traditional handle materials persisting in recreational-tier brooms and heritage-styled equipment lines.
Composite formulations are gaining share fastest in competitive broom segments while granite retains irreplaceable positioning in championship stone supply.
End User:
Procurement authority separates institutional volume buyers from individual recreational purchasers with divergent specification sensitivity.
- Professional Teams:ISO-certified equipment with sub-15 gram weight variance tolerances and championship federation approval. Health Canada safety framework compliance increasingly filters supplier selection in Canadian national competition circuits.
- Recreational Players:Price-sensitive individual purchasers through online retail and specialty store channels with lower specification tolerance requirements.
- Schools:Budget-constrained institutional procurement emphasizing durability and multi-user safety compliance over performance optimization.
- Clubs:Municipal and private facility operators combining volume purchasing power with component-level service unbundling for stone refurbishment economics.
Clubs command procurement volume while professional teams set specification standards that cascade to recreational tiers.
Distribution Channel:
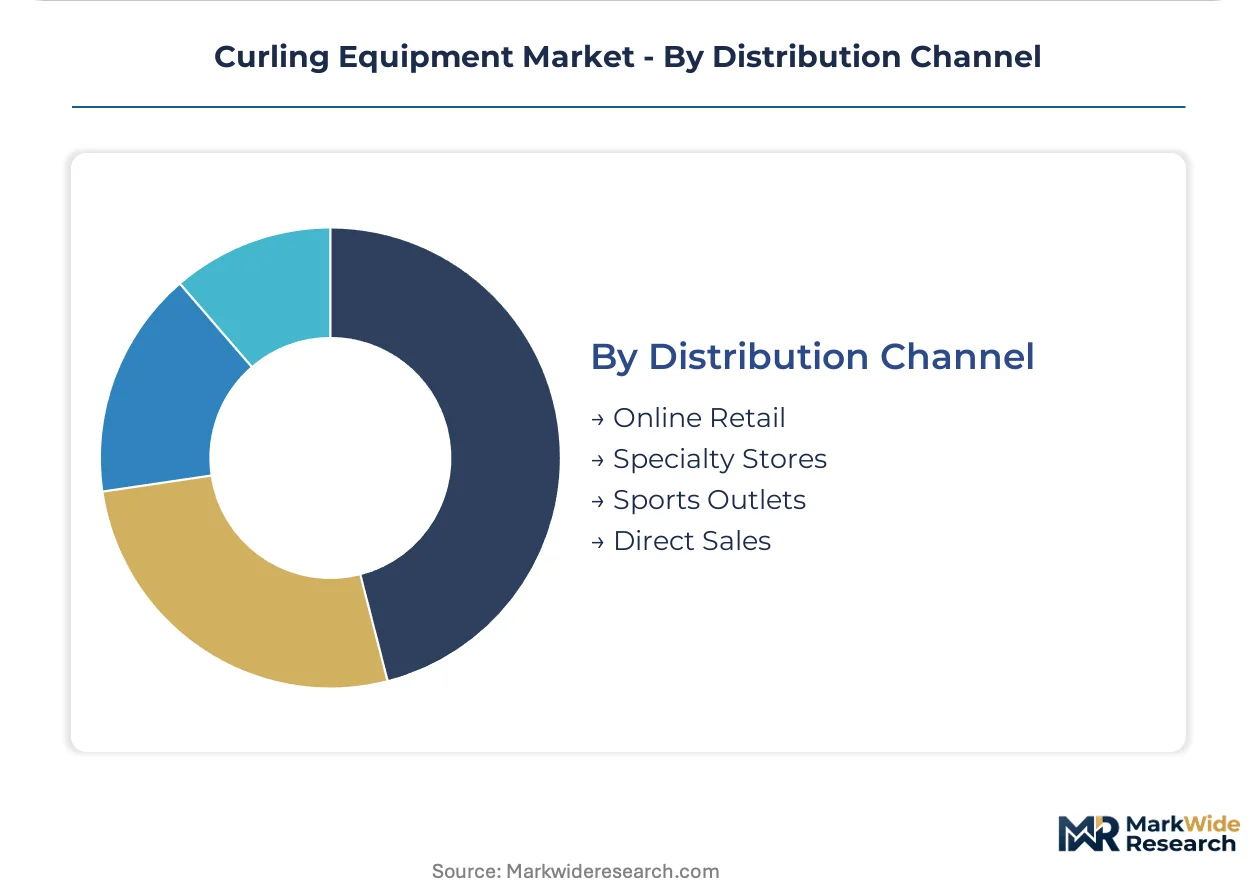
Direct club relationships capture institutional margin while online channels fragment recreational purchasing across price-comparison behaviors.
- Online Retail:E-commerce platforms aggregate recreational and amateur demand with price transparency and replacement part accessibility. Digital fulfillment accelerates brush head and accessory turnaround for remote facility operators.
- Specialty Stores:Pro shops at dedicated curling facilities provide fitting services and immediate equipment trial for serious amateur competitors.
- Sports Outlets:General sporting goods retailers stock entry-level shoes and brooms with limited stone inventory due to weight and shipping economics.
- Direct Sales:Manufacturer-to-club relationships bypass retail markup for municipal procurement committees and competitive bidding processes in Ontario and Alberta.
Direct sales anchor institutional profitability while online retail expands geographic reach into non-traditional curling markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal in curling equipment, where heritage granite extraction and club-level procurement concentrate production in Scotland and Canada regardless of compliance cost differentials. Equipment standards from Health Canada and ISO frameworks apply uniformly across export markets, eliminating migration incentives.
Canada
Municipal rink expansion across Ontario and Alberta drives systematic broom and shoe procurement as community membership rolls swell. Health Canada oversees sporting goods safety standards that mandate impact resistance testing for brush handles and stone collision scenarios. Curling clubs in Calgary and Edmonton negotiate direct manufacturer relationships for volume equipment refresh cycles.
Scotland
Heritage granite extraction from Ailsa Craig sustains irreplaceable championship-grade stone supply against rising international club demand. REACH compliance alignment opens EU certification pathways for synthetic brush exports from Scottish fabricators. Master stone finishing expertise concentrates among aging artisans in Mauchline and surrounding Ayrshire communities with limited apprenticeship pipeline scale.
United States
Club formation in non-traditional markets like Texas and Arizona creates equipment demand from synthetic surface facilities where natural ice formation is unreliable. No federal sporting goods regulator exists; state-level consumer protection statutes apply to equipment retail. Minneapolis and Duluth anchor Upper Midwest curling infrastructure with established club networks sourcing through Canadian distributors.
Sweden
Competitive team participation in international championships sustains premium equipment specification demand aligned with ISO durability certification requirements. The Swedish Chemicals Agency enforces REACH-aligned substance restrictions on synthetic brush head materials. Gothenburg and Stockholm house the country's densest club concentrations with direct procurement relationships to Scottish stone suppliers.
Switzerland
Alpine curling traditions in Graubünden and Bern cantons sustain niche equipment demand from historic club networks. Swissmedic oversees general product safety while sporting goods fall under cantonal consumer protection enforcement. Davos and St. Moritz host winter sports clusters where curling equipment procurement integrates with broader alpine facility maintenance budgets.
Curling Equipment Market Competitive Environment
Scottish producers anchor the premium stone tier; Canadian specialists hold dominant positions in broom technology and North American distribution. The vendor base splits between heritage granite craftsmen with century-old quarry access and composite material innovators compressing replacement cycles. Three archetypes prevail: quarry-integrated stone finishers, carbon fiber composite specialists, and direct-to-club distributors. Capacity expansion and REACH compliance alignment represent the dominant competitive moves.
Within the heritage stone tier, Kays of Scotland occupies a position exemplifying quarry-integrated production anchored to Ailsa Craig granite access. Among Canadian fabricators, Hardline Curling and Goldline Curling Supplies Ltd represent contrasting archetypes—technology leadership versus distribution scale—both serving municipal procurement committees across Ontario and Alberta.
| Leading Market Players |
|---|
| Hardline Curling |
| Canada Curling Stone Co |
| Goldline Curling Supplies Ltd |
| Performance Brush Co |
| Olson Curling |
| Balance Plus |
| Kays of Scotland |
| Shooters Curling Supply |
| Asham Curling Supplies |
| Others |
Value Chain & Pricing Dynamics
Health Canada safety framework mandates for impact resistance testing are forcing equipment distributors to absorb third-party laboratory costs, compressing channel margins and accelerating direct-to-club procurement bypass strategies. Municipal rink expansion across Ontario and Alberta concentrates volume purchasing power with procurement committees that negotiate component-level contracts rather than bundled equipment packages.
Pricing Analysis
Direct-to-club distributor margins face compression as municipal procurement committees in Calgary and Edmonton leverage volume scale for price concessions on broom and shoe refresh cycles. Three-tier pricing structure across premium championship-grade, standard club-level, and economy recreational tiers reflects ISO certification grade and Health Canada compliance status. Pricing pressure stems from ice facility energy cost volatility delaying equipment replacement timelines. Recreational players through online retail channels exhibit highest price sensitivity; professional teams seeking sub-15 gram weight variance tolerances show lowest sensitivity.
Supply Chain Analysis
Regional distribution centers in Glasgow and Toronto anchor hub-and-spoke patterns serving club networks across Scotland and Canada. Heritage granite extraction concentrates in Scotland while carbon fiber composite manufacturing clusters in Canada. Raw material dependencies include Ailsa Craig granite blocks, carbon fiber polymer matrices, and Teflon sliding sole inserts. Single-source vulnerability from Ailsa Craig quarry depletion risk threatens championship-grade stone supply. Distribution runs through manufacturer-to-club direct relationships for institutional accounts, with online retail fragmentation for recreational demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
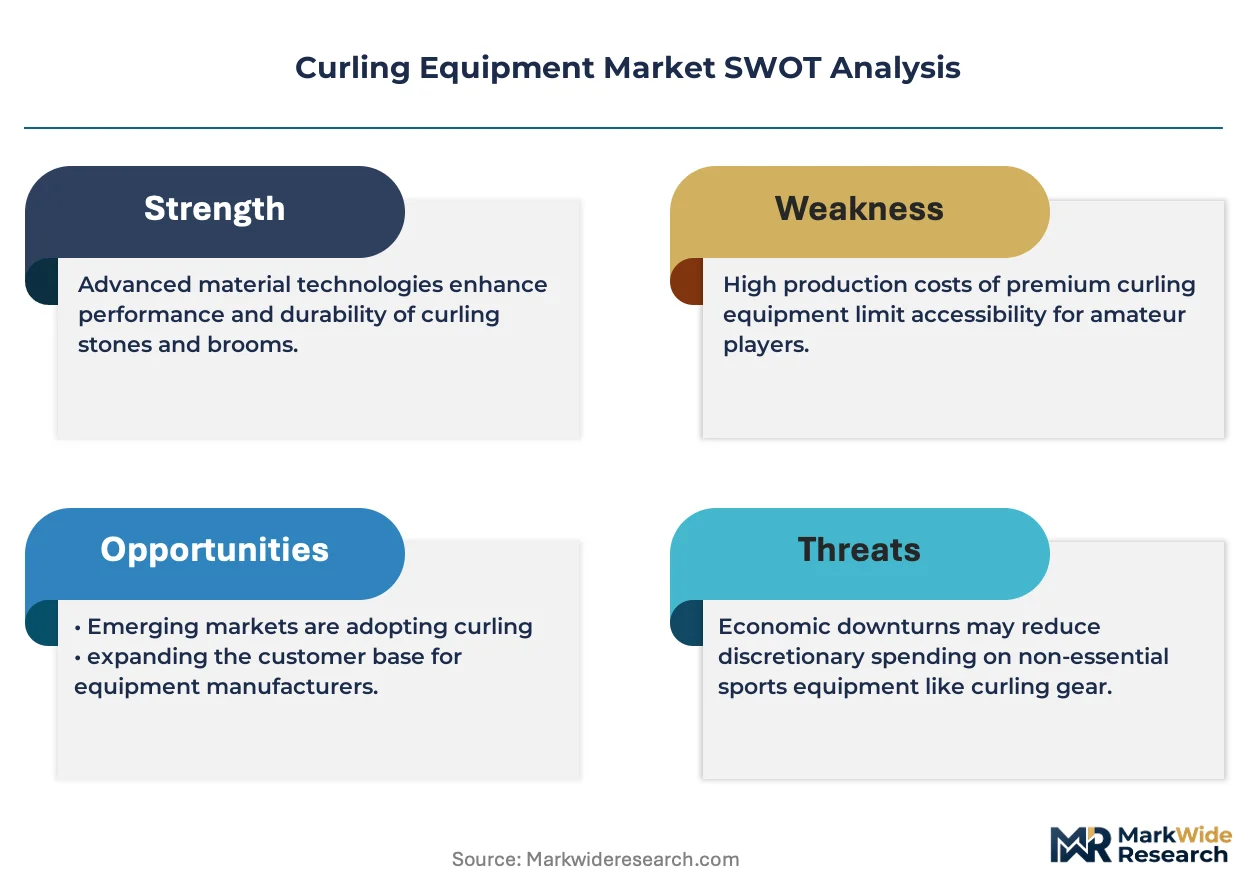
This market operates as a regulatory compounder where Health Canada safety framework expansion mandates systematic equipment upgrades across registered provincial leagues, creating replacement demand independent of organic growth.
For Market Incumbents: Deepen backward integration into carbon fiber composite manufacturing to capture margin from professional broom demand while insulating against REACH compliance cost escalation. Secure long-term Ailsa Craig granite access agreements before extraction constraints intensify. Invest in Health Canada certification infrastructure to filter competitor access to Ontario and Alberta municipal procurement channels. For New Entrants and Emerging Players: E-commerce platform routes offer lowest barrier entry for synthetic brush head and accessory sales into remote facility operators underserved by traditional distribution. Target Texas and Arizona club formation in non-traditional markets where synthetic surface facilities create equipment demand without established supplier relationships. Pursue direct-to-club digital fulfillment models capturing replacement part turnover from municipal rink expansion. For Investors and Strategic Acquirers: Asymmetric upside sits with quarry-integrated stone finishers possessing Ailsa Craig access rights and aging master craftsperson expertise. Long-term viability hinges on synthetic material substitution pace against heritage granite irreplaceability in championship certification. Watch REACH compliance alignment progress as signal for EU market access expansion by composite brush specialists.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Alignment | Opens EU certification pathways for Canadian composite brush exports into Swedish and Swiss markets. |
| Direct-to-Club Digital Distribution | Bypasses retail markup for municipal procurement committees in Ontario and Alberta. |
| Synthetic Surface Technology Partnership | Captures equipment demand from Texas and Arizona facilities where natural ice formation is unreliable. |
| Health Canada Certification Investment | Mandates impact resistance testing documentation filtering supplier selection in competitive bidding. |
| Granite Quarry Access Securement | Locks irreplaceable Ailsa Craig supply against rising international club demand from emerging Asian markets. |
Study Parameters
Multiple input streams — equipment procurement managers at municipal rinks, carbon fiber composite R&D directors, heritage stone finishing artisans, and Health Canada regulatory affairs specialists — were reconciled against customs trade records, curling federation equipment registries, club membership databases, and municipal capital expenditure disclosures. Primary fieldwork with Ontario and Alberta procurement committees validated secondary data on refresh cycle timing. Bottom-up club-level demand aggregation was triangulated against top-down manufacturer shipment estimates.
Data-stream reconciliation across product type, material composition, end-user tier, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from equipment replacement frequency modeling and municipal rink expansion pipeline analysis. Forecast inputs incorporated synthetic brush head adoption curves and ice facility energy cost volatility scenarios.
The model assumes a particular technology adoption path; alternative pathways for artificial ice sheet technology would alter the outlook for traditional equipment demand concentration. Forecasts reflect documented assumptions around Health Canada compliance timelines and Ailsa Craig extraction continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Gymnastic Hoops Market
Sports Equipment
Shuffleboard Equipment Market
Sports Equipment
Slam Ball Market
Sports Equipment
Global Horse Riding Equipment Market
Sports Equipment
Ladderball Market
Sports Equipment
GCC Running Gear Market
Sports Equipment
Concussion Helmets Market
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
Tennis Pole Market
Sports Equipment
Rowing Oars Market
Sports Equipment
Sports and Leisure Equipment Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Europe Winter Sports Equipment Market
Sports Equipment
Racket Sports Equipment Market
Sports Equipment
Global Sports Sunglasses Market
Sports Equipment
Asia-Pacific Bicycle Market