
 Rechargeable Medical Battery Market | 2026-2036
Rechargeable Medical Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Rechargeable Medical Battery Market Insights
UN 38.3 lithium transport certification is rotating the competitive landscape by filtering out suppliers lacking validated thermal runaway testing infrastructure. Panasonic Corporation leverages its vertically integrated cell chemistry operations to sustain qualification throughput across multiple medical OEM programs. EaglePicher Technologies anchors its position through dedicated cleanroom manufacturing for implantable-grade cells, while Saft Groupe competes on high-reliability aerospace-to-medical technology transfer.
A rechargeable medical battery is an electrochemical energy storage cell designed for repeated charge-discharge cycling in diagnostic, therapeutic, or patient-monitoring equipment, typically specified for 500–1,000 cycles at 20°C with less than 20% capacity fade. These power sources enable ambulatory care, reduce surgical battery replacement procedures, and support continuous physiological data collection. Lithium-Ion chemistry dominates value capture due to superior energy density and declining cell cost curves, while Nickel-Metal Hydride retains share in cost-sensitive portable devices where thermal stability outweighs gravimetric performance. Implantable Devices applications command premium pricing tiers because ISO 14708-1 active implantable safety standards demand exhaustive biocompatibility and hermetic sealing validation.
FDA 21 CFR Part 820 quality system regulation and EU MDR conformity assessment shape product development timelines by mandating design controls, risk management per ISO 14971, and post-market surveillance for battery-powered devices. The EPA and OSHA impose workplace chemical exposure limits on nickel-cadmium cell manufacturing, accelerating conversion to lithium-based chemistries in domestic production. Stakeholders must monitor evolving IEC 60601-1 third edition electromagnetic compatibility requirements for wireless charging integration in bedside and wearable systems.
Market Dynamics
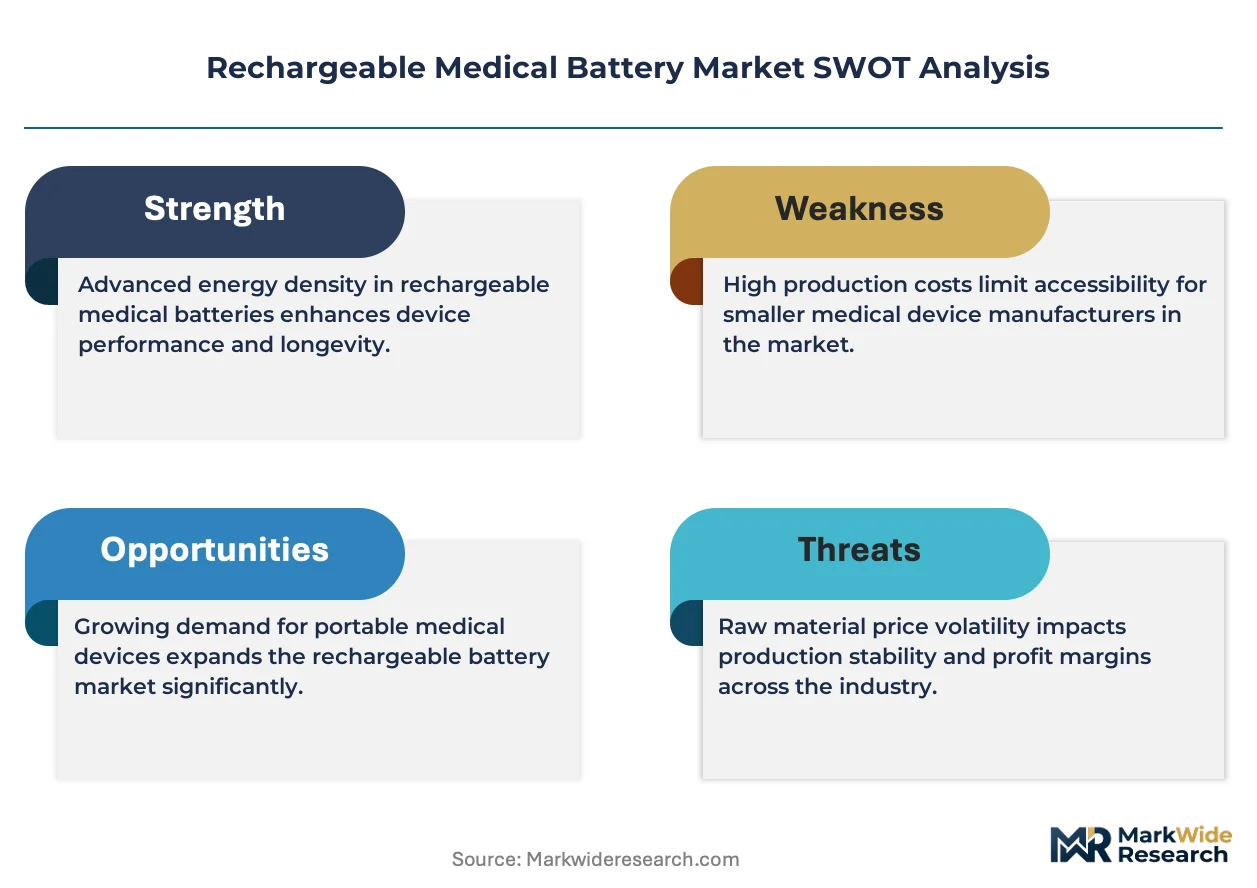
UN 38.3 lithium transport certification is compressing supplier participation by mandating validated thermal runaway testing infrastructure, filtering out cell producers lacking capital-intensive qualification capabilities and consolidating procurement relationships around vertically integrated manufacturers.
Growth Catalysts
- Portable diagnostic proliferation:Point-of-care testing devices in Germany and the United States require compact rechargeable power systems for ambulatory patient monitoring, driving procurement of high-cycle-life lithium-ion cells.
- EU MDR conformity assessment:The Medical Device Regulation's tightened battery safety annexes are accelerating OEM demand for pre-qualified cell suppliers with established ISO 14971 risk management documentation.
- Homecare monitoring expansion:Japan's aging demographic is sustaining volume procurement of wearable power systems for continuous glucose monitors and cardiac event recorders.
Market Restraints
- Cobalt supply concentration:Democratic Republic of Congo dominance in mined cobalt creates price volatility exposure for lithium-ion cathode formulations, compressing margin predictability for cell producers.
- Hermetic sealing capex:Implantable-grade titanium enclosure welding requires cleanroom infrastructure investments exceeding $50 million per facility, limiting supplier entry.
- Nickel-metal hydride displacement lag:Cost-sensitive portable device segments in India and Southeast Asia retain NiMH chemistry where thermal stability outweighs energy density requirements.
Strategic Opportunities
- Wireless charging integration:IEC 60601-1 third edition electromagnetic compatibility revisions are creating white space for inductive power transfer in bedside patient monitoring systems.
- India domestic manufacturing:PLI scheme incentives for advanced chemistry cell production are attracting medical-grade lithium-ion assembly capacity to serve regional diagnostic device OEMs.
- Solid-state electrolyte convergence:Polymer-ceramic hybrid electrolytes combined with silicon anodes promise 40% energy density gains for next-generation implantable neurostimulators.
Industry Challenges
- UN 38.3 testing backlog:Certified laboratory capacity constraints are extending cell qualification timelines to 18-24 months, delaying product launches for emerging OEMs.
- Biocompatibility validation complexity:ISO 10993 cytotoxicity and sensitization testing for implantable cells requires 36-month study protocols, compressing competitive response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rechargeable Medical Battery Market |
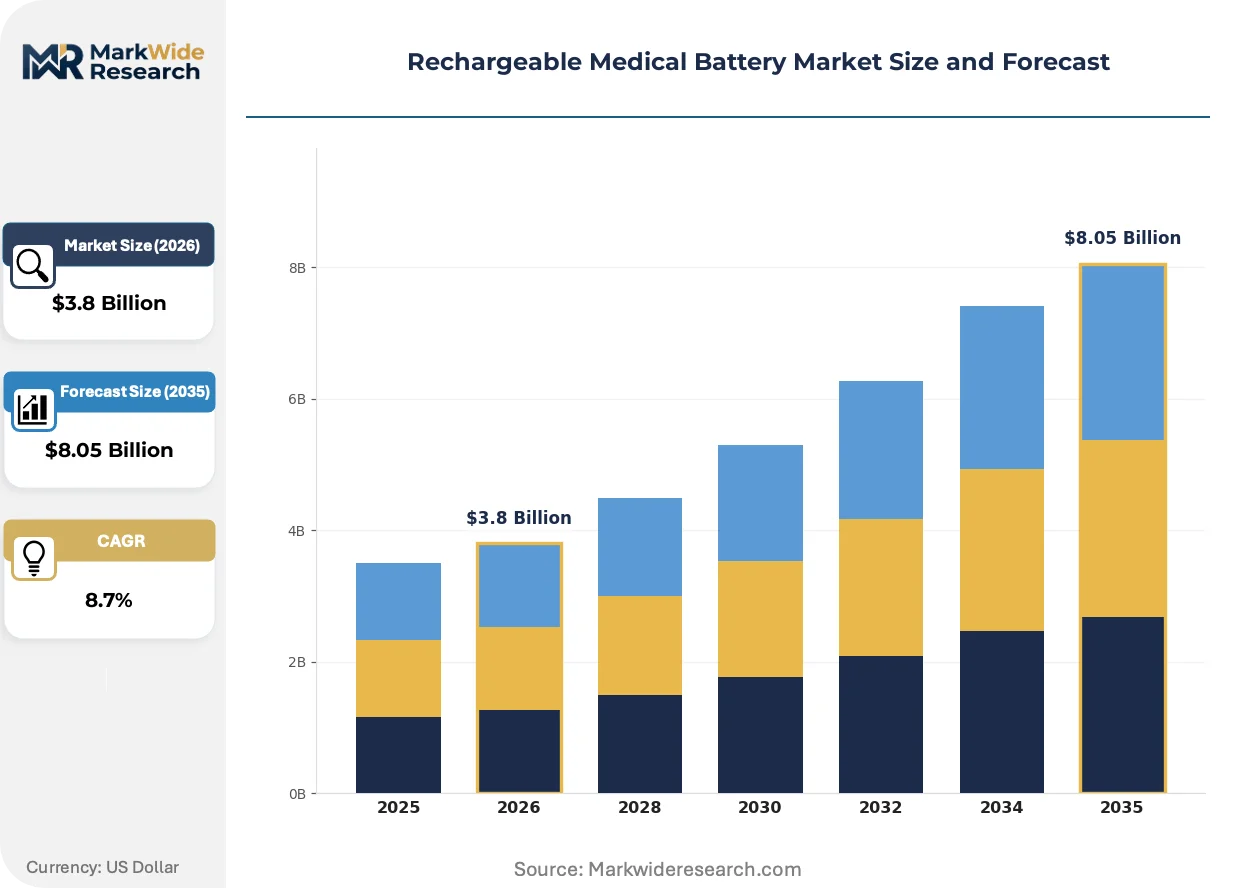
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Cadmium, Nickel-Metal Hydride, Lead Acid End User: Hospitals, Homecare, Diagnostics, Rehabilitation Centers Application: Portable Devices, Implantable Devices, Surgical Equipment, Monitoring Systems Technology: Smart Batteries, Rechargeable Batteries, Wireless Charging, Energy Harvesting |
| Companies Covered | Panasonic Corporation, EaglePicher Technologies, Ultralife Corporation, EnerSys, Tadiran Batteries, VARTA Microbattery, Saft Groupe, Murata Manufacturing, SHENZHEN KAYO BATTERY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rechargeable Medical Battery Market Trends and Innovations
Solid-state battery architectures are disrupting conventional lithium-ion supply relationships by demanding new manufacturing processes and material qualifications that favor capital-rich incumbents with captive R&D infrastructure.
Silicon nanowire anode technology is miniaturizing cell footprints while maintaining capacity ratings, enabling sub-millimeter power sources for ingestible sensors and micro-implantable drug delivery systems. Cardiac rhythm management device manufacturers in Switzerland and the United States are qualifying these cells for next-generation leadless pacemakers. The technology is miniaturizing device form factors to sub-cc volumes previously unreachable with graphite anode chemistry.
EU MDR Article 10 technical documentation requirements are forcing battery suppliers to maintain design history files traceable to individual cell lots, increasing compliance overhead but creating competitive moats for qualified manufacturers. German notified bodies are interpreting active implantable battery clauses more stringently than pre-2017 directives. Implantable device OEMs are responding by consolidating supplier panels to three qualified vendors maximum.
Hospital procurement departments are unbundling battery replacement service contracts from device capital purchases, creating standalone aftermarket revenue streams for cell manufacturers with field service capabilities. Group purchasing organizations in the United States are negotiating multi-year cell supply agreements with price collars indexed to lithium carbonate futures. This shift is most visible in acute care settings where bedside monitor fleet sizes exceed 500 units per health system.
Rechargeable Medical Battery Market Segmentation
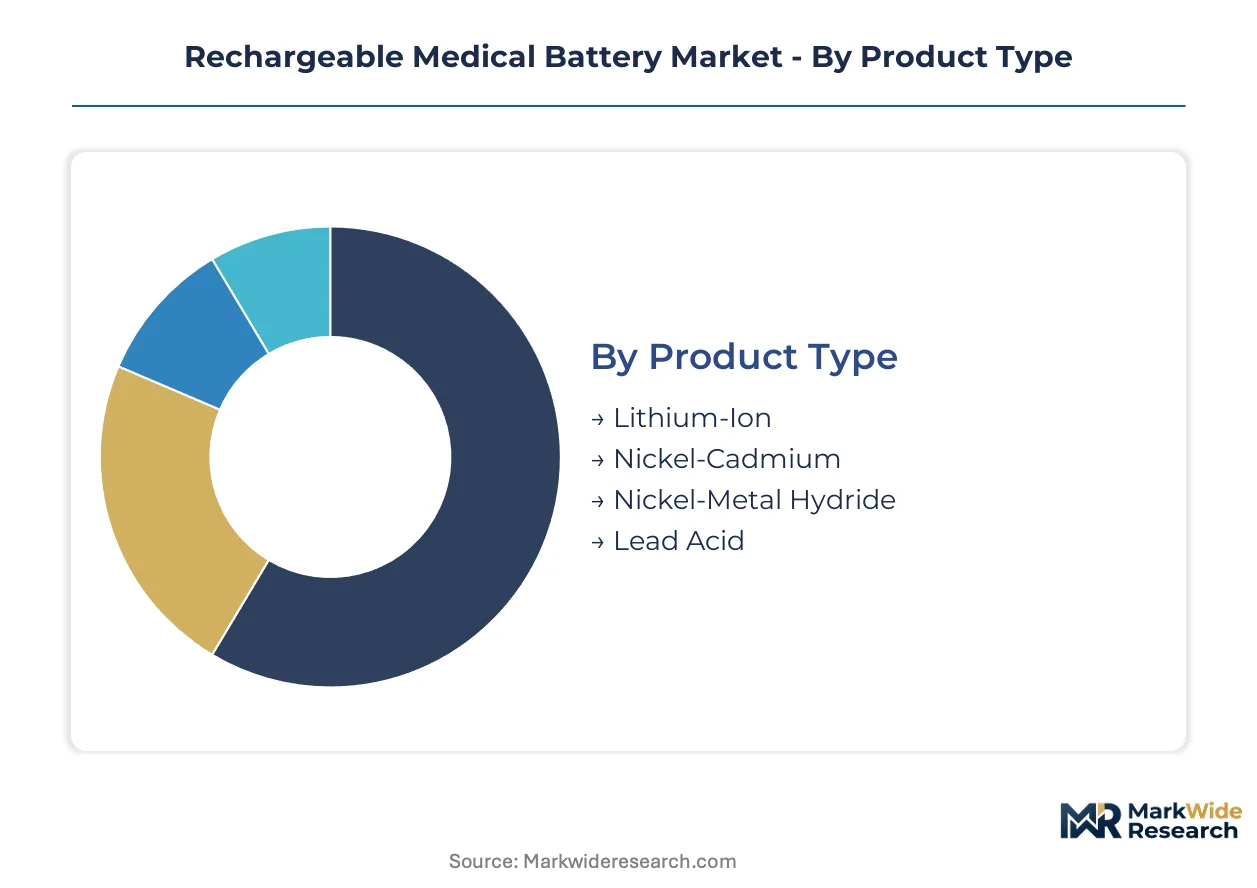
Segmentation in the rechargeable medical battery market reveals how chemistry choices, end-use environments, and charging modalities channel procurement decisions. Each dimension carries distinct qualification burdens and margin structures that shape supplier positioning.
Product Type:
Channel flows diverge sharply by chemistry: lithium-ion cells move predominantly through OEM direct contracts, while nickel-cadmium and lead acid circulate via distributor networks serving maintenance-replacement demand.
- Lithium-Ion:Cobalt-oxide and iron-phosphate cathode formulations deliver 150-250 Wh/kg energy density with 500-1,000 cycle life. Demand concentrates in Germany and the United States for portable diagnostic and implantable neurostimulator applications, where ISO 14708-1 hermetic sealing requirements filter supplier panels to three qualified vendors maximum.
- Nickel-Metal Hydride:Rare-earth alloy hydride anodes with nickel oxyhydroxide cathodes provide thermal stability superior to lithium-ion in ambient temperature extremes. Procurement in India's cost-sensitive portable device segment sustains volume despite energy density disadvantages, as BIS certification timelines favor established NiMH supply chains.
- Nickel-Cadmium:Sintered plate construction tolerates deep discharge cycling in surgical power tools. EPA workplace exposure limits on cadmium processing accelerate conversion to lithium-based chemistries in domestic US production.
- Lead Acid:Absorbed glass mat variants support uninterruptible power supplies for hospital bedside monitoring infrastructure. Replacement cycles run 3-5 years versus 8-12 years for lithium alternatives.
By volume, lead acid leads in hospital backup power installations. By growth pace, lithium-ion is expanding most quickly as implantable device OEMs consolidate supplier relationships.
End User:
Cost tier stratification separates acute care capital budgets from homecare reimbursement constraints, with diagnostics and rehabilitation occupying intermediate positions.
- Hospitals:Group purchasing organizations negotiate multi-year supply agreements with price collars indexed to lithium carbonate futures. Fleet sizes exceeding 500 bedside monitors per health system create standalone aftermarket revenue streams for cell manufacturers with field service capabilities.
- Homecare:Japan's aging demographic sustains wearable power system procurement for continuous glucose monitors and cardiac event recorders. Reimbursement codes in the United States favor disposable over rechargeable configurations, compressing addressable market scope.
- Diagnostics:Point-of-care testing devices require compact rechargeable power for ambulatory patient monitoring in Germany and US outpatient clinics.
- Rehabilitation Centers:Motorized mobility equipment and therapeutic stimulation devices demand deep-cycle durability under intermittent charging patterns.
Hospital procurement commands premium pricing tiers. Homecare applications are gaining share fastest as aging-in-place policies expand remote monitoring eligibility.
Application:
Margin concentration tracks regulatory burden: implantable devices require ISO 10993 biocompatibility validation spanning 36-month study protocols, while portable devices face lighter conformity assessment.
- Implantable Devices:Titanium enclosure welding with laser hermetic sealing meets ISO 14708-1 active implantable safety standards. Swiss and US cardiac rhythm management manufacturers qualify silicon nanowire anodes for sub-cc volume leadless pacemakers.
- Portable Devices:Handheld diagnostic instruments and infusion pumps prioritize gravimetric energy density. EU MDR Article 10 technical documentation requirements force battery suppliers to maintain design history files traceable to individual cell lots.
- Surgical Equipment:Motorized drills and shavers demand high-rate discharge capability under sterile field constraints. Sterilization cycle tolerance limits viable chemistry selections.
- Monitoring Systems:Bedside and wearable patient monitors integrate wireless charging per IEC 60601-1 third edition electromagnetic compatibility revisions.
Portable devices dominate unit volume. Implantable applications show the steepest expansion trajectory as neurostimulator indications broaden.
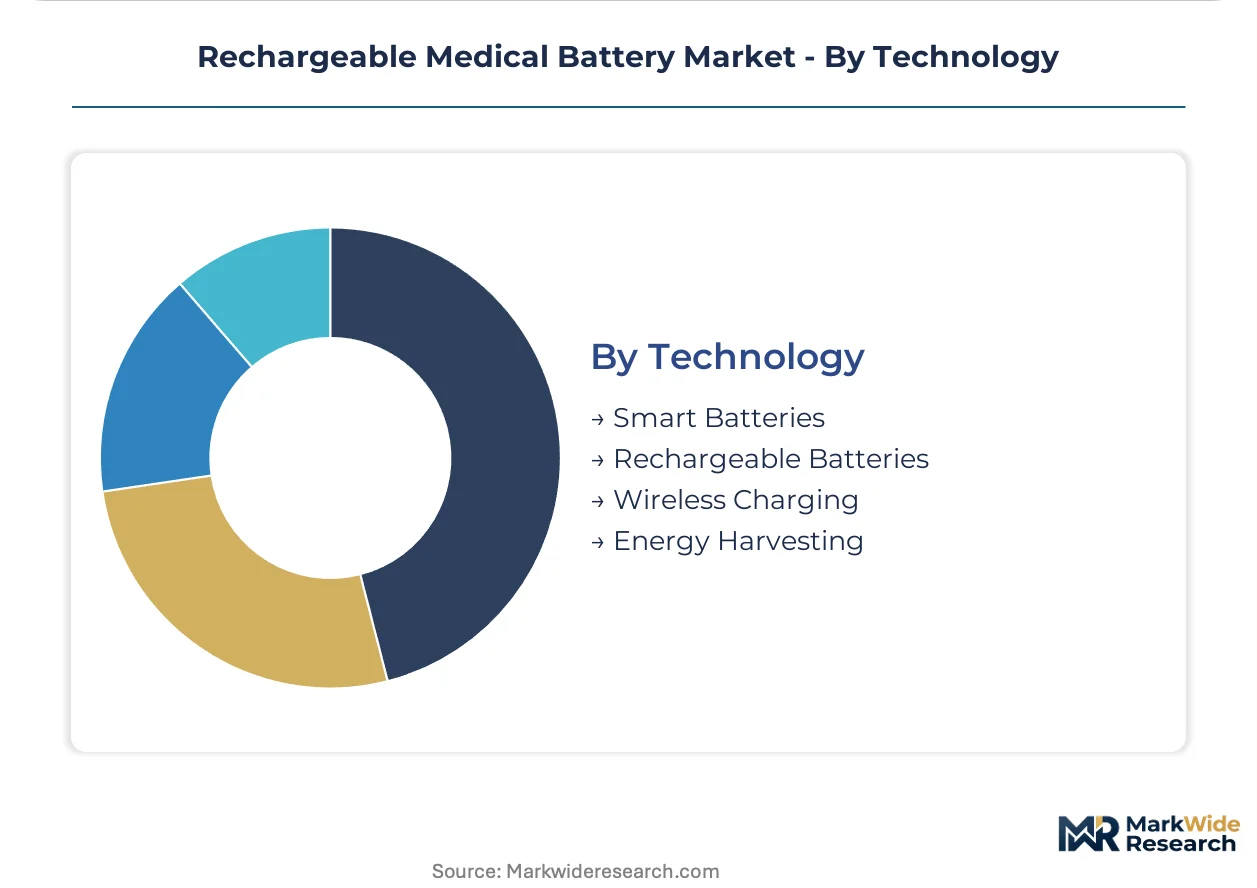
Technology:
Supply concentration favors capital-rich incumbents: smart battery management systems and solid-state architectures demand captive R&D infrastructure that filters out mid-tier competitors.
- Smart Batteries:Integrated fuel gauging and cycle counting electronics enable predictive maintenance algorithms. FDA 21 CFR Part 820 design controls mandate software validation documentation for battery management firmware.
- Rechargeable Batteries:Conventional electrochemical cells without embedded electronics serve cost-optimized device segments where bill-of-materials constraints predominate.
- Wireless Charging:Inductive power transfer coils in bedside patient monitoring systems require electromagnetic compatibility testing under IEC 60601-1 third edition.
- Energy Harvesting:Piezoelectric and thermoelectric transducers supplement primary cells in ultra-low-power ingestible sensors.
Rechargeable batteries without smart electronics retain volume leadership. Wireless charging is climbing the fastest as hospital infrastructure upgrades accelerate cable elimination initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and implantable device OEMs concentrate procurement authority in Germany, the United States, and Japan, where aging patient populations and advanced healthcare infrastructure sustain premium-tier battery demand.
United States
Group purchasing organizations negotiate multi-year supply agreements with price collars indexed to lithium carbonate futures for health systems operating 500-plus bedside monitor fleets. FDA 21 CFR Part 820 quality system regulation mandates design controls and risk management documentation that extend cell qualification timelines. Greater Boston and Minneapolis-St. Paul anchor cardiac rhythm management device manufacturing clusters where silicon nanowire anode cells undergo qualification for leadless pacemakers.
Germany
Point-of-care testing devices in outpatient clinics drive compact rechargeable power system procurement for ambulatory patient monitoring applications. EU MDR Article 10 technical documentation requirements force battery suppliers to maintain design history files traceable to individual cell lots. Stuttgart and Munich concentrate notified body activity where German regulators interpret active implantable battery clauses more stringently than pre-2017 directives.
Japan
Continuous glucose monitors and cardiac event recorders for aging-in-place policies sustain volume procurement of wearable power systems. METI standards and PMDA conformity assessment shape domestic qualification protocols for implantable-grade cells. Tokyo and Osaka metropolitan areas concentrate OEM headquarters where procurement panels consolidate to three qualified vendors maximum under tightened supplier qualification requirements.
Switzerland
Cardiac rhythm management device manufacturers qualify advanced cell chemistries for next-generation neurostimulator applications with broadening clinical indications. Swissmedic regulates active implantable medical devices under standards harmonized with EU MDR safety annexes. The Lake Geneva region hosts precision manufacturing clusters where titanium enclosure welding with laser hermetic sealing meets ISO 14708-1 requirements.
India
Cost-sensitive portable diagnostic devices in domestic and export markets retain nickel-metal hydride chemistry where thermal stability outweighs energy density requirements. PLI scheme incentives for advanced chemistry cell production attract medical-grade lithium-ion assembly capacity to serve regional OEMs. Maharashtra and Gujarat concentrate emerging cleanroom manufacturing investments targeting BIS certification timelines for established supply chains.
Rechargeable Medical Battery Market Competitive Landscape
Player mix skews toward vertically integrated electronics conglomerates and dedicated electrochemical specialists with captive qualification infrastructure. Three to five qualified vendors dominate implantable-grade procurement panels due to ISO 14708-1 hermetic sealing and ISO 10993 biocompatibility validation requirements. Strategic archetypes include diversified materials conglomerates with in-house cell chemistry operations, pure-play battery specialists with cleanroom manufacturing capabilities, and aerospace-to-medical technology transfer firms. Competitive moves center on backward integration into cathode material supply and multi-year OEM service contracts bundling cell supply with predictive maintenance algorithms.
Among diversified electronics manufacturers, Panasonic Corporation and Murata Manufacturing occupy positions representing materials conglomerates with vertically integrated cell chemistry operations. EaglePicher Technologies exemplifies the specialist archetype with dedicated cleanroom infrastructure for implantable-grade production. Saft Groupe sits within the technology transfer tier, applying high-reliability aerospace electrochemical expertise to medical device applications.
| Leading Market Players |
|---|
| Panasonic Corporation |
| EaglePicher Technologies |
| Ultralife Corporation |
| EnerSys |
| Tadiran Batteries |
| VARTA Microbattery |
| Saft Groupe |
| Murata Manufacturing |
| SHENZHEN KAYO BATTERY |
| Others |
Pricing and Supply Chain Analysis
UN 38.3 lithium transport certification gates both supplier qualification and price differentiation simultaneously, filtering cell producers lacking thermal runaway testing infrastructure while concentrating procurement relationships around vertically integrated manufacturers capable of absorbing multi-year validation timelines. This regulatory chokepoint stratifies pricing tiers by certification burden rather than raw material cost alone.
Pricing Analysis
Cost-plus contracts with lithium carbonate futures indexation dominate hospital GPO negotiations, creating three-tier pricing structure across implantable-grade, portable diagnostic, and replacement battery levels. Price differentiation rests on ISO 14708-1 hermetic sealing certification and cleanroom manufacturing pedigree rather than energy density specifications alone. Pricing pressure stems from cobalt price volatility in DRC-sourced cathode materials, compressing margin predictability for non-integrated cell producers. Homecare wearable segments show highest price sensitivity due to reimbursement codes favoring disposable configurations, while implantable neurostimulator applications tolerate premium tiers for biocompatibility-validated supply.
Supply Chain Analysis
Democratic Republic of Congo cobalt concentrate transit through Durban and Dar es Salaam ports underwrites cathode material cost stability for lithium-ion formulations. Cell manufacturing concentrates in China, South Korea, and Japan, with Panasonic and Murata anchoring Japan's vertically integrated output while Chinese producers feed cost-sensitive portable device demand. Raw material dependencies span DRC cobalt, Australian spodumene, and Chilean lithium brine. Single-source vulnerability runs through hermetic sealing equipment suppliers in Germany and Switzerland, where titanium laser welding systems face 18-month order backlogs. Distribution runs through OEM direct contracts for implantable grades and distributor networks for replacement demand in hospital maintenance operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against solid-state battery architectures that threaten to obsolete conventional lithium-ion manufacturing relationships and qualification investments.
For Market Incumbents: Shield ISO 14708-1 certification moats by accelerating silicon nanowire anode qualifications for sub-cc implantable applications before solid-state electrolytes mature. Backward integration into cathode material supply reduces DRC cobalt exposure while captive cleanroom capacity in Stuttgart or Minneapolis-St. Paul clusters defends against emerging Asian competitors with PLI-subsidized capacity. For New Entrants and Emerging Players: Lead with wireless charging integration for bedside monitoring systems under IEC 60601-1 third edition revisions, where established suppliers lag in inductive coil miniaturization. India's domestic diagnostic device OEMs present the most penetrable white space, with BIS certification timelines favoring local assembly partnerships over fully qualified imports. Position through field service capabilities that unbundle battery replacement from device capital purchases. For Investors and Strategic Acquirers: EU MDR Article 10 traceability requirements reshape the acquisition landscape by elevating design history file infrastructure above raw cell chemistry expertise. Five-to-ten-year viability favors targets with captive UN 38.3 testing relationships and established notified body rapport in Germany or Switzerland. Watch FDA 21 CFR Part 820 software validation enforcement for battery management firmware as the signal indicating which qualification assets will appreciate versus depreciate.| Strategic Initiative | Industry Significance |
|---|---|
| UN 38.3 Testing Infrastructure Investment | Certified laboratory capacity in Germany and Japan filters competitor entry and extends contract durations. |
| Silicon Nanowire Anode Qualification | Sub-cc volume cells for leadless pacemakers in Swiss and US cardiac device clusters capture premium tiers. |
| Wireless Charging Module Development | IEC 60601-1 third edition compliance for bedside monitors opens standalone aftermarket revenue streams. |
| Cobalt Supply Chain Restructuring | Australian and Indonesian nickel-cobalt laterite sourcing reduces DRC concentration risk for cathode formulations. |
| Hospital GPO Service Contract Bundling | Predictive maintenance algorithms for 500-plus monitor fleets lock in multi-year cell supply agreements. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with biomedical engineers, hospital GPO contracts managers, implantable device procurement leads, and cleanroom manufacturing operations directors; and secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, UN 38.3 test laboratory certification records, and lithium carbonate futures exchange data. Bottom-up cell shipment estimates by chemistry and application were triangulated against top-down medical device OEM revenue attribution to power systems.
Across the analysis window, the forecasting framework modeled volume and value trajectories through chemistry segmentation, end-use environment, regulatory qualification tier, and charging modality dimensions. CAGRs were derived from regression analysis against implantable device procedure volumes, portable diagnostic unit shipments, and hospital capital expenditure patterns. Industry-specific inputs included UN 38.3 testing backlog durations, ISO 10993 biocompatibility study timelines, and notified body interpretation variance across German and Swiss regulators.
The analysis sits within stated boundaries; outcomes outside sustained cobalt price volatility, accelerated solid-state electrolyte commercialization, or tightened EU MDR battery safety annexes would require recalibration. Forecasts reflect documented assumptions regarding qualification timeline stability and OEM supplier panel consolidation limits. Practitioners should keep alternative scenarios live as MDR enforcement intensity and wireless charging standard adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
GCC Implantable Medical Devices Market
Medical Devices
Intraoral Scanners Market
Medical Devices
Contact Thermometer Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
USA Artificial Organs and Bionic Implants Market
Medical Devices
Dose Monitoring Devices Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Pressotherapy Systems Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Balloon Catheters for Bile Stone Removal Market
Medical Devices
China Intrauterine Devices Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
Medical Goggle Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Sensor Based Smart Catheters Market
Medical Devices
Conduction Vaporizers Market