
 Rotary Actuators Market | 2026-2036
Rotary Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Actuators Market Intelligence
The historical separation between mechanical engineering and software development expertise is collapsing as demand for smart, connected actuators rises. This shift benefits companies with deep mechatronics capabilities, creating new competitive dynamics. Parker Hannifin Corp. leverages its extensive portfolio in motion and control technologies to serve diverse end markets. Meanwhile, Rockwell Automation, Inc. specializes in integrated automation platforms for complex industrial applications, and SMC Corporation dominates in pneumatic control systems essential for factory automation.
A rotary actuator is a device converting energy from sources like electric, hydraulic, or pneumatic power into rotational motion. These components deliver controlled torque for precise angular positioning, typically from 90 to 360 degrees, to operate valves and robotic joints. Electric actuators incorporating servo motors are gaining share over traditional types for their superior precision and efficiency. Hydraulic systems continue to serve heavy-duty valve automation, while pneumatic actuators are standard in cost-sensitive packaging and robotics applications.
Product design and market access are governed by safety and performance standards, including the EU's Machinery Directive and CE marking for European sales. In the United States, components used in hazardous locations must comply with OSHA and specific UL/ATEX certifications, influencing material selection and enclosure design. Suppliers must decide whether to invest in integrated IIoT sensor platforms or focus on optimizing core mechanical performance for specific applications.
Market Dynamics
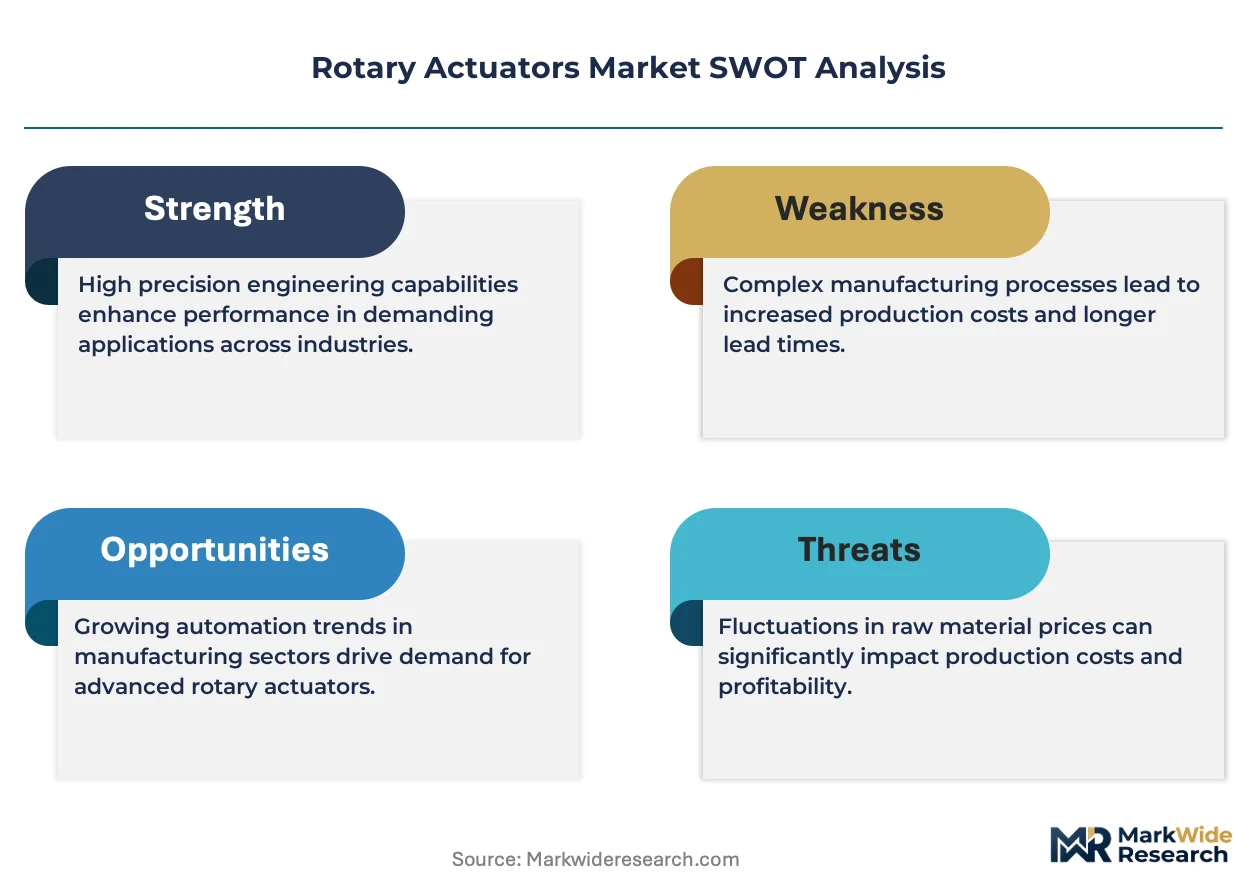
The convergence of mechanical engineering and software development under Industry 4.0 is the central force shaping the market. This creates intense demand for smart actuators with integrated IIoT capabilities, fundamentally altering product design and vendor requirements.
Growth Catalysts
- Industrial Robotics Investment:Accelerated investment in industrial robotics, particularly within Japan's electronics manufacturing and Germany's automotive assembly lines, directly fuels demand for high-precision electric rotary actuators for robotic joints.
- Aerospace Modernization:Modernization programs for commercial and military aircraft drive requirements for lightweight, high-torque actuators in flight control systems and landing gear, benefiting suppliers who meet stringent aerospace certifications.
- Industry 4.0 Adoption:The adoption of Industry 4.0 principles across manufacturing hubs necessitates actuators with embedded sensors and network connectivity, enabling predictive maintenance and improving overall equipment effectiveness.
Market Restraints
- High Cost of Electric Actuators:The significant upfront investment required for high-precision electric servo actuators compared to traditional pneumatic systems limits adoption in cost-sensitive applications like basic packaging machinery.
- System Integration Complexity:Integrating smart actuators with legacy factory control systems and disparate IIoT platforms presents a significant technical hurdle, often requiring specialized mechatronics expertise that is in short supply.
- Hydraulic System Dominance:In heavy-duty applications such as large valve automation in the oil and gas sector, hydraulic actuators maintain dominance due to their superior torque density and established infrastructure.
Strategic Opportunities
- Medical Automation:The growing field of laboratory automation and surgical robotics presents a significant opportunity for miniaturized, high-precision electric actuators that meet stringent cleanliness and reliability standards.
- Actuator-as-a-Service Models:Developing business models based on selling rotational motion or uptime, enabled by IIoT data from smart actuators, offers a path to recurring revenue beyond initial hardware sales.
- Renewable Energy Infrastructure:The expansion of wind and solar energy infrastructure creates new demand for durable actuators in applications like solar tracker positioning and wind turbine blade pitch control.
Industry Challenges
- Mechatronics Talent Scarcity:A persistent shortage of engineers with combined expertise in mechanical systems, electronics, and software engineering hampers new product development and customer support for integrated smart actuators.
- Fragmented Certification Requirements:Suppliers face complexity and cost in securing multiple certifications, such as CE marking for Europe and UL/ATEX for hazardous locations in the US, for a single product line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Actuators Market |
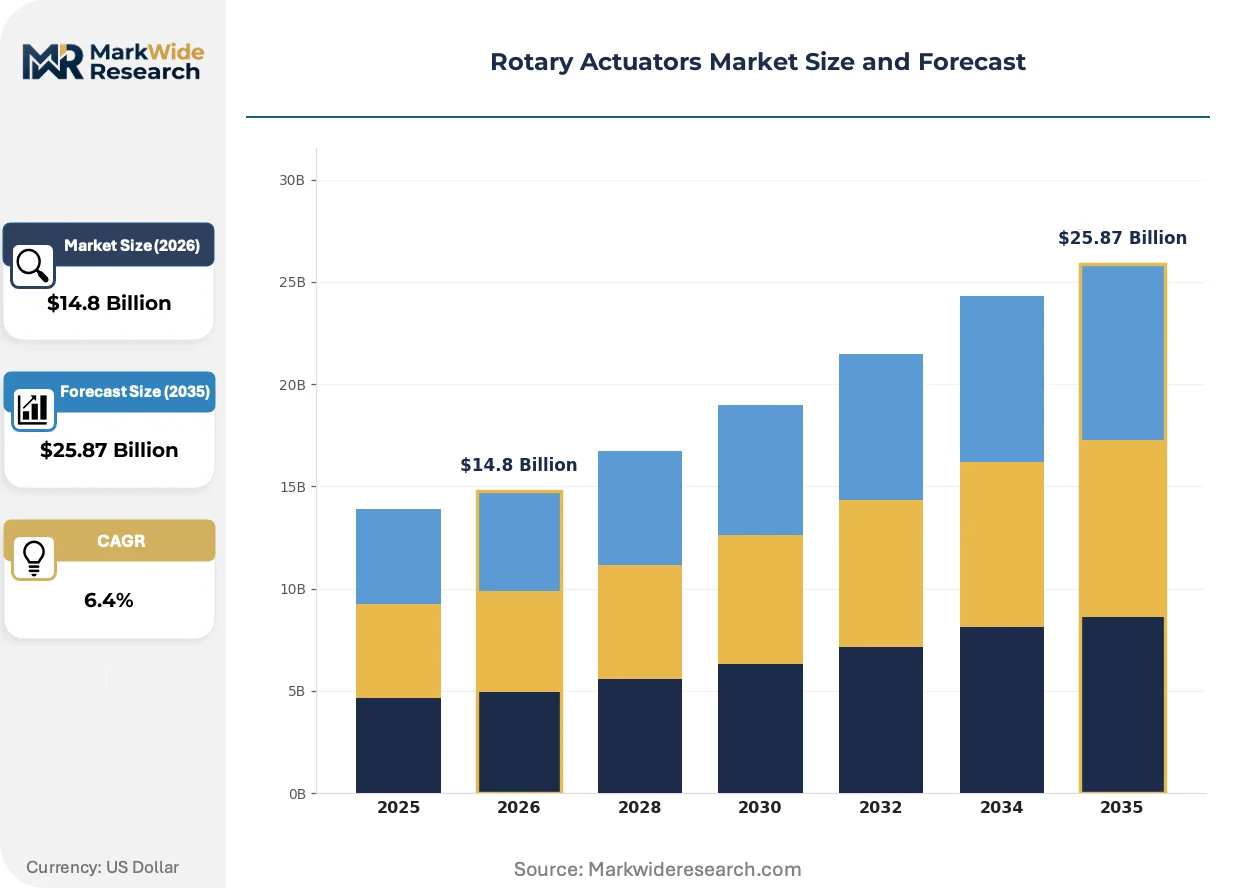
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Actuator Type: Electric, Pneumatic, Hydraulic, Mechanical Technology: Stepper Motors, Servo Motors, Rack and Pinion, Scotch Yoke, Worm Gear Application: Packaging Equipment, Robotics, Valve Automation, Aerospace Systems, Marine Controls End User Sector: OEMs, System Integrators, Aftermarket Service Providers, Industrial Automation Firms |
| Companies Covered | ABB Ltd., Emerson Electric Co., Rockwell Automation, Inc., Moog Inc., Parker Hannifin Corp., Curtiss-Wright, Flowserve Corporation, SMC Corporation, Rotork plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Actuators Market Strategic Shifts & Innovations
The fundamental role of the rotary actuator is evolving from a simple motion component into a critical data-generating node within connected industrial ecosystems. This transformation is driven by embedded intelligence and the demands of digital manufacturing.
Integrated motor-driver-actuator packages combine drive electronics and the mechanical actuator into a single unit. Machine builders in packaging and semiconductor manufacturing adopt these solutions to simplify design and reduce cabinet space. This integration is bifurcating the market between vendors of all-in-one mechatronic solutions and suppliers of discrete, high-performance mechanical components for custom systems.
Stricter functional safety standards, including the EU's Machinery Directive and ISO 13849-1, impose rigorous requirements on component reliability. This trend compels actuator manufacturers to integrate features like safe torque off (STO) and provide extensive performance level documentation. Electric actuator designs are most affected, with suppliers investing heavily in certified safety functions to access the European factory automation market.
A notable shift in purchasing behavior involves OEMs moving from sourcing individual components toward procuring pre-integrated and tested sub-assemblies. This challenges traditional distributors and favors suppliers offering complete mechatronic solutions, including cabling and software configuration. This procurement model is most visible within Germany's specialized machine building sector and in the North American medical device industry.
Rotary Actuators Market Segmentation
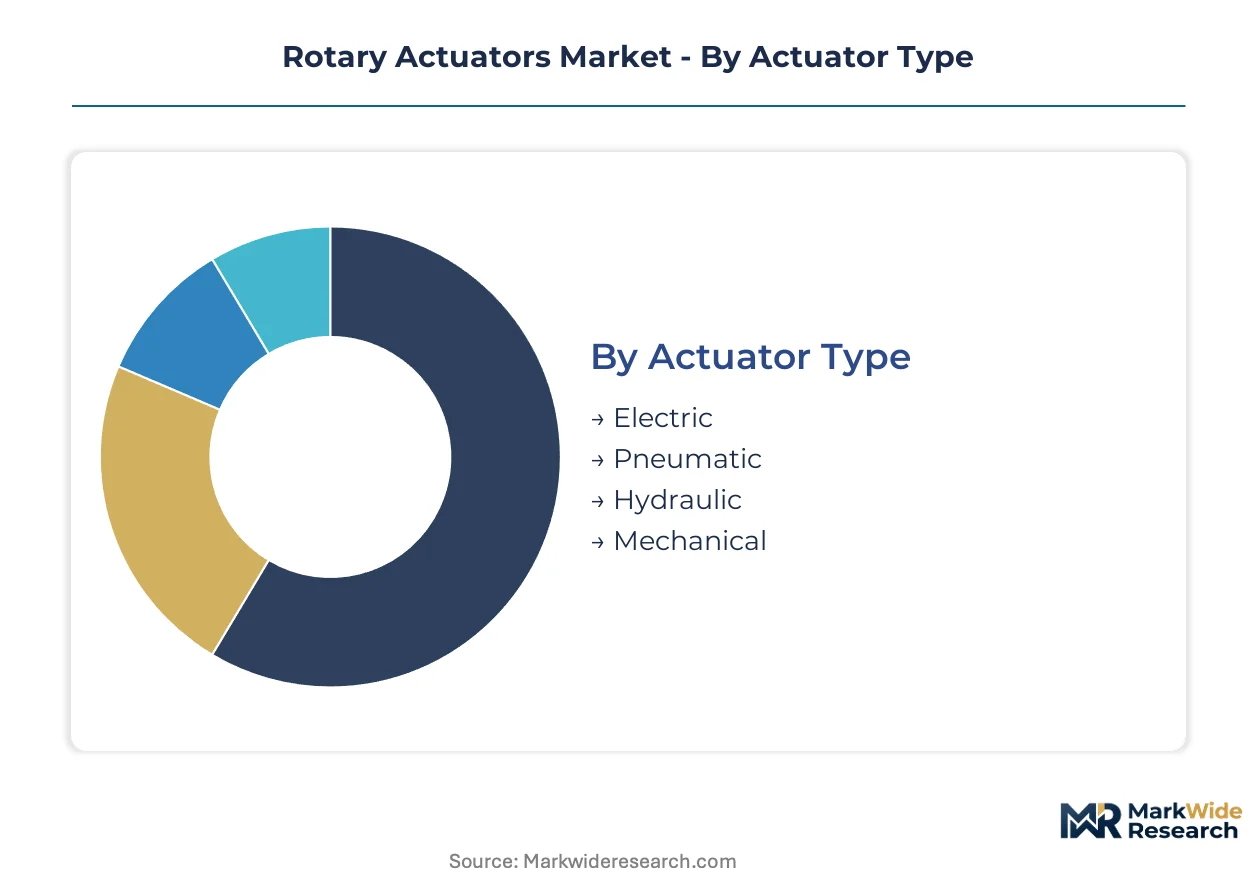
The rotary actuators market exhibits multifaceted segmentation, reflecting the diverse technical requirements and operational environments of modern industrial applications. Understanding these distinct segments is crucial for suppliers to tailor product development, refine market strategies, and address specific end-user demands effectively.
Actuator Type:
The channel mix for rotary actuators varies significantly based on their power source, influencing distribution and procurement pathways.
- Electric:These actuators convert electrical energy into precise rotational motion, often integrating servo motors for advanced control. Demand concentrates in advanced manufacturing hubs like Germany's automotive sector, driven by Industry 4.0 adoption requiring integrated IIoT capabilities.
- Pneumatic:Utilizing compressed air, these actuators produce angular motion for various industrial tasks, favored for their simplicity and cost-effectiveness.
- Hydraulic:Employing pressurized fluid, hydraulic actuators generate significant torque and force for robust rotational movement. Heavy-duty valve automation in the oil and gas sector relies on these systems, where their superior torque density is critical for large-scale operations.
- Mechanical:These actuators use gears, linkages, or cams to convert linear or intermittent motion into controlled rotation, typically for simpler, lower-power applications.
Pneumatic actuators dominate the installed base for cost-sensitive applications. Electric actuators are where expansion concentrates, driven by precision and efficiency demands.
Technology:
Different rotary actuator technologies reflect varying cost tiers and performance envelopes, dictating their suitability for specific industrial requirements.
- Stepper Motors:These motors provide discrete angular movements through a series of electrical pulses, suitable for open-loop control in applications requiring repeatable positioning.
- Servo Motors:Offering precise positional control and dynamic response through closed-loop feedback systems, servo motors are critical for high-performance automation. Demand from robotics and semiconductor manufacturing drives their adoption, where accuracy and speed are paramount.
- Rack and Pinion:This technology converts the linear motion of a piston into rotary motion via a rack engaging a pinion gear. These are commonly used in valve automation for quarter-turn valves, providing robust and reliable operation in industrial processes.
- Scotch Yoke:Scotch yoke mechanisms convert linear motion into rotary motion, offering high torque output and a compact design for specific valve operations.
- Worm Gear:Worm gear actuators utilize a worm screw engaging a worm wheel to achieve high gear ratios and self-locking capabilities, often found in heavy-duty positioning systems.
Servo motor technologies attract significant investment for their precision capabilities. Rack and pinion designs maintain a consistent presence across general industrial applications.
Application:
Rotary actuators find diverse utility across industrial applications, each demanding specific performance characteristics and environmental tolerances.
- Packaging Equipment:This sector employs actuators for precise positioning, gripping, and conveying tasks in automated lines, optimizing production efficiency.
- Robotics:Robotics applications require compact, high-precision actuators for joint articulation and end-effector control, critical for complex movements. Investment in industrial robotics, particularly in Japan's electronics industry, drives this segment's expansion.
- Valve Automation:Actuators integrate into valve systems to open, close, and regulate fluid flow in various industrial pipelines, ensuring process control and safety.
- Aerospace Systems:This sector utilizes lightweight, high-torque actuators for flight control surfaces and landing gear mechanisms, where reliability is paramount. Modernization programs for commercial and military aircraft necessitate actuators meeting stringent aerospace certifications.
- Marine Controls:Marine applications require durable actuators for steering systems, propulsion control, and cargo handling in harsh, corrosive environments.
Robotics applications represent the fastest-growing segment by value. Valve automation consistently generates high volume demand across process industries.
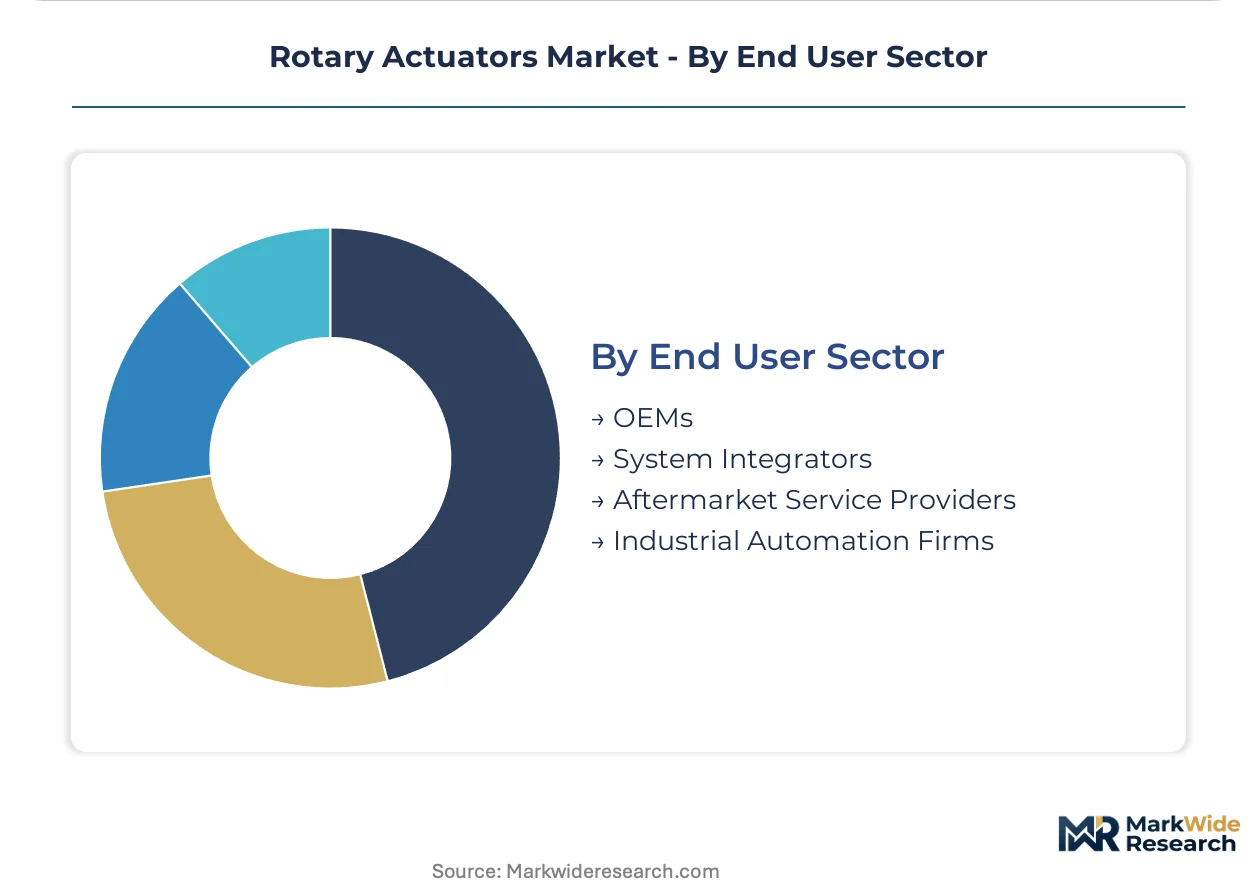
End User Sector:
Different end-user sectors engage with rotary actuator suppliers through distinct purchasing models and integration requirements.
- OEMs (Original Equipment Manufacturers):OEMs incorporate rotary actuators directly into their machinery and equipment during the manufacturing process. German machine builders and Japanese electronics manufacturers represent significant OEM demand for pre-integrated mechatronic solutions.
- System Integrators:These entities design and implement complete automation solutions for end-users, sourcing actuators as components within larger projects. These firms often require specialized mechatronics expertise to integrate smart actuators with legacy factory control systems.
- Aftermarket Service Providers:Aftermarket service providers focus on the maintenance, repair, and replacement of actuators for existing industrial installations, ensuring operational continuity.
- Industrial Automation Firms:These firms develop and deploy comprehensive automation platforms, often incorporating advanced rotary actuator solutions for factory modernization.
OEM engagements typically involve high volume contracts with competitive pricing. Aftermarket service provision offers stable, higher-margin revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for rotary actuators shows asymmetry, with premium solutions commanding higher margins in Germany, while cost-sensitive markets like China prioritize volume. This regional divergence influences product development and supply chain strategies. Demand for advanced mechatronic solutions is particularly strong in mature industrial economies.
Germany
Demand for high-precision electric actuators in Germany's automotive sector and specialized machine building drives innovation. The EU's Machinery Directive and CE marking requirements impose strict safety and performance standards. Bavaria and North Rhine-Westphalia are key industrial clusters, focusing on advanced manufacturing and automation.
Japan
Japan's electronics industry and robotics manufacturing fuel significant demand for compact, high-precision servo actuators. METI initiatives support advanced automation and smart factory development. Tokyo and Osaka Bay areas concentrate robotics and semiconductor equipment production, fostering mechatronics integration.
United States
Investment in aerospace modernization and medical automation sustains demand for high-reliability, lightweight actuators across the United States. OSHA and UL/ATEX certifications are critical for components used in hazardous industrial environments. The Pacific Northwest and Greater Boston areas host aerospace and medical device manufacturing hubs.
China
China's rapid industrial automation expansion and electric vehicle manufacturing drive high volume demand for rotary actuators. GB standards influence product design and market access for industrial components. The Yangtze River Delta and Pearl River Delta regions are major centers for robotics and general industrial machinery production.
South Korea
South Korea's advanced electronics and automotive sectors require high-performance actuators for assembly lines and robotics. MFDS regulations apply to medical device components, influencing actuator design for healthcare applications. The Seoul Capital Area and Busan-Ulsan region house major automotive and electronics manufacturing facilities.
Rotary Actuators Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the rotary actuators market, creating distinct competitive arenas. The market exhibits a tiered structure, with specialized mechatronics firms offering high-precision, integrated solutions alongside volume manufacturers of standard components. Strategic archetypes include integrated automation providers, niche component specialists focused on specific applications like aerospace, and regional suppliers catering to local industrial needs. Product portfolio diversification, often through advanced sensor integration, and strategic partnerships to expand market access are dominant competitive moves.
Specialists in integrated automation platforms, such as Rockwell Automation, Inc., offer comprehensive control solutions for complex industrial applications. These firms cater to advanced manufacturing hubs requiring seamless system integration. Parker Hannifin Corp. exemplifies a diversified motion and control technology provider, serving a broad array of end markets with its extensive product portfolio. SMC Corporation maintains a strong position in pneumatic control systems, which are essential for factory automation in cost-sensitive segments globally. These companies anchor different value propositions, from high-precision mechatronics to robust, economical solutions.
| Leading Market Players |
|---|
| ABB Ltd. |
| Emerson Electric Co. |
| Rockwell Automation, Inc. |
| Moog Inc. |
| Parker Hannifin Corp. |
| Curtiss-Wright |
| Flowserve Corporation |
| SMC Corporation |
| Rotork plc |
Cost & Logistics Intelligence
Project-based contracts for advanced rotary actuators lock in material supply and provide pricing visibility for specialized components. These agreements help manage the complex integration requirements for high-precision systems.
Pricing Analysis
Configured-to-order pricing commands a premium for high-precision electric actuators, contrasting with transactional models for standard pneumatic units. Price differentiation stems from precision capabilities, IIoT integration, and specific safety certifications like UL/ATEX. Pricing pressure in cost-sensitive pneumatic segments arises from high-volume manufacturing in Asia. Basic packaging machinery OEMs exhibit the highest price sensitivity, while aerospace and medical device manufacturers prioritize performance over cost.
Supply Chain Analysis
Port congestion and container availability impact inbound logistics costs for specialized actuator components, particularly from Asian suppliers. Actuator manufacturing concentrates in Germany for advanced electric units, Japan for high-precision servo motors, and China for high-volume pneumatic systems. The industry sources rare earth magnets, specialized semiconductors, and high-grade steel, creating single-source vulnerabilities for certain integrated circuit boards. Distribution runs through direct OEM engagements for integrated solutions and via industrial distributors for standard components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rotary actuators market presents a significant service-attach opportunity, with IIoT-enabled predictive maintenance subscriptions expanding faster than initial hardware sales. This shift offers new avenues for recurring revenue streams.
For Market Incumbents:
Shield core electric actuator market share by investing heavily in advanced functional safety certifications for European markets. Incumbents must also expand IIoT platform integration capabilities to counter emerging specialized mechatronics firms. Deepening R&D in miniaturization for medical and robotics applications mitigates margin pressure from commoditized pneumatic units. Control over critical component supply chains remains a vital lever.
For New Entrants and Emerging Players:
Differentiate on specialized mechatronics expertise for miniaturized actuators in medical automation and surgical robotics. White-space opportunities exist in developing energy-harvesting actuators for remote industrial applications. The North American medical device industry represents a penetrable segment for high-precision, low-volume solutions. A compelling go-to-market angle involves offering pre-integrated and tested sub-assemblies directly to OEMs.
For Investors and Strategic Acquirers:
The market sits at a growth phase that favors specialized mechatronics firms capable of integrating software and hardware. Long-term viability is strong, driven by the ongoing Industry 4.0 adoption and robotics investment across manufacturing. Acquisition targets include companies with proprietary IIoT sensor platforms or deep expertise in functional safety certifications. A key signal to watch is the accelerating shift by OEMs towards procuring pre-integrated actuator sub-assemblies.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Integrated Motor-Driver-Actuator Packages | Machine builders in packaging and semiconductor manufacturing gain simplified design and reduced cabinet space. |
| Invest in Functional Safety Certifications (e.g., ISO 13849-1) | Access to the European factory automation market requires rigorous compliance with component reliability standards. |
| Expand IIoT-Enabled Predictive Maintenance Services | This offers recurring revenue streams beyond hardware sales and improves overall equipment effectiveness for end-users. |
| Target Miniaturized Actuators for Medical Automation | The growing field of laboratory automation and surgical robotics demands high-precision, cleanroom-compatible components. |
| Form Strategic Partnerships with Robotics OEMs | Collaborations with Japanese electronics manufacturers and German automotive suppliers accelerate new product adoption. |
Research Approach
Desk research of industry association reports, technical journals, and patent databases preceded structured interviews with plant engineers, OEM procurement managers, and R&D directors. This primary research was further validated through discussions with system integrators. A comprehensive approach combined both bottom-up market sizing and top-down validation to ensure data accuracy. Secondary data from company financial filings also informed the analysis.
Variance decomposition isolated the impact of key market drivers and restraints across the analysis window. The analytical framework modeled actuator type, technology, application, and end-user sector, alongside regional adoption patterns. Compound annual growth rates were derived from historical growth trends and projected investment cycles in automation. Industrial robotics investment rates and aerospace modernization budgets served as critical forecast inputs.
Material uncertainties — including geopolitical shifts and major supply chain disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained industrial automation investment and stable technological progression. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Industrial Automation Products Market
Industrial Automation
Global Operational Technology Market
Industrial Automation
Human Machine Interface (HMI) Market
Industrial Automation
Predictive Maintenance Market
Industrial Automation
Global Industrial Control and Factory Automation Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
US Smart Manufacturing Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Rotary Vector (RV) Reducer Market
Industrial Automation
Global Automated Sortation System Market
Industrial Automation
Magnetic Grippers Market
Industrial Automation
Global Mining Automation Consumption Market
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Cold Storage AGV Market