
 Resonator Design Software Market | 2026-2036
Resonator Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Resonator Design Software Market Insights
The resonator design software landscape is restructuring around a sharp split between premium multiphysics suites and stripped-down acoustic solvers. ANSYS leverages its breadth across finite element and electromagnetic modules to anchor enterprise accounts with bundled annual licenses. COMSOL competes through physics customization depth that sustains loyalty among research labs solving nonlinear cavity problems.
Resonator design software encompasses computational tools that model vibrational, electromagnetic, or optical resonance phenomena using numerical methods such as finite element meshing with tetrahedral or hexahedral discretization down to sub-wavelength scales. These platforms enable engineers to predict quality factors, mode shapes, and frequency response before physical prototyping in applications spanning RF filters, laser cavities, MEMS gyroscopes, and ultrasonic transducers. Integrated Solutions currently dominate revenue as vendors bundle electromagnetic simulation with thermal and mechanical solvers to capture cross-physics contracts from automotive radar and 5G base station developers. Cloud-Based deployment is expanding fastest among educational institutions and mid-sized engineering firms that lack capital for on-premise GPU clusters but require burst compute for parametric sweeps.
ISO 9001 quality management standards shape vendor eligibility for aerospace and defense supply chains, while the U.S. Department of Commerce export controls under EAR Category 3D001 restrict electromagnetic simulation code transfers to specific destinations. The EU AI Act and emerging software transparency requirements will add compliance layers for autonomous resonator tuning algorithms embedded in next-generation platforms. Stakeholders must weigh the long-term cost of cloud dependency against the strategic value of maintaining captive solver infrastructure as geopolitical access rules tighten.
Market Dynamics
Export control tightening around dual-use electromagnetic simulation code is fragmenting vendor access and forcing procurement localization across aerospace supply chains.
Growth Catalysts
- 5G mmWave Infrastructure Rollouts:Base station OEMs in South Korea and Japan require high-frequency resonator optimization for sub-6 GHz and mmWave filter banks, pulling demand for multiphysics simulation bundles.
- EU AI Act Compliance Pathways:Autonomous tuning algorithms for optical cavities now face transparency mandates, creating upgrade cycles for software with embedded explainability modules.
- MEMS Gyroscope Miniaturization:Consumer drone and automotive stability control programs in Germany's precision engineering corridor are contracting resonator design services for sub-millimeter scale devices.
Market Restraints
- GPU Compute Cost Volatility:Cloud-based parametric sweeps depend on NVIDIA A100/H100 availability, with spot pricing fluctuations compressing margins for mid-sized engineering firms.
- EAR Category 3D001 Licensing Friction:U.S. Department of Commerce export controls delay code transfers to Chinese aerospace contractors, blocking revenue from a significant addressable base.
- Open-Source Acoustic Solver Substitution:Free alternatives like Elmer FEM and deal.II are capturing university research budgets that once licensed commercial cavity analysis tools.
Strategic Opportunities
- India PLI Scheme for Semiconductors:Domestic fab construction under India's production-linked incentive program will require RF filter design capabilities for indigenous 5G chipset programs.
- Quantum Photonics Integration:Convergence of nonlinear cavity solvers with cryogenic thermal modules addresses emerging demand from superconducting qubit foundries.
- Outcome-Based Licensing Models:Subscription tiers tied to successful tape-out verification rather than seat counts are penetrating fabless design houses in Taiwan.
Industry Challenges
- Multiphysics Talent Scarcity:Engineers capable of bridging electromagnetic, thermal, and mechanical domains command premium compensation, constraining vendor scaling.
- ISO 9001 Certification Timelines:Aerospace vendor qualification cycles extend 18-24 months, delaying revenue recognition from defense contractor accounts.
- Legacy CAD Integration Complexity:Siemens NX and Dassault CATIA interoperability gaps force custom API development for enterprise customers with entrenched workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resonator Design Software Market |
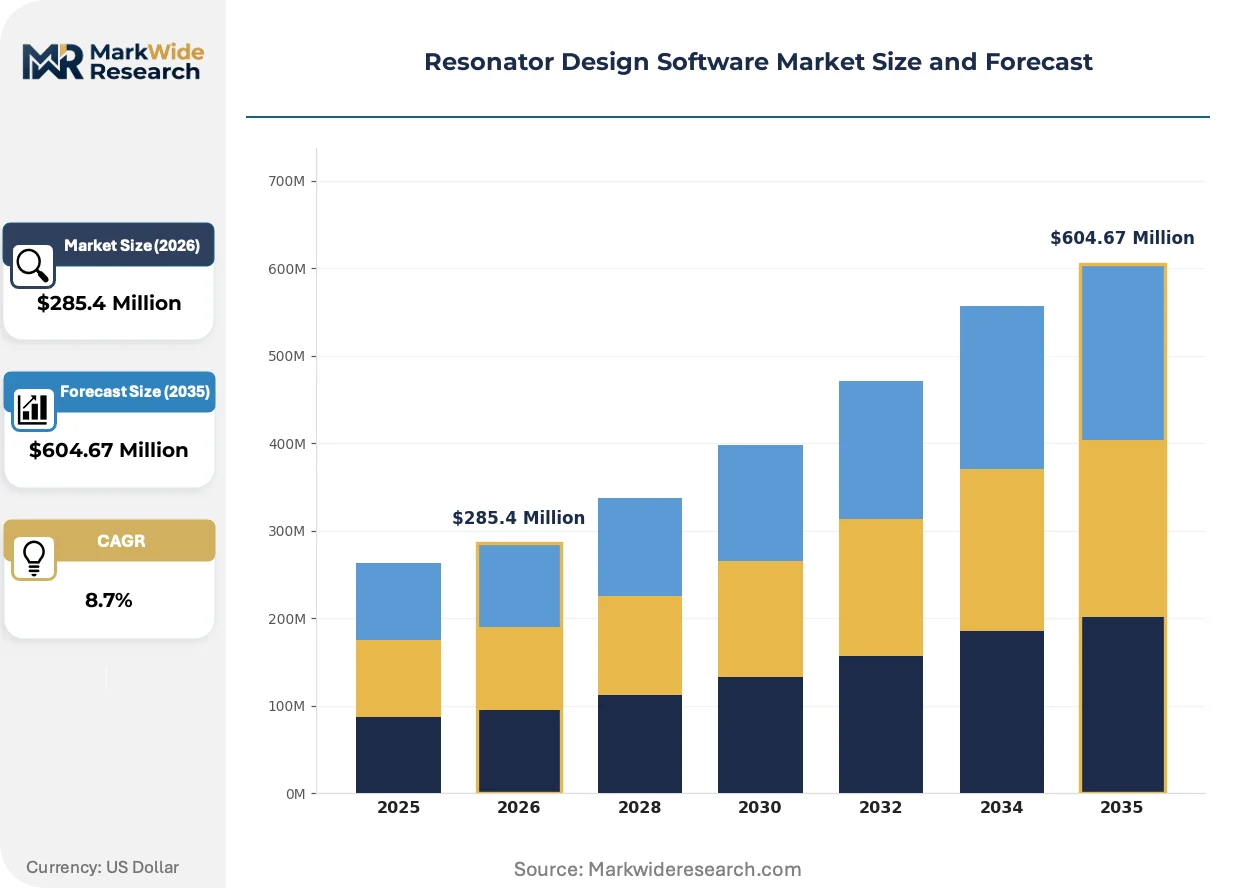
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Integrated Solutions, Web-Based Platforms, Mobile Applications End User: Engineering Firms, Educational Institutions, Research Labs, Manufacturing Companies Technology: Finite Element Analysis, Computational Fluid Dynamics, Acoustic Simulation, Electromagnetic Simulation Deployment: On-Premise, Cloud-Based, Hybrid, Open Source |
| Companies Covered | ANSYS, COMSOL, CST Studio Suite, Sonnet Software, Agilent Technologies, Synopsys, Mentor Graphics, Lumerical, RP Photonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resonator Design Software Market Trends and Innovations
Computational methods are converging with hardware-aware optimization, compressing design cycles from months to weeks while embedding compliance documentation directly into simulation workflows.
Physics-informed neural networks for resonator eigenmode prediction are electrifying traditional finite element workflows. RF filter designers at automotive radar suppliers are adopting these surrogates for real-time geometry optimization. The technology is compressing overnight batch jobs into interactive design sessions that iterate during working hours.
REACH restrictions on per- and polyfluoroalkyl substances are forcing material library updates across European resonator design platforms. Vendors must recertify dielectric substrate models for PFAS-free alternatives in high-frequency laminates. German automotive radar developers are prioritizing software vendors with validated halogen-free material datasets.
Subscription-to-outcome contracting is displacing perpetual licenses in mid-market engineering services. Design bureaus in Italy and Spain now pay only for simulation runs that pass foundry validation checks. This model is penetrating photonics foundry partnerships where tape-out success determines payment.
Resonator Design Software Market Segmentation
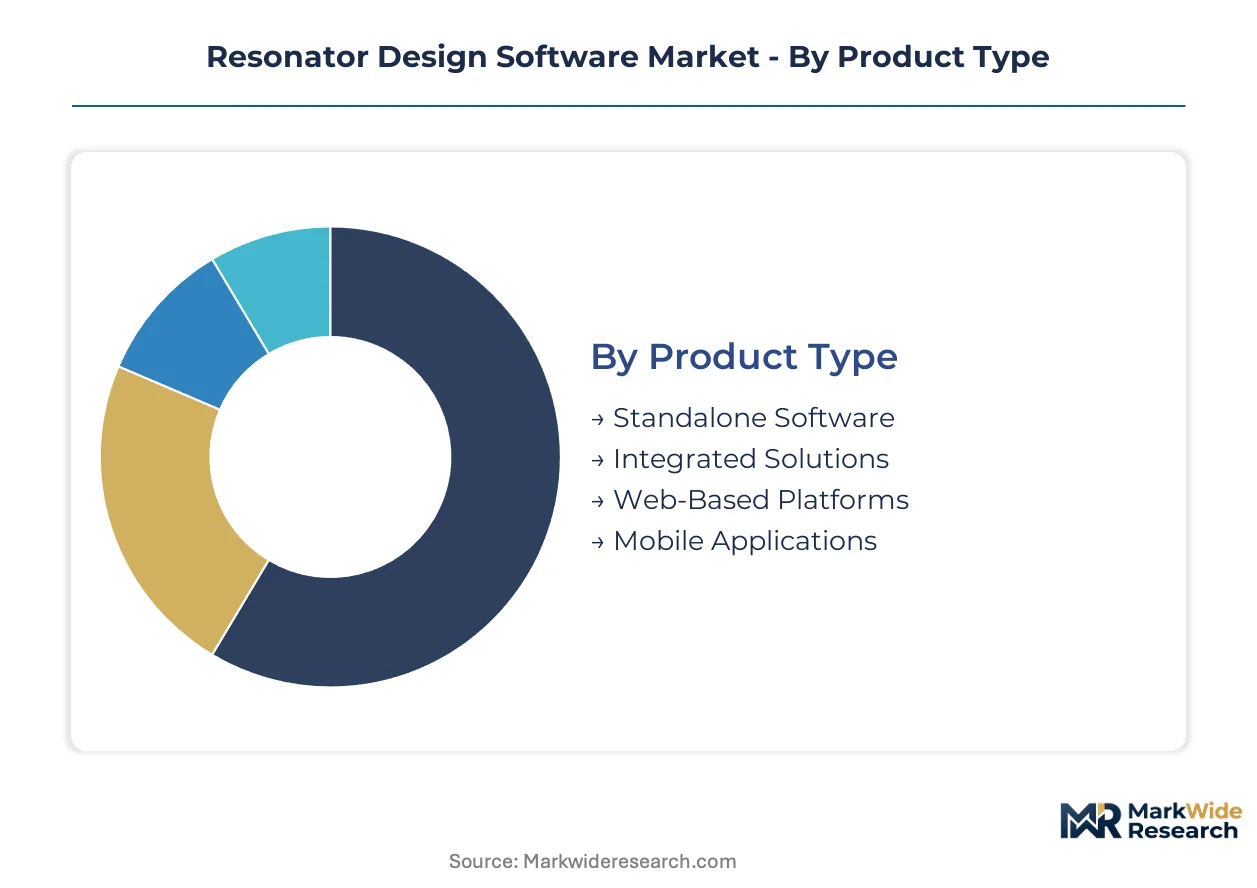
Resonator design software segments diverge sharply by capital intensity and technical integration depth. Procurement patterns cluster around bundled multiphysics suites for enterprise accounts versus modular cloud deployments for resource-constrained engineering teams.
Product Type:
Integrated Solutions demand the heaviest upfront capital commitment through annual enterprise licenses and mandatory GPU cluster infrastructure. Standalone Software requires lower initial outlay but incurs hidden integration costs with legacy CAD workflows.
- Integrated Solutions:Bundled electromagnetic, thermal, and mechanical solvers enable cross-physics contracts from automotive radar developers in Germany and 5G base station OEMs in South Korea. Aerospace contractors in the United States prioritize these suites for ISO 9001-compliant supply chain qualification.
- Standalone Software:Specialized acoustic or electromagnetic modules serve mid-sized engineering firms with focused cavity design needs. Italian and Spanish design bureaus favor these for outcome-based licensing tied to foundry validation.
- Web-Based Platforms:Browser-accessible solvers eliminate local compute infrastructure for educational users.
- Mobile Applications:Lightweight geometry preview and parameter monitoring tools for field engineers.
Integrated Solutions absorb the bulk of installed capacity; Web-Based Platforms are expanding most quickly among institutions lacking capital for on-premise clusters.
End User:
Research Labs generate the steepest per-seat licensing revenue through specialized nonlinear cavity physics requirements. Educational Institutions concentrate volume through site-wide academic pricing but at suppressed per-license yields.
- Engineering Firms:Mid-sized design bureaus in Taiwan and Italy drive outcome-based contracting innovation, paying only for simulation runs passing tape-out verification. These firms bridge fabless semiconductor houses with foundry partners.
- Manufacturing Companies:Precision engineering clusters around Munich and Stuttgart contract resonator design services for MEMS gyroscope miniaturization in automotive stability control and consumer drone programs.
- Research Labs:University and national laboratory users demand physics customization depth for nonlinear cavity problems.
- Educational Institutions:Engineering schools deploy cloud-based burst compute for parametric sweep training.
Manufacturing Companies anchor current revenue concentration; Engineering Firms are climbing the fastest through outcome-based model adoption.
Technology:
Electromagnetic Simulation commands premium pricing through EAR Category 3D001 export control complexity and specialized talent scarcity. Acoustic Simulation faces acute price pressure from open-source substitution in university settings.
- Electromagnetic Simulation:High-frequency resonator optimization for sub-6 GHz and mmWave filter banks pulls demand from South Korean and Japanese base station OEMs. U.S. Department of Commerce licensing friction blocks Chinese aerospace contractor access.
- Finite Element Analysis:Tetrahedral and hexahedral meshing down to sub-wavelength scales underpins quality factor and mode shape prediction across RF filter and laser cavity applications.
- Acoustic Simulation:Ultrasonic transducer and MEMS resonator modeling faces competition from Elmer FEM and deal.II in European university budgets.
- Computational Fluid Dynamics:Thermal-fluid coupling for cryogenic resonator environments in superconducting qubit foundries.
Finite Element Analysis carries the deepest installed base; Electromagnetic Simulation is gaining share fastest through 5G infrastructure rollout timing.
Deployment:
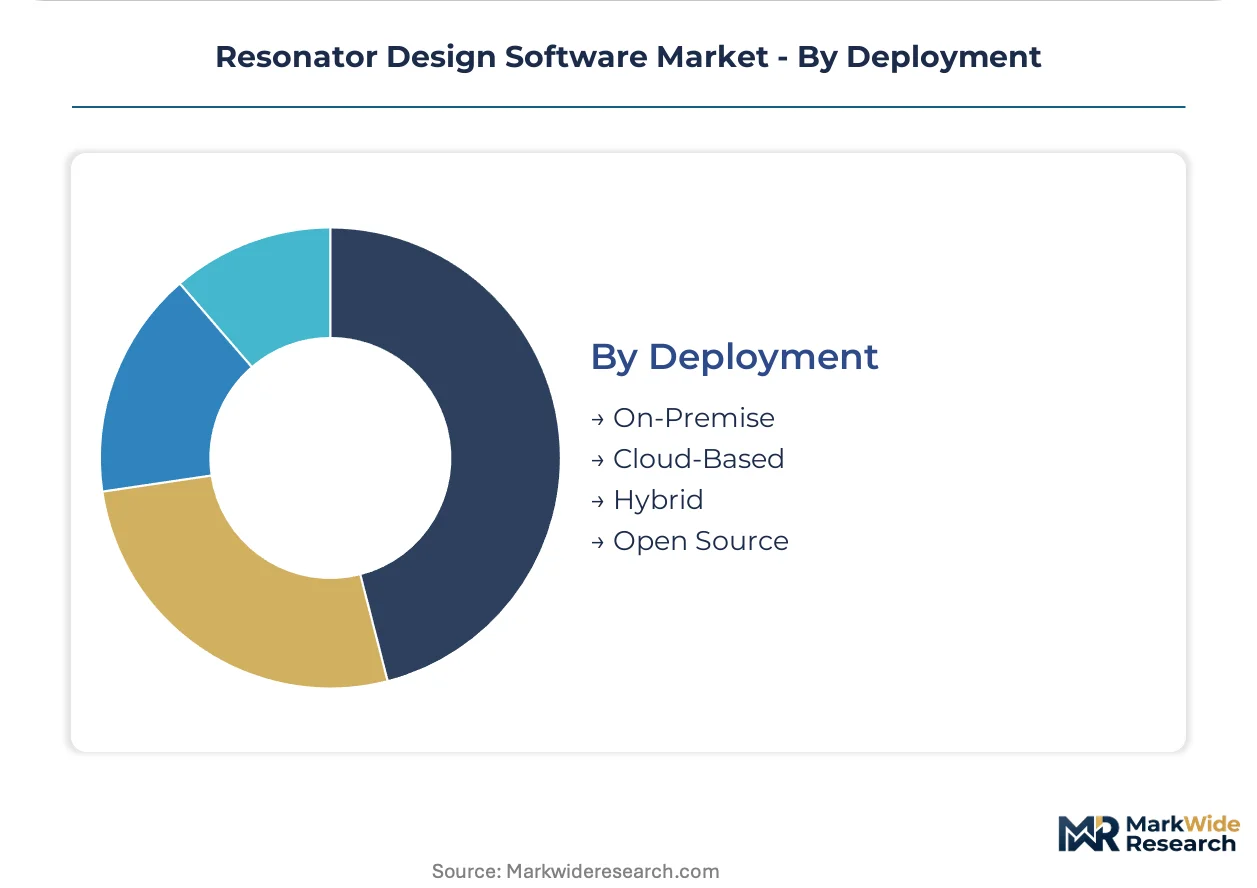
On-Premise deployments demand captive GPU infrastructure investment that only enterprise accounts with predictable utilization can justify. Cloud-Based alternatives convert capital expenditure to operational spend with spot pricing volatility exposure.
- Cloud-Based:Burst compute for parametric sweeps serves mid-sized engineering firms without capital for NVIDIA A100/H100 clusters. GPU spot pricing fluctuations compress margins for Italian and Spanish design bureaus running large-scale optimization jobs.
- Hybrid:Sensitive electromagnetic simulation cores remain on-premise while non-critical preprocessing shifts to cloud instances.
- On-Premise:Full captive solver infrastructure for defense contractors managing EAR-controlled code access.
- Open Source:Free alternatives capture university research budgets and constrain commercial acoustic solver pricing.
On-Premise retains the largest footprint in defense-aerospace supply chains; Cloud-Based is expanding most quickly among commercial engineering services firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich and Stuttgart anchor the precision engineering corridor driving European resonator design software procurement, while South Korean and Japanese base station OEMs pull demand for mmWave optimization tools.
United States
Aerospace contractors in California and Texas require electromagnetic simulation suites for defense radar and satellite communication programs. The Department of Commerce enforces EAR Category 3D001 export controls that restrict code transfers to Chinese aerospace firms. Boston-area research labs contract specialized nonlinear cavity physics customization from commercial vendors.
Germany
Automotive radar developers in Baden-Württemberg and Bavaria optimize MEMS gyroscopes for stability control systems in premium vehicles. REACH regulations mandate PFAS-free dielectric substrate recertification for high-frequency laminate models. Stuttgart's precision engineering cluster contracts resonator design services for sub-millimeter scale consumer drone components.
South Korea
Base station OEMs in Seoul and Suwon demand multiphysics bundles for sub-6 GHz and mmWave filter bank development. The national telecommunications regulator shapes spectrum allocation timelines that accelerate RF component design cycles. Gyeonggi Province semiconductor foundries integrate resonator simulation with indigenous 5G chipset programs.
Japan
Telecommunication equipment manufacturers in Tokyo and Osaka optimize high-frequency resonators for dense urban 5G deployment. METI industrial policy supports domestic electromagnetic simulation capability retention for critical infrastructure supply chains. Yokohama-based engineering firms adopt outcome-based licensing tied to foundry tape-out verification.
India
Domestic fab construction under the PLI scheme for semiconductors requires RF filter design capabilities for indigenous 5G programs. The national standards body coordinates electromagnetic simulation tool validation protocols for defense supply chain entry. Karnataka and Telangana engineering services firms deploy cloud-based burst compute for parametric sweep optimization.
Resonator Design Software Market Competitive Landscape
Capital-heavy integrated suite producers compete with asset-light specialized module vendors across the resonator design software landscape. The vendor base clusters around three tiers: premium multiphysics platforms commanding annual enterprise licenses, mid-market modular tools with CAD interoperability APIs, and cloud-native entrants converting capital expenditure to operational spend. Strategic differentiation concentrates on physics customization depth versus bundled cross-physics convenience. Dominant competitive moves include outcome-based licensing contracts displacing perpetual seats and strategic partnerships with photonics foundries embedding simulation validation into tape-out workflows.
Within the premium multiphysics tier, ANSYS and COMSOL occupy positions as reference anchors for enterprise procurement decisions. ANSYS exemplifies the breadth-driven archetype spanning finite element and electromagnetic modules, while COMSOL represents physics customization depth sustaining research lab loyalty. CST Studio Suite sits within the specialized electromagnetic simulation segment where high-frequency optimization commands premium pricing through export control complexity. These three vendors collectively illustrate the strategic split between bundled convenience and technical depth that structures competitive positioning across aerospace, automotive radar, and telecommunications verticals.
| Leading Market Players |
|---|
| ANSYS |
| COMSOL |
| CST Studio Suite |
| Sonnet Software |
| Agilent Technologies |
| Synopsys |
| Mentor Graphics |
| Lumerical |
| RP Photonics |
| Others |
Pricing and Supply Chain Analysis
Aerospace and defense contractors in the United States and Germany anchor procurement volume for resonator design software, locking vendors into annual enterprise licensing with ISO 9001 certification premiums. Their concentration of buying power enforces value-based contracting tied to tape-out verification success rather than seat counts, compressing margins for mid-tier suppliers.
Pricing Analysis
Outcome-based pricing tied to foundry verification success now dominates mid-market engineering services in Taiwan and Italy. Three-tier pricing structure across premium, standard, and economy levels separates ISO 9001-certified aerospace bundles from academic site licenses and open-source alternatives. Cost compression in the standalone acoustic solver tier intensifies because Elmer FEM and deal.II capture European university budgets. Educational institutions exhibit the highest price sensitivity, while defense contractors accept certification premiums without negotiation.
Supply Chain Analysis
Regional distribution centers in Germany, South Korea, and the United States warehouse GPU cluster hardware for on-premise deployments while cloud instances burst through Singapore and Frankfurt hubs. NVIDIA A100/H100 availability in Taiwan and Japan feeds from foundry partnerships with base station OEMs. Single-source vulnerability around NVIDIA accelerator supply creates chokepoint exposure for parametric sweep workloads. Distribution runs through direct vendor sales teams for aerospace accounts and channel partners for mid-sized engineering firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resonator design software is consolidating around vendors with captive multiphysics depth, as EAR Category 3D001 licensing friction and ISO 9001 qualification timelines force weaker players toward niche module specialization or exit.
For Market Incumbents: Deploy physics-informed neural network integration to compress overnight batch jobs into interactive sessions, defending against cloud-native entrants. Anchor enterprise accounts through backward integration into photonics foundry validation workflows, neutralizing the threat of outcome-based pricing disruption from Taiwanese design bureaus. For New Entrants and Emerging Players: Capture white-space in India's PLI-driven domestic fab construction, where RF filter design capability gaps outpace incumbent localization. Target cloud-based burst compute for Karnataka and Telangana engineering services firms, penetrating through browser-accessible solvers that eliminate GPU cluster capital requirements. For Investors and Strategic Acquirers: The window for entry favors specialized electromagnetic simulation boutiques with EAR-compliant code bases and existing aerospace contractor relationships. Watch for inflection when India's semiconductor standards body finalizes electromagnetic simulation tool validation protocols for defense supply chain entry, signaling procurement localization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding resonator solvers within Siemens NX and Dassault CATIA workflows captures entrenched automotive radar developers in Baden-Württemberg. |
| Strategic Partnership | Photonics foundry alliances in Gyeonggi Province tie simulation validation to tape-out success, locking in outcome-based revenue. |
| Acquisition of Specialist Firm | Absorbing cryogenic thermal module developers addresses superconducting qubit foundry demand from emerging quantum photonics integrators. |
| Geographic Expansion | Localizing sales and support in Stuttgart's precision engineering cluster captures MEMS gyroscope miniaturization contracts from automotive stability control programs. |
| Product Launch | REACH-compliant PFAS-free material libraries differentiate vendors for German automotive radar developers facing substrate recertification mandates. |
Research Methodology
Document review covered SEC filings from electromagnetic simulation vendors, EU AI Act regulatory drafts, and U.S. Department of Commerce EAR guidance, complemented by interviews with RF filter design leads at South Korean base station OEMs, MEMS engineering directors in Stuttgart's precision cluster, and procurement officers at Indian semiconductor fabs. Secondary validation drew from IEEE publication databases, TRAI spectrum allocation notices, and India's PLI scheme implementation reports. Bottom-up segment sizing triangulated against top-down aerospace and defense procurement budget analysis.
Historical revenue trajectories for ANSYS, COMSOL, and CST Studio Suite cross-referenced against panel input from 5G infrastructure program managers and quantum photonics foundry executives. Segmentation dimensions modeled deployment mode, end-user organization type, physics domain specialization, and regional regulatory cluster across the analysis window. CAGRs derived from multivariate regression against 5G base station deployment schedules, MEMS miniaturization roadmaps, and export control policy evolution scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NVIDIA GPU supply constraints, EAR licensing enforcement shifts, and open-source acoustic solver feature maturation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Interior Design Software Market
Software & Services
Airline Route Profitability Software Market
Software & Services
Global AB Testing Software Market
Software & Services
Global Business Management Software Market
Software & Services
Computer Assisted Translation Software Market
Software & Services
Europe Feedback Management Software Market
Software & Services
Live Software Market
Software & Services
E-Invoicing Software Market
Software & Services
Global Cloud Testing Market
Software & Services
Global Help Desk Software Market
Software & Services
Global Sales Engagement Platform Market
Software & Services
Semiconductor Fabrication Software Market
Software & Services
Multivariate Testing Software Market
Software & Services
Poland IT Software and Service Market
Software & Services
Medical E-Commerce Software Market
Software & Services
Live Chat Software Market