
 Hardware in the Loop Market | 2026-2036
Hardware in the Loop Market Size, Share, and Industry Trends Forecast 2026-2036
Hardware in the Loop Market Intelligence
The modularization of HIL test benches, allowing for customized configurations of real-time processors and signal conditioning devices, is broadening access for smaller engineering teams. National Instruments Corporation leverages its extensive hardware and software ecosystem to offer scalable solutions for aerospace and automotive clients. dSPACE GmbH specializes in high-fidelity simulation for autonomous driving validation, particularly within the German automotive sector. Vector Informatik GmbH differentiates through its focus on ECU testing and network communication analysis tools.
Hardware in the Loop (HIL) is a real-time simulation technique used to test complex embedded systems. It involves connecting a physical electronic control unit (ECU) to a simulation model that emulates the behavior of a complete system, such as a vehicle or aircraft, with response times often under one millisecond. The automotive OEM end-user segment commands the largest share, driven by electric vehicle testing applications. Within technology, Field-Programmable Gate Array (FPGA) based systems represent the fastest-growing segment due to their performance in high-frequency signal processing.
Functional safety standards like ISO 26262 for road vehicles and DO-178C for avionics software mandate exhaustive testing, directly driving HIL system adoption. Regulations from the US Environmental Protection Agency (EPA) and the EU's F-Gas Regulation on emissions also necessitate precise engine and powertrain control validation. Stakeholders must now decide between investing in comprehensive, high-cost platforms or adopting more flexible, modular systems for specific testing needs.
Market Dynamics
The central force shaping the market is the escalating complexity of embedded software, particularly within the automotive and aerospace sectors. The proliferation of advanced driver-assistance systems and the transition to electric powertrains demand exhaustive, real-time testing capabilities that only Hardware in the Loop simulation can provide at scale.
Growth Catalysts
- Functional Safety Mandates:The enforcement of standards like ISO 26262 for road vehicles compels automotive developers to conduct rigorous validation of safety-critical electronic systems, directly spurring HIL system adoption for repeatable and automated testing scenarios.
- Electric Vehicle Powertrain Development:The global shift to electric mobility creates immense demand for testing battery management systems, inverters, and electric motor controllers, for which HIL simulation is an essential development tool.
- ADAS Complexity:Automotive OEMs, especially in Germany and Japan, are accelerating HIL investment to validate the intricate sensor fusion and decision-making algorithms required for autonomous driving functionalities, ensuring system reliability before road trials.
Market Restraints
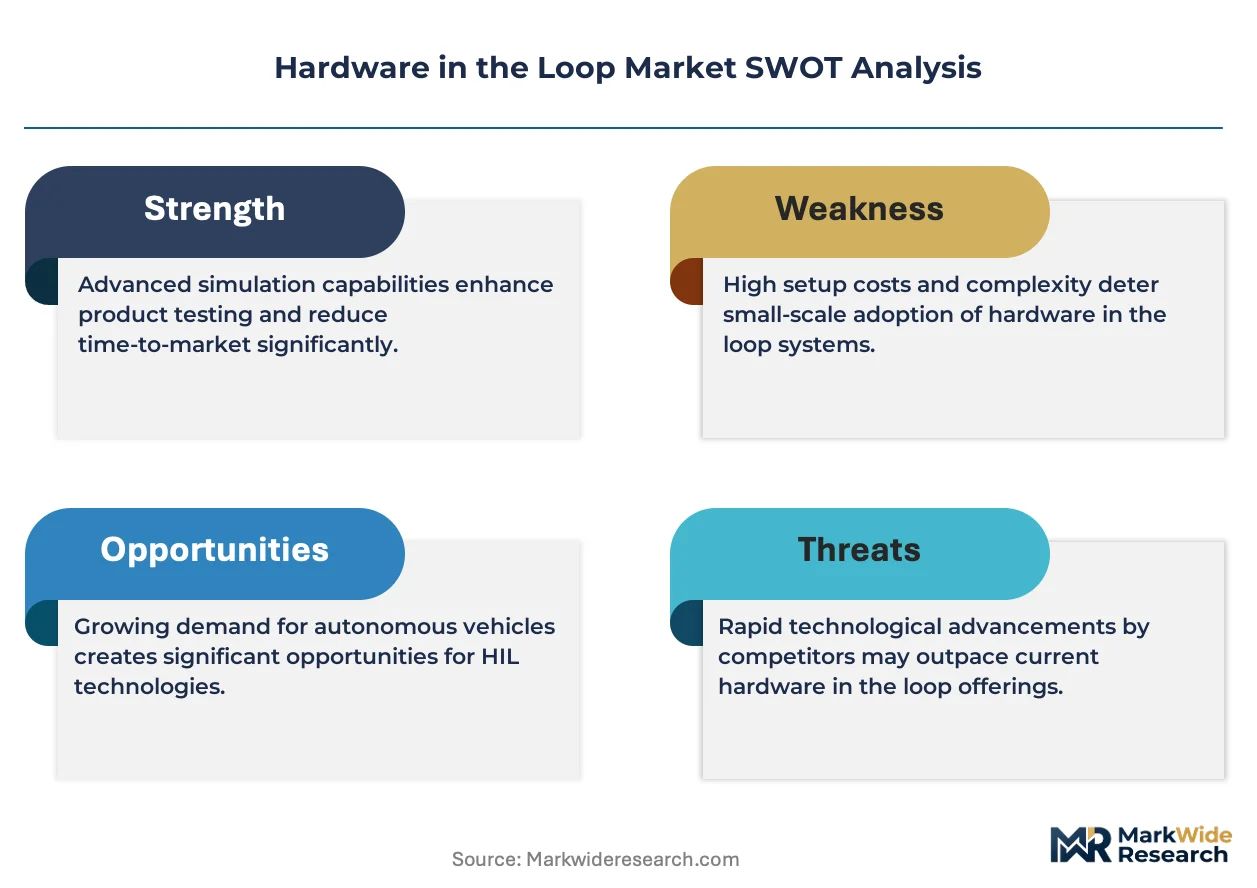
- High Capital Investment:The substantial upfront cost of comprehensive HIL systems, including real-time processors, signal conditioning hardware, and specialized software licenses, presents a significant barrier to entry for smaller companies and academic research institutions.
- Simulation Fidelity Limits:Accurately modeling the physics of high-frequency sensors, such as radar and LiDAR, or complex electromechanical interactions in real-time remains a persistent technical challenge, potentially limiting test coverage for certain edge cases.
- Vendor Concentration:The market for high-performance, turnkey HIL platforms is concentrated among a few specialized vendors, which can limit buyer negotiation power and slow down innovation cycles in specific niche application areas.
Strategic Opportunities
- Expansion into Industrial Automation:Applying HIL testing methodologies to the development of complex robotics, smart factory controllers, and industrial IoT devices presents a significant growth vector beyond the core automotive and aerospace segments.
- AI and Digital Twin Integration:Combining HIL simulators with AI-driven test case generation and digital twin models offers an opportunity to create predictive, self-learning validation platforms that can anticipate failures and optimize system performance.
- Modular System Adoption in Emerging Markets:Offering scalable, lower-cost modular HIL solutions provides an entry point into emerging automotive development hubs in India and Eastern Europe, where budgets are constrained but testing needs are growing.
Industry Challenges
- Specialized Talent Scarcity:A shortage of engineers with combined expertise in real-time systems, control theory, and specific domain knowledge like vehicle dynamics creates a bottleneck for deploying and effectively utilizing advanced HIL test benches.
- Integration with Legacy Systems:Engineering teams face significant operational hurdles when integrating modern HIL platforms with a diverse array of existing ECUs, proprietary communication protocols, and older test automation frameworks.
- Lack of Interface Standardization:The absence of universal standards for connecting I/O modules and software components from different vendors complicates the creation of truly open and flexible test systems, risking vendor lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hardware in the Loop Market |
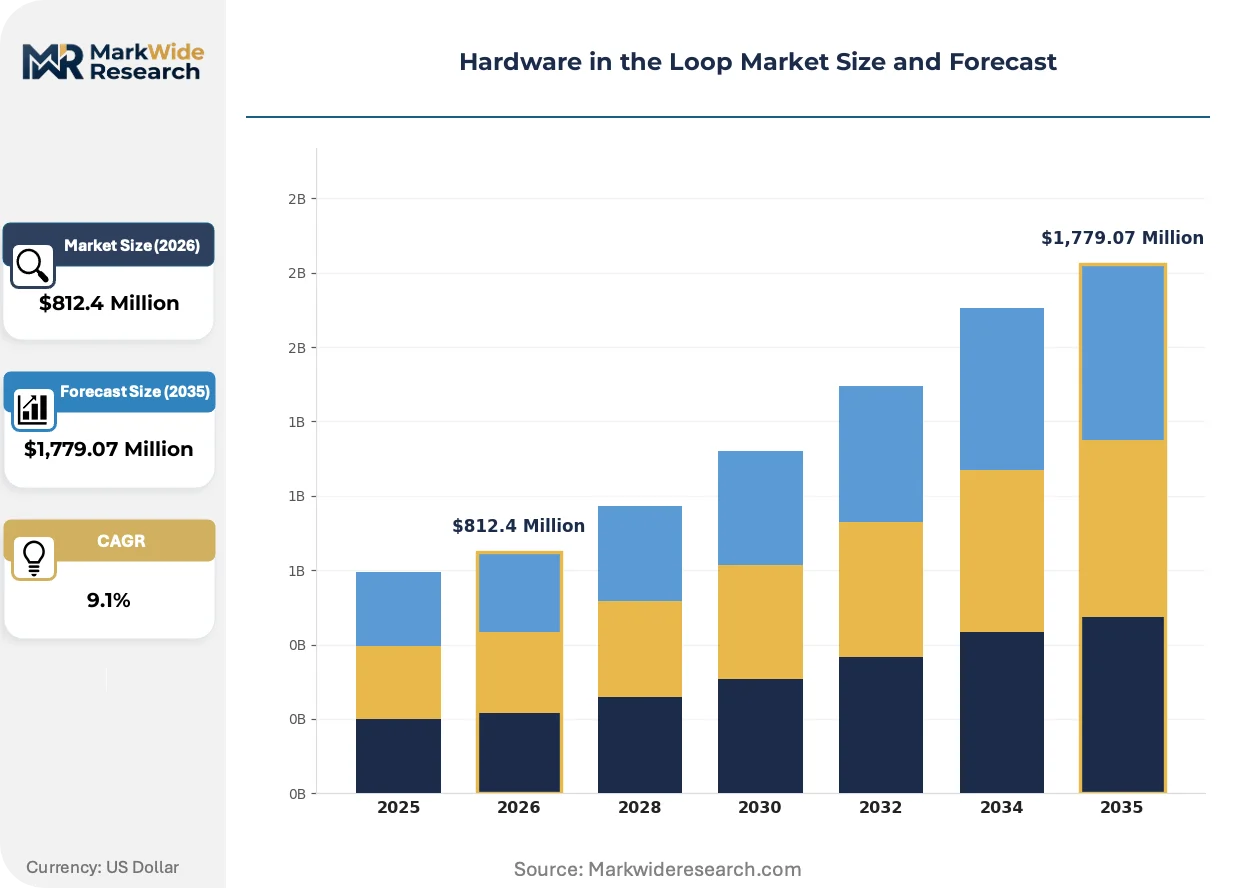
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,779.07 Million |
| CAGR (2026 – 2036) | 9.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Simulation Controllers, Real-Time Processors, Signal Conditioning Devices, Communication Interfaces Technology: Field-Programmable Gate Array, Digital Signal Processing, Embedded Systems, Microcontroller-Based Modules Application: Electric Vehicle Testing, Aerospace Control Systems, Industrial Automation, Robotics Validation End User: Automotive OEMs, Aircraft Manufacturers, Factory Automation Providers, Robotics Integrators |
| Companies Covered | Vector Informatik GmbH, Siemens, dSPACE GmbH, Elektrobit Automotive GmbH, Speedgoat GmbH, National Instruments Corporation, OPAL-RT Technologies, IPG Automotive GmbH, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hardware in the Loop Market Strategic Shifts & Innovations
A fundamental shift toward software-defined validation is redefining the market's trajectory. This evolution prioritizes flexible, reconfigurable test platforms that can adapt to rapid development cycles, moving beyond simple ECU verification to encompass full-system and network-level simulation.
Field-Programmable Gate Array (FPGA) technology provides the high-speed processing necessary for simulating complex physical systems and sensor inputs. Automotive and aerospace developers are rapidly adopting these systems for testing high-frequency components like electric motor controllers and radar sensors. FPGA-based simulation is unifying the execution of plant models and high-speed I/O protocols on a single hardware platform, which reduces latency and streamlines test bench architectures.
The European Union's AI Act introduces a risk-based framework for artificial intelligence systems, which directly impacts the validation of autonomous driving software. This regulation is forcing automotive developers to implement more structured and auditable testing processes for AI-powered perception and control algorithms. Consequently, HIL platforms are becoming critical tools for generating the evidence required to demonstrate compliance for high-risk AI applications in vehicles.
Customer purchasing behavior is moving away from monolithic, turnkey HIL systems toward more modular, platform-based procurement models. This change disrupts the traditional direct sales channel focused on large OEMs, creating space for value-added resellers and system integrators catering to startups and specialized engineering teams. This trend is particularly pronounced in the agile electric vehicle development sector in the United States and China.
Hardware in the Loop Market Segmentation
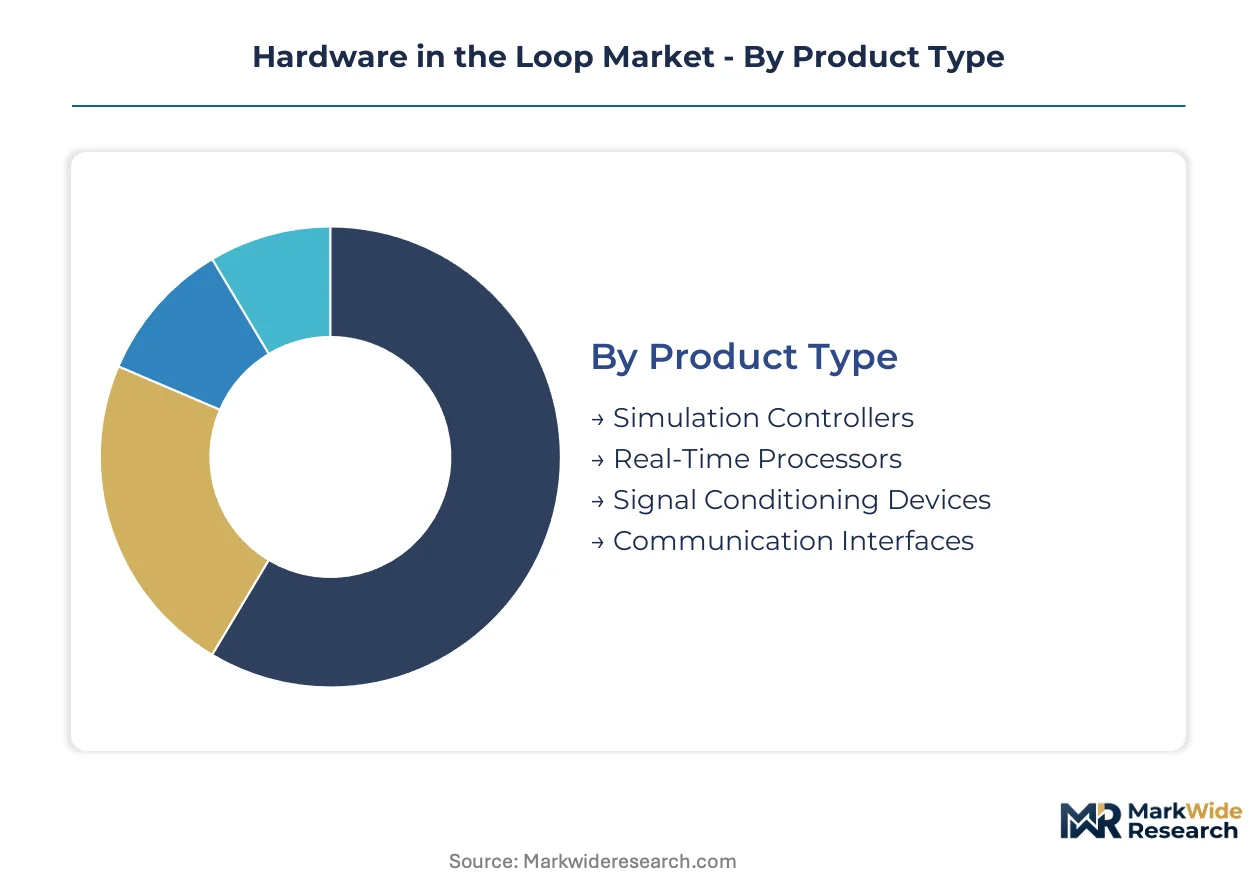
The Hardware in the Loop market analysis delineates distinct segments, reflecting the varied technological demands and application landscapes. Understanding these divisions helps pinpoint specific growth vectors and technological shifts influencing development and procurement. This granular view clarifies where innovation and investment are most active.
Product Type:
The core technical specifications of HIL systems are defined by their constituent hardware product types.
- Real-Time Processors:These units execute complex simulation models with deterministic timing, often under one millisecond, ensuring accurate emulation of physical systems. Automotive OEMs in Germany utilize these for rigorous validation of ADAS functions and electric powertrain controls.
- Signal Conditioning Devices:These components adapt real-world sensor and actuator signals to the voltage levels and formats required by the ECU under test, maintaining signal integrity. Aerospace clients integrate these for precise validation of flight control surfaces and avionics systems.
- Simulation Controllers:These manage the overall test execution, orchestrating the interaction between the real-time model and the physical ECU.
- Communication Interfaces:These modules enable data exchange between the HIL system and the ECU using protocols like CAN, FlexRay, and Ethernet.
Mature deployment sits with Communication Interfaces. Newer deployment is concentrated in Real-Time Processors.
Technology:
Performance differentiation drives the selection of specific HIL technologies for diverse simulation requirements.
- Field-Programmable Gate Array:FPGA-based systems provide ultra-low latency and parallel processing capabilities essential for high-frequency signal processing and complex plant model execution. Automotive developers are rapidly adopting these for electric motor controllers and radar sensor validation.
- Digital Signal Processing:DSP technology offers powerful computational performance for real-time algorithm execution and signal manipulation, commonly used in audio and image processing applications within HIL. Aerospace control systems leverage DSP for complex sensor data integration and filtering.
- Embedded Systems:These integrated hardware and software solutions provide dedicated functionality for specific HIL tasks, offering efficiency and reliability.
- Microcontroller-Based Modules:Cost-effective and versatile, these modules handle less complex control logic and I/O tasks within modular HIL setups.
Digital Signal Processing technology holds a substantial market share. Field-Programmable Gate Array technology is expanding most quickly.
Application:
The market volume for HIL solutions is significantly shaped by their specific application areas.
- Electric Vehicle Testing:This application involves rigorous validation of battery management systems, inverters, and electric motor controllers to ensure performance and safety. Global automotive OEMs are driving significant demand for HIL in EV powertrain development.
- Aerospace Control Systems:HIL is critical for testing flight control software, engine management systems, and avionics, ensuring compliance with stringent safety standards like DO-178C. Aircraft manufacturers globally depend on these systems for validation.
- Industrial Automation:HIL supports the development and validation of programmable logic controllers and robotic systems in smart factories.
- Robotics Validation:This segment uses HIL to test complex robotic algorithms and hardware interactions in a safe, simulated environment.
Electric Vehicle Testing currently represents the largest demand area. Robotics Validation is gaining share fastest.
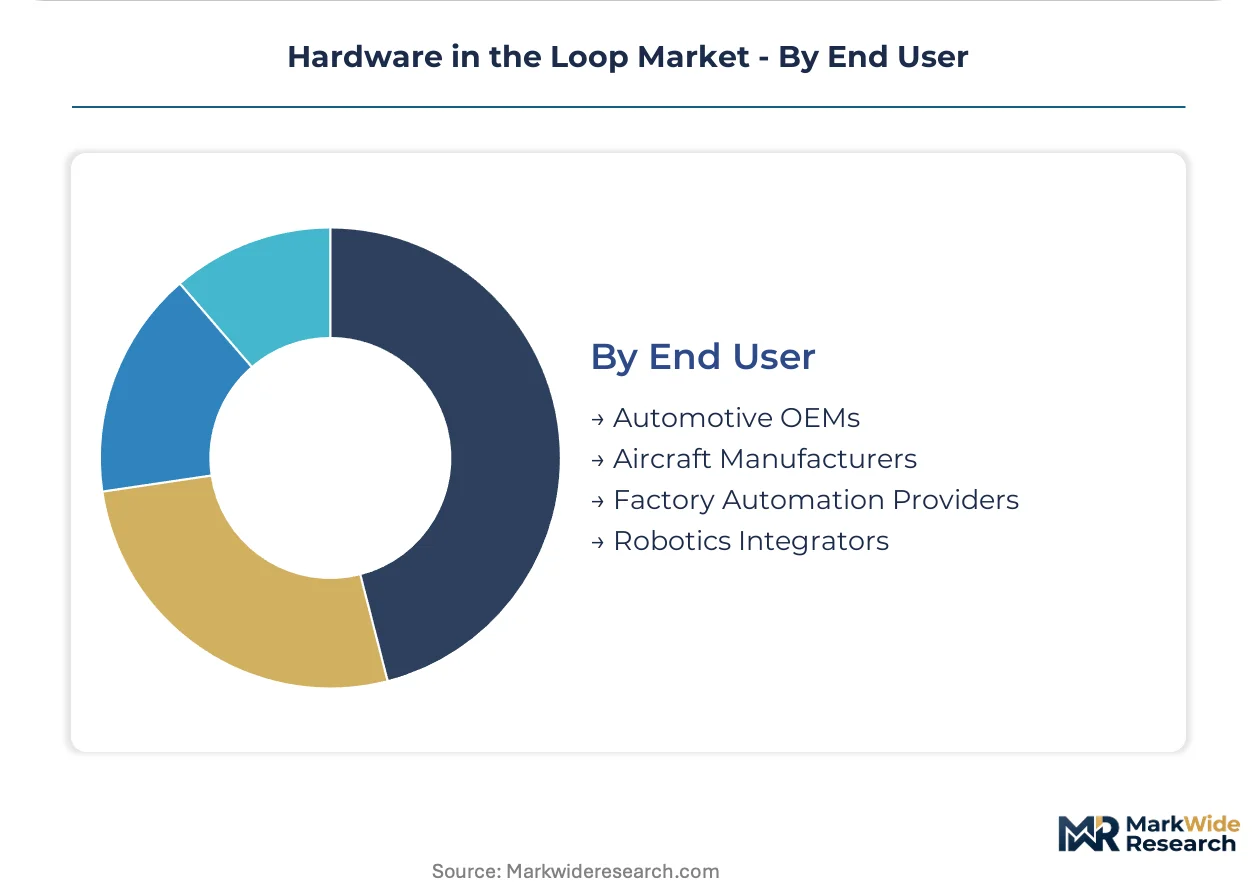
End User:
Distinct customer types exhibit unique procurement patterns and technology requirements for HIL systems.
- Automotive OEMs:These manufacturers represent the largest end-user segment, utilizing HIL extensively for validating ADAS, electric powertrains, and complex embedded software. OEMs in Germany and Japan are primary investors in advanced HIL platforms.
- Aircraft Manufacturers:Companies developing commercial and military aircraft require high-fidelity HIL systems for verifying critical flight control software and avionics systems. Functional safety standards like DO-178C mandate this exhaustive testing.
- Factory Automation Providers:These companies integrate HIL for testing and debugging control systems used in manufacturing processes and industrial robotics.
- Robotics Integrators:Specialists in robotic system deployment use HIL to validate software and hardware interfaces before physical deployment.
Automotive OEMs command the largest share of HIL market expenditure. Robotics Integrators are showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing clusters drive significant Hardware in the Loop (HIL) market concentration, fueled by stringent functional safety mandates. These specialized zones attract substantial investment for advanced driver-assistance systems (ADAS) and electric vehicle powertrain validation. Global OEMs prioritize these regions for rigorous testing infrastructure development.
Germany
German automotive OEMs demand sophisticated HIL systems for advanced ADAS and electric powertrain validation. The KBA's stringent vehicle safety regulations, alongside ISO 26262, mandate exhaustive testing processes. Bavaria's automotive R&D centers concentrate HIL investments for high-fidelity simulation.
Japan
Japanese automotive manufacturers are accelerating HIL investments to validate complex ADAS functionalities and autonomous driving algorithms. METI initiatives support advanced manufacturing and testing infrastructure development for next-generation vehicles. The Nagoya region, a hub for automotive innovation, sees significant HIL platform deployment.
United States
The United States market exhibits strong HIL demand, particularly within the agile electric vehicle development sector. NHTSA safety standards for advanced vehicle systems compel rigorous validation of embedded software. Silicon Valley's tech ecosystem and Detroit's automotive heritage drive HIL adoption for innovative mobility solutions.
China
China's rapidly expanding electric vehicle industry fuels substantial HIL market growth for battery management systems and motor controllers. MIIT policies promoting new energy vehicle development encourage investment in advanced testing facilities. The Yangtze River Delta region, with its numerous EV manufacturers, actively deploys modular HIL solutions.
India
India's automotive sector shows increasing demand for HIL solutions, especially for cost-effective modular systems. BIS standards for vehicle components and systems necessitate robust validation procedures. Chennai's automotive manufacturing corridor is becoming a significant hub for HIL testing infrastructure.
Hardware in the Loop Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered Hardware in the Loop market structure. This market exhibits consolidation among high-performance, turnkey platform providers, while modular solution providers introduce fragmentation. Strategic archetypes include integrated solution providers, niche technology developers, and specialized service integrators. Companies engage in strategic partnerships to expand their technology portfolios and pursue targeted geographic expansion.
Specialists in high-fidelity simulation and comprehensive ecosystems, National Instruments Corporation, with its extensive hardware and software offerings, exemplifies a broad platform provider. dSPACE GmbH, a German company, occupies a strong position as a pure-play HIL vendor, particularly within the German automotive sector for autonomous driving validation. Vector Informatik GmbH, another German entity, represents a focused provider of ECU testing and network communication analysis tools. These entities anchor distinct segments, from expansive system integration to specialized software validation. Their market presence reflects the varied technical demands across automotive and aerospace applications.
| Leading Market Players |
|---|
| Vector Informatik GmbH |
| Siemens |
| dSPACE GmbH |
| Elektrobit Automotive GmbH |
| Speedgoat GmbH |
| National Instruments Corporation |
| OPAL-RT Technologies |
| IPG Automotive GmbH |
| Robert Bosch GmbH |
| Others |
Cost & Logistics Intelligence
High-fidelity, integrated HIL platforms versus modular, lower-cost systems represent a clear tier divergence that manifests in both pricing and supply chain configurations. The specialized components required for high-fidelity systems command premium pricing and draw from a concentrated vendor supply, while modular offerings provide more flexible pricing and component sourcing.
Pricing Analysis
Premium pricing often applies to HIL systems with short lead times for highly customized configurations. The dominant pricing structure combines project-based hardware sales with licensing and royalty models for specialized software. Price differentiation stems from the customization level, ISO 26262 certification compliance, and comprehensive after-sales service. Pricing softness runs through modular systems due to increased competition from new entrants. Academic research institutions and smaller engineering teams exhibit the highest price sensitivity, while large automotive OEMs prioritize performance over cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized real-time processor and FPGA component suppliers. Geographic supply concentration includes Germany for turnkey systems, the United States for platform providers, and Japan for high-volume automotive OEM demand. Raw material dependencies involve high-performance FPGAs, specialized real-time processors, and signal conditioning ASICs. Geopolitical tensions impacting semiconductor supply chains represent a significant structural risk. Distribution runs through direct sales channels for major OEMs and value-added resellers for modular HIL solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hardware in the Loop market remains supply-constrained, particularly for advanced components. Specialized FPGA manufacturing capacity props pricing for high-performance HIL systems, creating a bottleneck.
For Market Incumbents:Anticipate the emergence of open-source simulation frameworks by deepening software ecosystem integration. Acquire niche technology developers to expand capabilities in AI-driven test case generation. Invest in R&D for advanced sensor simulation to counter threats from virtual validation tools. Bolster global support networks to maintain client relationships against new entrants.
For New Entrants and Emerging Players:Smaller engineering teams in emerging markets represent a significant entry point. Target industrial automation and robotics validation as white-space opportunities. Penetrate the Indian automotive sector with cost-effective modular HIL solutions. Implement a go-to-market strategy featuring subscription-based software licenses and hardware-as-a-service models for affordability.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized HIL software providers given the shift towards software-defined validation. The market maintains strong fundamentals for the next decade, driven by embedded system complexity. Identify acquisition targets with robust AI and digital twin integration capabilities. A key signal to watch is the increased standardization of HIL interfaces across vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Streamlines testing workflows for automotive OEMs using diverse HIL components. |
| Strategic Partnership | Expands market reach into new industrial automation sectors through collaboration. |
| Acquisition of Specialist Firm | Enhances capabilities in advanced sensor simulation and AI-driven validation. |
| Geographic Expansion | Captures demand from rapidly growing electric vehicle markets in China. |
| Software-Defined Validation Investment | Future-proofs offerings against shifting market preferences for flexible test platforms. |
Research Approach
Independent corroboration across industry reports, academic publications, and regulatory filings underwrites the qualitative findings of this study. Primary interviews with automotive OEM engineers, aerospace system architects, and HIL vendor R&D leads provided critical insights. Secondary data sources included NHTSA safety reports, ISO 26262 compliance documents, and company financial statements, informing both bottom-up and top-down triangulation.
Rate-of-change decomposition informed the forecast model, isolating growth drivers and inhibitors across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and geographic region. Compound annual growth rates reflect historical trends and future demand projections, incorporating electric vehicle production forecasts and ADAS feature penetration rates as key inputs.
Revisions become necessary when significant shifts in regulatory mandates or accelerated adoption of new simulation technologies materialize. Forecasts reflect assumptions regarding market dynamics and technological advancements. Unforeseen economic downturns or rapid advancements in virtual validation represent specific risk factors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Industrial Automation Device Manager Software Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
Smart Factory Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
North America Smart Manufacturing Market
Industrial Automation
Grippers Market
Industrial Automation
Global Automated Sortation System Market
Industrial Automation
Asia Industry 4.0 Market
Industrial Automation
Embedded Automation Computers Market
Industrial Automation
Machine Automation Controllers Market
Industrial Automation
Global Robotic Laser Cutting Machine Market
Industrial Automation
Monitor Arm Market
Industrial Automation
Rotary Vector (RV) Reducer Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market
Industrial Automation
Magnetic Grippers Market
Industrial Automation
Digital Transformation in Manufacturing Market