
 Port Equipment Automation Market | 2026-2036
Port Equipment Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Port Equipment Automation Market Analytics
Container terminal operations is pivoting toward fully automated berth-to-yard workflows as shipping lines demand faster vessel turnaround. Konecranes leverages its deep installed base of ship-to-shore cranes to anchor retrofit automation contracts across Nordic and Baltic ports. Shanghai Zhenhua Heavy Industries dominates new-build automated quay crane deliveries with manufacturing scale that sustains cost advantages on mega-vessel class orders. Kalmar competes through integrated terminal operating system bundles that extend beyond hardware into software-controlled yard optimization.
Port equipment automation encompasses the sensor networks, control systems, and robotic machinery that replace manual intervention in cargo handling, container storage, and dock management functions, typically operating with positioning precision within centimeters via laser guidance and GPS correction. Automated cranes command the largest capital allocation in current procurement cycles due to their direct impact on vessel loading rates and berth utilization metrics. Terminal operating systems represent the fastest-expanding margin pool as recurring software licenses and data analytics layers attach to hardware deployments. IoT solutions underpin real-time equipment health monitoring that shifts maintenance from scheduled intervals to condition-based interventions, reducing unplanned downtime in high-throughput environments.
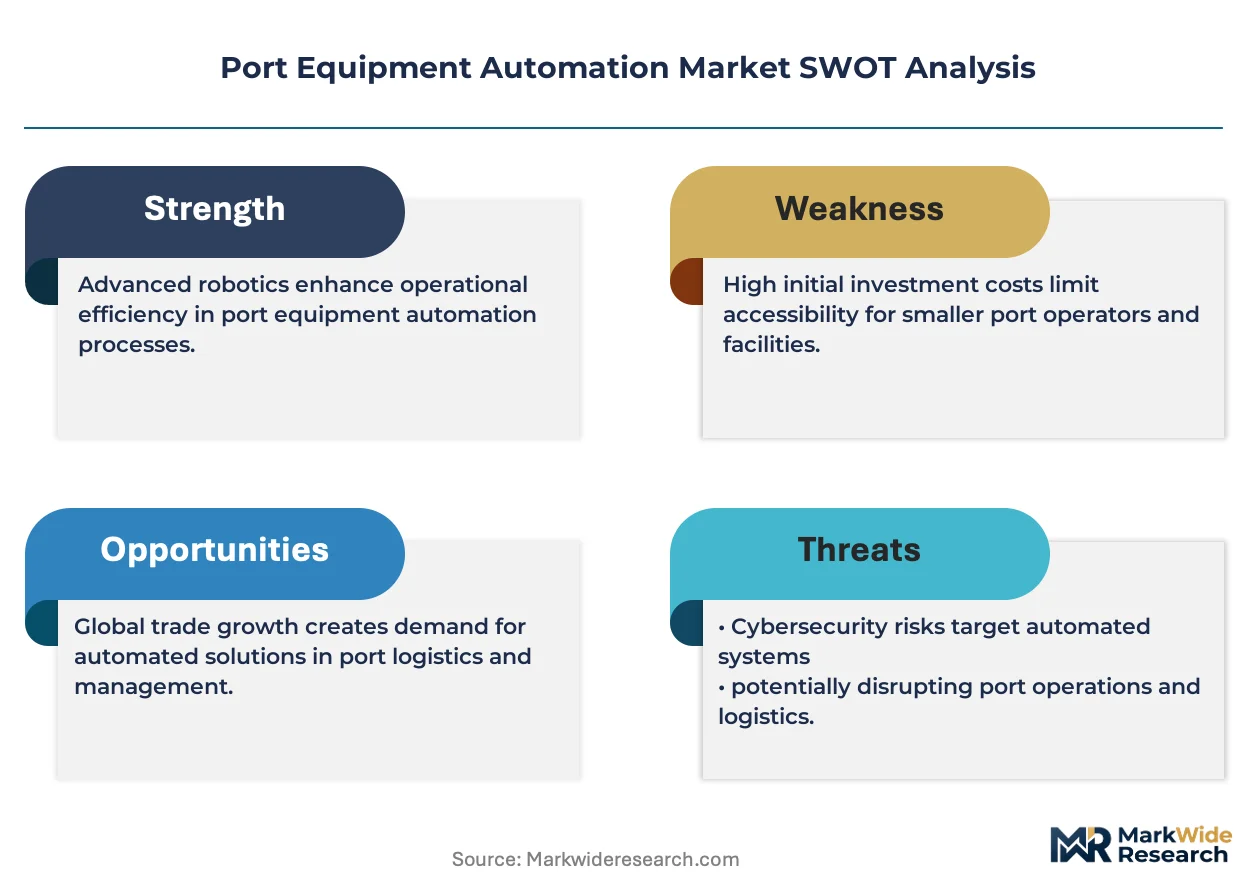
The International Maritime Organization's greenhouse gas strategy and port state control regimes in the EU, China, and the US are tightening emissions thresholds that favor electric automated guided vehicles over diesel terminal tractors. OSHA workplace safety directives and China's GB standards for port machinery interoperability shape equipment design requirements and cross-vendor system integration protocols. Stakeholders must weigh the capital intensity of full-stack automation against modular upgrade paths that preserve optionality as terminal traffic patterns and vessel size distributions continue shifting.
Market Dynamics
Terminal operators face a structural squeeze between IMO decarbonization deadlines and the capital intensity of berth electrification, forcing staged automation rollouts that prioritize crane retrofits over full-stack yard automation.
Growth Catalysts
- EU Green Deal port mandates:Binding emissions thresholds at North Sea hubs are accelerating electric AGV procurement ahead of 2030 compliance deadlines.
- China's GB standards for port machinery interoperability:Unified communication protocols reduce integration friction between crane OEMs and terminal operating system vendors.
- Yangtze River Delta throughput expansion:Shanghai and Ningbo-Zhoushan port clusters are deploying smart pilot programs that bundle automated quay cranes with IoT-enabled predictive maintenance.
Market Restraints
- Steel and rare-earth input volatility:Automated crane manufacturing depends on concentrated Chinese steel supply and neodymium magnet sourcing, creating margin compression during commodity spikes.
- High-voltage shore power infrastructure gaps:Many legacy berths lack grid capacity for electrified equipment, delaying ROI realization on automation investments.
- Cyber-physical system integration complexity:Laser guidance and GPS correction systems require sub-centimeter calibration that conflicts with legacy terminal layouts designed for manual operations.
Strategic Opportunities
- India's Sagarmala port modernization:Jawaharlal Nehru Port and Mundra are soliciting automation tenders for greenfield terminals without legacy equipment constraints.
- 5G private network convergence with edge computing:Ultra-low latency connectivity enables real-time crane coordination and autonomous yard truck routing previously impossible with Wi-Fi.
- Outcome-based maintenance contracts:Equipment vendors can capture recurring revenue by guaranteeing uptime rather than selling hardware, shifting risk to suppliers.
Industry Challenges
- Control systems engineering talent scarcity:Terminal operators compete with automotive and aerospace sectors for PLC programmers and robotics integration specialists.
- Multi-vendor interoperability certification:China's GB standards and EU machinery directives impose overlapping testing protocols that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Port Equipment Automation Market |
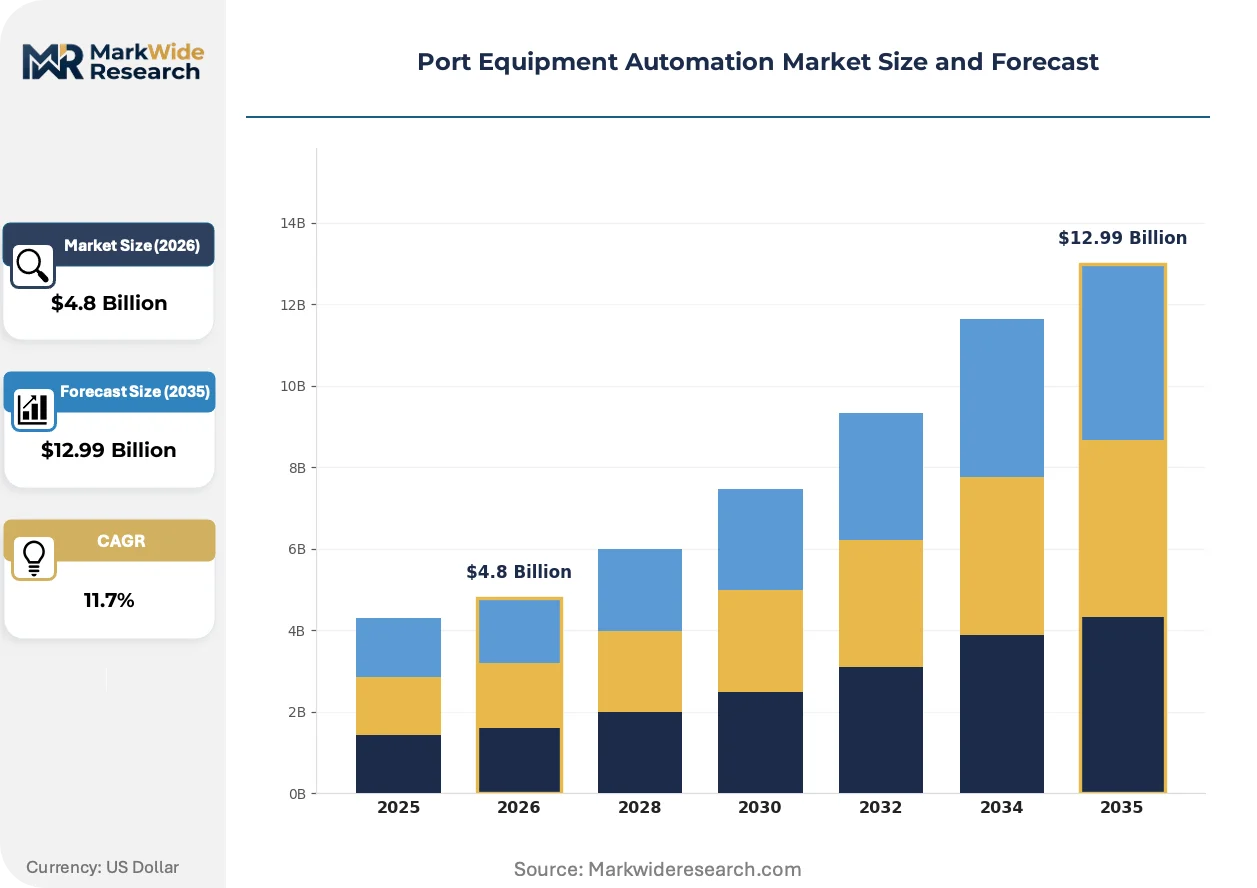
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
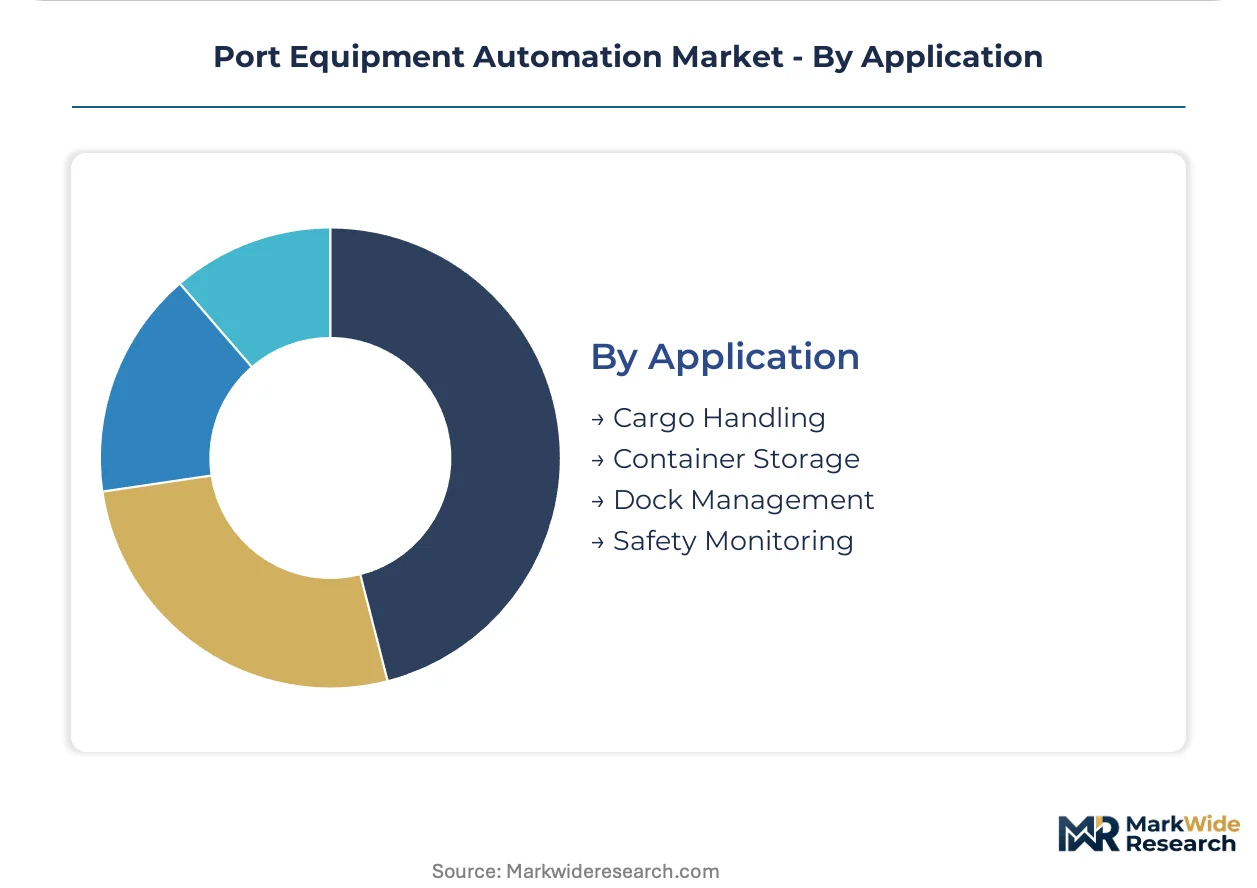
| Segmentation | Product Type: Automated Cranes, Automated Guided Vehicles, Terminal Operating Systems, Remote Monitoring Solutions Technology: IoT Solutions, Machine Learning, AI Algorithms, Robotics End User: Shipping Lines, Terminal Operators, Freight Forwarders, Dock Management Firms Application: Cargo Handling, Container Storage, Dock Management, Safety Monitoring |
| Companies Covered | Shanghai Zhenhua Heavy Industries, Sany Heavy Industry, Konecranes, CVS Ferrari, Kalmar, Cargotec Corporation, ABB, Cavotec, Liebherr Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Port Equipment Automation Market Evolving Landscape
Automation architecture is pivoting from isolated equipment upgrades toward orchestrated berth-to-yard systems where software layers extract value from hardware commoditization.
Battery-electric automated guided vehicles are electrifying yard operations at Rotterdam and Hamburg terminals, replacing diesel terminal tractors. Maersk and MSC are mandating electric AGV fleets for new long-term service contracts. This shift is compressing the payback period for charging infrastructure investments as fuel differentials widen.
REACH chemical registration and EU F-Gas Regulation are restricting hydraulic fluids and refrigerants in port machinery, forcing OEMs to redesign crane drive systems. The regulations are accelerating adoption of all-electric winch mechanisms over hydraulic alternatives. Nordic ports are responding fastest due to stricter national implementations of the framework.
Shipping lines are consolidating procurement authority for terminal automation decisions, displacing fragmented purchasing by individual port authorities. COSCO and CMA CGM now specify automation compatibility requirements in terminal concession agreements. This concentration is most visible in East Asia where carrier alliances control berth allocation at mega-vessel hubs.
Port Equipment Automation Market Segmentation
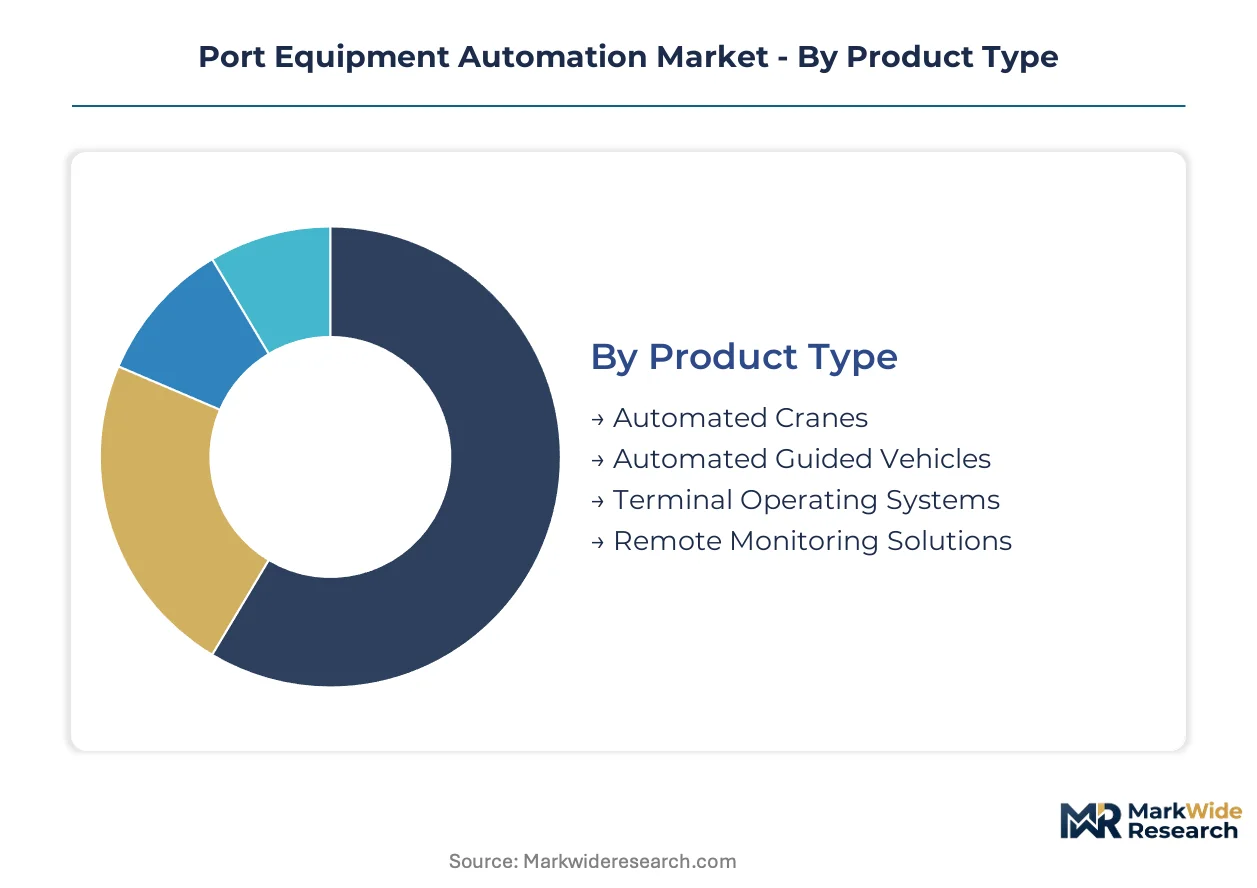
Port equipment automation procurement splits sharply between high-capex hardware systems and recurring software layers, with capital allocation decisions increasingly bundled across berth-to-yard workflows rather than isolated equipment purchases.
Product Type:
Capital intensity peaks in quay-side crane retrofits where single-unit investments exceed multi-million dollar thresholds and berth downtime during installation amplifies total project cost.
- Automated Cranes:Ship-to-shore and rubber-tired gantry variants integrate laser positioning with anti-sway algorithms to achieve sub-centimeter container placement precision. Demand clusters at Shanghai and Ningbo-Zhoushan where berth productivity targets above 40 moves per hour drive retrofit urgency. IMO decarbonization timelines compress payback calculations for all-electric winch mechanisms.
- Automated Guided Vehicles:Battery-electric yard tractors replace diesel terminal equipment under EU Green Deal procurement mandates at Rotterdam and Hamburg. Maersk and MSC contract specifications now require electric AGV compatibility for new terminal concessions, accelerating fleet turnover timelines.
- Terminal Operating Systems:Software layers orchestrate equipment dispatch, vessel stowage planning, and yard optimization through API integrations with crane PLCs.
- Remote Monitoring Solutions:IoT sensor networks transmit equipment health data to cloud analytics platforms for condition-based maintenance scheduling.
Most installed capacity flows through Automated Cranes. Expansion is steepest in Terminal Operating Systems.
Technology:
Technology selection tracks the maturity curve from proven industrial IoT deployments toward experimental AI layers that remain unproven at production scale.
- IoT Solutions:Vibration, temperature, and hydraulic pressure sensors on crane hoists and spreaders feed edge computing nodes for real-time anomaly detection. Yangtze River Delta ports deploy predictive maintenance pilots that reduce unplanned downtime by shifting from calendar-based to condition-triggered service intervals.
- Machine Learning:Pattern recognition algorithms optimize yard block assignments and vessel loading sequences based on historical throughput data. Training data scarcity at smaller terminals limits model accuracy outside mega-hub deployments.
- AI Algorithms:Computer vision systems identify container damage and misalignment during crane operations.
- Robotics:Autonomous maintenance drones and robotic inspection crawlers access confined crane structures.
Deployment maturity concentrates in IoT Solutions. Investment velocity is climbing fastest in Machine Learning.
End User:
Procurement authority is consolidating toward carrier-controlled terminal operators as shipping lines embed automation requirements in concession agreements.
- Terminal Operators:PSA International and DP World manage automation capex programs spanning crane retrofits, AGV fleet procurement, and TOS migrations. Their investment horizons balance IMO compliance deadlines against 15-20 year concession amortization schedules.
- Shipping Lines:COSCO and CMA CGM now specify minimum automation compatibility thresholds in terminal service contracts, displacing fragmented port authority purchasing decisions.
- Freight Forwarders:Visibility platform providers integrate terminal automation data streams for cargo tracking and dwell time optimization.
- Dock Management Firms:Specialized berth scheduling and pilotage coordination services purchase automation interfaces to align vessel arrival windows with crane availability.
Contract volume concentrates with Terminal Operators. Influence is shifting fastest toward Shipping Lines.
Application:
Application prioritization follows the cargo flow from vessel to gate, with berth-side operations commanding automation investment precedence over back-of-terminal functions.
- Cargo Handling:Automated quay cranes and yard equipment execute container lifts with positioning precision that eliminates manual lash verification delays. Rotterdam Maasvlakte terminals achieve 98% automated gate-in/gate-out processing through OCR and weight verification integration.
- Container Storage:Automated stacking cranes and yard inventory systems optimize block density while maintaining accessibility for priority vessel loads. High-bay container storage at Singapore's Tuas terminal demonstrates vertical space utilization impossible with manual yard tractors.
- Dock Management:Berth allocation algorithms and vessel traffic coordination systems reduce anchorage wait times.
- Safety Monitoring:Perimeter intrusion detection and personnel tracking systems enforce exclusion zones around automated equipment.
Operational throughput concentrates in Cargo Handling. Automation penetration is deepening fastest in Container Storage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in port equipment automation favors jurisdictions with harmonized standards and subsidized electrification infrastructure, tilting procurement toward EU and Chinese terminals where compliance costs are offset by state-backed decarbonization programs.
China
GB standards for port machinery interoperability reduce integration friction between crane OEMs and terminal operating system vendors. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate electric AGV deployment. Shanghai and Ningbo-Zhoushan anchor demand as smart port pilot programs bundle automated quay cranes with IoT-enabled predictive maintenance systems.
Germany
The EU Green Deal's binding emissions thresholds compress payback calculations for electrified yard equipment at Hamburg and Bremerhaven terminals. REACH chemical registration restricts hydraulic fluids in crane drive systems, forcing OEM redesigns toward all-electric winch mechanisms. The KBA certifies automated guided vehicle safety protocols for mixed-traffic terminal environments.
Netherlands
Rotterdam Maasvlakte terminals achieve 98% automated gate-in/gate-out processing through OCR and weight verification integration. The EU F-Gas Regulation phases out refrigerants in port machinery, accelerating adoption of electric alternatives. The port authority mandates electric AGV compatibility in new terminal concession agreements.
United States
OSHA workplace safety directives shape equipment design requirements for automated crane exclusion zones and personnel tracking systems. The Inflation Reduction Act's port electrification credits offset shore power infrastructure investments at Los Angeles and Long Beach terminals. Pacific Northwest ports pilot 5G private networks for real-time crane coordination.
Singapore
The Maritime and Port Authority incentivizes automation through berth productivity targets that exceed 40 moves per hour. Tuas terminal demonstrates high-bay container storage with vertical space utilization impossible with manual yard tractors. PSA International manages automation capex programs spanning crane retrofits and AGV fleet procurement across 15-20 year concession schedules.
Port Equipment Automation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-stack automation integrators commanding premium pricing against modular equipment vendors. The vendor base organizes around three archetypes: crane OEMs with deep installed bases anchoring retrofit contracts, industrial conglomerates bundling hardware with terminal operating software, and pure-play automation technology providers licensing sensor and control systems. Consolidation pressure intensifies as shipping lines consolidate procurement authority and mandate cross-vendor interoperability.
Within the heavy machinery tier, Shanghai Zhenhua Heavy Industries and Sany Heavy Industry represent Chinese manufacturing scale advantages on mega-vessel class orders, while Konecranes occupies a position anchoring Nordic and Baltic retrofit automation contracts through its installed base of ship-to-shore cranes. Kalmar exemplifies the integrated-systems archetype, competing through terminal operating system bundles that extend beyond hardware into software-controlled yard optimization.
| Leading Market Players |
|---|
| Shanghai Zhenhua Heavy Industries |
| Sany Heavy Industry |
| Konecranes |
| CVS Ferrari |
| Kalmar |
| Cargotec Corporation |
| ABB |
| Cavotec |
| Liebherr Group |
| Others |
Value Network & Pricing Analysis
Chinese steel price indices and neodymium magnet benchmarks cascade through automated crane manufacturing into three-tier pricing structures that separate premium OEM retrofits from standard new-build deliveries and economy-grade component supply. Terminal operators absorb commodity volatility through contract escalation clauses tied to Shanghai Futures Exchange steel futures, while electric AGV procurement faces lithium-ion battery cost compression that narrows the total-cost-of-ownership gap against diesel alternatives.
Pricing Analysis
Direct-to-OEM volume discounts dominate crane procurement, with project-based pricing for integrated berth-to-yard automation bundles commanding premium positioning over modular equipment sales. Price differentiation separates CE-certified European systems from GB-standard Chinese alternatives, with certification-grade premiums widening as EU machinery directives tighten. Cost compression in standard-tier crane manufacturing intensifies due to Shanghai Zhenhua Heavy Industries' manufacturing scale advantages. Small-to-mid terminal operators exhibit highest price sensitivity, deferring full-stack automation for staged crane retrofits that preserve capital optionality.
Supply Chain Analysis
CE marking and KBA safety certification gate European market access for automated guided vehicles, forcing non-EU vendors through extended homologation timelines that concentrate procurement with pre-qualified suppliers. Manufacturing gravity centers on China for steel structures and electric drivetrains, Germany for precision control systems, and South Korea for battery cell supply. Raw material dependencies span high-grade structural steel, rare-earth permanent magnets, and silicon carbide power semiconductors. Single-source vulnerability concentrates in Chinese neodymium processing. Distribution runs through crane OEM direct sales teams for large projects and specialized port equipment distributors for aftermarket components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Port equipment automation functions as a geographic-arbitrage play where EU Green Deal compliance subsidies at Rotterdam and Hamburg offset capital intensity that would stall adoption at unsubsidized US Gulf Coast terminals.
For Market Incumbents: Deploy outcome-based maintenance contracts to lock in recurring revenue streams and raise switching costs against emerging pure-play software vendors. Incumbents should anchor retrofit automation contracts through deep installed bases of ship-to-shore cranes at Nordic and Baltic ports, while accelerating backward integration into sensor networks to capture margin pools shifting from hardware to software layers. The threat of carrier-controlled procurement consolidation demands defensive positioning through integrated terminal operating system bundles. For New Entrants and Emerging Players: Launch via 5G private network infrastructure partnerships to bypass capital-intensive crane manufacturing and capture value from ultra-low latency connectivity services. India's Sagarmala greenfield terminals present the most penetrable geography, free from legacy equipment constraints that complicate retrofit markets. White-space targets include edge computing nodes for real-time crane coordination and AI-driven yard optimization software that layers atop existing terminal operating systems. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play automation technology providers licensing sensor and control systems, as hardware commoditization concentrates margin capture in software layers. Long-term viability favors vendors with recurring revenue exposure through terminal operating system subscriptions and predictive maintenance contracts. Acquisition targets should demonstrate cross-vendor interoperability certification under China's GB standards or EU machinery directives. The signal to watch is carrier alliance procurement consolidation that displaces fragmented port authority purchasing decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Outcome-Based Maintenance Contracts | Guaranteed uptime shifts risk to suppliers and captures recurring revenue from PSA International and DP World terminal networks. |
| 5G Private Network Deployment | Ultra-low latency enables real-time crane coordination at Rotterdam Maasvlakte previously impossible with Wi-Fi infrastructure. |
| Backward Integration into Sensors | In-house production of laser positioning systems captures margin pools migrating from hardware commoditization to software layers. |
| Cross-Vendor Interoperability Certification | GB standards compliance unlocks Chinese terminal procurement and reduces deployment friction at Yangtze River Delta ports. |
| Battery-Electric AGV Fleet Conversion | Maersk and MSC contract mandates accelerate fleet turnover timelines at Hamburg and Bremerhaven terminals. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with terminal operations directors, crane OEM procurement teams, port authority technology officers, and shipping line fleet managers with secondary validation through customs trade data, SEC filings of listed equipment vendors, EU ETS emissions registry records, and Chinese Ministry of Transport port throughput statistics. Bottom-up equipment shipment tracking and top-down terminal capex budget analysis were triangulated against reported automation deployment announcements.
Segment-weighting approaches applied differential growth assumptions across hardware systems and software layers, with product type splits for automated cranes, AGVs, terminal operating systems, and remote monitoring solutions cross-referenced against technology maturity curves for IoT, machine learning, and AI algorithm deployments. End-user concentration weights reflected procurement authority shifts from port authorities toward carrier-controlled terminal operators. CAGRs were derived from installed base expansion rates and replacement cycle timing, with electric AGV penetration curves calibrated against EU Green Deal compliance deadlines and IMO decarbonization timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price spikes in steel and rare-earth inputs or accelerated carrier consolidation in terminal concession agreements. Forecasts reflect documented assumptions regarding berth electrification infrastructure buildout timelines and 5G private network deployment pace across major port clusters. A model refresh is warranted upon material change in EU ETS carbon price levels or Chinese dual carbon policy enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Factory Automation in Japan Market
Industrial Automation
Europe Smart Manufacturing Market
Industrial Automation
Programmable Automation Controller (PAC) Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
North America Automated Storage and Retrieval System Market
Industrial Automation
Middle East and Africa Medical Automation Market
Industrial Automation
Linear Motion System Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Smart Industries Market
Industrial Automation
North America Smart Manufacturing Market
Industrial Automation
Global Feeder Automation Market
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
Digital Rotator Market
Industrial Automation
Asia-Pacific Automation Components Market
Industrial Automation
Automatic Screw Feeding System Market
Industrial Automation
Smart Escalator Market