
 Global Risk and Compliance Consulting Services Market | 2026-2036
Global Risk and Compliance Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Risk and Compliance Consulting Services Market Foresight
Artificial intelligence is shifting from experimental tool to core compliance infrastructure, replacing manual audit sampling with algorithmic risk detection. Deloitte leverages its regulatory technology partnerships to embed machine learning into client governance frameworks. PwC sustains competitive position through proprietary risk quantification models that span multiple jurisdictions. Accenture anchors its practice in cloud-native compliance platforms that integrate with enterprise resource planning systems.
Risk and compliance consulting services encompass advisory engagements that identify, evaluate, and mitigate operational, financial, and regulatory threats through structured methodologies, data analytics, and domain expertise delivered by specialized practitioners. These services functionally operate through continuous monitoring protocols, control design, and remediation planning that align organizational conduct with enforceable legal standards. Regulatory compliance services command the largest revenue share among service type segments, reflecting perpetual updates to financial services law, environmental mandates, and data privacy statutes. Outcome-based engagement models are expanding fastest as procurement departments demand measurable risk reduction rather than hourly professional fees. Large corporations represent the most mature client size segment, though mid-sized enterprises present the steepest growth trajectory as regulatory thresholds lower and enforcement intensifies.
The SEC, EMA, and EU AI Act collectively reshape service demand by mandating documented risk governance, algorithmic accountability, and supply chain due diligence that internal teams cannot independently satisfy. GDPR enforcement actions by CNIL and comparable national regulators in Germany and Italy generate recurring compliance validation work. Stakeholders must monitor the divergence between EU comprehensive regulation and US sector-specific approaches when structuring cross-border service delivery models.
Market Dynamics
Algorithmic risk detection is compressing audit cycles from quarterly reviews to continuous monitoring, forcing consulting firms to restructure delivery models around machine-readable compliance data rather than manual documentation.
Growth Catalysts
- SEC climate disclosure mandates:Public companies must document Scope 3 emissions across supply chains, generating recurring advisory demand for carbon accounting frameworks and attestation protocols.
- EU AI Act enforcement preparation:Financial services firms are procuring algorithmic impact assessments and bias testing protocols ahead of binding conformity deadlines in 2026.
- Digital transaction velocity:Real-time payment rails and embedded finance platforms require transaction monitoring systems that internal compliance teams cannot architect independently.
Market Restraints
- Specialized talent scarcity:Practitioners combining regulatory expertise with machine learning engineering command compensation premiums that compress consulting margin structures.
- Client procurement centralization:Fortune 500 procurement departments are consolidating vendor rosters to three preferred compliance advisors, squeezing mid-tier firms from competitive tenders.
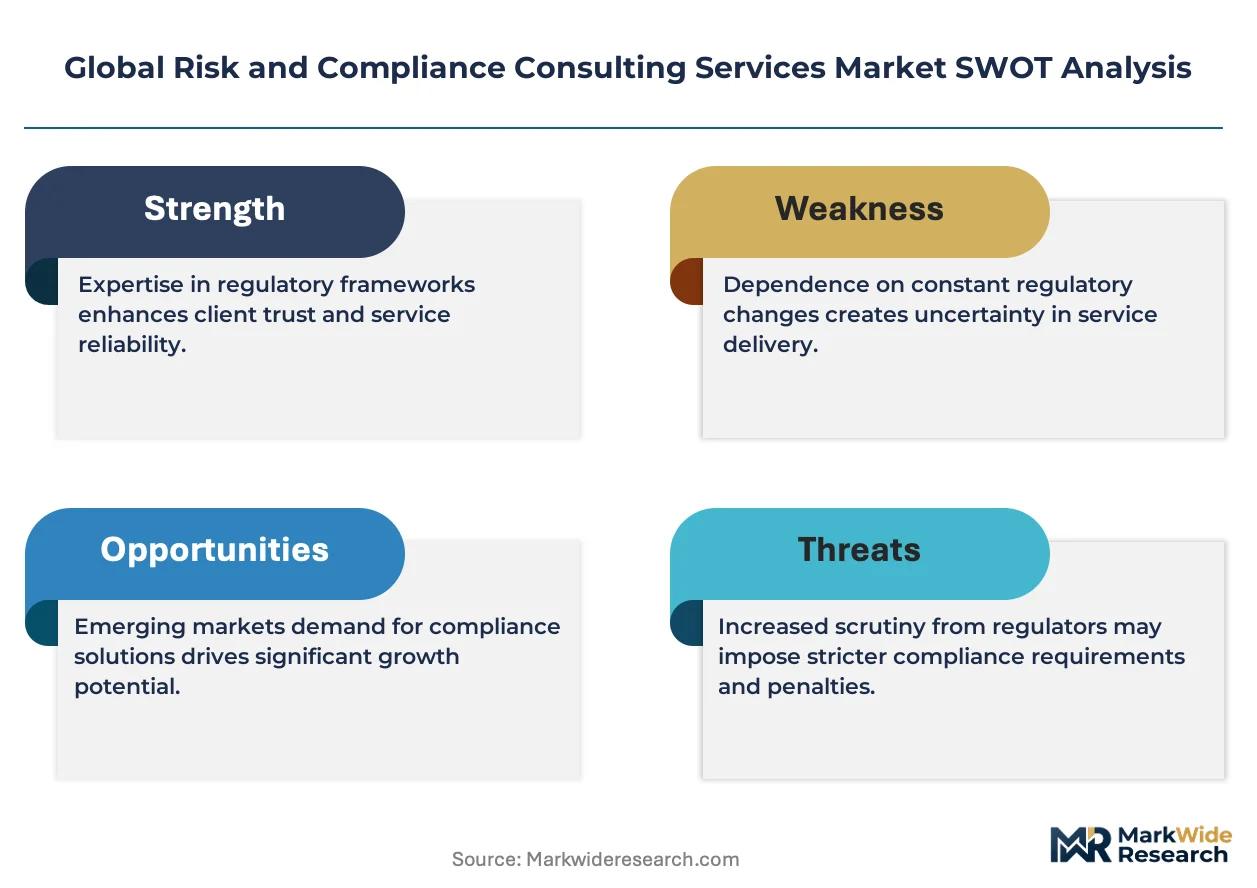
- Regulatory divergence friction:The gap between EU comprehensive AI governance and US sector-specific enforcement creates cross-border service architecture costs that deter smaller engagements.
Strategic Opportunities
- Mid-market enterprise penetration:Lowering regulatory thresholds in Germany and France are pulling mid-sized manufacturers into mandatory ESG reporting regimes previously reserved for large-cap firms.
- Convergence of cyber and compliance:Integration of NIST cybersecurity frameworks with SOX internal controls creates bundled advisory demand that single-specialist competitors cannot fulfill.
- Outcome-based contracting:Procurement departments in the United Kingdom are piloting fixed-fee engagements tied to measurable regulatory finding reductions rather than hourly billing.
Industry Challenges
- Legacy system integration complexity:Mainframe-based transaction monitoring at established banks resists API connectivity with cloud-native compliance platforms, extending implementation timelines.
- Cross-jurisdictional credential recognition:Practitioners licensed under US state bar or CPA frameworks face mobility barriers when delivering EU-regulated advisory services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Risk and Compliance Consulting Services Market |
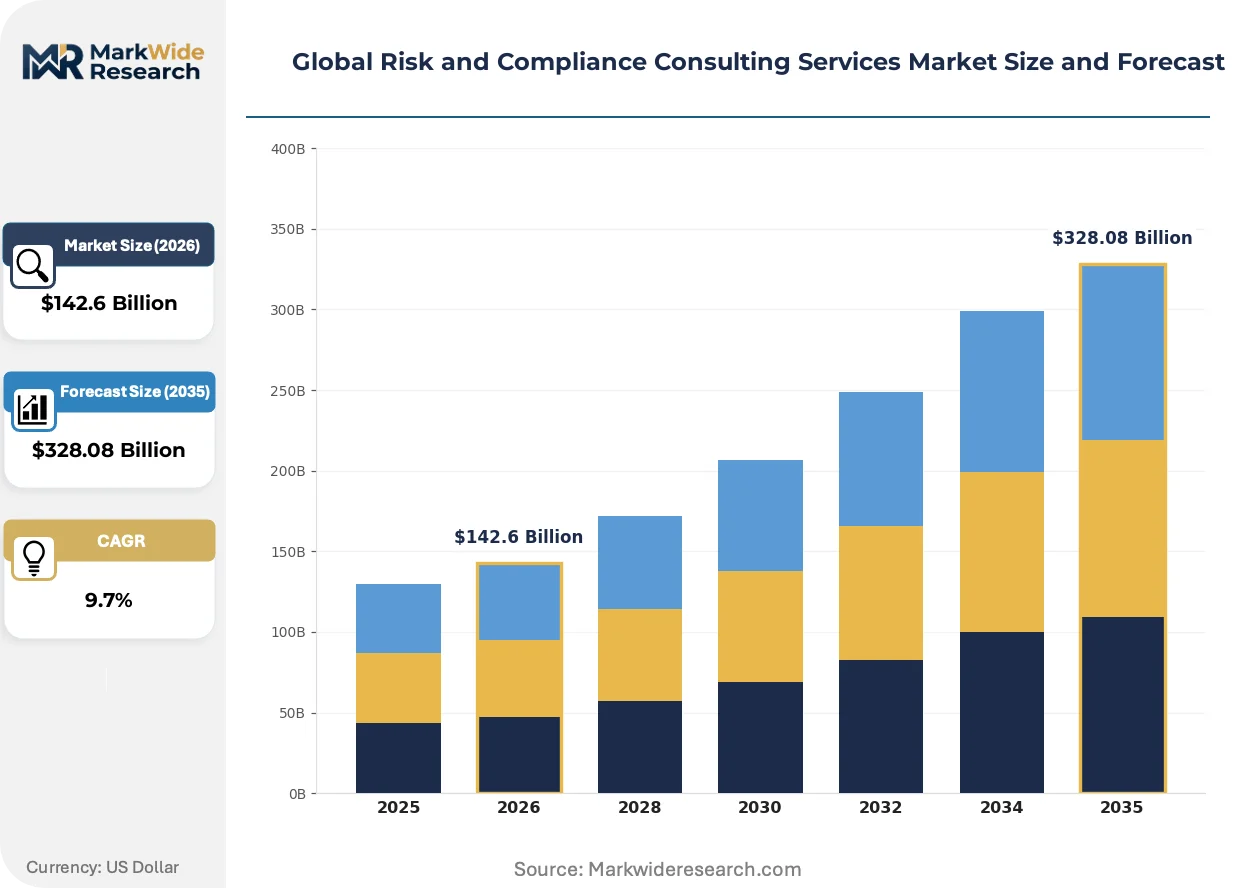
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $328.08 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Risk Assessment, Regulatory Compliance, Internal Audit, Fraud Detection, Crisis Management, Business Continuity Industry Vertical: Banking, Insurance, Energy & Utilities, Telecommunications, Manufacturing, Government Client Size: Small Businesses, Mid-sized Enterprises, Large Corporations, Multinational Companies Engagement Model: Project-based, Retainer, Advisory, Managed Services, Outcome-based |
| Companies Covered | KPMG, Accenture, Deloitte, Alvarez & Marsal, Boston Consulting Group, PwC, Protiviti, FTI Consulting, EY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Risk and Compliance Consulting Services Market Shifts & Advancements
Compliance infrastructure is migrating from retrospective documentation to predictive risk sensing, with machine learning models now flagging anomalies before they crystallize into regulatory violations.
Natural language processing engines are unifying contract analysis, regulatory text monitoring, and incident reporting into single workflow platforms. Large asset managers in the United States are deploying these systems to scan counterparty agreements against evolving SEC no-action letters. The technology is unifying previously siloed legal, risk, and compliance functions into shared data architectures that compress response latency from weeks to hours.
The EU AI Act's risk classification framework is mandating conformity assessments for high-risk algorithmic systems used in credit scoring and insurance underwriting. Financial institutions must maintain technical documentation, human oversight protocols, and accuracy testing records subject to market surveillance authority audit. German and Italian regulators are building enforcement capacity through 2025, creating sustained demand for algorithmic accountability advisory.
Enterprise buyers are unbundling compliance advisory from bundled audit relationships, issuing separate RFPs for specialized risk quantification and regulatory technology implementation. This pattern is most pronounced among US-based multinational corporations with operations spanning California consumer privacy law and New York financial services regulations. Specialized boutiques with domain-specific machine learning capabilities are capturing share from generalist advisory networks in these competitive tenders.
Global Risk and Compliance Consulting Services Market Segmentation
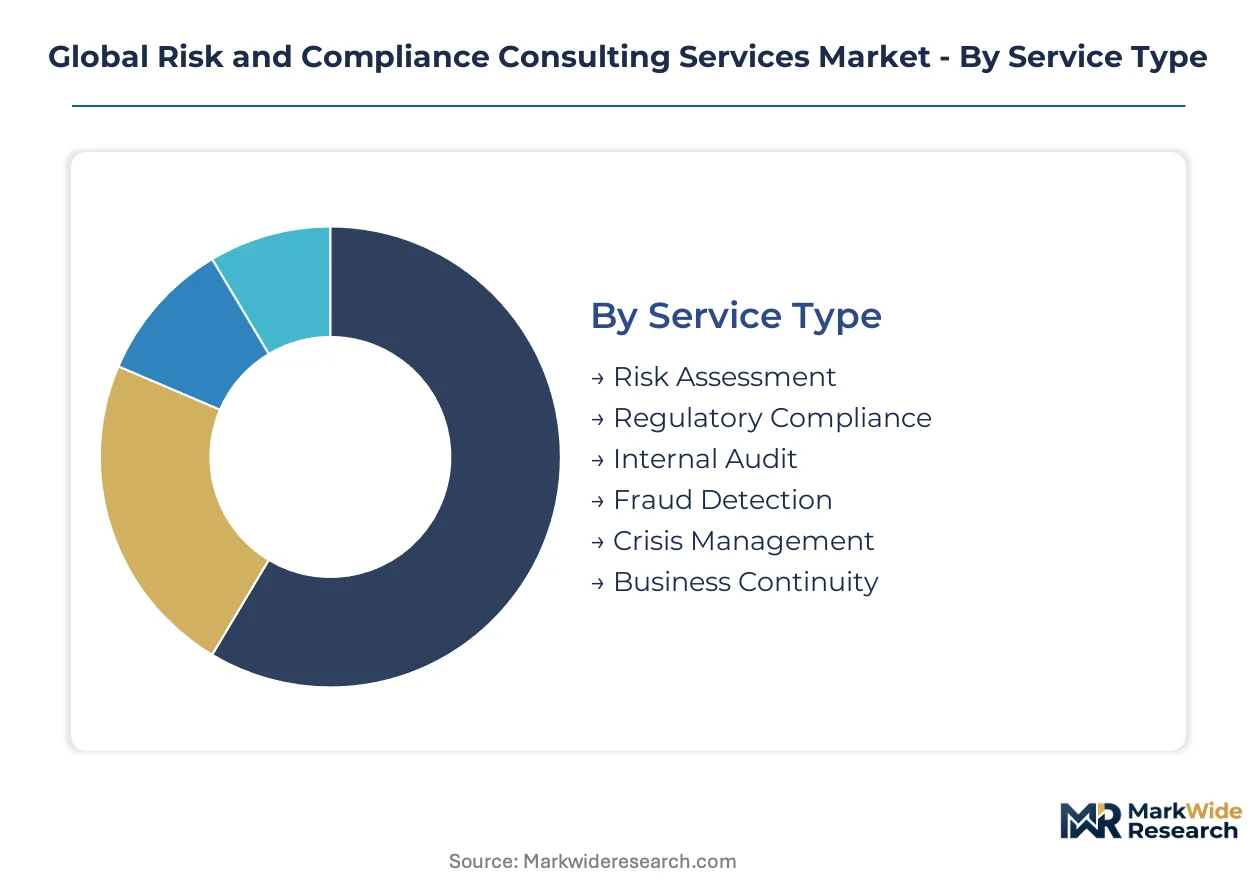
Service architecture in risk and compliance consulting fragments across delivery mechanisms, client sophistication, and regulatory exposure. Procurement patterns diverge sharply between institutions seeking episodic crisis response versus those building embedded governance infrastructure.
Service Type:
Technical depth and regulatory specificity separate high-value advisory from commoditized offerings.
- Regulatory Compliance:Continuous monitoring of evolving mandates from SEC, EMA, and EU AI Act enforcement bodies. Financial services firms in the United States generate concentrated demand for attestation protocols and documented risk governance frameworks that satisfy examiner scrutiny.
- Risk Assessment:Quantitative modeling of operational, financial, and cyber threats using proprietary algorithms and scenario simulation. Large asset managers deploy these services to stress-test portfolio concentration against climate transition risks and geopolitical volatility.
- Internal Audit:Independent control testing and governance validation for board audit committees.
- Fraud Detection:Forensic analytics and transaction pattern recognition for suspicious activity monitoring.
- Crisis Management:Incident response protocols and reputation recovery for operational disruptions.
- Business Continuity:Resilience planning and disaster recovery architecture for critical infrastructure operators.
Regulatory Compliance leads volumes today; Outcome-based contracting models are gaining share fastest.
Industry Vertical:
Regulatory intensity and penalty severity determine willingness to pay for external advisory.
- Banking:Transaction monitoring system design, anti-money laundering program validation, and Basel III capital adequacy stress testing. US and EU institutions face overlapping enforcement from SEC, EBA, and national competent authorities that internal compliance teams cannot navigate independently.
- Insurance:Solvency II technical provision validation, climate risk integration into underwriting models, and algorithmic fairness testing for automated claims processing. German and French carriers are procuring EU AI Act conformity assessments ahead of binding deadlines.
- Energy & Utilities:Environmental permit compliance and carbon accounting for Scope 3 emissions disclosure.
- Telecommunications:Data retention mandates and consumer privacy protection across multi-jurisdictional operations.
- Manufacturing:Supply chain due diligence and ESG reporting for extended producer responsibility frameworks.
- Government:Public sector procurement integrity and grant compliance monitoring.
Banking captures the largest fee pools currently; Manufacturing is expanding most quickly as ESG thresholds lower.
Client Size:
Organizational complexity and regulatory threshold exposure shape procurement sophistication.
- Large Corporations:Multi-jurisdictional program design integrating SOX internal controls with NIST cybersecurity frameworks and GDPR data governance. These clients unbundle compliance from audit relationships, issuing separate competitive tenders for specialized risk quantification capabilities.
- Mid-sized Enterprises:Rapidly expanding procurement as Germany and France lower regulatory thresholds for mandatory ESG reporting and supply chain due diligence. These organizations lack internal regulatory technology infrastructure and require turnkey compliance platform implementation.
- Multinational Companies:Cross-border service architecture managing divergence between EU comprehensive regulation and US sector-specific enforcement.
- Small Businesses:Outsourced compliance monitoring for sector-specific licensing and tax authority reporting.
Large Corporations dominate current advisory spend; Mid-sized Enterprises show the steepest expansion trajectory.
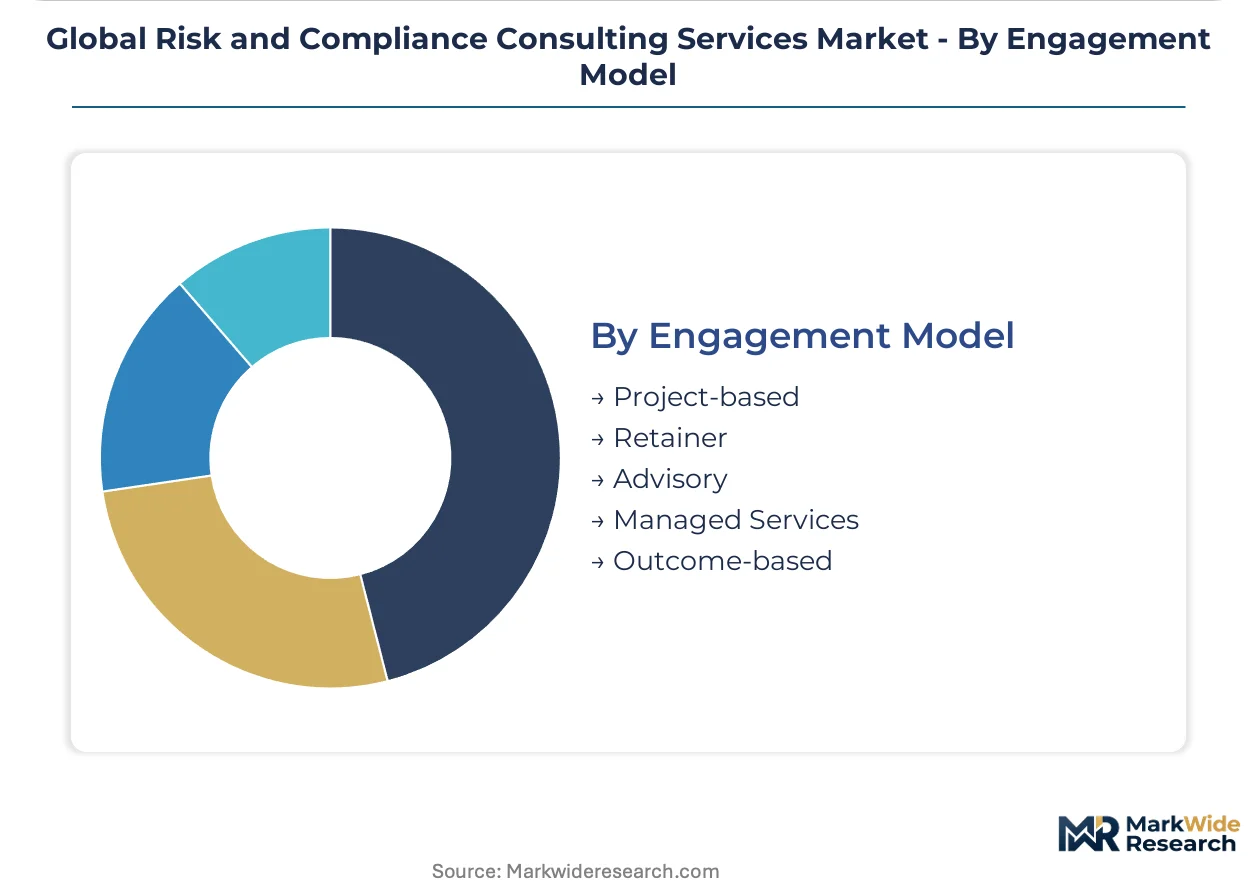
Engagement Model:
Pricing structure and risk transfer mechanisms differentiate procurement approaches.
- Outcome-based:Fixed-fee contracts tied to measurable regulatory finding reductions and audit deficiency remediation. UK procurement departments pilot these structures to shift performance risk onto advisory firms and escape hourly billing constraints.
- Managed Services:Continuous compliance monitoring and regulatory change management delivered through subscription platforms. Cloud-native architecture enables real-time anomaly detection that compresses response latency from weeks to hours.
- Retainer:Ongoing access to specialist practitioners for episodic regulatory interpretation and enforcement response.
- Project-based:Discrete engagements for specific compliance validation or remediation events.
- Advisory:Strategic counsel on governance framework design and board-level risk oversight.
Retainer arrangements still anchor the revenue base; Outcome-based structures are climbing the fastest as procurement functions mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services clusters in New York, London, Frankfurt, and Singapore generate concentrated demand for regulatory advisory as transaction volumes surge and enforcement intensifies across jurisdictions.
United States
SEC climate disclosure mandates and real-time payment system expansion drive procurement of carbon accounting frameworks and transaction monitoring architecture. The New York financial services corridor anchors advisory demand as multinational banks unbundle compliance from audit relationships. Delaware-registered corporations and California technology firms generate parallel demand for privacy and algorithmic accountability advisory.
Germany
Solvency II technical provisions and EU AI Act conformity deadlines pull insurance carriers and automotive manufacturers into mandatory algorithmic impact assessments. Frankfurt's banking concentration sustains demand for Basel III stress testing and anti-money laundering program validation. Bavarian industrial clusters are expanding ESG reporting mandates to mid-sized suppliers previously exempt from supply chain due diligence.
United Kingdom
Outcome-based contracting pilots by FTSE 100 procurement departments reshape fee structures toward fixed-fee regulatory finding reduction guarantees. London's asset management concentration demands climate transition risk quantification and counterparty agreement monitoring against evolving FCA guidance. Edinburgh and Manchester regional centers are building specialized fraud detection and crisis management capabilities.
France
CNIL enforcement actions under GDPR generate recurring compliance validation work for data governance frameworks and breach response protocols. Paris-based luxury conglomerates and aerospace manufacturers are procuring supply chain due diligence advisory as extended producer responsibility thresholds lower. Lyon and Toulouse industrial clusters face new mandatory carbon disclosure requirements for mid-market enterprises.
Singapore
MAS digital banking licenses and cross-border payment corridor expansion create demand for real-time transaction monitoring system design. The city-state's wealth management concentration requires integration of OECD tax transparency frameworks with Asia-Pacific regulatory divergence management. Regional headquarters of European and North American multinationals use Singapore as a hub for ASEAN compliance program coordination.
Global Risk and Compliance Consulting Services Market Competitive Landscape
Global majors compete with regional champions across service delivery models and pricing structures. The vendor base separates into three tiers: full-service networks with regulatory technology partnerships, specialized boutiques with machine learning capabilities, and mid-market firms consolidating around managed services subscriptions. Strategic moves center on outcome-based contracting pilots and cloud-native platform integration with client enterprise resource planning systems.
Within the full-service network tier, Deloitte, PwC, and Accenture anchor competitive positioning through differentiated infrastructure investments. Deloitte exemplifies the regulatory technology partnership archetype, embedding machine learning into governance frameworks through external platform alliances. PwC occupies a position defined by proprietary risk quantification models spanning multiple jurisdictions. Accenture anchors the cloud-native delivery vector, integrating compliance platforms directly with enterprise resource planning systems to compress implementation latency.
| Leading Market Players |
|---|
| KPMG |
| Accenture |
| Deloitte |
| Alvarez & Marsal |
| Boston Consulting Group |
| PwC |
| Protiviti |
| FTI Consulting |
| EY |
| Others |
Supply & Pricing Matrix
Fortune 500 procurement departments concentrate advisory demand among three preferred vendor rosters, anchoring pricing power with full-service networks and compressing margins for mid-tier competitors. This buyer concentration feeds a bifurcated market where outcome-based contracting pilots in the United Kingdom reshape fee structures while retainer arrangements still dominate revenue.
Pricing Analysis
Specialized talent scarcity drives input-cost pass-through into client fees, with practitioners combining regulatory expertise and machine learning engineering commanding compensation premiums. Three-tier pricing structure across premium, standard, and economy levels separates global network advisory from boutique algorithmic specialists and commoditized compliance monitoring subscriptions. Cost compression in mid-tier project-based engagements is intensifying because procurement centralization squeezes competitive positioning. Mid-sized enterprises exhibit highest price sensitivity due to limited regulatory technology budgets, while large corporations with multi-jurisdictional exposure demonstrate lowest sensitivity given penalty exposure.
Supply Chain Analysis
ISO 27001 and SOC 2 certification gating restricts platform vendor eligibility for financial services procurement, filtering cloud-native compliance infrastructure providers. Supply concentrates in the United States, United Kingdom, and Germany where regulatory complexity sustains practitioner density and methodology development. Raw material dependencies include machine learning engineering talent, regulatory text databases, and API connectivity infrastructure. Single-source vulnerability runs through concentrated cloud infrastructure providers hosting compliance platforms. Distribution runs through direct enterprise sales teams and strategic partnerships with systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder sustained by perpetual regulatory updates that internal teams cannot independently satisfy. The structural driver of enforcement intensification across SEC, EMA, and EU AI Act jurisdictions generates recurring advisory demand with low cyclical sensitivity.
For Market Incumbents: Anchor competitive position through proprietary risk quantification model investments spanning multiple jurisdictions. Defend against specialized boutique encroachment by deepening machine learning engineering capabilities in-house. Prioritize outcome-based contracting pilots to align fee structures with procurement department demands for measurable risk reduction guarantees.
For New Entrants and Emerging Players: Begin with mid-sized enterprise penetration in Germany and France where lowering ESG reporting thresholds pull manufacturers into mandatory compliance regimes. Target algorithmic accountability advisory for EU AI Act conformity assessments ahead of binding deadlines. Deploy cloud-native platform implementation as the primary go-to-market angle given turnkey infrastructure gaps at these organizations.
For Investors and Strategic Acquirers: Private equity firms with regulatory technology portfolio companies are the most active acquirer in this space, seeking tuck-in advisory capabilities. The 5-10 year viability window favors platforms with recurring managed services revenue over project-dependent boutiques. Acquisition target archetype: specialized boutiques with domain-specific machine learning capabilities and established EU AI Act methodology. The signal to watch is enforcement headcount expansion at German and Italian market surveillance authorities indicating sustained algorithmic accountability demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Outcome-Based Contracting Pilot | UK procurement departments shift performance risk onto advisory firms through fixed-fee regulatory finding reduction guarantees. |
| Machine Learning Engineering Acquisition | Full-service networks acquire specialized boutiques to embed algorithmic risk detection into governance frameworks. |
| Cloud-Native Platform Integration | Compliance infrastructure vendors compress implementation latency through direct ERP system connectivity. |
| EU AI Act Conformity Methodology Buildout | German and Italian regulatory headcount expansion creates sustained demand for algorithmic impact assessment capabilities. |
| Mid-Market Managed Services Launch | Subscription platforms capture rapidly expanding procurement from manufacturers newly subject to ESG reporting mandates. |
Research Methodology
Multiple input streams — primary interviews with compliance officers and regulatory technology procurement leads, secondary validation through SEC enforcement action databases and EU AI Act implementation guidance — were reconciled through bottom-up and top-down triangulation. Stakeholder roles engaged include chief risk officers at multinational banks, regulatory affairs directors at insurance carriers, procurement managers at asset management firms, and platform engineering leads at advisory firms. Secondary sources span SEC no-action letter repositories, EBA guideline publications, CNIL enforcement decision archives, and hyperscaler compliance infrastructure disclosures.
Historical trend analysis cross-referenced against panel input from practitioner interviews established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include service type, industry vertical, client size tier, and engagement model complexity alongside regional regulatory cluster divergence. CAGRs were derived from weighted scenario outputs incorporating enforcement frequency projections and regulatory threshold adjustment schedules. Industry-specific forecast inputs include SEC climate disclosure mandate implementation pace and EU AI Act conformity deadline proximity.
Several conditions sit outside the modeled scope, including unanticipated regulatory repeal, geopolitical disruption of cross-border service delivery, and technological substitution of advisory services through autonomous compliance systems. Forecasts reflect assumptions regarding sustained enforcement intensification and regulatory complexity expansion. A model refresh is warranted upon material change in SEC examination staffing levels or EU AI Act penalty precedent establishment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Sustainable Finance Market
Risk Management and Compliance
Asia-Pacific Sustainable Finance Market
Risk Management and Compliance
Sell-Side Due Diligence Services Market
Risk Management and Compliance
China Enterprise Risk Management Market
Risk Management and Compliance
Risk Analytics Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Financial Risk Management Software Market
Risk Management and Compliance
Treasury and Risk Management Application Market
Risk Management and Compliance
United States Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Third Party Risk Management Market
Risk Management and Compliance
Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Regtech Market
Risk Management and Compliance
UK Anti Money Laundering Solutions Market
Risk Management and Compliance
Compliance As a Service Market
Risk Management and Compliance
NPL Management Market
Risk Management and Compliance
Southeast Asia Credit and Risk Management Market