
 NPL Management Market | 2026-2036
NPL Management Market Size, Share, and Industry Trends Forecast 2026-2036
NPL Management Market Insights
Spain's distressed-asset servicing infrastructure is reconfiguring how European banks offload legacy exposure. Intrum leverages its pan-European collections platform to sustain scale advantages across multiple jurisdictions. Cerberus Capital Management anchors its position through deep workout capabilities in commercial real estate portfolios. Davidson Kempner competes by specializing in complex corporate restructurings that require litigation-ready capital deployment.
Non-performing loan management encompasses the systematic identification, valuation, recovery, and resolution of defaulted or delinquent credit exposures through specialized servicing platforms, analytics engines, and legal enforcement mechanisms. The discipline relies on probability-of-default modeling, collateral valuation algorithms, and cash-flow forecasting to maximize recovery rates while minimizing time-to-resolution. Software platforms dominate technology spending as banks prioritize real-time portfolio monitoring and automated workflow orchestration over legacy spreadsheet-based tracking. Debt recovery applications absorb the largest share of operational investment, though loan restructuring tools are expanding fastest as regulators encourage sustainable borrower workouts over immediate foreclosure. Cloud-based deployment modes now lead new implementations, displacing on-premises installations that require dedicated IT maintenance and longer integration cycles.
Basel III capital adequacy rules, the EU's Non-Performing Loans Directive, and national insolvency codes collectively reshape how servicers structure resolution timelines and reporting transparency. The European Banking Authority's standardized NPL definition forces cross-border comparability, while the US OCC issues guidance on prudent workout arrangements for national banks. Stakeholders must monitor how digital asset tokenization and secondary market platforms alter traditional recovery timelines and buyer-seller matching efficiency.
Market Dynamics
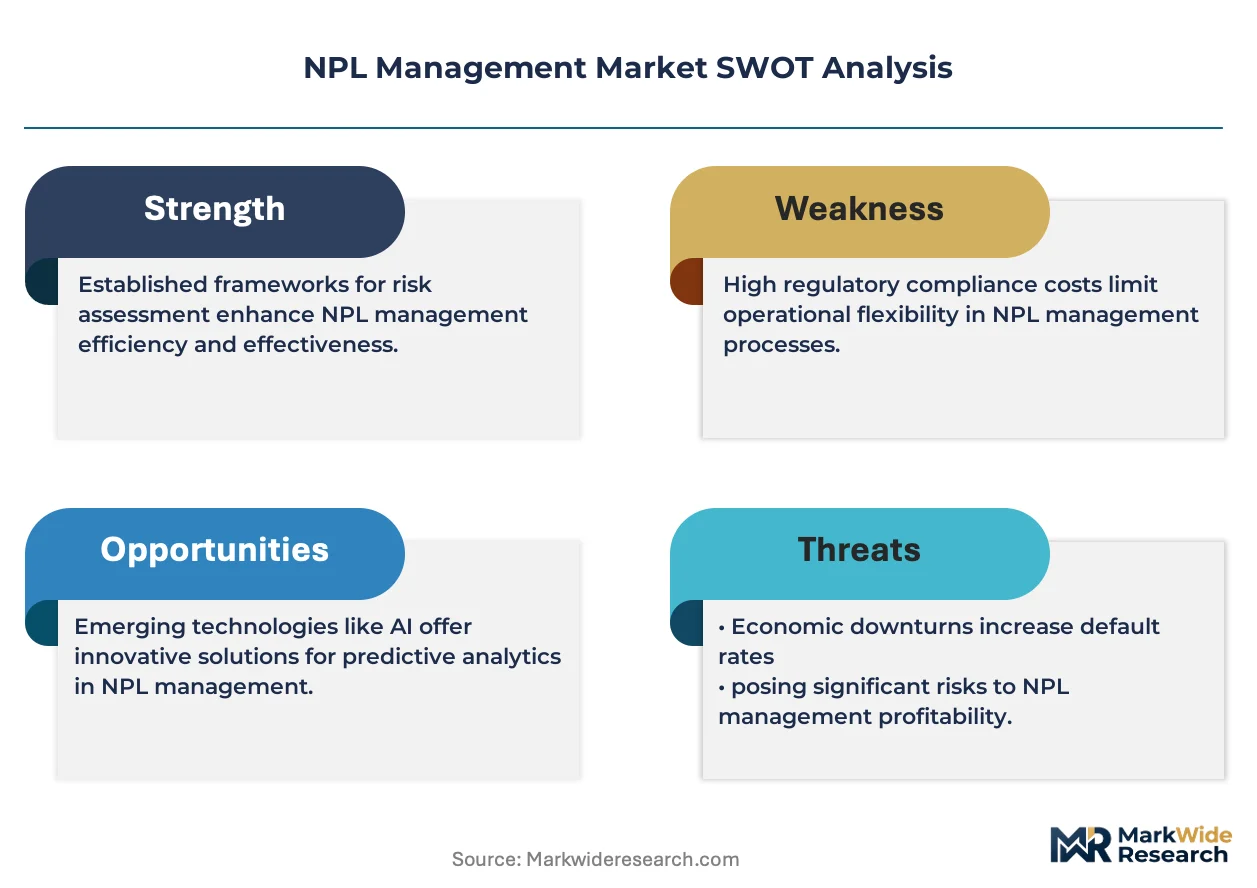
Basel III endgame rules are compressing resolution timelines for distressed credit, forcing servicers to deploy real-time analytics platforms that automate provisioning workflows and collateral liquidation sequencing.
Growth Catalysts
- India's Asset Quality Review:The Reserve Bank of India mandated recognition of stressed assets across commercial bank portfolios, creating immediate demand for specialized workout platforms and legal enforcement services.
- Cloud Migration:Debt servicers are abandoning on-premises infrastructure for cloud-native deployment models that reduce IT maintenance cycles and accelerate portfolio onboarding.
- Southeast Asian NPL Ratios:Commercial banks in Indonesia, Thailand, and Vietnam face elevated non-performing loan levels post-pandemic, driving outsourcing of recovery operations to specialized third-party platforms.
Market Restraints
- Legacy System Integration:Core banking systems at established institutions resist API connectivity with modern servicing platforms, extending implementation timelines and inflating customization costs.
- Collateral Valuation Volatility:Commercial real estate price uncertainty in European urban centers complicates loan-to-value assessments and delays recovery rate projections.
- Cross-Border Enforcement Friction:Divergent national insolvency codes across EU member states fragment resolution strategies for pan-European loan portfolios.
Strategic Opportunities
- Digital Asset Tokenization:Blockchain-based secondary market platforms are enabling fractional ownership of distressed debt, expanding the buyer pool beyond traditional institutional investors.
- EU NPL Directive:The European Banking Authority's standardized disclosure requirements create compliance-driven demand for automated reporting and portfolio monitoring tools.
- Sustainable Workout Tools:Regulators in Germany and France are incentivizing loan modification over foreclosure, accelerating adoption of borrower-centric restructuring software.
Industry Challenges
- Specialized Talent Scarcity:The intersection of credit analytics, legal enforcement, and software engineering creates recruitment bottlenecks for platform operators seeking hybrid skill profiles.
- Data Fragmentation:Borrower financial records scattered across credit bureaus, court filings, and proprietary bank systems obstruct unified probability-of-default modeling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NPL Management Market |
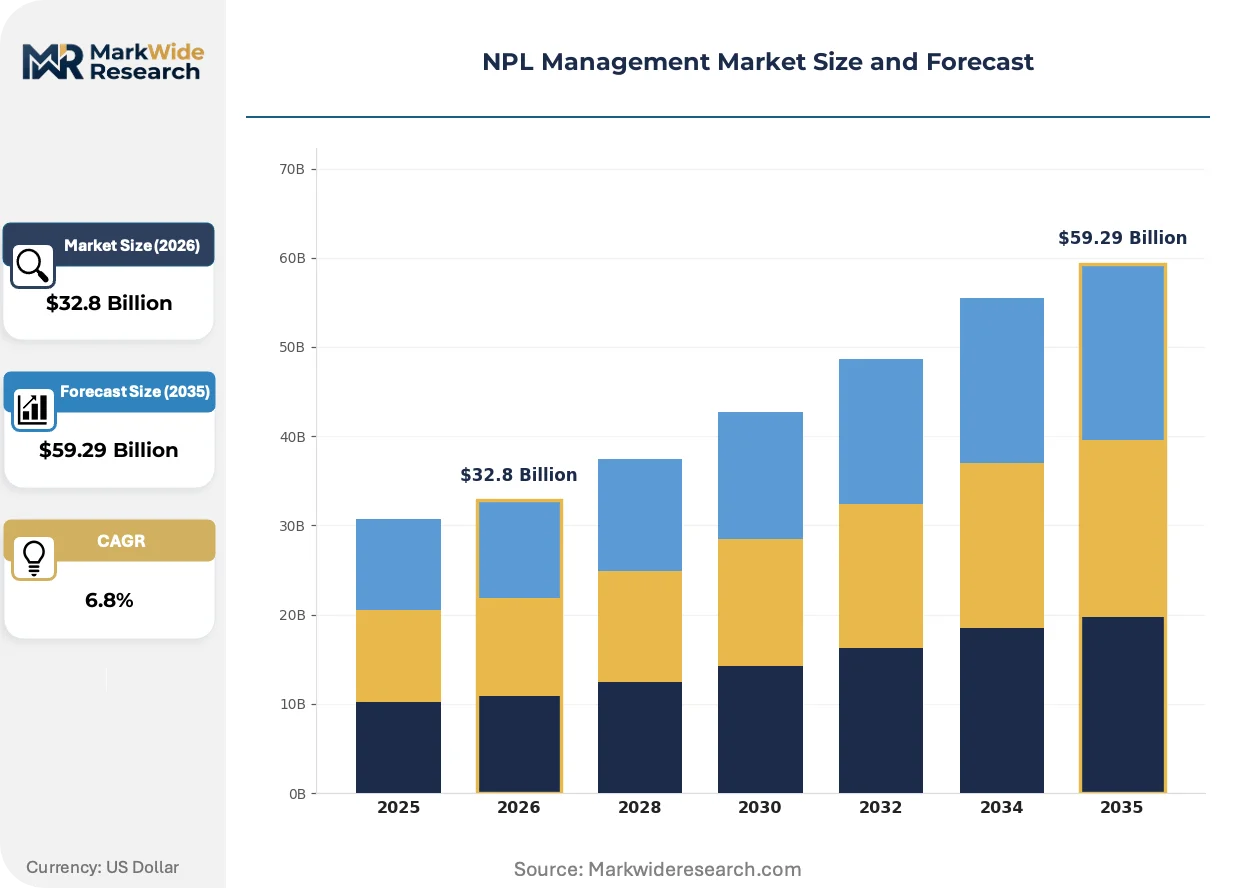
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $59.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Platforms, Analytics Tools, Automation Systems, Reporting Solutions, Risk Assessment Models Application: Debt Recovery, Loan Restructuring, Credit Monitoring, Risk Mitigation, Portfolio Analytics End User: Commercial Banks, Non-Banking Financial Companies, Credit Unions, Debt Collection Agencies, Microfinance Institutions Deployment Mode: Cloud-Based, On-Premises, Hybrid Systems, SaaS, Managed Services |
| Companies Covered | Intrum, Lone Star Funds, Cerberus Capital Management, Davidson Kempner, Bain Capital Credit, Blackstone, Arrow Global, Attestor Capital, Apollo Global Management, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NPL Management Market Trends and Innovations
Artificial intelligence is compressing the gap between loan delinquency detection and recovery initiation, reshaping how servicers prioritize accounts and allocate field agent resources across distributed portfolios.
Machine learning-based probability-of-default scoring is hybridizing traditional statistical models with alternative data streams including utility payment histories and digital transaction patterns. Regional banks in Spain and Italy are piloting these engines for retail mortgage portfolios. The technology is hybridizing risk assessment speed with predictive accuracy, shortening the window between first missed payment and targeted intervention.
The EU's Non-Performing Loans Directive mandates standardized disclosure templates and accelerated provisioning timelines for distressed credit exposures. Servicers must now report granular loan-level data to national regulators within compressed windows. Commercial real estate portfolios across Portugal and Greece face the steepest compliance burdens, driving consolidation among smaller servicing platforms lacking automated reporting infrastructure.
Institutional buyers are unbundling after-sales servicing from primary debt acquisition, contracting specialized platforms for collections while retaining workout strategy in-house. This bifurcation is displacing vertically integrated servicers in the UK and Netherlands. Private credit funds deploying capital into Italian distressed corporate loans most visibly exhibit this pattern, separating capital deployment from operational execution.
NPL Management Market Segmentation
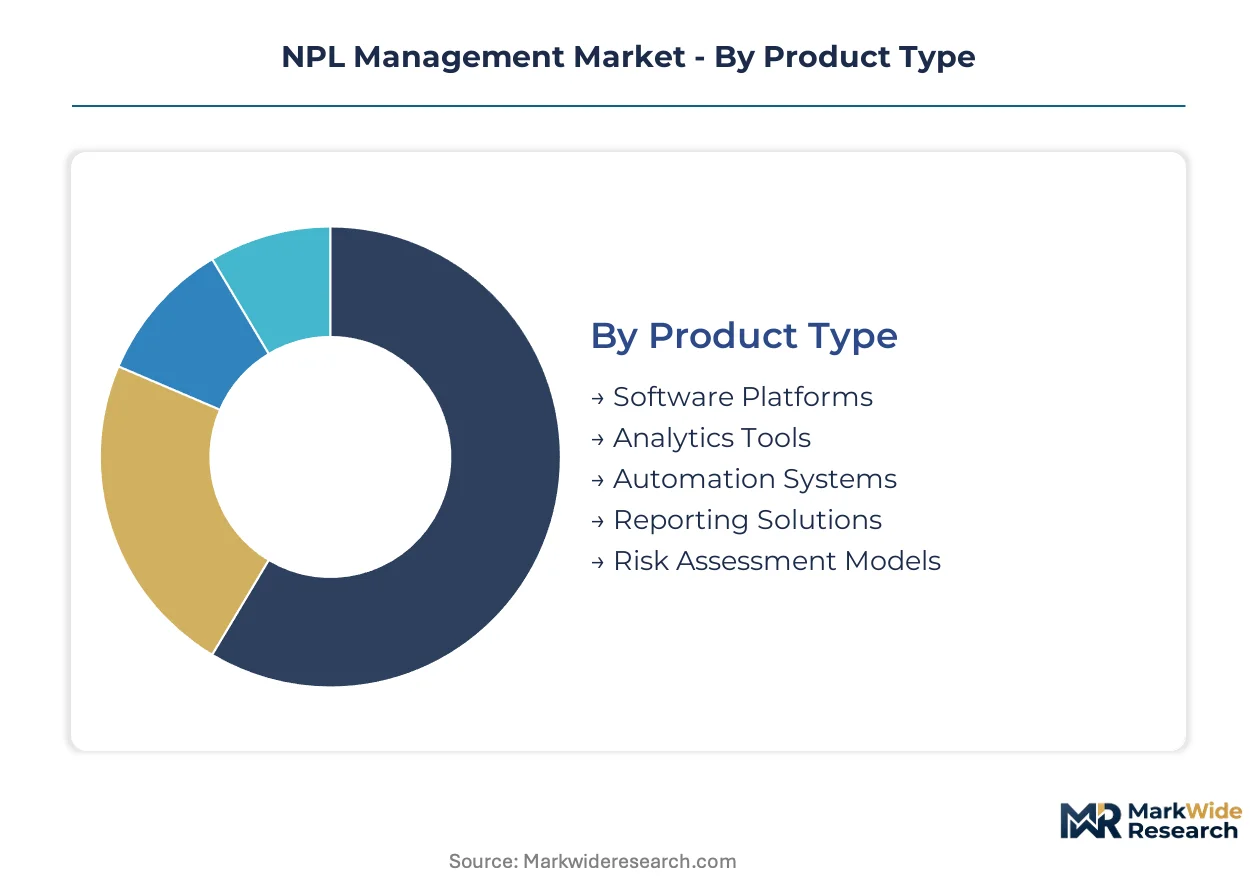
NPL management platforms segment across technology layers, operational applications, and institutional buyer profiles. Each dimension reveals distinct procurement priorities: banks prioritize Basel III compliance tools, while collection agencies favor automation density over analytics depth.
Product Type:
After-sales service intensity varies sharply across product categories, with software platforms demanding continuous update cycles and risk models requiring recalibration support.
- Software Platforms:Core operating systems orchestrate workflow automation, collateral tracking, and regulatory reporting through modular architectures. Commercial banks in India deploy these for Reserve Bank of India-mandated asset quality reviews, prioritizing real-time provisioning engines.
- Analytics Tools:Probability-of-default engines and recovery rate forecasters process borrower behavioral data and macroeconomic indicators. Spanish distressed-asset servicers leverage these for commercial real estate valuation amid price volatility in Madrid and Barcelona.
- Automation Systems:Field agent dispatch algorithms and automated communication protocols reduce time-to-first-contact.
- Reporting Solutions:Standardized disclosure templates align with EU Non-Performing Loans Directive requirements.
- Risk Assessment Models:Machine learning hybrids incorporating alternative data streams.
By volume, Software Platforms leads. By growth pace, Analytics Tools is ahead.
Application:
Application segmentation tracks operational workflow stages from delinquency detection through final recovery, with cost tiers separating enterprise-grade suites from point solutions.
- Debt Recovery:Collections orchestration spans call center automation, legal enforcement triggering, and asset liquidation sequencing. Indonesian commercial banks outsource these functions to third-party platforms as post-pandemic NPL ratios strain internal capacity.
- Loan Restructuring:Borrower workout tools model sustainable payment modifications and forbearance scenarios. German regulators incentivize these over foreclosure, accelerating adoption among Landesbanken and cooperative banks.
- Credit Monitoring:Early warning systems flag deterioration before technical default.
- Risk Mitigation:Portfolio-level hedging and diversification analytics.
- Portfolio Analytics:Granular loan-level performance tracking for investor reporting.
Debt Recovery captures the largest operational spend. Loan Restructuring is expanding most quickly.
End User:
Customer type segmentation distinguishes regulated deposit-takers from specialized servicers, with procurement authority and compliance burdens shaping platform requirements.
- Commercial Banks:Full-service institutions with Basel III provisioning obligations and board-level risk oversight. Vietnamese banks drive regional demand as asset quality reviews force recognition of legacy construction and hospitality exposures.
- Non-Banking Financial Companies:Shadow banking entities with lighter regulatory capital requirements but concentrated credit risk. These firms in India prioritize cost-efficient cloud deployment over on-premises infrastructure.
- Credit Unions:Member-owned cooperatives with limited IT budgets.
- Debt Collection Agencies:Pure-play servicers unbundled from capital deployment.
- Microfinance Institutions:High-volume, small-ticket lenders with mobile-first requirements.
Commercial Banks dominate procurement value. Non-Banking Financial Companies are gaining share fastest.
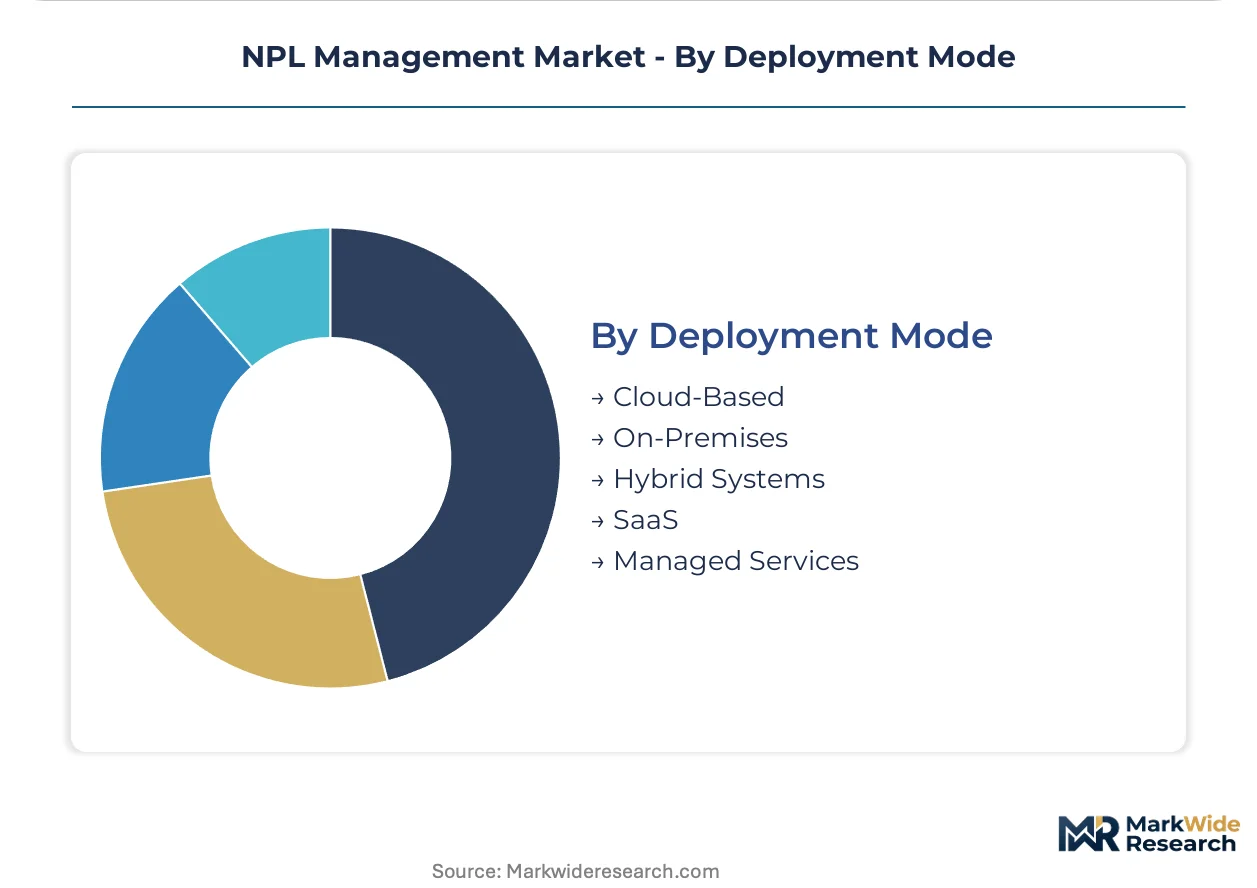
Deployment Mode:
Deployment segmentation reflects infrastructure maturity and data sovereignty constraints, with geography influencing regulatory acceptance of cross-border hosting.
- Cloud-Based:Scalable, API-native architectures with subscription pricing and rapid onboarding. Thai banks accelerated migration post-pandemic to reduce dedicated IT maintenance cycles.
- On-Premises:Installed software behind institutional firewalls for sensitive borrower data. European urban centers with strict data localization requirements retain this model.
- Hybrid Systems:Split architectures keeping core data on-site while leveraging cloud analytics.
- SaaS:Multi-tenant platforms with standardized configurations.
- Managed Services:Outsourced operations combining technology and personnel.
Cloud-Based leads new implementations. Hybrid Systems are climbing fastest among established institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The SWIFT financial messaging infrastructure underwrites Europe's centrality in cross-border NPL trading, while India's Unified Payments Interface accelerates domestic recovery workflows. Southeast Asian banking networks rely on Singapore's interbank clearing systems to coordinate multi-jurisdictional servicing.
Spain
Commercial real estate price volatility in Madrid and Barcelona drives demand for collateral valuation platforms. The EU Non-Performing Loans Directive mandates standardized disclosure templates for distressed credit exposures. Distressed-asset servicers cluster around Barcelona's financial district, where workout specialists manage legacy corporate loan portfolios.
India
The Reserve Bank of India's asset quality reviews forced recognition of stressed assets across commercial bank portfolios. RBI provisioning requirements compel institutions to strengthen capital buffers against non-performing exposures. Mumbai-based servicers deploy cloud-native platforms to manage high-volume retail and SME loan restructuring workflows.
Germany
Landesbanken and cooperative banks prioritize borrower-centric workout tools over foreclosure mechanisms. Federal Financial Supervisory Authority guidelines incentivize sustainable loan modifications for distressed corporate borrowers. Frankfurt's regulatory technology cluster hosts servicing platforms specializing in automated compliance reporting.
Indonesia
Post-pandemic NPL ratios in construction and hospitality sectors strain internal bank capacity. The central bank's macroprudential policies mandate accelerated provisioning for substandard loans. Jakarta-based third-party platforms absorb outsourcing demand from state-owned banks seeking operational scale.
United States
The Office of the Comptroller of the Currency issues guidance on prudent workout arrangements for national banks. OCC examination protocols emphasize documentation standards for loan modification decisions. New York's distressed debt trading desks anchor secondary market liquidity for institutional portfolio transfers.
NPL Management Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in analytics and automation modules. The vendor base concentrates among pan-European servicing conglomerates and private credit funds with captive workout capabilities. Three archetypes dominate: vertically integrated asset owners, pure-play technology platforms, and hybrid capital-deployment specialists. Competitive moves center on portfolio acquisition scale and regulatory technology integration speed.
Within the pan-European servicing tier, Intrum exemplifies platform scale across multiple jurisdictions. Cerberus Capital Management occupies a position among asset-heavy operators with deep workout capabilities. Davidson Kempner represents litigation-ready capital deployment for complex corporate restructurings. These three anchors illustrate how geographic reach, asset specialization, and legal enforcement capacity differentiate competitive positioning.
| Leading Market Players |
|---|
| Intrum |
| Lone Star Funds |
| Cerberus Capital Management |
| Davidson Kempner |
| Bain Capital Credit |
| Blackstone |
| Arrow Global |
| Attestor Capital |
| Apollo Global Management |
| Others |
Pricing and Supply Chain Analysis
Pan-European fiber-optic corridors connecting Frankfurt to Mumbai carry the data traffic that NPL servicing platforms depend on, with bandwidth costs shaping where cloud-native deployment concentrates and how software vendors tier their subscription pricing across emerging and mature banking markets.
Pricing Analysis
Volume-discount tiering structures separate enterprise-grade implementations for Indian commercial banks from mid-market packages serving Indonesian NBFCs and entry-level SaaS for Vietnamese microfinance institutions. Price differentiation hinges on API integration depth and Basel III compliance module bundling, with premium tiers commanding substantial markups for real-time provisioning engines. Cost compression in the standard tier is intensifying because Spanish and Italian regional banks are consolidating vendor relationships to reduce IT maintenance overhead. NBFCs exhibit the highest price sensitivity due to thinner capital buffers, while pan-European servicing conglomerates prioritize functionality over cost.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities allow Indian software developers and Irish cloud infrastructure providers to bridge cash-flow gaps while servicing long implementation cycles at European banks. Component sourcing draws from Estonia for blockchain tokenization modules, India for machine learning development talent, and Ireland for EU data residency compliance. Single-source vulnerability concentrates in specialized credit analytics engines developed by a narrow tier of quantitative firms. Distribution runs through direct enterprise sales teams for commercial banks, supplemented by channel partnerships with systems integrators targeting NBFCs and collection agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward commercial banks in India and Southeast Asia as these institutions consolidate procurement authority under centralized digital transformation offices, fragmenting the previously distributed decision-making that favored point-solution vendors.
For Market Incumbents: Pre-empt displacement by cloud-native entrants through captive development of modular microservices architectures that API-connect with legacy core banking systems. Threat substitution comes from fintech platforms offering workout-as-a-service models that bypass traditional licensing entirely. Priority lever: backward integration into alternative data scoring engines to differentiate probability-of-default offerings. For New Entrants and Emerging Players: Build out specialized restructuring tools for German Landesbanken and French cooperative banks where regulatory incentives favor sustainable borrower workouts over foreclosure mechanisms. The most penetrable segment sits with Indonesian state-owned banks outsourcing post-pandemic recovery operations. Go-to-market angle: partner with Singapore-based interbank clearing infrastructure to credential regional trust. For Investors and Strategic Acquirers: Carve-out targets emerge from European banking groups spinning off captive servicing units to meet EU NPL Directive capital efficiency requirements. Long-term viability frames around regulatory technology integration speed rather than portfolio acquisition scale. Signal to watch: accelerated provisioning timelines forcing smaller Spanish and Greek servicers toward automated reporting infrastructure investments.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Thai and Vietnamese banks reduce IT maintenance cycles while accelerating portfolio onboarding velocity. |
| Alternative Data Scoring Integration | Spanish retail mortgage pilots hybridize utility payment histories with traditional probability-of-default models. |
| EU NPL Directive Compliance Automation | Portuguese commercial real estate servicers consolidate to meet granular loan-level reporting windows. |
| Blockchain Tokenization Partnership | Secondary market platforms expand distressed debt buyer pools beyond traditional institutional investors. |
| Vertical Workout Capability Buildout | Private credit funds unbundle collections execution from capital deployment strategy in Italian corporate loans. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chief risk officers at Indian commercial banks, workout specialists at Spanish distressed-asset servicers, platform engineers at cloud-native NPL software vendors, and regulatory technology leads at Frankfurt compliance consultancies. Secondary validation drew from Reserve Bank of India circulars on asset quality reviews, European Banking Authority disclosure templates, OCC guidance on prudent workout arrangements, and Basel Committee on Banking Supervision provisioning frameworks. Bottom-up segmentation modeling triangulated against top-down macroeconomic scenario analysis.
Calibration against historical provisioning cycles and regulatory implementation timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled encompass deployment mode, institutional buyer type, application workflow stage, and jurisdictional regulatory cluster. CAGRs derived from growth driver elasticity estimates applied to baseline provisioning intensity ratios. Forecast inputs incorporated cloud migration velocity at Southeast Asian banks and EU NPL Directive compliance cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private credit funds deploying litigation-ready capital or fintech platforms offering zero-implementation workout tools would shift outcomes. Macroeconomic deviation, regulatory timeline acceleration, or breakthrough tokenization liquidity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Global Asset Integrity Management Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
Global Liquidity Asset Liability Management Solutions Market
Risk Management and Compliance
Asset Liability Management (ALM) Solution Market
Risk Management and Compliance
Compliance As a Service Market
Risk Management and Compliance
China Enterprise Risk Management Market
Risk Management and Compliance
Europe Risk Management Market
Risk Management and Compliance
Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Trade Surveillance Market
Risk Management and Compliance
BFSI Security Market
Risk Management and Compliance
Surety Market
Risk Management and Compliance
Certificates Market
Risk Management and Compliance
North America Strategic Consulting Market
Risk Management and Compliance
Legal Advisory Service Market
Risk Management and Compliance
Corporate Investigation Services Market