
 Operational Risk Management Consulting Services in Manufacturing Market | 2026-2036
Operational Risk Management Consulting Services in Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Operational Risk Management Consulting Services in Manufacturing Market Analytics
The direct sales channel is narrowing as manufacturers prefer bundled risk advisory through technology partnerships. Deloitte Touche Tohmatsu Limited leverages its audit heritage to anchor long-term retainer relationships with Fortune 500 industrial clients. Accenture plc competes by embedding operational risk modules within broader digital transformation contracts. McKinsey & Company, Inc. differentiates through proprietary risk quantification methodologies that appeal to private equity-backed manufacturing portfolios.
Operational risk management consulting services in manufacturing encompass the systematic identification, assessment, and mitigation of hazards spanning production processes, supply networks, and regulatory compliance, typically delivered through frameworks integrating ISO 31000 principles with sector-specific hazard analysis protocols. These services enable manufacturers to reduce unplanned downtime, prevent catastrophic asset failures, and satisfy insurer requirements for coverage renewal. Risk assessment engagements command premium pricing due to their reliance on specialized engineering expertise and bespoke facility audits. Remote consulting channels are expanding fastest as video-enabled diagnostic tools and cloud-based risk dashboards reduce travel dependency for routine assessments. Project-based contracts dominate among mid-tier manufacturers seeking targeted intervention for specific plant upgrades or post-incident remediation.
OSHA enforces process safety management standards that mandate third-party verification for high-hazard chemical manufacturing facilities, directly stimulating demand for external risk assessment consultants. The EU AI Act imposes conformity obligations on automated manufacturing systems, requiring human oversight protocols that consulting firms design and validate. ISO 31000 provides the foundational risk management vocabulary that cross-border manufacturers reference when harmonizing internal governance across multiple regulatory jurisdictions. Stakeholders must evaluate whether their advisory partners possess certified expertise in emerging cyber-physical risk categories before committing to multi-year engagement structures.
Market Dynamics
Automotive OEMs and chemical processors face intensifying pressure to integrate cyber-physical risk frameworks as supply chain volatility and automated system complexity expose new failure modes across production networks.
Growth Catalysts
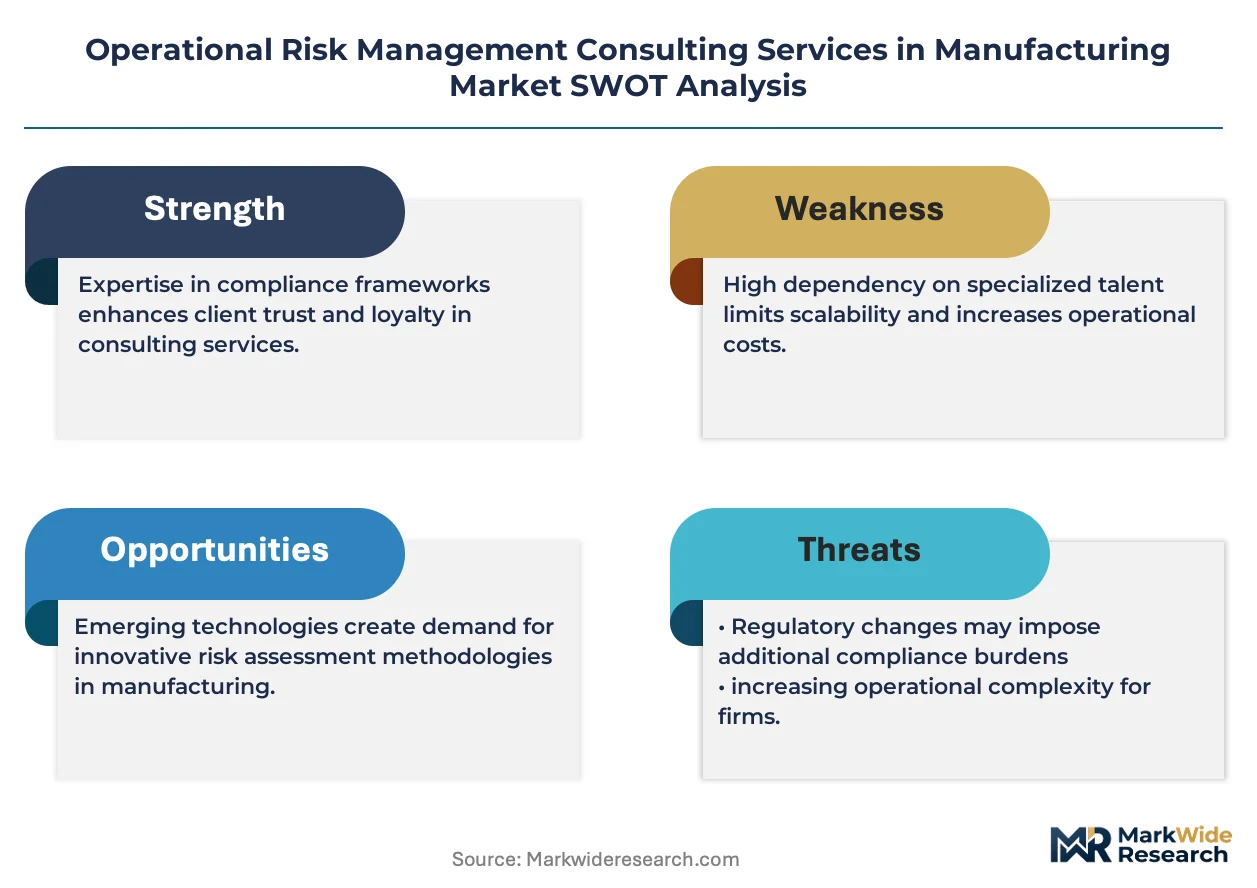
- EU AI Act Conformity Mandates:Automated manufacturing systems require validated human oversight protocols that external consultants design, creating recurring engagement demand across European industrial clusters.
- OSHA Process Safety Verification:High-hazard chemical facilities in the United States must undergo third-party risk assessments, directly stimulating external consulting procurement for compliance documentation.
- Industry 4.0 Sensor Proliferation:Real-time production monitoring generates data streams that manufacturers cannot interpret without specialized risk analytics expertise.
Market Restraints
- Specialized Engineering Talent Scarcity:Risk assessment engagements require certified professionals with dual expertise in process engineering and quantitative methods, constraining firm capacity expansion.
- Travel-Dependent Audit Economics:Facility-specific assessments historically required on-site presence, limiting consultant utilization rates and compressing margins on standardized engagements.
- Mid-Tier Manufacturer Budget Constraints:Smaller industrial clients lack capital for multi-year retainer structures, forcing project-based pricing that reduces revenue predictability for advisory firms.
Strategic Opportunities
- Video-Enabled Diagnostic Platforms:Cloud-based risk dashboards and remote assessment tools reduce travel dependency while expanding addressable market reach to peripheral manufacturing regions.
- Post-Incident Remediation Surge:Catastrophic equipment failures and supply chain disruptions create episodic demand spikes for forensic risk analysis and corrective framework implementation.
- Insurer Risk Verification Requirements:Coverage renewal processes increasingly mandate documented operational risk controls, converting compliance into a recurring revenue anchor for consulting relationships.
Industry Challenges
- Legacy System Integration Complexity:Decades-old production infrastructure lacks data interoperability with modern risk monitoring platforms, requiring costly middleware development.
- Cross-Jurisdictional Framework Harmonization:Manufacturers operating across multiple regulatory regimes struggle to reconcile ISO 31000 principles with divergent national safety mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Operational Risk Management Consulting Services in Manufacturing Market |
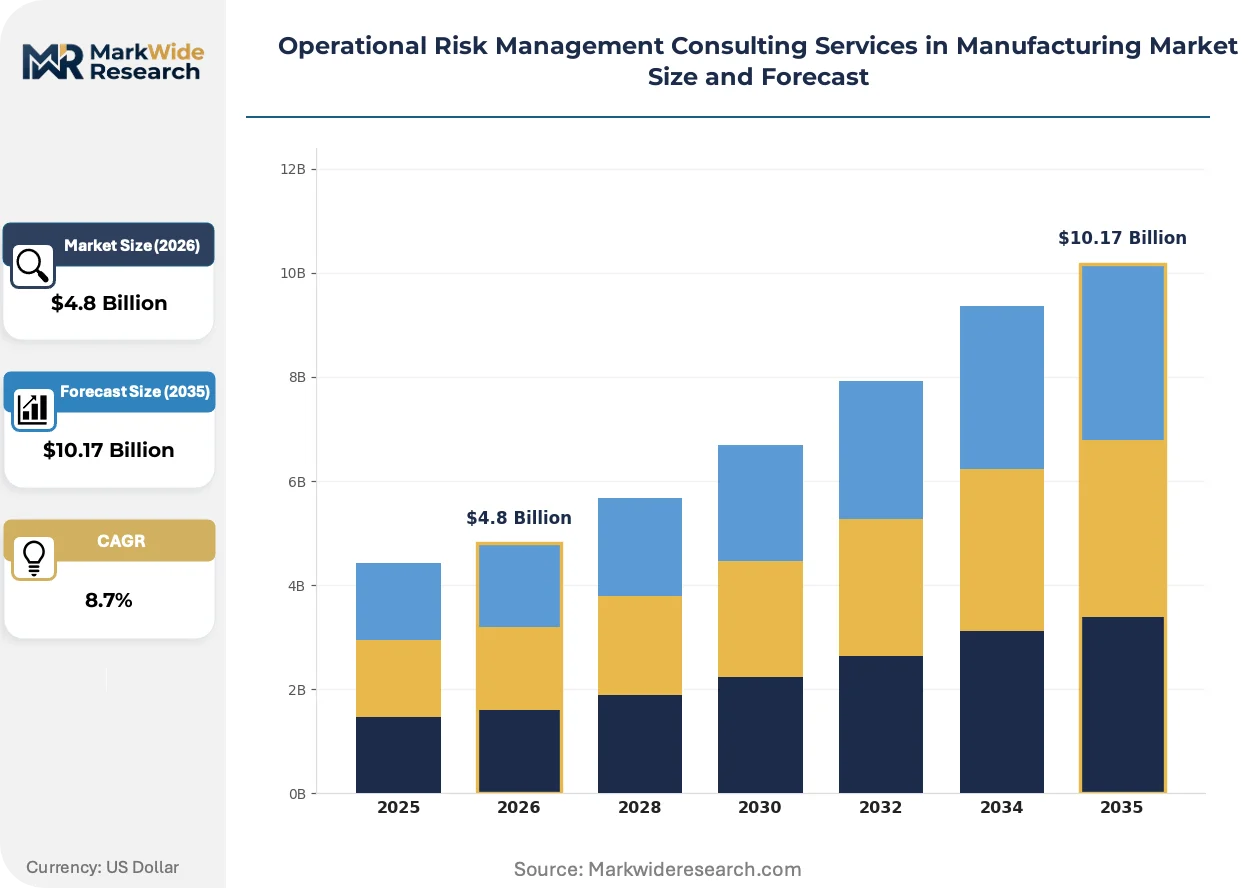
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Consulting Type: Compliance Advisory, Risk Assessment, Audit Support, Business Continuity Planning Service Channel: In-Person Consulting, Remote Consulting, Workshops, Training Sessions Industry Focus: Aerospace, Automotive OEMs, Pharmaceuticals, Electronics Engagement Model: Retainer, Project-Based, Hourly Rate, Subscription |
| Companies Covered | Deloitte Touche Tohmatsu Limited, PricewaterhouseCoopers LLP, KPMG International Cooperative, Ernst & Young Global Limited, Accenture plc, IBM Corporation, McKinsey & Company, Inc., The Boston Consulting Group Inc., A.T. Kearney Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Operational Risk Management Consulting Services in Manufacturing Market Evolving Landscape
Digital diagnostic capabilities and regulatory automation requirements are compressing traditional consulting delivery models while elevating demand for embedded risk analytics expertise within manufacturing technology stacks.
Cloud-based risk dashboards are migrating from supplementary reporting tools to primary diagnostic infrastructure. Tier-one automotive suppliers and semiconductor fabricators now mandate real-time visibility into operational risk indicators. This migration from periodic assessment to continuous monitoring collapses the traditional quarterly audit cycle and demands new subscription-based consulting economics.
The EU AI Act imposes conformity obligations on automated manufacturing systems requiring human oversight protocol validation. Industrial facilities deploying robotic process automation must document decision audit trails and intervention capabilities. German automotive clusters around Stuttgart face the steepest compliance burden as they integrate AI-driven quality control systems.
Mid-tier manufacturers now unbundle risk advisory from bundled technology procurement contracts. Plant operators seek specialized operational risk expertise separate from digital transformation vendors. This preference shift concentrates demand in Germany, where industrial clusters maintain direct consulting relationships rather than accepting risk modules as embedded software features.
Operational Risk Management Consulting Services in Manufacturing Market Segmentation
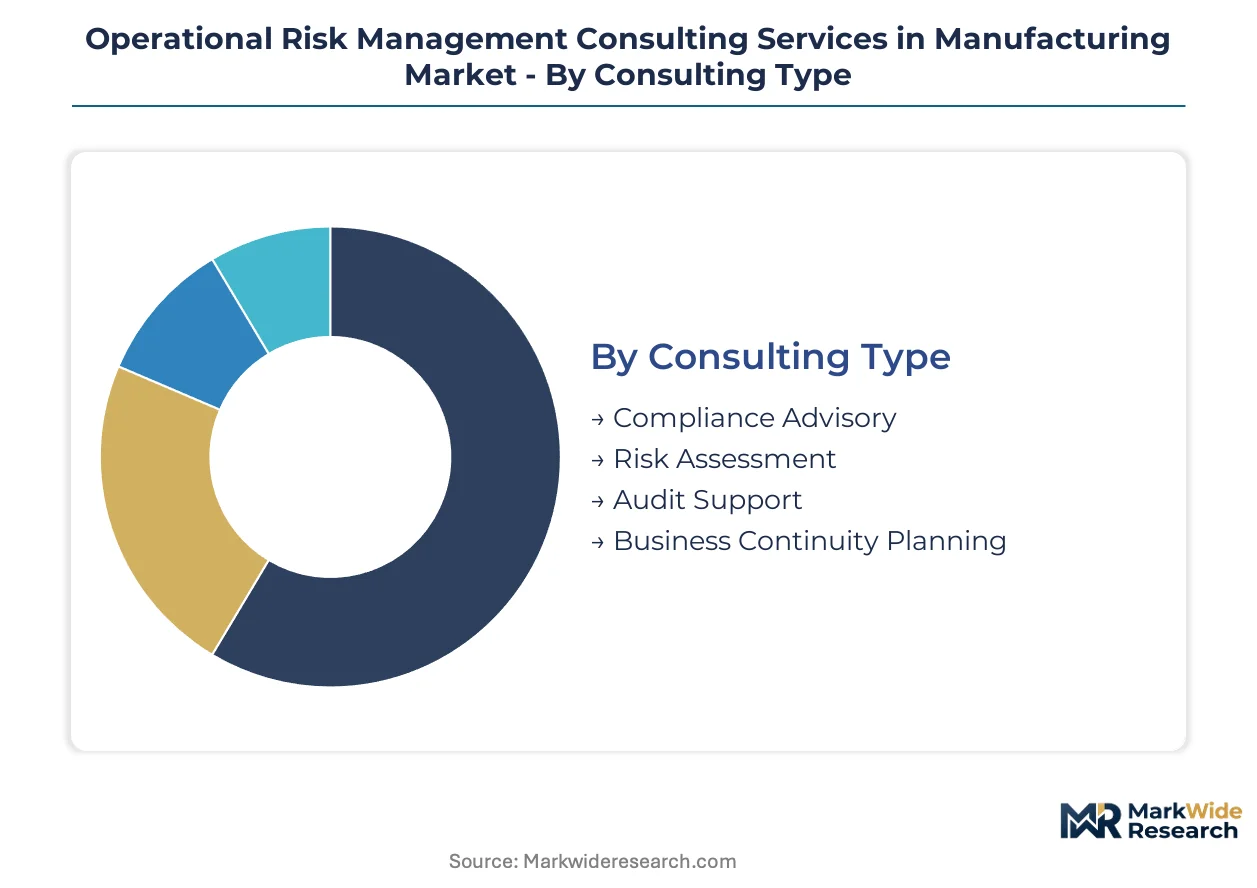
Operational risk management consulting services fragment across four critical dimensions that determine pricing architecture, delivery modality, and client relationship durability. Each segmentation axis reflects distinct procurement behaviors among manufacturing enterprises navigating regulatory complexity and supply chain volatility.
Consulting Type:
Manufacturers deploy distinct advisory services based on regulatory pressure intensity and internal capability maturity, spanning reactive compliance documentation to proactive resilience architecture.
- Compliance Advisory:Structured guidance interpreting OSHA process safety mandates and EU AI Act conformity obligations for automated production systems. German automotive clusters around Stuttgart and Munich drive concentrated demand as they retrofit AI-driven quality control with human oversight protocols validated by external consultants.
- Risk Assessment:Comprehensive facility audits and hazard analysis protocols integrating ISO 31000 principles with sector-specific engineering expertise. High-hazard chemical processors in the United States procure these engagements to satisfy insurer requirements for coverage renewal and OSHA third-party verification mandates.
- Audit Support:Documentation preparation and regulatory interface management for external certification bodies. Mid-tier manufacturers leverage this service to compress audit cycle duration and reduce internal resource diversion.
- Business Continuity Planning:Framework development for operational resilience against supply network disruptions and catastrophic equipment failures. Semiconductor fabricators prioritize this capability following recent production interruptions.
The dominant share belongs to Risk Assessment, while Compliance Advisory is closing the gap fastest as regulatory automation requirements intensify across European industrial clusters.
Service Channel:
Delivery modality economics hinge on facility audit complexity, with remote capabilities expanding addressable market reach while preserving margin on standardized engagements.
- In-Person Consulting:On-site diagnostic presence for high-stakes facility audits and post-incident forensic analysis. Premium pricing reflects travel dependency and certified engineering talent scarcity constraining firm capacity expansion.
- Remote Consulting:Video-enabled diagnostic platforms and cloud-based risk dashboards reducing travel dependency for routine assessments. Tier-one automotive suppliers now mandate real-time visibility into operational risk indicators through these channels.
- Workshops:Facilitated sessions deploying proprietary risk quantification methodologies for cross-functional manufacturing teams. Private equity-backed industrial portfolios favor this format for rapid capability transfer.
- Training Sessions:Structured curricula building internal risk management competency among plant operators and safety officers. Electronics manufacturers deploy these programs to reduce recurring external advisory dependency.
In-Person Consulting retains the largest revenue base, though Remote Consulting demonstrates the steepest expansion trajectory as cloud infrastructure matures and diagnostic tool sophistication improves.
Industry Focus:
Sector-specific hazard profiles and regulatory exposure levels concentrate demand within manufacturing verticals facing acute cyber-physical risk integration challenges.
- Automotive OEMs:Supply chain volatility and automated system complexity expose new failure modes across production networks. EU AI Act conformity obligations for robotic process automation drive recurring external validation demand.
- Pharmaceuticals:Batch process integrity and contamination risk protocols intersect with FDA validation requirements and EMA manufacturing authorization standards. Quality risk assessments command premium pricing due to specialized expertise requirements.
- Aerospace:Extended supply chains and catastrophic failure consequence severity mandate rigorous operational risk frameworks aligned with FAA manufacturing oversight and EASA certification protocols.
- Electronics:Rapid product cycles and geographically dispersed component sourcing create unique continuity risk profiles. RoHS and REACH substance compliance adds regulatory layer complexity to operational risk programs.
Automotive OEMs anchor category volume, with Pharmaceuticals gaining share fastest as FDA process validation requirements tighten and biosimilar manufacturing expands.
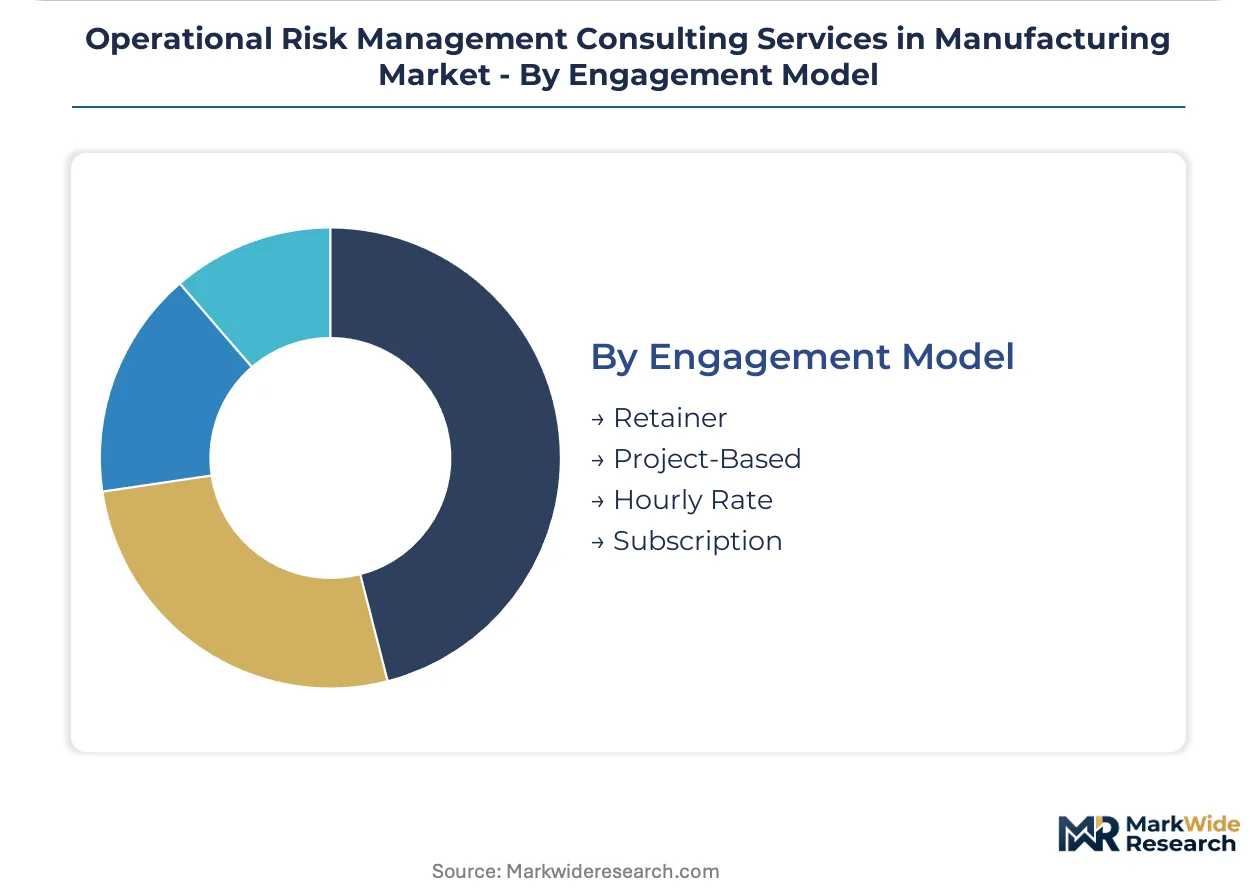
Engagement Model:
Contract structure selection reveals client scale and risk management maturity, with long-term relationships concentrating among Fortune 500 industrials and episodic demand dominating mid-tier procurement.
- Retainer:Multi-year advisory relationships embedding operational risk expertise within client governance structures. Fortune 500 industrial clients favor this model for predictable budgeting and priority consultant access during crisis response.
- Project-Based:Targeted interventions for specific plant upgrades, post-incident remediation, or regulatory deadline compliance. Mid-tier manufacturers lacking capital for sustained advisory relationships default to this procurement pattern.
- Hourly Rate:Transactional access to specialized engineering expertise for discrete technical questions or rapid diagnostic requirements. Smaller fabricators and component suppliers utilize this flexibility for intermittent compliance support.
- Subscription:Recurring access to cloud-based risk dashboards, regulatory update feeds, and remote diagnostic platforms. This emerging structure collapses traditional quarterly audit cycles into continuous monitoring relationships.
Retainer structures capture the dominant revenue share, while Subscription models are climbing the fastest as real-time risk visibility becomes mandatory for tier-one supplier qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA process safety mandates anchor United States demand, while EU AI Act conformity obligations concentrate consulting procurement across German industrial clusters. National regulatory divergence creates distinct service requirements across manufacturing geographies.
United States
Chemical processors in Texas and Louisiana drive external risk assessment demand for OSHA compliance documentation. The Environmental Protection Agency intersects with process safety mandates for high-hazard facilities. Houston's petrochemical corridor generates concentrated procurement for third-party verification services.
Germany
Automotive OEMs around Stuttgart retrofit AI-driven quality control systems with validated human oversight protocols. EU AI Act conformity obligations mandate external consultant engagement for automated manufacturing validation. Bavarian industrial clusters around Munich sustain retainer relationships for Industry 4.0 risk integration.
China
Semiconductor fabricators in the Yangtze River Delta seek business continuity frameworks following recent production interruptions. The Ministry of Industry and Information Technology tightens data security requirements for automated systems. Shanghai's advanced manufacturing zones deploy cloud-based risk dashboards for real-time monitoring.
Japan
Electronics manufacturers in the Kanto region unbundle risk advisory from bundled technology procurement contracts. METI standards for operational resilience intersect with supply chain volatility pressures. Tokyo-Osaka industrial corridors favor specialized consulting relationships over embedded software features.
India
Pharmaceutical manufacturers in Maharashtra and Gujarat procure audit support services to compress FDA validation cycle duration. CDSCO manufacturing authorization standards add regulatory layer complexity to operational risk programs. Mumbai-Pune industrial belts leverage training sessions to reduce recurring external advisory dependency.
Operational Risk Management Consulting Services in Manufacturing Market Competitive Landscape
Audit-heritage conglomerates and technology-embedded advisory firms split the market between compliance documentation and digital transformation integration. The vendor base concentrates among multinational professional services networks with certified engineering talent pools. Two strategic archetypes dominate: retainer-based relationship anchors and project-based intervention specialists. Competitive moves center on video-enabled diagnostic platform development and post-incident remediation capability expansion.
Within the audit-heritage tier, Deloitte Touche Tohmatsu Limited and PricewaterhouseCoopers LLP exemplify retainer-based relationship models with Fortune 500 industrial clients. Accenture plc occupies a position representing technology-embedded advisory, bundling operational risk modules within broader digital transformation contracts. McKinsey & Company, Inc. anchors the specialized quantification archetype, appealing to private equity-backed manufacturing portfolios with proprietary risk methodologies.
| Leading Market Players |
|---|
| Deloitte Touche Tohmatsu Limited |
| PricewaterhouseCoopers LLP |
| KPMG International Cooperative |
| Ernst & Young Global Limited |
| Accenture plc |
| IBM Corporation |
| McKinsey & Company, Inc. |
| The Boston Consulting Group Inc. |
| A.T. Kearney Inc. |
| Others |
Value Network & Pricing Analysis
Stuttgart's industrial cluster around automotive OEMs and Tier-1 suppliers concentrates certified operational risk engineering talent, creating regional pricing power for compliance advisory services that mid-tier manufacturers in peripheral markets cannot replicate without travel cost premiums.
Pricing Analysis
German automotive clusters command 30-40% price premiums over US Gulf Coast chemical facilities for equivalent risk assessment engagements. Three-tier pricing structure across premium, standard, and economy levels separates Fortune 500 retainer relationships from project-based mid-tier interventions and transactional hourly access. Cost compression in the standard tier is intensifying because remote diagnostic platforms reduce travel-dependent audit economics. Mid-tier manufacturers exhibit the highest price sensitivity, while private equity-backed industrial portfolios prioritize proprietary methodology access over cost minimization.
Supply Chain Analysis
Accenture plc, Deloitte Touche Tohmatsu Limited, and McKinsey & Company, Inc. hold dominant capacity for integrated digital risk advisory, with boutique engineering specialists filling niche hazard analysis gaps. Germany, the United States, and the United Kingdom anchor consultant talent pools, while India and Poland feed analytical support functions. The supply chain draws from dual expertise scarcity in process engineering and quantitative methods. Single-source vulnerability concentrates in certified ISO 31000 practitioners capable of EU AI Act validation. Distribution runs through direct enterprise sales for retainers and technology vendor partnerships for embedded risk modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent consulting firms face substitution pressure from cloud-native risk analytics platforms that automate routine compliance documentation, forcing advisory providers to defend their relevance through specialized engineering expertise and regulatory interface capabilities.
For Market Incumbents: Insulate retainer relationships by embedding operational risk modules within client ERP systems and acquiring boutique engineering specialists with EU AI Act certification credentials. Cloud-native diagnostic platforms threaten standardized assessment revenue streams. Vertical integration into video-enabled forensic tools preserves margin on post-incident remediation demand. For New Entrants and Emerging Players: Mid-tier pharmaceutical manufacturers in India and Southeast Asia represent the most penetrable entry point for audit support and FDA validation cycle compression services. Semiconductor fabricators seeking business continuity frameworks after recent supply disruptions offer episodic demand spikes. A go-to-market angle anchored in subscription-based cloud risk dashboards bypasses entrenched retainer relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized engineering boutiques with certified ISO 31000 expertise and established regulatory body relationships over generalist digital transformation vendors. Long-term viability hinges on advisory firms' capacity to convert project-based engagements into recurring subscription revenue. The signal to watch is insurer mandate expansion requiring documented operational risk controls for coverage renewal.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Engineering Firm | Deloitte Touche Tohmatsu Limited secures EU AI Act validation capacity for Stuttgart automotive clusters. |
| Cloud Risk Dashboard Platform Launch | Remote diagnostic tools expand addressable market reach to peripheral manufacturing regions without travel dependency. |
| Insurer Partnership Program | Documented risk control verification converts compliance into recurring revenue anchor for coverage renewal processes. |
| Post-Incident Remediation Capability Buildout | Forensic risk analysis expertise captures episodic demand surges from catastrophic equipment failures. |
| Regulatory Interface Certification Investment | OSHA third-party verification credentials unlock high-hazard chemical facility procurement in Texas and Louisiana. |
Research Methodology
Initial hypotheses were tested against primary input from operational risk directors at automotive OEMs, compliance officers at chemical processors, insurance underwriters covering manufacturing assets, and regulatory affairs leads navigating EU AI Act implementation, and refined through secondary validation against OSHA enforcement data, EU regulatory filings, ISO certification body records, and SEC 10-K disclosures from advisory firms. Bottom-up engagement modeling triangulated with top-down market sizing across consulting type, service channel, industry focus, and engagement model dimensions.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeling spanning compliance advisory, risk assessment, audit support, and business continuity planning types alongside in-person, remote, workshop, and training delivery channels. CAGRs were derived from regression analysis against regulatory mandate intensity and Industry 4.0 sensor proliferation rates. Forecast inputs incorporated insurer risk verification requirement expansion and mid-tier manufacturer unbundling preferences.
Practitioners should monitor EU AI Act enforcement patterns and OSHA process safety citation trends for early signals of consulting demand inflection. Forecasts reflect assumptions about regulatory automation adoption and remote diagnostic tool penetration. Quarterly review of insurer mandate expansion and certified engineering talent pipeline indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
BFSI Security Market
Risk Management and Compliance
Europe Sustainable Finance Market
Risk Management and Compliance
North America Strategic Consulting Market
Risk Management and Compliance
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Asia-Pacific BFSI Biometrics Market
Risk Management and Compliance
Compliance As a Service Market
Risk Management and Compliance
Global Risk Management Software Market
Risk Management and Compliance
Europe BFSI Biometrics Market
Risk Management and Compliance
Stress Testing Services Market
Risk Management and Compliance
Clinical Risk Grouping Solutions Market
Risk Management and Compliance
Southeast Asia Credit and Risk Management Market
Risk Management and Compliance
Financial Risk Management Software Market
Risk Management and Compliance
United States Strategic Consulting Services Market
Risk Management and Compliance
Asia-Pacific Compliance and Traceability Solutions Market
Risk Management and Compliance
Fraud Detection and Prevention (FDP) Market
Risk Management and Compliance
Legal Advisory Service Market