
 UK Anti Money Laundering Solutions Market | 2026-2036
UK Anti Money Laundering Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
UK Anti Money Laundering Solutions Market Analytics
Project finance tied to multi-year SaaS subscriptions is narrowing the competitive field for mid-tier vendors. Quantexa leverages network analytics capabilities to anchor its position in complex entity-resolution deployments. BAE Systems sustains its defence-adjacent credibility through intelligence-grade data fusion architectures. Experian Information Solutions competes on credit-data adjacency, embedding identity verification within broader risk orchestration workflows.
Anti money laundering solutions comprise software platforms that automate suspicious activity detection, customer risk scoring, and regulatory reporting through rules engines, machine learning classifiers, and graph analytics. These systems process transactional telemetry, adverse media, and biometric identity signals to flag predicate offences including layering, structuring, and trade-based laundering before filing suspicious activity reports. Transaction monitoring occupies the largest solution-type position, though customer due diligence is expanding fastest as perpetual KYC mandates replace point-in-time checks. Cloud-based deployment leads among challenger banks and fintechs, while hybrid architectures dominate established financial institutions balancing latency sensitivity with regulatory data-localization expectations.
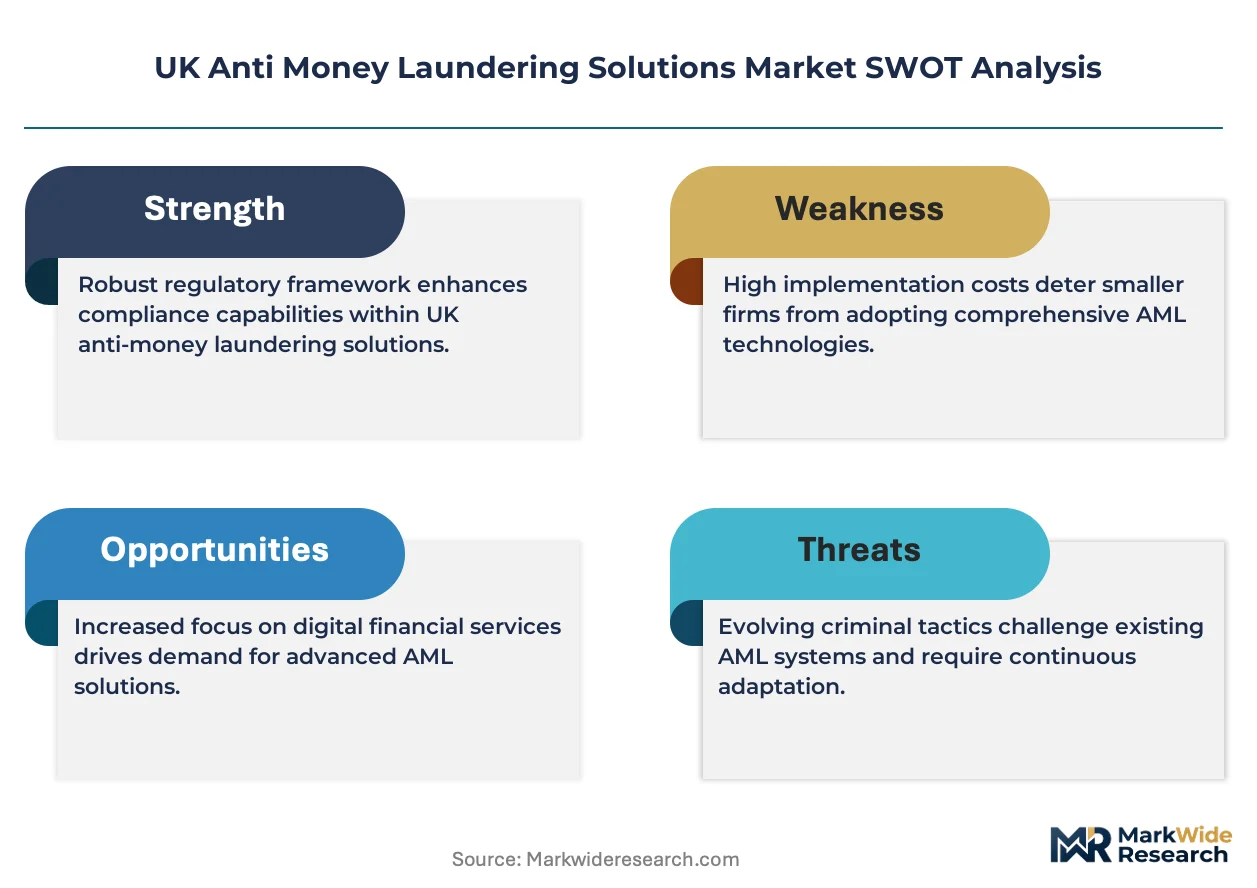
The Financial Conduct Authority enforces the Money Laundering Regulations through thematic reviews and significant financial penalties, directly shaping vendor feature priorities around audit trails and explainability. HMRC supervises accountancy and legal sector compliance, creating fragmented buyer requirements across client-type segments. The UK's post-Brexit alignment with FATF Recommendation 16 on wire transfer transparency sustains cross-border data-sharing infrastructure investments. Stakeholders must weigh the pace of AI-guided transaction monitoring adoption against pending regulatory clarity on algorithmic accountability standards.
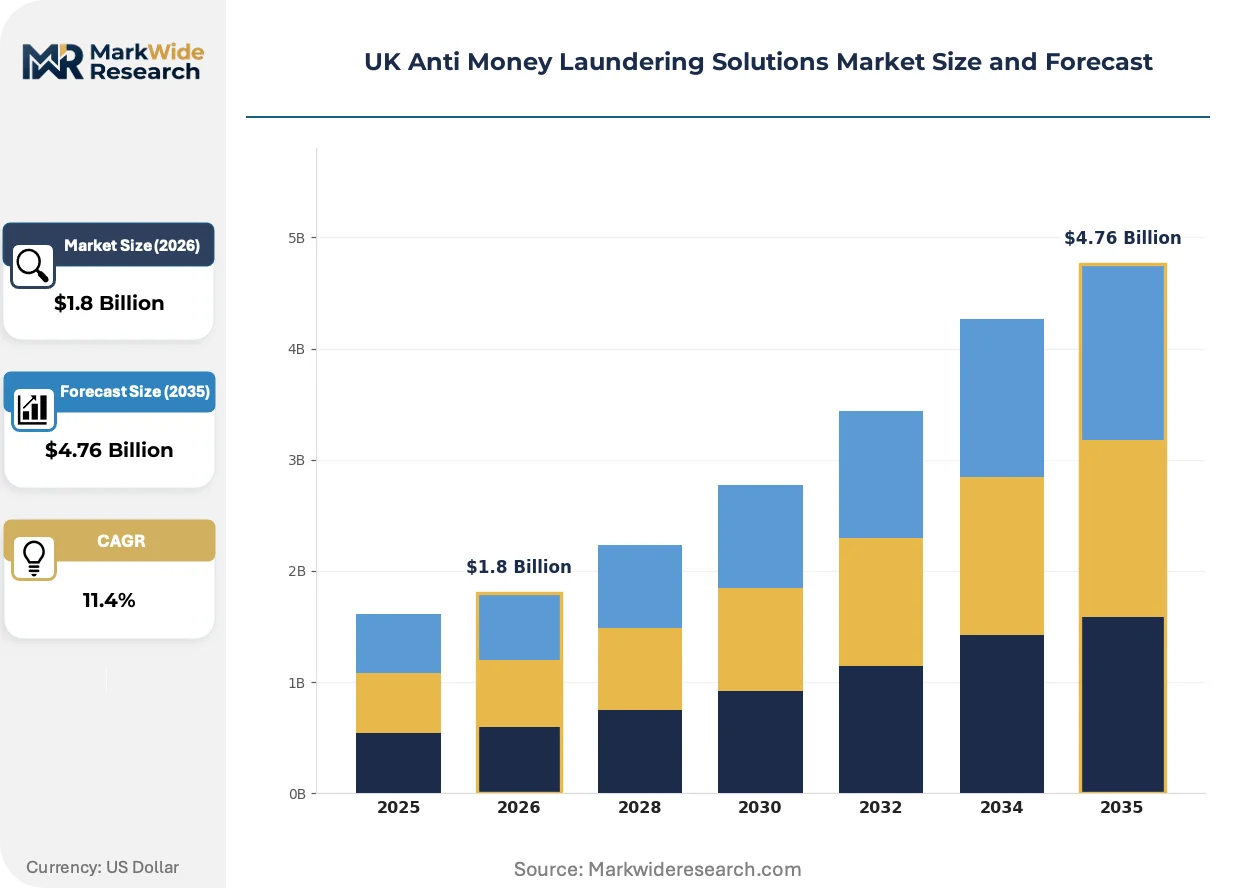
Market Dynamics
FCA enforcement intensity is compressing procurement cycles for transaction monitoring upgrades, forcing British retail banks to accelerate SaaS migrations while maintaining audit-grade explainability for machine learning classifiers.
Growth Catalysts
- Perpetual KYC mandates:The Money Laundering Regulations are displacing point-in-time customer checks with continuous due diligence, expanding software licensing volumes for identity verification and risk scoring modules.
- Correspondent banking concentration:London's financial district hosts the densest cluster of clearing relationships in Europe, creating concentrated demand spikes for cross-border wire transparency tools aligned with FATF Recommendation 16.
- Cloud-native challenger banks:Digital-first institutions are bypassing on-premise legacy stacks entirely, purchasing fully managed detection-as-a-service platforms with embedded regulatory reporting.
Market Restraints
- Data localization friction:The UK's post-Brexit divergence from EU data adequacy decisions is forcing hybrid architecture investments that inflate total cost of ownership for cloud deployments.
- Specialized talent scarcity:The shortage of compliance engineers capable of tuning machine learning models for SAR explainability is extending implementation timelines and inflating professional services costs.
- Legacy system entanglement:Tier-one clearing banks remain anchored to decades-old core banking infrastructure, creating integration complexity that slows vendor substitution and feature adoption.
Strategic Opportunities
- Scotland's fintech corridor:Edinburgh and Glasgow are cultivating regulatory technology clusters outside London's cost base, offering lower operational overhead for vendor delivery centers and pilot programs.
- HMRC sector expansion:Accountancy and legal sector supervision is creating fragmented but high-margin demand for client onboarding tools tailored to non-bank obligated entities.
- Real-time payments convergence:The integration of open banking APIs with instant settlement rails is virtualizing transaction monitoring from batch to stream processing, enabling sub-second detection architectures.
Industry Challenges
- Algorithmic accountability ambiguity:Pending FCA guidance on machine learning model governance is freezing procurement decisions for AI-guided detection systems as compliance officers await audit protocol clarity.
- False positive fatigue:Tuned rule engines at major institutions generate alert volumes exceeding investigator capacity, degrading operational efficiency and regulatory confidence in automated outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Anti Money Laundering Solutions Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Transaction Monitoring, Customer Due Diligence, Risk Assessment, Case Management Client Type: Financial Institutions, Law Firms, Insurance Providers, Accountancy Firms Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS Compliance Standard: FCA Regulations, FATF Recommendations, AMLD-5, GDPR |
| Companies Covered | NICE Actimize, BAE Systems, Fiserv, ACI Worldwide, LexisNexis Risk Solutions, Quantexa, Experian Information Solutions, Trulioo, Oracle Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Anti Money Laundering Solutions Market Evolving Landscape
Graph analytics architectures are displacing relational database approaches to entity resolution, compressing the time required to map beneficial ownership structures across layered corporate vehicles.
Network analytics platforms are virtualizing the detection of layering schemes by mapping transactional relationships across previously siloed data sources. Tier-two British banks and building societies are adopting these tools fastest, seeking to close the capability gap with larger competitors. The technology is virtualizing vendor competitive positioning, rewarding providers with pre-built industry graph schemas over generic machine learning offerings.
The Financial Conduct Authority's thematic review on financial crime systems and controls is mandating explainable audit trails for all automated detection decisions. This regulatory pressure is forcing vendors to retrofit black-box machine learning models with interpretable surrogate models or rule-based overlays. Retail banking compliance teams are responding by prioritizing vendors with native model documentation capabilities over pure predictive accuracy.
Consolidated procurement through group-level risk orchestration platforms is displacing point-solution purchasing for transaction monitoring, KYC, and sanctions screening. British banking groups with multiple licensed entities are unifying vendor relationships to reduce contract fragmentation and improve data sharing across subsidiaries. This pattern is most visible among the UK's mid-tier challenger banks seeking operational leverage against larger incumbents.
UK Anti Money Laundering Solutions Market Segmentation
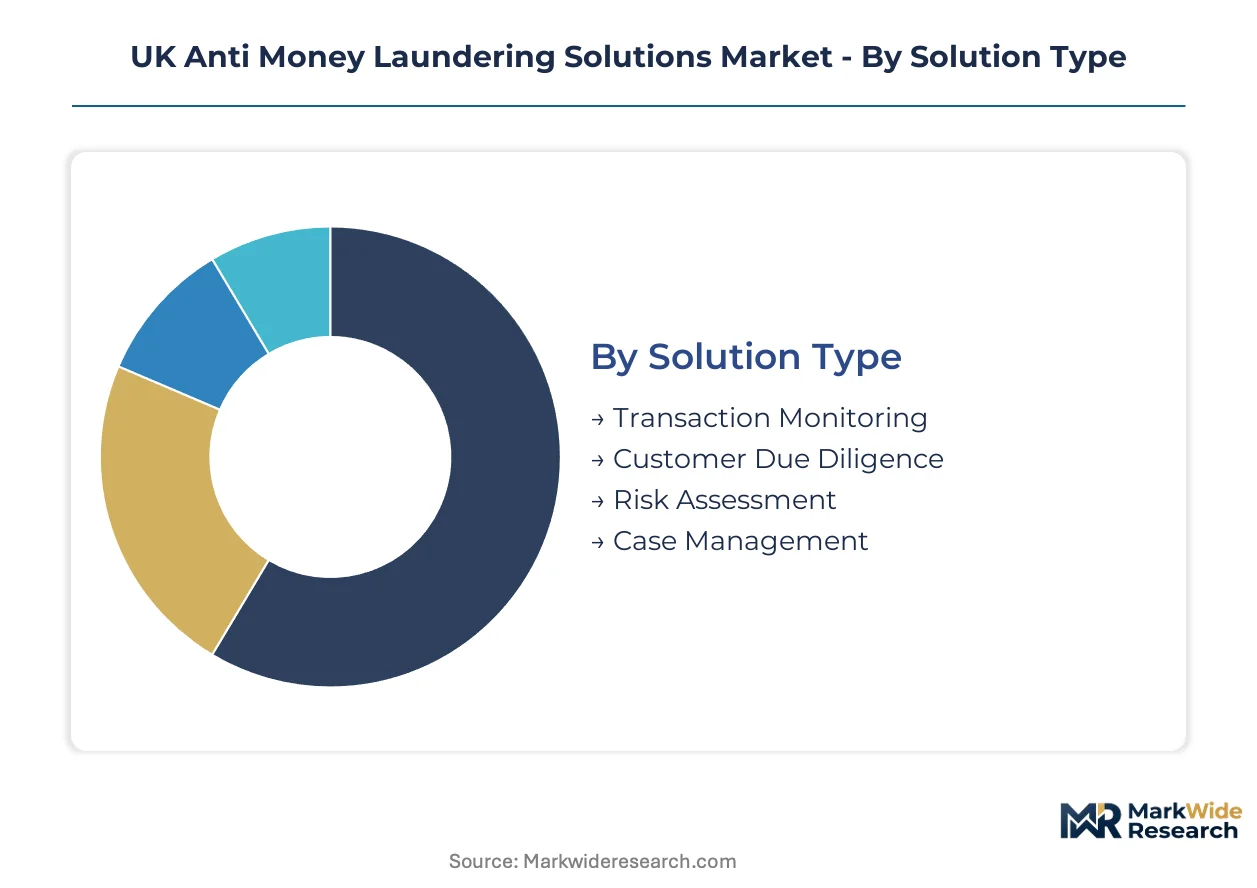
Segmentation in the UK Anti Money Laundering Solutions Market reveals how regulatory pressure, infrastructure maturity, and client sophistication fragment procurement patterns. Buyers select architectures based on FCA audit expectations, legacy system constraints, and the velocity of transactional data they must process.
Solution Type:
Deployment complexity spans from real-time streaming detection to episodic regulatory reporting, with each solution type commanding distinct integration timelines and skill requirements.
- Transaction Monitoring:Rules engines and machine learning classifiers process wire transfers, ACH payments, and cash transactions to flag structuring, layering, and rapid movement anomalies. British retail banks concentrate procurement here to satisfy FCA enforcement expectations around suspicious activity detection coverage.
- Customer Due Diligence:Perpetual KYC platforms automate identity verification, adverse media screening, and beneficial ownership mapping through API-orchestrated data fusion. Digital challenger banks in London's financial district drive fastest adoption as they bypass legacy onboarding stacks entirely.
- Risk Assessment:Quantitative scoring models aggregate customer behavioral signals, geographic exposure, and product risk to tier review frequencies.
- Case Management:Workflow platforms structure investigator queues, evidence documentation, and SAR filing preparation for regulatory submission.
Established volume favors Transaction Monitoring; emerging adoption favors Customer Due Diligence.
Client Type:
Regulatory obligation intensity varies sharply across supervised sectors, with banking facing continuous monitoring mandates while professional services navigate episodic client onboarding requirements.
- Financial Institutions:Clearing banks, building societies, and payment service providers operate under direct FCA prudential supervision with the most intensive transaction monitoring obligations. Tier-one institutions anchor procurement volumes through multi-year SaaS renewals and hybrid architecture investments.
- Law Firms:Solicitors and barristers chambers fall under HMRC supervision for property and trust work, creating fragmented demand for client onboarding tools with lower transaction velocity requirements. Edinburgh's legal sector generates concentrated regional procurement outside London.
- Insurance Providers:Life and property-casualty underwriters apply AML screening to premium financing, claims settlement, and policyholder identity verification.
- Accountancy Firms:Audit and advisory practices face HMRC compliance checks for client money handling, driving modular KYC purchases rather than enterprise detection platforms.
Financial Institutions dominate current spending; Accountancy Firms represent the steepest expansion trajectory as HMRC widens supervision scope.
Deployment Model:
Infrastructure choices reflect latency sensitivity, data residency requirements, and the pace of legacy system displacement across buyer maturity tiers.
- Cloud-Based:Fully managed detection-as-a-service platforms eliminate capital expenditure and accelerate deployment for digital-native institutions. Challenger banks and fintechs concentrate adoption here, prioritizing elastic compute for periodic regulatory stress testing.
- On-Premises:Dedicated hardware installations within client data centers satisfy the most stringent data localization requirements and sub-millisecond latency tolerances. Tier-one clearing banks maintain these deployments for core transaction processing despite higher total cost of ownership.
- Hybrid:Split architectures route sensitive data through on-premise infrastructure while pushing analytics workloads to cloud environments. This configuration dominates established British banking groups navigating post-Brexit data adequacy uncertainty.
- SaaS:Subscription-licensed software delivered through vendor-managed cloud instances with embedded regulatory reporting and model governance tooling.
Hybrid architectures capture incumbent bank spending; Cloud-Based deployments gain share fastest among new market entrants.
Compliance Standard:
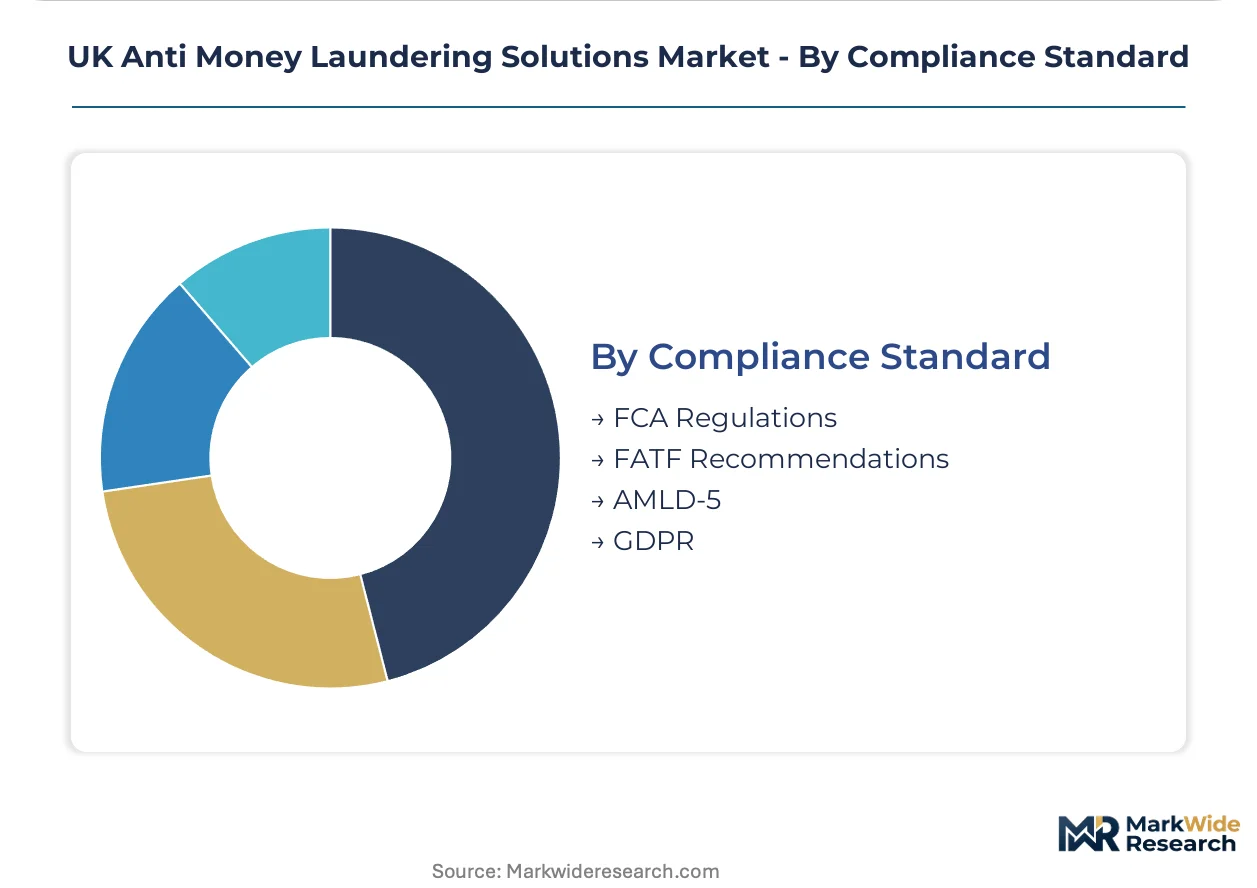
Regulatory alignment requirements shape feature roadmaps, with UK-specific mandates taking precedence over retained EU frameworks and international standards.
- FCA Regulations:The Financial Conduct Authority's Money Laundering Regulations and thematic review protocols mandate explainable audit trails, model governance documentation, and senior management accountability frameworks. Vendors prioritize FCA-aligned feature development for UK market access.
- FATF Recommendations:The Financial Action Task Force's wire transfer transparency standards sustain cross-border data-sharing infrastructure investments. Correspondent banking relationships in London require Recommendation 16 compliance for counterparty due diligence.
- AMLD-5:The EU's fifth Anti-Money Laundering Directive legacy framework continues influencing beneficial ownership registry integration and cryptocurrency exchange supervision standards retained in UK guidance.
- GDPR:Data protection requirements constrain biometric identity verification storage, adverse media screening retention periods, and cross-border investigative data sharing.
FCA Regulations dominate vendor prioritization; GDPR constraints create the most implementation friction across deployment architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK maintains a structural surplus in financial services exports, importing AML technology components while exporting compliance advisory services to Commonwealth banking networks. London's correspondent banking relationships generate concentrated demand for cross-border wire transparency tools. Scotland and Northern England are cultivating delivery centers that capture operational spillover from the capital's procurement cycles.
London and the Southeast
The capital's clearing banks anchor procurement volumes for transaction monitoring upgrades driven by FCA enforcement intensity. The Money Laundering Regulations mandate explainable audit trails for automated detection decisions. The Square Mile and Canary Wharf host the densest vendor-client relationship networks in European financial crime technology.
Scotland
Edinburgh's fintech corridor is attracting AML SaaS delivery centers seeking lower operational overhead than London. HMRC supervision of Scottish legal and accountancy practices creates fragmented but high-margin demand for client onboarding tools. Glasgow's universities supply compliance engineering talent that extends implementation timelines for network analytics deployments.
Midlands
Birmingham's building societies and regional banks are accelerating SaaS migrations to close capability gaps with tier-one clearing institutions. The FCA's thematic reviews on financial crime systems apply uniform pressure across institution size tiers. Nottingham's insurance sector generates specialized demand for premium financing and claims settlement screening.
North England
Manchester's professional services cluster faces expanding HMRC supervision for property and trust work. The EU's AMLD-5 legacy framework on beneficial ownership registries influences retained UK guidance for corporate vehicle transparency. Leeds's accountancy firms are purchasing modular KYC tools rather than enterprise detection platforms.
Wales and Northern Ireland
Cardiff's emerging fintech presence is bypassing on-premise legacy stacks entirely for cloud-native detection-as-a-service platforms. Northern Ireland's data center infrastructure supports hybrid architectures navigating post-Brexit data adequacy uncertainty. Belfast's regulatory technology startups are piloting real-time payment monitoring through open banking API integration.
UK Anti Money Laundering Solutions Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying identity verification modules and graph analytics engines. The vendor base organizes around three strategic archetypes: defence-adjacent intelligence platforms, credit-data adjacent risk orchestrators, and network analytics pure-plays. Consolidation pressure favors providers with pre-built industry graph schemas over generic machine learning offerings. M&A activity targets perpetual KYC capabilities; strategic partnerships focus on real-time payment rail integration.
Within the network analytics tier, Quantexa anchors entity-resolution deployments through pre-built financial services graph schemas. BAE Systems occupies a position among intelligence-grade platform providers leveraging defence-adjacent credibility for data fusion architectures. Experian Information Solutions exemplifies credit-data adjacent competition, embedding identity verification within broader risk orchestration workflows.
| Leading Market Players |
|---|
| NICE Actimize |
| BAE Systems |
| Fiserv |
| ACI Worldwide |
| LexisNexis Risk Solutions |
| Quantexa |
| Experian Information Solutions |
| Trulioo |
| Oracle Corporation |
| Others |
Value Network & Pricing Analysis
Specialized compliance engineering talent concentrated in London's financial district and Edinburgh's fintech corridor anchors margin pools in professional services and managed detection layers rather than software licensing alone. Tier-one clearing banks absorb premium pricing for hybrid architectures that satisfy FCA audit expectations, while mid-tier institutions face cost compression from SaaS standardization.
Pricing Analysis
Tier-one clearing banks anchor pricing stratification across premium, standard, and economy tiers in the UK AML solutions market. Premium tiers bundle perpetual KYC modules with embedded regulatory reporting and model governance documentation demanded by FCA thematic reviews. Price differentiation rests on deployment complexity and audit-grade explainability rather than raw detection accuracy. Cost compression in the mid-tier SaaS segment is intensifying because challenger banks are bypassing customization for standardized detection-as-a-service platforms. Digital-native fintechs exhibit the highest price sensitivity, while tier-one institutions prioritize compliance assurance over licensing expenditure.
Supply Chain Analysis
Cloud infrastructure providers in Ireland, the Netherlands, and the UK hold capacity for AML platform delivery, with hyperscale data centers in Frankfurt and Amsterdam serving continental backup requirements. Software vendors draw from specialized talent pools in machine learning engineering, regulatory compliance consulting, and adverse media data aggregation. Single-source vulnerability in graph analytics engine licensing creates concentration risk for tier-two British banks dependent on pre-built industry schemas. Distribution runs through direct enterprise sales teams for tier-one accounts and channel partners serving mid-market building societies and accountancy firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK AML solutions market represents a service-attach opportunity where perpetual KYC maintenance contracts and regulatory reporting automation expand faster than initial platform licensing. Managed detection services and compliance engineering retainers now constitute the primary margin expansion layer.
For Market Incumbents: Insulate core relationships with tier-one clearing banks by embedding model governance documentation capabilities that preempt FCA audit scrutiny. Deepen vertical integration into adverse media data aggregation to reduce third-party licensing exposure. Acquire specialized perpetual KYC vendors before challenger banks consolidate alternative supplier relationships. For New Entrants and Emerging Players: Scottish legal and accountancy practices under expanding HMRC supervision represent the most penetrable entry point outside London's saturated procurement cycles. Mid-sized building societies in Birmingham and Manchester seeking SaaS migration without tier-one implementation timelines offer second-mover advantage. A channel partnership strategy with regional compliance consultancies accelerates credibility transfer faster than direct sales investment. For Investors and Strategic Acquirers: Capital is best deployed toward network analytics pure-plays with pre-built financial services graph schemas that resist commoditization. The long-term viability window favors vendors combining entity-resolution technology with regulatory reporting automation rather than point-solution machine learning classifiers. Watch FCA guidance publication on algorithmic accountability standards as the inflection signal for AI-guided detection system procurement resumption.| Strategic Initiative | Industry Significance |
|---|---|
| Perpetual KYC Platform Integration | FCA-mandated continuous due diligence displaces point-in-time checks, expanding recurring revenue pools. |
| Graph Analytics Engine Acquisition | Pre-built financial services schemas compress implementation timelines for tier-two British banks. |
| Scotland Delivery Center Establishment | Edinburgh and Glasgow offer compliance engineering talent at lower operational overhead than London. |
| Real-Time Payment Rail Partnership | Open banking API integration enables sub-second detection architectures for instant settlement networks. |
| HMRC Sector Expansion Program | Accountancy and legal supervision creates fragmented but high-margin demand for client onboarding tools. |
Research Methodology
A standing panel of FCA supervisory staff, bank compliance officers, AML vendor product managers, and HMRC sector supervisors provided ongoing calibration for this study. Primary interviews with these stakeholders combined with secondary validation against FCA enforcement notices, Money Laundering Regulations guidance, FATF mutual evaluation reports, and British Banking Association policy submissions. Bottom-up vendor revenue triangulation against top-down regulatory obligation sizing anchored market estimates.
Scenario bracketing around FCA enforcement intensity and cloud migration pace structured the analytical framework across the projection horizon. Segmentation dimensions modeled include solution type, client sector, deployment architecture, and regulatory compliance tier. CAGRs derived from vendor booking trajectories and procurement cycle compression rates observed in tier-one bank renewals. Industry-specific inputs incorporated correspondent banking volume trends and perpetual KYC mandate implementation timelines.
Practitioners should monitor FCA algorithmic accountability guidance publication, post-Brexit data adequacy determinations, and real-time payment rail adoption curves for early signals of forecast revision. Quarterly review of vendor booking backlogs, regulatory enforcement penalty trends, and compliance engineering wage inflation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Global Financial Crime and Fraud Management Solutions Market
Risk Management and Compliance
Europe Risk Management Market
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
Healthcare Fraud Detection Market
Risk Management and Compliance
Global Liquidity Asset Liability Management Solutions Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market
Risk Management and Compliance
Enterprise Risk Management Market
Risk Management and Compliance
Operations Advisory Service Market
Risk Management and Compliance
Global Management Decision Market
Risk Management and Compliance
Vendor Risk Management Market
Risk Management and Compliance
Third Party Risk Management Market
Risk Management and Compliance
Global Risk and Compliance Consulting Services Market
Risk Management and Compliance
Global Backstop Netting Systems Market
Risk Management and Compliance
Treasury and Risk Management Application Market
Risk Management and Compliance
Oil and Gas Risk Management Market
Risk Management and Compliance
Financial Risk Management Software Market