
 Treasury and Risk Management Application Market | 2026-2036
Treasury and Risk Management Application Market Size, Share, and Industry Trends Forecast 2026-2036
Treasury and Risk Management Application Market Analytics
Multi-source procurement of treasury infrastructure is consolidating around fewer strategic vendors as enterprises seek unified risk visibility. SAP SE leverages its ERP footprint to embed treasury modules within broader finance transformation programs. Oracle Corporation sustains competitive pressure through database-tier integration with cash forecasting engines. Kyriba Corporation specializes in cloud-native connectivity to banking networks, positioning it for mid-market displacement of legacy installations.
Treasury and risk management applications encompass software systems that automate cash positioning, hedge accounting, counterparty exposure monitoring, and regulatory reporting through real-time data aggregation from ERP, banking, and market data feeds. Their primary commercial purpose centers on protecting enterprise liquidity while satisfying audit and compliance obligations across distributed operations. Cloud-based solutions represent the fastest-expanding technology dimension as banks and corporates retire mainframe-era installations. Financial institutions anchor end-user demand due to Basel III liquidity coverage ratio calculations and stress-testing workflows that require sub-hour data refresh cycles. Hybrid deployment models capture growing interest from European corporates navigating data residency requirements under GDPR.
The SEC, EU's Digital Operational Resilience Act (DORA), and Japan's FSA impose granular requirements on financial resilience reporting that directly expand module demand within treasury suites. GDPR and national banking regulators further constrain where transaction data resides, pushing vendors to certify regional cloud instances. Stakeholders must monitor how AI-powered predictive cash flow modules reshape R&D allocation across incumbent and emerging platform providers.
Market Dynamics
Cloud migration mandates from the SEC and EU's DORA framework are compressing vendor consolidation timelines as enterprises abandon fragmented legacy installations for unified platforms with real-time risk visibility.
Growth Catalysts
- DORA Resilience Mandates:The EU's Digital Operational Resilience Act requires financial institutions to maintain sub-hour data refresh cycles for stress-testing workflows, directly expanding module demand within integrated treasury suites.
- Basel III Liquidity Coverage:Banking verticals must automate liquidity ratio calculations across distributed operations, driving replacement of spreadsheet-dependent processes with API-connected forecasting engines.
- AI-Powered Predictive Modules:Machine learning algorithms analyzing ERP and banking feed patterns are compressing cash positioning cycles from days to minutes for corporate treasury departments.
Market Restraints
- Data Residency Constraints:GDPR and Japan's FSA impose granular requirements on where transaction data resides, forcing vendors to certify multiple regional cloud instances and fragmenting development resources.
- Mainframe Migration Costs:Capital intensity of retiring COBOL-era installations with decades of custom hedge accounting logic creates sticky incumbent positions in Fortune 500 treasuries.
- Counterparty Exposure Volatility:Real-time monitoring requirements for banking network connectivity expose platforms to API downtime risks during market stress events.
Strategic Opportunities
- Mid-Market Cloud Displacement:Germany's Mittelstand manufacturing sector presents underpenetrated demand for SaaS treasury modules replacing Excel-based cash management.
- Hybrid Deployment Architectures:European corporates navigating GDPR constraints are adopting edge-computing configurations that process sensitive data locally while leveraging cloud analytics.
- Embedded Finance Convergence:Integration of treasury functions directly into ERP workflows is creating white space for vendors with native SAP or Oracle database-tier connectivity.
Industry Challenges
- Quantitative Risk Talent Scarcity:Shortage of professionals combining derivatives pricing expertise with Python-based API engineering is constraining implementation velocity for predictive cash flow modules.
- Legacy System Entanglement:Decades of custom SWIFT message formats and proprietary bank connectivity protocols create integration friction during platform migrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Treasury and Risk Management Application Market |
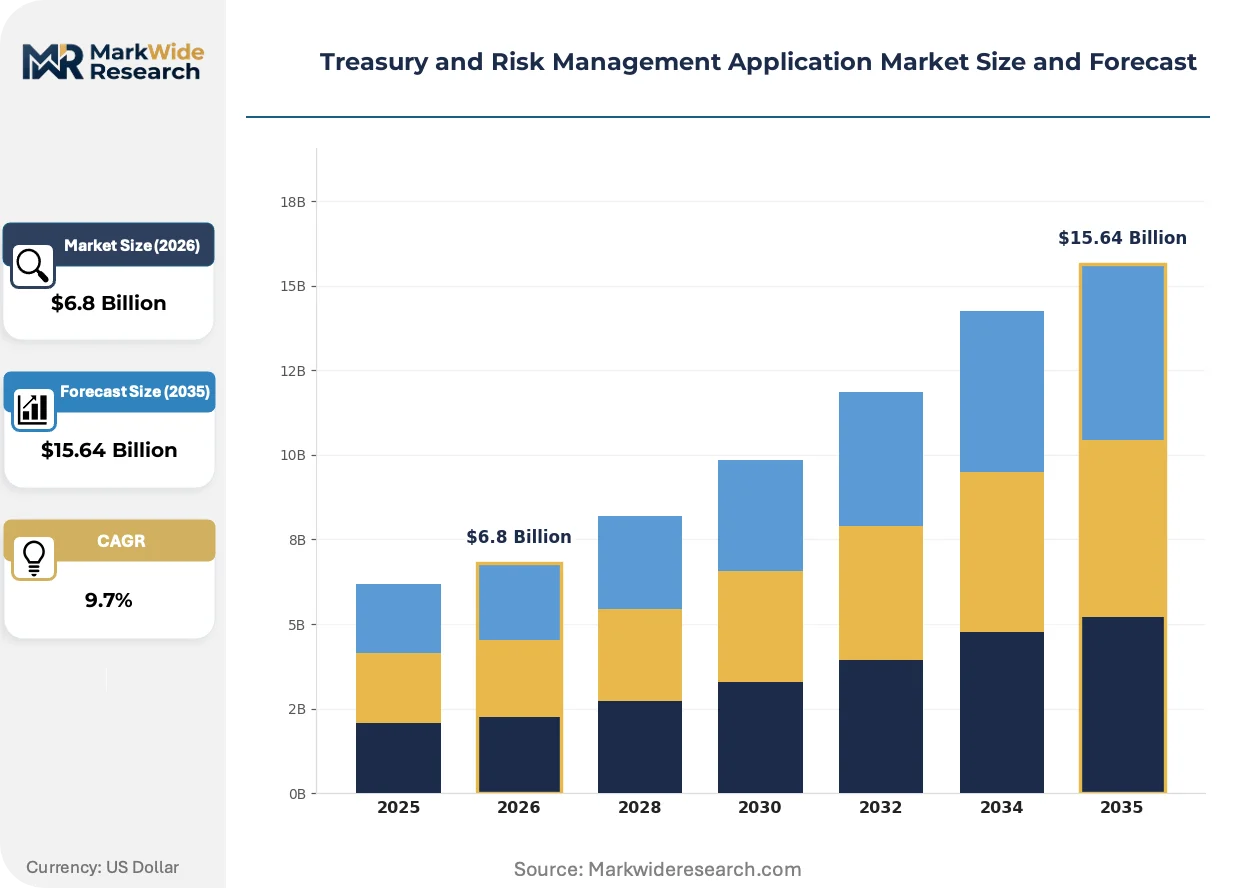
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.64 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Liquidity Management, Risk Assessment, Investment Portfolio Management, Compliance Tracking Technology: Cloud-Based Solutions, On-Premises Software, Mobile Platforms, Hybrid Solutions End User: Corporates, Financial Institutions, Government Agencies, Non-Profit Organizations Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises |
| Companies Covered | SAP SE, Oracle Corporation, FIS, Kyriba Corporation, ION Group, GTreasury, Finastra, Sage Group PLC, Fiserv Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Treasury and Risk Management Application Market Evolving Landscape
Real-time data architectures are compressing decision cycles from batch overnight processing to continuous liquidity monitoring, reshaping how treasury functions interface with trading floors and regulatory reporting systems.
API-first connectivity fabrics are electrifying how treasury platforms ingest multi-bank cash positions. Corporate treasuries at multinational manufacturers are replacing manual file-based reconciliation with direct ERP-to-bank data streams. This compression of latency from hours to seconds is enabling intraday hedging decisions that were previously operationally impossible.
The EU's Digital Operational Resilience Act mandates granular reporting on third-party risk exposure for financial institutions. This regulatory pressure is forcing banks to demand deeper audit trails from treasury software vendors. European insurance groups are responding by consolidating vendor relationships to reduce compliance documentation burden across fragmented supplier bases.
Subscription pricing models are displacing perpetual license structures in procurement patterns for treasury infrastructure. Mid-market enterprises in the United States are favoring annual SaaS contracts with bundled implementation support over multi-year capital expenditure commitments. This shift is most visible among regional banking clients seeking faster deployment without internal IT resource allocation.
Treasury and Risk Management Application Market Segmentation
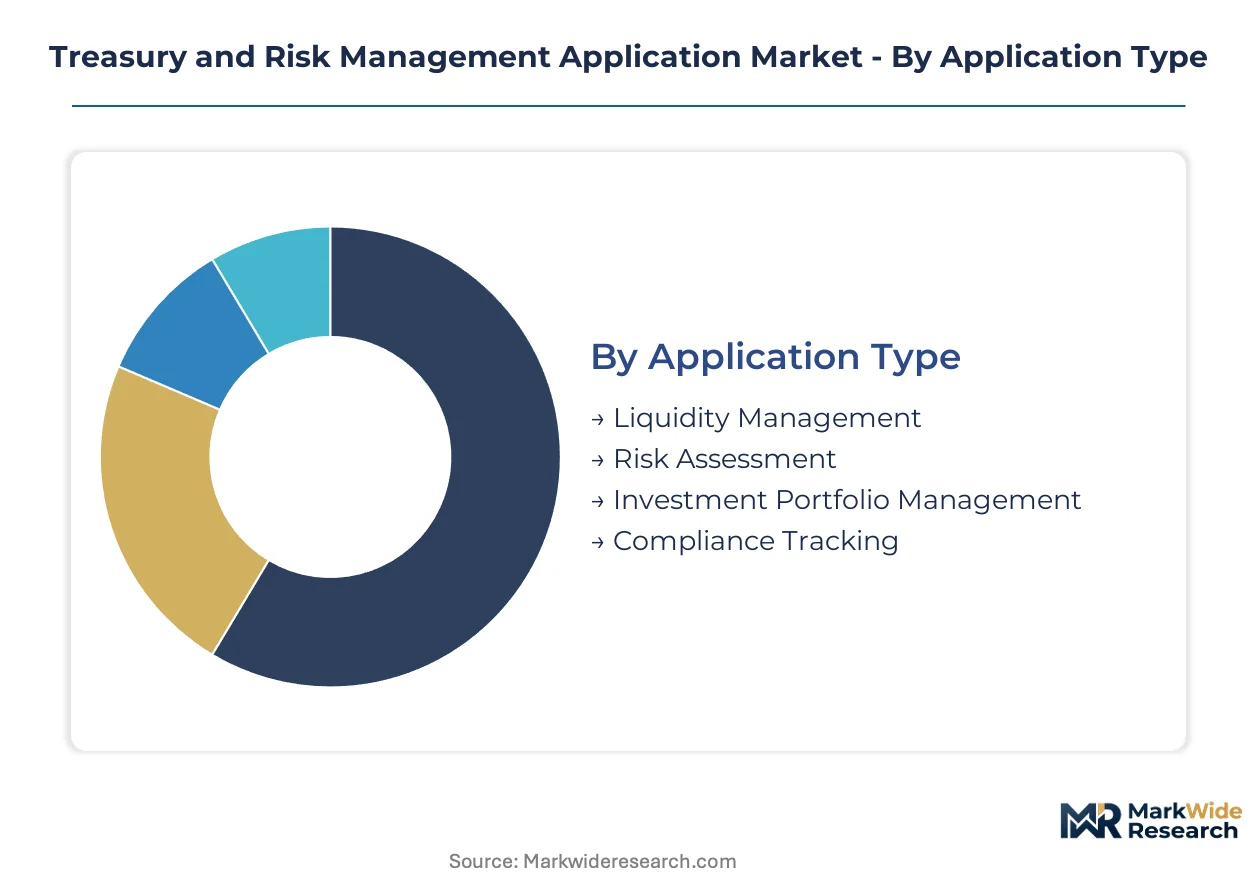
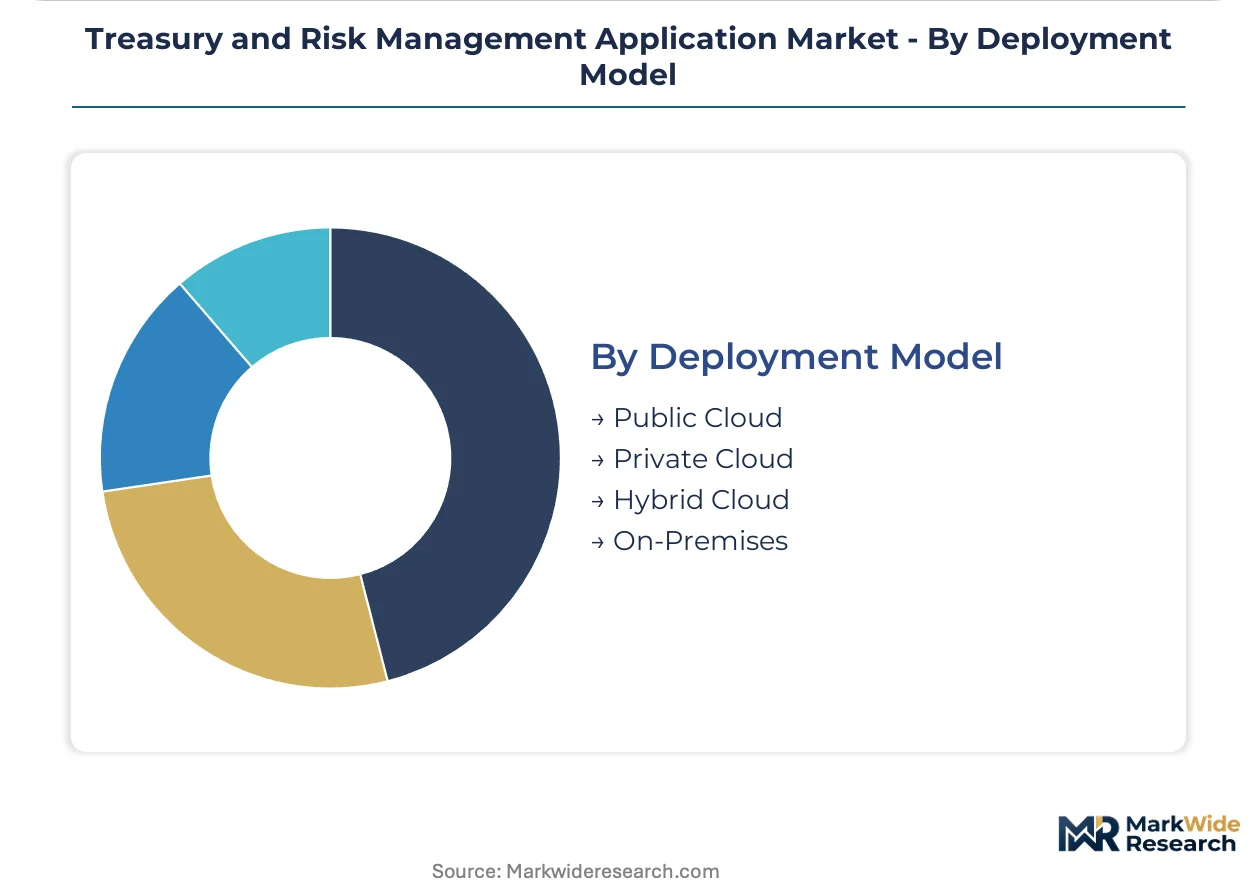
Treasury platform procurement varies sharply across application types and deployment models. Regulatory mandates from the SEC, EU's DORA framework, and Japan's FSA create divergent certification burdens that reshape vendor selection criteria within each segment.
Application Type:
DORA resilience mandates and Basel III liquidity coverage rules impose distinct certification requirements on each application module. Liquidity management suites face the most stringent audit trail demands from EU banking regulators.
- Liquidity Management:Modules automate cash positioning, intraday funding optimization, and liquidity buffer calculations across multi-bank relationships. Demand concentrates among US and German banking verticals where Basel III liquidity coverage ratio workflows require sub-hour data refresh cycles and real-time ERP connectivity.
- Risk Assessment:Platforms quantify counterparty exposure, interest rate sensitivity, and foreign exchange volatility through Monte Carlo simulations and stress-testing engines. Japanese financial institutions anchor procurement volume as the FSA mandates granular operational resilience reporting with predictive scenario modeling.
- Investment Portfolio Management:Systems track security positions, perform attribution analysis, and automate hedge accounting across treasury investment books.
- Compliance Tracking:Modules aggregate audit trails for SEC, GDPR, and DORA reporting obligations with automated regulatory filing generation.
Leading the category by volume: Liquidity Management. Growing fastest: Risk Assessment.
Technology:
Cost tier structures separate enterprise-grade cloud-native architectures from legacy on-premises installations with heavy customization overhead. Mid-market buyers in Germany's Mittelstand manufacturing sector are compressing procurement timelines around SaaS delivery models.
- Cloud-Based Solutions:SaaS platforms deliver API-connected cash forecasting and real-time bank aggregation without internal infrastructure investment. US regional banks and insurance groups favor annual subscription contracts with bundled implementation support over capital-intensive perpetual licenses.
- On-Premises Software:Legacy installations running COBOL-era hedge accounting logic persist in Fortune 500 treasuries with decades of custom SWIFT message formats. Migration costs and regulatory recertification requirements create sticky incumbent positions despite cloud migration mandates.
- Mobile Platforms:iOS and Android applications enable executive cash visibility and approval workflows for distributed treasury teams.
- Hybrid Solutions:Edge-computing configurations process sensitive transaction data locally while leveraging cloud analytics for non-sensitive operations.
Dominant by revenue: Cloud-Based Solutions. Steepest expansion trajectory: Hybrid Solutions.
End User:
Customer type determines functional depth requirements and integration complexity with existing ERP footprints. Financial institutions demand the most sophisticated real-time data architectures.
- Corporates:Multinational manufacturers seek unified platforms replacing fragmented Excel-based cash management with API-connected bank feeds and automated hedge accounting. German automotive and chemical conglomerates represent concentrated demand as DORA compliance deadlines approach.
- Financial Institutions:Banks and insurers require sub-hour stress-testing workflows, Basel III liquidity calculations, and granular third-party risk exposure reporting mandated by EU and Japanese regulators. These users command premium pricing for platforms with certified resilience architectures.
- Government Agencies:Sovereign wealth funds and public pension systems prioritize audit trail completeness and multi-currency exposure monitoring.
- Non-Profit Organizations:Endowments and foundations seek simplified cash forecasting with donor-restricted fund tracking capabilities.
Highest spend per seat: Financial Institutions. Fastest onboarding velocity: Corporates.
Deployment Model:
Supply concentration among hyperscale cloud providers shapes regional availability and data residency compliance. GDPR constraints fragment vendor development resources across certified regional instances.
- Public Cloud:Multi-tenant SaaS architectures from AWS, Azure, and Google Cloud enable rapid deployment with elastic compute for stress-testing workloads. US mid-market enterprises favor this model for fastest time-to-value without internal IT resource allocation.
- Private Cloud:Single-tenant dedicated instances satisfy data residency requirements for European insurance groups navigating GDPR transaction location constraints and Japanese FSA granular reporting mandates.
- Hybrid Cloud:Edge-processing of sensitive liquidity data combined with cloud-based analytics is gaining share among European corporates with complex cross-border treasury operations.
- On-Premises:Air-gapped installations persist in defense contractors and critical infrastructure operators with national security classification requirements.
Widest adoption: Public Cloud. Gaining share fastest: Hybrid Cloud.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure concentration in Northern Virginia and Frankfurt anchors procurement patterns for treasury platforms. Regulatory divergence between SEC mandates, EU DORA frameworks, and Japan FSA requirements fragments vendor certification priorities across these three demand centers.
United States
Regional banks and insurance groups in New York and Chicago drive SaaS adoption for Basel III liquidity workflows. SEC disclosure rules mandate granular audit trails for stress-testing data. Charlotte's banking cluster accelerates replacement of spreadsheet-dependent cash forecasting with API-connected platforms.
Germany
Mittelstand manufacturers in Bavaria and Baden-Württemberg present underpenetrated demand for cloud treasury modules. EU DORA resilience mandates require sub-hour data refresh cycles for operational continuity reporting. Frankfurt's financial center concentrates procurement of hybrid deployment architectures navigating GDPR constraints.
Japan
Tokyo-based financial institutions anchor demand for predictive risk assessment modules with Monte Carlo simulation capabilities. FSA operational resilience reporting mandates granular third-party exposure documentation. Osaka's insurance sector consolidates vendor relationships to reduce compliance documentation burden.
United Kingdom
London's asset management and insurance verticals prioritize investment portfolio management systems with automated hedge accounting. PRA and FCA regulations align with EU DORA requirements for financial resilience reporting. Edinburgh's banking cluster experiments with edge-computing configurations for sensitive transaction processing.
India
Mumbai and Bangalore corporates accelerate treasury digitization as RBI guidelines tighten liquidity reporting standards. SEBI mandates for corporate bond market transparency expand compliance tracking module demand. Hyderabad's IT services sector enables implementation partnerships for mid-market cloud deployments.
Treasury and Risk Management Application Market Competitive Landscape
Global majors compete with regional champions across deployment architecture and integration depth. The vendor base stratifies into three tiers: ERP-embedded platforms leveraging database-tier connectivity, cloud-native specialists with banking network APIs, and legacy on-premises installations with sticky incumbent positions. Dominant competitive moves include M&A to acquire API connectivity assets and strategic partnerships with hyperscale cloud providers for certified regional instances.
Within the ERP-embedded tier, SAP SE and Oracle Corporation exemplify archetypes that leverage existing finance transformation footprints to displace standalone treasury installations. Kyriba Corporation occupies a position among cloud-native specialists with concentrated banking network connectivity expertise. These three anchors represent divergent strategic postures: database-tier integration versus API-first architectures versus hybrid deployment flexibility.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| FIS |
| Kyriba Corporation |
| ION Group |
| GTreasury |
| Finastra |
| Sage Group PLC |
| Fiserv Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialists including ION Group and GTreasury enforce pricing discipline through bundled implementation services and multi-year SaaS contracts, while their fragmented acquisition histories create supply chain complexity across cloud infrastructure partners and banking network API providers. This ownership pattern concentrates pricing power with vendors who can amortize compliance certification costs across scaled customer bases.
Pricing Analysis
Warranty and service bundling separates premium-tier offerings with dedicated customer success teams and 24/7 incident response from standard subscriptions with business-hours support only. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity, with cloud-native SaaS commanding annual subscriptions, hybrid configurations requiring professional services fees, and on-premises legacy licenses retaining perpetual models with maintenance uplifts. Cost compression in mid-market segments intensifies because Kyriba and Sage Group PLC compete aggressively for Germany's Mittelstand manufacturers. Regional banks exhibit highest price sensitivity due to constrained IT budgets, while Japanese financial institutions show lowest sensitivity given FSA-mandated resilience requirements.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure mandate that treasury platform vendors qualify both AWS and Azure instances for EU data residency compliance, fragmenting development resources across certification pathways. Software development concentrates in the United States, India, and Ireland, with implementation partnerships anchored in Hyderabad and Bangalore. Core dependencies include SWIFT network connectivity licenses, ERP integration middleware, and Monte Carlo simulation engines. Single-source vulnerability runs through hyperscale cloud concentration in Northern Virginia and Frankfurt. Distribution runs through direct enterprise sales teams for Fortune 500 accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from DORA compliance deadlines and SEC cloud migration mandates will force sub-scale vendors without certified multi-region architectures to exit or sell. Regulatory recertification costs favor scaled platforms with existing compliance infrastructure.
For Market Incumbents: Extend database-tier integration capabilities to deepen ERP-embedded positioning against cloud-native challengers, particularly for SAP SE and Oracle Corporation customers undergoing finance transformation. Acquire API connectivity assets to neutralize Kyriba Corporation's banking network advantage. Counterparty exposure monitoring modules represent the priority R&D area as real-time data architectures reshape competitive differentiation.
For New Entrants and Emerging Players: Launch via vertical-specific SaaS bundles targeting Germany's Mittelstand manufacturing sector, where Excel-based cash management persists and procurement timelines compress around DORA deadlines. White-space targets include hybrid deployment architectures for European corporates navigating GDPR constraints and AI-powered predictive cash flow modules for mid-market displacement. Partner with Hyderabad-based implementation specialists to accelerate deployment velocity without internal consulting buildout.
For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native specialists with banking network APIs in the United States and Germany, where regulatory pressure creates forced sellers among legacy on-premises vendors. Long-term viability hinges on multi-region cloud certification and ERP integration depth. Watch for FSA enforcement actions on operational resilience reporting as the inflection signal for Japanese market consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Region Cloud Certification | EU DORA and Japan FSA mandates require certified instances across Frankfurt, Tokyo, and Northern Virginia. |
| API-First Banking Connectivity | Direct ERP-to-bank data streams displace manual file-based reconciliation for multinational manufacturers. |
| Predictive Cash Flow Module Development | Machine learning algorithms compress positioning cycles from days to minutes for corporate treasury departments. |
| Hybrid Deployment Architecture Launch | Edge-computing configurations process sensitive liquidity data locally while leveraging cloud analytics. |
| ERP-Embedded Treasury Integration | SAP and Oracle database-tier connectivity creates white space within broader finance transformation programs. |
Research Methodology
SEC filings, EU regulatory databases, and SWIFT network documentation formed the secondary backbone, supplemented by customs records tracking software services trade and hyperscaler capex disclosures. Primary interviews with corporate treasury directors, banking technology officers, ERP implementation consultants, and regulatory compliance leads validated segmentation assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled vendor-reported subscription metrics with end-user procurement patterns across the United States, Germany, and Japan.
Bottom-up modeling aggregated individual application modules—liquidity management, risk assessment, investment portfolio management, and compliance tracking—by deployment model and end-user vertical. Segmentation dimensions included technology architecture, organization size tier, integration complexity with existing ERP footprints, and regional regulatory cluster. CAGRs were derived from trend extrapolation of cloud migration timelines and compliance deadline impacts, with stress-testing against Basel III liquidity coverage implementation velocity and DORA enforcement patterns.
Regulatory delay, cloud infrastructure concentration events, and talent scarcity in quantitative risk engineering are the dominant revision risks to the outlook. Deviation in DORA enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Europe Sustainable Finance Market
Risk Management and Compliance
Sustainable Finance Market
Risk Management and Compliance
Global Compliance Management Software Market
Risk Management and Compliance
Medical Device Cyber Risk Quantification Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Global Risk and Compliance Consulting Services Market
Risk Management and Compliance
Compliance As a Service Market
Risk Management and Compliance
BFSI Crisis Management Market
Risk Management and Compliance
Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Global Regulatory Reporting and Compliance Market
Risk Management and Compliance
Surety Market
Risk Management and Compliance
Crypto Compliance Software Market
Risk Management and Compliance
NPL Management Market
Risk Management and Compliance
Global Strategy Consulting Market
Risk Management and Compliance
Enterprise Risk Management Market
Risk Management and Compliance
Global Asset Integrity Management Market