
 Asia-Pacific Sustainable Finance Market | 2026-2036
Asia-Pacific Sustainable Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sustainable Finance Market Insights
Japan's green bond issuance framework is narrowing the gap between regional and European disclosure standards. Sumitomo Mitsui Financial Group leverages its domestic institutional network to anchor yen-denominated sustainable debt placement. Mizuho Financial Group specializes in transition finance advisory for heavy industrial borrowers seeking decarbonization pathways. DBS Group Holdings dominates Singapore-dollar sustainable bond underwriting across ASEAN corporate issuers.
Asia-Pacific sustainable finance encompasses capital allocation instruments that integrate environmental, social, and governance criteria into pricing, structuring, and reporting mechanisms, with instruments typically featuring use-of-proceeds restrictions, key performance indicator-linked coupon step-ups, or third-party verification protocols designed to redirect institutional capital toward climate-aligned projects. Green bonds lead investment type volumes due to established ICMA harmonized framework acceptance, while sustainability-linked loans represent the fastest-expanding segment as borrowers prefer balance-sheet flexibility over proceeds ring-fencing. Energy transition commands the largest industry focus allocation as regional power utilities refinance coal-dependent generation portfolios.
Japan's METI green transformation standards, China's MEE environmental information disclosure rules, and Singapore's MAS green finance taxonomy collectively reshape product eligibility criteria and reporting obligations across the region. These frameworks force issuers to adopt verified metrics or risk exclusion from benchmark indices and central bank collateral eligibility pools. Stakeholders must monitor divergence between national taxonomies and emerging ASEAN regional standards to anticipate restructuring costs for cross-border instruments.
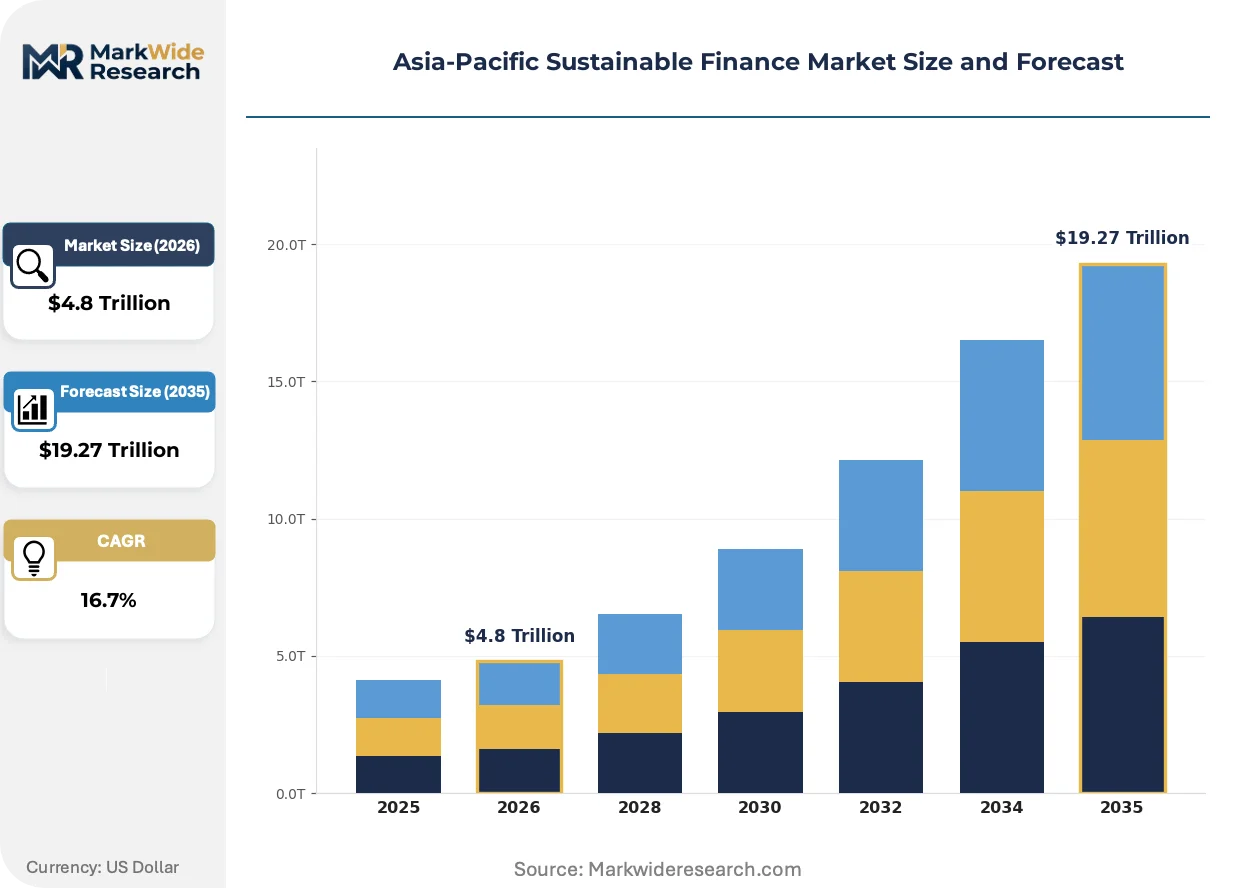
Market Dynamics
China's dual carbon goals and Japan's green transformation taxonomy are compressing disclosure timelines and forcing institutional capital into verified climate-aligned instruments across the region.
Growth Catalysts
- Singapore's MAS green finance taxonomy:The framework tightens product eligibility criteria and expands central bank collateral pools for sustainable debt instruments, drawing ASEAN corporate issuers to the financial hub.
- Energy transition refinancing:Regional power utilities are retiring coal-dependent generation portfolios and replacing them with renewable infrastructure, generating sustained demand for green bond and sustainability-linked loan structures.
- Third-party verification protocols:ICMA harmonized frameworks now govern use-of-proceeds reporting across Asia-Pacific markets, reducing investor due diligence friction and accelerating institutional capital deployment.
Market Restraints
- Input cost volatility in rare earth minerals:Battery storage and wind turbine manufacturing depend on concentrated Indonesian and Australian rare earth supply chains subject to export restriction uncertainty.
- Regulatory friction from divergent national taxonomies:China's MEE environmental information disclosure rules and Japan's METI green transformation standards create conflicting eligibility criteria for cross-border instruments.
- Technical limitation in scope 3 emissions verification:Supply chain carbon accounting lacks standardized measurement protocols, forcing issuers to exclude upstream and downstream impacts from KPI-linked coupon structures.
Strategic Opportunities
- Underpenetrated Australian sustainable finance:The country's superannuation funds hold substantial dry powder for domestic renewable infrastructure but lack specialized sustainable debt placement expertise concentrated in Singapore and Tokyo.
- Technology convergence of blockchain and carbon accounting:Distributed ledger systems are enabling real-time emissions verification for sustainability-linked loan KPI monitoring, reducing audit costs and accelerating disclosure cycles.
- Regulatory tailwind from ASEAN regional standards:Emerging harmonized taxonomies across Southeast Asian markets will reduce restructuring costs for cross-border instruments and expand benchmark index eligibility.
Industry Challenges
- Skill scarcity in transition finance advisory:Heavy industrial borrowers seeking decarbonization pathways require specialized structuring expertise that outstrips current regional bank desk capacity in Singapore and Tokyo.
- Certification timeline compression:Third-party verification protocols for green bond frameworks now require annual post-issuance reporting, straining issuer compliance resources and escalating audit fees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sustainable Finance Market |
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $19.27 Trillion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Type: Green Bonds, ESG Funds, Social Impact Investments, Sustainability-linked Loans Industry Focus: Energy Transition, Agriculture Sustainability, Waste Management, Carbon Trading Client Type: Institutional Investors, Corporations, Nonprofits, Retail Investors Service Model: Advisory Services, Asset Management, Certification, Reporting Tools |
| Companies Covered | Sumitomo Mitsui Financial Group, Bank of China, Mizuho Financial Group, United Overseas Bank, HSBC Holdings, DBS Group Holdings, OCBC Bank, Standard Chartered Bank, MUFG Bank, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sustainable Finance Market Trends and Innovations
Financial instrument architecture is pivoting from rigid use-of-proceeds restrictions toward flexible balance-sheet-linked structures that reward verified performance improvement rather than prescriptive project allocation.
Blockchain-enabled carbon accounting is migrating from pilot-stage renewable energy certificates to mainstream sustainability-linked loan KPI verification. Regional banks in Singapore and Tokyo are deploying distributed ledger infrastructure to automate emissions data collection from corporate borrowers. The technology is compressing third-party audit cycles from annual to quarterly reporting frequencies, reducing compliance costs and accelerating coupon step-up trigger assessments.
Japan's METI green transformation standards are mandating transition plan disclosure for heavy industrial borrowers accessing sustainable finance markets. The regulation requires verified decarbonization pathways with interim targets for steel, cement, and chemical sector issuers. Japanese institutional investors are now excluding borrowers lacking METI-compliant transition plans from benchmark sustainable debt indices, reshaping regional underwriting standards.
Corporate treasury procurement of sustainable finance instruments is rotating from single-transaction green bonds toward programmatic sustainability-linked loan facilities. Multinational manufacturers with ASEAN operations are consolidating banking relationships around revolving credit structures tied to science-based emissions targets. This behavioral shift is most visible in Singapore-dollar denominated facilities where DBS Group Holdings and regional competitors compete on KPI calibration flexibility rather than pricing alone.
Asia-Pacific Sustainable Finance Market Segmentation
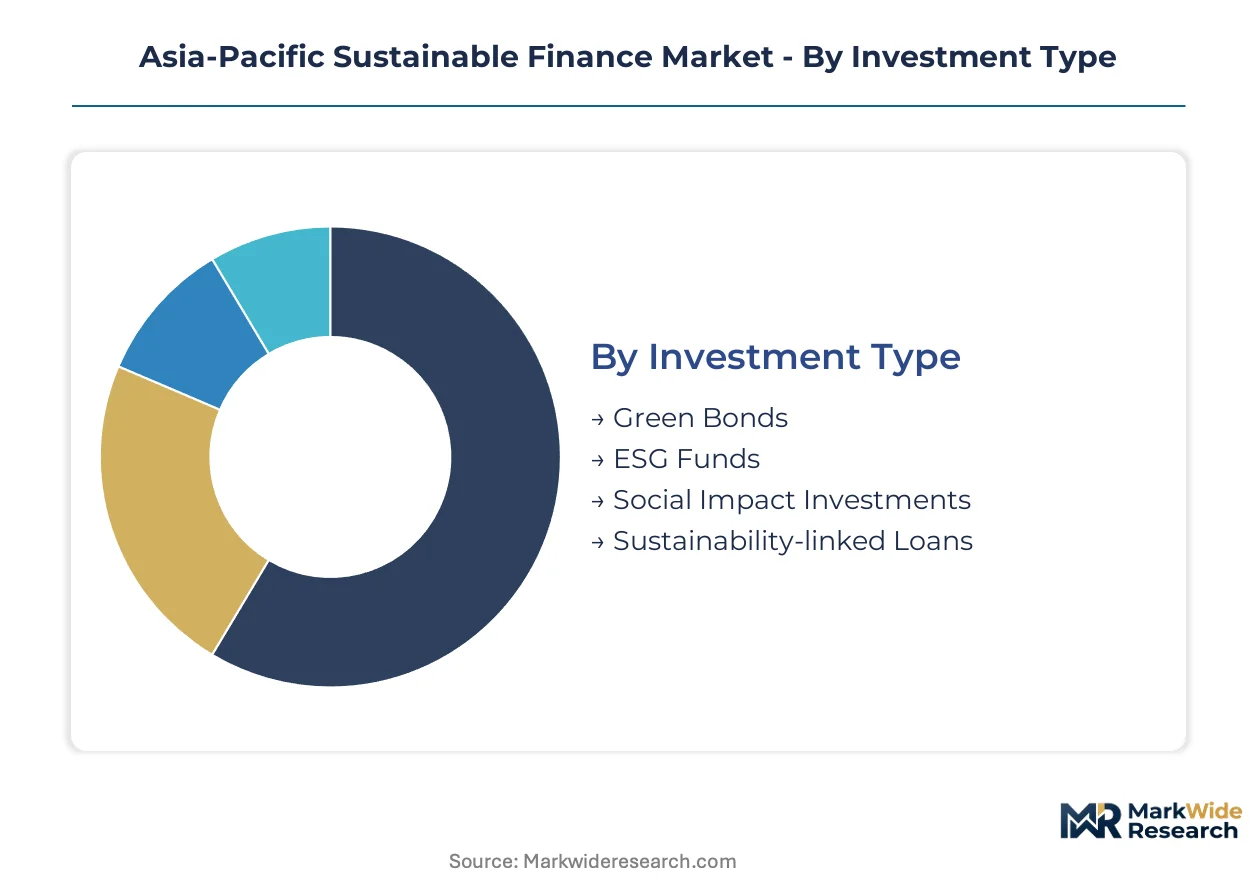
Sustainable finance instruments in the Asia-Pacific region diverge sharply in structural flexibility, regulatory treatment, and capital deployment speed. Understanding these distinctions enables treasurers to match financing vehicles to project pipelines and disclosure capabilities.
Investment Type:
The use-case spectrum spans rigid proceeds ring-fencing to performance-linked balance sheet flexibility, with each structure carrying distinct verification burdens and investor eligibility criteria.
- Green Bonds:Proceeds are legally segregated for eligible green projects with ICMA-compliant use-of-proceeds frameworks. Japanese power utilities and Singaporean REITs dominate regional issuance as they refinance coal-dependent generation portfolios into renewable infrastructure.
- Sustainability-linked Loans:Pricing ties directly to borrower KPI performance rather than project allocation, offering treasury teams balance-sheet flexibility. Corporate borrowers across ASEAN manufacturing hubs favor this structure for working capital facilities where proceeds ring-fencing proves operationally impractical.
- ESG Funds:Pooled vehicles screening portfolios against environmental, social, and governance criteria with varying materiality thresholds.
- Social Impact Investments:Targeted capital addressing measurable social outcomes including financial inclusion and affordable housing.
Established volume favors Green Bonds; emerging adoption favors Sustainability-linked Loans.
Industry Focus:
Capital allocation intensity tracks regulatory pressure and asset replacement cycles, with sectors facing imminent carbon border adjustments commanding premium structuring attention.
- Energy Transition:Dominates capital flows as regional utilities retire coal generation and refinance into solar, wind, and battery storage portfolios. China's State Grid and Japan's JERA anchor the largest green bond programs, driven by METI green transformation standards and dual carbon disclosure mandates.
- Carbon Trading:Emerging infrastructure for compliance and voluntary offset markets, with Singapore's Climate Impact Exchange and China's national ETS creating settlement demand for associated sustainable finance instruments.
- Agriculture Sustainability:Supply chain financing for regenerative practices and methane reduction in livestock operations.
- Waste Management:Circular economy project finance targeting plastic recycling and organic waste-to-energy facilities.
Regulatory tailwinds concentrate in Energy Transition; voluntary market liquidity is expanding most quickly in Carbon Trading.
Client Type:
Treasury sophistication and reporting bandwidth determine instrument access, with disclosure requirements creating tiered market participation.
- Institutional Investors:Pension funds, insurance reserves, and sovereign wealth vehicles with dedicated sustainable allocation mandates. Australia's superannuation funds deploy substantial dry powder through Singapore-based placement agents, constrained by domestic sustainable debt expertise scarcity.
- Corporations:Multinational manufacturers and regional utilities accessing bilateral and syndicated sustainable credit facilities. Heavy industrial borrowers in Japan's steel and cement sectors face METI-mandated transition plan disclosure requirements for benchmark index eligibility.
- Nonprofits:Development finance institutions and impact-first organizations deploying concessional capital.
- Retail Investors:Individual savers accessing ESG-screened products through distribution platforms with simplified disclosure.
Transaction scale favors Institutional Investors; product innovation targets Corporations.
Service Model:
Value chain positioning determines margin capture and regulatory dependency, with verification and data infrastructure gaining pricing power as disclosure timelines compress.
- Advisory Services:Transition pathway design, taxonomy alignment assessment, and KPI calibration for sustainability-linked structures. Japanese megabanks and Singaporean regional lenders compete for heavy industrial borrower mandates requiring specialized decarbonization expertise.
- Certification:Second-party opinion provision and post-issuance verification against ICMA, CBI, or national taxonomy standards. Annual reporting requirements now strain issuer compliance resources and escalate audit fees across the region.
- Asset Management:Portfolio construction and active stewardship of sustainable investment mandates.
- Reporting Tools:Software platforms for emissions data collection, aggregation, and disclosure automation.
Revenue concentration sits with Advisory Services; technology leverage is climbing fastest in Reporting Tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Changi Airport financial district anchors regional capital flows, while Tokyo's Shibuya financial hub and Shanghai's Lujiazui district channel sovereign wealth into verified climate instruments. The region's grid interconnection infrastructure underwrites cross-border renewable project finance.
Singapore
Multinational manufacturers consolidate ASEAN treasury operations around sustainability-linked loan facilities. The Monetary Authority of Singapore's green finance taxonomy tightens product eligibility criteria and expands central bank collateral pools. DBS Group Holdings and OCBC Bank anchor underwriting capacity for Singapore-dollar denominated sustainable bonds.
Japan
Heavy industrial borrowers in steel and cement sectors face METI-mandated transition plan disclosure requirements. The Ministry of Economy, Trade and Industry's green transformation standards reshape benchmark index eligibility for yen-denominated instruments. Tokyo's financial district concentrates transition finance advisory expertise for decarbonization pathway design.
China
State Grid and regional utilities refinance coal-dependent generation portfolios into renewable infrastructure. The Ministry of Ecology and Environment's environmental information disclosure rules compress reporting timelines for corporate issuers. Shanghai's Lujiazui financial cluster anchors green bond issuance for domestic institutional placement.
Australia
Superannuation funds hold substantial dry powder for domestic renewable infrastructure deployment. The Australian Prudential Regulation Authority's climate risk disclosure guidance shapes institutional allocation mandates. Sydney's financial district lacks specialized sustainable debt placement expertise concentrated in Singapore and Tokyo.
South Korea
Corporate treasurers in battery storage and electric vehicle supply chains access sustainability-linked credit structures. The Financial Services Commission's green taxonomy alignment requirements govern KOSPI-listed issuer eligibility. Seoul's Yeouido financial hub concentrates ESG fund management for regional institutional mandates.
Asia-Pacific Sustainable Finance Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The market structures around diversified financial conglomerates with dedicated sustainable finance desks, regional lenders with ASEAN corporate relationships, and international banks with cross-border placement networks. Japanese megabanks and Singaporean regional lenders compete for heavy industrial borrower mandates. Dominant competitive moves include strategic partnerships for transition finance advisory capacity and geographic expansion into underpenetrated Australian superannuation fund relationships.
Among Japan-based diversified financial groups, Sumitomo Mitsui Financial Group and Mizuho Financial Group exemplify platform integrators anchoring yen-denominated sustainable debt placement. Within the Singapore-based regional banking tier, DBS Group Holdings occupies a position representing specialized ASEAN corporate issuer relationships. These three entities collectively illustrate the competitive archetype spectrum spanning domestic institutional network leverage, transition finance advisory specialization, and regional currency underwriting dominance.
| Leading Market Players |
|---|
| Sumitomo Mitsui Financial Group |
| Bank of China |
| Mizuho Financial Group |
| United Overseas Bank |
| HSBC Holdings |
| DBS Group Holdings |
| OCBC Bank |
| Standard Chartered Bank |
| MUFG Bank |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Singapore's sustainable debt underwriting desks is compressing arrangement fees for green bond issuances while simultaneously forcing regional banks to absorb higher verification costs from compressed disclosure timelines mandated by MAS taxonomy requirements.
Pricing Analysis
Volume-discount tiering structures dominate sustainable finance arrangement fees, with three-tier pricing separating benchmark-sized green bond issuances from mid-market sustainability-linked loans and bilateral advisory mandates. Price differentiation hinges on certification grade—ICMA-compliant frameworks command premium placement fees—and geographic delivery cost, with Singapore-dollar denominated instruments carrying lower distribution overhead than multi-currency cross-border structures. Pricing pressure stems from regional bank desk proliferation outpacing qualified issuer pipeline growth, particularly in ASEAN manufacturing credits. Institutional investors exhibit lowest price sensitivity, absorbing verification premium for index-eligible instruments, while mid-cap corporate treasurers negotiate aggressively on arrangement fees.
Supply Chain Analysis
Upstream feedstock concentration in Indonesian nickel processing and Australian rare earth extraction anchors battery storage project finance viability across the region. Raw material dependencies span lithium carbonate from Chilean salares, cobalt hydroxide from DRC mining operations, and processed cathode materials from South Korean chemical conglomerates. Supply chain risk centers on export restriction uncertainty from Indonesian mineral policy shifts, threatening wind turbine and battery manufacturing cost assumptions. Distribution runs through Singapore's financial hub for ASEAN corporate placement, with Tokyo handling yen-denominated institutional allocation and Shanghai channeling domestic Chinese green bond absorption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific sustainable finance market is entering a cyclical recovery phase as regional utilities accelerate coal portfolio retirement schedules, with refinancing waves from Japan's METI-mandated transition timelines driving instrument origination volume.
For Market Incumbents: Insulate core arrangement fee streams from margin compression by embedding proprietary transition finance advisory capabilities that emerging competitors cannot replicate overnight. Sumitomo Mitsui Financial Group and Mizuho Financial Group should deepen certification investment in blockchain-enabled carbon accounting infrastructure, creating technical moats against fintech verification challengers. Channel control through exclusive relationships with Australia's superannuation fund placement agents represents a defensible lever against Singaporean regional lender encroachment.
For New Entrants and Emerging Players: Pursue white-space capture in Australian sustainable debt placement, where domestic superannuation fund demand substantially exceeds specialized underwriting capacity concentrated in Singapore and Tokyo. Technology convergence opportunities in real-time emissions verification software for sustainability-linked loan KPI monitoring offer the most penetrable segment, with ASEAN manufacturing treasurers seeking audit cost reduction. A go-to-market angle anchored in quarterly disclosure automation—versus incumbent annual reporting cycles—addresses acute issuer pain points.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among certification and verification service providers with multi-year post-issuance monitoring contracts, suggesting durable cash flow quality in this archetype over the projection horizon. Long-term viability favors acquisition targets with established ICMA framework approval relationships and proprietary data infrastructure for scope 3 emissions estimation. The signal to watch is METI taxonomy alignment acceleration for Japanese heavy industrial borrowers, which will trigger benchmark index rebalancing and associated placement demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Enabled Verification Infrastructure | Distributed ledger deployment by DBS Group Holdings compresses audit cycles from annual to quarterly reporting frequencies. |
| Transition Finance Advisory Capacity Buildout | Mizuho Financial Group's specialized decarbonization pathway design captures METI-mandated heavy industrial borrower mandates. |
| Australian Superannuation Fund Relationship Expansion | Singaporean regional lenders penetrate dry powder concentration lacking domestic sustainable debt placement expertise. |
| ASEAN Regional Taxonomy Harmonization Partnership | Cross-border instrument restructuring cost reduction expands benchmark index eligibility for multi-jurisdictional issuers. |
| Real-Time Emissions Data Platform Integration | Technology convergence enables automated KPI monitoring for sustainability-linked loan coupon step-up trigger assessment. |
Research Methodology
Initial hypotheses were tested against primary input from sustainable finance desk heads, corporate treasury officers at ASEAN manufacturing multinationals, third-party verification specialists, and institutional fixed-income portfolio managers, and refined through secondary validation against MAS regulatory filings, ICMA Green Bond Principles documentation, METI transition plan disclosure guidelines, and ASEAN sustainable finance taxonomy development papers. Bottom-up instrument origination data triangulated against top-down central bank collateral pool expansion metrics.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning investment type flexibility, industry focus regulatory pressure intensity, client type disclosure bandwidth, and service model value chain positioning. CAGRs derived from instrument origination volume trajectories, verification protocol adoption curves, and institutional mandate allocation shifts. Forecast inputs incorporated coal retirement schedule acceleration from Japan's JERA and China's State Grid, alongside Singapore-dollar sustainable bond benchmark inclusion eligibility timelines.
Sensitivities concentrate around ASEAN regional taxonomy harmonization delays, Indonesian rare earth export restriction policy shifts, and scope 3 emissions measurement protocol standardization failures that could compress sustainability-linked loan adoption below modeled trajectories. Cross-checking against Climate Bonds Initiative regional market sizing and ICMA Green Bond Market Summary data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Enterprise Risk Management Market
Risk Management and Compliance
Financial Services Security Software Market
Risk Management and Compliance
Financial Risk Management Software Market
Risk Management and Compliance
Asia-Pacific BFSI Biometrics Market
Risk Management and Compliance
Treasury and Risk Management Market
Risk Management and Compliance
Europe Strategic Consulting Services Market
Risk Management and Compliance
Global Compliance Management Software Market
Risk Management and Compliance
Pre Trade Risk Management Solution Market
Risk Management and Compliance
NPL Management Market
Risk Management and Compliance
Global Patient Safety and Risk Management Softwares Market
Risk Management and Compliance
Travel Risk Management Services Market
Risk Management and Compliance
Global Energy Trading and Risk Management (ETRM) Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market
Risk Management and Compliance
Risk Assessment Software Market
Risk Management and Compliance
Quality Warranty Management Market
Risk Management and Compliance
Surety Market