
 Sell-Side Due Diligence Services Market | 2026-2036
Sell-Side Due Diligence Services Market Size, Share, and Industry Trends Forecast 2026-2036
Sell-Side Due Diligence Services Market Insights
Quality of earnings analysis is decoupling from full-scope vendor due diligence, allowing sponsors to purchase modular assurance without committing to comprehensive packages. Deloitte leverages its audit heritage to anchor complex carve-out engagements across multiple jurisdictions. PwC sustains competitive positioning through integrated tax and financial due diligence workflows. KPMG specializes in operational review modules that address EBITDA normalization and working capital mechanics.
Sell-side due diligence services encompass preparatory financial and operational assessments conducted on behalf of vendors prior to transaction launch, typically involving quality of earnings reports, working capital analyses, and vendor assistance protocols delivered under tight confidentiality constraints. The primary purpose is to surface and resolve issues before buyer scrutiny, thereby preserving valuation and accelerating timeline certainty. Financial analysis and market assessment segments command premium pricing due to their direct linkage to valuation confidence, while risk assessment modules are gaining traction among private equity firms navigating leveraged buyout exits. Operational review work remains comparatively mature, with margin pools shifting toward technology and healthcare verticals where regulatory complexity demands specialized expertise.
The SEC enforces disclosure standards that elevate preparatory rigor for US-listed transactions, while the EU's CSRD and GDPR frameworks impose additional data governance requirements on cross-border engagements involving European targets. These regulatory layers shape service scope, dictate staffing models, and influence pricing structures for multi-jurisdictional mandates. Stakeholders must monitor evolving disclosure thresholds and determine whether to build captive diligence capabilities or deepen reliance on external advisory partnerships.
Market Dynamics
Private equity sponsors now demand modular assurance packages that decouple quality of earnings analysis from full-scope vendor due diligence, compressing engagement timelines and forcing advisory firms to unbundle legacy service bundles.
Growth Catalysts
- SPAC Disclosure Mandates:The SEC's heightened disclosure requirements around de-SPAC transactions compel sellers to commission preparatory financial assessments before auction launch, embedding sell-side diligence into standard exit protocols.
- Healthcare Regulatory Complexity:Specialized operational review modules addressing FDA compliance and revenue recognition for pharmaceutical carve-outs command premium pricing as sponsors navigate intricate reimbursement mechanics.
- Cross-Border Data Governance:The EU's GDPR and CSRD frameworks impose additional assurance layers on transactions involving European targets, expanding service scope for multi-jurisdictional mandates.
Market Restraints
- Talent Concentration Risk:Experienced transaction services professionals cluster in New York, London, and Singapore, creating geographic supply bottlenecks that extend staffing timelines for urgent engagements.
- Input Cost Volatility:Specialized industry expertise in technology and healthcare verticals commands compensation premiums that compress margin pools on fixed-fee arrangements.
- Regulatory Friction:China's SAMR data localization requirements complicate cross-border information sharing for carve-outs involving Chinese subsidiaries, delaying report finalization.
Strategic Opportunities
- India Sponsor Market Expansion:SEBI's evolving disclosure standards for listed company acquisitions create demand for vendor assistance protocols among domestic private equity firms executing control transactions.
- Climate Risk Integration:The EU Green Deal's due diligence directives position carbon footprint assessment modules as emerging service lines for industrial carve-outs facing buyer scrutiny.
- AI-Assisted Document Analysis:Natural language processing tools converging with financial statement extraction technology compress data room review cycles, enabling advisory firms to restructure pricing toward outcome-based models.
Industry Challenges
- Confidentiality Protocol Complexity:Strict information barriers between audit and transaction advisory practices at diversified professional services firms complicate resource deployment for carve-out engagements.
- Integration with Legacy ERP Systems:Targets running on outdated financial reporting infrastructure require manual data reconciliation that extends working capital analysis timelines and strains junior staffing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sell-Side Due Diligence Services Market |
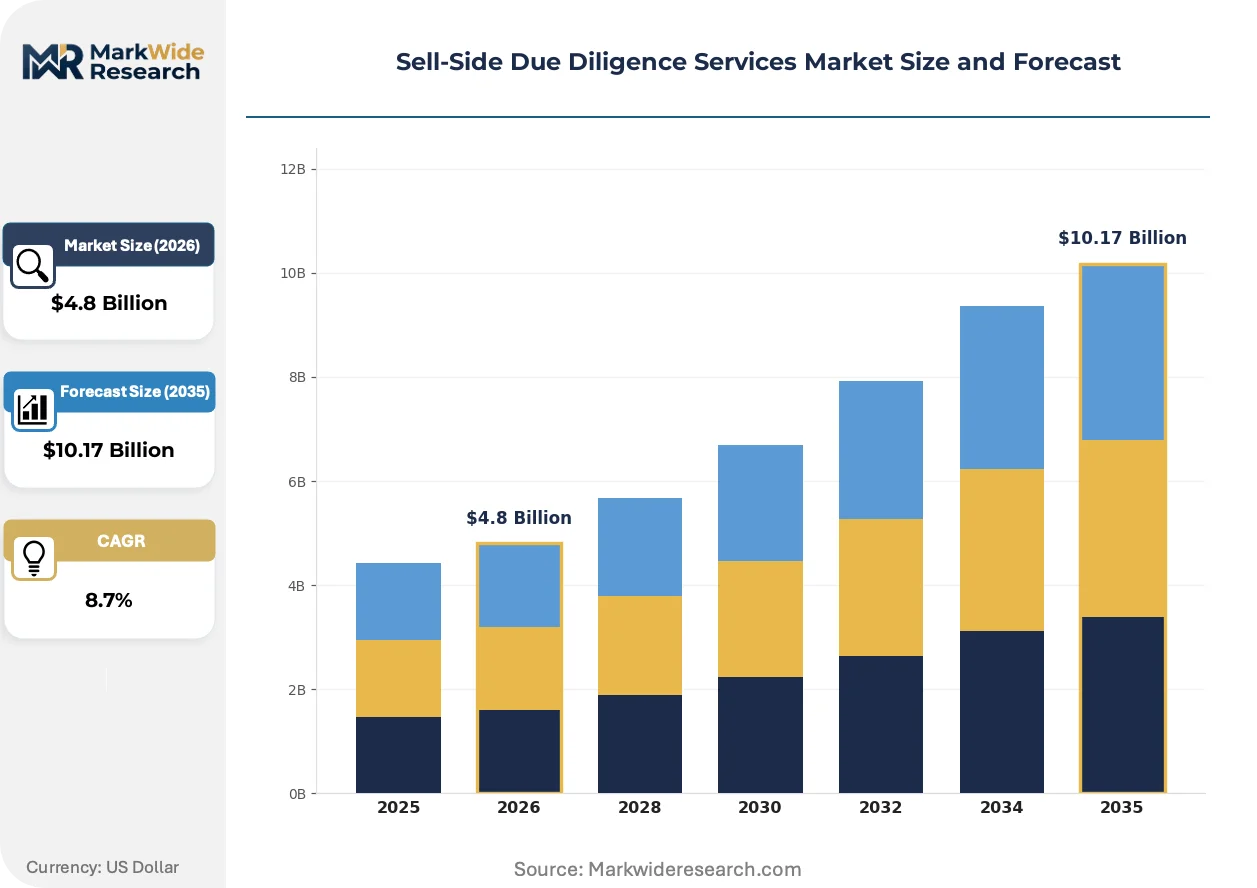
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Financial Analysis, Market Assessment, Operational Review, Risk Assessment Client Type: Private Equity Firms, Investment Banks, Corporations, Individual Sellers Industry Vertical: Technology, Healthcare, Manufacturing, Retail Engagement Model: Fixed Fee, Contingency, Retainer, Hourly |
| Companies Covered | Deloitte, PwC, KPMG, Ernst & Young, FTI Consulting, Alvarez & Marsal, RSM International, Houlihan Lokey, L.E.K. Consulting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sell-Side Due Diligence Services Market Trends and Innovations
Technology-enabled assurance tools and regulatory fragmentation are reshaping how sell-side diligence is scoped, priced, and delivered across transaction types and geographies.
Automated data extraction platforms using machine learning algorithms are expanding into quality of earnings workflows, enabling mid-market sponsors to access analytical capabilities previously reserved for large-cap auctions. Private equity firms with standardized portfolio company reporting systems are adopting these tools at accelerating pace. This compression of manual review hours is expanding into adjacent modules like contract abstraction and lease identification.
The EU's Corporate Sustainability Reporting Directive mandates granular disclosure of environmental and social metrics for in-scope entities, elevating ESG due diligence from optional add-on to core transaction preparation. Industrial targets with complex supply chains face expanded buyer scrutiny on Scope 3 emissions and labor practices. European carve-outs are responding by commissioning specialized sustainability assurance modules ahead of auction launch.
Buyers are unbundling full-scope vendor due diligence reports, purchasing discrete modules directly from advisory firms rather than relying on seller-furnished packages. This disintermediation of traditional sell-side distribution channels is most visible in the United States, where sponsor-backed buyers with captive diligence capabilities prefer direct advisory relationships. Seller advisors are responding by developing proprietary data rooms and interactive reporting formats that resist modular disaggregation.
Sell-Side Due Diligence Services Market Segmentation
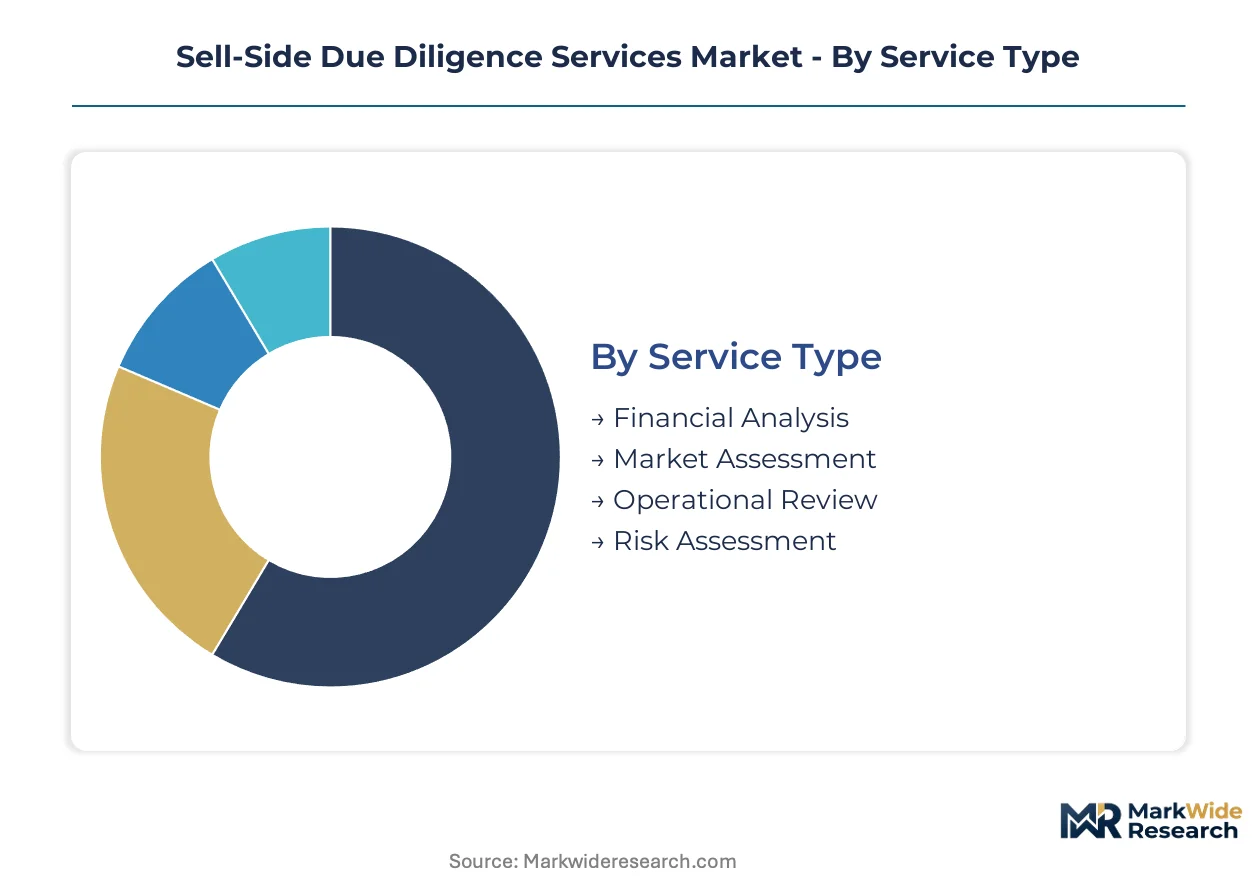
Sell-side due diligence services fragment across service architecture, client sophistication, and regulatory exposure. Each dimension shapes staffing models, pricing structures, and jurisdictional coverage requirements.
Service Type:
SEC disclosure mandates for SPAC mergers and FDA compliance protocols in healthcare carve-outs dictate which service modules require specialized certifications versus generalist execution.
- Financial Analysis:Quality of earnings reports and working capital mechanics form the core deliverable for auction-bound sellers. Private equity sponsors in the United States commission these modules most intensively ahead of sponsor-backed exits.
- Market Assessment:Competitive positioning studies and addressable market sizing address buyer scrutiny on growth sustainability. Technology verticals in California and Massachusetts drive concentrated demand given valuation sensitivity to TAM assumptions.
- Operational Review:EBITDA normalization and cost structure analysis support manufacturing carve-outs.
- Risk Assessment:Regulatory compliance and litigation exposure screening addresses cross-border transactions.
Financial Analysis sits at the top of the volume ranking, with Market Assessment climbing the fastest.
Client Type:
Engagement complexity scales with the client's captive diligence capabilities and auction timeline pressures.
- Private Equity Firms:Sponsors with standardized portfolio reporting systems demand modular assurance packages that decouple quality of earnings from full-scope vendor due diligence. Firms headquartered in New York and Boston compress timelines through repeat relationships with advisory practices.
- Investment Banks:Sell-side advisors commission preparatory work to accelerate buyer confidence and reduce valuation leakage.
- Corporations:Strategic divestitures require carve-out financial statements and stranded cost analyses.
- Individual Sellers:Founder-owned businesses seek limited-scope vendor assistance for auction preparation.
Private Equity Firms command the largest share of advisory capacity, while Corporations are expanding their engagement fastest as corporate carve-out activity accelerates.
Industry Vertical:
Regulatory complexity and revenue recognition standards determine the specialist expertise required per engagement.
- Technology:SaaS targets with recurring revenue models require specialized subscription revenue recognition analysis and churn metric validation. Buyers scrutinize net revenue retention and CAC payback periods, elevating the analytical burden beyond traditional manufacturing assessments.
- Healthcare:FDA compliance documentation and reimbursement mechanics command premium pricing. Pharmaceutical carve-outs face expanded scrutiny on revenue recognition for milestone payments and royalty streams.
- Manufacturing:Working capital cycles and inventory valuation dominate diligence scope.
- Retail:Omnichannel cost allocation and lease identification address margin compression concerns.
Technology verticals absorb the highest advisory hours, with Healthcare posting the steepest expansion trajectory.
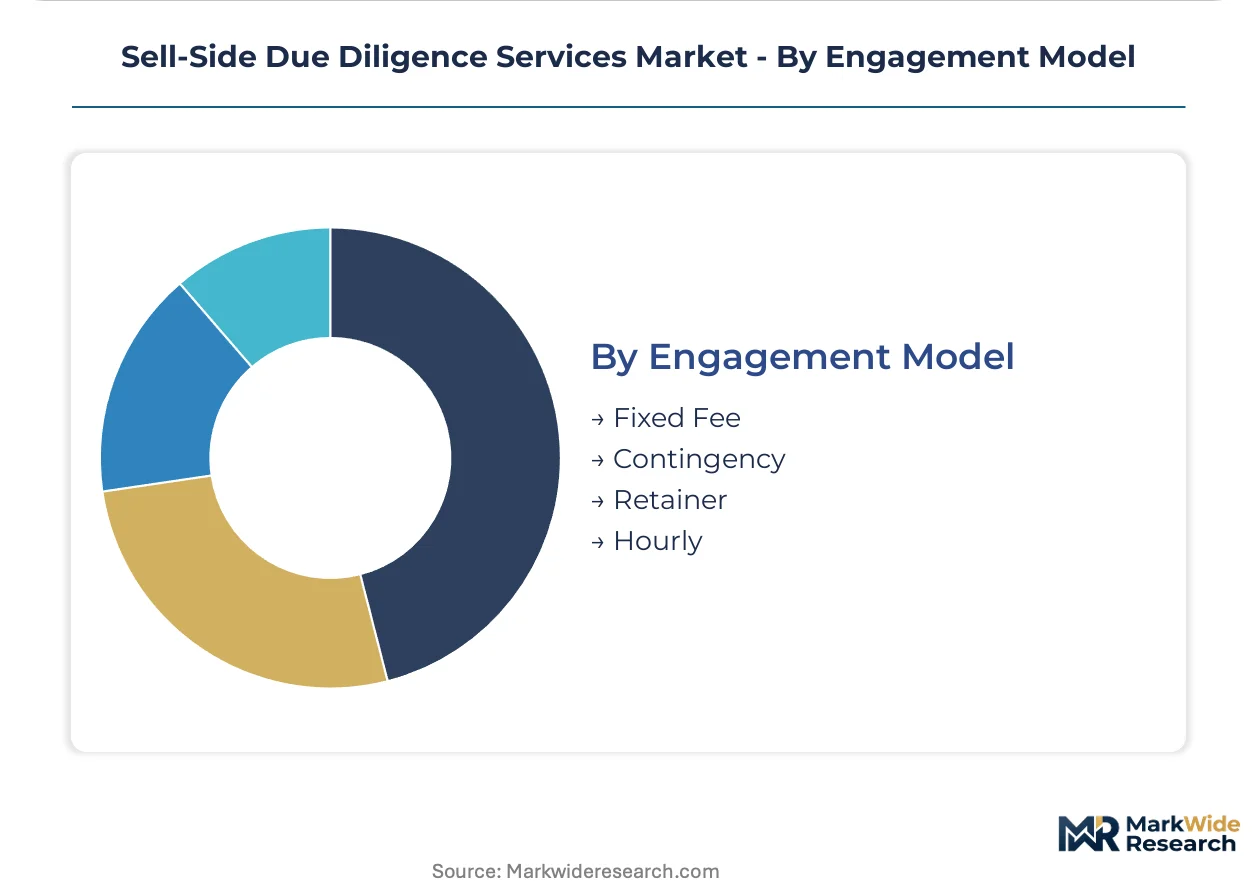
Engagement Model:
Pricing structures align with outcome certainty and timeline predictability.
- Fixed Fee:Pre-scoped modules with defined deliverables and timeline boundaries. Private equity sponsors with standardized auction processes prefer this structure for budget predictability on repeat engagements.
- Contingency:Success-based pricing tied to transaction close or valuation achievement.
- Retainer:Ongoing advisory relationships for portfolio companies with recurrent divestiture activity.
- Hourly:Time-and-materials billing for exploratory or scope-uncertain engagements.
Fixed Fee structures dominate current volume, with Retainer arrangements gaining share fastest among sponsor firms with active portfolio monetization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where sell-side due diligence engagements concentrate, as compliance cost differentials and disclosure standard variations drive advisory demand toward jurisdictions with the most transaction velocity and the steepest preparatory requirements.
United States
Private equity sponsor-backed exits and corporate carve-outs generate the densest advisory volume globally. SEC disclosure mandates for SPAC mergers and de-SPAC transactions compel sellers to commission preparatory financial assessments before auction launch. New York and Boston anchor the professional talent cluster, though staffing bottlenecks extend timelines for urgent engagements.
United Kingdom
Cross-border transaction flows between London and European financial centers sustain demand for multi-jurisdictional assurance modules. FCA listing rules and the UK's retained EU law framework impose layered disclosure requirements on target entities. The City of London concentrates advisory capacity for technology and healthcare carve-outs facing buyer scrutiny.
Germany
Industrial manufacturing divestitures and Mittelstand exits drive operational review work addressing EBITDA normalization and working capital mechanics. The EU's CSRD and GDPR frameworks impose additional data governance requirements on engagements involving German targets. Bavaria and North Rhine-Westphalia host the densest concentration of mid-market advisory mandates.
India
Domestic private equity firms executing control transactions are expanding vendor assistance protocol adoption as SEBI evolves disclosure standards for listed company acquisitions. Regulatory convergence with international practice is elevating preparatory rigor ahead of auction processes. Mumbai and Delhi-NCR concentrate advisory relationships among sponsor firms with active portfolio monetization programs.
Singapore
Southeast Asian carve-outs and regional headquarters divestitures channel demand through Singapore-based advisory practices. MAS regulatory frameworks and cross-border data sharing protocols shape engagement scoping for transactions involving ASEAN subsidiaries. The financial district concentrates talent for technology and healthcare verticals where regulatory complexity commands premium pricing.
Sell-Side Due Diligence Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with diversified professional services networks capturing the largest advisory capacity while boutique transaction specialists occupy premium niches. The market structure concentrates around four global networks and a tier of specialized consultancies. Three archetypes dominate: audit-heritage firms leveraging cross-service synergies, independent transaction advisors emphasizing speed and customization, and restructuring specialists converting distress mandates into sell-side preparation. Competitive moves center on modular service unbundling and technology-enabled delivery compression.
Within the audit-heritage tier, Deloitte, PwC, and KPMG anchor competitive positioning through integrated tax, financial, and operational due diligence workflows. Deloitte exemplifies the cross-jurisdictional carve-out specialist archetype, while PwC occupies a position emphasizing tax-integrated execution. KPMG represents the operational review module specialist, particularly for EBITDA normalization and working capital mechanics. Boutique independents including FTI Consulting and Alvarez & Marsal sit within the speed-and-customization tier, serving sponsors demanding compressed timelines and discrete assurance packages outside bundled structures.
| Leading Market Players |
|---|
| Deloitte |
| PwC |
| KPMG |
| Ernst & Young |
| FTI Consulting |
| Alvarez & Marsal |
| RSM International |
| Houlihan Lokey |
| L.E.K. Consulting |
| Others |
Pricing and Supply Chain Analysis
Private equity sponsors demanding compressed auction timelines are forcing advisory firms to restructure engagement economics around outcome certainty rather than hourly recovery. This procurement preference rewards modular service architectures and penalizes legacy bundled pricing, concentrating margin in specialized regulatory verticals where certification scarcity commands premium positioning.
Pricing Analysis
Advisory margin layers stratify across partner-led assurance, director-executed modules, and staff-augmented data processing tiers. Pricing stratifies across premium carve-out specialists, standard multi-service bundles, and economy vendor-assistance protocols differentiated by jurisdictional coverage depth and regulatory certification level. Cost compression in standard-tier engagements is intensifying because AI-assisted document review tools commoditize basic financial analysis. Corporate carve-out sponsors exhibit highest price sensitivity due to captive finance capabilities, while SPAC-bound sellers demonstrate lowest sensitivity given SEC disclosure failure costs.
Supply Chain Analysis
Regional talent distribution centers in New York, London, and Singapore anchor hub-and-spoke deployment patterns for cross-border mandates. Professional service supply concentrates in the United States, United Kingdom, and Singapore, drawing from specialized transaction services expertise pools and audit-heritage training pipelines. Raw material dependencies include experienced CPA-certified professionals, industry-specialist sector leads, and regulatory-certified compliance advisors. Single-source vulnerability concentrates in healthcare FDA specialists and technology SaaS revenue recognition experts. Distribution runs through direct sponsor relationships and investment bank referral channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate where SEC disclosure mandates impose steeper preparatory costs than EU CSRD frameworks, favoring advisory capacity placement in jurisdictions with regulatory burden asymmetries.
For Market Incumbents: Extend modular service architectures into climate risk integration modules ahead of EU Green Deal due diligence directives. Consolidate talent retention through equity participation structures addressing poaching from technology-enabled entrants. Vertical integration into AI-assisted document extraction platforms defends margin position against automated workflow disruption. For New Entrants and Emerging Players: Begin with boutique positioning in India's SEBI-evolving disclosure market where domestic private equity firms lack captive diligence capabilities. Target founder-owned businesses in secondary US metropolitan markets underserved by New York-centric talent clusters. Pursue direct-to-sponsor go-to-market relationships bypassing investment bank referral intermediation. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-enabled advisory platforms possessing proprietary data extraction infrastructure. Long-term viability across the next decade hinges on workflow automation differentiation rather than talent scale alone. Acquisition focus should center on mid-market specialists with healthcare FDA certification depth. Monitor AI-assisted quality of earnings tool adoption rates as inflection indicator for incumbent margin compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Service Unbundling | Delivers sponsor-preferred assurance packages decoupled from comprehensive vendor due diligence mandates. |
| AI-Assisted Document Analysis | Compresses data room review cycles through natural language processing converging with financial extraction technology. |
| Climate Risk Integration | Positions carbon footprint assessment modules for industrial carve-outs facing EU Green Deal buyer scrutiny. |
| India Market Expansion | Captures SEBI disclosure standard evolution among domestic private equity control transactions. |
| Healthcare Regulatory Specialization | Commands premium pricing for FDA compliance documentation and pharmaceutical reimbursement mechanics. |
Research Methodology
Direct dialogue with transaction services partners, private equity operating partners, investment bank coverage officers, and corporate development executives grounded qualitative assessment in practitioner workflow realities. Secondary validation drew from SEC filing disclosures, SEBI regulatory circulars, EU CSRD implementation guidance, and professional services firm transparency reports. Bottom-up engagement volume analysis triangulated with top-down market sizing across service type, client archetype, and industry vertical dimensions.
Segment-level value outputs across the projection horizon reflect modeled pricing trajectories by engagement complexity tier and regulatory certification requirements. Forecast segmentation incorporated service architecture modularity, sponsor captive capability maturity, and jurisdictional disclosure burden intensity. CAGRs were derived from historical advisory volume patterns and projected transaction velocity assumptions. Industry-specific inputs included SPAC merger pipeline tracking and private equity exit timeline survey data.
Caveats apply where regulatory disclosure threshold revisions or AI workflow adoption acceleration could materially shift the outlook for traditional hourly-based engagement economics. Forecasts reflect documented assumptions around sponsor behavior continuity and cross-border transaction friction persistence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Global Regulatory Reporting and Compliance Market
Risk Management and Compliance
BFSI Crisis Management Market
Risk Management and Compliance
Global Liquidity Asset Liability Management Solutions Market
Risk Management and Compliance
Enterprise Risk Management Market
Risk Management and Compliance
Crypto Compliance Software Market
Risk Management and Compliance
Legal Advisory Service Market
Risk Management and Compliance
Europe Strategic Consulting Services Market
Risk Management and Compliance
Europe Risk Management Market
Risk Management and Compliance
BFSI Security Market
Risk Management and Compliance
Asia-Pacific Compliance and Traceability Solutions Market
Risk Management and Compliance
Loan Compliance Management Software Market
Risk Management and Compliance
Travel Risk Management Services Market
Risk Management and Compliance
Third Party Risk Management Market
Risk Management and Compliance
Global Credit Risk Rating Software Market
Risk Management and Compliance
Stress Testing Solutions Market
Risk Management and Compliance
Operations Advisory Service Market