
 Southeast Asia Credit and Risk Management Market | 2026-2036
Southeast Asia Credit and Risk Management Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Credit and Risk Management Market Insights
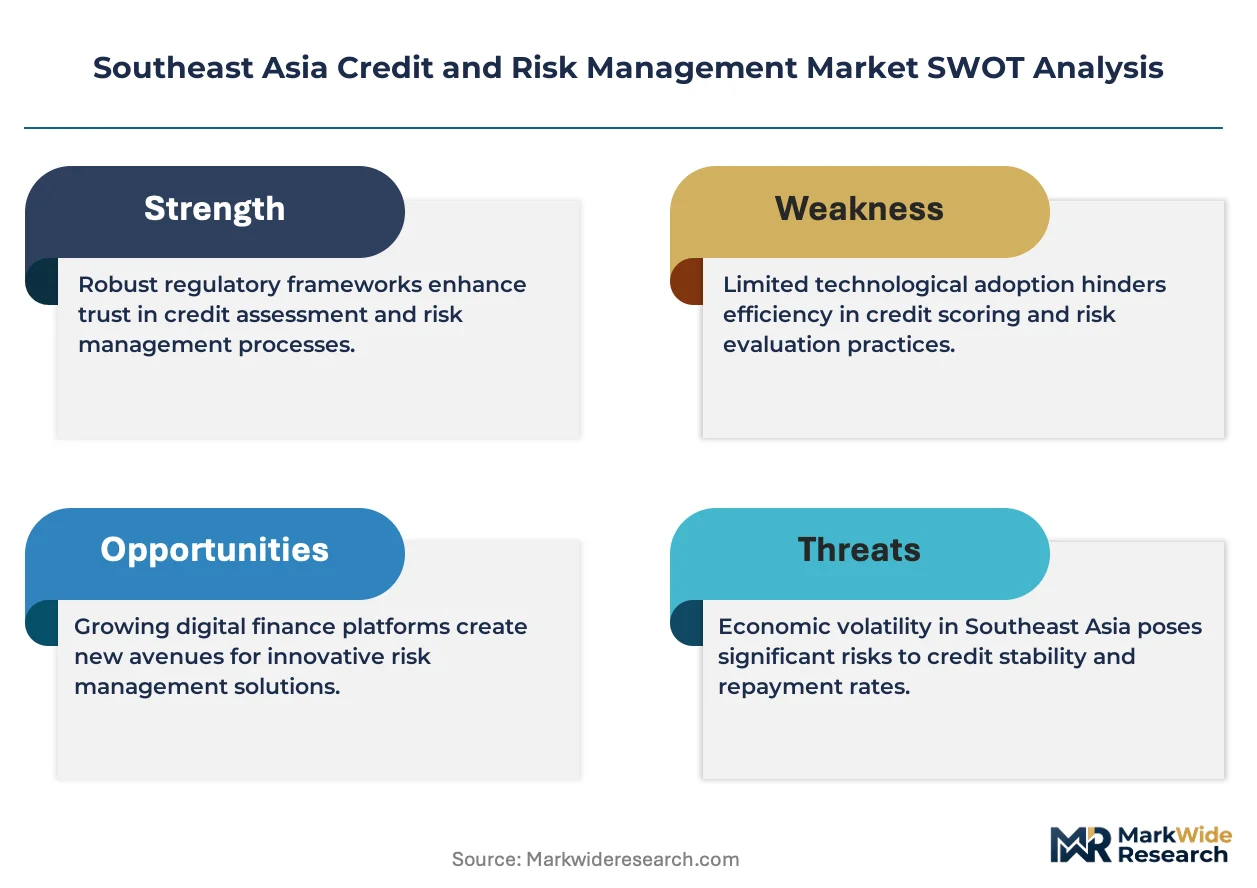
Basel III capital adequacy rules is recalibrating the cost-of-entry calculus for risk technology vendors across Southeast Asia. Moody's Analytics leverages its sovereign risk databases to anchor pricing models for regional banks navigating fragmented credit bureaus. SAS Institute Inc. competes through advanced machine learning fraud layers tailored to ASEAN's mobile-first transaction patterns. Experian plc extends its alternative data partnerships into Indonesia and Vietnam, where thin-file borrowers dominate credit portfolios.
Credit and risk management encompasses the systematic evaluation, quantification, and mitigation of financial default probability across lending, investment, and counterparty relationships, employing statistical scoring models, behavioral analytics, and real-time monitoring dashboards to flag anomalies. Its primary commercial purpose is to minimize expected loss while optimizing capital allocation against regulatory thresholds. Cloud Solutions within the Technology dimension leads deployment preferences as ASEAN banks bypass legacy infrastructure, while Fraud Detection under Service Type captures the fastest growth trajectory given surging e-commerce transaction volumes. Machine Learning competes for margin pools by automating pattern recognition in historically manual underwriting workflows across the region's emerging middle-class segments.
Bank Negara Malaysia, the Monetary Authority of Singapore, and the ASEAN Banking Integration Framework collectively shape data localization mandates, cross-border credit information sharing protocols, and operational risk capital requirements that dictate vendor selection criteria. The Philippines' central bank has issued circulars requiring real-time fraud monitoring for digital wallet providers, tightening compliance windows. Stakeholders must monitor which national regulators harmonize with ASEAN-wide standards versus maintaining idiosyncratic local rules that fragment platform architectures.
Market Dynamics
Digital lending platforms across Indonesia, Thailand, and Vietnam are forcing banks to replace batch-processed credit scoring with real-time engines that ingest mobile transaction data, telecommunications usage patterns, and e-commerce behavioral signals.
Growth Catalysts
- ASEAN Framework on Digital Data Governance:Cross-border data sharing protocols are compelling Indonesian and Vietnamese banks to modernize risk infrastructure, opening procurement windows for cloud-native scoring platforms.
- Mobile-first transaction volumes:Surging e-commerce penetration across Thailand's digital wallet ecosystem is generating alternative data streams that feed machine learning fraud detection layers.
- Archipelago banking dispersion:Geographic fragmentation across Indonesia's 17,000 islands amplifies default monitoring complexity, creating demand for satellite-enabled field verification tools.
Market Restraints
- Data localization mandates:Bank Negara Malaysia and Monetary Authority of Singapore storage requirements fragment platform architectures, raising compliance costs for regional deployments.
- Thin-file borrower dominance:Vietnam's credit bureau coverage gaps limit traditional scoring accuracy, forcing reliance on expensive alternative data partnerships.
- Legacy core banking debt:Southeast Asian tier-2 institutions maintain decades-old COBOL systems that resist API integration with modern risk engines.
Strategic Opportunities
- Philippines digital wallet compliance:Central bank circulars mandating real-time fraud monitoring for GCash and Maya create immediate procurement demand for behavioral analytics suites.
- Embedded finance convergence:Ride-hailing and e-commerce platforms in Thailand are integrating credit underwriting into checkout flows, requiring white-label risk-as-a-service modules.
- Climate risk stress testing:ASEAN Banking Integration Framework guidelines on environmental exposure quantification are opening advisory service lines for agricultural lending portfolios.
Industry Challenges
- Quantitative risk talent scarcity:Vietnamese and Indonesian institutions compete with Singaporean fintechs for data scientists capable of tuning gradient-boosted default models on sparse training data.
- Multi-bureau reconciliation complexity:Divergent scoring methodologies across Indonesia's OJK-licensed bureaus and Vietnam's CIC require costly normalization layers in platform implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Credit and Risk Management Market |
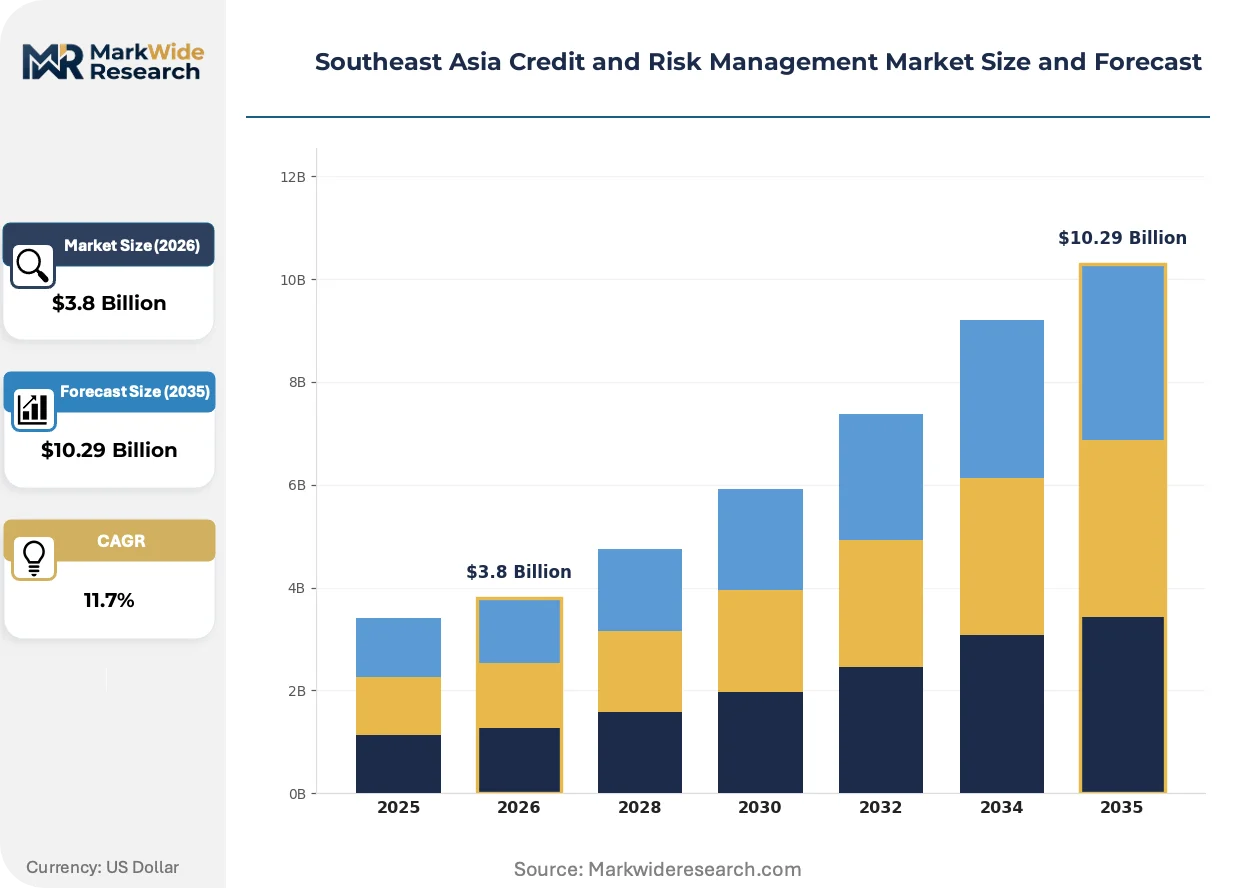
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Credit Scoring, Risk Assessment, Fraud Detection, Compliance Management Technology: Machine Learning, Data Analytics, Blockchain, Cloud Solutions End User: Financial Institutions, Insurance Companies, Retailers, Telecom Providers Delivery Model: On-premises, SaaS, Managed Services, Hybrid |
| Companies Covered | Moody's Analytics, SAS Institute Inc., Oracle Corporation, Experian plc, FICO, IBM Corporation, SAP SE, Temenos AG, GBG Group, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Credit and Risk Management Market Trends and Innovations
Machine learning automation is compressing underwriting timelines from days to seconds across Southeast Asia's digital lending channels, while regulatory pressure on data governance is reshaping vendor selection criteria.
Federated learning architectures are rewriting how banks train credit models without centralizing sensitive borrower data. Indonesian digital lenders are piloting these frameworks to comply with cross-border data restrictions while maintaining model accuracy. The technology is rewriting competitive dynamics by allowing consortium-based scoring pools that previously required monolithic data warehouses.
Philippines central bank circulars on real-time fraud monitoring are tightening compliance windows for digital wallet providers. The regulation forces technology refreshes among e-money issuers that previously relied on batch reconciliation. Rural banking cooperatives face the steepest adaptation curve given limited IT staffing and satellite connectivity constraints.
Buyers are unbundling risk technology procurement from core banking relationships, fragmenting vendor concentration that historically favored incumbent platform providers. Thai commercial banks now run parallel scoring engines from specialized fintechs alongside legacy systems. This pattern is most visible in Vietnam's state-owned banking sector, where procurement committees evaluate cloud-native alternatives against on-premise installations.
Southeast Asia Credit and Risk Management Market Segmentation
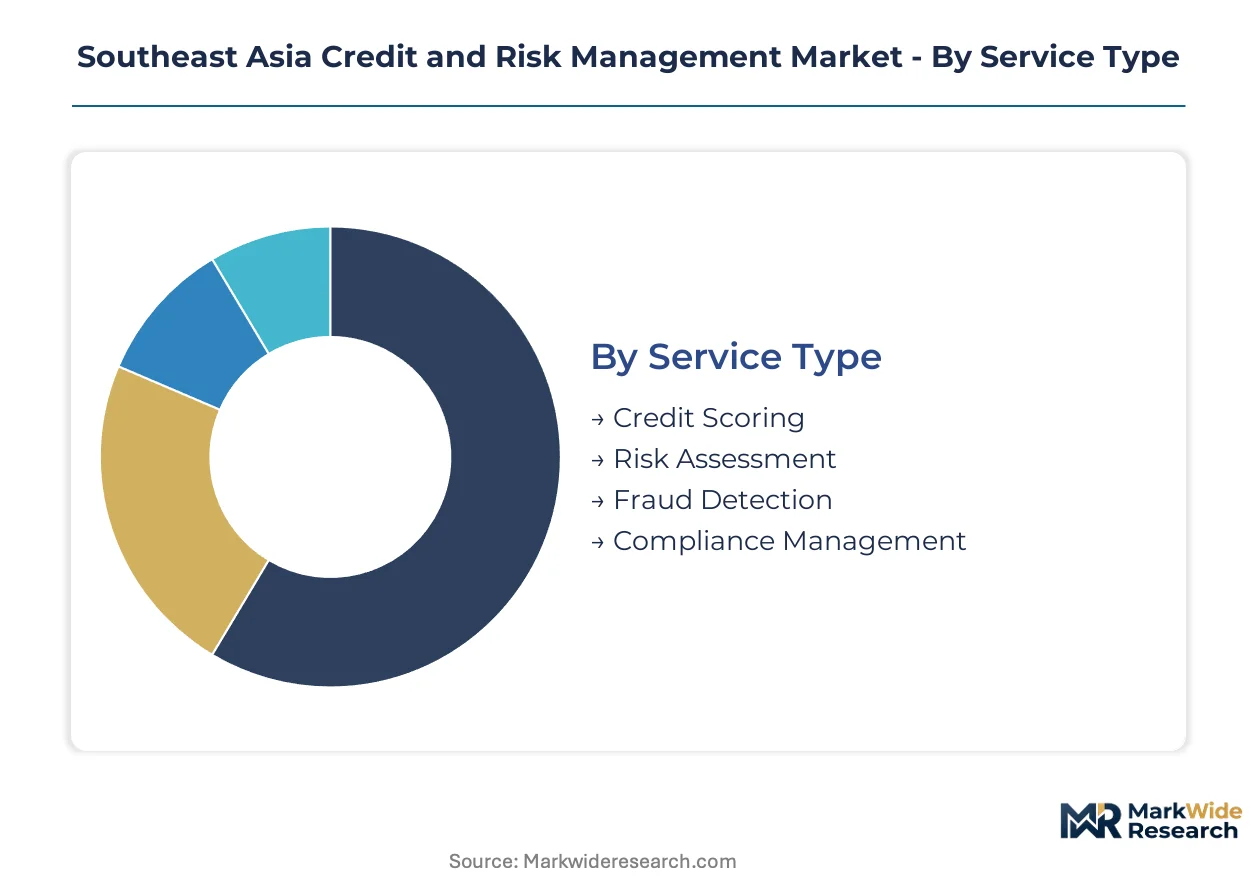
Southeast Asian banks and non-bank lenders configure procurement decisions around deployment speed, regulatory compliance windows, and legacy system integration constraints. Segmentation reveals how vendor selection prioritizes real-time scoring capabilities over batch-processing heritage systems across Indonesia's archipelago banking networks.
Service Type:
Procurement committees weight compliance urgency against fraud exposure severity when allocating annual technology budgets.
- Fraud Detection:Real-time behavioral analytics engines ingest mobile transaction patterns, telecommunications metadata, and e-commerce signals to flag anomalous payment flows. Thai digital wallet providers and Indonesian peer-to-peer lenders drive procurement volume as central bank circulars tighten monitoring windows. Demand concentrates in Philippines e-money issuers facing satellite connectivity constraints in rural cooperative networks.
- Credit Scoring:Statistical models quantify default probability through traditional bureau data and alternative streams including utility payments, ride-hailing transaction histories, and agricultural commodity price feeds. Vietnamese thin-file borrower dominance forces reliance on telco partnership data layers. Indonesian tier-2 banks bypass legacy batch systems for API-native scoring engines.
- Risk Assessment:Portfolio-level stress testing frameworks evaluate concentration exposure across geographic and sectoral dimensions.
- Compliance Management:Automated reporting modules map transaction records against ASEAN Framework on Digital Data Governance protocols and national localization mandates.
Fraud Detection leads on scale; Credit Scoring leads on momentum.
Technology:
Architecture choices reflect infrastructure debt levels and cloud migration timelines across state-owned and private banking sectors.
- Cloud Solutions:Elastic compute environments enable real-time model training and scoring without capital-intensive data center builds. ASEAN banks bypass decades of legacy infrastructure accumulation, deploying containerized risk engines across Indonesian, Vietnamese, and Thai regulatory jurisdictions. Bank Negara Malaysia and Monetary Authority of Singapore data localization rules fragment platform architectures.
- Machine Learning:Gradient-boosted and neural network architectures automate pattern recognition in underwriting workflows previously requiring manual analyst review. Indonesian digital lenders pilot federated learning frameworks to comply with cross-border data restrictions while maintaining model accuracy. Talent scarcity in Vietnam and Indonesia intensifies competition with Singaporean fintechs.
- Data Analytics:Descriptive and predictive visualization layers aggregate multi-bureau credit information into unified borrower profiles.
- Blockchain:Distributed ledger prototypes enable consortium-based identity verification and immutable audit trails for agricultural lending collateral.
Cloud Solutions captures the dominant procurement share; Machine Learning exhibits the steepest expansion trajectory.
End User:
Vertical-specific regulatory pressure and transaction volume characteristics shape solution customization requirements.
- Financial Institutions:Commercial banks, rural cooperatives, and digital lenders deploy integrated risk platforms spanning retail, SME, and corporate credit portfolios. Indonesian archipelago dispersion amplifies field verification complexity, driving demand for satellite-enabled mobile underwriting tools. Thai banks run parallel scoring engines from specialized fintechs alongside legacy core systems.
- Insurance Companies:Underwriting automation and claims fraud detection modules address motor, health, and agricultural policy lines.
- Retailers:Embedded finance integrations at Thai e-commerce and ride-hailing checkout flows require white-label risk-as-a-service modules.
- Telecom Providers:Device financing and mobile money credit products leverage proprietary subscriber data for alternative scoring in thin-file markets.
Financial Institutions anchor procurement volume; Retailers demonstrate the sharpest adoption acceleration.
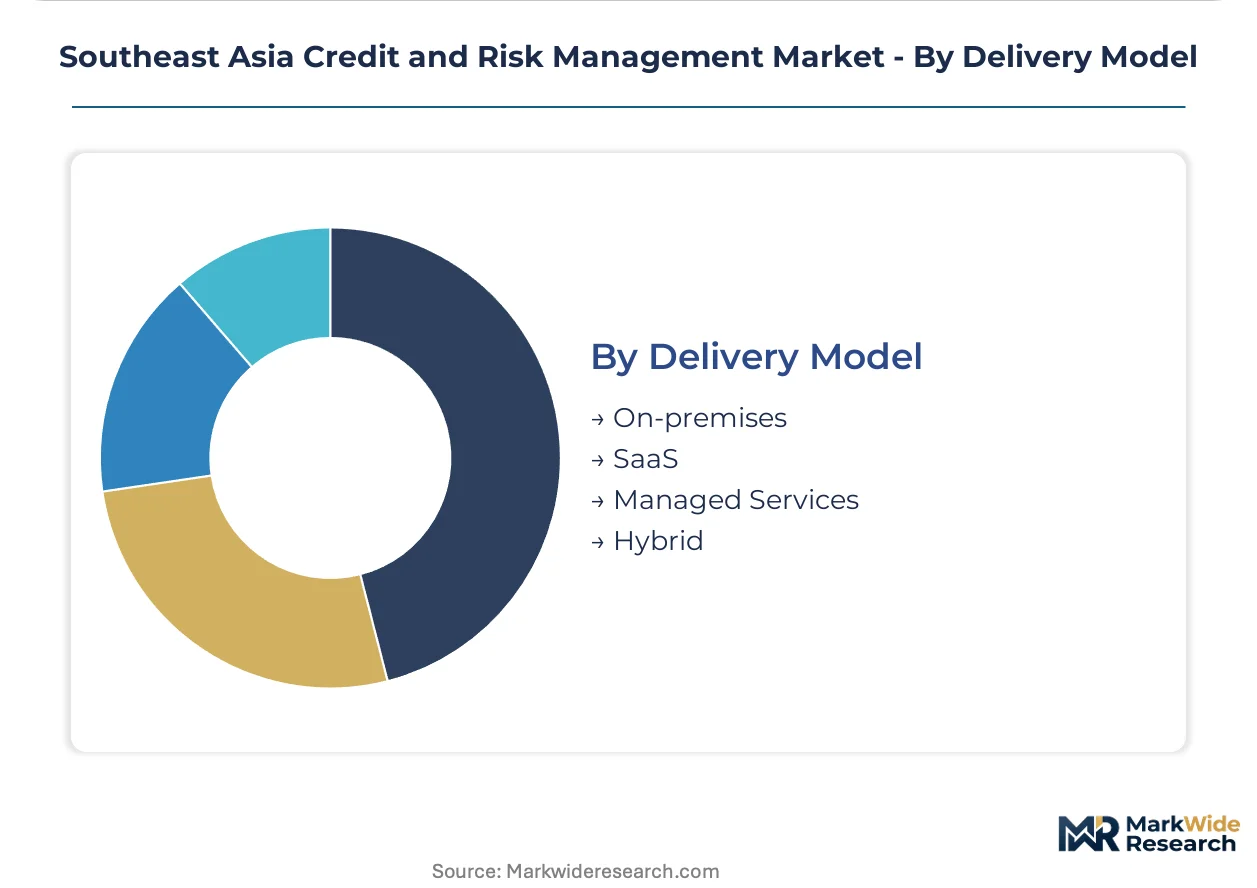
Delivery Model:
Total cost of ownership calculations weigh subscription predictability against customization depth and data sovereignty requirements.
- SaaS:Multi-tenant cloud deployments accelerate time-to-value for mid-tier Vietnamese and Indonesian institutions lacking dedicated infrastructure teams. Subscription economics align procurement with operational expenditure budgets, though data localization mandates in Malaysia and Singapore complicate regional platform standardization.
- On-premises:Installed software maintains control over sensitive borrower data and enables deep customization for tier-1 Thai and Indonesian banks with established security operations centers.
- Managed Services:Outsourced model development and monitoring addresses quantitative talent scarcity in emerging markets.
- Hybrid:Split architectures place sensitive scoring logic on-premises while leveraging cloud elasticity for non-critical analytics workloads.
SaaS dominates new procurement; Hybrid architectures gain traction among tier-1 institutions navigating compliance complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quantitative risk talent pools concentrate in Singapore's financial district, drawing data scientists from Vietnamese and Indonesian institutions into regional headquarters operations. This migration pattern fragments model development capacity across emerging market banking sectors while centralizing advanced analytics capabilities.
Indonesia
Seventeen-thousand-island banking dispersion demands satellite-enabled field verification tools for rural cooperative networks. OJK licensing requirements for credit bureaus create multi-bureau reconciliation complexity that fragments scoring standardization. Jakarta's fintech corridor hosts parallel scoring engine pilots alongside legacy core systems.
Thailand
Digital wallet transaction volumes from GCash competitors generate alternative data streams feeding machine learning fraud layers. Bank of Thailand oversight tightens real-time monitoring windows for e-money issuers. Bangkok's embedded finance integrations at ride-hailing checkout flows require white-label risk-as-a-service modules.
Vietnam
Thin-file borrower dominance forces reliance on telco partnership data layers where State Bank of Vietnam regulations intersect with credit bureau coverage gaps. Ho Chi Minh City's tier-2 institutions bypass decades-old COBOL systems for API-native scoring engines. Agricultural lending portfolios face climate risk stress testing under emerging guidelines.
Singapore
Monetary Authority of Singapore data localization mandates fragment regional platform architectures while attracting quantitative talent from across ASEAN. The city-state's banking integration framework headquarters shape cross-border credit information sharing protocols. Marina Bay financial district hosts vendor regional headquarters competing for procurement committees.
Philippines
Bangko Sentral ng Pilipinas circulars mandate real-time fraud monitoring for digital wallet providers including GCash and Maya. Rural banking cooperatives face steepest adaptation curves given limited IT staffing and satellite connectivity constraints. Manila's e-money issuers force technology refreshes from batch reconciliation systems.
Southeast Asia Credit and Risk Management Market Competitive Landscape
The competitive structure tilts toward global risk technology vendors with sovereign risk databases and machine learning fraud layers. Tier-1 institutions maintain parallel scoring relationships with specialized fintechs alongside legacy platform providers. Three archetypes dominate: global analytics conglomerates with regulatory data moats, cloud-native scoring specialists, and core-integrated risk suite providers. Competitive moves concentrate on federated learning consortiums and white-label risk-as-a-service modules for embedded finance.
Within the global analytics tier, Moody's Analytics and SAS Institute Inc. anchor procurement decisions through regulatory data partnerships and machine learning capabilities. Experian plc occupies a position emphasizing alternative data networks in thin-file markets. These three exemplify how vendor selection prioritizes real-time scoring architectures over batch-processing heritage across Indonesian, Thai, and Vietnamese banking procurement committees.
| Leading Market Players |
|---|
| Moody's Analytics |
| SAS Institute Inc. |
| Oracle Corporation |
| Experian plc |
| FICO |
| IBM Corporation |
| SAP SE |
| Temenos AG |
| GBG Group |
| Others |
Pricing and Supply Chain Analysis
Cloud compute costs cascade through SaaS subscription tiers as ASEAN financial institutions migrate from on-premise data centers to elastic infrastructure, compressing per-seat pricing for mid-tier Indonesian and Vietnamese banks while preserving premium rates for tier-1 institutions demanding sovereign data residency.
Pricing Analysis
The bundled-vs-unbundled service split defines procurement economics across Southeast Asia's risk technology market. SaaS-native vendors price through three-tier subscription structures across premium, standard, and economy levels, with premium tiers capturing institutions requiring Bank Negara Malaysia and Monetary Authority of Singapore data localization compliance. Price differentiation rests on API integration depth and real-time scoring latency guarantees. Cost compression in standard tiers intensifies because cloud infrastructure commoditization erodes margins, while tier-1 Thai and Indonesian banks show least price sensitivity given regulatory penalty exposure.
Supply Chain Analysis
Quantitative risk talent scarcity in Vietnamese and Indonesian cities feeds into Singapore-based delivery centers, concentrating advanced model development capacity in the city-state while fragmentating implementation staffing across emerging market banking sectors. Technology sourcing draws from India for software engineering, Singapore for regulatory expertise, and Malaysia for multilingual customer support. Raw material dependencies center on GPU compute clusters, proprietary credit bureau data feeds, and telecommunications metadata streams. Single-source vulnerability concentrates in federated learning framework licensing. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Southeast Asia's credit and risk management market stems from cloud infrastructure cost curves declining faster than subscription pricing, enabling vendors to capture wider spreads on real-time scoring deployments.
For Market Incumbents: Extend sovereign risk database moats into alternative data partnerships before Experian plc and cloud-native entrants consolidate telco and e-commerce relationships. Defensive consolidation moves center on acquiring Vietnamese and Indonesian implementation specialists to address quantitative talent scarcity. Capacity addition in Jakarta and Ho Chi Minh City service centers counters Singaporean fintech poaching of local data scientists. For New Entrants and Emerging Players: Capture Philippines rural banking cooperative networks where Bangko Sentral ng Pilipinas compliance mandates outpace incumbent vendor service capacity. White-space targets include satellite-enabled field verification tools for Indonesia's archipelago dispersion and climate risk stress testing modules for Vietnamese agricultural portfolios. Go-to-market execution through Thai systems integrators with existing Bank of Thailand relationships accelerates embedded finance penetration. For Investors and Strategic Acquirers: Consolidation pressure builds where quantitative talent scarcity intersects with regulatory compliance window tightening. Long-term viability favors vendors with federated learning intellectual property and established ASEAN Banking Integration Framework advisory relationships. Acquisition target archetypes include cloud-native scoring specialists with OJK or State Bank of Vietnam deployment credentials. Watch central bank circular velocity in Philippines and Thailand as inflection indicator for procurement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Consortium Formation | Enables Indonesian digital lenders to train models without centralizing borrower data across 17,000 islands. |
| Alternative Data Partnership Expansion | Experian plc extends telco and ride-hailing relationships into Vietnam's thin-file borrower segments. |
| Real-Time Fraud Monitoring Deployment | Philippines e-money issuers replace batch reconciliation to meet Bangko Sentral ng Pilipinas circular requirements. |
| Climate Risk Stress Testing Advisory | Agricultural lending portfolios in Vietnam face new ASEAN Banking Integration Framework exposure quantification guidelines. |
| White-Label Risk-as-a-Service Launch | Thai ride-hailing and e-commerce platforms integrate credit underwriting into checkout flows via API modules. |
Research Methodology
Coverage spans Indonesia, Thailand, Vietnam, Singapore, and the Philippines, with primary inputs from each market's banking procurement committees and technology vendor regional headquarters. The analysis combines structured interviews with chief risk officers, digital lending platform heads, regulatory compliance leads, and quantitative model development directors alongside secondary validation through Bank Negara Malaysia circulars, Monetary Authority of Singapore guidance papers, OJK licensing databases, and ASEAN Banking Integration Framework documentation. Bottom-up deployment counts across tier-1, tier-2, and rural cooperative institutions triangulate against top-down technology spending estimates from central bank statistical releases.
Rate-of-change decomposition separates volume effects from pricing effects across the analysis window, with CAGRs derived from segment-level adoption curves and infrastructure investment pipelines. The analytical framework models service type, technology architecture, end-user vertical, and delivery model dimensions alongside regulatory compliance urgency as an industry-specific overlay. Forecast inputs incorporate cloud migration timelines, credit bureau coverage expansion rates, and central bank circular implementation deadlines without year-specific anchoring.
Underlying measurement precision varies by segment; SaaS deployment counts carry tighter precision than on-premise installation estimates given vendor disclosure practices. Forecasts reflect assumptions around regulatory harmonization pace, cloud infrastructure cost trajectories, and quantitative talent pool expansion that could shift materially. Material deviation in Philippines central bank enforcement intensity or Indonesia OJK bureau licensing velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
United States Strategic Consulting Services Market
Risk Management and Compliance
Third Party Risk Management Market
Risk Management and Compliance
Global Patient Safety and Risk Management Softwares Market
Risk Management and Compliance
Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
Revenue Assurance Market
Risk Management and Compliance
Europe Strategy Consulting Market
Risk Management and Compliance
Regtech Market
Risk Management and Compliance
AI in Fraud Management Market
Risk Management and Compliance
BFSI Crisis Management Market
Risk Management and Compliance
Certificates Market
Risk Management and Compliance
Cyber Security in BFSI Market
Risk Management and Compliance
Global Financial Crime and Fraud Management Solutions Market
Risk Management and Compliance
Healthcare Safety and Risk Management Solutions Market
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
Global Compliance Management Software Market