
 Governance, Risk and Compliance Platform Market | 2026-2036
Governance, Risk and Compliance Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Governance, Risk and Compliance Platform Market Intelligence
GDPR enforcement is consolidating the vendor landscape by raising compliance infrastructure costs beyond the reach of fragmented point-solution providers. IBM leverages its Watson AI layer to automate risk scoring across multinational data estates. SAP anchors its GRC portfolio inside the S/4HANA ecosystem, creating captive demand among existing ERP customers. Oracle competes through database-level governance hooks that embed policy controls directly into data infrastructure.
A governance, risk and compliance platform is an integrated software architecture that unifies policy management, risk quantification, audit trails, and regulatory reporting through configurable workflow engines, role-based access matrices, and real-time control monitoring dashboards. Its primary commercial purpose is to reduce regulatory penalty exposure while compressing the cycle time from control failure detection to remediation. Cloud-based solutions now dominate new deployments as financial services and government end users abandon capital-intensive on-premises maintenance. The compliance area dimension shows data protection modules commanding premium pricing due to cross-border data transfer complexity, while environmental standards tracking represents the fastest-growing segment as CSRD-aligned disclosure obligations proliferate across European supply chains.
The SEC's climate disclosure rules, the EU's CSRD reporting framework, and the UK Financial Conduct Authority's operational resilience requirements are collectively mandating auditable control environments with sub-second telemetry. These frameworks reshape product roadmaps by requiring API-first architectures that can ingest regulatory updates without custom engineering. Stakeholders must evaluate whether their current platforms can absorb emerging AI governance obligations without wholesale replacement.
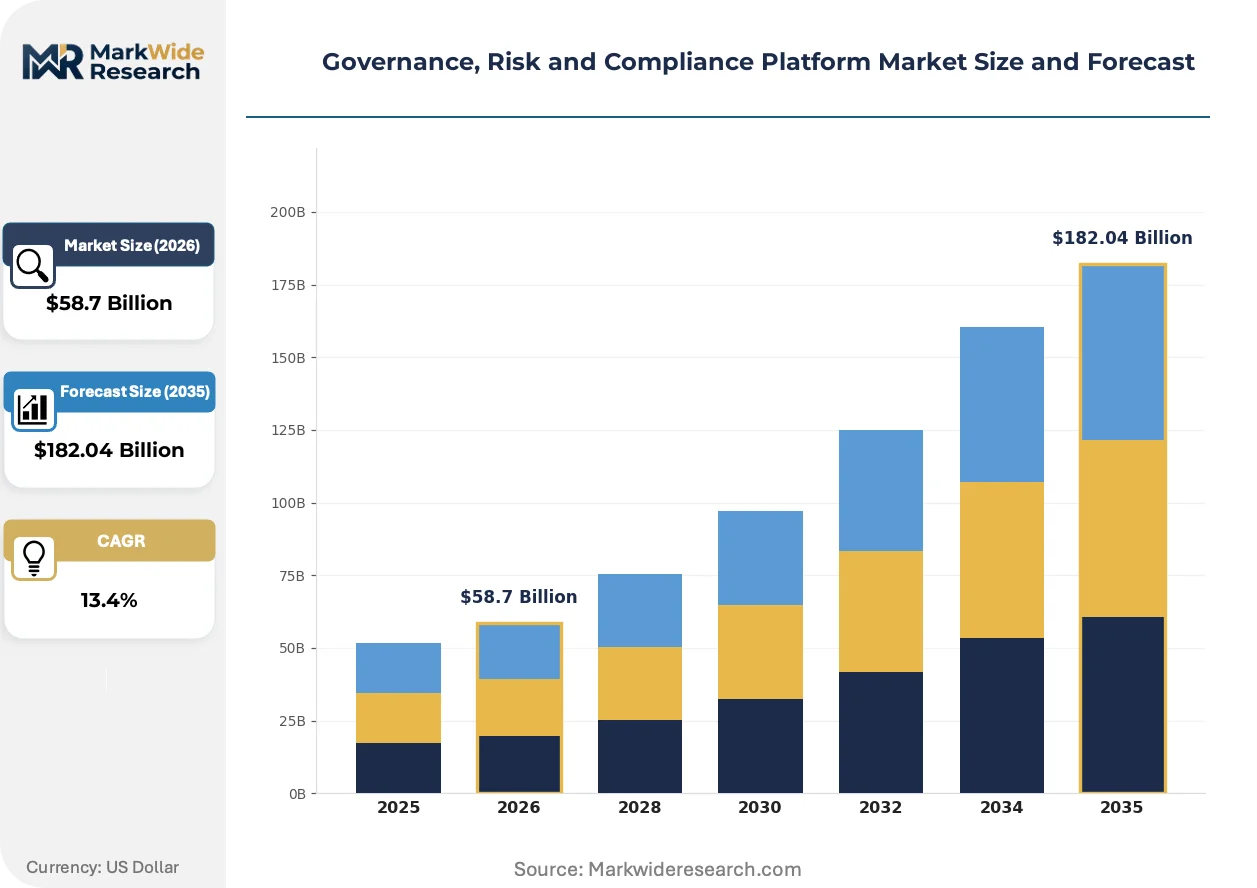
Market Dynamics
The EU AI Act and CSRD disclosure mandates are compressing procurement cycles as financial institutions abandon fragmented point solutions for unified governance architectures. This regulatory convergence is redrawing competitive boundaries between incumbent ERP vendors and specialized compliance software providers.
Growth Catalysts
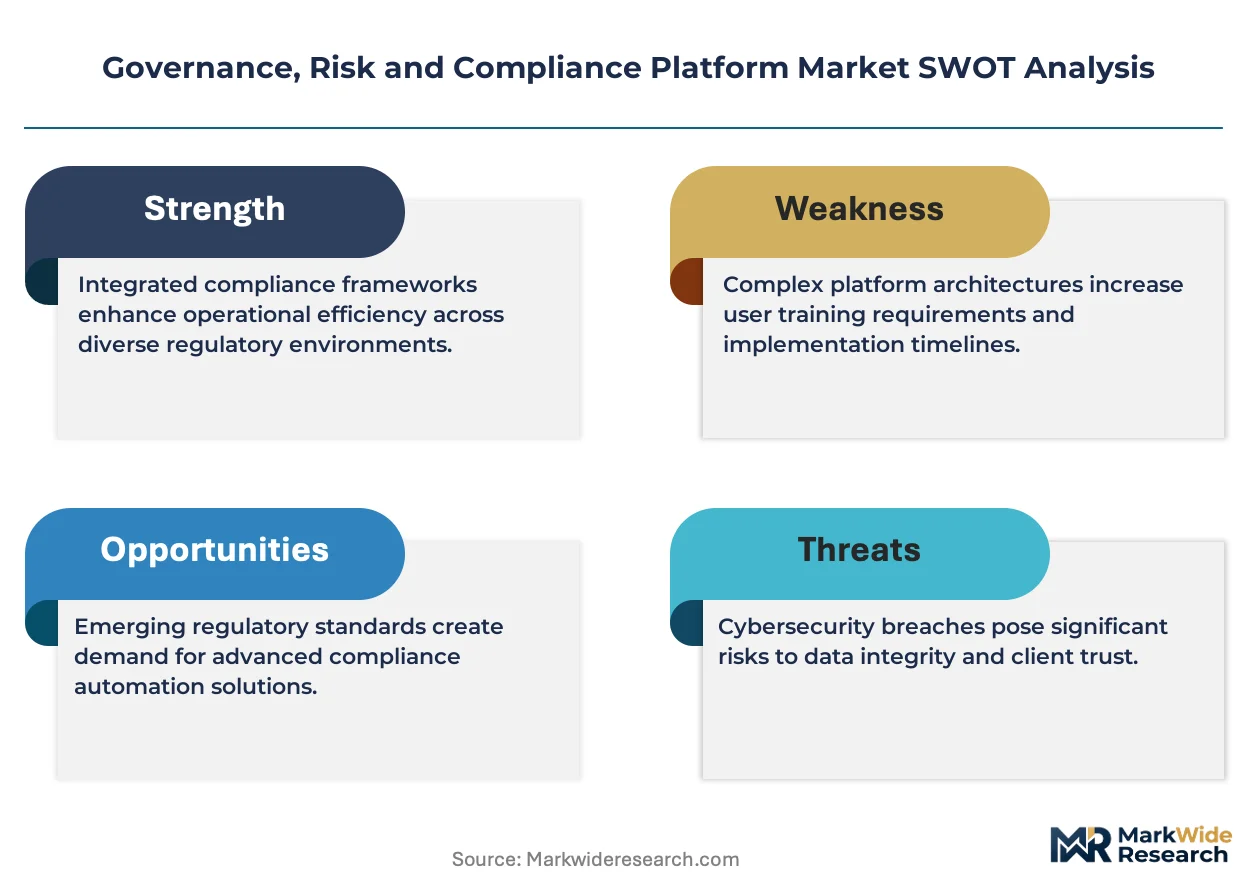
- CSRD-aligned ESG tracking:European supply chains now require auditable carbon accounting modules, pulling manufacturers into integrated platform contracts.
- US federal cybersecurity rules:Defense contractors and critical infrastructure operators face mandatory supply chain attestation, driving demand for real-time control monitoring.
- API-first architecture migration:Cloud-native ingestion frameworks allow banks to absorb regulatory updates without engineering sprints, shortening implementation timelines.
Market Restraints
- Concentrated cloud infrastructure:Three hyperscalers dominate hosting for GRC workloads, creating single-point-of-failure exposure for regulated entities.
- Legacy system entrenchment:Mainframe-based risk engines at Tier-1 banks resist API integration, trapping data in siloed repositories.
- Specialized talent scarcity:The intersection of regulatory expertise and cloud engineering commands compensation premiums that mid-market vendors cannot sustain.
Strategic Opportunities
- AI governance white space:Algorithmic impact assessment modules remain undersupplied as EU AI Act enforcement deadlines approach.
- Operational resilience mandates:UK Financial Conduct Authority requirements for sub-second telemetry create captive demand among London-headquartered insurers.
- Embedded finance compliance:Fintech-BaaS partnerships need lightweight governance layers that traditional suites cannot provide.
Industry Challenges
- Cross-border data localization:Conflicting sovereignty requirements between GDPR, China's PIPL, and US CLOUD Act fragment platform architectures.
- Skills mismatch in audit functions:Traditional compliance officers lack training in continuous control monitoring dashboards, slowing adoption curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Governance, Risk and Compliance Platform Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $182.04 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-Based, On-Premises, Hybrid, Open Source End User: Large Enterprises, SMEs, Government, Financial Services Deployment Model: Public Cloud, Private Cloud, Community Cloud, Multi-Cloud Compliance Area: Data Protection, Financial Regulations, Environmental Standards, Workplace Safety |
| Companies Covered | IBM, SAP, Oracle, MetricStream, Microsoft, Riskonnect, Archer, LogicManager, AuditBoard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Governance, Risk and Compliance Platform Market Strategic Shifts & Innovations
Distributed ledger architectures and zero-trust security models are converging with regulatory technology stacks, creating new product categories that bypass centralized data aggregation. This shift favors vendors with modular, API-centric roadmaps over monolithic suite providers.
Blockchain-based audit trails are decentralizing evidence storage for financial services compliance, eliminating single-source document repositories. Tier-1 banks in Singapore and Switzerland are piloting immutable transaction logs for cross-border payment attestation. This architecture compresses reconciliation cycles from weeks to hours while satisfying multi-jurisdictional examiner demands.
The EU AI Act's risk classification framework is forcing platform vendors to embed algorithmic governance modules directly into workflow engines. High-risk AI deployments in credit scoring and insurance underwriting now require auditable bias detection. German automotive lenders and French health insurers are restructuring procurement specifications around these mandatory control points.
Subscription fatigue among mid-market buyers is fragmenting purchasing authority away from centralized IT procurement. Divisional risk officers now directly contract specialized modules for ESG tracking or third-party risk monitoring. This pattern is most pronounced in US regional banks and UK mutual insurers, where shadow IT spending on compliance tools has doubled.
Governance, Risk and Compliance Platform Market Segmentation
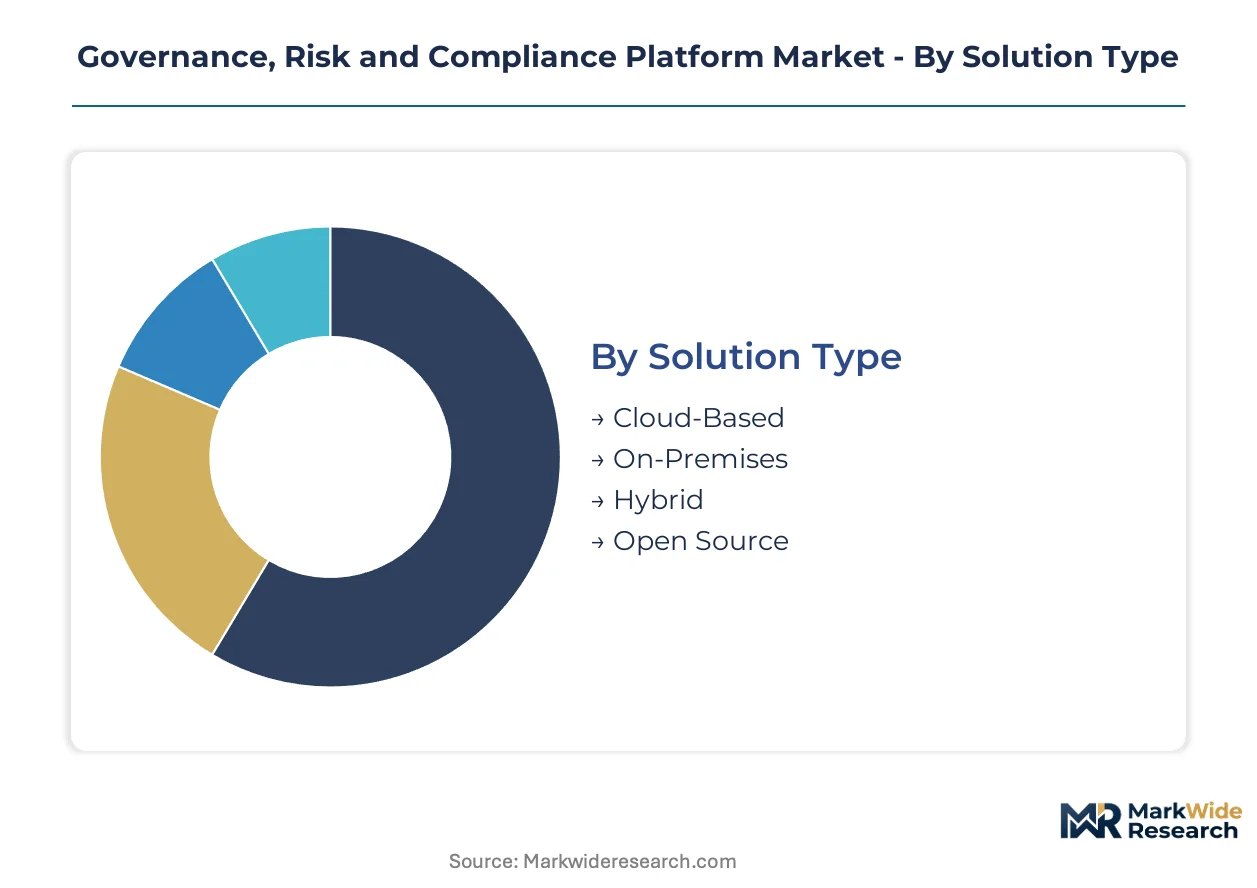
Segmentation in the Governance, Risk and Compliance Platform Market reveals how procurement authority splits between centralized IT and divisional risk officers. Deployment preferences diverge sharply between regulated financial institutions requiring sovereign data control and mid-market buyers prioritizing operational agility over customization depth.
Solution Type:
Deployment economics separate buyers into capital-intensive operators versus subscription-oriented adopters seeking faster implementation cycles.
- Cloud-Based:Multi-tenant architectures with automatic patch management dominate new procurement at financial services firms abandoning data center maintenance. European banks under CSRD deadlines favor these platforms for rapid ESG module deployment without infrastructure engineering.
- On-Premises:Dedicated hardware installations retain preference at defense contractors and critical infrastructure operators subject to US federal cybersecurity supply chain attestation rules. Sovereign data requirements in Germany and France sustain demand despite higher total cost of ownership.
- Hybrid:Split workloads placing sensitive risk data on-premises while routing analytics to cloud substrates.
- Open Source:Community-developed frameworks attracting mid-market manufacturers with internal engineering capacity.
Cloud-Based solutions lead volumes today; Hybrid deployments are gaining share fastest as tier-1 banks navigate conflicting data sovereignty mandates.
End User:
Organizational scale determines platform complexity requirements and integration depth with existing ERP ecosystems.
- Large Enterprises:Global implementations requiring multi-jurisdictional regulatory mapping and consolidated risk dashboards across subsidiary networks. These buyers command vendor roadmaps through direct engineering collaboration and multi-year framework agreements.
- SMEs:Modular subscriptions purchased by divisional risk officers outside centralized IT procurement, particularly pronounced at US regional banks and UK mutual insurers. Shadow IT spending on specialized compliance tools has doubled in this segment.
- Government:Sovereign cloud mandates and classified workload requirements driving specialized procurement vehicles.
- Financial Services:Integrated GRC suites replacing fragmented point solutions under EU AI Act and expanding ESG disclosure obligations.
Large Enterprises anchor current revenue; SMEs are expanding most quickly as subscription fatigue fragments purchasing authority.
Deployment Model:
Infrastructure control preferences reflect varying tolerance for shared tenancy and hyperscaler concentration risk.
- Public Cloud:Shared infrastructure delivering elastic compute for seasonal regulatory reporting spikes without capital commitment. Three hyperscalers dominate hosting, creating single-point-of-failure exposure that concerns regulated entities.
- Private Cloud:Dedicated single-tenant environments satisfying UK Financial Conduct Authority operational resilience requirements for sub-second telemetry isolation.
- Community Cloud:Sector-specific instances shared among non-competing peers in banking or insurance verticals.
- Multi-Cloud:Workload distribution across providers to mitigate vendor lock-in and satisfy divergent data localization rules.
Public Cloud installations dominate new deployments; Multi-Cloud strategies show the steepest expansion trajectory as cross-border data fragmentation intensifies.
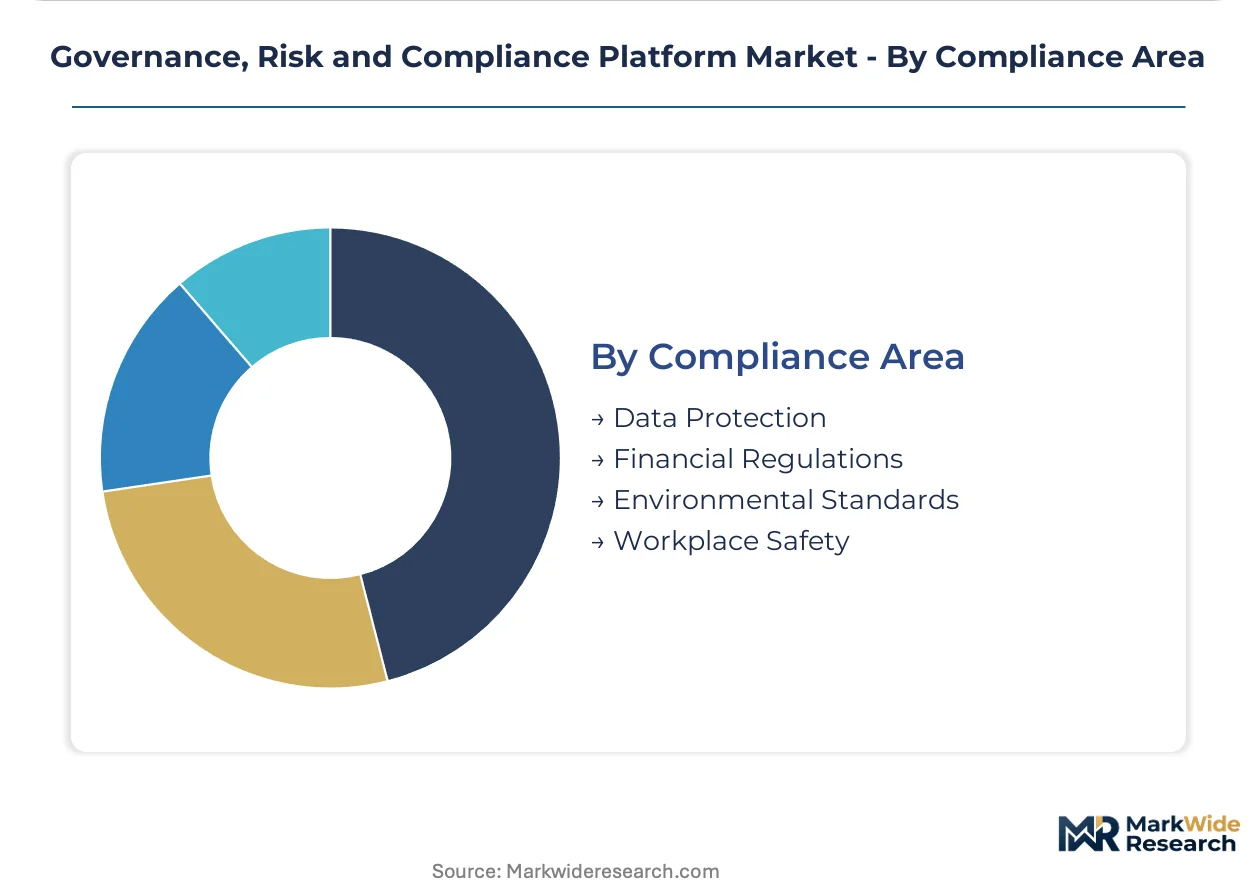
Compliance Area:
Regulatory scope breadth directly correlates with module pricing power and integration complexity requirements.
- Data Protection:Cross-border transfer mechanisms, consent management, and breach notification workflows commanding premium pricing due to GDPR enforcement complexity and conflicting US CLOUD Act obligations.
- Environmental Standards:Carbon accounting, supply chain disclosure, and CSRD-aligned reporting representing the fastest-growing segment as European manufacturers restructure procurement specifications around mandatory disclosure obligations.
- Financial Regulations:Capital adequacy, anti-money laundering, and securities reporting modules.
- Workplace Safety:Incident tracking, audit trails, and OSHA-aligned documentation systems.
Data Protection modules command the highest pricing; Environmental Standards tracking is climbing the fastest as disclosure mandates proliferate across supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory technologists and compliance engineers cluster in financial centers where disclosure mandates are tightest. Talent density in London, New York, Frankfurt, and Singapore determines platform development velocity and customer proximity.
United States
Defense contractors and critical infrastructure operators drive sovereign cloud deployments under federal cybersecurity supply chain attestation rules. The SEC's climate disclosure framework and HIPAA enforcement actions force healthcare and financial institutions toward real-time control monitoring. New York's financial district anchors demand for integrated GRC suites that consolidate fragmented point solutions.
Germany
Automotive lenders and industrial manufacturers restructure procurement around CSRD-aligned carbon accounting and EU AI Act algorithmic governance requirements. The Federal Financial Supervisory Authority (BaFin) operational resilience directives push insurers toward sub-second telemetry architectures. Frankfurt's banking cluster sustains captive demand for on-premises risk engines despite cloud migration pressure elsewhere.
United Kingdom
London-headquartered insurers face UK Financial Conduct Authority mandates for continuous control monitoring with sub-second isolation requirements. Shadow IT spending on specialized compliance modules has doubled among mutual insurers as divisional risk officers bypass centralized procurement. The City's regulatory technology workforce supports rapid deployment of API-first governance architectures.
France
Health insurers and credit scoring operators embed algorithmic bias detection modules under EU AI Act high-risk deployment classifications. The CNIL's GDPR enforcement actions raise compliance infrastructure costs beyond fragmented point-solution provider reach. Parisian financial services clusters demand multi-jurisdictional regulatory mapping for cross-border data transfer complexity.
Singapore
Tier-1 banks pilot blockchain-based audit trails for cross-border payment attestation under Monetary Authority of Singapore guidance. Immutable transaction logs compress reconciliation cycles while satisfying multi-jurisdictional examiner demands. The city-state's regulatory sandbox environment accelerates zero-trust security model integration with governance technology stacks.
Governance, Risk and Compliance Platform Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across procurement cycles compressed by regulatory convergence. ERP-anchored vendors leverage captive demand inside existing customer ecosystems while specialized compliance providers capture modular subscription contracts from divisional risk officers. Three strategic archetypes dominate: database infrastructure incumbents embedding policy controls at the data layer, cloud-native challengers offering API-first ingestion frameworks, and AI-augmented platforms automating risk scoring across multinational estates. Competitive moves concentrate on vertical integration into upstream data infrastructure and strategic partnerships with hyperscaler hosting providers.
Within the ERP-anchored tier, SAP and Oracle exemplify platform vendors capturing sustained demand through ecosystem lock-in. IBM occupies a position at the AI-augmented intersection, leveraging cognitive automation layers for cross-border risk quantification. These three conglomerates represent the consolidation pressure forcing specialized point-solution providers toward acquisition or exit.
| Leading Market Players |
|---|
| IBM |
| SAP |
| Oracle |
| MetricStream |
| Microsoft |
| Riskonnect |
| Archer |
| LogicManager |
| AuditBoard |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure costs cascade through GRC platform tiers as hyperscaler concentration concentrates pricing power among three dominant hosting providers, forcing mid-market vendors toward modular unbundling to preserve margins.
Pricing Analysis
Module unbundling versus suite bundling defines the pricing architecture across buyer segments. Three-tier pricing structure across premium, standard, and economy levels separates enterprise multi-tenant deployments from divisional SaaS subscriptions and open-source community editions. Price differentiation hinges on API integration depth and CSRD-aligned ESG module certification. Cost compression in the standard tier is intensifying because SME buyers fragment procurement authority away from centralized IT. Regional banks and UK mutual insurers exhibit highest price sensitivity; defense contractors accepting sovereign cloud mandates show lowest.
Supply Chain Analysis
Specialized compliance engineering talent supply rests on educational pipelines in Germany, the United Kingdom, and Singapore. Cloud compute substrates, cybersecurity middleware, and regulatory content feeds constitute critical input dependencies. Single-source vulnerability concentrates around hyperscaler hosting concentration for regulated workloads. Distribution runs through direct enterprise sales teams, hyperscaler marketplaces, and specialized compliance consultancies serving financial services verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GRC platform procurement has shifted toward late-cycle quality specifications as buyers prioritize API-first architectures capable of absorbing regulatory updates without engineering sprints.
For Market Incumbents: Anticipate margin compression from cloud-native challengers by embedding policy controls deeper into database infrastructure and securing captive demand through ERP ecosystem lock-in. Vertical integration into upstream data infrastructure addresses hyperscaler concentration risk. Certification investment in EU AI Act algorithmic governance modules defends position against specialized compliance pure-plays. For New Entrants and Emerging Players: Divisional risk officers at US regional banks represent the most penetrable buyer archetype, with shadow IT spending on specialized ESG and third-party risk modules doubling. Lightweight governance layers for fintech-BaaS partnerships offer white-space expansion. Go-to-market through compliance consultancies bypasses entrenched IT procurement gatekeepers. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented point-solution providers face GDPR and EU AI Act infrastructure cost barriers beyond their capital reach. Long-term viability favors vendors with modular API-centric roadmaps over monolithic suite architectures. Acquisition targets should demonstrate sub-second telemetry capabilities aligned with UK Financial Conduct Authority operational resilience mandates. The signal to watch is hyperscaler partnership depth as a proxy for distribution scalability.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Migration | Enables banks to ingest SEC climate disclosure updates without custom engineering sprints. |
| EU AI Act Module Certification | Positions vendors for mandatory algorithmic bias detection in French health insurer deployments. |
| Hyperscaler Partnership Deepening | Addresses single-point-of-failure exposure troubling US federal cybersecurity supply chain attestation. |
| Blockchain Audit Trail Integration | Compresses Singapore bank reconciliation cycles from weeks to hours under Monetary Authority guidance. |
| Operational Resilience Telemetry Buildout | Satisfies UK Financial Conduct Authority sub-second isolation requirements for London insurers. |
Research Approach
Direct dialogue with chief risk officers, compliance technology architects, regulatory affairs directors at financial institutions, and hyperscaler solution engineers grounded the qualitative foundation. Secondary validation drew from SEC enforcement actions, EU AI Act implementation guidance, UK Financial Conduct Authority consultation papers, and BaFin operational resilience circulars. Bottom-up deployment sizing across cloud, on-premises, and hybrid configurations triangulated against top-down vendor revenue analysis.
Segmentation outputs across deployment model, organization scale, compliance area specialization, and regional regulatory cluster density fed the analytical framework across the analysis window. CAGRs derived from regression against historical procurement velocity and regulatory deadline compression. Model inputs included CSRD-aligned disclosure obligation timelines and US federal cybersecurity supply chain attestation rule adoption curves.
Inputs from regulatory filing databases and vendor financial disclosures were available through the study window; gaps in private mid-market vendor transaction data introduce uncertainty bands around SME segment sizing. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and cloud migration velocity. Regulatory deadline delays, hyperscaler service disruptions, and cross-border data localization conflicts warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Regtech Market
Risk Management and Compliance
Disclosure Management Market
Risk Management and Compliance
Europe Sustainable Finance Market
Risk Management and Compliance
Southeast Asia Credit and Risk Management Market
Risk Management and Compliance
Artificial Intelligence and Regtech Market
Risk Management and Compliance
Pre Trade Risk Management Solution Market
Risk Management and Compliance
North America BFSI Biometrics Market
Risk Management and Compliance
Surety Market
Risk Management and Compliance
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Risk Assessment Software Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Travel Risk Management Services Market
Risk Management and Compliance
Oil and Gas Risk Management Market
Risk Management and Compliance
Crypto Compliance Software Market
Risk Management and Compliance
Treasury and Risk Management Application Market