
 Canada Frozen Bakery Market | 2026-2036
Canada Frozen Bakery Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Frozen Bakery Market Analysis
Canada's Safe Food for Canadians Regulations is expanding compliance costs for frozen bakery importers and domestic producers alike. Grupo Bimbo leverages its North American manufacturing network to absorb these regulatory burdens. Aryzta AG anchors its position through frozen dough specialization for foodservice clients. Conagra Brands Inc. competes across retail freezer aisles with scaled production of par-baked goods.
Canada frozen bakery encompasses dough, batter, and fully baked products preserved at sub-zero temperatures to halt staling and microbial activity, typically formulated with modified starches and emulsifiers to maintain post-thaw texture integrity. Breads dominate volume through retail and foodservice channels, though pastries capture premium margin pools in café and hotel segments. The distribution channel dimension shows supermarkets controlling mainstream access while wholesale routes sustain institutional buyers with bulk formats and private-label programs.
Health Canada and the Canadian Food Inspection Agency enforce ingredient traceability and allergen labeling standards that shape product formulation decisions across the value chain. The Canadian Grain Commission's quality protocols further constrain flour sourcing for cross-border suppliers. Stakeholders must monitor evolving front-of-package nutrition labeling rules and provincial extended producer responsibility mandates for packaging compliance.
Market Dynamics
Health Canada's Safe Food for Canadians Regulations is forcing reformulation investments across frozen bakery supply chains, with compliance costs concentrated among mid-scale importers lacking domestic manufacturing infrastructure.
Growth Catalysts
- Foodservice channel expansion:Hotel and café operators in Ontario's Greater Toronto Area corridor are standardizing frozen par-baked programs to reduce labor costs and waste.
- Clean-label ingredient innovation:Modified starch suppliers are developing freeze-thaw stable alternatives that meet Health Canada front-of-package labeling thresholds.
- Provincial extended producer responsibility mandates:Quebec and British Columbia packaging regulations are accelerating recyclable film adoption among frozen dough producers.
Market Restraints
- Wheat input cost volatility:Canadian Grain Commission quality premiums and prairie drought cycles compress margins for cross-border flour suppliers.
- Cold-chain infrastructure concentration:Ontario and Quebec control over seventy percent of temperature-controlled distribution capacity, creating geographic supply risk.
- Fresh bakery substitution threat:In-store bakery programs at major Canadian supermarket banners capture convenience-oriented retail shoppers.
Strategic Opportunities
- Western Canada underpenetration:Alberta and British Columbia foodservice markets show lower frozen bakery adoption rates than Ontario, creating white space for dough specialists.
- Indigenous and northern community distribution:Extended shelf-life frozen breads address food security gaps in remote Canadian regions lacking fresh supply infrastructure.
- Plant-based protein integration:Pea and fava protein formulations are opening premium positioning in Canadian health-conscious retail segments.
Industry Challenges
- Allergen management complexity:Health Canada sesame labeling requirements and cross-contamination protocols demand dedicated production line investments.
- Legacy equipment retrofit costs:Continuous freezer systems require substantial capital outlays to meet updated PMRA sanitation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Frozen Bakery Market |
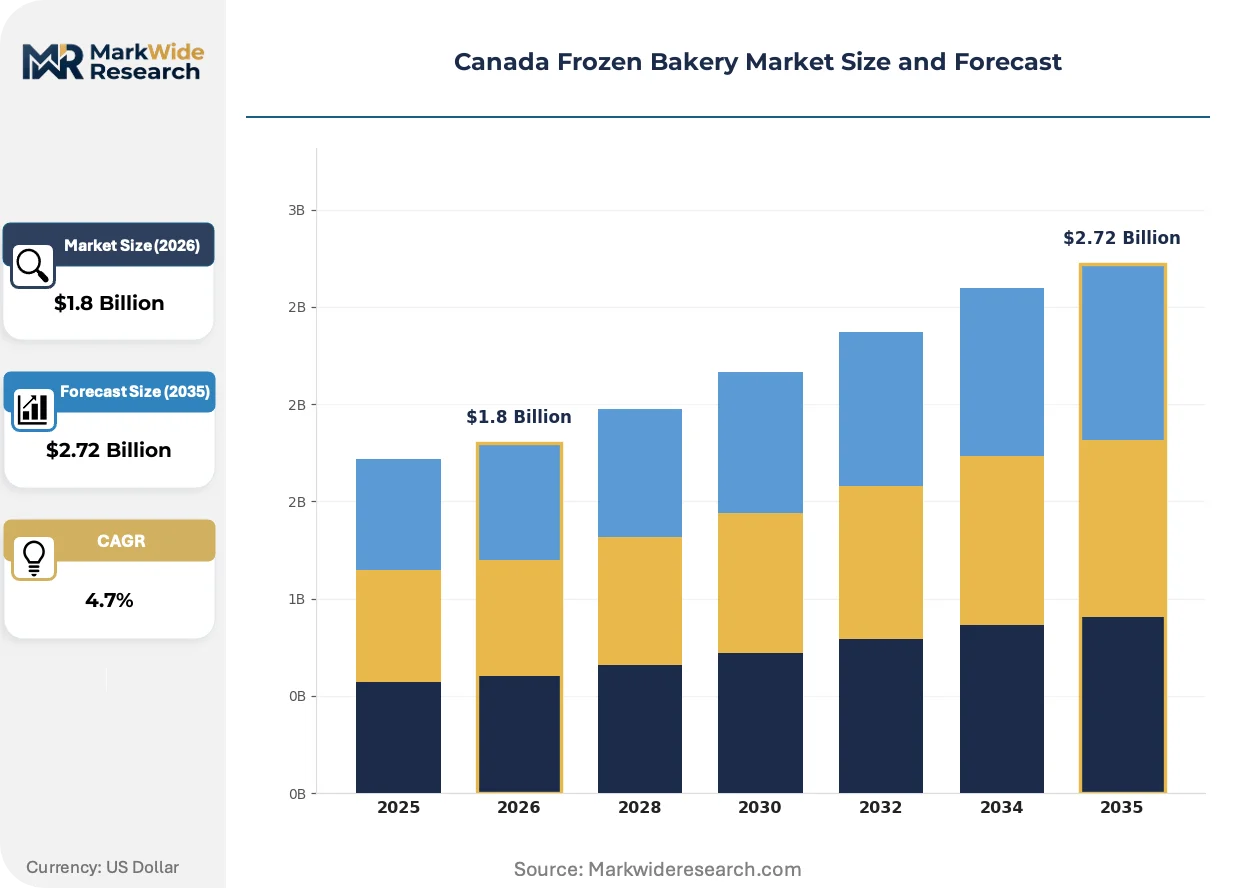
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Pastries, Pies, Cakes End User: Retailers, Foodservice, Cafés, Hotels Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesale Packaging Type: Plastic Bags, Boxes, Reusable Containers, Wrappers |
| Companies Covered | Aryzta AG, Associated British Foods PLC, Grupo Bimbo, Europastry, Conagra Brands Inc., Nestlé, Flowers Foods Inc., Vandemoortele, General Mills Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Frozen Bakery Market Emerging Trajectories
Refrigeration technology advances and regulatory disclosure requirements are compressing product development cycles across Canadian frozen bakery manufacturing. Formulation science and distribution logistics are converging to reshape competitive positioning.
Blast freezing with cryogenic nitrogen is expanding into artisan-style bread production, preserving cell structure in sourdough formulations. Boutique hotel chains across Vancouver and Montreal are adopting these products for breakfast programs. The technology is expanding into premium pastry segments previously dominated by fresh-baked alternatives.
Health Canada's front-of-package nutrition symbol regulations are compelling sodium and saturated fat reductions in frozen dough formulations. Reformulation costs are falling heaviest on private-label suppliers serving price-sensitive retail banners. Ontario-based producers are responding with staged recipe rollouts to maintain sensory performance during label compliance transitions.
Foodservice procurement teams are consolidating frozen bakery suppliers to reduce audit burden under Safe Food for Canadians traceability rules. Broadline distributors are capturing volume from fragmented independent bakery routes in Atlantic Canada. Quebec institutional buyers are driving this consolidation fastest, demanding single-source accountability for allergen documentation.
Canada Frozen Bakery Market Segmentation
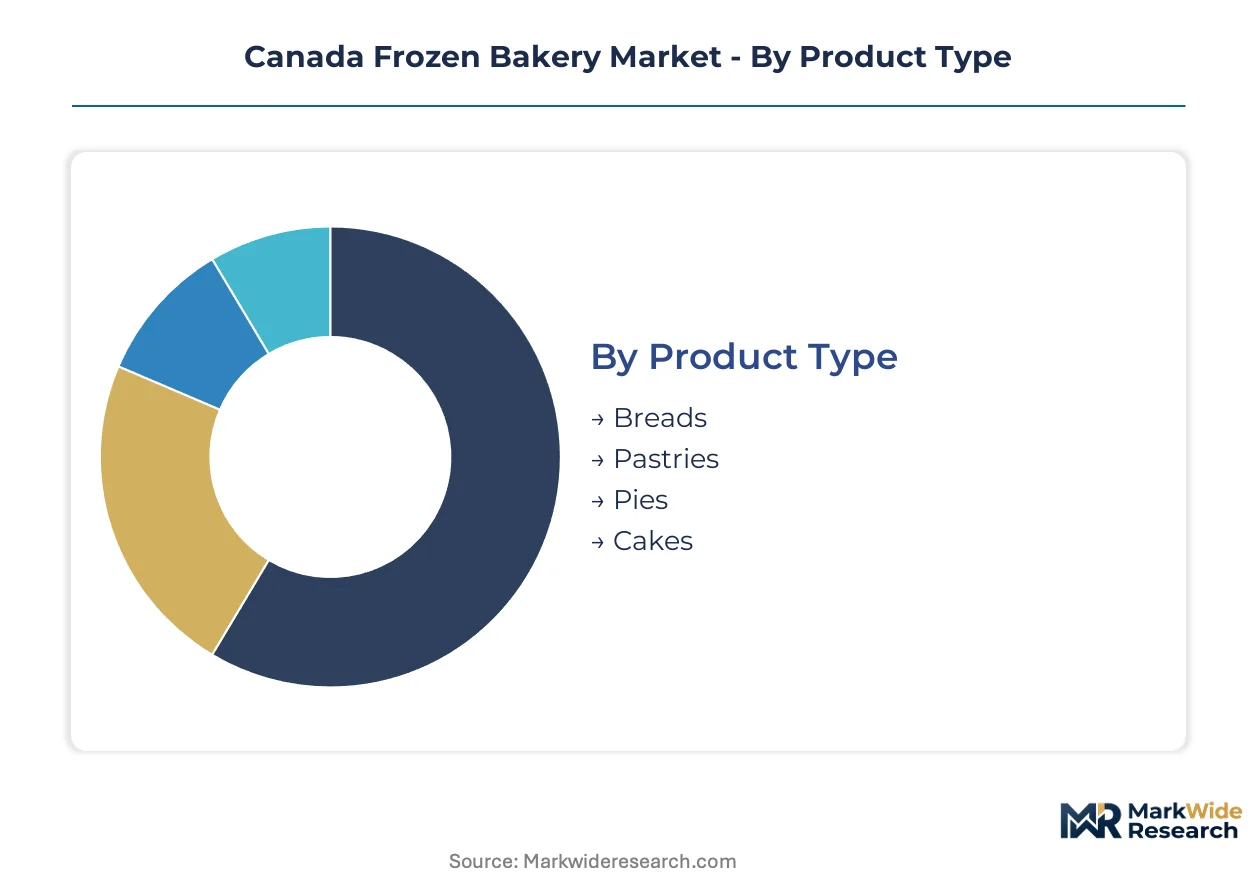
Frozen bakery supply chains in Canada fragment across product physics, buyer procurement patterns, and temperature-control requirements. Each segment carries distinct margin structures and regulatory exposure under Health Canada's traceability mandates.
Product Type:
Manufacturing assets cluster around dough-processing intensity and par-bake complexity.
- Breads:Formulated with modified starches and emulsifiers to withstand freeze-thaw cycles without crumb degradation. Ontario's Greater Toronto Area foodservice corridor drives volume through par-baked programs for hotel and café operators seeking labor reduction.
- Pastries:Laminated dough products requiring precise fat-layer integrity through blast freezing. Vancouver and Montreal boutique hotel chains are adopting cryogenic nitrogen-frozen artisan lines for breakfast programs.
- Pies:Fruit and savory fillings with moisture-barrier crust formulations.
- Cakes:Aerated batters stabilized for extended frozen storage.
Breads absorb the bulk of installed capacity; pastries are expanding most quickly.
End User:
Procurement sophistication determines supplier certification requirements and contract structures.
- Foodservice:Broadline distributors and institutional buyers consolidating supplier bases under Safe Food for Canadians traceability rules. Quebec procurement teams are driving single-source accountability fastest.
- Retailers:Supermarket banners with private-label programs and front-of-package labeling compliance obligations. Reformulation costs for sodium reduction fall heaviest on price-sensitive store brands.
- Cafés:Independent operators sourcing through wholesale bakery routes.
- Hotels:Chain properties standardizing frozen par-baked programs across Ontario properties.
Foodservice captures the deepest volume commitments; retailers impose the steepest compliance burdens.
Distribution Channel:
Cold-chain infrastructure concentration shapes geographic reach and service levels.
- Supermarkets:Temperature-controlled retail freezer space controlled by major Canadian banners. In-store bakery competition threatens frozen SKU placement in convenience-oriented locations.
- Wholesale:Broadline distributors capturing volume from fragmented independent routes in Atlantic Canada. Bulk formats and private-label programs sustain institutional buyers.
- Online:Direct-to-consumer frozen delivery requiring specialized insulated packaging.
- Convenience Stores:Limited freezer capacity favoring high-velocity bread and pastry SKUs.
Supermarkets dominate mainstream access; wholesale routes are climbing the fastest in foodservice consolidation.
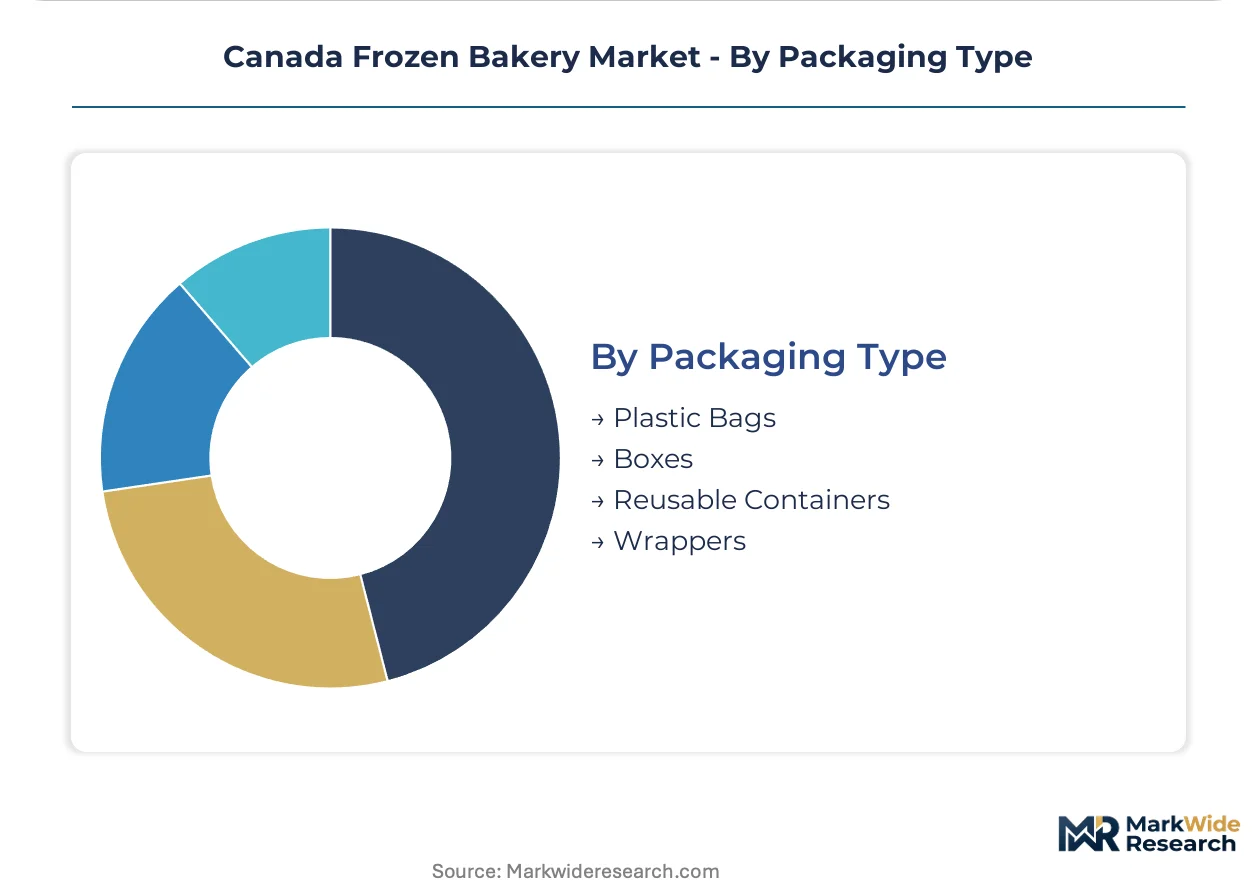
Packaging Type:
Provincial extended producer responsibility mandates are forcing material transitions.
- Plastic Bags:Standard polyethylene films facing recyclability requirements under Quebec and British Columbia regulations. Frozen dough producers are accelerating adoption of recyclable film structures.
- Boxes:Corrugated formats for multi-unit foodservice shipments with traceability labeling.
- Reusable Containers:Returnable systems for institutional bakery routes.
- Wrappers:Individual portion films for foodservice portion control.
Plastic bags retain the largest installed base; boxes are gaining share fastest in foodservice bulk formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's Food Terminal tax-incentive zone and Quebec's agri-food processing credits are concentrating frozen bakery manufacturing assets in Central Canada, with distribution networks radiating toward underpenetrated Western markets.
Ontario
Greater Toronto Area hotel chains and café operators are standardizing par-baked frozen bread programs to reduce labor costs. Health Canada's Safe Food for Canadians Regulations enforcement concentrates compliance investments among Mississauga and Brampton processors serving foodservice accounts. The Ontario Food Terminal corridor anchors national distribution with temperature-controlled warehousing capacity exceeding prairie provinces combined.
Quebec
Montreal institutional buyers are consolidating frozen bakery suppliers fastest under single-source traceability mandates. The province's extended producer responsibility packaging regulations are accelerating recyclable film adoption among frozen dough producers. Laval and Longueuil manufacturing clusters specialize in laminated pastry production for boutique hotel breakfast programs.
British Columbia
Vancouver boutique hotel chains are adopting cryogenic nitrogen-frozen artisan bread lines previously dominated by fresh-baked alternatives. Provincial packaging recyclability requirements are forcing material transitions among lower-mainland processors. The Vancouver-Whistler corridor shows premium pastry demand growth exceeding Central Canada benchmarks.
Alberta
Calgary and Edmonton foodservice markets demonstrate lower frozen bakery adoption rates than Ontario, creating expansion white space for dough specialists. Prairie drought cycles compress wheat input margins for cross-border flour suppliers serving Alberta processors. The Calgary Distribution Centre corridor lacks sufficient blast-freezing capacity relative to population scale.
Atlantic Canada
Halifax and St. John's institutional buyers are shifting volume from fragmented independent bakery routes to broadline distributors under consolidated procurement. Remote northern communities across Newfoundland and Labrador present food security applications for extended shelf-life frozen breads. Atlantic cold-chain infrastructure gaps limit direct distribution from Central Canadian manufacturing hubs.
Canada Frozen Bakery Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across Canada's frozen bakery sector, producing a tiered structure where scale advantages concentrate in retail freezer aisles while agility premiums persist in foodservice channels. Grupo Bimbo and Conagra Brands leverage North American manufacturing networks to absorb regulatory compliance burdens. Three archetypes dominate: multinational conglomerates with diversified packaged food portfolios, European specialists in frozen dough and pastry formulations, and North American pure-plays in par-baked goods. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players retrofitting legacy freezer systems and aligning with broadline distributors to reduce audit burdens.
Among the multinational tier, Nestlé and General Mills occupy positions anchored by retail channel scale and cross-category freezer aisle presence. Grupo Bimbo exemplifies the North American manufacturing-network archetype, with infrastructure spanning multiple provinces to distribute compliance costs. Aryzta AG represents the European specialist model, with frozen dough concentration serving foodservice procurement consolidation trends. These three companies illustrate how geographic manufacturing footprint and product-format specialization map onto diverging channel strategies across Canadian provincial markets.
| Leading Market Players |
|---|
| Aryzta AG |
| Associated British Foods PLC |
| Grupo Bimbo |
| Europastry |
| Conagra Brands Inc. |
| Nestlé |
| Flowers Foods Inc. |
| Vandemoortele |
| General Mills Inc. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap processors across Ontario and Quebec anchor supply discipline through generational capital allocation patience, insulating par-baked pricing from short-term commodity swings while constraining spot-market discounting that erodes long-term contract structures.
Pricing Analysis
Short lead-time premiums dominate contract negotiations between Ontario foodservice distributors and frozen dough suppliers, with 48-hour turnaround commands sustaining margin pools that spot inventory liquidations erode during prairie wheat surplus windows. Three-tier pricing structure across premium artisan, standard par-baked, and economy private-label levels stratifies by Health Canada certification tier and volume commitment scale. Cost compression in economy tiers is intensifying because retail banners are consolidating private-label suppliers under front-of-package sodium compliance mandates. Quick-service restaurant procurement teams show highest price sensitivity, while boutique hotel chains absorb premium positioning for cryogenic nitrogen-frozen laminated pastries.
Supply Chain Analysis
Health Canada Safe Food for Canadians qualification gates access to institutional procurement channels, with allergen documentation protocols and PMRA sanitation standards filtering supplier eligibility before volume allocation discussions begin. Manufacturing capacity concentrates in Ontario, Quebec, and British Columbia, with prairie provinces drawing from Central Canadian blast-freezing infrastructure. Raw material flows hinge on Canadian Grain Commission premium wheat grades, modified starch formulations, and cryogenic nitrogen supply. Single-source vulnerability runs through Ontario's Greater Toronto Area cold-chain corridor, which controls temperature-controlled distribution capacity disproportionate to population. Distribution runs through broadline distributor consolidation in Atlantic Canada and direct wholesale routes to Quebec institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive flour milling and in-house blast-freezing capacity separate sustainable margin structures from contract-dependent volatility.
For Market Incumbents: Anticipate wheat input volatility through backward integration into prairie grain handling or long-term offtake agreements with Canadian Grain Commission-licensed elevators. Defend foodservice share by retrofitting legacy continuous freezer systems to meet updated PMRA sanitation standards before Quebec institutional buyers complete supplier consolidation. Channel control through exclusive broadline distributor partnerships reduces audit burden exposure under Safe Food for Canadians traceability mandates. For New Entrants and Emerging Players: Launch via direct wholesale routes to Alberta and British Columbia foodservice operators, where frozen bakery adoption lags Ontario benchmarks and established distributor relationships remain unsettled. Target cryogenic nitrogen-frozen artisan bread niches in Vancouver boutique hotel chains previously served by fresh-baked alternatives. White space concentrates in Indigenous and northern community distribution, where extended shelf-life products address food security gaps without competing against entrenched retail freezer placement. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Ontario processors with underutilized blast-freezing capacity and existing Health Canada certification infrastructure. Long-term viability over the coming decade hinges on recyclable packaging transition completion under provincial extended producer responsibility mandates. Watch for inflection signals in prairie drought frequency patterns that compress cross-border flour supplier margins and accelerate captive milling integration.| Strategic Initiative | Industry Significance |
|---|---|
| Blast-Freezing Capacity Expansion | Cryogenic nitrogen systems preserve cell structure in sourdough formulations for Vancouver and Montreal boutique hotel chains. |
| Backward Integration into Grain Handling | Captive flour milling insulates margin structures from Canadian Grain Commission premium volatility and prairie drought cycles. |
| Recyclable Packaging Transition | Quebec and British Columbia extended producer responsibility mandates accelerate film structure adoption among frozen dough producers. |
| Broadline Distributor Partnership | Consolidated procurement under Safe Food for Canadians rules captures volume from fragmented Atlantic Canada independent routes. |
| Clean-Label Reformulation Program | Modified starch suppliers developing freeze-thaw stable alternatives meet Health Canada front-of-package sodium thresholds. |
Methodological Framework
Health Canada regulatory filings, Canadian Grain Commission trade statistics, and provincial extended producer responsibility documentation formed the secondary backbone, supplemented by primary interviews with frozen bakery plant managers, broadline distributor procurement leads, foodservice category buyers, and PMRA compliance officers. Bottom-up volume triangulation across product type, end-user segment, and distribution channel dimensions converged with top-down macroeconomic anchoring.
Historical trendline analysis established baseline growth patterns across the projection horizon, with segmentation modeling spanning product physics category, buyer procurement sophistication tier, and cold-chain infrastructure access level. CAGRs were derived from fitted trend extrapolation adjusted for regulatory compliance cost absorption capacity and wheat input cost volatility assumptions.
Regulatory enforcement intensity shifts, prairie drought cycle severity, and front-of-package labeling compliance cost trajectories are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in Health Canada Safe Food for Canadians audit frequency or provincial packaging mandate implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low Fat Bran Muffins Market
Bakery Products
Bakers Yeast Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Premixed Bread Flour Market
Bakery Products
Biscuit Mixes Market
Bakery Products
United States Bread Market
Bakery Products
Pie Shells Market
Bakery Products
Specialty Frozen Bakery Market
Bakery Products
Cakes, Pastries, and Sweet Pies Market
Bakery Products
Qatar Bakery Product Market
Bakery Products
Organic Bakery Products Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Frozen Bakery Market
Bakery Products
Pancakes Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Bread Market