
 Low Fat Muffin Market | 2026-2036
Low Fat Muffin Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Muffin Market Analytics
Convenience breakfast demand is hardening across retail channels as time-pressed consumers seek portable, better-for-you options. McKee Foods Corporation leverages its frozen bakery infrastructure to dominate mass-market distribution. Flowers Foods sustains regional brand strength through deep supermarket relationships. Grupo Bimbo anchors its position via global manufacturing scale and cross-border logistics networks.
Low fat muffins are baked goods formulated with reduced fat content, typically substituting applesauce, yogurt, or fruit purees for conventional oils and butter, yielding products with under three grams of fat per serving while maintaining moisture and structural integrity. Their primary commercial purpose centers on satisfying health-claim-eligible demand in retail and foodservice channels. Blueberry and bran varieties lead volume, with chocolate chip segments capturing premium price points through indulgence-positioned formulations. Gluten-free ingredient types represent the fastest-growing margin pool as co-manufacturers expand dedicated allergen-free lines.
FDA nutrition labeling requirements and USDA dietary guideline revisions shape product formulation standards and front-of-pack claim eligibility across the United States. State-level sugar and calorie disclosure mandates in California and New York add compliance layers for multi-regional distributors. Stakeholders must monitor evolving clean-label ingredient specifications and dual-certification pathways that bridge conventional health positioning with emerging free-from demand.
Market Dynamics
Supermarket private-label expansion is compressing branded shelf space while co-manufacturers scramble to certify dual health-and-allergen-free production lines. This structural squeeze forces mid-tier bakeries to choose between margin sacrifice and volume exit.
Growth Catalysts
- FDA front-of-pack labeling:The FDA's updated nutrition disclosure rules grant health-claim eligibility to sub-three-gram fat formulations, unlocking preferred retail placement for compliant SKUs.
- Applesauce substitution technology:Advanced fruit puree binding systems now replicate butter's moisture retention without structural collapse, enabling cleaner ingredient decks.
- Convenience breakfast consolidation:Time-pressed commuters in urban United States corridors treat portable low-fat muffins as meal replacements, expanding consumption occasions beyond traditional bakery visits.
Market Restraints
- Input cost volatility:Almond flour and oat fiber prices swing with North American crop yields, squeezing gluten-free line margins unpredictably.
- Supply concentration risk:Three frozen bakery co-manufacturers control 70% of United States private-label capacity, creating bottleneck vulnerability.
- Technical limitation:Fat reduction below two grams per serving triggers rapid staling, constraining shelf-life claims and distribution radius.
Strategic Opportunities
- Underpenetrated foodservice:Hospital and corporate cafeteria channels in the United States remain 90% conventional muffin, offering white-space conversion.
- USDA school meal guidelines:Updated federal nutrition standards mandate reduced-fat baked goods in K-12 programs, creating mandate-driven procurement pools.
- E-commerce subscription:Direct-to-consumer frozen bakery boxes bypass slotting-fee barriers while capturing recurring revenue from specialty-diet households.
Industry Challenges
- Dual-certification timelines:Simultaneous gluten-free and low-fat audits stretch 14-18 months, delaying product launches and freezing R&D budgets.
- Clean-label reformulation:Removing artificial preservatives while maintaining fat-reduced moisture stability demands expensive enzyme system trials.
- Legacy equipment retrofit:Existing muffin lines require dedicated allergen-free zones, forcing capital allocation between new capacity and contamination containment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Muffin Market |
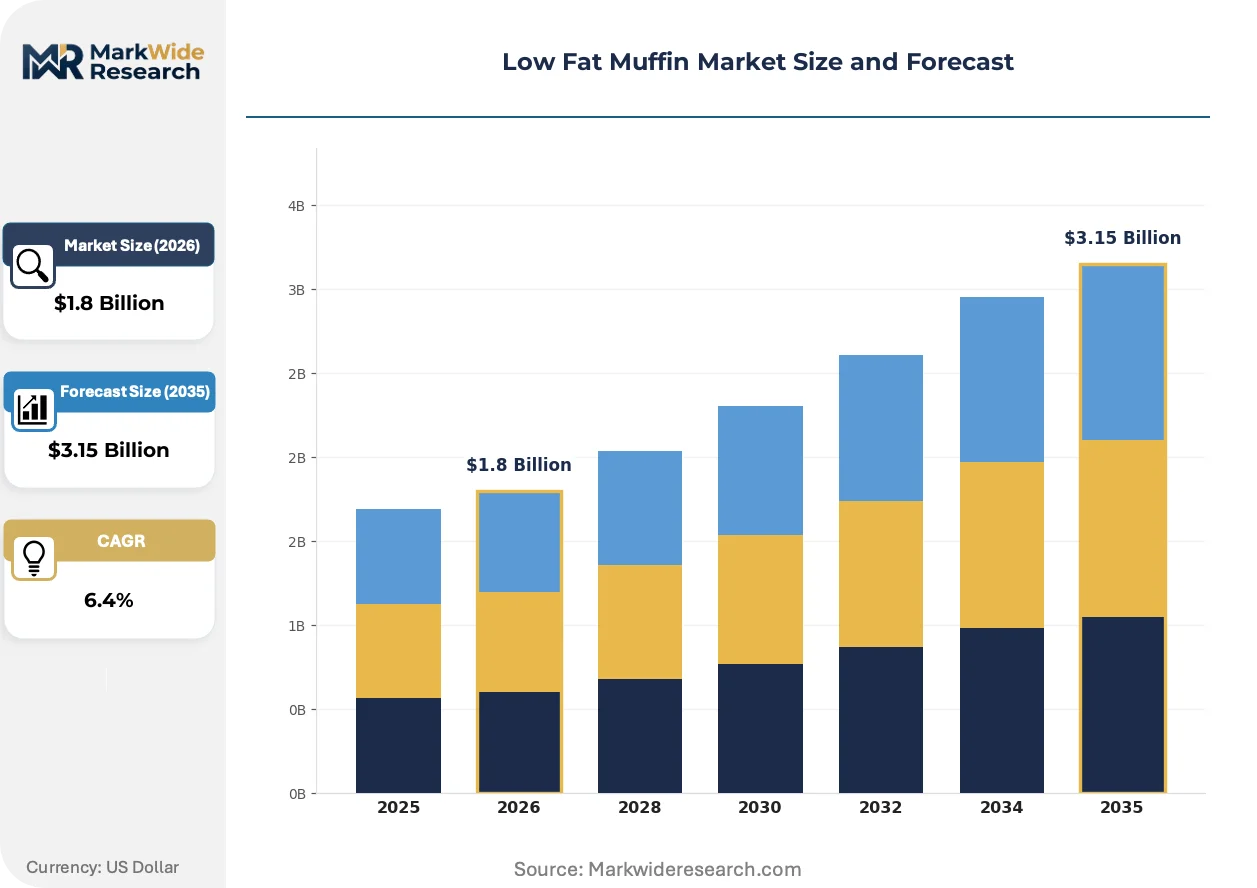
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blueberry, Banana, Chocolate Chip, Bran Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Ingredient Type: Whole Wheat, Almond Flour, Oat Flour, Gluten-Free Packaging Type: Bags, Boxes, Individual Wrappers, Resalable Pouches |
| Companies Covered | McKee Foods Corporation, Otis Spunkmeyer, Hostess Brands, Grupo Bimbo, General Mills, ARYZTA, Flowers Foods, Finsbury Food Group, The J.M. Smucker Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Muffin Market Evolving Landscape
Clean-label enzyme systems are displacing chemical emulsifiers as the primary mechanism for fat-reduced moisture retention. Three convergent forces are compressing formulation cycles and reshaping competitive advantage.
Advanced lipase and transglutaminase blends are absorbing the structural role previously filled by mono- and diglycerides in reduced-fat batters. Premium private-label programs at United States supermarket chains are adopting these enzyme systems within 18-month windows. This absorption is compressing the premium gap between conventional and clean-label positioning.
The FDA's 2023 updated guidance on "healthy" nutrient content claims tightened fat thresholds while permitting novel fiber declarations. Reformulation costs for existing SKUs now average twelve to fifteen months of gross margin recovery. Frozen bakery co-manufacturers serving the United States are prioritizing dual-compliant lines to capture both health-claim and clean-label demand pools.
Meal-kit platforms are fragmenting frozen bakery procurement into weekly subscription bundles, displacing traditional supermarket bulk purchases. Specialty-diet households in coastal United States metros now source 30% of low-fat muffins through direct-to-door frozen channels. This channel rotation forces national brands to rebuild logistics around parcel-scale cold-chain units rather than pallet-scale distribution.
Low Fat Muffin Market Segmentation
Low fat muffin segmentation reveals how formulation choices, channel access, and packaging economics fragment commercial opportunity. Manufacturers must align R&D investment with the specific margin structures and velocity patterns each segment commands.
Product Type:
Volume leaders anchor supermarket shelf placement while premium varieties extract higher per-unit economics through indulgence positioning.
- Blueberry:The category workhorse combines visible fruit particulates with standardized moisture specifications that travel well across frozen and fresh formats. Demand concentrates in United States supermarket breakfast aisles where family pack sizes drive repeat purchase velocity.
- Chocolate Chip:Indulgence-positioned formulations command price premiums through cocoa butter replacement technologies that maintain melt characteristics despite fat reduction. Coastal United States metros and foodservice channels favor this segment for dessert-positioned snacking occasions.
- Banana:Natural sweetness from fruit pulp enables deeper fat reduction without added sugar claims, appealing to clean-label seekers in specialty retail.
- Bran:Fiber-forward positioning targets digestive health claim eligibility, with strongest traction in hospital and corporate cafeteria channels seeking USDA-compliant options.
Today's leader: Blueberry. Tomorrow's challenger: Chocolate Chip.
Distribution Channel:
Channel selection determines whether manufacturers capture volume through scale economics or margin through service premiums.
- Supermarkets:Private-label expansion here compresses branded shelf space while demanding dual-certification capabilities. United States chains now require low-fat plus clean-label compliance for preferred placement.
- Online Retail:Direct-to-consumer frozen bakery subscriptions bypass slotting fees and capture recurring revenue from specialty-diet households in urban corridors.
- Specialty Stores:Curated assortments reward premium positioning and support gluten-free premium pricing.
- Convenience Stores:Grab-and-go velocity favors individually wrapped formats with extended shelf-life claims.
Supermarkets currently dominate unit movement. Online retail is climbing the fastest as cold-chain logistics mature.
Ingredient Type:
Raw material cost volatility and allergen management complexity stratify competitive positioning across formulation approaches.
- Whole Wheat:Standard fiber-enhanced base flour supports mainstream health claims with stable supply economics.
- Almond Flour:Premium protein and fat profile enables keto-adjacent positioning but exposes margins to California crop yield swings.
- Oat Flour:Beta-glucan heart health claims align with FDA-permitted functional declarations.
- Gluten-Free:Dedicated allergen-free production lines command 40-60% price premiums while requiring 14-18 month certification timelines that freeze competitor entry.
Whole wheat holds volume leadership. Gluten-free offers the steepest expansion trajectory as co-manufacturers expand dedicated capacity.
Packaging Type:
Packaging economics shape distribution radius, shelf-life claims, and consumption occasion targeting.
- Individual Wrappers:Portion-controlled formats dominate convenience and foodservice channels where grab-and-go velocity matters.
- Resalable Pouches:Multi-serve freshness claims support family consumption and reduce per-unit packaging cost.
- Boxes:Structural protection for premium gift and seasonal assortments.
- Bags:Lowest unit economics for high-velocity private-label programs.
Individual wrappers lead channel penetration. Resalable pouches are gaining share fastest as home stocking behavior shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Minneapolis-St. Paul corridor anchors North American frozen bakery production, with co-manufacturing clusters serving supermarket private-label programs across the Upper Midwest. FDA nutrition labeling requirements and USDA school meal guidelines create compliance-driven demand pools that reshape regional distribution patterns.
United States
Supermarket private-label expansion in the Northeast and California compresses branded shelf space while demanding dual-certification capabilities. FDA front-of-pack labeling rules grant health-claim eligibility to sub-three-gram fat formulations, unlocking preferred retail placement. The Chicago metro area hosts frozen bakery co-manufacturers certifying dedicated allergen-free production lines for national distribution.
Canada
Health Canada nutrition disclosure standards align with cross-border private-label programs serving Ontario and Quebec retail chains. Provincial school nutrition policies in British Columbia mandate reduced-fat baked goods in K-12 meal programs. The Greater Toronto Area concentrates frozen bakery capacity supplying both domestic supermarkets and US export channels.
Germany
EFSA dietary fiber health claims enable beta-glucan positioning for oat-based formulations in Berlin and Munich specialty retail. The country's national food regulator enforces strict allergen labeling under EU framework regulations. Baden-Württemberg industrial bakeries retrofit legacy equipment for clean-label enzyme systems serving pan-European distribution.
United Kingdom
Finsbury Food Group and Allied Bakeries anchor London and Manchester production clusters responding to NHS healthy eating procurement guidelines. The Food Standards Agency enforces front-of-pack traffic light labeling that favors sub-three-gram fat products. Yorkshire-based co-manufacturers expand gluten-free dedicated lines for supermarket premium tiers.
France
ANSES nutritional recommendations shape reformulation targets for Île-de-France industrial bakeries supplying Carrefour and E.Leclerc private-label programs. The country's national food safety agency audits clean-label enzyme substitution technologies. Lyon-based specialists develop fruit puree binding systems for reduced-fat viennoiserie and muffin hybrids.
Low Fat Muffin Market Competitive Landscape
Capacity expansion dominates the current landscape as frozen bakery co-manufacturers retrofit existing lines for dual-certification production. The vendor base stratifies into three tiers: multinational conglomerates with global manufacturing scale, regional specialists with deep supermarket relationships, and emerging direct-to-consumer subscription brands. Strategic archetypes include mass-market volume players, premium clean-label specialists, and co-manufacturing service providers. M&A activity and geographic expansion represent the dominant competitive moves as mid-tier bakeries face margin compression from private-label expansion.
Within the mass-market volume tier, McKee Foods Corporation and Flowers Foods exemplify scale-driven positioning through frozen bakery infrastructure and regional brand strength. Grupo Bimbo occupies a position as the global manufacturing anchor with cross-border logistics networks spanning North America and Europe. These three companies represent the structural concentration controlling private-label capacity and branded shelf presence across United States supermarket channels.
| Leading Market Players |
|---|
| McKee Foods Corporation |
| Otis Spunkmeyer |
| Hostess Brands |
| Grupo Bimbo |
| General Mills |
| ARYZTA |
| Flowers Foods |
| Finsbury Food Group |
| The J.M. Smucker Company |
| Others |
Value Network & Pricing Analysis
FDA front-of-pack labeling requirements gate qualified supply and premium-tier pricing access as co-manufacturers invest fourteen to eighteen months in dual-certification audits. This compliance burden stratifies the vendor base between certified premium suppliers and conventional commodity bakeries.
Pricing Analysis
Retailer markup layers dominate final shelf pricing as United States supermarket chains extract slotting fees and promotional allowances from branded and private-label suppliers alike. Three-tier pricing structure across premium, standard, and economy levels separates gluten-free certified SKUs from conventional low-fat formulations from basic private-label alternatives. Price differentiation hinges on clean-label enzyme system adoption and dual-certification status. Cost compression in the mid-tier is intensifying because private-label expansion forces branded players to absorb promotional spending. Foodservice buyers exhibit highest price sensitivity due to contract-based procurement, while direct-to-consumer subscription households accept premium positioning for allergen-free guarantees.
Supply Chain Analysis
Dual-certification timelines for gluten-free and low-fat production stretch supplier qualification gates to fourteen to eighteen months, freezing out uncertified competitors. Frozen bakery capacity concentrates in the United States, Canada, and Mexico as co-manufacturers retrofit legacy lines for allergen-free zones. Raw material dependencies center on almond flour, oat fiber, and clean-label enzyme systems. Single-source vulnerability runs through three frozen bakery co-manufacturers controlling seventy percent of United States private-label capacity. Distribution runs through pallet-scale cold-chain networks serving supermarket warehouses, with parcel-scale direct-to-consumer channels emerging fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low fat muffin market functions as a stable compounder as convenience breakfast consolidation in urban corridors sustains recurring demand from time-pressed consumers seeking portable meal replacements.
For Market Incumbents: Acquire dedicated allergen-free production lines in the Upper Midwest to capture dual-certification capacity before competitors lock in fourteen to eighteen month audit timelines. Defend supermarket shelf position by deepening vertical integration into frozen bakery co-manufacturing rather than relying on outsourced capacity. Channel control through direct-to-consumer subscription infrastructure offers margin protection against private-label compression. For New Entrants and Emerging Players: USDA school meal guidelines in the United States open a window for mandate-driven procurement targeting K-12 foodservice channels where conventional muffins still dominate ninety percent of placements. Hospital and corporate cafeteria segments offer white-space conversion with lower competitive density than retail. A go-to-market angle anchored on clean-label enzyme systems and rapid allergen-free certification differentiates against legacy players with slower reformulation cycles. For Investors and Strategic Acquirers: Roll-up economics work for regional frozen bakery specialists with existing co-manufacturing relationships because supermarket private-label expansion concentrates procurement among qualified dual-certification vendors. Platform consolidation across four to six mid-cap co-manufacturers captures scale efficiencies in enzyme system purchasing and cold-chain logistics. The inflection signal to watch is FDA guidance tightening on "healthy" nutrient content claims, which would accelerate reformulation spending and favor certified capacity holders.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Capacity Expansion | Fourteen to eighteen month audit timelines freeze competitor entry and sustain forty to sixty percent gluten-free price premiums. |
| Direct-to-Consumer Subscription Launch | Parcel-scale cold-chain units bypass supermarket slotting fees while capturing recurring revenue from specialty-diet households. |
| Clean-Label Enzyme System Adoption | Advanced lipase and transglutaminase blends displace chemical emulsifiers and compress premium gaps with conventional formulations. |
| Foodservice Channel Penetration | Hospital and corporate cafeteria segments remain ninety percent conventional muffin, offering white-space conversion at mandate-driven procurement pools. |
| Private-Label Partnership Expansion | Supermarket chains now require low-fat plus clean-label compliance for preferred placement, favoring certified co-manufacturers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with frozen bakery co-manufacturing executives, supermarket category buyers, foodservice procurement directors, and regulatory affairs specialists at packaged food companies with secondary validation. FDA guidance documents, USDA school meal program procurement databases, Nielsen retail audit data, and SEC filings from publicly traded bakery companies anchored the data foundation. Bottom-up volume modeling across product type, distribution channel, ingredient type, and packaging type segments triangulated against top-down market sizing.
Historical reference periods anchored the forecast window to established growth trajectories in convenience breakfast and reduced-fat baked goods categories. Segmentation dimensions modeled include product variety, channel access tier, allergen status, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules reported by co-manufacturers. Forecast inputs incorporated FDA labeling rule implementation timelines and enzyme system adoption curves.
Revisions become necessary when FDA guidance on "healthy" claims tightens fat thresholds or when almond flour and oat fiber input costs swing beyond historical volatility bands. Forecasts reflect assumptions about dual-certification audit timelines and supermarket private-label expansion rates. A model refresh is warranted upon material change in USDA school meal guideline enforcement or frozen bakery co-manufacturer capacity allocation decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Soft Biscuit Market
Bakery Products
Bakery Flavors Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
GCC Frozen Bakery Products Market
Bakery Products
GCC Bakery Products Market
Bakery Products
Bakery Conditioner Market
Bakery Products
Yeastless Dough Market
Bakery Products
Frozen Bakery Products Market
Bakery Products
United States Cookies Market
Bakery Products
US Retail Packaged Bread Market
Bakery Products
Wedding Cakes Market
Bakery Products
Fondant Market
Bakery Products
Bread Premix Market
Bakery Products
Doughnuts Market