
 Radio Frequency (RF) Signal Generators Market | 2026-2036
Radio Frequency (RF) Signal Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Radio Frequency (RF) Signal Generators Market Analytics
US-based defense electronics manufacturing is consolidating around fewer qualified suppliers capable of meeting MIL-STD-461G emission and susceptibility testing requirements. Keysight Technologies leverages its broad portfolio of vector signal generators to dominate calibration-intensive segments such as 5G base station validation. Rohde & Schwarz sustains deep relationships with European aerospace primes through specialized high-frequency units designed for satellite payload verification. Tabor Electronics competes aggressively in the arbitrary waveform niche by offering compact, software-defined platforms suited to automated test environments.
Radio Frequency signal generators produce controlled electromagnetic waveforms across specified frequency bands, typically spanning kilohertz to millimeter-wave ranges, with phase noise, harmonic distortion, and output power serving as critical performance parameters. These instruments calibrate receivers, characterize amplifiers, and simulate real-world propagation conditions for telecommunications and radar development. Vector signal generators now capture the fastest expansion within the Type dimension, driven by complex modulation requirements in 5G and satellite communications. Test & Measurement applications anchor the largest revenue pool across the Application dimension, though Defense procurement exhibits the steepest budget acceleration. Ultra High Frequency ranges command premium positioning as 6G research and automotive radar push center frequencies past 100 GHz.
FCC Part 15 rules, EU RED 2014/53/EU conformity requirements, and MIL-STD-461G testing protocols collectively shape product roadmaps, certification costs, and geographic market access for RF signal generator vendors. The FCC's evolving spectrum allocation decisions directly determine which frequency bands require new test equipment investments, while EU RED mandates force harmonized electromagnetic compatibility documentation across member states. Stakeholders must monitor pending 6G spectrum designations and corresponding test standard revisions to anticipate replacement cycles and R&D allocation priorities.
Market Dynamics
Defense procurement programs in the United States are expanding their test equipment budgets to address next-generation radar and electronic warfare validation needs, while the FCC's Part 15 rules for unlicensed RF devices continue tightening spurious emission limits.
Growth Catalysts
- MIL-STD-461G Testing Mandates:United States defense procurement programs require validated electromagnetic compatibility for all electronic subsystems, forcing prime contractors to upgrade signal generation capabilities for susceptibility and emission testing.
- 5G Base Station Deployment:Telecommunications infrastructure buildouts demand vector signal generators capable of complex modulation verification across sub-6 GHz and millimeter-wave bands.
- Satellite Payload Verification:European aerospace primes require specialized high-frequency units for geostationary and low-earth orbit payload characterization before launch.
Market Restraints
- Precision Component Costs:Ultra-low phase noise oscillators and high-linearity amplifiers rely on specialized III-V semiconductor materials subject to supply volatility.
- Calibration Infrastructure Concentration:Primary metrology laboratories capable of traceable RF power and frequency standards concentrate in Germany, the United States, and Japan.
- Millimeter-Wave Thermal Limitations:Output power degradation above 100 GHz restricts practical testing range for automotive radar and 6G research applications.
Strategic Opportunities
- India Electronics Manufacturing:Production-linked incentive schemes for semiconductor and telecom equipment assembly create demand for localized test equipment procurement.
- EU RED 2014/53/EU Harmonization:Conformity assessment streamlining across member states reduces certification duplication costs for multi-market product launches.
- Software-Defined Instrument Convergence:FPGA-based arbitrary waveform synthesis merging with cloud-native test orchestration platforms enables remote calibration and distributed measurement networks.
Industry Challenges
- RF Engineering Talent Scarcity:Microwave circuit design and electromagnetic simulation expertise concentrates among aging specialist cohorts with limited university pipeline replenishment.
- Multi-Standard Certification Timelines:Simultaneous FCC Part 15, EU RED, and MIL-STD-461G validation creates sequential testing bottlenecks for multi-market product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radio Frequency (RF) Signal Generators Market |
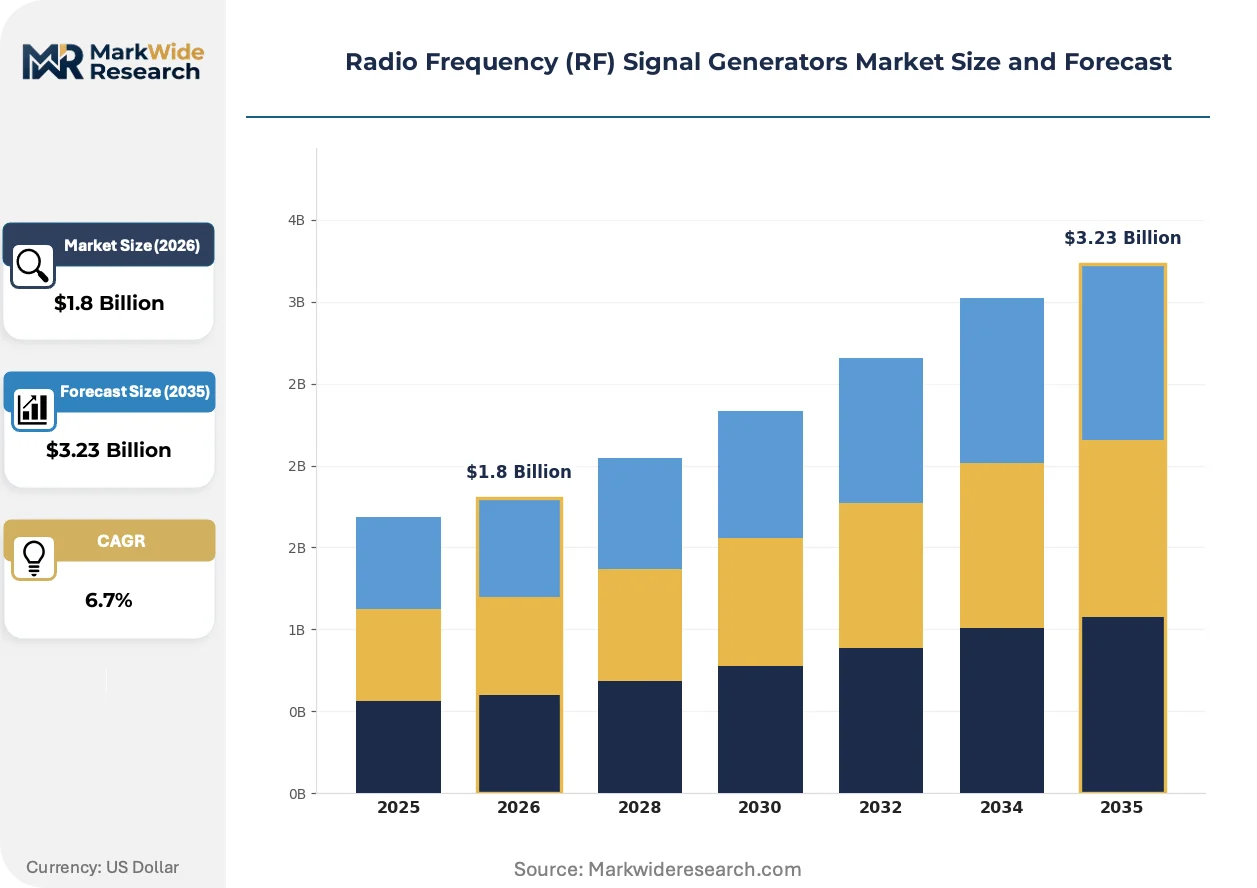
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Analog, Digital, Arbitrary Waveform, Vector Signal Application: Telecommunications, Aerospace, Defense, Test & Measurement End User: Research Institutions, Manufacturing Firms, Military, Educational Institutions Frequency Range: Low Frequency, Medium Frequency, High Frequency, Ultra High Frequency |
| Companies Covered | Berkeley Nucleonics, Tabor Electronics, Keysight Technologies, Vaunix, AnaPico AG, Rohde & Schwarz, B&K Precision Corporation, Holzworth Instrumentation, Anritsu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radio Frequency (RF) Signal Generators Market Evolving Landscape
Vector signal generation architectures are displacing traditional analog designs as modulation complexity escalates across telecommunications and defense applications. Three developments dominate vendor roadmaps and customer upgrade cycles.
Wideband digital-to-analog conversion with direct RF synthesis is electrifying instrument architectures by eliminating intermediate frequency stages. Defense electronics manufacturers in the United States adopt these platforms for electronic warfare scenario generation, compressing hardware footprint while expanding instantaneous bandwidth for multi-emitter simulation.
EU RED 2014/53/EU conformity requirements are tightening electromagnetic compatibility documentation obligations across member states. Test houses in Germany and France expand automated reporting capabilities to handle harmonized spectrum usage and spurious emission declarations, with satellite communications equipment facing the steepest compliance burden.
Buyer organizations are consolidating vendor relationships around calibration-integrated service agreements rather than discrete equipment purchases. European aerospace primes now specify multi-year metrology support contracts, with Germany-based testing facilities leading this contractual evolution toward outcome-based instrument uptime guarantees.
Radio Frequency (RF) Signal Generators Market Segmentation
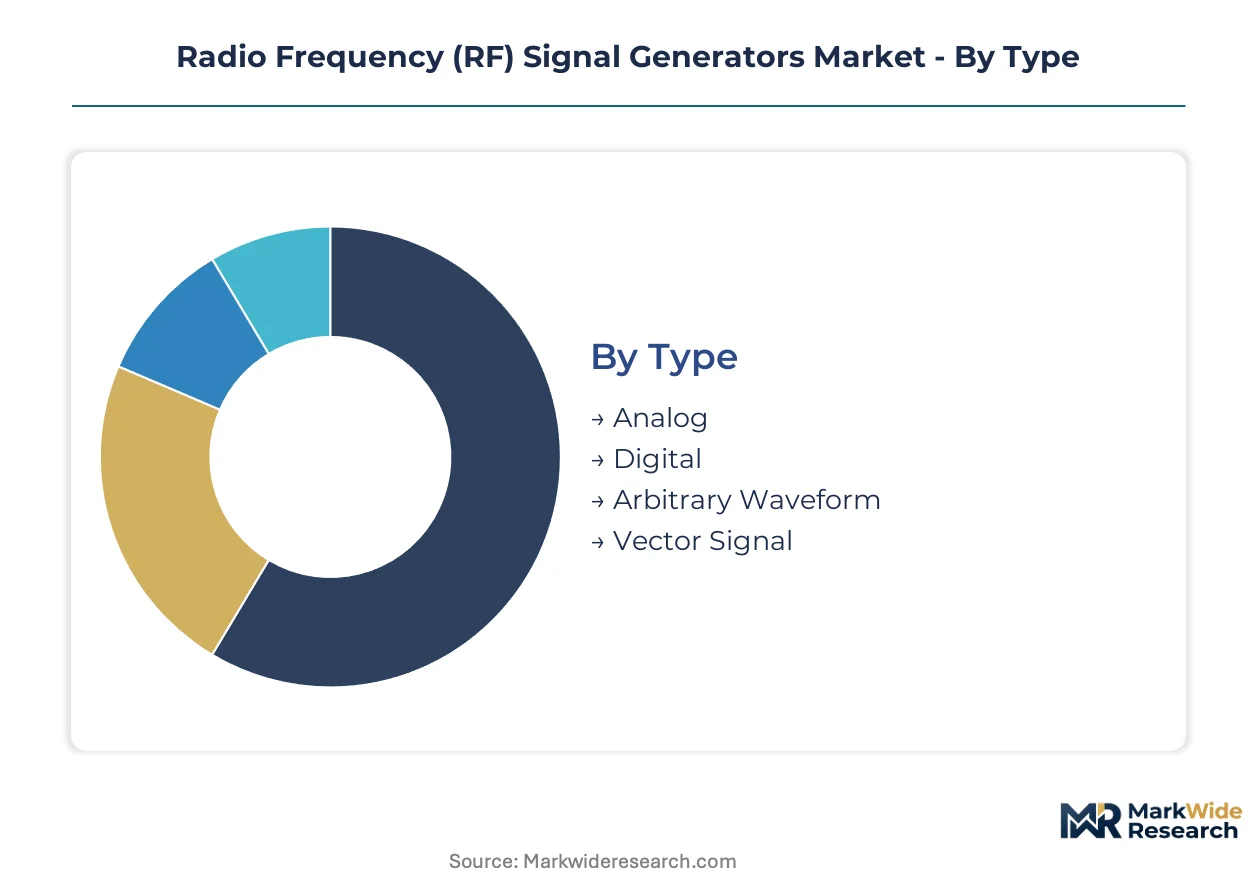
RF signal generator segmentation reveals stark capital-intensity gradients across instrument architectures and frequency capabilities. Procurement patterns diverge sharply between calibration-heavy telecommunications validation and mission-critical defense testing workflows.
Type:
Capital intensity escalates dramatically from basic analog architectures to software-defined vector platforms requiring multi-million-dollar R&D amortization.
- Vector Signal:Digital modulation engines with real-time baseband processing support 5G NR and satellite waveform generation. Telecommunications infrastructure vendors in Germany and the United States concentrate procurement here, driven by millimeter-wave base station certification mandates from the FCC and EU RED conformity frameworks.
- Arbitrary Waveform:FPGA-based synthesis enables user-defined envelope tracking and custom modulation schemes for electronic warfare simulation. Defense primes in the United States prioritize these units for radar threat replication, constrained by III-V semiconductor foundry capacity for ultra-wideband digital-to-analog converters.
- Analog:Continuous-wave generation for basic receiver calibration and filter characterization.
- Digital:Synthesized frequency stepping with moderate modulation depth for production-line testing.
Vector Signal absorbs the bulk of installed capacity; Arbitrary Waveform is expanding most quickly.
Application:
Application mix tracks directly to regulatory certification burden and equipment replacement cadence.
- Test & Measurement:Metrology-grade instruments with traceable calibration chains anchor commercial laboratory operations. German testing facilities cluster around Rohde & Schwarz service infrastructure, while Keysight Technologies dominates North American calibration-integrated contracts.
- Defense:MIL-STD-461G susceptibility and emission testing demands specialized high-power amplifiers and automated test sequences. United States procurement programs accelerate budget allocation for next-generation radar validation, constrained by qualified supplier consolidation.
- Telecommunications:Base station conformance testing and UE certification workflows.
- Aerospace:Satellite payload verification and avionics electromagnetic compatibility validation.
Test & Measurement commands the deepest installed base; Defense shows the steepest budget acceleration.
End User:
End-user economics separate capital-expense-heavy manufacturing operations from grant-funded research environments.
- Manufacturing Firms:High-volume production testing demands rack-mounted signal generators with automated handler interfaces. Electronics manufacturing services in India leverage Production-Linked Incentive schemes to localize test equipment procurement, constrained by metrology infrastructure gaps.
- Research Institutions:6G and automotive radar frontier work requires experimental mmWave signal generation above 100 GHz. University laboratories in Japan and Germany concentrate procurement here, driven by national research council funding for spectrum exploration.
- Military:Program-specific electromagnetic compatibility validation and electronic warfare training.
- Educational Institutions:Undergraduate laboratory instruction with entry-level synthesized sources.
Manufacturing Firms deploy the largest unit volumes; Research Institutions drive specification advancement.
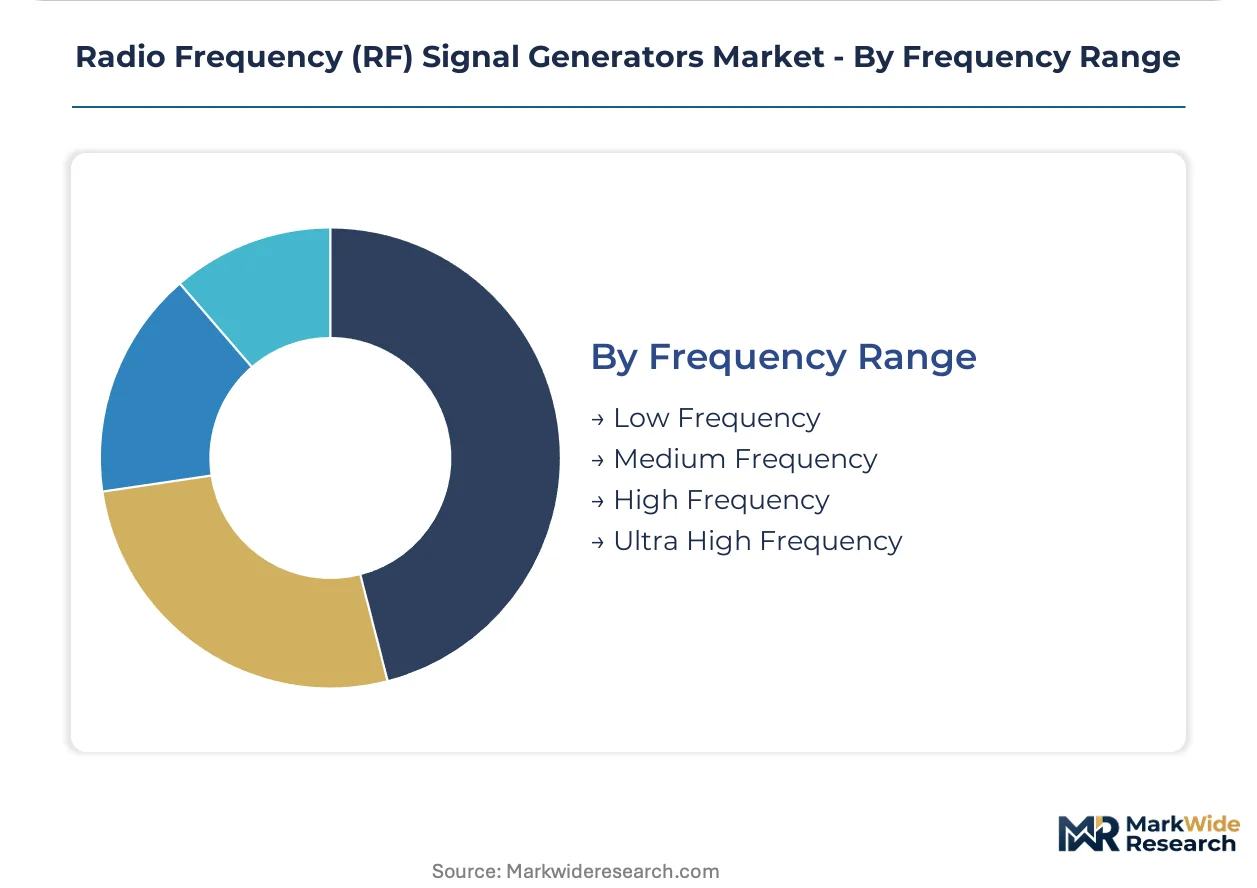
Frequency Range:
Frequency capability scales exponentially with component cost and thermal management complexity.
- Ultra High Frequency:Millimeter-wave and sub-THz generation above 40 GHz demands indium phosphide amplifiers and precision waveguide interfaces. Automotive radar development in Germany and 6G research in the United States concentrate demand here, limited by output power degradation and calibration traceability gaps.
- High Frequency:Microwave synthesis from 3 GHz to 40 GHz serves 5G sub-6 GHz and satellite communications testing. Aerospace primes in France and the United Kingdom anchor procurement, driven by payload verification requirements under EU RED harmonized standards.
- Medium Frequency:HF and VHF bands for broadcast and maritime communications testing.
- Low Frequency:Sub-3 GHz ranges for general-purpose receiver calibration and educational use.
High Frequency carries the broadest commercial footprint; Ultra High Frequency gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium arsenide and indium phosphide substrate production concentrates in Germany and the United States, anchoring precision oscillator supply chains for millimeter-wave instrumentation. Defense procurement and telecommunications infrastructure deployment shape regional demand patterns across four major markets.
United States
Next-generation radar validation programs and electronic warfare simulation drive defense procurement budgets upward. FCC Part 15 rules tighten spurious emission limits for unlicensed devices, compelling test equipment upgrades. Boston-area research clusters and California aerospace corridors concentrate 6G development and automotive radar testing facilities.
Germany
EU RED 2014/53/EU harmonization mandates streamline conformity assessment across member states for satellite communications equipment. Rohde & Schwarz anchors a dense metrology cluster serving European aerospace primes. Bavaria and Baden-Württemberg host specialized high-frequency calibration laboratories for geostationary payload verification.
Japan
METI-funded 6G spectrum exploration programs accelerate millimeter-wave research instrument procurement. National research council grants support university laboratories acquiring sub-THz signal generation above 100 GHz. Tokyo-Osaka corridor concentrates automotive radar development and electromagnetic compatibility testing infrastructure.
India
Production-Linked Incentive schemes for semiconductor assembly create localized test equipment procurement demand. TRAI spectrum allocation decisions determine which frequency bands require new capital investment. Karnataka and Telangana electronics manufacturing zones face metrology infrastructure gaps constraining calibration-integrated service adoption.
South Korea
5G base station export certification requirements drive vector signal generator procurement for sub-6 GHz and millimeter-wave validation. MFDS equipment regulations align with international electromagnetic compatibility standards. Seoul Capital Area concentrates telecommunications infrastructure vendor testing operations and automated handler interface deployment.
Radio Frequency (RF) Signal Generators Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined and arbitrary waveform niches. The vendor base stratifies across calibration-integrated service providers, defense-specialized high-frequency unit fabricators, and compact platform specialists. Three archetypes dominate: metrology-grade instrument houses with traceable standards chains, FPGA-based arbitrary waveform developers, and broad-portfolio test equipment conglomerates. Competitive moves concentrate on multi-year service contract expansion and cloud-native test orchestration platform development.
Among United States-based instrumentation houses, Keysight Technologies exemplifies the calibration-integrated service archetype, while Berkeley Nucleonics occupies a position within the precision pulse and signal generation specialty tier. Rohde & Schwarz, a German GmbH, anchors the European metrology-grade segment through relationships with aerospace primes. Tabor Electronics represents the software-defined compact platform approach competing in automated test environments.
| Leading Market Players |
|---|
| Berkeley Nucleonics |
| Tabor Electronics |
| Keysight Technologies |
| Vaunix |
| AnaPico AG |
| Rohde & Schwarz |
| B&K Precision Corporation |
| Holzworth Instrumentation |
| Anritsu Corporation |
| Others |
Value Network & Pricing Analysis
Wideband digital-to-analog conversion with direct RF synthesis is eliminating intermediate frequency stages across instrument architectures, compressing hardware footprints while simultaneously concentrating production among III-V semiconductor foundries capable of indium phosphide fabrication. This architectural shift is reshaping cost economics by reducing unit bill-of-materials for vector signal generators while tethering margin performance to gallium arsenide substrate availability from Germany and the United States.
Pricing Analysis
Calibration-integrated service agreements now bundle multi-year metrology support with upfront instrument acquisition, separating premium positioning from unbundled equipment-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects traceability grade, with MIL-STD-461G-certified units commanding substantial premiums over general-purpose laboratory instruments. Pricing pressure stems from qualified supplier consolidation in United States defense procurement, compressing margins for non-specialized analog generators. Manufacturing firms in India exhibit highest price sensitivity due to metrology infrastructure gaps, while European aerospace primes demonstrate lowest sensitivity given mission-critical payload verification requirements.
Supply Chain Analysis
Dual-sourcing requirements from United States defense primes mandate qualified indium phosphide foundry relationships in both Germany and the United States, with Japanese substrate producers serving as contingency anchors. Raw material dependencies center on gallium arsenide wafers, precision yttrium iron garnet oscillators, and gold-plated waveguide interfaces. Single-source vulnerability concentrates in III-V semiconductor epitaxy capacity, where qualified cleanroom facilities number fewer than twelve globally. Distribution runs through direct manufacturer relationships with prime contractors and authorized test equipment distributors serving mid-tier manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FCC Part 15 emission limit tightening and MIL-STD-461G testing mandates erect substantial barrier-to-entry moats protecting incumbent metrology-grade instrument houses.
For Market Incumbents: Acquire calibration laboratory networks to deepen service-integrated contract penetration and defend against FPGA-based arbitrary waveform specialists eroding the automated test environment segment. Backward integration into indium phosphide substrate supply secures oscillator cost positioning against III-V semiconductor foundry volatility. Investment in cloud-native test orchestration platforms addresses emerging demand for distributed measurement networks among research institutions. For New Entrants and Emerging Players: Automated test environment buyers in Indian electronics manufacturing zones represent the most penetrable white-space target, constrained by incumbent metrology infrastructure concentration in legacy markets. Software-defined compact platforms with localized calibration partnerships bypass capital-intensive traceable standards chain requirements. Direct procurement relationships with Production-Linked Incentive scheme beneficiaries in Karnataka and Telangana offer lower competitive intensity than established German or United States aerospace corridors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by broad-portfolio test equipment conglomerates seeking vector signal generation capability. Long-term viability favors vendors with demonstrated MIL-STD-461G qualification history and established relationships with United States defense procurement programs. The signal to monitor is 6G spectrum designation timing, which would trigger replacement cycle acceleration for sub-THz-capable instruments above 100 GHz.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration-Integrated Service Contract Expansion | Multi-year metrology support agreements lock in instrument uptime guarantees with European aerospace primes. |
| III-V Semiconductor Foundry Partnership | Indium phosphide epitaxy capacity agreements secure oscillator supply chains against substrate volatility. |
| Cloud-Native Test Orchestration Platform | FPGA-based arbitrary waveform synthesis merges with remote calibration for distributed measurement networks. |
| MIL-STD-461G Qualification Investment | Validated electromagnetic compatibility testing capability opens United States defense procurement channels. |
| Localized Calibration Laboratory Buildout | Traceable RF power standards infrastructure addresses metrology gaps in Indian electronics manufacturing zones. |
Research Methodology
Independent corroboration across primary interviews with test equipment procurement managers, RF engineering directors at defense primes, calibration laboratory technical leads, and telecommunications infrastructure vendor supply chain executives underwrites the qualitative findings. Secondary validation draws from FCC Part 15 rulemaking dockets, EU RED 2014/53/EU conformity assessment documentation, MIL-STD-461G testing protocol revisions, and SEC filings from publicly traded instrumentation houses. Bottom-up instrumentation shipment analysis triangulates against top-down defense procurement budget allocation data.
Comparable-period anchoring to historical test equipment replacement cycles and spectrum allocation decision timelines structures the projection horizon. The analytical framework models value trajectories across instrument type, frequency range, application, and end-user archetype dimensions. CAGRs derive from segmented unit economics and capital-expense intensity differentials between calibration-heavy telecommunications validation and mission-critical defense testing workflows. Forecast inputs incorporate III-V semiconductor foundry capacity expansion announcements and pending 6G spectrum designation proceedings.
Revisions become necessary when III-V semiconductor supply disruptions, accelerated EU RED harmonization timelines, or defense procurement program cancellations materialize. Deviation in FCC spectrum allocation decisions or MIL-STD-461G testing protocol revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Radio Frequency Front End Market
RF Components
Harness-Level EMI and Shielding Component Systems Market
RF Components
Tunable Capacitors Market
RF Components
Digital Radio Frequency Market
RF Components
Radio Frequency Counter Market
RF Components
Global Ceramic Dielectric Filters Market
RF Components
433MHz Active RFID Reader Market
RF Components
RFID Antenna Market
RF Components
RF Transceiver Chip Market
RF Components
High-Power Microwave Source Market
RF Components
Gan RF Semiconductor Devices Market
RF Components
Asia-Pacific Small Signal Transistor Market
RF Components
Americas Small Signal Transistor Market
RF Components
Silicon Tuners Market
RF Components
RF Microwave MLCC Market
RF Components
High Power RF Amplifier Module Market