
 Household Induction Cooktops Market | 2026-2036
Household Induction Cooktops Market Size, Share, and Industry Trends Forecast 2026-2036
Household Induction Cooktops Market Outlook
Chinese induction coil and ceramic glass manufacturers are expanding output to serve OEM demand across Europe and Southeast Asia. Robert Bosch GmbH leverages its appliance ecosystem to bundle induction cooktops with ventilation and oven systems. Midea Group Co., Ltd. anchors global volume through vertically integrated magnetics and control board production. Samsung Electronics Co., Ltd. competes on smart kitchen integration, embedding Wi-Fi modules that sync with recipe apps and energy management platforms.
Household induction cooktops are electrically powered cooking surfaces that use high-frequency electromagnetic fields to generate heat directly in ferromagnetic cookware, typically operating at power frequencies between 20-50 kHz and achieving thermal efficiencies above 90 percent. Their primary purpose is to deliver precise, rapid temperature control for residential and light-commercial food preparation while eliminating open flames and reducing ambient kitchen heat. Built-in induction cooktops dominate margin pools in premium kitchen renovations, where flush countertop integration and zoneless full-surface designs command price premiums over portable and freestanding alternatives. Smart control features represent the fastest-expanding feature tier, with touch panels and app-connected timers now standard above entry power ratings, while 1800W and 2000W segments capture the bulk of replacement demand in North American and European households constrained by residential electrical infrastructure.
The European Union F-Gas Regulation and CE marking requirements under the Ecodesign Directive shape product efficiency thresholds and refrigerant-linked appliance certification pathways that manufacturers must navigate for market access. The U.S. Department of Energy appliance standards and EPA ENERGY STAR specifications influence federal procurement and utility rebate programs that steer consumer selection toward higher-efficiency induction models. China's GB standards and MIIT energy-labeling rules enforce domestic efficiency floors that export-oriented manufacturers like Haier Smart Home Co., Ltd. and Midea must satisfy for both local sale and overseas shipment. Stakeholders should monitor the divergence between European phase-out timelines for gas infrastructure and the pace of North American electrical panel upgrade cycles, as this gap determines where inventory and certification investments will yield priority returns.
Market Dynamics
The electrification of residential cooking infrastructure is compressing replacement cycles for legacy gas ranges as building codes and appliance efficiency mandates tighten across major economies.
Growth Catalysts
- EU F-Gas Regulation:The phase-down of fluorinated greenhouse gases in heating and cooling equipment creates parallel policy momentum for all-electric kitchen portfolios, accelerating induction cooktop specification in new construction.
- Zoneless full-surface designs:Induction coils arranged in matrix configurations eliminate fixed burner positions, enabling flexible cookware placement that commands premium positioning in kitchen renovation projects.
- German building codes:National bans on fossil-fuel heating in new residential construction, combined with consumer rebate programs, align procurement incentives toward induction over conventional gas ranges.
Market Restraints
- Copper and ferrite magnetics:Input cost volatility in induction coil materials compresses margin stability for manufacturers without captive supply arrangements or long-term purchase agreements.
- Residential electrical infrastructure:North American households face panel upgrade requirements to support 240V/40A circuits, creating installation friction that slows replacement velocity relative to European markets.
- Cast iron and aluminum cookware incompatibility:Ferromagnetic material requirements limit immediate usability for households with existing non-compatible cookware, necessitating incremental consumer education and accessory sales.
Strategic Opportunities
- Southeast Asia urbanization:Rising middle-class household formation in Indonesia and Vietnam creates first-time buyer segments where induction bypasses legacy gas infrastructure entirely.
- Smart kitchen convergence:Wi-Fi module integration with recipe applications and energy management platforms enables subscription revenue models and data monetization beyond hardware margins.
- US Inflation Reduction Act:Residential electrification tax credits and utility rebate programs for appliance upgrades reduce effective purchase price for induction cooktops in key state markets.
Industry Challenges
- Electromagnetic compatibility certification:FCC Part 18 testing for industrial, scientific and medical equipment creates timeline variability for new product introductions, with retest cycles averaging 8-12 weeks for design modifications.
- Legacy gas fitter workforce:Installation capacity constraints emerge as electrical contractor licensing requirements differ from traditional gas appliance installation certifications, creating regional service gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Induction Cooktops Market |
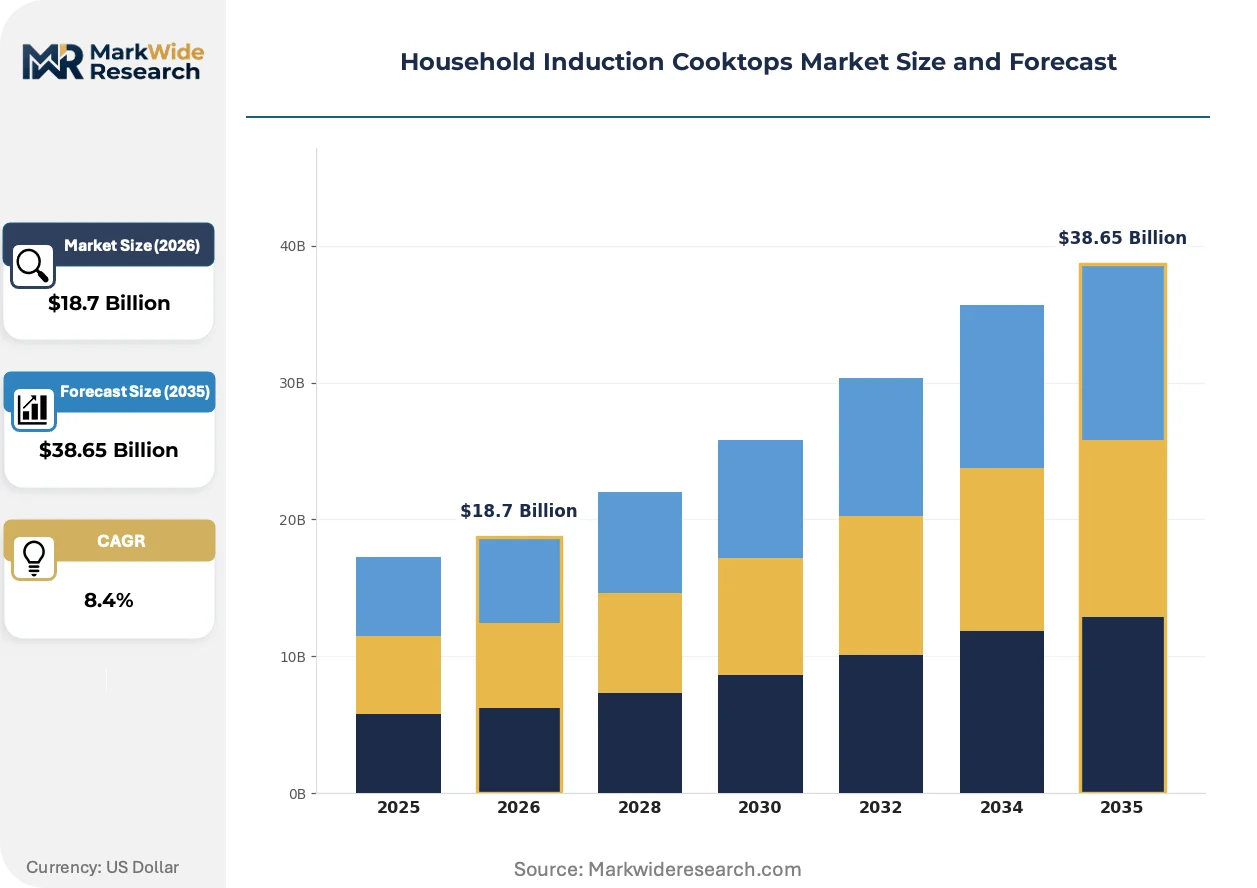
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Built-in, Freestanding, Countertop End User: Home, Restaurant, Catering, Institutional Power Rating: 1200W, 1800W, 2000W, 3000W Feature: Smart Control, Safety Lock, Timer, Touch Panel |
| Companies Covered | Robert Bosch GmbH, Samsung Electronics Co., Ltd., LG Electronics Inc., Midea Group Co., Ltd., Haier Smart Home Co., Ltd., Whirlpool Corporation, Electrolux Group, Koninklijke Philips N.V., Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Induction Cooktops Market Strategic Shifts
Digital control architectures and connectivity modules are redefining how cooking appliances interface with residential energy systems and consumer behavior platforms.
Induction power electronics with integrated bridgeless totem-pole PFC topologies is automating real-time load balancing across multiple cooking zones. Premium kitchen renovation contractors specify these systems for whole-home energy management integration. The technology is automating demand-response participation that was previously manual or absent.
REACH restrictions on persistent organic pollutants in electronic components are forcing reformulation of potting compounds and thermal interface materials used in IGBT and GaN power modules. Manufacturers serving the European market must validate alternative chemistries through ECHA notification procedures. Built-in cooktop segments face the steepest compliance cost escalation due to higher power density and thermal management requirements.
Builder and developer procurement of appliance packages now favors pre-integrated kitchen systems over standalone cooktop purchases. Custom home construction channels in Germany and the Netherlands specify bundled ventilation-oven-cooktop configurations from single-source suppliers. This concentration is most visible in multi-unit residential projects where standardization reduces installation complexity and warranty administration overhead.
Household Induction Cooktops Market Segmentation
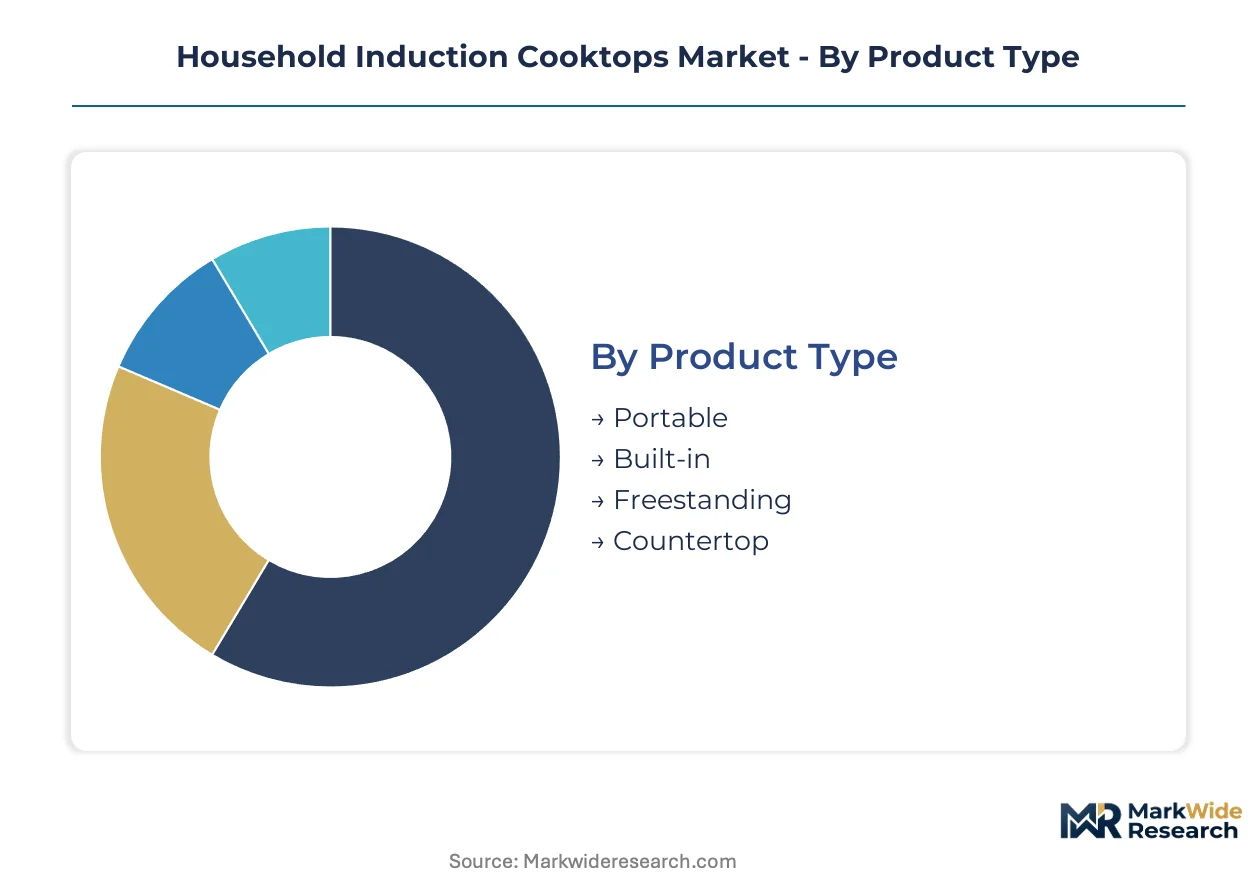
Induction cooktop segmentation reveals how power electronics, installation requirements, and control interfaces split demand across renovation and replacement cycles. Each axis carries distinct margin profiles and regulatory compliance burdens that shape manufacturer portfolio strategy.
Product Type:
Power electronics and installation permanence define the cost-to-performance gradient across form factors.
- Built-in:Flush countertop integration with zoneless matrix coil configurations eliminates fixed burner positions. German kitchen renovation contractors specify these for premium residential projects where full-surface flexibility commands price premiums over conventional alternatives.
- Portable:Single-zone units with 120V plug-and-play operation target rental households and temporary foodservice setups. Demand concentrates in North American apartments where electrical panel upgrades remain prohibitive for permanent installation.
- Freestanding:Self-contained units with integrated ovens suit replacement of legacy gas ranges without cabinetry modification.
- Countertop:Compact multi-zone designs bridge portable convenience with semi-permanent placement for secondary cooking stations.
Mature deployment sits with Built-in. Newer deployment is concentrated in Portable.
End User:
Volume scale and replacement frequency separate consumer from commercial procurement patterns.
- Home:Residential replacement cycles compress as EU F-Gas Regulation and national fossil-fuel heating bans accelerate electric cooking mandates. German building codes and consumer rebate programs align procurement incentives toward induction specification in new construction.
- Restaurant:Commercial kitchens demand rapid thermal response and precise temperature control for high-throughput service. Zoneless full-surface designs enable flexible cookware placement during peak service windows.
- Catering:Mobile foodservice operations prioritize portable units with generator-compatible power draw for off-grid events.
- Institutional:School and hospital cafeterias specify safety-lock features and timer-controlled operation for compliance with food safety protocols.
Volume leadership rests with Home. Margin expansion is steepest in Restaurant.
Power Rating:
Residential electrical infrastructure constraints and cooking performance requirements segment the wattage ladder.
- 1800W:Standard single-zone output for North American 120V circuits without panel upgrades. Captures bulk of replacement demand in households constrained by legacy electrical infrastructure.
- 2000W:European baseline specification for built-in cooktops operating on 230V residential supply. Aligns with Ecodesign Directive efficiency thresholds for CE marking compliance.
- 1200W:Entry-level portable units for supplemental cooking and warming applications.
- 3000W:Commercial-grade output requiring dedicated 240V/40A circuits for rapid boiling and wok-style cooking.
Replacement volume clusters at 1800W. Performance upgrades concentrate at 3000W.
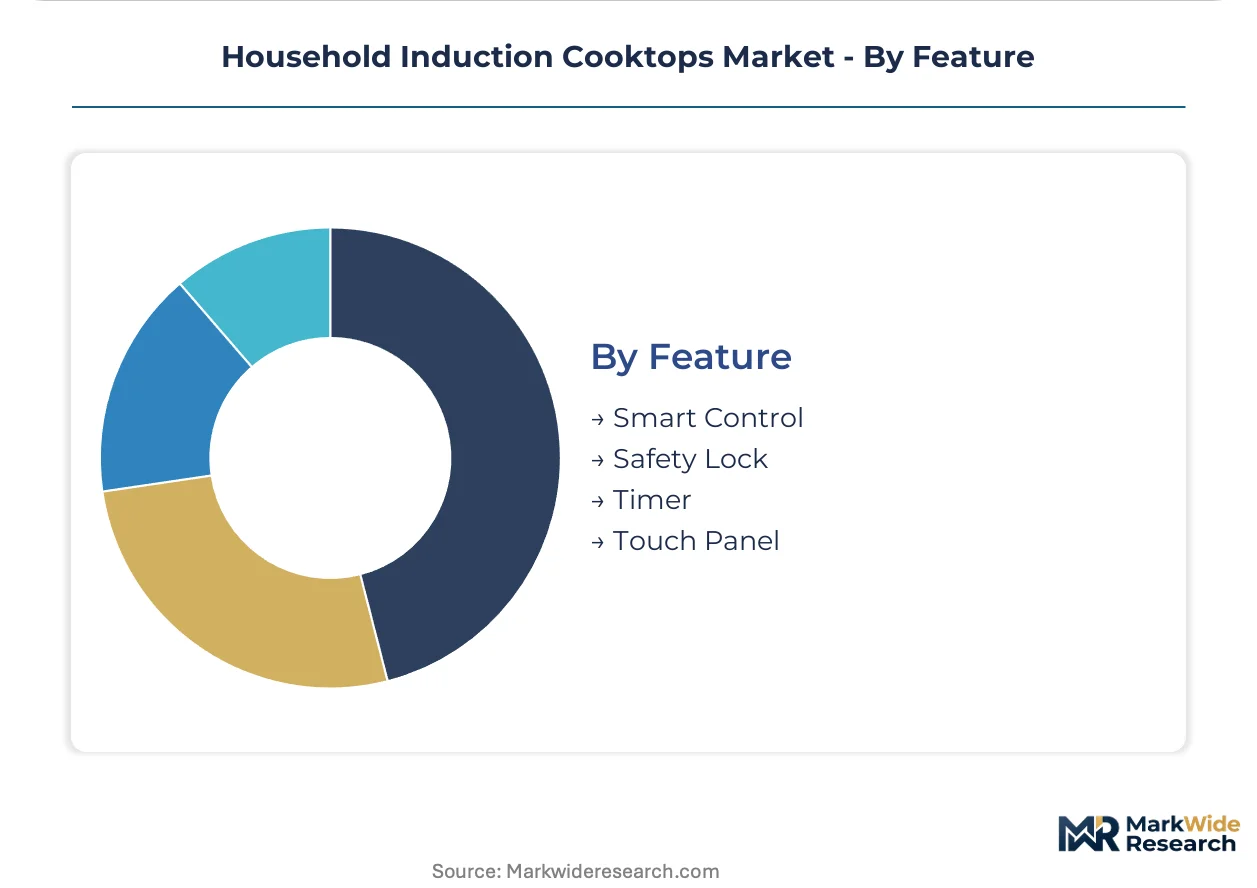
Feature:
Digital control architectures and connectivity modules are redefining how cooking appliances interface with residential energy systems.
- Smart Control:Wi-Fi module integration enables app-connected timers, recipe synchronization, and energy management platform participation. Premium kitchen renovation contractors specify these for whole-home automation integration.
- Touch Panel:Capacitive glass interfaces with haptic feedback have displaced mechanical knobs across mid-tier and premium product lines. REACH restrictions on persistent organic pollutants force reformulation of potting compounds in control module manufacturing.
- Safety Lock:Child-proof activation sequences prevent unintended power-on in households with young children.
- Timer:Programmable shutoff functions support unattended cooking of rice, stocks, and slow-simmer applications.
Feature penetration is deepest in Touch Panel. Connectivity expansion is climbing the fastest in Smart Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ferrite magnetics and copper coil manufacturing clusters in Zhejiang and Guangdong provinces anchor Asia-Pacific supply capacity for induction power electronics serving export markets.
Germany
Kitchen renovation contractors specify zoneless full-surface induction cooktops for premium residential projects in Berlin and Munich. The national ban on fossil-fuel heating in new construction, paired with KfW consumer rebate programs, aligns procurement incentives toward electric cooking. Baden-Württemberg's appliance engineering corridor hosts testing facilities for CE marking under Ecodesign Directive efficiency thresholds.
United States
Electrical panel upgrade requirements in older housing stock constrain 240V/40A circuit installation for high-power induction units. The Inflation Reduction Act's residential electrification tax credits and state-level utility rebate programs reduce effective purchase prices in California and New York markets. Pacific Northwest metropolitan areas lead retrofit adoption where municipal building codes prioritize all-electric new construction.
China
Vertically integrated magnetics and control board production in the Yangtze River Delta region supplies OEM demand across Europe and Southeast Asia. MIIT energy-labeling rules and GB standards enforce domestic efficiency floors that export-oriented manufacturers must satisfy for overseas shipment. Guangdong province's ceramic glass foundries scale output to serve global built-in cooktop assembly lines.
Netherlands
Randstad metropolitan contractors specify bundled ventilation-oven-cooktop configurations from single-source suppliers in multi-unit residential projects. The EU F-Gas Regulation creates parallel policy momentum for all-electric kitchen portfolios in new construction. Eindhoven's electronics cluster develops bridgeless totem-pole PFC topologies for real-time load balancing across multiple cooking zones.
Vietnam
Rising middle-class household formation in Ho Chi Minh City and Hanoi creates first-time buyer segments where induction bypasses legacy gas infrastructure entirely. Urban apartment construction favors portable and countertop units compatible with constrained electrical infrastructure. Local distributors import 1800W and 2000W segments from Chinese manufacturers to serve replacement demand in emerging residential developments.
Household Induction Cooktops Market Competitive Environment
Global majors compete with regional champions across power electronics integration and kitchen ecosystem bundling, creating a tiered structure where appliance conglomerates face pressure from specialized coil and control module suppliers. The vendor base splits between vertically integrated magnetics producers and brand assemblers sourcing components across Asian manufacturing clusters. Two strategic archetypes dominate: full-stack kitchen ecosystem providers bundling ventilation and oven systems, and component specialists capturing margin through captive ferrite and ceramic glass supply. Competitive moves concentrate on strategic partnerships for smart kitchen platform integration and capacity expansion in Southeast Asian export hubs.
Among German-based appliance conglomerates, Robert Bosch GmbH exemplifies the ecosystem-bundling archetype through integrated kitchen system offerings. Samsung Electronics Co., Ltd. and Midea Group Co., Ltd. occupy distinct positions on the technology-integration versus vertical-control spectrum, with the former representing smart connectivity convergence and the latter anchoring magnetics-to-assembly supply chain depth. These three entities collectively illustrate how geographic origin and corporate structure map onto divergent competitive vectors in power electronics and residential kitchen automation.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Samsung Electronics Co., Ltd. |
| LG Electronics Inc. |
| Midea Group Co., Ltd. |
| Haier Smart Home Co., Ltd. |
| Whirlpool Corporation |
| Electrolux Group |
| Koninklijke Philips N.V. |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
The certification-performance gap between CE-marked zoneless full-surface systems and uncertified portable units manifests in both manufacturer margin capture and raw material sourcing strategies across German and Chinese production clusters.
Pricing Analysis
Warranty bundling separates premium built-in offerings from unbundled portable alternatives. Pricing stratifies across premium, standard, and economy tiers based on zoneless coil density and smart control module inclusion. Cost compression in entry-level portable segments is intensifying because Chinese OEMs flood Southeast Asian markets with 1800W units. Residential renovation contractors in Germany show least price sensitivity, while Vietnamese apartment developers prioritize lowest first-cost procurement.
Supply Chain Analysis
CE marking and FCC Part 18 certification gates determine which manufacturers access European and North American distribution channels. Ferrite core production concentrates in China, South Korea, and Japan. Copper coil winding and ceramic glass sourcing draw from Zhejiang and Guangdong provinces. Single-source vulnerability in GaN power module supply creates procurement risk for premium product lines. Distribution runs through appliance retail chains and direct builder specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrical contractor licensing bottlenecks in North America constrain installation capacity, propping pricing power for manufacturers with certified service networks.
For Market Incumbents: Lock in ferrite magnetics supply through captive arrangements or long-term purchase agreements with Zhejiang coil manufacturers. Expand certified installer networks in California and New York to capture Inflation Reduction Act rebate-driven demand. Defend against emerging Chinese OEMs by accelerating zoneless full-surface R&D roadmaps.
For New Entrants and Emerging Players: Direct-to-consumer digital channels offer lowest-friction entry for portable induction units targeting North American rental households. Target Vietnamese and Indonesian urban apartment segments where legacy gas infrastructure is absent. Bypass electrical contractor dependencies by marketing plug-and-play 120V compatibility.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated magnetics specialists given EU F-Gas Regulation acceleration and German building code tightening. Long-term viability hinges on smart kitchen platform integration capabilities. Watch FCC certification backlog duration as inflection indicator for new product introduction velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Core Production | Captive magnetics supply insulates margin from copper price volatility in Zhejiang manufacturing clusters. |
| Smart Kitchen Platform Partnership | Wi-Fi module integration with recipe applications enables recurring revenue beyond hardware margins. |
| Certified Installer Network Expansion | Licensed electrical contractor relationships reduce installation friction in California and New York rebate markets. |
| Zoneless Full-Surface Product Launch | Matrix coil configurations command premium positioning in German kitchen renovation specifications. |
| Southeast Asian Distribution Channel Buildout | Direct importer relationships in Vietnam and Indonesia bypass legacy gas infrastructure entirely. |
Study Parameters
Trade databases, appliance manufacturer SEC filings, and EU Ecodesign Directive regulatory notices formed the secondary backbone. Primary interviews with kitchen renovation contractors, electrical contractor licensing boards, appliance procurement managers at multi-unit residential developers, and ferrite core manufacturing plant managers validated demand assumptions. Bottom-up unit shipment estimates triangulated against top-down residential electrification spending projections.
Historical trendline analysis of replacement cycle compression and new construction appliance specification rates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, power rating, feature tier, and regional electrical infrastructure constraint. CAGRs derived from unit volume trajectories weighted by average selling price evolution. Bridgeless totem-pole PFC adoption curves and smart control module penetration rates served as technology-specific forecast inputs.
The model holds under stable copper and ferrite pricing; deviation in raw material cost spikes or FCC certification timeline extensions would shift manufacturer margin assumptions. Forecasts reflect documented assumptions regarding EU F-Gas Regulation enforcement pace and US electrical panel upgrade subsidy uptake. A model refresh is warranted upon material change in German building code implementation timelines or REACH restriction scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
UAE Home Appliances Market
Home Appliances
Saudi Arabia Small Home Appliances Market
Home Appliances
India Major Home Appliances Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
South Korea Home Appliances Market
Home Appliances
India Laundry Appliances Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
White Goods Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
Israel Home Needs Appliances Market
Home Appliances
Sweden Home Appliances Market
Home Appliances
GCC Major Home Appliances Market
Home Appliances
Global Residential Microwave Oven Market
Home Appliances
Mexico Home Appliances Market