
 Conveyor Belt Market | 2026-2036
Conveyor Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Conveyor Belt Market Analysis
Maintenance service contracts is rebalancing how conveyor belt vendors capture lifetime value from installed bases. Continental AG leverages its global service network to lock in multi-year aftermarket agreements. Habasit AG anchors its position through specialized splicing and belt monitoring services. Fenner competes by extending predictive maintenance capabilities to remote mining sites.
A conveyor belt is a continuous moving band of fabric, rubber, or metal that transports materials or products between points, typically rated by tensile strength measured in newtons per millimeter and operating temperature ranges from -30°C to 180°C depending on polymer composition. Flat belts dominate light manufacturing for their cost efficiency and quiet operation, while modular belts command premium positioning in food processing due to hygienic design and washdown compatibility. Wire mesh belts sustain niche demand in high-heat baking and heat-treatment applications where standard elastomers degrade.
OSHA mandates guarding and emergency stop standards that shape belt system design in US facilities, while REACH restricts phthalate plasticizers in European PVC belts and China's GB standards enforce flame-resistance ratings for underground mining applications. Stakeholders must weigh regulatory compliance costs against retrofit opportunities as emission and safety thresholds tighten across major manufacturing jurisdictions.
Market Dynamics
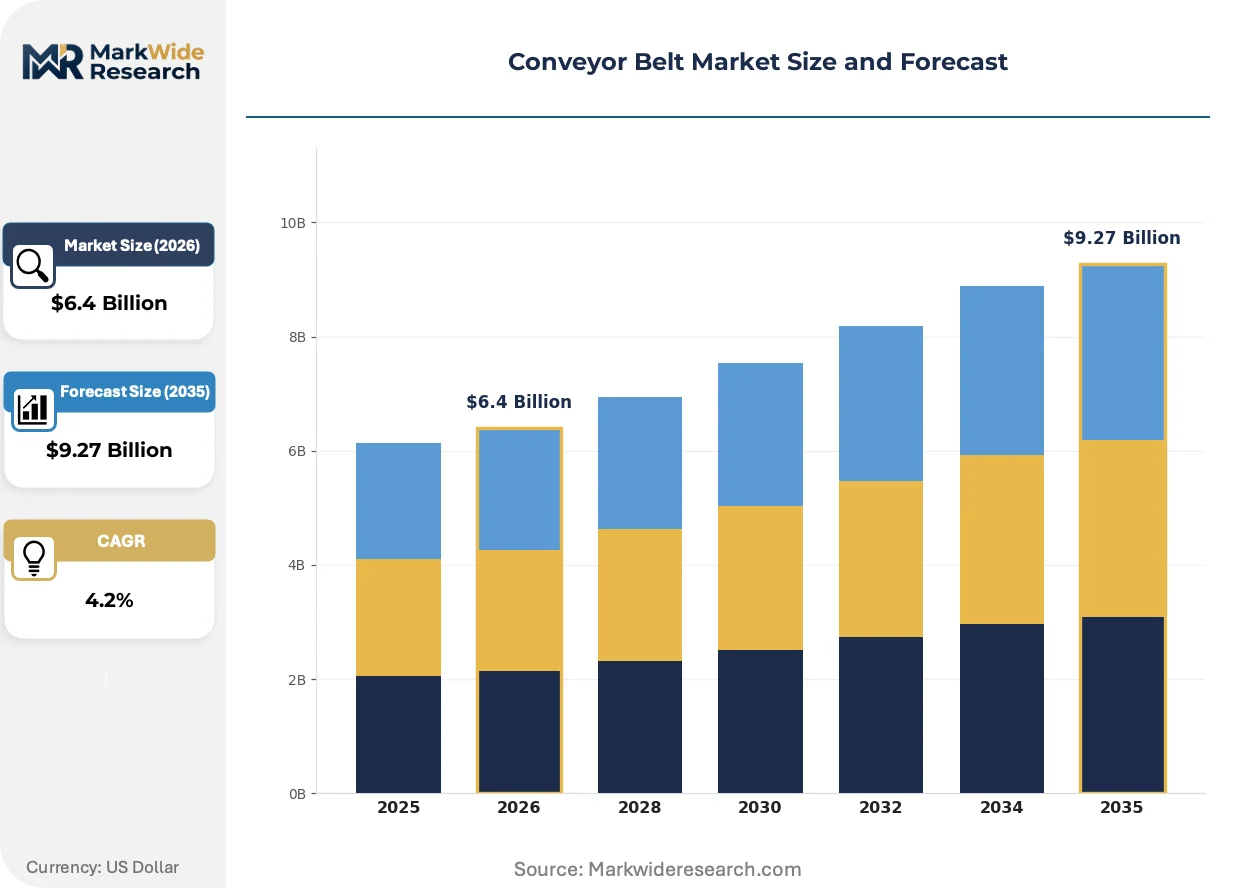
Maintenance service contracts are rebalancing how conveyor belt vendors capture lifetime value from installed bases, shifting revenue from one-time equipment sales toward recurring aftermarket streams and predictive service platforms.
Growth Catalysts
- Australian Mining Replacement Cycles:Heavy-duty rubber belts in Pilbara iron ore operations face accelerated wear from abrasive ore loads, generating sustained replacement demand for heat-resistant polymer formulations.
- REACH PVC Restrictions:ECHA's phasing of phthalate plasticizers is redirecting European food-processing buyers toward TPU and silicone alternatives with compliant migration profiles.
- Smart Splicing Technologies:Ultrasonic and hot-vulcanization automation is reducing downtime in bulk port terminals, cutting belt installation labor hours by half in high-throughput facilities.
Market Restraints
- Natural Rubber Price Volatility:Thai and Indonesian latex supply disruptions transmit directly to belt compound costs, squeezing margin predictability for mid-tier manufacturers without backward integration into polymer production.
- Chinese Capacity Concentration:Over half of global fabric ply capacity sits in Shandong and Jiangsu provinces, creating single-source vulnerability for multi-ply belt producers elsewhere.
- Thermal Degradation Limits:Standard NBR compounds fail above 120°C, forcing steel-cord belts in cement clinker applications where elastomeric solutions would suffice at lower temperatures.
Strategic Opportunities
- Indonesian Palm Oil Expansion:Kalimantan processing plants lack local belt fabrication, opening service-hub opportunities for regional players with heat-resistant oil-resistant compound expertise.
- EU CSRD Supply Chain Disclosure:Mandatory Scope 3 reporting is creating premium positioning for belt makers with certified recycled-content programs and carbon-accounted logistics.
- IoT-Enabled Condition Monitoring:Embedded RFID and fiber-optic strain sensors are converging with cloud analytics to enable outcome-based maintenance contracts in remote mining corridors.
Industry Challenges
- Vulcanization Technician Shortage:Hot-splice certification programs in North America and Australia cannot match retirement rates, delaying field installation timelines for critical infrastructure projects.
- Legacy System Integration:Retrofitting continuous belt monitoring into 1990s-era bulk handling lines requires custom mechanical interfaces that extend commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conveyor Belt Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $9.27 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Belts, Modular Belts, Wire Mesh Belts, Timing Belts End User: Manufacturing, Mining, Food Processing, Warehousing Material: Rubber, PVC, Metal, Fabric Application: Bulk Material Handling, Assembly Lines, Packaging, Transportation |
| Companies Covered | Bando Chemical Industries, Intralox, Continental AG, Volta Belting Technology, Interroll, Daifuku, Fenner, Habasit AG, Fives Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conveyor Belt Market Emerging Trajectories
Digitalization of belt condition monitoring and polymer formulation advances are compressing maintenance intervals while expanding operational temperature envelopes across heavy industry applications.
Aramid fiber reinforcement is absorbing tensile loads previously requiring steel cords, enabling lighter belt carcasses that reduce conveyor system power draw. Cement producers in Germany and Turkey are adopting these compounds for kilometer-length overland conveyors. The technology is absorbing market share from traditional steel-cord constructions in medium-tension applications.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing reformulation of fire-resistant PVC belts used in underground mining. Manufacturers serving Polish and Romanian coal operations are migrating to phosphate-ester plasticizer systems. The regulatory pressure is compressing margins for compounders lacking R&D scale to validate alternative formulations.
Buyers in Brazilian iron ore and Chilean copper operations are unbundling belt supply from installation service, awarding separate contracts to specialized splicing contractors with union-certified field crews. This procurement fragmentation is eroding integrated vendor pricing power and lengthening vendor qualification timelines for new market entrants.
Conveyor Belt Market Segmentation
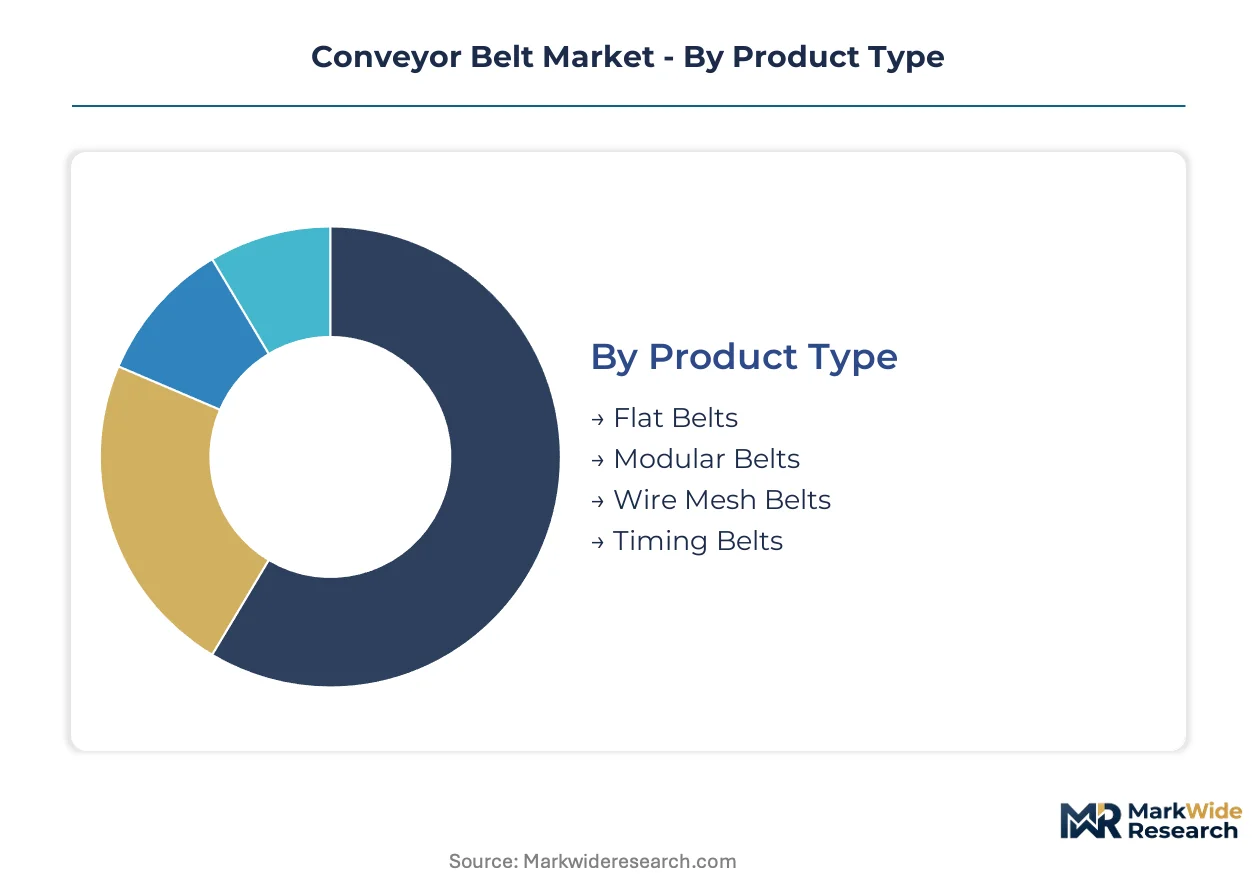
Conveyor belt segmentation reveals how polymer chemistry and tensile architecture determine regulatory pathways and service life economics across industrial deployments. Buyers select belt constructions based on load profiles, temperature exposure, and compliance mandates specific to their operational geography.
Product Type:
REACH Annex XVII and FDA food-contact regulations impose divergent certification burdens on belt constructions, with polymer migration limits and flame-resistance ratings dictating compound selection.
- Flat Belts:Fabric-reinforced elastomer constructions with single-ply or multi-ply carcasses, typically rated 100-800 N/mm tensile strength. Demand concentrates in German automotive assembly plants where quiet operation and precise speed control reduce worker fatigue claims. OSHA machine-guarding standards shape pulley enclosure specifications in US light manufacturing.
- Modular Belts:Interlocking plastic segments with open-hinge designs enabling tool-free disassembly for sanitization. Food processing facilities in France and Italy specify these for EU 1935/2004 compliance on plastic food-contact materials. Washdown compatibility drives replacement of traditional flat belts in dairy and ready-meal operations.
- Wire Mesh Belts:Stainless steel or carbon steel weave constructions sustaining continuous operation above 200°C. Heat treatment furnaces in Japan's automotive component sector specify these where elastomeric belts would carbonize.
- Timing Belts:Tooth-profiled synchronous drive belts with fiberglass or aramid cord reinforcement. Precision positioning requirements in Korean electronics assembly favor these over friction-driven alternatives.
Flat belts sit at the top of the volume ranking, with modular belts climbing the fastest as food safety audits intensify across European processing chains.
End User:
End-use concentration determines service contract structures and replacement cadence, with remote mining corridors requiring fundamentally different logistics than urban warehousing.
- Manufacturing:Assembly line and work-in-progress transport across discrete and process industries. Automotive plants in Mexico's Bajío region drive demand for oil-resistant NBR compounds under NAFTA-era supply chain configurations.
- Mining:Overland conveying and in-pit crushing transfer systems handling ore loads exceeding 5000 t/h. Australian Pilbara iron ore operations generate replacement demand for steel-cord and fabric-ply constructions with abrasion-resistant top covers.
- Food Processing:Hygienic conveying from raw intake through packaging with washdown protocols. USDA FSIS inspection requirements mandate blue-colored detectable belts in poultry operations to prevent contamination events.
- Warehousing:E-commerce fulfillment sortation and parcel distribution. Automated facilities in Poland and Czech Republic specify low-noise constructions to meet local occupational exposure limits.
Mining commands the highest per-meter pricing, while warehousing installations are expanding most quickly as fulfillment automation penetrates secondary European logistics hubs.
Material:
Raw material sourcing geography and polymer price volatility create margin pressure points that vary by belt chemistry and captive supply arrangements.
- Rubber:Natural and synthetic elastomer compounds including SBR, NBR, EPDM, and chloroprene. Natural rubber price swings in Thai and Indonesian spot markets transmit directly to compound costs for non-integrated manufacturers.
- PVC:Plasticized polyvinyl chloride with fire-retardant additives for underground mining. ECHA restrictions on short-chain chlorinated paraffins are forcing phosphate-ester plasticizer migrations in Polish coal operations.
- Metal:Carbon steel, stainless steel, and specialty alloys in wire mesh and solid plate constructions. High-temperature baking and heat treatment applications in Turkey's cement sector sustain niche demand.
- Fabric:Polyester, nylon, and aramid textile reinforcements in multi-ply carcass constructions. Aramid fiber substitution is reducing belt weight in German overland conveying projects.
Rubber formulations retain volume leadership, with aramid-reinforced fabric constructions gaining share fastest as power consumption becomes a tender evaluation criterion.
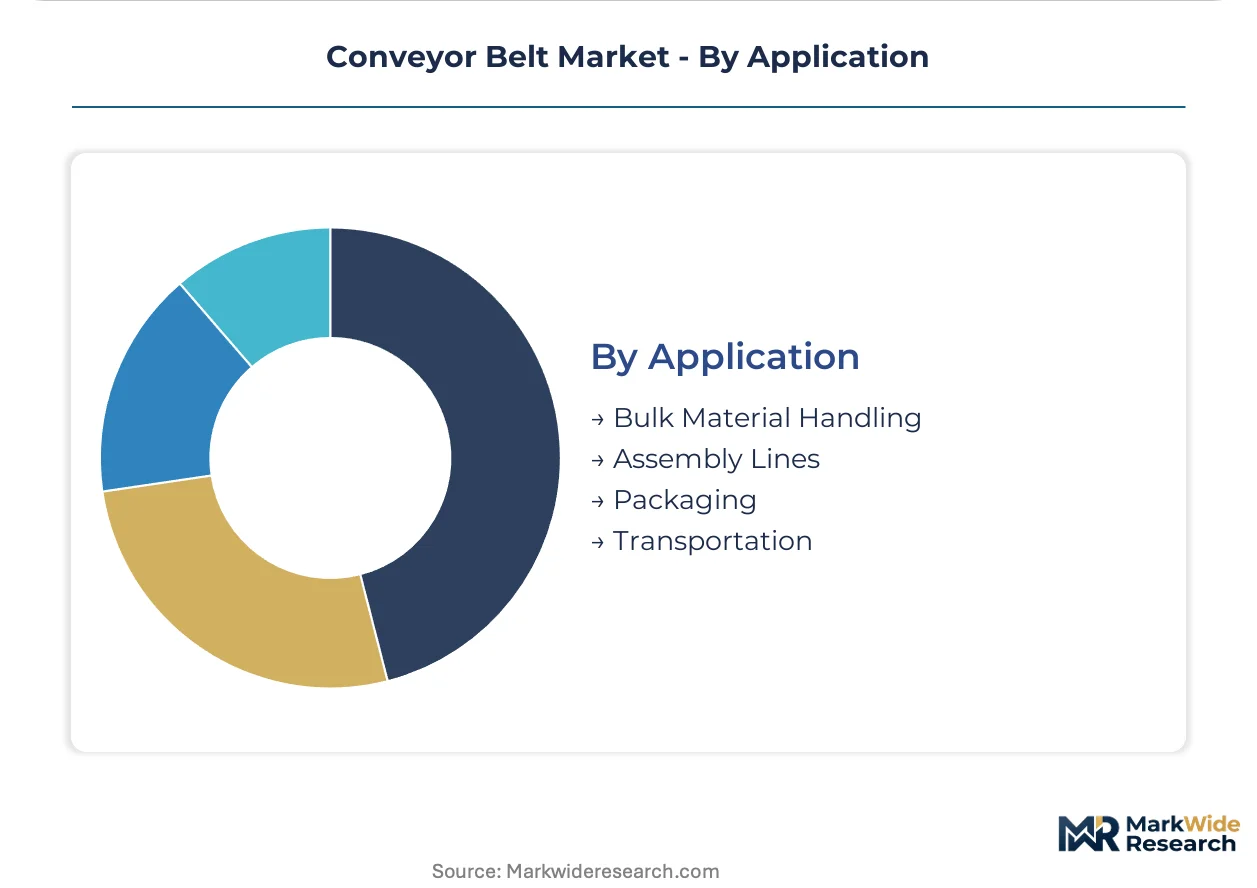
Application:
Load characteristics and duty cycles determine belt specification intensity, with continuous heavy-haul operations requiring fundamentally different architectures than intermittent packaging lines.
- Bulk Material Handling:Continuous transport of ores, aggregates, grains, and coal over extended distances. Brazilian iron ore export terminals specify steel-cord constructions with 10,000+ N/mm ratings for kilometer-length overland systems.
- Assembly Lines:Synchronized work-piece transport with precise speed control and indexing. German automotive OEMs specify low-stretch constructions to maintain tight tolerances in robotic welding cells.
- Packaging:Case, carton, and unit handling in secondary and tertiary packaging operations. Pharmaceutical serialization requirements in Italy are driving demand for track-and-trace compatible conveying surfaces.
- Transportation:Airport baggage handling and parcel sortation in logistics hubs. TSA screening integration in US airports specifies X-ray transparent belt constructions with specific attenuation properties.
Bulk material handling dominates installed base value, with packaging applications showing the steepest expansion trajectory as e-commerce fulfillment infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's Pilbara mining corridor generates replacement demand for heat-resistant steel-cord belts, while China's Shandong province concentrates half of global fabric-ply capacity. This geographic split between raw material supply and heavy-haul consumption shapes regional trade flows.
United States
OSHA machine-guarding mandates drive pulley enclosure specifications across automotive assembly plants in Michigan and Ohio. The Detroit-Windsor corridor sustains demand for oil-resistant NBR compounds in powertrain manufacturing. E-commerce fulfillment hubs in Pennsylvania and Texas specify low-noise constructions to meet local occupational exposure limits.
Germany
EU CSRD supply chain disclosure requirements are creating premium positioning for belt makers with certified recycled-content programs. The Ruhr industrial basin anchors demand for aramid-reinforced overland conveying in cement clinker applications. REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing phosphate-ester plasticizer migrations in underground mining belts.
China
GB standards enforce flame-resistance ratings for underground mining applications across Shanxi and Inner Mongolia coal basins. The Yangtze River Delta concentrates bulk port terminal automation projects deploying ultrasonic splicing technologies. Shandong and Jiangsu provinces host over half of global multi-ply fabric capacity, creating single-source vulnerability for belt producers elsewhere.
Australia
Pilbara iron ore operations generate sustained replacement demand for abrasion-resistant top covers rated above 10,000 N/mm tensile strength. The country's national mining regulator mandates emergency stop and guarding standards that shape belt system design in remote corridors. Perth-based service hubs coordinate predictive maintenance contracts across the northwest mining belt.
Brazil
Iron ore export terminals in Pará specify steel-cord constructions for kilometer-length overland systems handling 5000+ t/h loads. ANVISA food-contact regulations parallel EU migration limits for plasticized belts in soy and sugar processing. The São Paulo industrial corridor drives demand for modular belt sanitization systems in dairy and ready-meal operations.
Conveyor Belt Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals commanding premium positioning in mining and food processing while regional fabricators compete on price in light manufacturing. The vendor base organizes into three tiers: full-service providers with captive compounding, specialized splicing contractors, and commodity fabricators serving replacement markets. Consolidation pressure is concentrating share among players with backward integration into polymer production and certified service networks. Geographic expansion and predictive maintenance platform development represent the dominant competitive vectors.
Among German-origin industrials, Continental AG exemplifies the full-service archetype with integrated compounding and global service networks. Swiss-listed Habasit AG occupies a specialist position in hygienic conveying applications. Japanese manufacturer Bando Chemical Industries represents the precision-focused tier serving automotive and electronics assembly markets. These three entities anchor distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Bando Chemical Industries |
| Intralox |
| Continental AG |
| Volta Belting Technology |
| Interroll |
| Daifuku |
| Fenner |
| Habasit AG |
| Fives Group |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap compounders in Shandong province anchor pricing discipline through captive fabric-ply production, while private-equity-rolled-up service networks in Australia extract aftermarket premiums from remote mining corridors. This ownership fragmentation creates divergent pricing power across equipment sales and maintenance contracts.
Pricing Analysis
Capacity additions in Shandong and Jiangsu provinces are reshaping price floors for standard multi-ply fabric belts, compressing margins for non-integrated European and North American producers. Three-tier pricing structure across premium, standard, and economy levels separates aramid-reinforced overland constructions from commodity fabric-ply belts and PVC-based underground mining grades. Price differentiation hinges on certification tier—REACH-compliant TPU formulations command 15-20% premiums over legacy PVC in European food processing. Cost compression in commodity rubber grades is intensifying because Thai and Indonesian latex spot volatility transmits directly to compound costs. Warehousing and light manufacturing buyers exhibit highest price sensitivity, while Pilbara iron ore operators prioritize abrasion resistance and field service response over per-meter pricing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale mining and automotive buyer demand, while specialized splicing contractors serve fragmented procurement in Brazilian iron ore and Chilean copper operations. Geographic supply concentration centers on China for fabric-ply carcasses, Thailand and Indonesia for natural rubber latex, and Germany for aramid fiber reinforcement. Raw material dependencies draw from carbon black, synthetic rubber polymers, and phosphate-ester plasticizers migrating into REACH-compliant PVC formulations. Single-source vulnerability pervades Shandong's dominance in multi-ply fabric capacity, exposing non-Chinese belt producers to logistics disruption and input rationing during regional industrial policy shifts. Distribution runs through captive service networks for integrated multinationals and independent distributors for replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The conveyor belt market functions as a stable compounder anchored by replacement-driven mining demand and regulatory-mandated formulation upgrades across food processing and underground safety applications.
For Market Incumbents: Anchor defensive positioning through backward integration into aramid fiber compounding and certified splicing technician academies in Perth and Calgary. Consolidate predictive maintenance platforms to offset procurement unbundling by Brazilian and Chilean mining operators. Prioritize REACH Annex XVII pre-compliance for phosphate-ester plasticizer systems ahead of 2025 enforcement windows.
For New Entrants and Emerging Players: Begin with Indonesian palm oil processing corridors in Kalimantan, where heat-resistant oil-resistant compound expertise faces minimal local competition. Target EU CSRD-driven premium positioning for carbon-accounted belt logistics and certified recycled-content programs. Establish service-hub partnerships with regional plantation conglomerates rather than direct manufacturing investment.
For Investors and Strategic Acquirers: Industrial automation conglomerates with bulk material handling portfolios are the most active acquirer in this space, seeking predictive maintenance capabilities and geographic service density. Five-to-ten year viability rests on compound formulation IP and captive technician certification networks rather than manufacturing scale alone. Monitor ultrasonic splicing automation adoption rates as inflection indicator for labor-cost compression and field service margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive supply of aramid-reinforced compounds insulates Continental AG and Habasit AG from Thai latex volatility. |
| Predictive Maintenance Platform Deployment | IoT-enabled condition monitoring converts Fenner's Australian service contracts into recurring revenue streams. |
| REACH Pre-Compliance Formulation Migration | Phosphate-ester plasticizer validation secures Polish and Romanian coal mining access ahead of Annex XVII deadlines. |
| Regional Service Hub Establishment | Perth-based coordination centers capture Pilbara replacement cycles with sub-48-hour field response commitments. |
| Certified Technician Academy Investment | Hot-splice certification programs in North America address retirement-rate gaps delaying critical infrastructure timelines. |
Methodological Framework
Coverage spans Australia, Germany, China, Brazil, and the United States, with primary inputs from each mining and manufacturing cluster. The approach combines structured interviews with maintenance directors at Pilbara iron ore operations, procurement leads at German automotive OEMs, aftermarket service heads at bulk port terminals, and technical R&D directors at compound formulation facilities. Secondary validation draws from customs and trade data, SEC filings of listed belt manufacturers, ECHA regulatory submission databases, and Australian mining safety regulator incident reports. Bottom-up belt volume estimates triangulate against top-down bulk material handling capital expenditure projections.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include polymer chemistry, tensile architecture, end-use industry, and regional regulatory compliance tier. CAGRs derive from installed base replacement cycles, capacity expansion pipelines, and formulation upgrade mandates. Industry-specific forecast inputs incorporate natural rubber futures curves, mining production forecasts from Australian Bureau of Statistics, and EU CSRD disclosure timeline assumptions.
Several conditions sit outside the modeled scope, including force majeure disruptions to Thai latex supply, abrupt changes to Chinese industrial capacity policy, and unanticipated REACH substance restrictions beyond short-chain chlorinated paraffins. Forecasts reflect assumptions about technician training pipeline recovery, splicing automation adoption curves, and maintenance contract renewal rates in remote mining corridors. Periodic stress-testing of base assumptions is recommended against natural rubber price volatility bands and regulatory enforcement intensity scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Hook Loader Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Steel Coil Handling Equipment Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Rotating Fork Clamp Market
Material Handling Equipment
Loading Platform Canopies Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Coal Handling Equipment Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Global Automatic Palletizer and Depalletizer Market
Material Handling Equipment
Rolling Mill Machine Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Precision Gearbox Machinery Market