
 Global Refrigeration Lubricants Market | 2026-2036
Global Refrigeration Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Refrigeration Lubricants Market Intelligence
Formulation development for synthetic lubricants is rewriting the competitive landscape for traditional mineral oil suppliers. BASF SE leverages its chemical synthesis expertise to produce advanced Polyol Ester (POE) lubricants compatible with next-generation refrigerants. Idemitsu Kosan Co. Ltd. specializes in developing high-performance Polyalkylene Glycol (PAG) oils for CO2 refrigerant systems. ExxonMobil Corporation sustains a broad portfolio covering both synthetic and mineral-based products to serve diverse equipment needs across the globe.
Refrigeration lubricants are specialized fluids designed to lubricate compressors in refrigeration and air conditioning systems. These oils must exhibit high thermal stability, low pour points, and chemical compatibility with specific refrigerants like HFCs, HFOs, or natural refrigerants such as ammonia and CO2. Synthetic oils like Polyol Esters (POE) command a premium and are gaining share over traditional mineral oils. In application, the commercial refrigeration and industrial chillers segments drive significant volume, while aftermarket service providers represent a key channel for replacement sales.
Regulations such as the EU's F-Gas Regulation and the US EPA's SNAP program mandate the phase-down of high-GWP refrigerants, directly influencing lubricant choice. In parallel, China's GB standards for energy efficiency in appliances push manufacturers toward optimized compressor and lubricant systems. Success for lubricant manufacturers now depends on their ability to align R&D pipelines with the evolving refrigerant landscape and regional regulatory timelines.
Market Dynamics
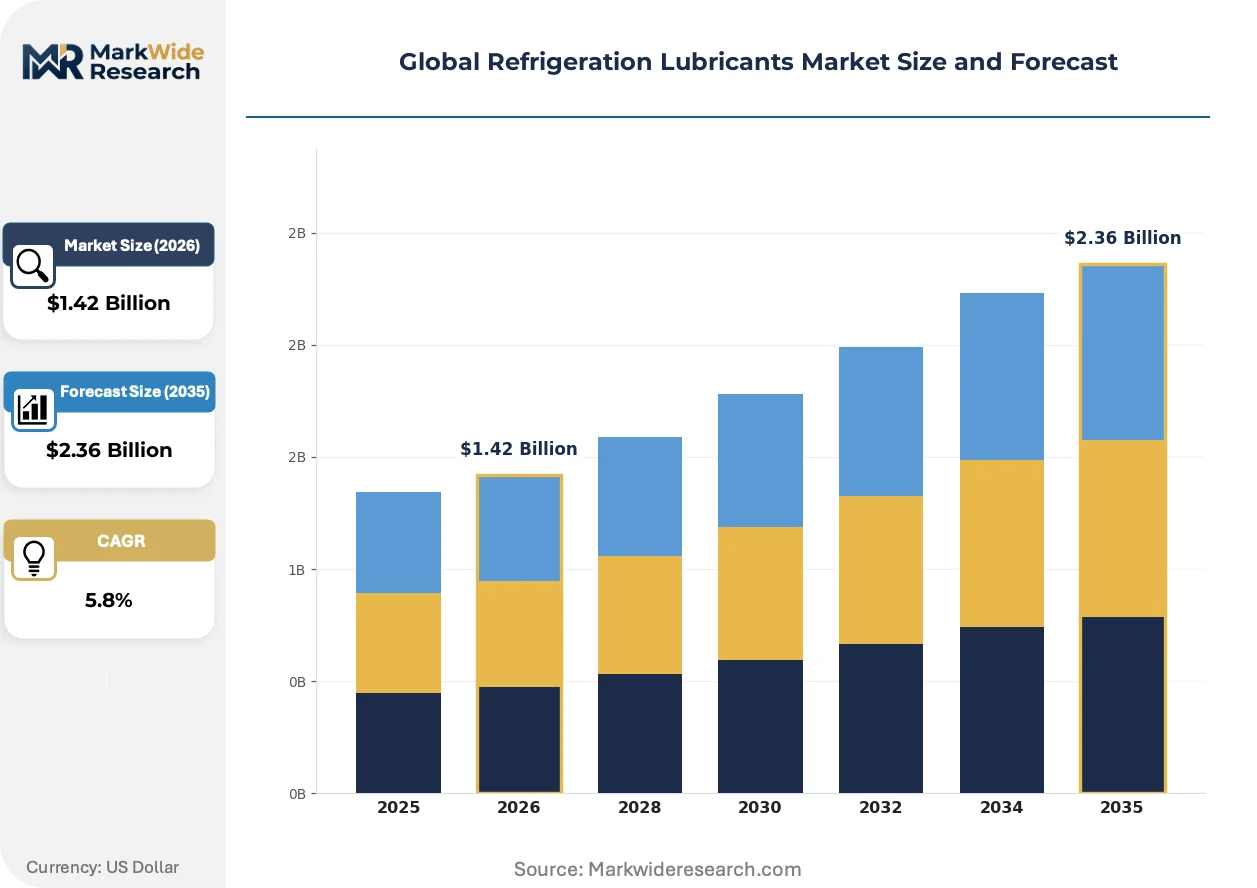
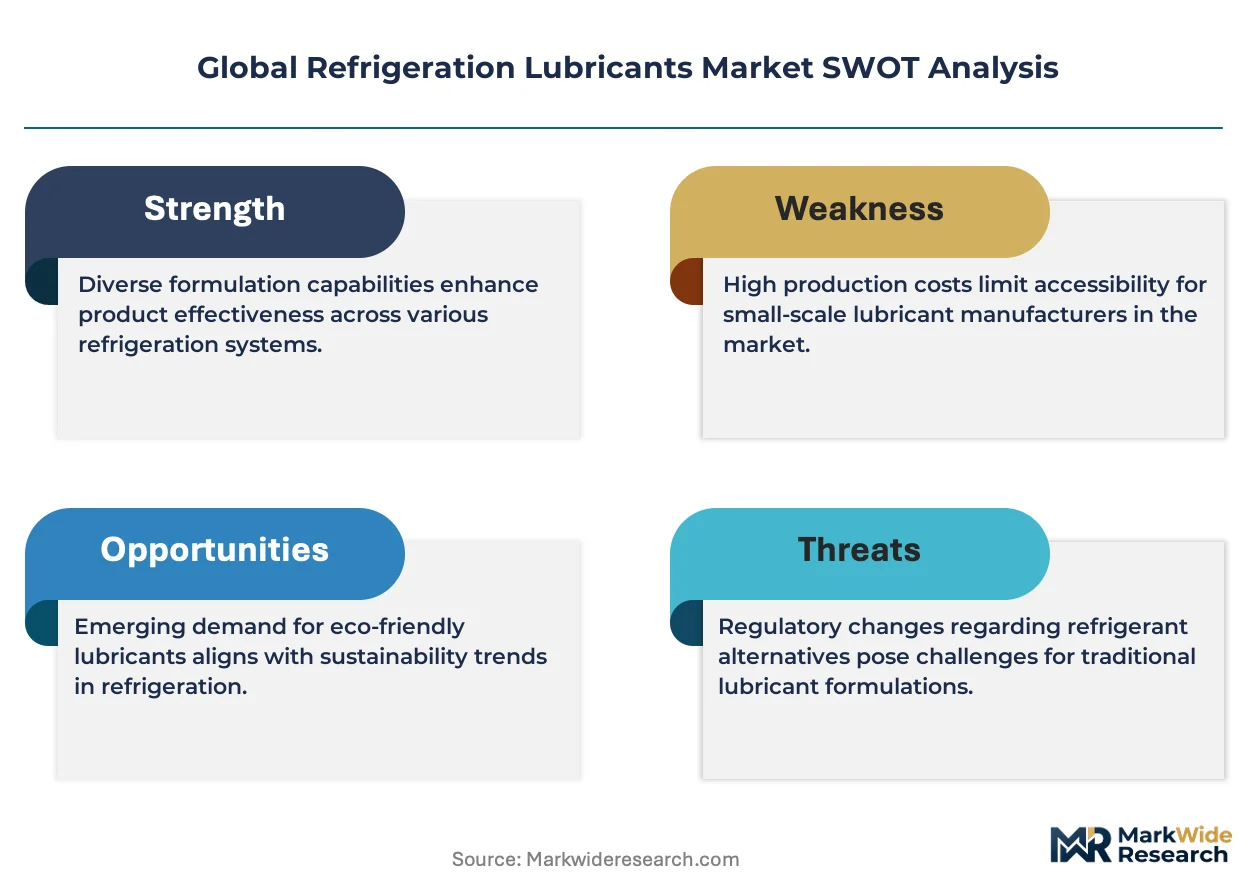
The global refrigeration lubricants market is defined by the compulsory technological pivot away from high-GWP refrigerants. This regulatory pressure, exemplified by mandates like the EU F-Gas Regulation, directly dictates lubricant formulation, creating a new basis of competition centered on chemical compatibility and system efficiency.
Growth Catalysts
- Cold Chain Expansion:The build-out of refrigerated warehousing and food processing infrastructure, particularly for perishable goods, creates sustained demand for high-performance lubricants in commercial and industrial refrigeration systems.
- Regulatory Mandates:Phasedown schedules for HFCs under frameworks like the US EPA's SNAP program and the Kigali Amendment compel equipment owners to adopt low-GWP alternatives like HFOs and natural refrigerants, which require new synthetic lubricants.
- HVACR Manufacturing in China:The country's role as a major production hub for air conditioning and refrigeration equipment generates significant first-fill lubricant volume, with GB standards for energy efficiency further influencing lubricant selection.
Market Restraints
- Input Cost Volatility:The price of synthetic base stocks, particularly polyol esters (POEs), is subject to fluctuations in chemical precursor markets, creating margin pressure for lubricant formulators.
- Technical Compatibility Hurdles:Ensuring miscibility, stability, and proper oil return with new HFO blends and natural refrigerants like CO2 across wide operating temperatures remains a significant formulation challenge.
- Oil-Free Compressor Technology:The emergence of oil-free compressors, such as magnetic bearing centrifugal chillers, presents a long-term substitution threat by eliminating the need for lubrication in certain high-end applications.
Strategic Opportunities
- Aftermarket Retrofit Services:A substantial opportunity exists in servicing the vast installed base of older HVACR systems being retrofitted from phased-out refrigerants to compliant alternatives, creating demand for specialized retrofit lubricants.
- Ultra-Low Temperature Applications:The growing biopharmaceutical and life sciences sectors require specialized lubricants for cryogenic and ultra-low temperature freezers used in vaccine and sample storage.
- Biodegradable Formulations:Developing lubricants with enhanced biodegradability offers a path to meet corporate sustainability mandates and differentiate products in environmentally sensitive applications or regions with stricter disposal rules.
Industry Challenges
- OEM Qualification Timelines:The lengthy and rigorous testing and approval process required by compressor and system OEMs for new lubricant formulations can delay market entry and increase R&D costs significantly.
- Field Service Skill Gaps:The hygroscopic nature of synthetic POE and PAG oils requires stricter handling procedures than traditional mineral oils, posing a training challenge for the fragmented base of field service technicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Refrigeration Lubricants Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyol Ester, Mineral Oil, Alkylbenzene, Polyalkylene Glycol, Silicone Oil Application: Domestic Refrigerators, Commercial Refrigeration, Air Conditioning Units, Industrial Chillers, Heat Pumps End User: OEM Manufacturers, Aftermarket Service Providers, HVAC Contractors, Cold Storage Facilities, Food Processing Plants Deployment: Hermetic Compressors, Semi-Hermetic Compressors, Open Drive Compressors, Scroll Compressors, Rotary Compressors |
| Companies Covered | ExxonMobil Corporation, Shell PLC, FUCHS, Idemitsu Kosan Co. Ltd., PETRONAS Lubricants International, Chevron Corporation, BASF SE, BP PLC, TotalEnergies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Refrigeration Lubricants Market Strategic Shifts & Innovations
Lubricant formulation is evolving from a standalone chemical discipline into an integrated component of system-level design. This shift is driven by the simultaneous pressures of regulatory compliance for refrigerants and OEM demands for greater energy efficiency and equipment reliability.
Digital twin modeling allows for the simulation of lubricant-refrigerant interactions under diverse operating conditions. Compressor and system original equipment manufacturers are adopting this approach to shorten research and development cycles. This technology is virtualizing the time-intensive process of physical prototyping and empirical compatibility testing, enabling faster innovation.
Continued phasedowns under the EU's F-Gas Regulation are accelerating the transition away from mid-GWP HFCs toward ultra-low GWP alternatives like HFOs and natural refrigerants. This forces equipment manufacturers to redesign systems, directly impacting lubricant choice to ensure reliability and performance. The commercial refrigeration and mobile air conditioning sectors are most affected, driving R&D in POE and PAG lubricant compatibility.
Consolidation of lubricant specification authority with equipment OEMs is altering purchasing behavior. This trend displaces lubricant selection from end-users or service contractors toward a factory-fill or OEM-approved model tied to extended warranties. This pattern is most visible in the data center cooling and industrial process chilling segments, where system uptime is critical.
Global Refrigeration Lubricants Market Segmentation
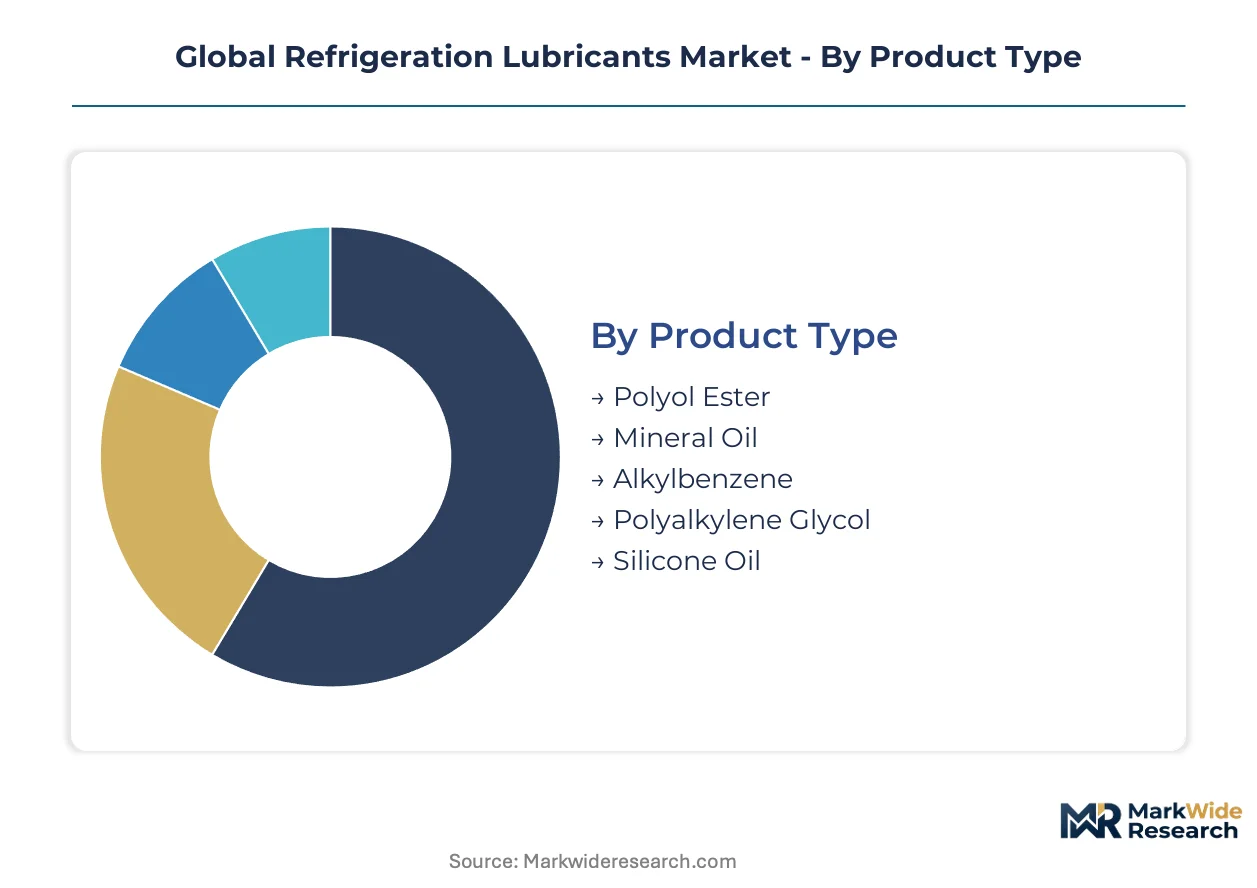
Segmentation within the global refrigeration lubricants market illuminates how specialized fluid requirements align with diverse equipment types and regulatory shifts. Understanding these distinct market slices enables lubricant manufacturers to strategically develop and position products for optimal compatibility and performance across the refrigeration and air conditioning ecosystem.
Product Type:
The intensity of after-sales service requirements often dictates the lubricant product type specified for maintenance and retrofits.
- Polyol Ester (POE):These synthetic oils exhibit excellent thermal stability and miscibility with HFCs and HFOs, making them critical for modern systems. Demand concentrates in commercial refrigeration and air conditioning, driven by the EU F-Gas Regulation and US EPA SNAP program.
- Polyalkylene Glycol (PAG):High-performance synthetic lubricants specifically formulated for CO2 (R-744) refrigerant systems, offering superior lubricity and thermal properties. The automotive air conditioning and industrial chiller sectors increasingly adopt PAGs for their efficiency with natural refrigerants.
- Mineral Oil:Traditional lubricants with good compatibility for HCFCs and ammonia, still widely used in older systems and some industrial applications due to cost-effectiveness.
- Alkylbenzene:Synthetic oils often blended with mineral oils to enhance miscibility with HCFCs and some HFCs, valued for their stability in specific retrofitting scenarios.
- Silicone Oil:Specialized lubricants used in niche, high-temperature applications or where extreme chemical inertness is required, often in very specific industrial processes.
By volume, Mineral Oil leads. By growth pace, Polyol Ester is ahead.
Application:
Application-specific performance demands and operating conditions significantly influence the selection of refrigeration lubricants.
- Commercial Refrigeration:Encompasses supermarket display cases, cold rooms, and food service equipment, demanding lubricants compatible with low-GWP refrigerants and capable of wide temperature ranges. Demand is concentrating in China due to expanding cold chain infrastructure.
- Air Conditioning Units:Includes residential, commercial, and automotive AC systems, requiring lubricants optimized for energy efficiency and compatibility with HFCs and HFOs. The US and European markets drive innovation for compliant, high-performance AC lubricants.
- Domestic Refrigerators:Utilizes lubricants designed for long-term reliability and energy efficiency in hermetic compressors, often with HFCs or isobutane.
- Industrial Chillers:Large-scale systems for process cooling, requiring robust lubricants for high-capacity compressors and diverse refrigerants like ammonia.
- Heat Pumps:Emerging segment needing lubricants compatible with various refrigerants and capable of efficient operation in both heating and cooling cycles, driven by energy efficiency mandates.
The commercial refrigeration sector drives significant lubricant volume, while heat pumps exhibit the steepest expansion trajectory.
End User:
Procurement patterns for refrigeration lubricants vary significantly across different end-user types.
- OEM Manufacturers:Compressor and system original equipment manufacturers select lubricants for factory-fill, prioritizing long-term reliability and energy efficiency to meet warranty requirements. This segment is concentrating in China due to its dominant HVACR manufacturing base.
- Aftermarket Service Providers:Technicians and companies performing maintenance, repair, and retrofit services, requiring a broad portfolio of compatible lubricants for diverse installed systems. This segment offers substantial opportunity for specialized retrofit formulations in Europe and North America.
- HVAC Contractors:Install and maintain air conditioning and refrigeration systems, often sourcing lubricants based on equipment specifications and local availability.
- Cold Storage Facilities:Large-scale refrigerated warehouses requiring lubricants for industrial compressors, with a focus on system uptime and efficiency.
- Food Processing Plants:Utilize refrigeration lubricants in equipment for food preservation, demanding high standards of safety and operational reliability.
OEM manufacturers dictate initial lubricant specifications, while aftermarket service providers ensure sustained consumption through maintenance and retrofits.
Deployment:
Compressor design and operating principles fundamentally determine the specific lubrication requirements.
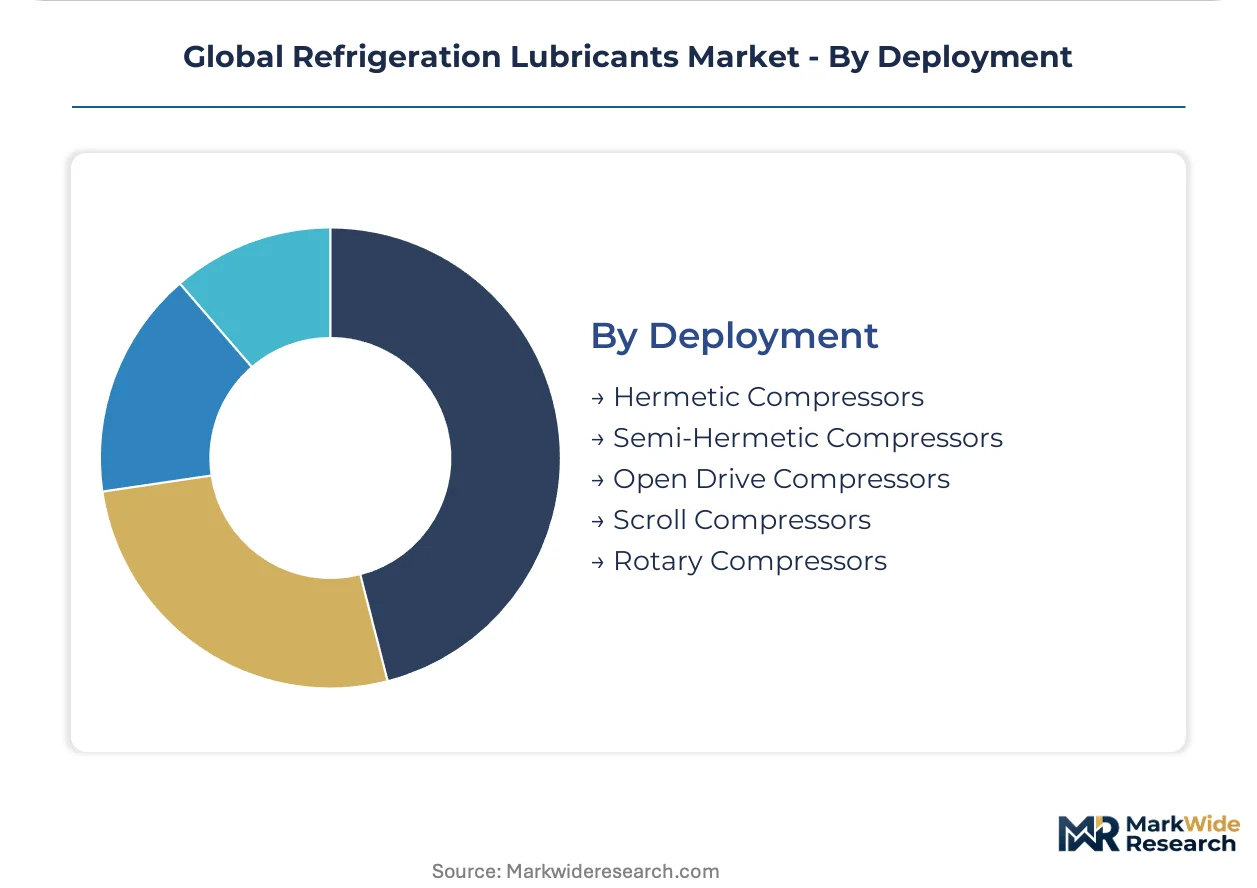
- Hermetic Compressors:Fully enclosed units where the motor and compressor operate within the refrigerant atmosphere, demanding lubricants with excellent chemical stability and dielectric properties. Domestic refrigerators and smaller AC units primarily use these compressors.
- Scroll Compressors:Known for their high efficiency and quiet operation, these compressors are widely used in residential and light commercial air conditioning systems. Lubricants for scroll compressors must maintain viscosity and film strength across varying load conditions.
- Semi-Hermetic Compressors:Allow for servicing of the motor and compressor, used in commercial refrigeration and industrial applications, requiring robust lubricant performance.
- Open Drive Compressors:Driven by external motors, these compressors are common in large industrial refrigeration systems and allow for flexible lubricant selection.
- Rotary Compressors:Compact and efficient, frequently found in domestic air conditioners and heat pumps, needing lubricants that ensure smooth operation and sealing.
Hermetic and scroll compressors collectively account for the largest lubricant volumes, while open drive compressors offer greater flexibility in lubricant choice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
In the global refrigeration lubricants market, demand elasticity varies; industrial and commercial sectors prioritize performance and regulatory compliance, while some aftermarket segments remain more price-sensitive. Low-GWP refrigerant transitions compel high-value lubricant adoption in developed economies. Developing markets balance cost-effectiveness with emerging efficiency standards.
China
China's expanding cold chain infrastructure and its position as a major HVACR manufacturing hub create substantial lubricant demand. GB standards for energy efficiency influence lubricant selection for new equipment. The Yangtze River Delta region drives significant first-fill lubricant volume for appliance production.
United States
United States demand stems from HFC phasedown and continuous cold storage expansion. The US EPA's SNAP program mandates low-GWP refrigerant alternatives, necessitating new lubricant formulations. California often leads in adopting HFO-compatible lubricants due to stringent environmental regulations.
Germany
Germany's market is shaped by strict EU F-Gas Regulation and its robust industrial refrigeration sector. This framework accelerates transition to low-GWP refrigerants, increasing demand for advanced synthetic lubricants. Bavaria's strong manufacturing base drives significant demand for high-performance PAG and POE lubricants.
India
India's market growth is propelled by rapid urbanization, a burgeoning food processing sector, and rising air conditioning demand. The Bureau of Indian Standards (BIS) promotes energy-efficient appliances, influencing lubricant specifications. Maharashtra shows increasing lubricant consumption in its expanding cold storage and food processing facilities.
Japan
Japan focuses on energy efficiency mandates and natural refrigerant adoption in advanced HVACR systems. METI's efficiency targets push manufacturers towards optimized compressor and lubricant pairings. The Kanto region drives demand for specialized lubricants in high-efficiency commercial refrigeration and heat pump applications.
Global Refrigeration Lubricants Market Key Industry Players
Capability concentration sits with specialized chemical companies; scale advantage sits with integrated oil and gas majors. The refrigeration lubricants market exhibits a tiered structure, with a few large players dominating base stock production and numerous smaller formulators offering niche solutions. Strategic archetypes include diversified energy companies, chemical specialists, and regional lubricant blenders. Companies primarily engage in strategic partnerships for R&D and portfolio diversification to adapt to new refrigerant requirements.
Within the diversified energy major archetype, ExxonMobil Corporation maintains a broad portfolio covering synthetic and mineral-based products for diverse equipment needs. Idemitsu Kosan Co. Ltd. exemplifies specialization, focusing on high-performance Polyalkylene Glycol (PAG) oils for CO2 refrigerant systems. BASF SE, a chemical synthesis expert, anchors the advanced materials segment, producing advanced Polyol Ester (POE) lubricants compatible with next-generation refrigerants. These companies actively align their R&D pipelines with evolving refrigerant landscapes and regional regulatory timelines.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell PLC |
| FUCHS |
| Idemitsu Kosan Co. Ltd. |
| PETRONAS Lubricants International |
| Chevron Corporation |
| BASF SE |
| BP PLC |
| TotalEnergies |
| Others |
Cost & Logistics Intelligence
Global shipping lanes for base stocks dictate cost dynamics, influencing synthetic lubricant supply concentration and downstream price differentiation across regions.
Pricing Analysis
Long-term offtake agreements characterize pricing for factory-fill volumes with OEM manufacturers. Price differentiation stems from lubricant quality grades, such as premium synthetic POEs, and specific OEM qualification. Pricing softness runs through the aftermarket segment due to intense competition among blenders and service providers. Aftermarket service providers exhibit higher price sensitivity compared to OEM manufacturers who prioritize system reliability and warranty compliance.
Supply Chain Analysis
Extended payment terms are common in the refrigeration lubricant supply chain, particularly for smaller blenders sourcing specialized synthetic base stocks. Geographic supply for key chemical precursors concentrates in China and Germany. The market draws from diverse base oils, including polyols and glycols, which are susceptible to commodity price volatility. Distribution runs through direct channels to OEM manufacturers and specialized chemical distributors for aftermarket service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refrigeration lubricants market presents a significant service-attach opportunity. Aftermarket retrofit services, driven by refrigerant phasedowns, expand faster than initial equipment sales, creating recurring revenue streams for specialized formulators.
For Market Incumbents:Entrench market share by deepening R&D collaboration with compressor and system OEMs for next-generation refrigerant compatibility. Invest in advanced testing facilities to accelerate OEM qualification timelines, countering the threat of oil-free compressor technology. Consolidate regional distribution networks to enhance service delivery, leveraging existing customer relationships. Focus R&D on high-performance POE and PAG formulations to maintain leadership against emerging niche players.
For New Entrants and Emerging Players:Establish a beachhead in the ultra-low temperature applications segment, targeting biopharmaceutical and life sciences sectors. The aftermarket retrofit services in Europe and North America represent a penetrable segment for specialized formulations. Develop biodegradable lubricant solutions to meet corporate sustainability mandates, differentiating products in environmentally sensitive applications. A go-to-market angle involves providing comprehensive technical support and training for field service technicians.
For Investors and Strategic Acquirers:The EU F-Gas Regulation and US EPA SNAP program reshape the acquisition landscape for refrigeration lubricant manufacturers. Long-term viability hinges on expertise in synthetic lubricant formulation and OEM qualification, crucial over the next decade. Target acquisition archetypes include specialized chemical companies with patented POE or PAG technologies. A signal to watch is the acceleration of HFO and natural refrigerant adoption rates in commercial refrigeration systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen OEM R&D Partnerships | Ensures lubricant compatibility with new compressor designs and low-GWP refrigerants. |
| Expand Aftermarket Retrofit Portfolio | Captures demand from older HVACR systems transitioning to compliant refrigerant alternatives. |
| Invest in Biodegradable Formulations | Differentiates products and meets corporate sustainability goals in environmentally sensitive markets. |
| Accelerate OEM Qualification Processes | Shortens time-to-market for advanced synthetic lubricants, gaining competitive advantage. |
| Enhance Field Service Training Programs | Addresses skill gaps for handling hygroscopic synthetic oils, improving system reliability. |
Research Approach
The analysis maps synthetic lubricant formulations and application segments, each validated through extensive primary interviews with industry stakeholders. We engaged R&D directors, procurement leads at OEMs, aftermarket service managers, and cold storage facility operators. Secondary data sources included customs trade statistics, chemical industry reports, and energy efficiency standards from regulatory bodies like the EU. Bottom-up market sizing was triangulated with top-down validation against macroeconomic indicators.
Assumptions regarding refrigerant phase-down schedules and global cold chain expansion were held fixed, while input cost volatility was varied. The analytical framework modeled market dynamics across the analysis window, segmenting by product type, application, and end-user. Compound Annual Growth Rates were derived from historical trends and projected regulatory impacts. Key forecast inputs included regional HVACR manufacturing output and low-GWP refrigerant adoption rates.
Sensitivities concentrate around unforeseen shifts in regulatory timelines and the pace of new refrigerant technology commercialization. Forecasts reflect documented assumptions concerning market drivers and restraints, but remain subject to external influences. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Agricultural Lubricants Market
Lubricants
Saudi Arabia Automotive Engine Oils Market
Lubricants
Morocco Lubricants Market
Lubricants
Global Lubricants Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
Vietnam Lubricants Market
Lubricants
Polyurea-Based Greases Market
Lubricants
Saudi Arabia Commercial Vehicles Lubricants Market
Lubricants
Myanmar Lubricants Market
Lubricants
Global Finished Lubricant Market
Lubricants
South Korea Automotive Lubricants Market
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
Malaysia Lubricants Market
Lubricants
Global Independent Lubricant Manufacturers Market
Lubricants
Global Lubrication Systems Market
Lubricants
Iran Passenger Vehicles Lubricants Market