
 Morocco Lubricants Market | 2026-2036
Morocco Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Lubricants Market Foresight
Market Context with Strategic Players
Capital-intensity divergence between integrated blenders and import-reliant distributors is bifurcating competitive returns in Morocco. TotalEnergies leverages its coastal storage infrastructure and captive supply chain to dominate bulk industrial contracts. Shell anchors its position through a dense retail network spanning Casablanca, Rabat, and Tangier. Afriquia competes aggressively on price in the aftermarket segment, while Petromin Corporation sustains OEM relationships through technical service partnerships with European automakers assembling vehicles locally.
Technical Definition and Structural Segments
Lubricants in Morocco comprise formulated oils and greases engineered from base stocks blended with performance additives to reduce friction, dissipate heat, and prevent wear in mechanical systems. Engine oils typically operate across viscosity grades from 0W-20 to 20W-50, with additive packages containing detergents, dispersants, and anti-wear agents such as zinc dialkyldithiophosphate. Engine oils command the largest volume share given Morocco's expanding vehicle parc and commercial transport intensity. Synthetic and semi-synthetic base oils are gaining traction among fleet operators seeking extended drain intervals, while mineral oils retain cost-sensitive segments. Industrial applications in manufacturing and marine represent concentrated margin pools where technical specification compliance determines supplier selection.
Regulatory Framework and Forward Outlook
Morocco's Ministry of Energy Transition and Sustainable Development enforces fuel quality and lubricant performance standards aligned with European benchmarks, while the Moroccan Institute for Standardization (IMANOR) certifies product conformity under national norms. The National Energy Strategy and associated emission reduction commitments are tightening specifications for low-SAPS (sulfated ash, phosphorus, sulfur) formulations compatible with after-treatment systems. Stakeholders must monitor regulatory harmonization with EU REACH chemical restrictions and decide whether to localize blending capacity or maintain import dependence as specification complexity rises.
Market Dynamics
Fleet operators across Morocco's Casablanca-Settat corridor are consolidating lubricant procurement under long-term supply agreements, compressing spot-market volumes and rewarding blenders with captive storage infrastructure. This buyer concentration is restructuring competitive returns between integrated suppliers and import-dependent distributors.
Growth Catalysts
- Commercial Transport Intensification:Port logistics expansion at Tanger Med and Casablanca is extending heavy-duty vehicle operating hours, accelerating consumption of high-performance engine oils and driveline fluids.
- IMANOR Specification Upgrades:Morocco's national standardization institute is certifying lubricants against Euro VI-equivalent emission benchmarks, mandating low-SAPS formulations that command technical premiums from compliant blenders.
- Automotive Assembly Localization:European OEMs producing vehicles in Morocco's free trade zones are specifying factory-fill synthetic lubricants, creating anchored demand for Group III base oil formulations.
Market Restraints
- Base Oil Import Dependence:Morocco lacks domestic Group II/III base oil production, exposing blenders to freight cost volatility from Mediterranean and Middle Eastern refiners.
- Price Sensitivity in Aftermarket:Independent workshops and owner-operators in secondary cities prioritize mineral oil economics over extended-drain synthetics, compressing margin expansion in volume segments.
- Technical Service Requirements:Industrial marine and manufacturing accounts demand on-site fluid analysis and condition monitoring, capabilities concentrated among a limited supplier tier.
Strategic Opportunities
- Rural and Secondary City Penetration:Distribution networks in Meknes, Fes, and Oujda remain fragmented, offering first-mover advantage to blenders establishing localized stocking points.
- Renewable Energy Equipment Fluids:Wind turbine installations in the Tarfaya corridor and solar concentrated power plants require specialized gearbox and heat transfer fluids with limited local supply.
- Used Oil Collection Infrastructure:Morocco's National Energy Strategy targets circular economy integration, rewarding investments in re-refining capacity and reverse logistics networks.
Industry Challenges
- Additive Package Sourcing Complexity:Formulation chemistries compliant with simultaneous IMANOR, REACH, and OEM approvals require multi-source qualification timelines stretching 18-24 months.
- Skilled Blender Technician Scarcity:Compound blending and quality control functions demand trained personnel, with competition for talent intensifying from pharmaceutical and food processing sectors in the Casablanca-Settat zone.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Lubricants Market |
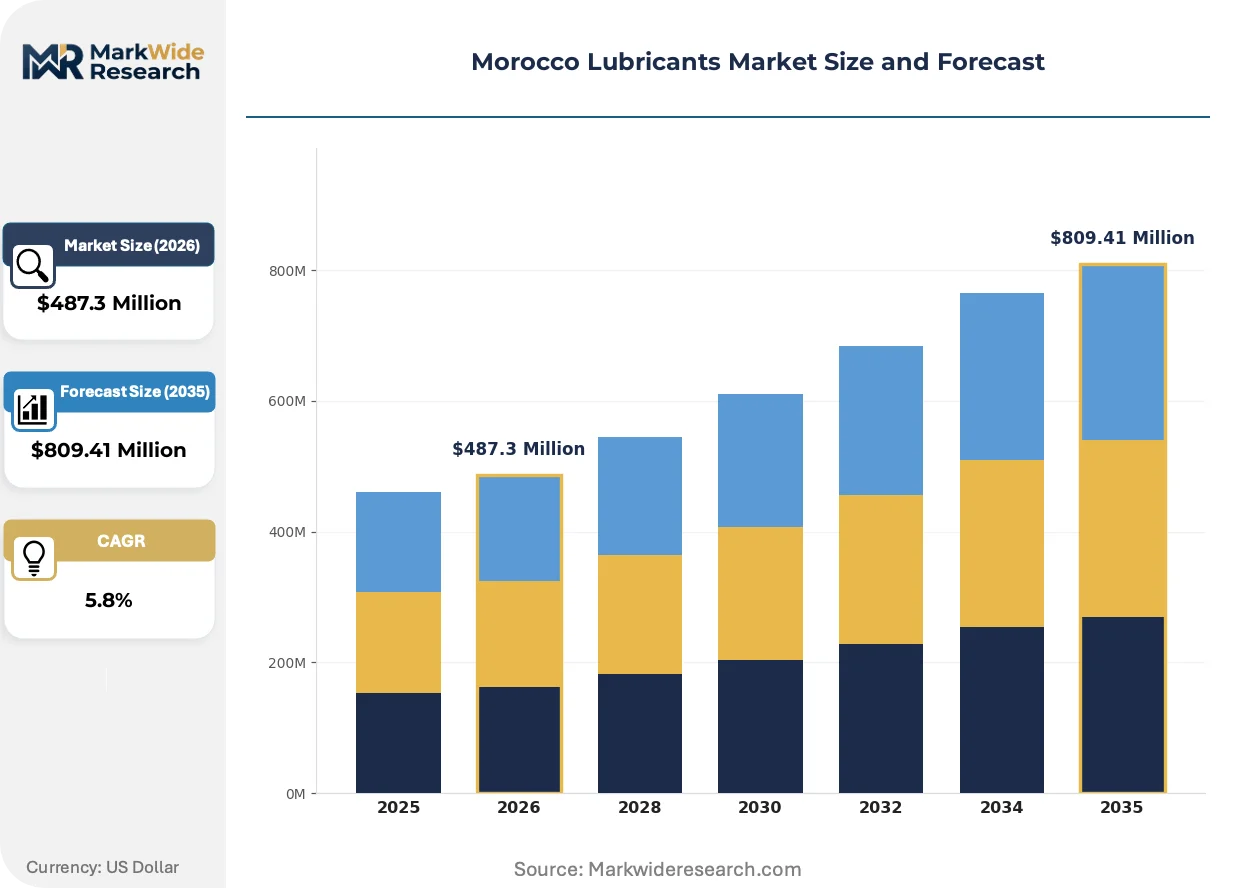
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Transmission Fluids, Industrial Oils, Greases Application: Automotive, Manufacturing, Marine, Agriculture Base Oil Type: Synthetic, Semi-synthetic, Mineral, Bio-based End User: OEMs, Aftermarket Suppliers, Industrial Plants, Fleet Operators |
| Companies Covered | FUCHS, OLA Energy, TotalEnergies, Petrom, Petromin Corporation, Afriquia, Motul, Ziz Lubrifiant, Shell, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Lubricants Market Shifts & Advancements
Synthetic base oil technology is advancing formulation performance beyond mineral oil economics, while regulatory alignment with European chemical frameworks is tightening compliance requirements. Distribution models are adapting to fleet procurement centralization.
Group III and PAO synthetic base oils are displacing Group I mineral stocks in heavy-duty fleet applications. Transport operators running Casablanca-Agadir corridors are adopting 15W-40 and 10W-40 synthetics to achieve 50,000+ kilometer drain intervals. This displacement is compressing demand for conventional mineral formulations in the highest-volume commercial segment.
IMANOR's harmonization with EU REACH chemical restrictions is restricting certain detergent and anti-wear additive chemistries. Blenders must reformulate legacy packages to eliminate specific sulfur and phosphorus compounds. Industrial accounts in phosphate processing and marine shipping are most affected, requiring accelerated re-qualification of hydraulic and cylinder oil specifications.
Fleet procurement centralization is consolidating purchasing authority within transport company headquarters. Spot buying through traditional distributors is yielding to direct supply agreements with integrated blenders. This pattern is most visible among refrigerated logistics operators serving the Tangier-Casablanca-Agadir axis, where total fluid cost management now supersedes per-liter pricing.
Morocco Lubricants Market Segmentation
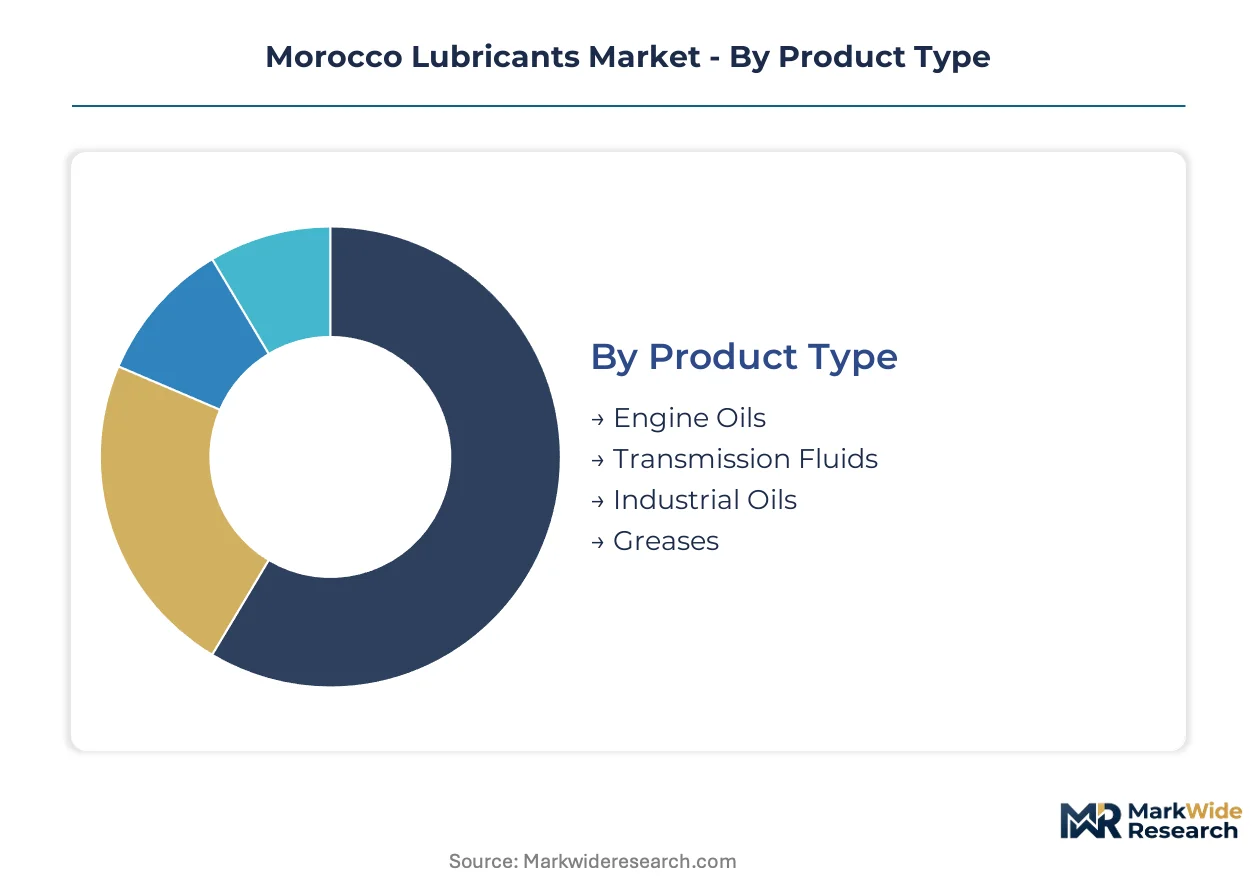
Lubricant purchasing patterns in Morocco fragment across technical specifications, procurement channels, and end-use intensity. Understanding these divisions reveals where formulation premiums command pricing power versus where volume throughput drives returns.
Product Type:
Marginal returns concentrate in industrial specialty formulations where technical compliance barriers limit supplier entry, while engine oils deliver volume scale through fleet and aftermarket channels.
- Engine Oils:Formulated across viscosity grades from 0W-20 to 20W-50 with detergent-dispersant additive packages including zinc dialkyldithiophosphate anti-wear agents. Demand clusters along the Casablanca-Settat corridor where commercial transport fleets operate extended duty cycles between Tanger Med port and Agadir logistics hubs. IMANOR certification against Euro VI-equivalent benchmarks is tightening specification compliance costs for non-integrated blenders.
- Industrial Oils:Hydraulic fluids, turbine oils, and compressor lubricants engineered for manufacturing and energy infrastructure applications. Morocco's phosphate processing facilities in Khouribga and Ben Guerir specify high-performance hydraulic formulations with advanced oxidation stability. Technical service partnerships with plant engineering teams create sticky supplier relationships resistant to price-based switching.
- Transmission Fluids:Automatic and manual gearbox lubricants with friction-modifier additive systems for synchronized shifting performance.
- Greases:Thickened lubricants for bearings, chassis, and open-gear applications in mining and construction equipment.
The dominant share belongs to Engine Oils, while Industrial Oils is closing the gap fastest.
Application:
Volume distribution tracks Morocco's economic geography, with coastal logistics corridors generating disproportionate fluid consumption relative to interior agricultural zones.
- Automotive:Light-duty passenger vehicles and heavy-duty commercial trucks operating on Morocco's developing motorway network. European OEM assembly plants in Tangier Free Zone and Kenitra specify factory-fill synthetic formulations, creating anchored demand for Group III base oil products. Extended drain interval adoption among fleet operators is accelerating synthetic displacement of mineral stocks.
- Manufacturing:Metalworking, plastics processing, and textile production facilities concentrated in Casablanca-Settat and Rabat-Sale-Kenitra regions. Fluid analysis and condition monitoring services differentiate supplier performance in this segment where unplanned downtime costs exceed lubricant expenditures.
- Marine:Cylinder oils and system lubricants for vessels calling at Tanger Med and Casablanca ports.
- Agriculture:Tractor hydraulic fluids and universal tractor oils for mechanized farming in Marrakech-Safi and Fes-Meknes regions.
Automotive absorbs the largest volume, though Manufacturing applications are expanding most quickly as industrial automation intensifies.
Base Oil Type:
Cost structure divergence between import-dependent synthetic stocks and mineral alternatives is reshaping competitive positioning among Moroccan blenders.
- Synthetic:Group III hydrocracked and PAO-based formulations delivering thermal stability and extended drain intervals. Fleet operators running refrigerated logistics on the Tangier-Casablanca-Agadir axis adopt 15W-40 and 10W-40 synthetics to achieve 50,000+ kilometer service intervals. Import dependence from Mediterranean and Middle Eastern refiners exposes pricing to freight cost volatility.
- Semi-synthetic:Blends combining Group I/II mineral bases with synthetic content for intermediate performance positioning.
- Mineral:Group I solvent-refined base oils serving price-sensitive owner-operators and independent workshops in secondary cities. Meknes, Fes, and Oujda distribution networks favor mineral economics where per-liter price sensitivity outweighs extended drain benefits.
- Bio-based:Vegetable oil-derived formulations for environmentally sensitive applications and government procurement preferences.
Synthetic holds the premium tier, yet Semi-synthetic is gaining share fastest as fleet operators balance performance requirements against total fluid cost management.
End User:
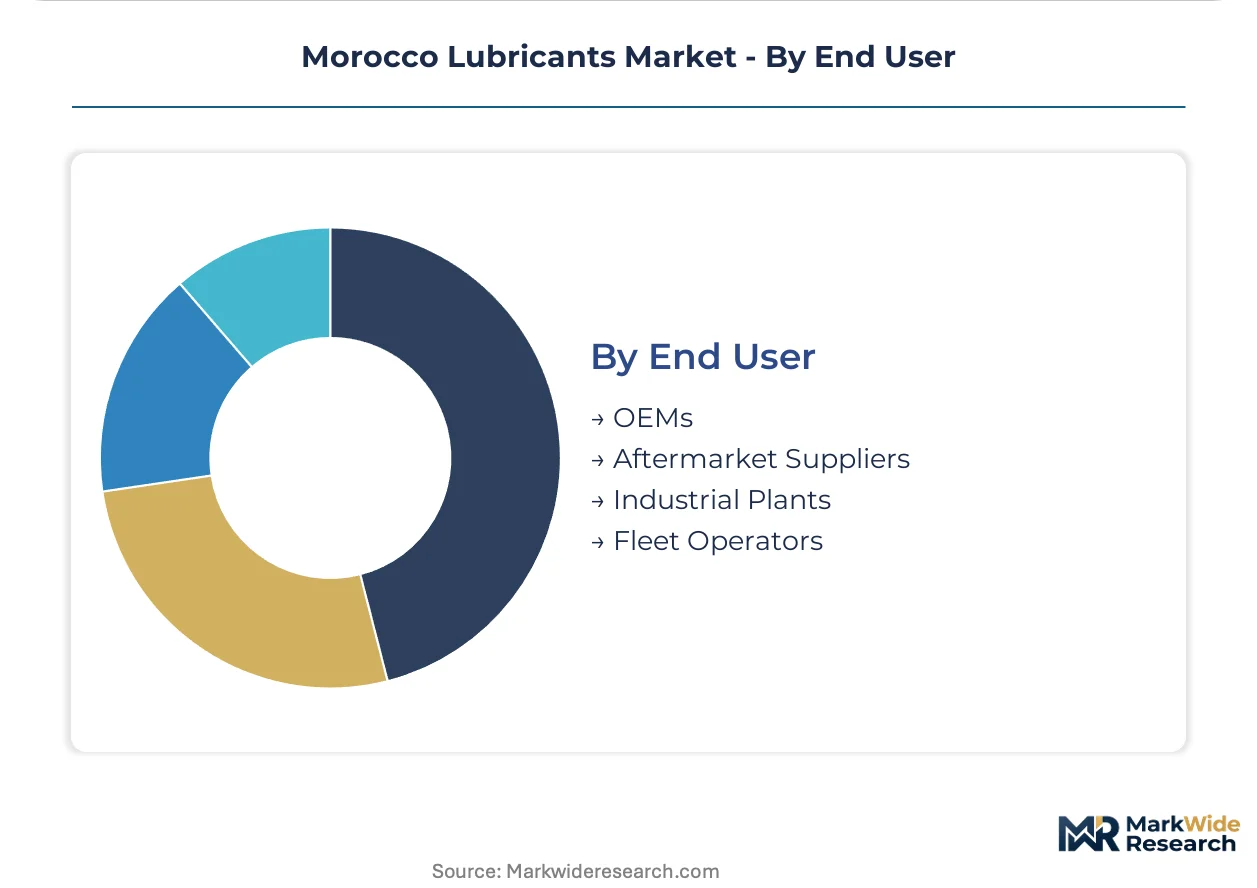
Procurement authority concentration among fleet headquarters and industrial procurement departments is compressing spot-market volumes and rewarding integrated suppliers with captive infrastructure.
- Fleet Operators:Commercial transport companies consolidating lubricant purchasing under long-term supply agreements with direct blender relationships. Refrigerated logistics and container haulage firms serving Tanger Med port operations specify total fluid management programs including bulk storage, scheduled delivery, and used oil collection.
- OEMs:European automakers assembling vehicles in Morocco's free trade zones specifying factory-fill and service-fill lubricant partnerships. Technical collaboration agreements with blender engineering teams support warranty compliance and brand positioning.
- Industrial Plants:Phosphate processing, cement manufacturing, and food production facilities with on-site bulk storage and condition monitoring requirements.
- Aftermarket Suppliers:Distributors serving independent workshops and retail channels with packaged lubricant products.
Fleet Operators command the largest procurement scale, while OEMs are tightening specification control fastest through factory-fill partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Casablanca-Settat corridor while secondary interior markets absorb compressed margins through fragmented distribution. This asymmetry reflects infrastructure density, fleet concentration, and regulatory enforcement gradients across Morocco's economic geography.
Casablanca-Settat
Industrial lubricant demand clusters around automotive assembly plants and phosphate processing facilities. The region operates under IMANOR certification requirements aligned with Euro VI-equivalent emission benchmarks. Port logistics at Casablanca generate heavy-duty fleet consumption of synthetic engine oils along the Tanger Med-Agadir transport axis.
Tangier-Tetouan-Al Hoceima
Free trade zone manufacturing anchors factory-fill lubricant specifications for European OEM operations. The National Energy Strategy drives low-SAPS formulation adoption across assembly plants. Tanger Med port expansion extends operating hours for container haulage fleets requiring extended-drain synthetic products.
Marrakech-Safi
Agricultural mechanization sustains demand for universal tractor oils and hydraulic fluids. Secondary city distribution networks favor mineral oil economics over synthetic premiums. Jorf Lasfar industrial zone phosphate processing creates concentrated demand for high-performance hydraulic formulations.
Fes-Meknes
Automotive component suppliers and textile manufacturing drive industrial lubricant procurement. Price-sensitive owner-operators in independent workshops prioritize conventional mineral stocks. Regional distribution fragmentation offers first-mover opportunity for localized stocking point establishment.
Rabat-Sale-Kenitra
Administrative capital concentration supports fleet operations for government and commercial transport. Manufacturing automation in Kenitra accelerates metalworking fluid and compressor oil demand. Technical service partnerships with industrial accounts differentiate supplier performance in this procurement segment.
Morocco Lubricants Market Competitive Landscape
Concentration sits with integrated blenders commanding captive storage infrastructure and direct fleet relationships. The competitive structure bifurcates between coastal-integrated suppliers and interior-dependent distributors. Three archetypes dominate: multinational energy majors with regional supply chains, North African regional blenders with price-focused aftermarket positioning, and specialized industrial formulators with technical service capabilities. Dominant competitive moves include backward integration into base oil sourcing networks and geographic expansion through secondary city distribution partnerships.
Within the integrated multinational tier, TotalEnergies and Shell exemplify coastal infrastructure leverage through bulk storage and direct fleet contracting. Afriquia occupies a position representing regional price-competitive positioning in aftermarket channels. Among specialized industrial formulators, FUCHS anchors the technical service archetype through phosphate processing and manufacturing plant relationships. Petromin Corporation sits within the OEM partnership tier, sustaining factory-fill specifications through European automaker technical collaborations. These four patterns—integrated multinational, regional price competitor, industrial specialist, and OEM-aligned formulator—structure competitive returns across Morocco's lubricant procurement segments.
| Leading Market Players |
|---|
| FUCHS |
| OLA Energy |
| TotalEnergies |
| Petrom |
| Petromin Corporation |
| Afriquia |
| Motul |
| Ziz Lubrifiant |
| Shell |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles at Casablanca bulk terminals concentrate pricing power among blenders with coastal storage infrastructure, compressing margins for distributors dependent on spot procurement. This lead-time asymmetry rewards integrated suppliers commanding captive supply chains while exposing import-reliant competitors to freight cost volatility from Mediterranean refiners.
Pricing Analysis
The customization-premium spread between configured-to-order industrial formulations and standard aftermarket products structures Morocco's lubricant economics. Three-tier pricing separates premium synthetic formulations from standard semi-synthetic blends from economy mineral oils, with differentiation driven by IMANOR certification grade and volume scale commitments. Pricing pressure stems from fleet procurement centralization demanding total fluid cost management rather than per-liter rates. Owner-operators in Meknes and Fes exhibit highest price sensitivity, while phosphate processing plants in Khouribga prioritize technical compliance over unit economics.
Supply Chain Analysis
Inventory concentration at Tanger Med and Casablanca port facilities exposes Moroccan blenders to Mediterranean shipping schedules and Middle Eastern refinery allocation decisions. Base oil supply draws from Spain, Italy, and Saudi Arabia, with additive packages sourcing from Germany and the United States. Single-source vulnerability concentrates in Group III hydrocracked stocks where European refiners dominate regional allocation. Distribution runs through coastal bulk terminals serving fleet direct contracts, with secondary city penetration requiring packaged goods logistics through fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent blenders face substitution pressure from re-refined base oils as Morocco's National Energy Strategy accelerates circular economy mandates. Defending market position requires securing captive infrastructure and specification control before regulatory thresholds tighten.
For Market Incumbents: Secure backward integration into used oil collection networks to feed re-refining capacity and lock in feedstock supply. Anchor specification control through IMANOR certification investments that create compliance barriers for import-dependent distributors. The re-refining substitution threat demands preemptive positioning before circular economy mandates harden.
For New Entrants and Emerging Players: IMANOR fast-track certification for low-SAPS formulations offers entry into fleet procurement panels currently dominated by established blenders. Target secondary city distribution gaps in Oujda and Fes where mineral oil economics still prevail and localized stocking points remain underdeveloped. A technical service partnership model with industrial phosphate processing accounts bypasses retail channel saturation.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because fleet procurement centralization and specification complexity will compress viable supplier counts to integrated blenders with captive infrastructure. Watch for IMANOR enforcement acceleration as the inflection signal indicating when compliance costs eliminate marginal competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Re-refining | Captures used oil feedstock supply before circular economy mandates tighten collection requirements. |
| IMANOR Certification Investment | Creates compliance barriers against import-reliant distributors lacking technical qualification resources. |
| Secondary City Distribution Partnership | Establishes localized stocking points in Meknes and Oujda before competitors consolidate fragmented channels. |
| Fleet Direct Supply Agreement | Locks in procurement volume as transport operators consolidate purchasing authority under headquarters control. |
| Industrial Technical Service Capability | Differentiates supplier performance in phosphate processing and manufacturing accounts requiring fluid analysis. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with lubricant procurement managers at fleet operators, plant engineers at phosphate processing facilities, and distribution channel partners; and secondary validation through customs trade data, IMANOR certification registries, and SEC filings of multinational energy majors. Bottom-up volume triangulation across end-use segments was cross-checked against top-down base oil import flows through Moroccan port authorities.
Across the projection horizon, the analytical framework modeled segmentation dimensions including base oil type tier, end-use application intensity, and regional procurement channel structure. CAGRs were derived from trend extrapolation of fleet expansion rates, automotive assembly localization, and industrial automation intensity. Forecast inputs incorporated Tanger Med port throughput expansion and National Energy Strategy implementation pace.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure investment and regulatory enforcement continuity would require recalibration. Forecasts reflect assumptions about IMANOR harmonization with EU REACH timelines and base oil import flow stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Saudi Arabia Commercial Vehicles Lubricants Market
Lubricants
Global Grease Cartridges Market
Lubricants
Firearm Lubricants Market
Lubricants
China Refrigeration Lubricants Market
Lubricants
Saudi Arabia Automotive Engine Oils Market
Lubricants
Kenya Lubricants Market
Lubricants
Iran Passenger Vehicles Lubricants Market
Lubricants
South Korea Commercial Vehicles Lubricants Market
Lubricants
Global Engineered Fluids Market
Lubricants
Graphite Lubricant Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Middle East Commercial Vehicles Lubricants Market
Lubricants
Gun Lubricant Market
Lubricants
Industrial Lubricants Market
Lubricants
Mexico Automotive Lubricants Market
Lubricants
Global Automotive Engine Oils Market