
 Environmental Catalysts Market | 2026-2036
Environmental Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Environmental Catalysts Market Analysis
Power generation is decoupling from coal-heavy catalyst demand as natural gas and hydrogen combustion gain share. BASF SE leverages its integrated precious metals refining to sustain cost leadership in platinum-group-metal catalyst formulations. Johnson Matthey anchors its position through membrane electrode assembly expertise that extends into hydrogen fuel cell catalyst adjacencies. Topsoe dominates hydroprocessing catalyst supply for refineries navigating sulfur reduction mandates.
Environmental catalysts are heterogeneous or homogeneous substances that accelerate chemical reactions to neutralize pollutants without being consumed, typically composed of platinum-group metals, base metal oxides, or zeolite structures deposited on ceramic or metallic substrates, and engineered to operate within specific temperature windows to convert NOx, CO, and hydrocarbons into nitrogen, carbon dioxide, and water. Catalytic converters remain the largest value pool in automotive applications, though selective catalytic reduction systems for diesel and stationary sources represent the fastest-expanding segment as ammonia-slip controls tighten. Non-metallic catalysts are gaining share in waste treatment where platinum-group metal volatility disrupts procurement budgets.
EPA tailpipe standards, the EU Green Deal's F-Gas Regulation, and China's MEE emission enforcement collectively mandate lower NOx and particulate thresholds, forcing catalyst reformulation and more frequent replacement cycles. REACH and RoHS compliance in Europe restricts certain substrate coatings, redirecting R&D toward ceria-zirconia mixed oxide alternatives. Stakeholders must monitor rare earth supply concentration and hydrogen combustion catalyst readiness as the technology mix diversifies beyond conventional automotive aftertreatment.
Market Dynamics
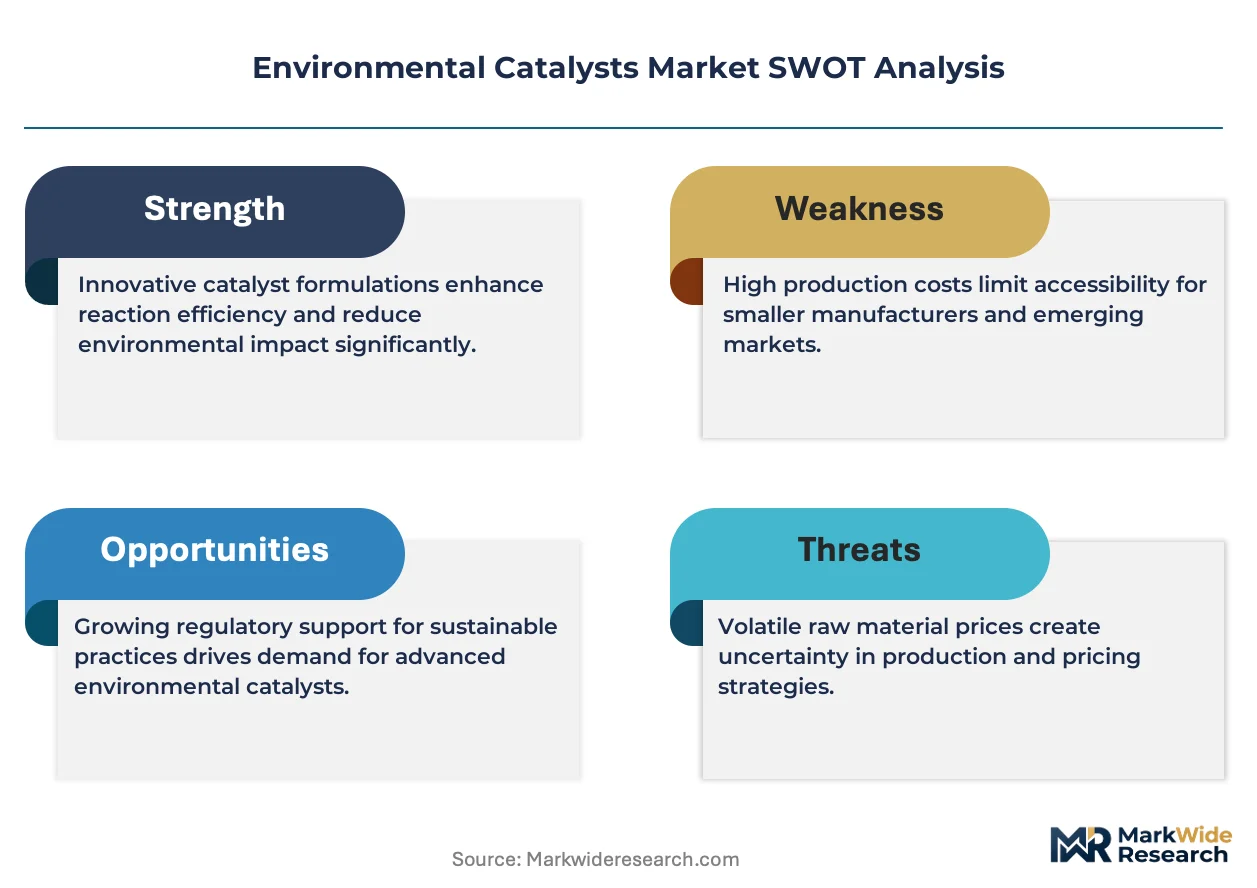
Platinum-group metal supply concentration in South Africa and Russia is forcing catalyst formulators to accelerate non-noble metal substitution programs while maintaining conversion efficiency thresholds for automotive and stationary source applications.
Growth Catalysts
- Euro 7 tailpipe mandates:European OEM procurement of selective catalytic reduction systems intensifies as NOx limits tighten for diesel passenger cars and light commercial vehicles.
- China MEE enforcement waves:Heavy-duty diesel fleet retrofit programs in the Yangtze River Delta and Pearl River Delta drive replacement catalyst demand.
- Ceria-zirconia mixed oxides:Advanced oxygen storage materials enable lower platinum loadings without sacrificing three-way conversion performance.
Market Restraints
- Palladium price volatility:Automotive catalyst procurement budgets face disruption from London Bullion Market Association price swings exceeding 40% annually.
- Rare earth oxide concentration:Lanthanum and cerium supply chains cluster in Chinese refining operations, creating single-source vulnerability.
- Hydrogen combustion catalyst readiness:Thermal stability limitations above 800°C delay commercial deployment for gas turbine and industrial boiler applications.
Strategic Opportunities
- India BS-VI Phase II compliance:Delhi and Mumbai municipal bus fleet tenders specify SCR-equipped systems for 2027-28 procurement cycles.
- Green hydrogen electrolyzer catalyst adjacencies:Proton exchange membrane stack manufacturers seek iridium and platinum coating partners for anode and cathode production.
- EPA Tier 3 off-road engine rules:Construction and agricultural equipment OEMs require new catalyst formulations for engines above 56kW.
Industry Challenges
- Zeolite synthesis expertise scarcity:Cu-SSZ-13 and Fe-ZSM-5 production requires molecular sieve chemists in short supply across European and North American manufacturing bases.
- REACH SVHC notification timelines:Catalyst substrate coatings containing cobalt compounds face extended European Chemicals Agency registration procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environmental Catalysts Market |
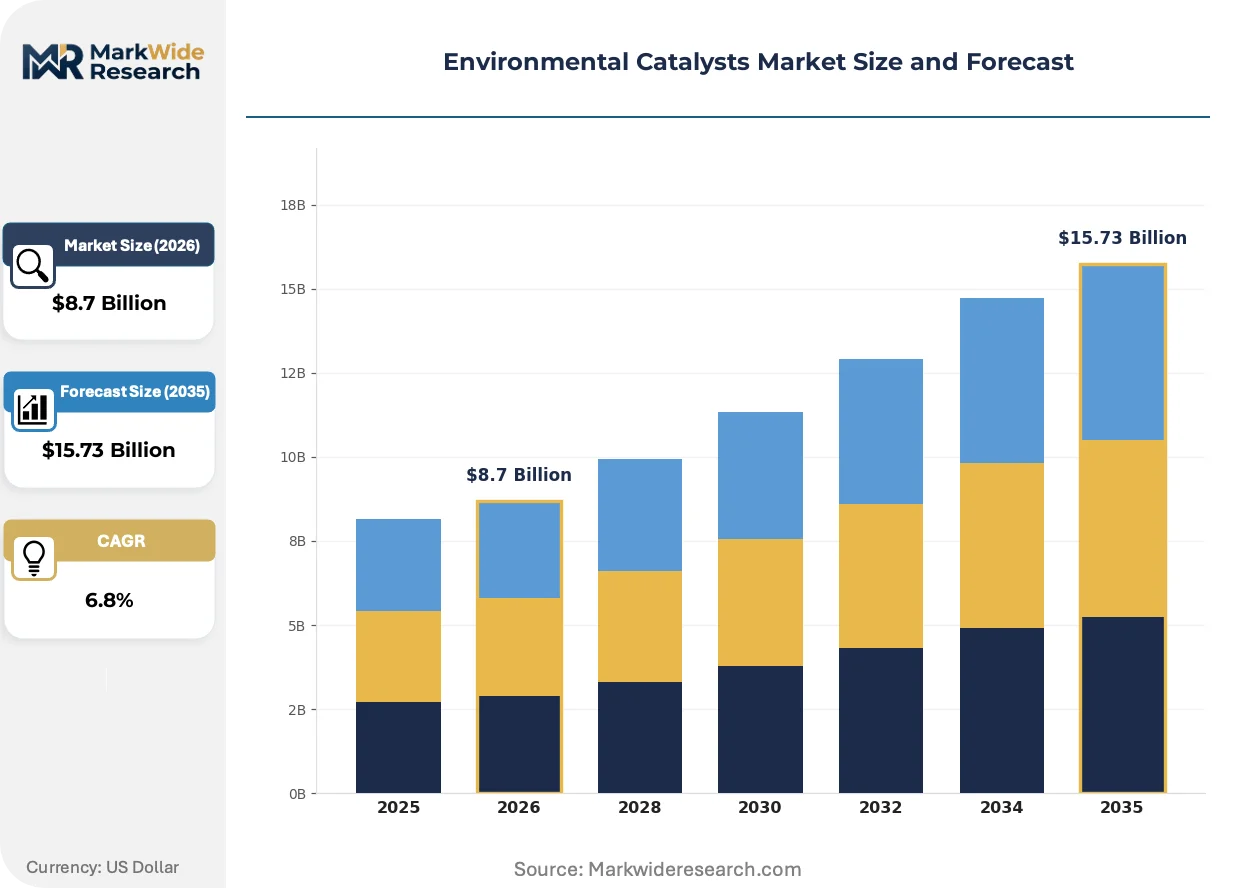
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catalytic Converters, Diesel Particulate Filters, Exhaust Gas Recirculation Systems, Selective Catalytic Reduction Systems Application: Automotive, Industrial Processes, Power Generation, Waste Treatment Technology: Platinum-Based Catalysts, Palladium-Based Catalysts, Rhodium-Based Catalysts, Non-Metallic Catalysts End User: OEMs, Tier-1 Suppliers, Refineries, Waste Management Firms |
| Companies Covered | BASF SE, Johnson Matthey, Clariant AG, Umicore, Evonik Industries, Topsoe, Honeywell, Albemarle, W. R. Grace & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environmental Catalysts Market Emerging Trajectories
Formulation chemistry is converging with hydrogen economy infrastructure buildout, creating catalyst architectures that must function across combustion, electrolysis, and fuel cell operating regimes simultaneously.
Atomically dispersed platinum on ceria-zirconia supports is unifying high-temperature stability with low-temperature light-off performance. Heavy-duty diesel engine manufacturers in Germany and the US Midwest are qualifying these formulations for 2026-27 model year engines. The technology is unifying previously separate catalyst bricks for close-coupled and underfloor positions into single-housing designs.
EPA's Good Neighbor Plan for 2015 Ozone National Ambient Air Quality Standards is compelling power plant operators in 23 upwind states to install or upgrade selective catalytic reduction systems by 2026. Coal and natural gas generators face different ammonia slip limits and catalyst deactivation profiles. Texas and Ohio utilities are prioritizing high-dust SCR configurations for existing pulverized coal units.
Refinery procurement departments are consolidating catalyst supply contracts across hydroprocessing, FCC, and sulfur recovery units to secure volume-based precious metal pass-through terms. Integrated operators in the US Gulf Coast and Rotterdam-Antwerp-Arwerp corridor favor single-source accountability for catalyst loading, activation, and spent catalyst reclamation. This contract consolidation is most visible among European refiners navigating EU Emissions Trading System compliance costs.
Environmental Catalysts Market Segmentation
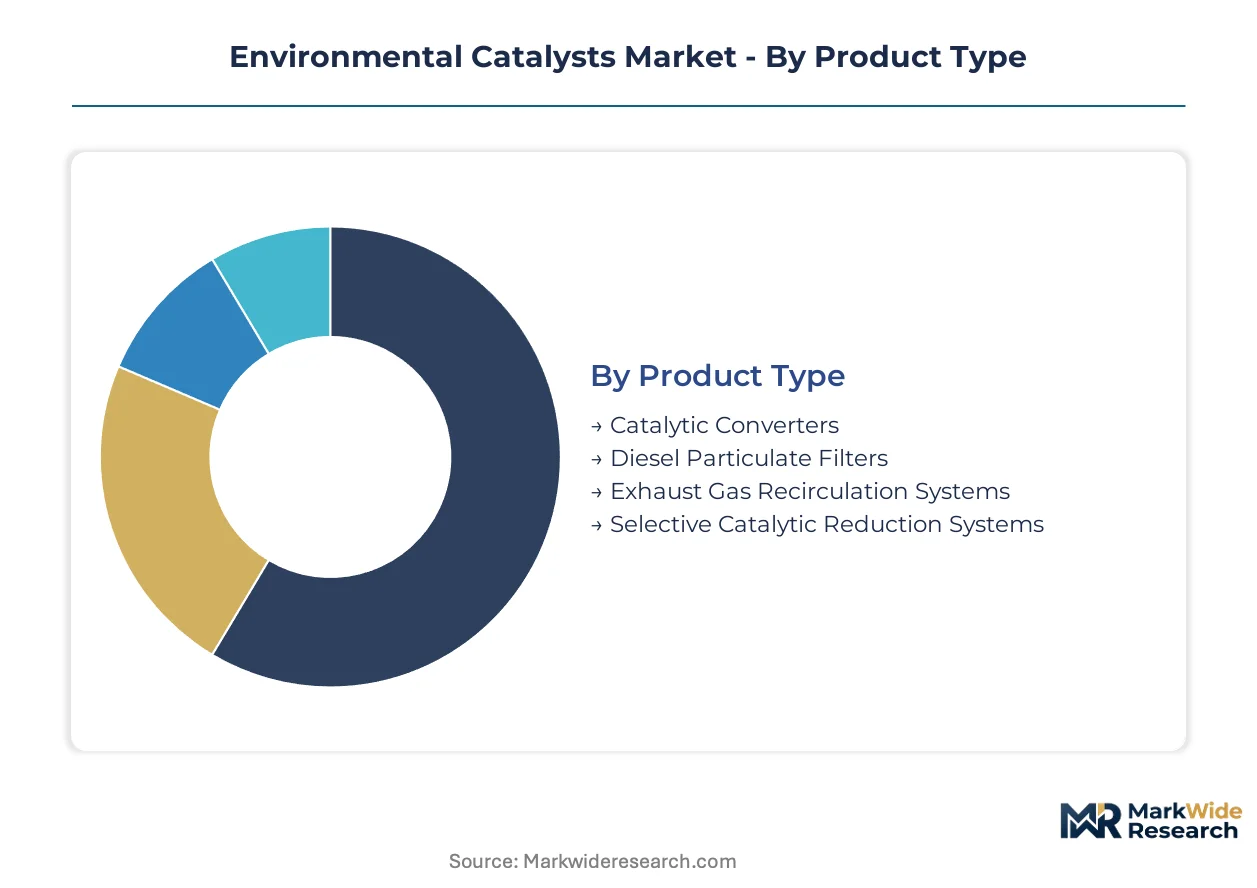
Environmental catalyst procurement splits between embedded automotive systems and standalone industrial installations, with each configuration demanding distinct substrate geometries, precious metal loadings, and regeneration protocols. Understanding these segment boundaries clarifies where formulation chemistry investments concentrate versus where commodity procurement dominates.
Product Type:
Integration depth varies sharply — catalytic converters and diesel particulate filters ship as embedded engine components, while selective catalytic reduction systems often deploy as standalone retrofit kits for stationary sources.
- Catalytic Converters:Three-way catalyst formulations using platinum-palladium-rhodium coatings on ceramic honeycomb substrates convert NOx, CO, and hydrocarbons simultaneously. European passenger vehicle OEMs in Germany and France specify these for Euro 7 compliance, driving platinum-group metal coating demand at Johnson Matthey and BASF SE facilities.
- Selective Catalytic Reduction Systems:Urea-based ammonia injection systems with vanadium or zeolite catalyst cores reduce NOx in diesel exhaust streams. China's MEE enforcement in the Yangtze River Delta is accelerating heavy-duty fleet retrofits, making this the fastest-expanding product category for stationary and mobile diesel applications.
- Diesel Particulate Filters:Silicon carbide or cordierite wall-flow substrates trap soot for periodic regeneration.
- Exhaust Gas Recirculation Systems:Cooler and valve assemblies recirculate exhaust to lower combustion temperatures and NOx formation.
Catalytic converters lead volumes today; selective catalytic reduction systems are gaining share fastest.
Application:
Cost tiers separate automotive volume contracts from industrial project-based procurement, with power generation and waste treatment commanding premium pricing for custom catalyst formulations.
- Automotive:Light-duty and heavy-duty vehicle exhaust aftertreatment consumes the majority of platinum-group metal catalyst production, with EPA Tier 3 and Euro 7 standards forcing more frequent catalyst replacement cycles and higher precious metal loadings per unit.
- Industrial Processes:Refinery hydroprocessing and chemical plant emissions control use specialized catalyst formulations. Topsoe dominates hydroprocessing catalyst supply for sulfur reduction mandates in the US Gulf Coast and Rotterdam-Antwerp corridor.
- Power Generation:Coal and natural gas turbine SCR installations face EPA Good Neighbor Plan deadlines for ozone compliance.
- Waste Treatment:Incinerator and wastewater treatment catalysts favor non-metallic formulations where platinum-group metal volatility disrupts municipal procurement budgets.
Automotive commands the largest revenue pool; waste treatment is expanding most quickly as non-noble metal substitution accelerates.
Technology:
Supply concentration in South African and Russian platinum-group metal mining is forcing formulators to diversify into palladium and rhodium alternatives while maintaining conversion efficiency thresholds.
- Platinum-Based Catalysts:Primary coating for diesel oxidation catalysts and hydrogen fuel cell electrodes. BASF SE leverages integrated precious metals refining to sustain cost leadership in platinum formulations for automotive and emerging electrolyzer applications.
- Non-Metallic Catalysts:Zeolite and base metal oxide formulations eliminate precious metal exposure. Waste treatment operators in Europe and North America specify these for budget stability, with ceria-zirconia mixed oxides enabling oxygen storage without platinum-group metals.
- Palladium-Based Catalysts:Dominant in gasoline three-way catalysts but subject to price volatility exceeding 40% annually.
- Rhodium-Based Catalysts:Critical for NOx reduction in gasoline applications with limited substitution options.
Platinum-based formulations anchor current revenue; non-metallic alternatives are climbing the fastest as procurement seeks price stability.
End User:
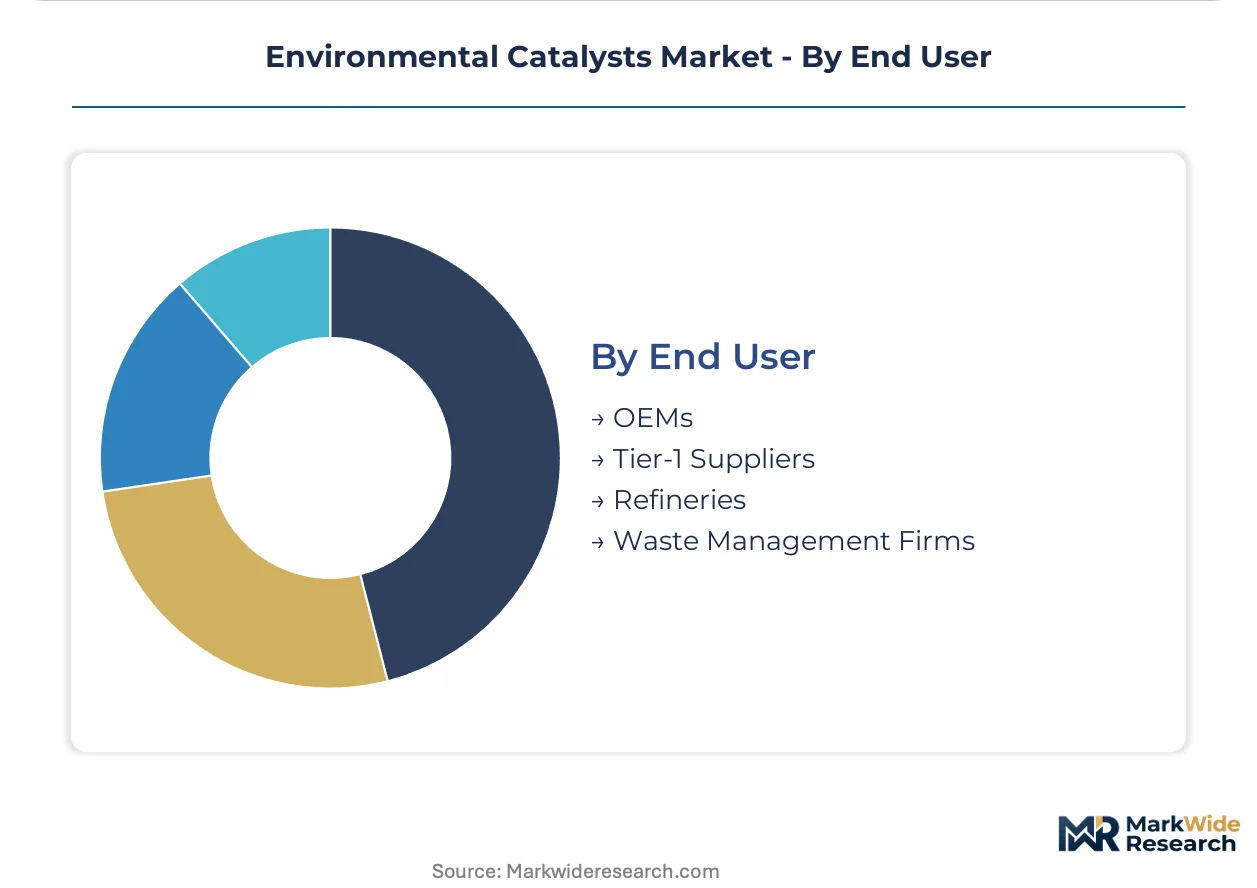
Customer type determines contract structure — OEMs demand multi-year supply agreements with precious metal pass-through clauses, while waste management firms favor spot procurement of standardized catalyst loads.
- OEMs:Volkswagen, Stellantis, and Ford specify catalyst formulations during engine development, locking in platinum-group metal loadings years before production. Euro 7 and EPA Tier 3 compliance timelines are compressing these development cycles.
- Refineries:Integrated operators in the US Gulf Coast consolidate catalyst supply across hydroprocessing, FCC, and sulfur recovery units to secure volume-based terms and single-source accountability for spent catalyst reclamation.
- Tier-1 Suppliers:Faurecia, Tenneco, and Eberspaecher manage catalyst coating and canning for OEM assembly lines.
- Waste Management Firms:Municipal and industrial incinerator operators prioritize total cost of ownership over performance optimization.
OEMs drive the largest contract values; refineries are consolidating procurement fastest through integrated supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting catalyst manufacturing investments toward jurisdictions with integrated precious metals refining and lower compliance cost structures, particularly as Euro 7 and EPA Tier 3 timelines compress development cycles.
United States
EPA Good Neighbor Plan deadlines for 2015 Ozone National Ambient Air Quality Standards are compelling power plant operators in Texas and Ohio to install high-dust selective catalytic reduction configurations. The EPA is enforcing ammonia slip limits for coal and natural gas generators across 23 upwind states by 2026. The US Gulf Coast refining corridor is consolidating catalyst supply contracts to secure volume-based precious metal pass-through terms.
Germany
Heavy-duty diesel engine manufacturers in Baden-Württemberg and Bavaria are qualifying atomically dispersed platinum formulations for 2026-27 model year engines. The KBA is administering Euro 7 tailpipe mandate compliance timelines for domestic OEMs. The Stuttgart industrial cluster is unifying close-coupled and underfloor catalyst bricks into single-housing designs.
China
Heavy-duty diesel fleet retrofit programs in the Yangtze River Delta and Pearl River Delta are accelerating replacement catalyst demand. The MEE is tightening NOx emission limits for diesel fleets nationwide. Shanghai and Guangzhou municipal procurement specifications are mandating selective catalytic reduction-equipped systems for municipal bus tenders.
India
Delhi and Mumbai municipal bus fleet tenders are specifying selective catalytic reduction-equipped systems for 2027-28 procurement cycles. The BIS is implementing BS-VI Phase II compliance deadlines for commercial vehicle operators. The Maharashtra industrial corridor is attracting catalyst formulators seeking to localize production for South Asian aftermarket demand.
Japan
Membrane electrode assembly manufacturers are sourcing iridium and platinum coating partners for proton exchange membrane electrolyzer production. METI is coordinating hydrogen economy infrastructure buildout timelines with catalyst readiness assessments. The Kansai industrial belt around Osaka is converging formulation chemistry across combustion, electrolysis, and fuel cell operating regimes.
Environmental Catalysts Market Vendor Landscape
Capacity expansion dominates the current landscape as formulators respond to compressed Euro 7 and EPA Tier 3 development timelines. The vendor base clusters around three strategic archetypes: integrated precious metals refiners with captive coating capabilities, specialized membrane electrode assembly producers extending into hydrogen adjacencies, and hydroprocessing catalyst specialists serving refinery sulfur reduction mandates. Geographic expansion and technology licensing represent the dominant competitive moves, with players seeking to secure rare earth oxide supply chains outside Chinese refining concentration.
Among European-based integrated chemical conglomerates, BASF SE and Johnson Matthey exemplify the precious-metals-integrated archetype, while Topsoe represents the hydroprocessing specialization vector. These three entities anchor distinct competitive positions without overlapping core competencies, reflecting deliberate portfolio boundaries that minimize direct confrontation while maximizing sector coverage.
| Leading Market Players |
|---|
| BASF SE |
| Johnson Matthey |
| Clariant AG |
| Umicore |
| Evonik Industries |
| Topsoe |
| Honeywell |
| Albemarle |
| W. R. Grace & Co. |
| Others |
Supply Flow & Price Mechanics
Captive precious metals refining anchors competitive positioning across the environmental catalyst value chain, with integrated operators commanding pricing power through in-house platinum-group metal recovery and reformulation capabilities that insulate procurement budgets from London Bullion Market Association volatility.
Pricing Analysis
Distributor margins for zeolite and base metal oxide formulations compress under OEM direct-sourcing pressure, while precious metal pass-through clauses dominate platinum-palladium-rhodium coatings. Three-tier pricing structure across premium, standard, and economy levels separates validated Euro 7-compliant formulations from developmental grades and commodity refinery catalysts. Cost compression in non-noble metal segments is intensifying because municipal waste treatment operators prioritize total cost of ownership over performance optimization. Tier-1 automotive suppliers exhibit lowest price sensitivity due to regulatory compliance imperatives, whereas municipal procurement teams in waste management show highest sensitivity to platinum-group metal volatility.
Supply Chain Analysis
Dual-sourcing requirements from European OEM procurement teams mandate qualified secondary suppliers for Cu-SSZ-13 and Fe-ZSM-5 zeolite cores, forcing molecular sieve manufacturers to maintain redundant production lines across Germany and the United States. Geographic supply concentration clusters in South Africa and Russia for platinum-group metals, with Chinese refining operations dominating lanthanum and cerium rare earth oxides. Raw material dependencies rest on palladium sponge, rhodium powder, and ceria-zirconia mixed oxide precursors. Single-source vulnerability in South African mining operations constitutes the primary structural risk. Distribution runs through integrated refiners with captive coating capabilities directly to OEM assembly lines and refinery process units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The environmental catalyst market functions as a stable compounder, with regulatory tailwinds from EPA Tier 3 and Euro 7 mandates ensuring replacement cycle visibility across automotive and stationary source applications.
For Market Incumbents: To counter palladium price volatility exceeding annual swings, BASF SE and Johnson Matthey should deepen backward integration into spent catalyst reclamation while accelerating atomically dispersed platinum formulations that reduce precious metal loadings. Certification investment in membrane electrode assembly capabilities for hydrogen fuel cell adjacencies provides defensive optionality against combustion engine decline. For New Entrants and Emerging Players: Tier-1 automotive coating partnerships represent the most penetrable entry vector, particularly for municipal bus fleet retrofits in India's BS-VI Phase II compliance window. Waste treatment non-metallic catalyst supply offers white-space expansion where procurement teams prioritize budget stability over brand recognition. Joint development agreements with proton exchange membrane electrolyzer manufacturers enable technology transfer without full precious metals integration. For Investors and Strategic Acquirers: Roll-up economics work for regional zeolite synthesis specialists because molecular sieve chemistry expertise scarcity across European and North American manufacturing bases limits organic replication. Five-to-ten year viability hinges on hydrogen combustion catalyst readiness for gas turbine applications. The signal to watch is EPA Good Neighbor Plan enforcement acceleration in Texas and Ohio utility procurement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precious Metals Refining | Captive platinum-group metal recovery insulates BASF SE and Johnson Matthey from London Bullion Market Association volatility. |
| Capacity Expansion in Ceria-Zirconia Mixed Oxides | Advanced oxygen storage materials enable lower platinum loadings without sacrificing three-way conversion performance thresholds. |
| Joint Venture for Hydrogen Fuel Cell Catalyst Production | Membrane electrode assembly partnerships with Japanese electrolyzer manufacturers extend formulation chemistry into electrolysis regimes. |
| Long-term Supply Agreement with Rare Earth Refiners | Direct offtake contracts with Chinese lanthanum and cerium processors reduce single-source vulnerability in European coating operations. |
| Technology Licensing for Non-Noble Metal Formulations | Waste treatment operators in Europe and North America license zeolite architectures to bypass platinum-group metal procurement disruption. |
Methodological Framework
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market combining structured interviews with catalyst formulator R&D directors, OEM procurement managers, refinery process engineers, municipal fleet operators, and hydrogen infrastructure developers alongside secondary validation from EPA enforcement databases, ECHA REACH registrations, China MEE emission filings, and SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up unit economics triangulate against top-down regulatory mandate sizing.
Rate-of-change decomposition separates volume growth from precious metal price effects and formulation mix shifts across the projection horizon. Segmentation dimensions modeled include product type integration depth, application cost tier, technology metal base, and end-user contract structure. CAGRs derive from regression against regulatory compliance timelines and fleet replacement cycles. Industry-specific forecast inputs incorporate Euro 7 and EPA Tier 3 implementation phasing and hydrogen combustion catalyst thermal stability thresholds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to South African mining output disruption and Chinese rare earth export policy revision. Deviation in EPA Good Neighbor Plan enforcement intensity or hydrogen fuel cell deployment acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Biorenewable Catalysts Market
Catalysts
Global VOC Catalysts Market
Catalysts
Photocatalyst Market
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
Precious Metal Catalysts Market
Catalysts
Catalyst for Hydrogen Production from Water Electrolysis Market
Catalysts
Global Emission Control Catalyst (ECC) Market
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Residue Hydrodesulphurization Catalyst Market
Catalysts
Global Polypropylene Catalyst Market
Catalysts
Marine Selective Catalytic Reduction Systems Market
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
Asia and Middle East FCC Catalyst Market
Catalysts
Hydrodeoxygenation [HDO] Catalysts Market