
 Iran Passenger Vehicles Lubricants Market | 2026-2036
Iran Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Passenger Vehicles Lubricants Market Foresight
Tehran's ride-hailing and taxi fleet segment is shifting toward higher-frequency oil change intervals as vehicle utilization rates climb. Behran Oil Company leverages its domestic refinery integration to control feedstock costs across northern distribution corridors. Iranol Oil Company anchors its position through state-backed procurement contracts with public transit authorities. Pardis Engine Oil Company differentiates via specialized formulations for Iran's hot-climate engine stress conditions.
Iran passenger vehicles lubricants comprise refined base oils blended with performance additives to reduce friction, dissipate heat, and prevent engine wear in gasoline and diesel powertrains operating across temperature extremes from Zagros mountain winters to Persian Gulf coastal humidity. Engine oil commands the dominant product volume share as Iranian vehicle parc skews toward aging passenger cars with elevated consumption rates. The 10W-40 viscosity grade occupies the mainstream channel due to compatibility with both imported and domestically assembled powertrains, while dispersant-heavy additive packages gain traction among fleet operators managing extended drain intervals.
Iran's Institute of Standards and Industrial Research enforces lubricant quality certifications that filter import access and shape domestic formulation requirements. The country's petroleum ministry aligns refining output with automotive sector demand through controlled base oil allocation mechanisms. Stakeholders must monitor regulatory adjustments to additive import protocols and domestic blending capacity expansion timelines.
Market Dynamics
Iran's Institute of Standards and Industrial Research lubricant quality certifications are tightening formulation requirements while domestic base oil allocation mechanisms concentrate supply control within the petroleum ministry's distribution corridors.
Growth Catalysts
- Tehran ride-hailing fleet expansion:Vehicle utilization rates above 200,000 kilometers annually are compressing oil change intervals and multiplying lubricant throughput per unit.
- Hot-climate additive formulations:Dispersant-heavy packages tailored to Persian Gulf humidity and Zagros temperature swings are extending drain intervals for commercial operators.
- 10W-40 viscosity standardization:Compatibility across both imported powertrains and domestically assembled Saipa and Iran Khodro engines is reducing inventory complexity for distribution networks.
Market Restraints
- Base oil import dependency:API Group II and III feedstock shipments face intermittent clearing delays at Bandar Abbas, creating formulation bottlenecks for blenders lacking captive refining.
- Additive import protocol friction:Iran's petroleum ministry permit requirements for antioxidant and detergent packages extend procurement cycles by 60-90 days versus regional benchmarks.
- Domestic refinery capacity concentration:Behran and Iranol control over 70 percent of Group I base oil output concentrates supply risk along the northern Tehran-Qom corridor.
Strategic Opportunities
- Isfahan and Fars provincial penetration:Vehicle ownership density in these southern corridors remains 40 percent below Tehran levels, creating whitespace for branded distributor networks.
- Synthetic blend conversion:Semi-synthetic 5W-30 formulations are gaining traction among 2016+ vehicle cohorts as drain interval extension becomes a fleet cost priority.
- Public transit authority contract consolidation:State-backed procurement tenders for municipal bus and metro feeder fleets are shifting from spot purchases to multi-year supply agreements.
Industry Challenges
- Formulation chemist scarcity:Blending facilities report 18-month recruitment cycles for specialists capable of balancing VI improver and pour point depressant ratios for Iranian climate extremes.
- Certification timeline compression:Institute of Standards and Industrial Research lubricant grade recertification cycles have shortened from 36 to 24 months, forcing accelerated R&D spend.
- Legacy distribution network reconfiguration:Traditional bazaar-based lubricant traders lack cold-chain and bulk handling infrastructure required for synthetic product integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Passenger Vehicles Lubricants Market |
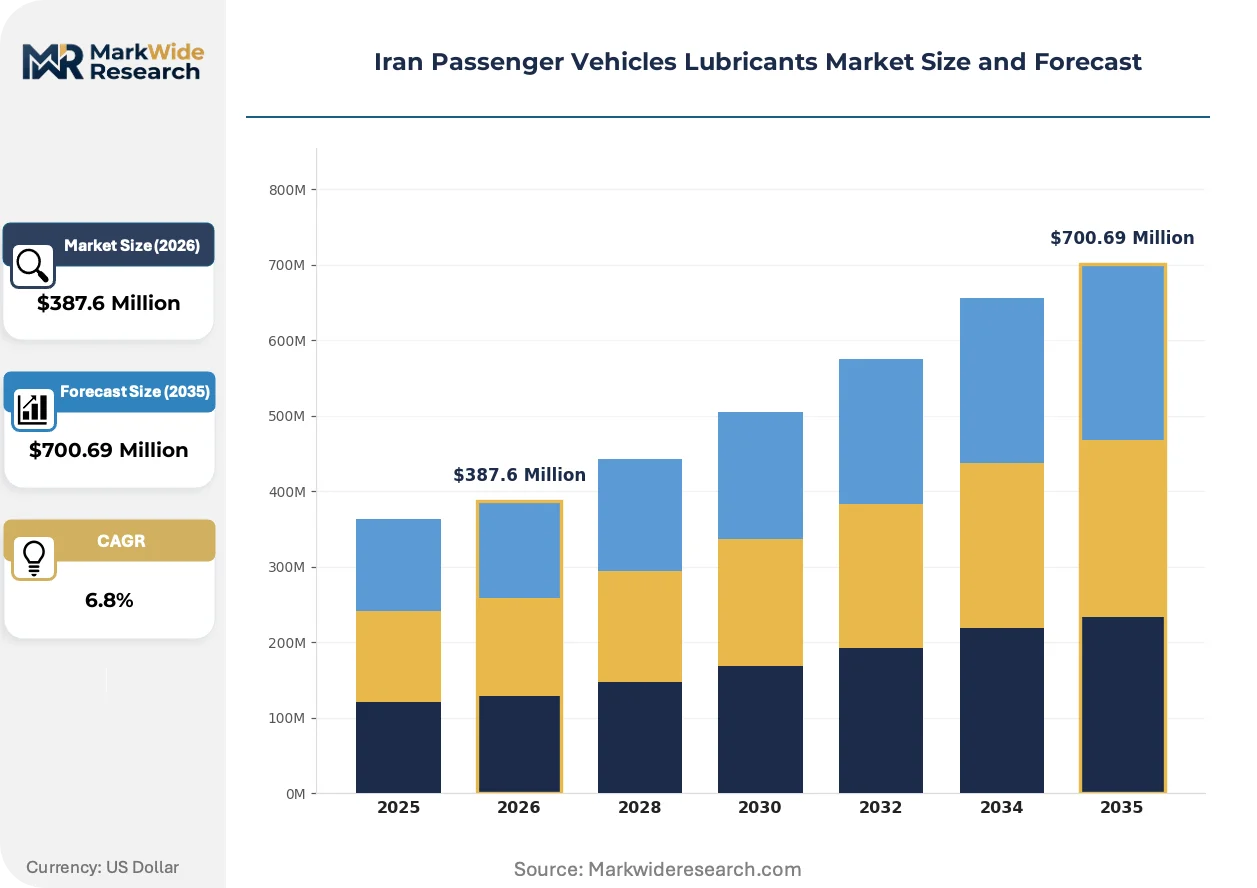
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Gear Oil Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Additives: Detergents, Dispersants, Anti-wear Agents, Viscosity Improvers Container Type: Bottle, Drum, Bag, Pail |
| Companies Covered | Behran Oil Company, Iranol Oil Company, Pardis Engine Oil Company, Pars Oil Company, Sepahan Oil Company, LIQUI MOLY, AZAR RAVAN SAZ (Petronol), Ghatran Kaveh Motor Oil Co, Zarrin Oil, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Passenger Vehicles Lubricants Market Shifts & Advancements
Additive technology convergence with base oil quality upgrades is compressing the performance gap between mineral and synthetic segments while regulatory enforcement tightens around drain interval claims.
Dispersant-lean, antioxidant-rich additive packages are consolidating as the dominant formulation architecture for Iranian passenger vehicle lubricants. Fleet operators managing Tehran ride-hailing and taxi assets are adopting these chemistries to extend drain intervals from 5,000 to 7,500 kilometers. The technology is consolidating mid-tier blender market share by rendering legacy detergent-heavy formulations uneconomical for high-utilization vehicles.
Iran's Institute of Standards and Industrial Research updated lubricant quality benchmarks are mandating elevated oxidation stability testing for 10W-40 and 5W-30 grades. Domestic blenders must now submit third-party laboratory verification of TBN retention and kinematic viscosity stability. Tehran Province's dense vehicle ownership corridor faces the steepest compliance burden as enforcement resources concentrate on metropolitan distribution channels.
Scheduled maintenance program bundling is displacing spot lubricant purchases among fleet operators. Ride-hailing platforms and taxi cooperatives are negotiating direct supply agreements with blenders, bypassing traditional retail petroleum product channels. This pattern is most visible in Tehran's southern industrial zones where fleet density and maintenance bay concentration enable bulk delivery economics.
Iran Passenger Vehicles Lubricants Market Segmentation
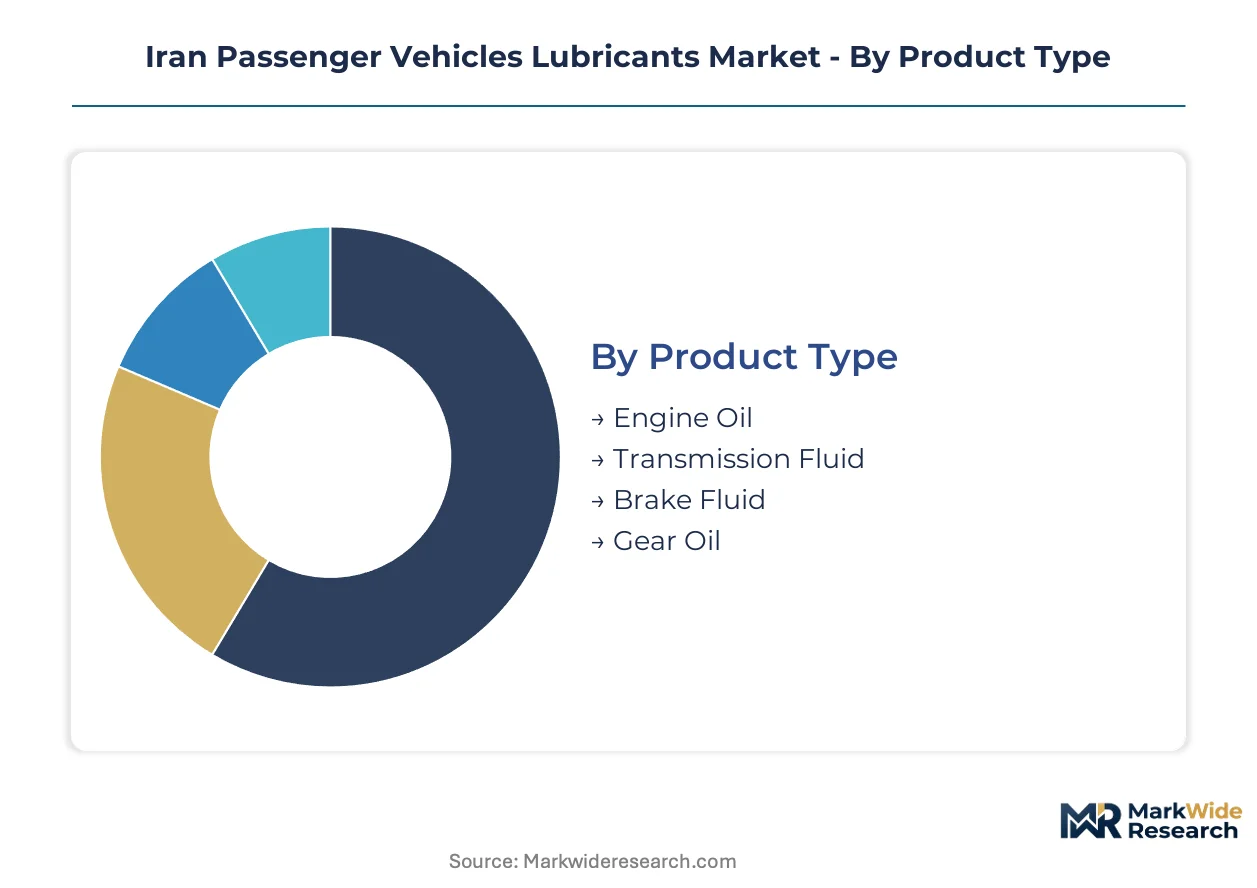
Iran's passenger vehicle lubricants market fragments across technical specifications, packaging formats, and additive chemistries that reflect the country's dual dependency on aging domestic vehicle parc and imported powertrain technologies. Each segmentation dimension carries distinct supply chain implications for blenders navigating petroleum ministry allocation mechanisms and Institute of Standards certification requirements.
Product Type:
Supply concentration among Tehran-Qom corridor blenders funnels base oil allocation toward high-volume product categories, with formulation capacity tilting toward segments that absorb captive Group I output.
- Engine Oil:Refined base oils blended with detergent-dispersant packages dominate volume throughput, formulated for gasoline and diesel powertrains across Zagros mountain winters and Persian Gulf coastal humidity. Tehran Province's dense vehicle ownership corridor consumes the majority share, driven by ride-hailing fleet operators compressing oil change intervals above 200,000 kilometers annually.
- Transmission Fluid:Specialized friction-modifier formulations serve both automatic and manual transmissions, with demand concentrating among 2016+ imported vehicle cohorts requiring synthetic-blend ATF specifications. Isfahan and Fars provincial penetration lags Tehran by 40 percent, creating whitespace for branded distributor networks.
- Brake Fluid:Glycol-ether and silicone-based formulations meeting DOT 3 and DOT 4 specifications serve hydraulic brake systems across Iran's aging vehicle parc.
- Gear Oil:Extreme-pressure additive packages protect differential and manual transmission gear sets, with demand skewing toward commercial taxi and ride-hailing assets.
Today's leader: Engine Oil. Tomorrow's challenger: Transmission Fluid.
Viscosity Grade:
Cost tier differentiation separates premium synthetic grades from mineral-based standards, with procurement patterns bifurcating between fleet operators prioritizing drain interval extension and retail consumers optimizing upfront expenditure.
- 0W-20:Full synthetic formulations with enhanced low-temperature pumpability serve latest-generation imported engines, primarily Toyota and Hyundai assemblies entering through Bandar Abbas. Tehran's northern affluent districts concentrate demand as vehicle ownership skews toward 2020+ imports.
- 5W-30:Semi-synthetic formulations are gaining traction among 2016+ vehicle cohorts as drain interval extension becomes a fleet cost priority. Public transit authority contract consolidation favors this grade for municipal bus and metro feeder fleet tenders.
- 10W-40:Compatibility across both imported powertrains and domestically assembled Saipa and Iran Khodro engines reduces inventory complexity for distribution networks.
- 15W-50:Heavy-duty mineral formulations serve high-mileage domestic assemblies and commercial taxi assets operating in elevated thermal stress conditions.
The 10W-40 grade anchors current volume. The 5W-30 grade climbs the fastest on synthetic conversion.
Additives:
Application-specific additive packages determine formulation economics, with import protocol friction from Iran's petroleum ministry permit requirements extending procurement cycles for specialized chemistries.
- Detergents:Calcium and magnesium sulfonate packages neutralize combustion acids and suspend deposits in high-utilization engines. Tehran ride-hailing fleet expansion multiplies throughput for these chemistries.
- Dispersants:Polyisobutylene succinimide formulations prevent sludge aggregation in Persian Gulf humidity conditions, extending drain intervals from 5,000 to 7,500 kilometers for commercial operators.
- Anti-wear Agents:Zinc dialkyldithiophosphate compounds protect camshaft and valve train components in Iran's stop-start urban traffic patterns.
- Viscosity Improvers:Polymethacrylate and olefin copolymer chemistries maintain lubricant film strength across Zagros temperature swings from sub-zero winters to 50°C summers.
Dispersants dominate current formulation architecture. Viscosity Improvers face steepest supply risk from import dependency.
Container Type:
Customer type segmentation separates bulk fleet procurement from retail aftermarket channels, with packaging format determining last-mile distribution economics and product integrity maintenance.
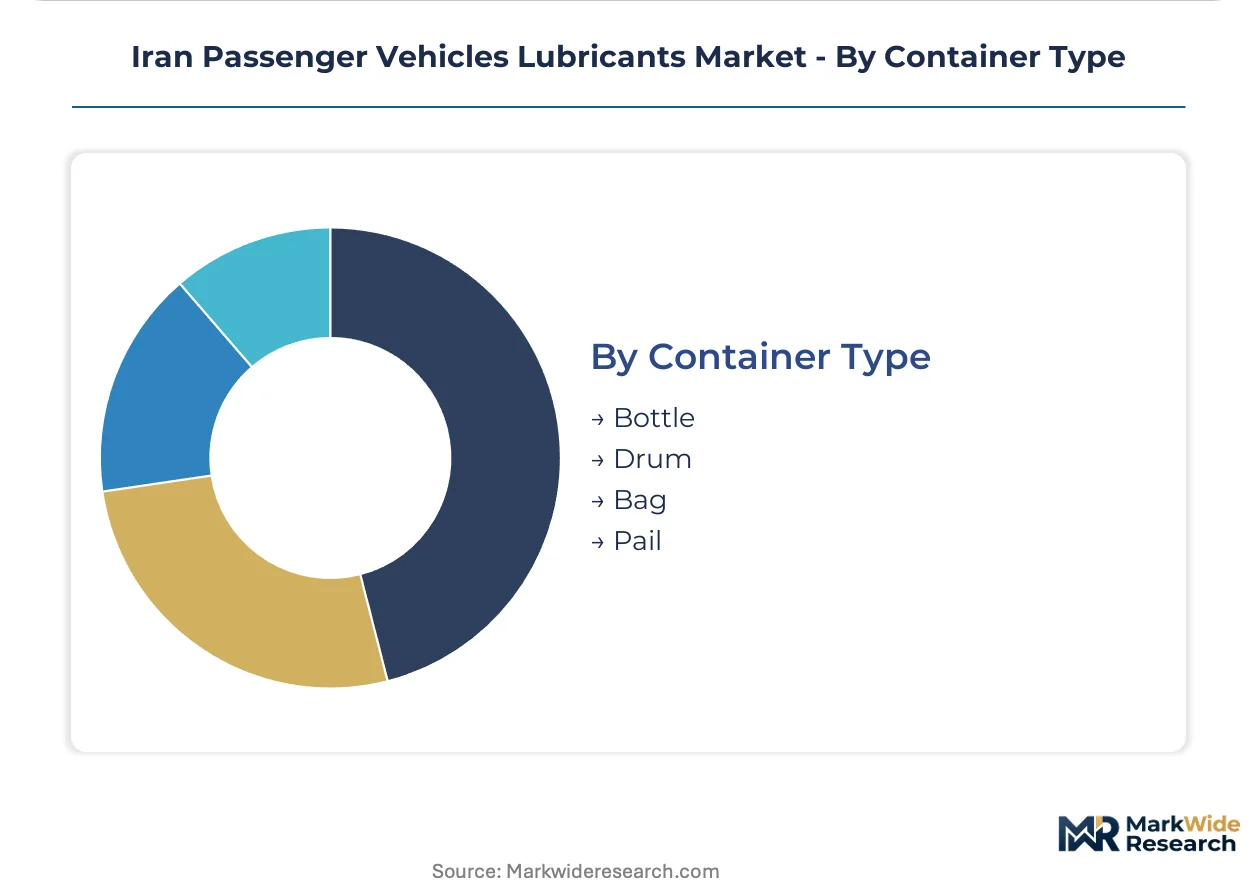
- Bottle:One-liter and four-liter polyethylene containers serve retail aftermarket channels and individual vehicle owners through traditional bazaar-based lubricant traders.
- Drum:200-liter steel containers enable bulk delivery economics for Tehran's southern industrial zone fleet maintenance bays and ride-hailing platform direct supply agreements.
- Bag:Flexible intermediate bulk containers serve high-volume blending facilities requiring feedstock transfer without drum handling infrastructure.
- Pail:Twenty-liter plastic pails bridge retail and commercial segments for independent repair shops and small fleet operators.
Drum format captures fleet conversion momentum. Bottle format retains retail lock-in despite infrastructure gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic blending capacity concentrates along the Tehran-Qom corridor where petroleum ministry allocation mechanisms and Institute of Standards certification requirements create cost-of-compliance gaps that favor integrated refiners over import-dependent competitors.
Tehran Province
Ride-hailing fleet operators compress oil change intervals above 200,000 kilometers annually, multiplying lubricant throughput per vehicle. The Institute of Standards and Industrial Research concentrates enforcement resources on metropolitan distribution channels. Southern industrial zones host dense maintenance bay clusters where fleet operators negotiate direct supply agreements bypassing traditional retail channels.
Isfahan Province
Vehicle ownership density remains 40 percent below Tehran levels, creating whitespace for branded distributor network expansion. Provincial transport authorities issue municipal procurement tenders for bus and metro feeder fleets. The Isfahan industrial corridor attracts blending facility investment targeting synthetic conversion demand among 2016+ vehicle cohorts.
Fars Province
Commercial taxi assets operate in elevated thermal stress conditions requiring heavy-duty mineral formulations. The petroleum ministry's controlled base oil allocation mechanisms extend procurement cycles for non-integrated blenders. Shiraz metropolitan distribution channels show accelerating drum-format adoption as fleet maintenance programs consolidate.
Mazandaran Province
Coastal humidity conditions drive dispersant-heavy additive package demand to prevent sludge aggregation. Northern distribution corridors benefit from Behran Oil Company's captive refinery integration controlling feedstock logistics. Caspian Sea port infrastructure faces intermittent clearing delays for API Group II and III shipments.
Khorasan Razavi Province
Eastern trade corridor positioning creates transshipment demand for bulk lubricant handling infrastructure. Mashhad's pilgrimage tourism fleet generates seasonal utilization spikes compressing maintenance intervals. Provincial blending capacity remains underdeveloped relative to vehicle parc growth rates.
Iran Passenger Vehicles Lubricants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated domestic refiners commanding base oil allocation advantages while import-dependent blenders face formulation bottlenecks. The market structure concentrates supply risk among Tehran-Qom corridor producers controlling over 70 percent of Group I output. Three archetypes dominate: captive refinery operators, state-backed procurement contractors, and climate-specialist formulators. Competitive moves center on synthetic blend conversion investments and multi-year public transit authority contract consolidation.
Among Tehran-based integrated operators, Behran Oil Company and Iranol Oil Company exemplify the captive refinery archetype through petroleum ministry-aligned distribution control. Pardis Engine Oil Company occupies a position within the climate-specialist tier, anchoring formulation differentiation for Persian Gulf humidity and Zagros temperature swing conditions. These three entities represent distinct strategic responses to Institute of Standards certification compression and additive import protocol friction.
| Leading Market Players |
|---|
| Behran Oil Company |
| Iranol Oil Company |
| Pardis Engine Oil Company |
| Pars Oil Company |
| Sepahan Oil Company |
| LIQUI MOLY |
| AZAR RAVAN SAZ (Petronol) |
| Ghatran Kaveh Motor Oil Co |
| Zarrin Oil |
| Others |
Supply & Pricing Matrix
Blending chemist concentration along the Tehran-Qom corridor compresses labor-cost differentials into pricing-tier spreads between mineral-based economy formulations and synthetic-blend premiums. Formulation specialist scarcity amplifies mid-tier price positioning as captive refinery operators exploit integrated cost structures against import-dependent competitors.
Pricing Analysis
Distributor margin layers separate bulk fleet procurement from retail bazaar channels, with drum-format direct agreements commanding 15-20 point markups below bottled retail. Three-tier pricing structure across premium synthetic, semi-synthetic standard, and mineral economy levels tracks base oil quality grades and Institute of Standards certification tiers. Cost compression in synthetic-blend tiers is intensifying because additive import protocol friction extends procurement cycles. Fleet operators exhibit lowest price sensitivity due to drain-interval economics, while individual vehicle owners in traditional retail channels drive volume through upfront expenditure optimization.
Supply Chain Analysis
Empty drum returns and used-oil collection flows remain underdeveloped, constraining closed-loop economics for synthetic product integrity maintenance. Base oil supply concentrates in Iran's Tehran-Qom corridor and Bandar Abbas import corridors, with API Group II and III feedstock sourcing from South Korea and the UAE. Formulation chemistry draws from antioxidant and detergent packages, viscosity improver polymers, and pour point depressants. Single-source vulnerability concentrates around petroleum ministry allocation mechanisms controlling Group I output. Distribution runs through state-aligned refinery networks and traditional bazaar-based lubricant traders lacking cold-chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iran's passenger vehicle lubricants market functions as a regulatory compounder where Institute of Standards certification compression accelerates R&D spend and consolidates compliant producer market share.
For Market Incumbents: Lock in multi-year public transit authority contracts before tender consolidation peaks, and accelerate synthetic-blend conversion investments to preempt formulation obsolescence. Emerging climate-specialist formulators threaten mid-tier positioning through dispersant-heavy additive differentiation. Certification investment in third-party laboratory verification capabilities anchors defensive positioning. For New Entrants and Emerging Players: Capture Isfahan and Fars provincial whitespace where vehicle ownership density trails Tehran by 40 percent and branded distributor networks remain underpenetrated. Transmission fluid demand among 2016+ imported vehicle cohorts offers the most penetrable segment. Direct supply agreement models with ride-hailing platform maintenance bays bypass traditional retail channel barriers. For Investors and Strategic Acquirers: Integrated domestic refiners with captive Group I base oil output are the most active acquirers in this space, targeting climate-specialist formulators with proven Persian Gulf humidity formulations. Long-term viability hinges on synthetic conversion trajectory and regulatory enforcement intensity. Monitor additive import protocol relaxation signals as inflection indicators for import-dependent blender margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Blend Conversion | Semi-synthetic 5W-30 formulations extend drain intervals for Tehran ride-hailing fleets above 200,000 kilometers annually. |
| Backward Integration into Base Oil | Captive refinery control over Group I output insulates Behran and Iranol from Bandar Abbas clearing delays. |
| Public Transit Contract Consolidation | Multi-year supply agreements with municipal bus authorities displace spot purchases and lock volume commitments. |
| Climate-Specialist Formulation Investment | Dispersant-heavy packages tailored to Persian Gulf humidity prevent sludge aggregation in high-utilization engines. |
| Provincial Distribution Network Expansion | Branded distributor buildout in Isfahan and Fars corridors captures 40 percent ownership density gaps versus Tehran. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with blending facility managers, petroleum ministry allocation officers, fleet maintenance directors at ride-hailing platforms, Institute of Standards certification specialists, and traditional bazaar-based lubricant traders with secondary validation against customs trade records, petroleum ministry production disclosures, vehicle registration databases, and industrial standards documentation. Bottom-up volume modeling across viscosity grades and additive chemistries triangulated against top-down market sizing from refinery output allocations and import clearance data.
Segment-weighting approaches distributed forecast mass across engine oil, transmission fluid, brake fluid, and gear oil categories, with further granularity by viscosity grade tier, additive chemistry type, and container format. Modeled dimensions included product type, viscosity specification, additive package composition, and regional demand cluster. CAGRs derived from trend extrapolation of fleet utilization rates, synthetic conversion trajectories, and regulatory enforcement intensity over the projection horizon. Forecast inputs incorporated base oil allocation mechanism stability, additive import protocol friction indices, and provincial vehicle ownership density differentials.
Underlying measurement precision varies by segment; engine oil volume estimates carry tighter precision than transmission fluid projections due to more consolidated reporting channels. Forecasts reflect documented assumptions regarding petroleum ministry policy continuity and Institute of Standards recertification timeline adherence. Practitioners should monitor additive import permit processing speeds and provincial fleet electrification announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Singapore Lubricants Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Lubrication Equipment Market
Lubricants
Hydro Lubricants Market
Lubricants
Synthetic Ester Lubricants Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
Saudi Arabia Automotive Engine Oils Market
Lubricants
Lubricated Tracks Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
Bangladesh Lubricants Market
Lubricants
Brazil Lubricants Market
Lubricants
Netherlands Metalworking Fluids Market