
 Plain Bearing Market | 2026-2036
Plain Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
Plain Bearing Market Intelligence
The modularization of bearing assemblies with integrated seals and lubrication systems is shifting buyer preference away from individual component procurement. SKF Group leverages its expertise in integrated solutions to capture this trend in the industrial machinery space. Schaeffler Group competes by offering customized mechatronic systems that combine bearings with sensors and actuators. NTN Corporation sustains its market position through extensive manufacturing scale in standard journal bearing types.
A plain bearing is a mechanical component designed to support a load and reduce friction between moving parts through a sliding action, without using rolling elements. These components are often manufactured from materials like sintered bronze or feature advanced polymer coatings to ensure low friction and wear resistance in machinery. Composite and advanced plastic types represent the fastest-growing product segments, displacing traditional bronze in weight-sensitive applications like aerospace systems. The construction equipment application remains a mature and high-volume consumer, particularly for robust bimetal and steel journal bearings.
Material composition and lifecycle management are governed by frameworks like the EU's REACH regulation, which restricts the use of certain substances in bearing alloys and coatings. In the United States, EPA regulations concerning lubricants and potential contaminants influence the design of self-lubricated and maintenance-free bearing systems. Vendor selection increasingly depends on the ability to document material compliance and demonstrate performance in harsh, non-lubricated environments.
Market Dynamics
The plain bearing market's evolution is driven by the tension between performance demands for advanced materials and stringent environmental regulations governing substance use. This dynamic is particularly acute as end-users in aerospace and automotive seek lightweight, maintenance-free solutions while complying with global materials standards.
Growth Catalysts
- Self-Lubricating Materials:The development of polymer and composite bearings with embedded solid lubricants like PTFE and graphite eliminates the need for external lubrication, driving adoption in food processing and medical equipment where contamination is a concern.
- Chinese Industrial Policy:Government-led infrastructure investment and the "Made in China 2025" initiative sustain high-volume demand for robust steel and bimetal bearings used in domestic construction machinery, mining equipment, and heavy-duty trucks.
- Vehicle Electrification:The transition to electric vehicles creates demand for specialized plain bearings that reduce noise, vibration, and harshness (NVH) in electric motors, transmissions, and suspension systems, replacing bearings designed for internal combustion engines.
Market Restraints
- Raw Material Price Volatility:The production cost of traditional sintered bronze and bimetal bearings is directly exposed to price fluctuations in global commodity markets for copper, tin, and steel, creating margin pressure for manufacturers.
- Substitution from Rolling Bearings:In applications where space and weight are not primary constraints, rolling-element bearings can offer lower coefficients of friction and longer service lives, presenting a persistent substitution threat.
- Regulatory Compliance Costs:Adherence to substance regulations like the EU's REACH framework, which restricts lead in bearing alloys, requires significant R&D investment in material reformulation, testing, and process requalification for manufacturers.
Strategic Opportunities
- Renewable Energy Systems:Wind turbines and solar tracking systems require large-diameter, high-load plain bearings for blade pitch, yaw, and positioning mechanisms, offering a significant growth area for specialized composite and polymer solutions.
- Sensor Integration:Embedding miniature sensors within bearing structures to monitor wear, temperature, and load in real-time creates an opportunity to offer "smart" bearings that enable predictive maintenance in industrial automation and robotics.
- Agricultural Modernization:Demand for durable, maintenance-free polymer bearings is growing in developing agricultural economies like Brazil and India, where they can replace traditional greased metal bearings in tractors and harvesting equipment.
Industry Challenges
- Material Compliance Documentation:The administrative burden of documenting and proving material compliance with regulations like RoHS in Europe and EPA rules in the United States for every component batch is a significant operational challenge.
- Tribology Expertise Scarcity:A skills gap exists in attracting and retaining tribologists and material scientists capable of designing and validating new bearing materials for increasingly harsh operational environments, such as cryogenic or high-temperature applications.
- Legacy System Integration:Ensuring the tribological compatibility of advanced polymer bearings with existing shaft materials and surface finishes during equipment retrofits is complex and, if done incorrectly, can lead to premature system failure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plain Bearing Market |
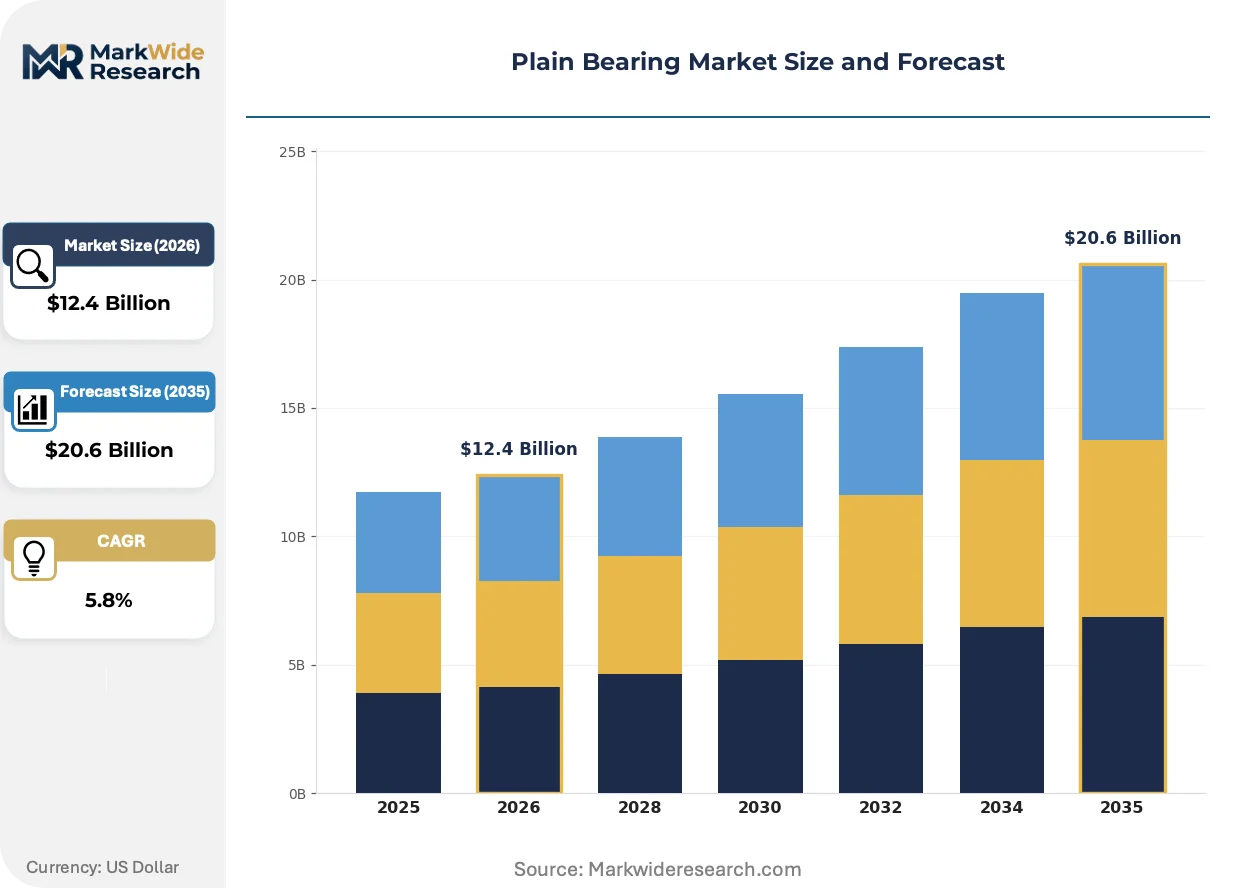
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bronze, Bimetal, Plastic, Composite, Steel Application: Construction Equipment, Agricultural Machinery, Marine Equipment, Aerospace Systems, Mining Machinery End User Industry: Manufacturing Plants, Transportation Providers, Heavy Machinery Operators, Energy Producers, Machinery Maintenance Firms Installation Type: Flanged, Sleeve, Journal, Thrust, Spherical |
| Companies Covered | Timken Company, NSK Ltd., SKF Group, RBC Bearings Incorporated, MinebeaMitsumi Inc., NTN Corporation, THK CO., Ltd., GGB Bearing Technology, Schaeffler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plain Bearing Market Strategic Shifts & Innovations
Material science innovation, driven by regulatory pressures and new performance requirements, is reshaping the competitive landscape. The push for lifecycle sustainability and maintenance-free operation is accelerating the shift from traditional metallic bearings to advanced engineered materials.
Self-lubricating composite materials combine structural fibers with polymer matrices like PEEK or PTFE. The aerospace and medical sectors are adopting these materials for their lightweight, non-galling, and contaminant-free properties. This technology is expanding into high-load industrial applications, including offshore equipment and hydraulic cylinders, previously served exclusively by greased metallic bearings.
The European Union's REACH regulation restricts or bans substances of very high concern, including lead, which has been a common element in bronze bearing alloys. This regulatory action is forcing a market-wide reformulation of materials supplied for equipment destined for the EU. The automotive and heavy machinery sectors are most affected, driving their transition to lead-free bronze alloys and advanced polymer alternatives.
Buyers in sophisticated industrial segments are moving away from sourcing individual components toward acquiring integrated, pre-assembled bearing assemblies. This model, which often includes seals and lubrication systems in a single cartridge, challenges component-level distributors and favors manufacturers who can provide system-level engineering support. This trend is most visible in German industrial automation and Japanese automotive manufacturing, where it reduces assembly time and total ownership costs.
Plain Bearing Market Segmentation
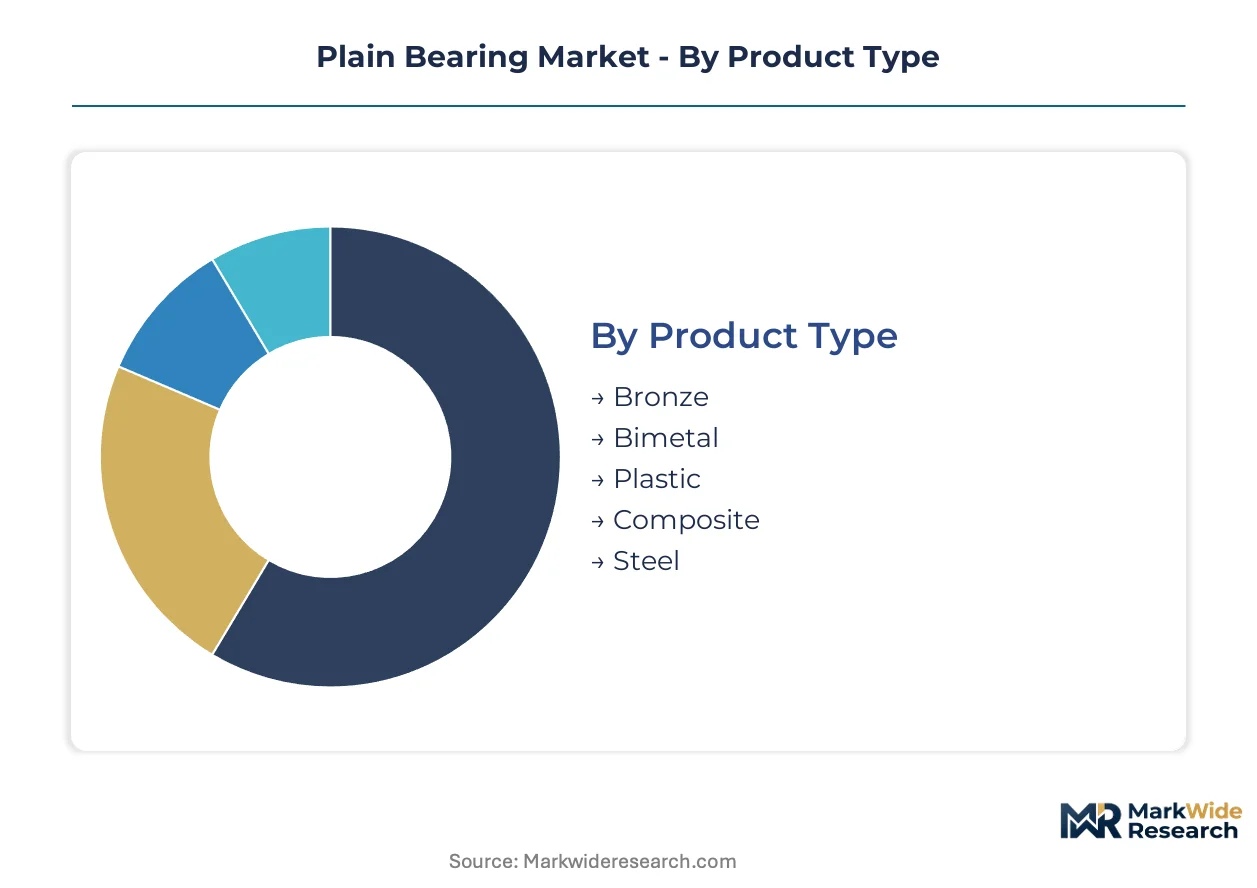
The plain bearing market's segmentation reflects the diverse performance criteria and operational demands across various industrial applications. Understanding these distinct segments is crucial for manufacturers to tailor material science innovations and integrated solutions effectively.
Product Type:
Buyers in the plain bearing market differentiate their material choices based on performance requirements, environmental compliance, and cost-efficiency.
- Composite:These materials combine structural fibers with polymer matrices like PEEK or PTFE, offering lightweight, non-galling properties. Demand concentrates in aerospace systems and medical equipment, driven by the need for contaminant-free operation and high strength-to-weight ratios.
- Plastic:Engineered polymers provide self-lubricating properties, reducing the need for external grease and oil, making them ideal for sensitive environments. The food processing and medical equipment sectors are increasingly adopting plastic bearings due to contamination concerns and cost-effectiveness.
- Bronze:Traditional bronze bearings, often sintered, offer good wear resistance and load capacity for general industrial machinery.
- Bimetal:Comprising a steel backing with a softer bearing alloy lining, bimetal types provide robustness for heavy-duty applications.
- Steel:Solid steel plain bearings are chosen for extremely high load capacities and durability in demanding industrial settings.
Bimetal leads volumes today; composite is gaining share fastest.
Application:
Operational environments and specific functional demands dictate the selection of plain bearings across diverse applications.
- Aerospace Systems:This sector requires lightweight, high-performance plain bearings capable of operating under extreme temperatures and loads. Demand is driven by the need for reduced weight and enhanced reliability in aircraft components.
- Construction Equipment:A mature and high-volume consumer, this segment demands robust bimetal and steel journal bearings for heavy-duty machinery. Manufacturing activity in China significantly concentrates consumption for these applications.
- Agricultural Machinery:Durable, maintenance-free polymer bearings are finding increased use in tractors and harvesting equipment.
- Marine Equipment:Plain bearings for marine applications require corrosion resistance and high load capacity for propulsion and steering systems.
- Mining Machinery:Heavy-duty trucks and excavation equipment in mining operations rely on robust steel and bimetal bearings for extreme operational conditions.
Aerospace systems and agricultural machinery exhibit the steepest expansion trajectory.
End User Industry:
Customer types influence plain bearing procurement patterns, ranging from direct OEM supply to aftermarket service providers.
- Heavy Machinery Operators:These operators, particularly in construction and mining, require durable and robust plain bearings for demanding, continuous operations. Government-led infrastructure investments in China sustain high-volume demand for these components.
- Transportation Providers:The transition to electric vehicles creates specialized demand for plain bearings that reduce noise, vibration, and harshness in electric motors and suspension systems. Vehicle electrification is reshaping material requirements.
- Manufacturing Plants:Industrial automation and robotics in manufacturing plants benefit from "smart" bearings with integrated sensors for predictive maintenance.
- Energy Producers:Wind turbines and solar tracking systems require large-diameter, high-load plain bearings for blade pitch and yaw mechanisms.
- Machinery Maintenance Firms:These firms focus on the aftermarket, providing replacement and retrofit plain bearings for existing equipment.
Heavy machinery operators consume substantial volumes, while energy producers are driving new demand.
Installation Type:
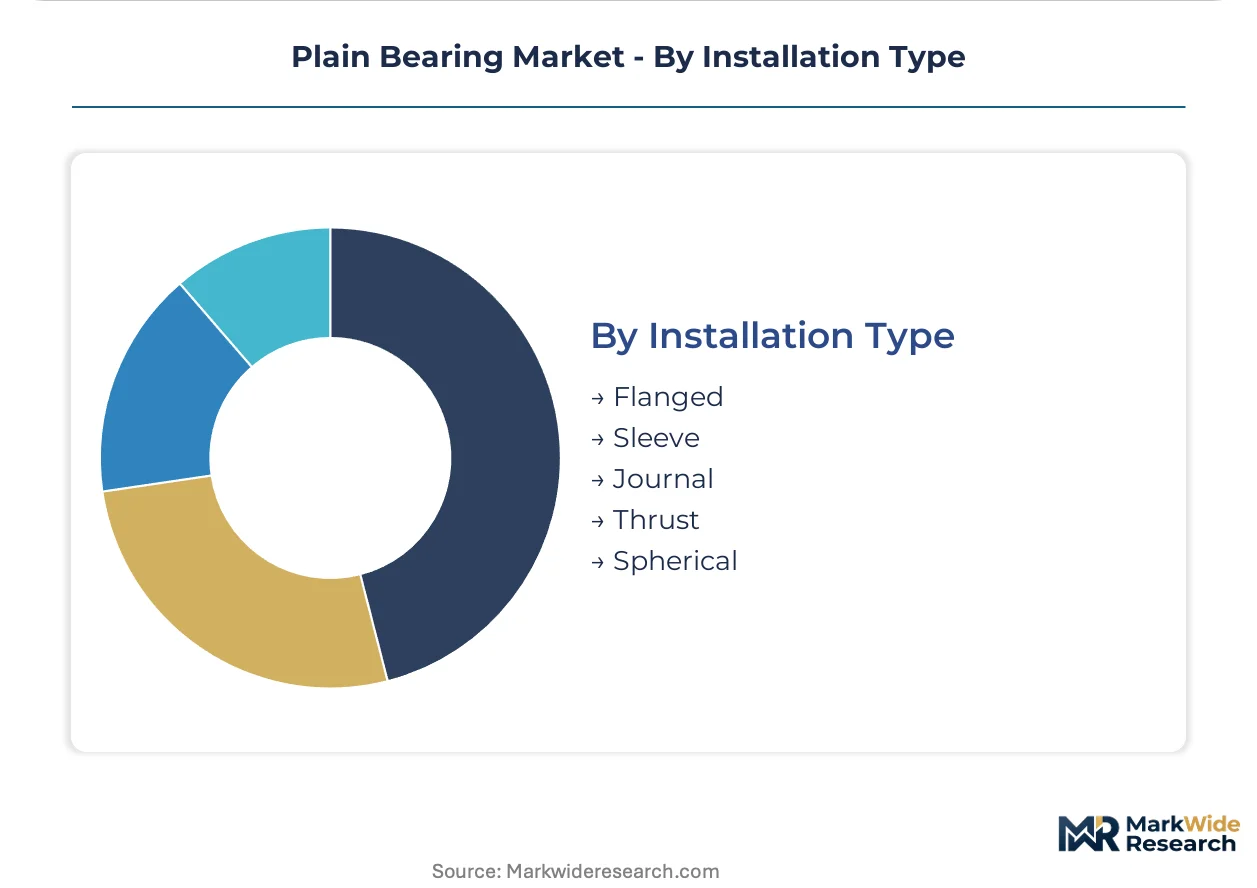
Functional design and the type of load supported are primary considerations for plain bearing installation types.
- Journal:These bearings are designed to support radial loads and are widely used in rotating shafts across various machinery. NTN Corporation sustains its market position through extensive manufacturing scale in standard journal bearing types.
- Sleeve:Simple and cost-effective, sleeve bearings are cylindrical components that provide a sliding surface for shafts. The development of self-lubricating composite materials expands their use into previously greased metallic bearing applications.
- Flanged:Flanged bearings combine radial and axial load support, providing mounting stability in applications requiring both types of load.
- Thrust:Specifically designed to support axial loads, thrust bearings are crucial in applications where force is exerted along the axis of rotation.
- Spherical:Spherical plain bearings accommodate misalignment between the shaft and housing, commonly found in agricultural and construction equipment.
Journal bearings maintain their widespread utility, with spherical types showing solid expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The plain bearing industry's foundational scaling emerged from the industrialization of Europe, particularly Germany, and the subsequent expansion of heavy machinery manufacturing. This historical context shaped early material science and application development. Today, global demand patterns reflect diverse industrial bases and regulatory environments.
United States
United States demand for plain bearings stems from its advanced aerospace systems and the ongoing vehicle electrification initiatives. EPA regulations concerning lubricants influence bearing design, promoting self-lubricated and maintenance-free systems. Major aerospace clusters in cities like Seattle drive innovation for lightweight, high-performance components.
China
Chinese industrial policy, including the "Made in China 2025" initiative, sustains high-volume demand for robust plain bearings. Government-led infrastructure investments concentrate consumption in construction equipment and heavy-duty trucks. The Yangtze River Delta region, a key manufacturing hub, drives significant production and application of bimetal and steel bearings.
Germany
Germany's industrial machinery sector and automotive industry require sophisticated plain bearing solutions, including integrated assemblies and mechatronic systems. The EU's REACH regulation restricts certain substances, compelling manufacturers to reformulate bearing alloys and coatings. Bavaria, a center for high-tech manufacturing, shows strong demand for precision and customized bearing components.
India
India's agricultural modernization efforts create substantial demand for durable, maintenance-free polymer bearings in farm equipment. The country's PLI scheme encourages domestic manufacturing, including components for industrial and automotive sectors. Industrial clusters in Pune and Chennai are seeing increased adoption of advanced bearing types for heavy machinery.
Plain Bearing Market Key Industry Players
Premium-margin players sit above commodity-margin players across product performance and customization capabilities. The market exhibits a tiered structure, with integrated solution providers and specialized material innovators occupying the upper echelons. High-volume standard bearing manufacturers form the base. Key competitive moves include strategic partnerships for advanced material development and portfolio diversification into smart bearing systems.
At the scale-driven end, NTN Corporation sustains its market position through extensive manufacturing scale in standard journal bearing types, anchoring the high-volume segment. SKF Group represents a major integrated solution provider, leveraging its expertise to capture the trend towards modular bearing assemblies with integrated seals and lubrication systems. Schaeffler Group occupies a position among innovators, exemplifying customized mechatronic systems that combine bearings with sensors and actuators, catering to advanced industrial automation and automotive applications. These players collectively illustrate the diverse strategic approaches within the plain bearing market.
| Leading Market Players |
|---|
| Timken Company |
| NSK Ltd. |
| SKF Group |
| RBC Bearings Incorporated |
| MinebeaMitsumi Inc. |
| NTN Corporation |
| THK CO., Ltd. |
| GGB Bearing Technology |
| Schaeffler Group |
Cost & Logistics Intelligence
Self-lubricating composite materials are reshaping cost economics and supply concentration in the plain bearing market. This material transition simultaneously reduces maintenance costs for end-users and shifts raw material dependencies for manufacturers.
Pricing Analysis
A tiered pricing structure across premium, standard, and economy levels characterizes the plain bearing market. Price differentiation stems from material composition, such as advanced polymers versus traditional bronze, and the level of integration, including seals and lubrication systems. Pricing softness reflects raw material price volatility for copper and steel, creating margin pressure for bimetal manufacturers. Aerospace systems buyers prioritize performance over cost, while construction equipment operators exhibit higher price sensitivity for high-volume orders.
Supply Chain Analysis
Regulatory compliance requirements, like the EU's REACH framework, act as a critical gating factor for plain bearing suppliers. Geographic supply concentrations for raw materials include China for steel and copper, and Europe for specialized polymer components. Raw material dependencies on copper, tin, and steel expose manufacturers to global commodity market fluctuations. Single-source vulnerability for advanced polymer precursors represents a structural supply chain risk, while distribution runs primarily through direct OEM supply and specialized aftermarket firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plain bearing market acts as a regulatory compounder, with the EU's REACH regulation driving market-wide reformulation of materials. This regulatory milestone accelerates the shift towards lead-free alloys and advanced polymer alternatives.
For Market Incumbents: Acquire specialized material science startups focusing on advanced polymers and lead-free alloys to mitigate regulatory risks. Expand manufacturing capacity in regions like the Yangtze River Delta to capture high-volume construction equipment demand. This defensive move counters the threat of material substitution from new entrants and ensures compliance with global standards. Invest in R&D for integrated sensor technologies to enhance product differentiation and leverage predictive maintenance trends.
For New Entrants and Emerging Players: Online technical support platforms offer a digital-channel route to penetrate niche applications in industrial automation and robotics. Target developing agricultural economies like India and Brazil with durable, maintenance-free polymer bearings, leveraging their underpenetrated market for farm equipment. A go-to-market angle focusing on lifecycle cost reduction and environmental compliance can differentiate offerings. Focus on specialized composite solutions for renewable energy systems, which demand high-load, maintenance-free components.
For Investors and Strategic Acquirers: Roll-up economics work for specialized material innovators because structural fragmentation across advanced polymer and composite technologies allows for consolidation. The market exhibits long-term viability, driven by increasing performance demands in aerospace and vehicle electrification. Target mid-sized firms with strong intellectual property in self-lubricating materials or sensor integration capabilities. Watch for new regulatory mandates driving material compliance as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire Advanced Material Startups | Securing intellectual property in self-lubricating composites enhances product portfolio and regulatory compliance. |
| Expand Integrated Solution Offerings | Bundling bearings with seals and lubrication systems captures buyer preference in industrial machinery. |
| Invest in Sensor Integration R&D | Developing "smart" bearings enables predictive maintenance capabilities for industrial automation clients. |
| Target Renewable Energy Applications | Specialized composite bearings can address high-load requirements in wind turbines and solar trackers. |
| Develop Lead-Free Bearing Alloys | Reformulating materials to comply with EU REACH regulations ensures market access in automotive and heavy machinery. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a comprehensive view of the plain bearing market. Primary research involved discussions with R&D directors, procurement managers, plant engineers, and regulatory compliance officers across key geographies. Secondary validation drew from industry association reports, government economic data, company annual reports, and patent filings. This approach ensured bottom-up and top-down triangulation for robust market sizing.
Historical performance data provided the comparable-period framing, anchoring the forecast window for plain bearing market projections. The analytical framework modeled segmentation dimensions including product type, application, end-user industry, installation type, and regional regulatory clusters. Compound annual growth rates were derived through a multi-variable regression analysis. Key industry-specific forecast inputs included vehicle electrification projections and global infrastructure spending plans.
The model assumes a particular technology adoption path; alternative pathways for advanced polymer materials would alter the outlook. Forecasts reflect assumptions regarding raw material price stability and the consistent enforcement of environmental regulations. A model refresh is warranted upon material change in global economic growth rates or significant disruptive material science breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Catalyst Bins Market
Industrial Materials
Thermal Spray Guns Market
Industrial Materials
High Purity Quartz Market
Industrial Materials
Plastic Gears Market
Industrial Materials
Soil Stabilization Materials Market
Industrial Materials
Weatherstrip Seal Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
HV Glass Insulator Market
Industrial Materials
Wood Shavings Market
Industrial Materials
Hose Reinforcement Wire Market
Industrial Materials
Acrylic Sheet Market
Industrial Materials
Industrial Heaters Market
Industrial Materials
Pre-Painted Steel Coil Market
Industrial Materials
Diamond Wire Market