
 Concentrated Milk Fat Market | 2026-2036
Concentrated Milk Fat Market Size, Share, and Industry Trends Forecast 2026-2036
Concentrated Milk Fat Market Analysis
Bakery applications are repositioning concentrated milk fat toward premium formulation channels. Fonterra Co-operative Group leverages its New Zealand sourcing base to supply industrial bakeries across Asia-Pacific. Arla Foods anchors European supply through its Danish processing network. FrieslandCampina differentiates via specialized anhydrous milk fat grades for chocolate tempering.
Concentrated milk fat denotes dairy fat stripped of water and non-fat solids, typically achieving 99.8% milk fat content through centrifugal separation and vacuum drying. Manufacturers deploy it for flavor stability, extended shelf life, and precise fat functionality in temperature-sensitive recipes. Anhydrous milk fat commands the largest value share among product types due to its interchangeability with cocoa butter and clean-label appeal. Bakery applications generate the fastest volume growth as artisan and industrial producers reformulate away from hydrogenated oils. Food manufacturers represent the deepest margin pool among end users, locking in multi-year supply contracts.
The EU Green Deal and FDA dairy standards collectively shape product specifications and cross-border trade flows. REACH compliance in Europe and USDA grading in the United States determine access thresholds for imported concentrated milk fat. Stakeholders must monitor evolving emissions rules and fat purity benchmarks to secure formulation partnerships and avoid supply disqualification.
Market Dynamics
The EU Green Deal is compressing margins across European dairy processors while simultaneously accelerating capital deployment into vacuum concentration and membrane filtration technologies that slash thermal energy use per kilogram of milk fat extracted.
Growth Catalysts
- Clean-label bakery reformulation:Industrial bakeries in Germany and France are eliminating hydrogenated oils from laminated doughs and shortening blends, creating pull-through demand for anhydrous milk fat with precise melting profiles.
- REACH compliance as market access gate:ECHA registration requirements for imported dairy lipids are filtering out smaller traders, consolidating procurement relationships with established processors who maintain full substance dossiers.
- Chocolate tempering specification tightening:Confectionery houses are specifying narrower polymorphic stability windows for cocoa butter equivalents, favoring specialized AMF grades with controlled crystal seeding behavior.
Market Restraints
- Butter price volatility transmission:Cream input costs fluctuate with New Zealand and EU auction cycles, compressing blender margins when fat values spike without corresponding finished goods pricing power.
- Supply concentration in Oceania:Fonterra and a limited co-operative network control the majority of exportable anhydrous milk fat volume, creating single-source risk for Asian manufacturers without backward integration into cream sourcing.
- Plant lipid substitution:Fractionated palm stearin and shea butter derivatives are capturing volume in cost-sensitive confectionery applications where clean-label positioning carries lower consumer premium.
Strategic Opportunities
- Indian organized dairy expansion:Amul and Mother Dairy are building fractionation capacity to serve domestic bakery and ice cream chains, creating partnership openings for European technology licensors.
- EU carbon border adjustment mechanism:CBAM phase-in for dairy-derived imports will advantage processors with verified low-emission concentration technologies, rewarding early adopters of mechanical vapor recompression.
- Specialized nutrition channels:Infant formula manufacturers are requesting microencapsulated milk fat with specific surface lipid compositions for enhanced oxidative stability during spray drying.
Industry Challenges
- Fractionation technologist scarcity:The specialized knowledge required to operate controlled-melting-point AMF lines is concentrated among retiring European dairy engineers, constraining capacity expansion timelines.
- Multi-jurisdiction certification stacking:Simultaneous kosher, halal, and organic audits for a single production batch extend release timelines and tie up quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concentrated Milk Fat Market |
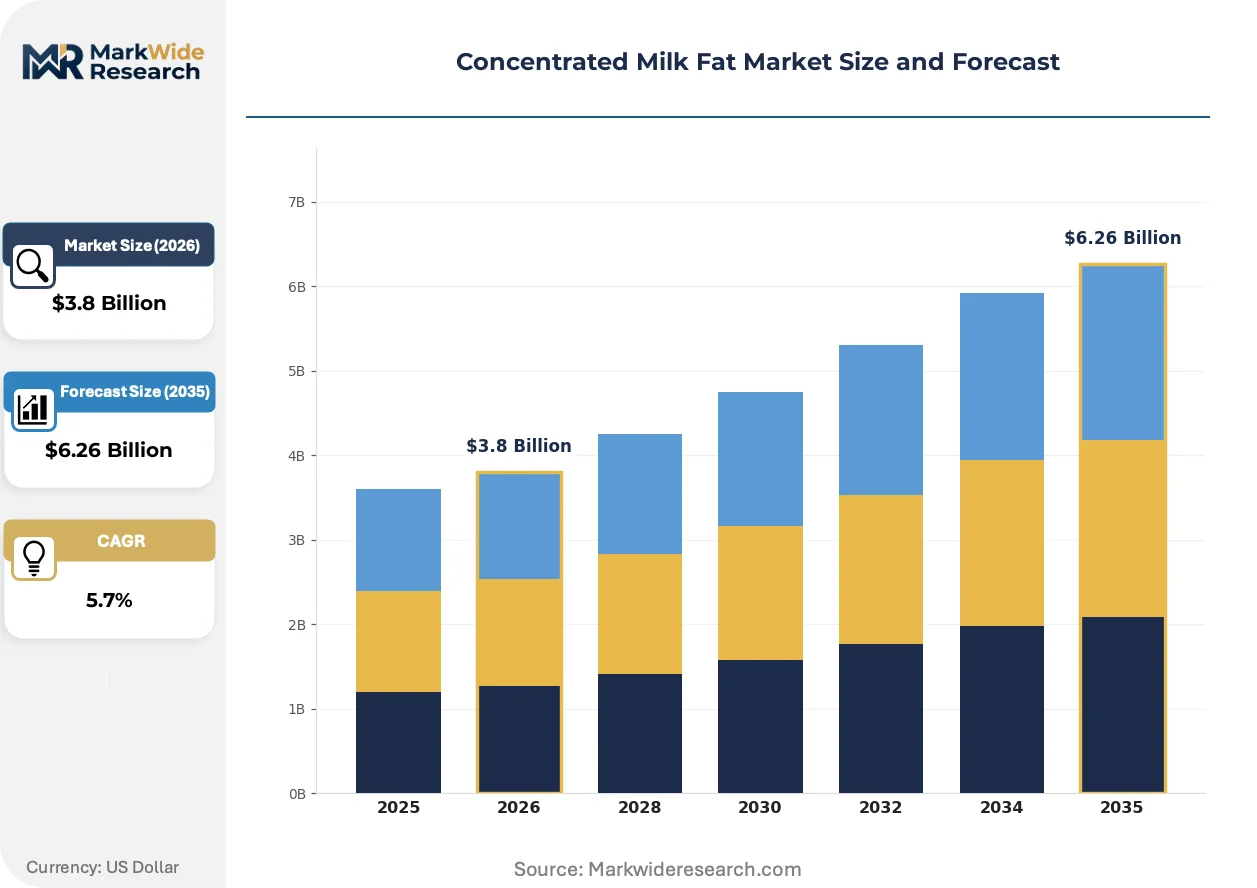
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter Oil, Anhydrous Milk Fat, Ghee, Cream Application: Dairy Products, Confectionery, Bakery, Sauces End User: Food Manufacturers, Retailers, Restaurants, Households Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Arla Foods, Grassland Dairy Products Inc., Fonterra Co-operative Group, Dairy Farmers of America, California Dairies Inc., FrieslandCampina, Darigold Inc., Glanbia plc, Lactalis Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concentrated Milk Fat Market Emerging Trajectories
Membrane and thermal processing advances are rewriting the capital-efficiency frontier for milk fat concentration, while regulatory carbon accounting and buyer procurement centralization are restructuring how value pools get distributed across the supply chain.
Ultrafiltration-diafiltration cascades paired with direct-contact cooling crystallization are rewriting the economics of anhydrous milk fat production. Arla Foods and FrieslandCampina are retrofitting Danish and Dutch plants with these hybrid lines. The technology is rewriting the competitive map by enabling smaller cream processors to achieve export-grade purity without the energy intensity of traditional vacuum drying.
The EU Green Deal's emissions benchmarking requirements are forcing dairy processors to document Scope 1 and 2 carbon intensity per ton of milk fat shipped. Industrial bakeries in Germany and the Netherlands are now requesting verified low-carbon AMF certificates as standard contract terms. The regulation is rewriting procurement specifications, with buyers in the Benelux region already screening suppliers against Science Based Targets initiative alignment.
Centralized procurement by pan-European bakery and confectionery groups is consolidating purchase decisions into fewer hands. Regional procurement directors are replacing plant-level buyers, standardizing specifications across multi-country manufacturing footprints. This shift is most visible in Germany, where industrial bakeries now negotiate annual fat supply agreements covering production across Poland, Czechia, and domestic facilities.
Concentrated Milk Fat Market Segmentation
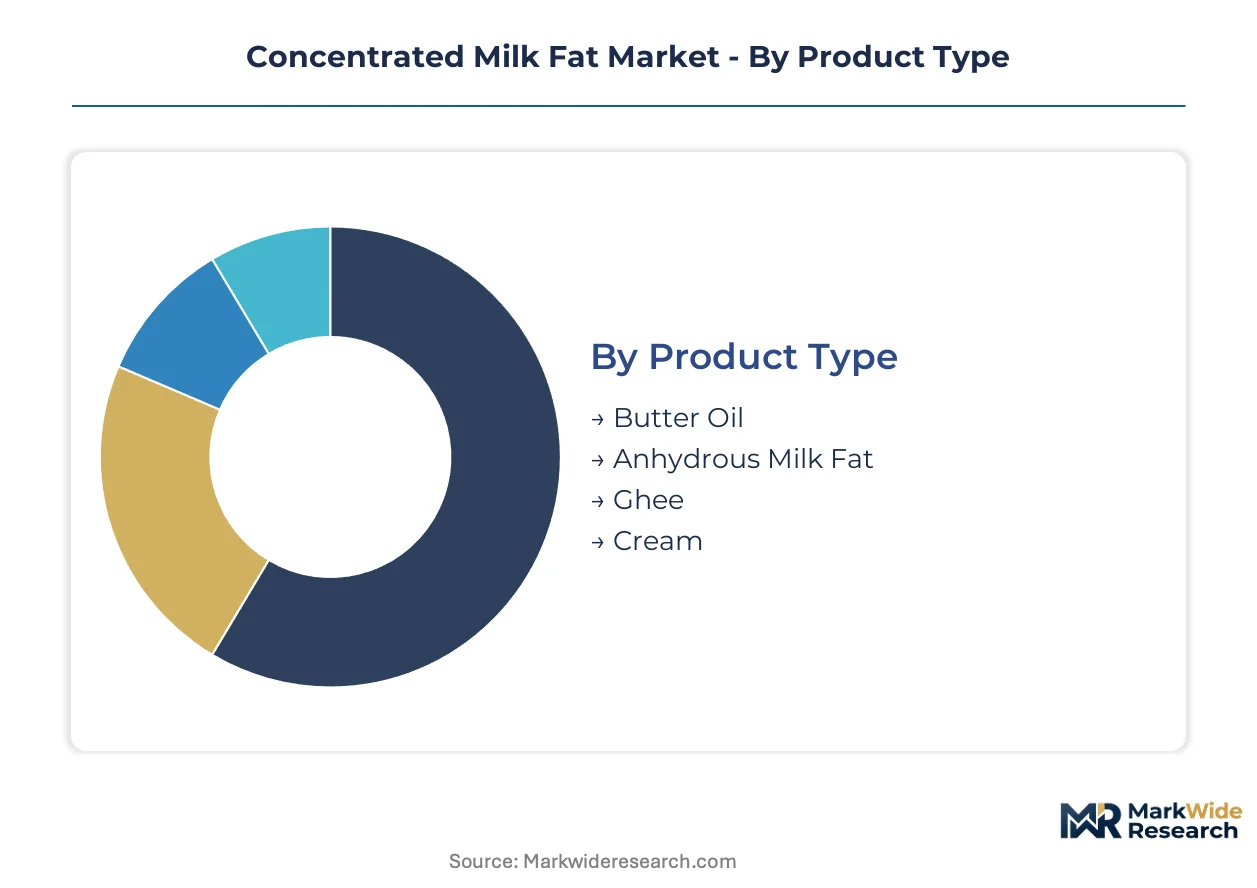
Segmentation in concentrated milk fat reveals how product specifications, application requirements, and channel economics fragment procurement patterns. Buyers optimize across purity grades, melting profiles, and supply security rather than treating milk fat as a commodity input.
Product Type:
Integration depth varies sharply across product types, with some grades functioning as standalone ingredients while others embed into complex formulations requiring precise functional behavior.
- Anhydrous Milk Fat:Achieves 99.8% milk fat content through centrifugal separation and vacuum drying, delivering flavor stability and extended shelf life. Industrial bakeries in Germany specify this grade for laminated dough applications where precise melting profiles eliminate hydrogenated oils. REACH compliance requirements filter out smaller traders, consolidating procurement with established processors maintaining full substance dossiers.
- Butter Oil:Retains trace moisture and milk solids, typically 99.0-99.5% fat content, suited for applications tolerating slight compositional variation. Confectionery houses in France and Belgium source butter oil for cost-sensitive recipes where polymorphic stability demands are less stringent than chocolate tempering specifications.
- Ghee:Clarified butter with characteristic nutty flavor profile from traditional heating processes, commanding premium positioning in South Asian cuisine applications.
- Cream:Lower concentration stage retaining significant water content, serving as input feedstock for downstream fractionation rather than finished ingredient deployment.
Volume placements concentrate in Anhydrous Milk Fat; the faster expansion belongs to Butter Oil as mid-tier confectionery producers seek functional alternatives to cocoa butter.
Application:
Application segmentation tracks how thermal stability requirements and clean-label positioning reshape formulation choices across food manufacturing verticals.
- Bakery:Industrial producers in Germany and France are eliminating hydrogenated oils from laminated doughs and shortening blends, creating pull-through demand for anhydrous milk fat with controlled crystal seeding behavior. Artisan bakeries specify narrower polymorphic stability windows than commodity bread operations.
- Confectionery:Chocolate tempering applications demand specialized AMF grades with verified low-carbon certificates under EU Green Deal procurement terms now standard in Benelux buyer contracts.
- Dairy Products:Ice cream and recombined dairy applications utilize milk fat for mouthfeel and freeze-thaw stability, with infant formula manufacturers requesting microencapsulated variants for oxidative stability during spray drying.
- Sauces:Emulsion stability in hot-fill and retort applications drives specification of specific melting point fractions, though volume remains constrained by cost competition from vegetable oil alternatives.
Margin capture concentrates in Confectionery; the steepest volume trajectory belongs to Bakery as clean-label reformulation accelerates across European industrial baking.
End User:
End user segmentation exposes divergent procurement sophistication, from multi-year supply contracts with verified carbon accounting to spot-market household purchases.
- Food Manufacturers:Pan-European bakery and confectionery groups centralize procurement decisions, with regional directors replacing plant-level buyers and standardizing specifications across Poland, Czechia, and German manufacturing footprints. These buyers lock in multi-year supply agreements with Science Based Targets initiative alignment requirements.
- Retailers:Private-label development teams specify AMF for premium store-brand chocolate and bakery lines, though volume remains secondary to foodservice and industrial channels.
- Restaurants:High-volume foodservice operations in institutional catering specify ghee and butter oil for ethnic cuisine authenticity, with procurement fragmented across regional distributors.
- Households:Direct consumer purchases concentrate in ethnic grocery channels for ghee, with minimal penetration of anhydrous milk fat due to lack of culinary familiarity.
Contract value concentrates in Food Manufacturers; the expanding procurement sophistication belongs to Retailers as private-label premiumization extends into clean-label bakery and confectionery.
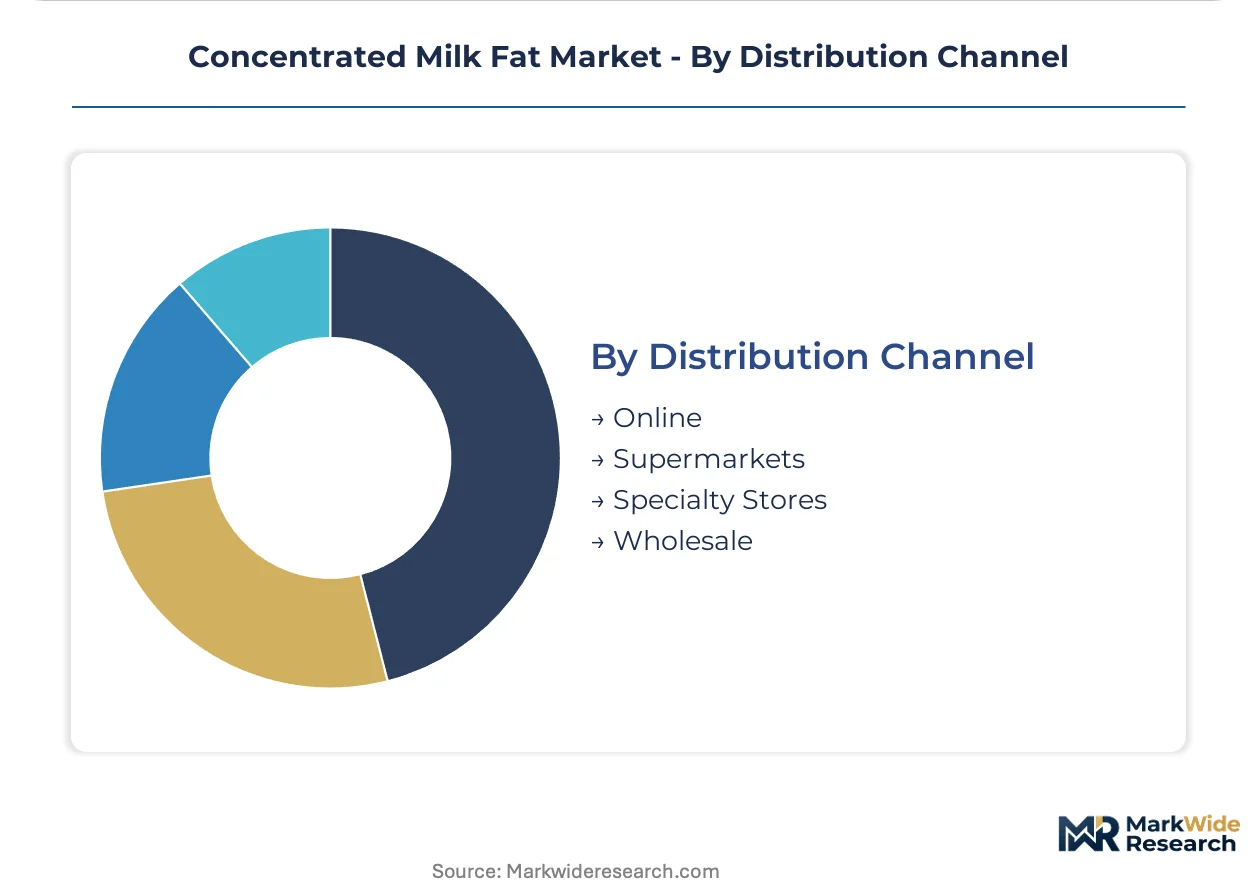
Distribution Channel:
Channel segmentation reflects how buyer scale and specification complexity determine route-to-market economics, with bulk industrial supply diverging sharply from packaged retail distribution.
- Wholesale:Tanker and intermediate bulk container shipments dominate anhydrous milk fat movement to industrial bakeries and confectionery houses, with Fonterra and Arla Foods anchoring supply through established dairy processor networks.
- Supermarkets:Packaged ghee and premium butter oil SKUs reach household and small restaurant buyers through conventional grocery retail, with shelf placement concentrated in ethnic food aisles.
- Specialty Stores:Artisan bakery supply shops and confectionery ingredient distributors serve small-batch producers requiring technical consultation on tempering specifications.
- Online:Direct-to-producer platforms and B2B marketplaces are gaining traction for spot purchases and specialty grade sourcing, though bulk industrial contracts remain offline.
Shipment volume concentrates in Wholesale; the channel gaining share fastest belongs to Online as smaller confectionery producers seek alternative sourcing routes beyond traditional processor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Maharashtra and Gujarat concentrate Indian dairy processing capacity, attracting European technology licensors seeking joint ventures with organized cooperatives.
Germany
Industrial bakeries in Lower Saxony and North Rhine-Westphalia anchor European procurement volumes for anhydrous milk fat, eliminating hydrogenated oils from laminated doughs. The EU Green Deal's emissions benchmarking requirements now appear in standard Benelux buyer contracts. Frankfurt-Rhine-Main logistics clusters coordinate multi-country distribution to Poland and Czechia.
United States
USDA grading standards determine access thresholds for imported concentrated milk fat, filtering smaller traders from food manufacturer supply chains. Wisconsin and California dairy cooperatives dominate domestic fractionation capacity. Chicago Mercantile Exchange butter futures transmit price volatility directly to blender margins.
New Zealand
Fonterra Co-operative Group controls the majority of exportable anhydrous milk fat volume, creating single-source concentration risk for Asian manufacturers. The country's national dairy regulator enforces strict compositional standards for international shipments. Canterbury processing clusters supply industrial bakeries across Asia-Pacific.
India
Amul and Mother Dairy are building fractionation capacity to serve domestic bakery and ice cream chains. FSSAI standards govern milk fat purity benchmarks for organized sector procurement. Anand and Delhi-NCR dairy clusters attract European mechanical vapor recompression technology partnerships.
Netherlands
FrieslandCampina anchors European supply through Dutch processing networks, retrofitting plants with ultrafiltration-diafiltration hybrid lines. REACH compliance requirements filter out traders lacking full substance dossiers. Rotterdam-Antwerp port complexes handle bulk tanker shipments to German confectionery houses.
Concentrated Milk Fat Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with cooperative structures dominating exportable volume and investor-owned processors capturing premium formulation channels. The vendor base concentrates among Oceania-based exporters and European dairy giants, leaving limited niche openings for regional specialists. Three archetypes prevail: scale-driven cooperatives with backward cream integration, technology-licensing processors with carbon-verified production, and regional dairy collectives serving domestic bakery chains. Capacity expansion and strategic technology licensing represent the dominant competitive moves, as energy-efficient concentration systems rewrite capital-efficiency frontiers.
Within the scale-driven cooperative tier, Fonterra Co-operative Group and Arla Foods exemplify export-oriented structures with integrated cream sourcing. FrieslandCampina occupies a position among technology-forward processors differentiating via specialized anhydrous milk fat grades. Dairy Farmers of America and California Dairies Inc. represent North American cooperative archetypes with domestic fractionation focus. Glanbia plc and Lactalis Ingredients sit within the diversified dairy ingredients segment, while Grassland Dairy Products Inc. and Darigold Inc. anchor regional US supply positions.
| Leading Market Players |
|---|
| Arla Foods |
| Grassland Dairy Products Inc. |
| Fonterra Co-operative Group |
| Dairy Farmers of America |
| California Dairies Inc. |
| FrieslandCampina |
| Darigold Inc. |
| Glanbia plc |
| Lactalis Ingredients |
| Others |
Supply Flow & Price Mechanics
Fractionation technologist scarcity in Denmark and the Netherlands widens pricing-tier spreads as labor-cost differentials between European engineering hubs and emerging dairy clusters reshape procurement economics for energy-efficient concentration systems.
Pricing Analysis
Lead-time-driven premiums separate contract-grade anhydrous milk fat from spot-market butter oil, with industrial bakeries paying up for guaranteed quarterly delivery while confectionery houses absorb discount pricing for excess inventory. A three-tier pricing structure across premium, standard, and economy levels tracks certification stacking—kosher-halal-organic triple verification commands top rates, while single-certification grades trade at mid-tier, and uncertified spot lots fill economy channels. Pricing pressure stems from cream input volatility transmitted through New Zealand and EU auction cycles, squeezing blender margins when fat values spike without corresponding finished goods pricing power. Food manufacturers show least price sensitivity, locking multi-year agreements with carbon-verified supply, while cost-sensitive confectionery producers in Southern Europe exhibit highest elasticity, substituting toward fractionated palm stearin when spreads widen.
Supply Chain Analysis
Tanker freight economics from Rotterdam-Antwerp clusters to German industrial bakeries concentrate cost structure analysis, with bulk liquid logistics consuming margin share that packaged-ghee distributors avoid through shorter-haul retail distribution. Supply concentrates in New Zealand, Denmark, and the Netherlands, with Fonterra and Arla Foods controlling exportable volume through cooperative structures. Raw material flows draw from pasture-based cream in Oceania, mixed-feed dairy in Europe, and emerging buffalo-milk fractions in India. Single-source vulnerability runs through Fonterra's dominance of Asia-Pacific exportable anhydrous milk fat, creating procurement risk for Japanese and Southeast Asian manufacturers without backward cream integration. Distribution runs through processor-direct tanker shipments for industrial accounts, regional dairy distributors for foodservice, and ethnic grocery wholesale for ghee channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The concentrated milk fat sector sits in a technology-transition phase as mechanical vapor recompression and ultrafiltration-diafiltration hybrid lines displace legacy vacuum drying infrastructure, rewarding early equipment adopters with carbon-verified production certificates.
For Market Incumbents: Lock in multi-year supply agreements with pan-European bakery groups before CBAM phase-in advantages processors with verified low-emission concentration technologies. Secure retiring European dairy engineering talent through knowledge-transfer partnerships with Indian organized dairy expansion projects, mitigating fractionation technologist scarcity that constrains competitor capacity timelines. Defend margin position by anchoring procurement relationships with Science Based Targets initiative alignment requirements that filter spot-market traders from qualified supplier lists. For New Entrants and Emerging Players: Specialty ingredient distributors serving artisan confectionery producers represent the most accessible channel partner type for microencapsulated milk fat variants targeting infant formula manufacturers. White-space concentration sits with Indian domestic bakery and ice cream chains as Amul and Mother Dairy build fractionation capacity, creating partnership openings for European technology licensors without established local presence. Target the microencapsulated nutrition channel through direct technical sales to spray-drying operations, bypassing consolidated wholesale distribution controlled by incumbent processors. For Investors and Strategic Acquirers: Re-rating potential sits with technology-licensing processors given EU carbon border adjustment mechanism phase-in rewarding verified low-emission concentration technologies. Long-term viability over a five-to-ten year window favors mechanical vapor recompression equipment suppliers and hybrid membrane-thermal system operators over legacy vacuum drying assets. Acquisition target archetype: regional dairy collectives with captive cream supply and retrofit-ready plant infrastructure. The signal to watch is Benelux buyer contract terms mandating Science Based Targets initiative alignment as standard procurement language, indicating premium-tier market access gates.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Vapor Recompression Retrofit | EU Green Deal emissions benchmarking rewards early adopters with CBAM-advantaged export positioning. |
| Backward Integration into Cream Sourcing | Fonterra's single-source dominance creates vulnerability for Asian manufacturers without captive supply. |
| Multi-Certification Quality Assurance Investment | Kosher-halal-organic stacking extends release timelines but unlocks premium-tier pricing spreads. |
| Joint Venture with Indian Organized Dairy | Amul and Mother Dairy fractionation buildouts attract European technology licensors seeking local manufacturing footholds. |
| Microencapsulated Product Line Development | Infant formula manufacturers request specific surface lipid compositions for oxidative stability during spray drying. |
Methodological Framework
Multi-period observation of Fonterra auction price cycles, EU dairy processing emissions benchmarks, and Indian organized dairy capacity buildouts anchored the trend analysis, supplemented by interviews with plant managers at Danish and Dutch fractionation facilities, procurement directors at German industrial bakeries, regulatory affairs specialists tracking REACH compliance, and technical R&D directors developing microencapsulation systems. Secondary validation drew from ECHA substance dossier databases, EU Green Deal implementation tracking reports, FSSAI dairy standards documentation, and SEC filings of listed dairy ingredients processors. Bottom-up volume triangulation across product type, application, and end-user segments was cross-checked against top-down value estimates derived from trade flow analysis.
An input-output matrix framed the analytical approach, modeling concentrated milk fat supply through product type, application vertical, end-user procurement sophistication, and regional production hub characteristics across the projection horizon. Segmentation dimensions included purity grade tier, thermal processing technology, certification stacking level, and channel structure. CAGRs were derived from trend extrapolation of clean-label bakery reformulation rates, chocolate tempering specification tightening patterns, and infant formula microencapsulation adoption curves, calibrated against historical dairy ingredients demand elasticity and regulatory compliance cost trajectories.
Several conditions sit outside the modeled scope, including abrupt butter price volatility spikes beyond historical auction cycle ranges, geopolitical disruption to Oceania export logistics, and unanticipated breakthroughs in plant lipid functional equivalence. Forecasts reflect documented assumptions around EU Green Deal implementation pacing and CBAM phase-in schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Goat Milk Market
Dairy Products
US Cheese Market
Dairy Products
Cheese Packaging Market
Dairy Products
A2 Protein Milk Market
Dairy Products
Japan Casein Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
Flavored Yogurt Market
Dairy Products
Europe Flavored Milk Market
Dairy Products
Low Cholesterol Cheese Market
Dairy Products
GCC Cheese Market
Dairy Products
Ultra High Temperature Sterilized Milk Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
Donkey Milk Market
Dairy Products
Asia-Pacific Flavored Milk Market
Dairy Products
Dairy Carton Market
Dairy Products
Low Fat Yogurt Market