
 Dermatology Cryosurgery Units Market | 2026-2036
Dermatology Cryosurgery Units Market Size, Share, and Industry Trends Forecast 2026-2036
Dermatology Cryosurgery Units Market Outlook
The dermatology cryosurgery equipment landscape is restructuring around a widening gap between premium precision systems and basic commodity units. Brymill Cryogenic Systems leverages its liquid nitrogen expertise to dominate hospital procurement channels. CryoPen, Inc. differentiates through portable pen-style platforms that anchor outpatient dermatology workflows.
Dermatology cryosurgery units are precision medical instruments that deliver controlled cryogenic temperatures to targeted skin tissue for therapeutic destruction, typically operating at minus 196 degrees Celsius using liquid nitrogen or alternative cryogens to achieve selective cell necrosis. These devices serve dermatologists, cosmetic surgeons, and hospital specialists requiring minimally invasive treatment of benign and precancerous lesions. Portable units command expanding share among dermatology clinics seeking point-of-care flexibility, while liquid nitrogen technology sustains margin leadership despite cryogen-Enhanced alternatives gaining traction in cosmetic surgery centers. Pen-style devices represent the fastest-growing configuration, though desktop systems retain volume dominance in hospital settings where multi-procedure throughput justifies capital investment.
The FDA's 510(k) framework governs device clearance in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for cryosurgical equipment marketed in Europe. BIS certification mandates in India and NMPA oversight in China create divergent compliance pathways that fragment manufacturer go-to-market strategies. Stakeholders must monitor evolving cryogen handling regulations and reimbursement coding shifts that will determine which technology configurations achieve sustainable commercial traction.
Market Dynamics
The dermatology cryosurgery market restructures around liquid nitrogen supply chain concentration and the FDA's 510(k) clearance pathway, which compresses product development timelines for pen-style devices while elevating compliance costs for new entrants.
Growth Catalysts
- Outpatient procedural volume:Dermatology clinics in Germany and the United States expand lesion removal services under favorable reimbursement codes, driving unit placement in ambulatory settings.
- MDR clinical evidence requirements:The EU Medical Device Regulation mandates robust technical documentation for cryosurgical equipment, creating competitive moats for established manufacturers with regulatory infrastructure.
- Liquid nitrogen infrastructure:Hospital procurement channels leverage existing cryogen supply contracts to justify premium desktop system investments over portable alternatives.
Market Restraints
- Cryogen cost volatility:Liquid nitrogen pricing fluctuates with industrial gas supply dynamics, compressing margins for high-volume users dependent on consistent cryogen access.
- Supply concentration risk:Brymill Cryogenic Systems dominates liquid nitrogen device manufacturing, creating single-source vulnerability for hospital procurement teams.
- Technical limitation:Portable pen-style units deliver reduced freeze depth compared to desktop systems, restricting their therapeutic applicability for thicker lesions.
Strategic Opportunities
- Underpenetrated cosmetic surgery centers:Cryogen-enhanced alternatives gain traction in aesthetic practices seeking reduced infrastructure requirements compared to liquid nitrogen systems.
- India BIS certification pathway:Domestic manufacturing incentives under PLI scheme structures attract regional assembly investments for price-sensitive South Asian markets.
- Technology convergence:Integrated imaging systems combining cryosurgery with real-time lesion visualization enable precision workflows in academic medical centers.
Industry Challenges
- Cryogen handling certification:OSHA workplace safety mandates require specialized training for liquid nitrogen device operators, extending deployment timelines.
- 510(k) documentation burden:FDA substantial equivalence determinations demand extensive predicate device analysis, delaying market entry for novel cryogen formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermatology Cryosurgery Units Market |
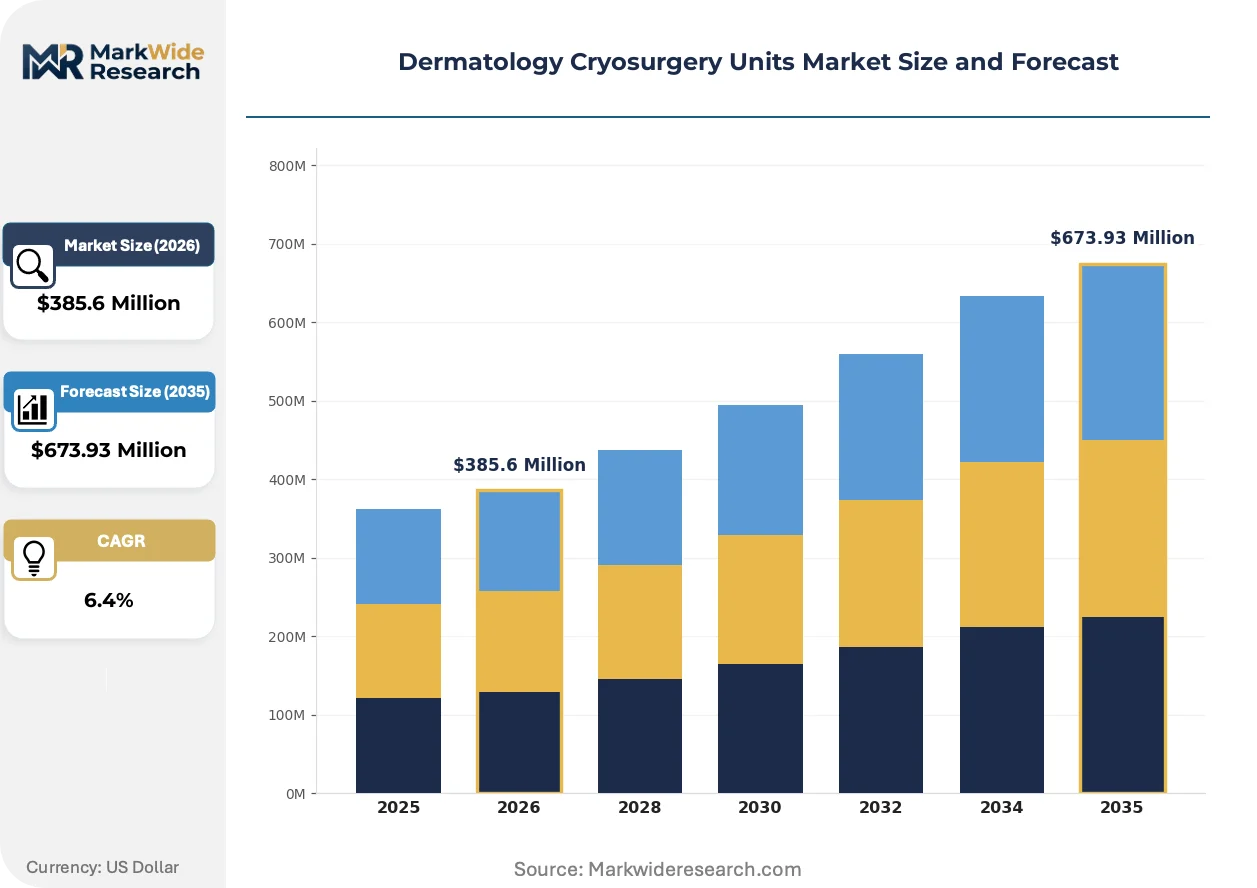
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Units, Portable Units, Pen-Style Devices, Cryo-Spray Devices Technology: Liquid Nitrogen, Carbon Dioxide, Cryogen-Enhanced, Electrosurgery End User: Dermatology Clinics, Hospitals, Cosmetic Surgery Centers, Research Laboratories Application: Wart Removal, Skin Lesion Treatment, Cryoablation, Psoriasis Management |
| Companies Covered | Brymill Cryogenic Systems, CryoPen, Inc., CryoConcepts LP, CryoIQ AB, Special Medical Technology Co., Ltd., BOVIE MEDICAL, CORTEX TECHNOLOGY ApS, H&O Equipment, CooperSurgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermatology Cryosurgery Units Market Strategic Shifts
Device miniaturization converges with enhanced temperature control algorithms to redefine precision parameters in dermatological cryotherapy. Regulatory harmonization efforts across major markets reshape competitive positioning.
Cryogen-enhanced systems using nitrous oxide cartridges are integrating closed-loop temperature monitoring to achieve lesion-specific necrosis depth without liquid nitrogen infrastructure. Cosmetic surgery centers in Spain and Italy adopt these platforms for rapid patient turnover. The technology is integrating automated freeze-thaw cycle programming that standardizes outcomes across operator skill levels.
The EU Medical Device Regulation imposes strengthened post-market surveillance obligations on cryosurgical equipment manufacturers marketing in Europe. Technical documentation requirements now encompass clinical performance data beyond traditional bench testing. German notified bodies process the majority of MDR certifications for cryosurgical devices, concentrating regulatory expertise in Central Europe.
Service unbundling separates device procurement from cryogen supply contracts in United States hospital systems. Group purchasing organizations negotiate multi-year liquid nitrogen agreements independent of capital equipment acquisitions. This pattern appears most pronounced in Texas and Florida dermatology networks seeking operational flexibility.
Dermatology Cryosurgery Units Market Segmentation
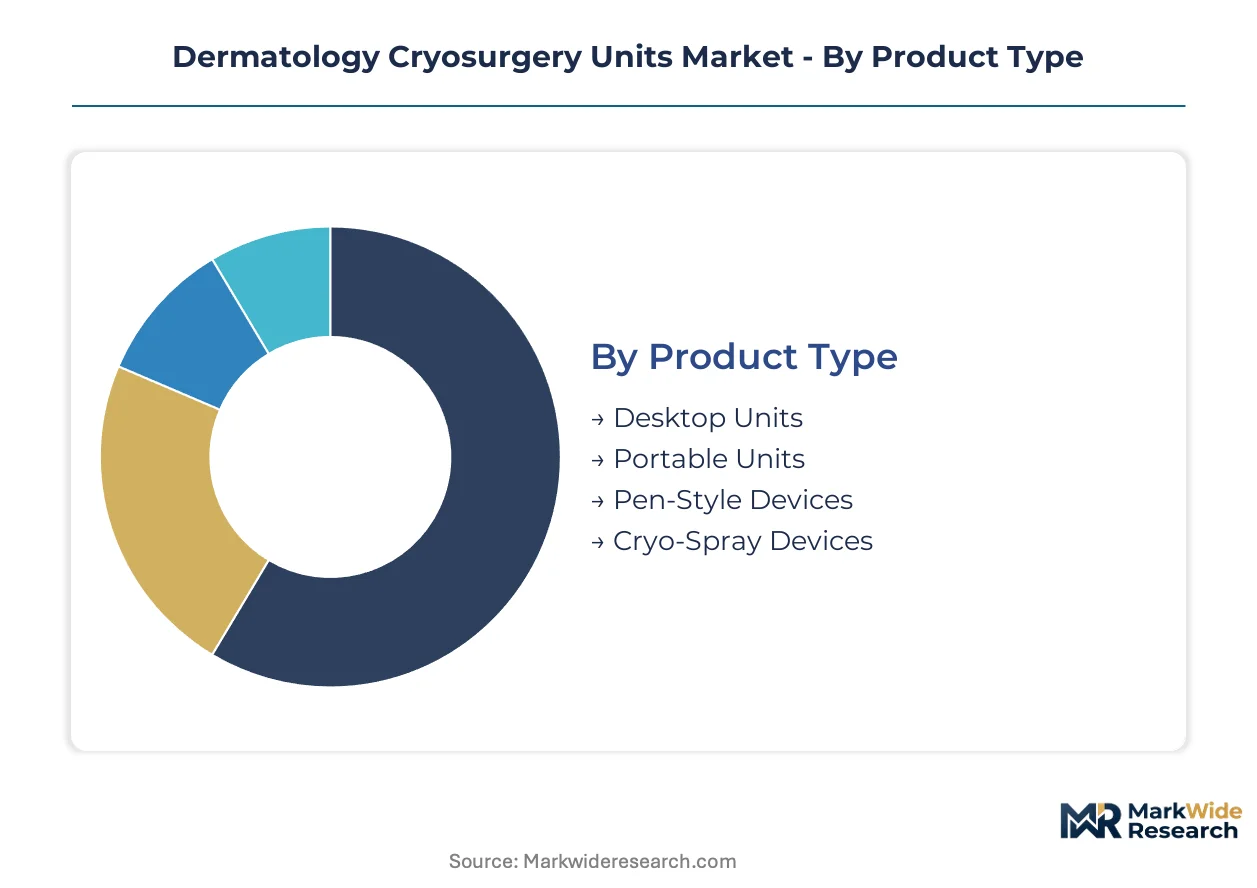
Segmentation in dermatology cryosurgery equipment reveals how regulatory pathways and clinical workflows shape procurement decisions across settings. Understanding these divisions exposes where compliance burdens concentrate and which configurations command premium positioning.
Product Type:
FDA 510(k) clearance timelines vary sharply across product configurations, with pen-style devices navigating streamlined substantial equivalence reviews while desktop systems trigger extended predicate analysis and clinical data requirements.
- Desktop Units:These capital-intensive systems integrate multi-probe capacity and sustained cryogen reservoirs for high-throughput hospital environments. Demand concentrates in German academic medical centers where reimbursement for complex lesion procedures justifies infrastructure investment. The EU MDR technical documentation burden falls heaviest on this segment due to electrical safety and cryogen containment protocols.
- Pen-Style Devices:Handheld precision instruments deliver targeted freeze-thaw cycles through ergonomic single-probe designs optimized for ambulatory dermatology workflows. Outpatient clinics in the United States expand adoption under favorable procedural coding, though OSHA operator certification requirements extend deployment timelines. These devices climb the fastest in placement volume.
- Portable Units:Mobile cart-based systems balance cryogen capacity with relocation flexibility for multi-room clinic configurations.
- Cryo-Spray Devices:Open-spray delivery mechanisms enable broad field treatment of superficial lesions without probe contact.
Desktop units sit at the top of the volume ranking, with pen-style devices climbing the fastest.
Technology:
Cost tier stratification separates infrastructure-dependent modalities from cartridge-based alternatives, with liquid nitrogen systems commanding capital premiums and cryogen-enhanced platforms reducing total cost of ownership for smaller practices.
- Liquid Nitrogen:Minus 196-degree Celsius cryogen delivery achieves deepest tissue necrosis for thick lesions and cryoablation applications. Hospital procurement in Germany and the United States leverages existing industrial gas supply contracts to justify premium system investments. FDA 510(k) predicates for liquid nitrogen devices are extensively documented, accelerating clearance for incremental innovations.
- Cryogen-Enhanced:Nitrous oxide cartridge systems eliminate external cryogen infrastructure while integrating closed-loop temperature monitoring for standardized outcomes. Cosmetic surgery centers in Spain and Italy adopt these platforms for rapid patient turnover without storage facility requirements. These systems expand most quickly in aesthetic practice penetration.
- Carbon Dioxide:Solid CO2 slug delivery provides intermediate freeze depth for superficial dermatological applications.
- Electrosurgery:Thermal ablation alternative competes for lesion removal indications with distinct reimbursement coding.
Liquid nitrogen technology maintains the dominant revenue share, while cryogen-enhanced alternatives gain share fastest among new clinic establishments.
End User:
Customer type determines procurement channel access, with hospital systems leveraging group purchasing organization contracts and independent dermatology practices navigating direct manufacturer relationships.
- Dermatology Clinics:Independent and network-affiliated outpatient facilities drive pen-style device volume through point-of-care workflow optimization. German dermatology practice density supports premium unit penetration under favorable statutory reimbursement. BIS certification requirements in India shape supplier selection for imported equipment.
- Hospitals:Integrated health systems prioritize desktop multi-probe capacity for academic and community medical centers. United States hospital networks in Texas and Florida unbundle device procurement from cryogen supply contracts to preserve operational flexibility. These facilities face the steepest OSHA compliance burdens for cryogen handling certification.
- Cosmetic Surgery Centers:Aesthetic-focused practices favor reduced-infrastructure alternatives for elective lesion removal.
- Research Laboratories:Academic and commercial R&D facilities utilize specialized configurations for protocol development and device validation.
Hospitals command the largest installed base, with dermatology clinics expanding placement most rapidly.
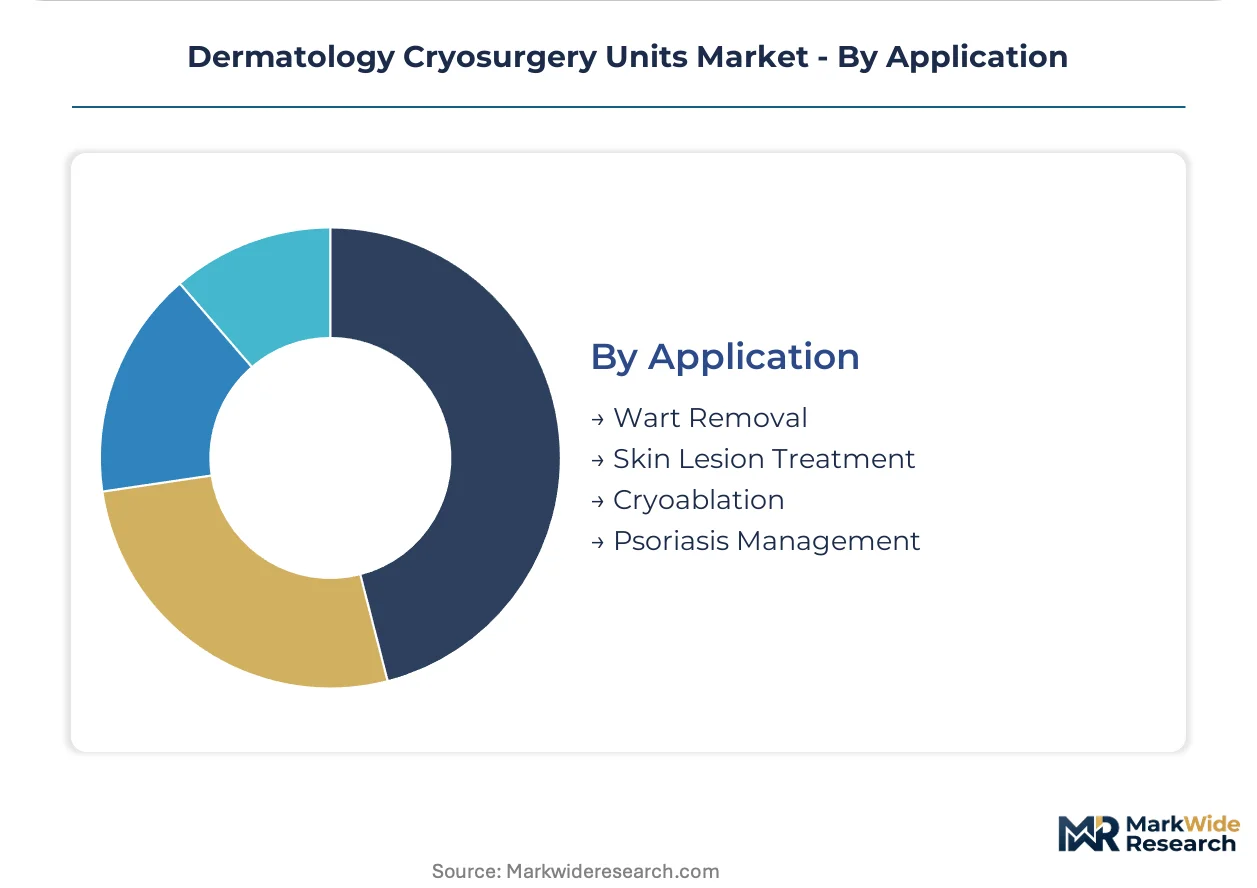
Application:
Procedure reimbursement codes and clinical evidence requirements segment demand by therapeutic indication, with precancerous lesion treatments commanding stronger coverage than cosmetic indications.
- Skin Lesion Treatment:Benign and precancerous lesion removal constitutes the core therapeutic application across all device configurations. German dermatology reimbursement frameworks specifically cover cryosurgical actinic keratosis treatment, supporting premium device penetration. NMPA oversight in China imposes clinical trial requirements for precancerous indication claims.
- Wart Removal:Viral lesion cryotherapy represents high-volume, lower-reimbursement outpatient procedures. Pediatric and adult dermatology clinics in the United States perform these procedures under modified procedural codes with reduced facility fees. This application shows steepest volume growth in school-age population segments.
- Cryoablation:Deep tissue freeze protocols for selected malignancies require specialized probe configurations.
- Psoriasis Management:Cryotherapy adjunctive treatment for plaque psoriasis remains investigational in most jurisdictions.
Skin lesion treatment dominates procedure volume, with wart removal applications expanding most quickly in pediatric-focused practices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dermatology specialists cluster in Germany's university hospital networks and the United States' metropolitan outpatient corridors, anchoring regional demand for precision cryosurgical equipment.
United States
FDA 510(k) clearance pathways compress product development timelines for pen-style devices, while Texas and Florida dermatology networks unbundle device procurement from cryogen supply contracts. OSHA workplace safety mandates require specialized operator certification, extending deployment timelines in hospital systems. The Dallas-Fort Worth metroplex concentrates ambulatory surgery center investments in liquid nitrogen infrastructure.
Germany
Dermatology practice density and statutory reimbursement for cryosurgical actinic keratosis treatment support premium unit penetration. The EU Medical Device Regulation concentrates regulatory expertise in German notified bodies, processing the majority of MDR certifications for cryosurgical devices. Munich and Berlin academic medical centers drive demand for multi-probe desktop systems with integrated imaging capabilities.
China
NMPA oversight imposes clinical trial requirements for precancerous indication claims, fragmenting manufacturer go-to-market strategies. Domestic manufacturing incentives under industrial policy structures attract regional assembly investments for price-sensitive markets. Shanghai and Guangzhou hospital procurement teams prioritize cryogen-enhanced alternatives to reduce infrastructure requirements in expanding outpatient facilities.
India
BIS certification mandates shape supplier selection for imported equipment, while domestic production incentives under PLI scheme structures attract regional assembly investments. Price-sensitive South Asian markets favor portable configurations over capital-intensive desktop systems. Maharashtra and Karnataka dermatology clinics expand adoption of pen-style devices for point-of-care lesion removal workflows.
Spain
Cosmetic surgery centers in Madrid and Barcelona adopt cryogen-enhanced nitrous oxide platforms for rapid patient turnover without liquid nitrogen storage facilities. Favorable procedural economics in aesthetic practices drive fastest-segment growth for reduced-infrastructure alternatives. The Catalan medical device cluster supports regional distribution networks serving Mediterranean cosmetic surgery markets.
Dermatology Cryosurgery Units Market Competitive Environment
Top-tier vendors anchor hospital procurement channels through liquid nitrogen expertise, while mid-tier specialists compete on portable pen-style configurations. The vendor base stratifies across infrastructure-dependent and reduced-infrastructure technology vectors. Three archetypes dominate: cryogen supply integrators, workflow optimization specialists, and aesthetic-focused platform developers. Competitive moves concentrate on regulatory infrastructure investments and cryogen supply contract bundling.
Within the cryogen supply integration tier, Brymill Cryogenic Systems occupies a position exemplifying liquid nitrogen infrastructure dominance. CryoPen, Inc. and CryoConcepts LP represent the portable precision archetype, anchoring outpatient dermatology workflows through ergonomic single-probe designs. These three entities collectively illustrate how technology configuration determines channel access and procurement positioning across hospital and ambulatory settings.
| Leading Market Players |
|---|
| Brymill Cryogenic Systems |
| CryoPen, Inc. |
| CryoConcepts LP |
| CryoIQ AB |
| Special Medical Technology Co., Ltd. |
| BOVIE MEDICAL |
| CORTEX TECHNOLOGY ApS |
| H&O Equipment |
| CooperSurgical |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement unbundling in Texas and Florida dermatology networks forces suppliers to separate device sales from liquid nitrogen service contracts, compressing margin capture and pushing vendors toward standalone equipment pricing models.
Pricing Analysis
Bundled cryogen-plus-device contracts are fragmenting into unbundled procurement structures across United States hospital systems. Three-tier pricing structure across premium desktop, standard portable, and economy pen-style levels stratifies by FDA clearance tier and after-sales service bundling. Cost compression in the portable segment is intensifying because cryogen-enhanced alternatives eliminate infrastructure requirements. Independent dermatology clinics exhibit highest price sensitivity, while German academic medical centers demonstrate lowest sensitivity due to statutory reimbursement guarantees.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China anchor hub-and-spoke patterns for cryosurgical equipment fulfillment. Manufacturing concentrates in Germany for precision desktop systems and China for portable device assembly, drawing from stainless steel probe components, cryogen containment vessels, and temperature control sensors. Single-source vulnerability persists in liquid nitrogen cryogen supply, where industrial gas contracts lock buyers into multi-year commitments. Distribution runs through group purchasing organizations in United States hospital networks and direct manufacturer relationships in European dermatology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation's strengthened clinical evidence requirements compound competitive moats for established manufacturers, elevating regulatory infrastructure as the primary demand driver across European markets.
For Market Incumbents: Hedge against cryogen-enhanced substitution by securing backward integration into liquid nitrogen distribution networks. Deepen FDA 510(k) predicate libraries to accelerate clearance timelines for incremental innovations. Defensive patent positioning around closed-loop temperature monitoring algorithms protects against emerging nitrous oxide platform developers. For New Entrants and Emerging Players: Begin with cosmetic surgery centers in Spain and Italy, where reduced-infrastructure requirements and rapid patient turnover economics favor cryogen-enhanced platforms. Target India's price-sensitive dermatology clinics through BIS-certified portable pen-style configurations. A reimbursement strategy anchored to favorable procedural coding in ambulatory settings accelerates initial placement velocity. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier specialists possessing MDR certification infrastructure and established German notified body relationships. Long-term viability hinges on regulatory capacity rather than manufacturing scale alone. Watch for OSHA cryogen handling certification mandates as the inflection indicator signaling structural shift toward reduced-infrastructure alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Investment | German notified body relationships create European market access barriers for competitors. |
| Cryogen Supply Contract Unbundling | Texas and Florida hospital networks preserve operational flexibility through separated procurement. |
| Closed-Loop Temperature Integration | Automated freeze-thaw programming standardizes outcomes across operator skill levels. |
| India PLI Scheme Assembly | Domestic manufacturing incentives attract regional investments for price-sensitive South Asian markets. |
| Reimbursement Strategy Development | Favorable procedural coding in United States ambulatory settings drives pen-style adoption. |
Study Parameters
Direct dialogue with dermatology clinic operators, hospital procurement managers, biomedical engineers, and GPO contracts specialists anchored qualitative grounding. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up and top-down triangulation cross-checked unit placement estimates against cryogen consumption data and procedural volume reports.
Segment-level outputs across the projection horizon reflect modeled dimensions including product configuration, cryogen technology type, end-user facility category, and therapeutic application indication. CAGRs were derived from regression analysis against historical placement trajectories and reimbursement code evolution. Industry-specific forecast inputs incorporated OSHA certification mandate timelines and EU MDR transition completion rates.
Several conditions sit outside the modeled scope, including unannounced regulatory enforcement actions, cryogen price volatility spikes, and predicate device recalls affecting 510(k) clearance pathways. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Dermatology Devices Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Seborrheic Keratosis Treatment Market
Dermatology
Folliculitis Market
Dermatology
Microneedling Market
Dermatology
Hyperpigmentation Treatment Market
Dermatology
Dermatological Products Market
Dermatology
Common Warts Market
Dermatology
Global Radiodermatitis Market
Dermatology
Australia Skin Laser Market
Dermatology
Acne Vulgaris Market
Dermatology
Athletes Foot (Tinea Pedis) Treatment Market
Dermatology
Psoriasis Treatment Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Keloid Treatment Market
Dermatology
Europe Scar Treatment Market