
 Laparoscopic Surgical Robot Market | 2026-2036
Laparoscopic Surgical Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Laparoscopic Surgical Robot Market Insights
EU MDR is hardening the cost-of-entry calculus for laparoscopic surgical robot manufacturers seeking CE marking in Europe. Intuitive Surgical leverages decades of clinical data to sustain its installed base dominance. Medtronic anchors its competitive position through deep integration of surgical navigation with robotic platforms. CMR Surgical differentiates via a portable, modular system architecture targeting cost-sensitive hospital segments.
A laparoscopic surgical robot is a computer-assisted electromechanical system that manipulates instruments through small abdominal incisions under stereoscopic visualization, typically operating at 7-15 mm port diameters with sub-millimeter tremor filtration. The primary purpose is to enable minimally invasive procedures with enhanced dexterity, reduced blood loss, and shorter patient recovery trajectories. Robotic arms and visualization systems capture the dominant share of hardware value pools, while software solutions represent the fastest-expanding margin segment as hospitals seek procedure analytics and remote mentoring capabilities. Applications in gynecologic surgery and urologic procedures remain the most mature revenue channels, whereas bariatric surgery is gaining robotic penetration as sleeve gastrectomy protocols standardize.
FDA premarket clearance pathways, EU MDR technical documentation requirements, and NMPA innovation approval channels in China collectively shape product development timelines and geographic launch sequencing for manufacturers. ISO 13485 quality management standards and IEC 62304 software lifecycle controls add compliance layers that favor established players with dedicated regulatory infrastructure. Stakeholders must monitor how reimbursement decisions by national health technology assessment bodies influence hospital capital allocation for robotic surgery programs.
Market Dynamics
Hospital capital allocation committees now prioritize robotic platforms that demonstrate measurable length-of-stay reduction, compressing vendor selection cycles and elevating outcome-analytics capabilities over hardware specifications alone.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for surgical robotics with novel indication claims are shortening time-to-revenue for qualified submissions.
- CMR Surgical's modular architecture:Portable, cart-based systems reduce installation footprint and enable multi-OR deployment without dedicated infrastructure.
- Bariatric surgery standardization:Sleeve gastrectomy protocol maturation is driving robotic penetration in metabolic surgical programs.
Market Restraints
- EU MDR technical documentation:Expanded clinical evidence requirements for Class III devices are extending CE marking timelines and inflating regulatory compliance costs.
- Supply concentration in precision motors:German and Japanese suppliers dominate harmonic drive actuators, creating single-source vulnerability for arm articulation subsystems.
- Disposable instrument economics:Per-procedure consumable costs exceed reusable laparoscopic instrument depreciation, constraining adoption in capitated reimbursement environments.
Strategic Opportunities
- Remote mentoring infrastructure:5G-enabled telesurgery observation platforms allow academic medical centers to monetize procedural expertise across distributed hospital networks.
- India's PLI scheme for medical devices:Production-linked incentives for domestic manufacturing are attracting component assembly investments to reduce import duties on finished systems.
- Ophthalmic microsurgery convergence:Adaptation of tremor-filtering algorithms from abdominal platforms to vitreoretinal procedures opens adjacent specialty markets.
Industry Challenges
- Surgeon proctoring bottlenecks:Intuitive Surgical's da Vinci training ecosystem maintains credentialing capacity constraints that limit competitor system onboarding velocity.
- Legacy OR integration:Anesthesia information systems and imaging PACS require custom API development for seamless robotic platform connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laparoscopic Surgical Robot Market |
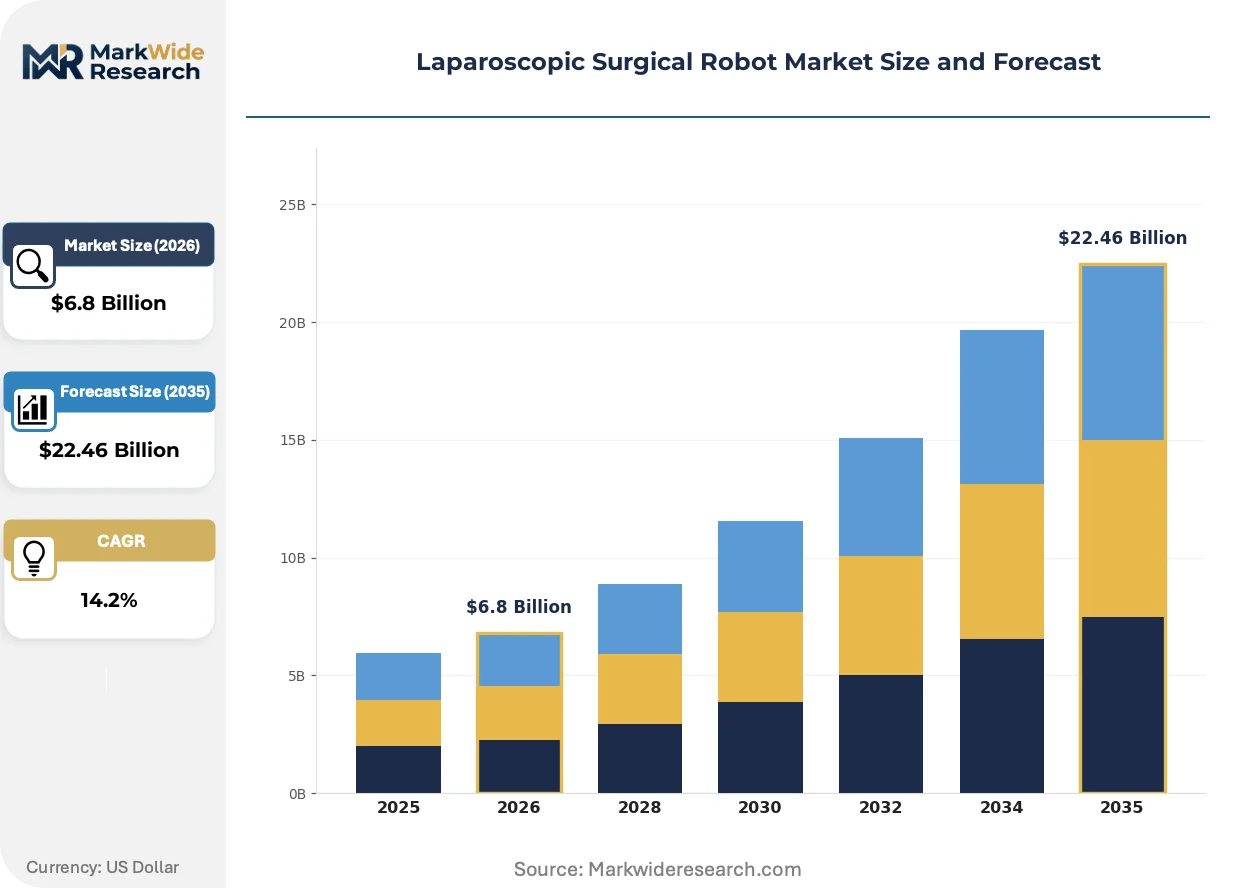
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Arms, Visualization Systems, Surgical Instruments, Software Solutions Application: Hernia Repair, Gynecologic Surgery, Bariatric Surgery, Urologic Procedures End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Academic Institutions Technology: Telemanipulation, Haptics, 3D Visualization, Enhanced Motion Control |
| Companies Covered | Intuitive Surgical, Stryker Corporation, Medtronic, Smith & Nephew, Zimmer Biomet, Renishaw, Asensus Surgical, CMR Surgical, Titan Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laparoscopic Surgical Robot Market Trends and Innovations
Real-time surgical analytics platforms are compressing the feedback loop between intraoperative decision-making and postoperative quality measurement, reshaping how hospitals evaluate platform value.
Haptic feedback restoration through force-sensing instrument shafts is unifying tactile tissue assessment with robotic precision. Tertiary hospital general surgery departments are adopting these systems at accelerating cadence as fellowship programs integrate force-feedback training modules. This convergence is unifying open-surgery diagnostic confidence with minimally invasive access trajectories, eroding residual skepticism among senior surgeons.
EU MDR's post-market surveillance requirements are mandating systematic implantable device registries for robotic surgical staplers. Manufacturers must now fund multi-year follow-up studies as a condition of continued CE marking. High-volume bariatric centers in Germany and the Netherlands are restructuring data collection infrastructure to satisfy these obligations.
Hospital procurement committees are consolidating vendor relationships through single-source robotic platform commitments. Integrated delivery networks in the United States are replacing multi-manufacturer evaluations with enterprise-wide standardization mandates. This concentration is most visible among Catholic health systems seeking to simplify training logistics across geographically dispersed facilities.
Laparoscopic Surgical Robot Market Segmentation
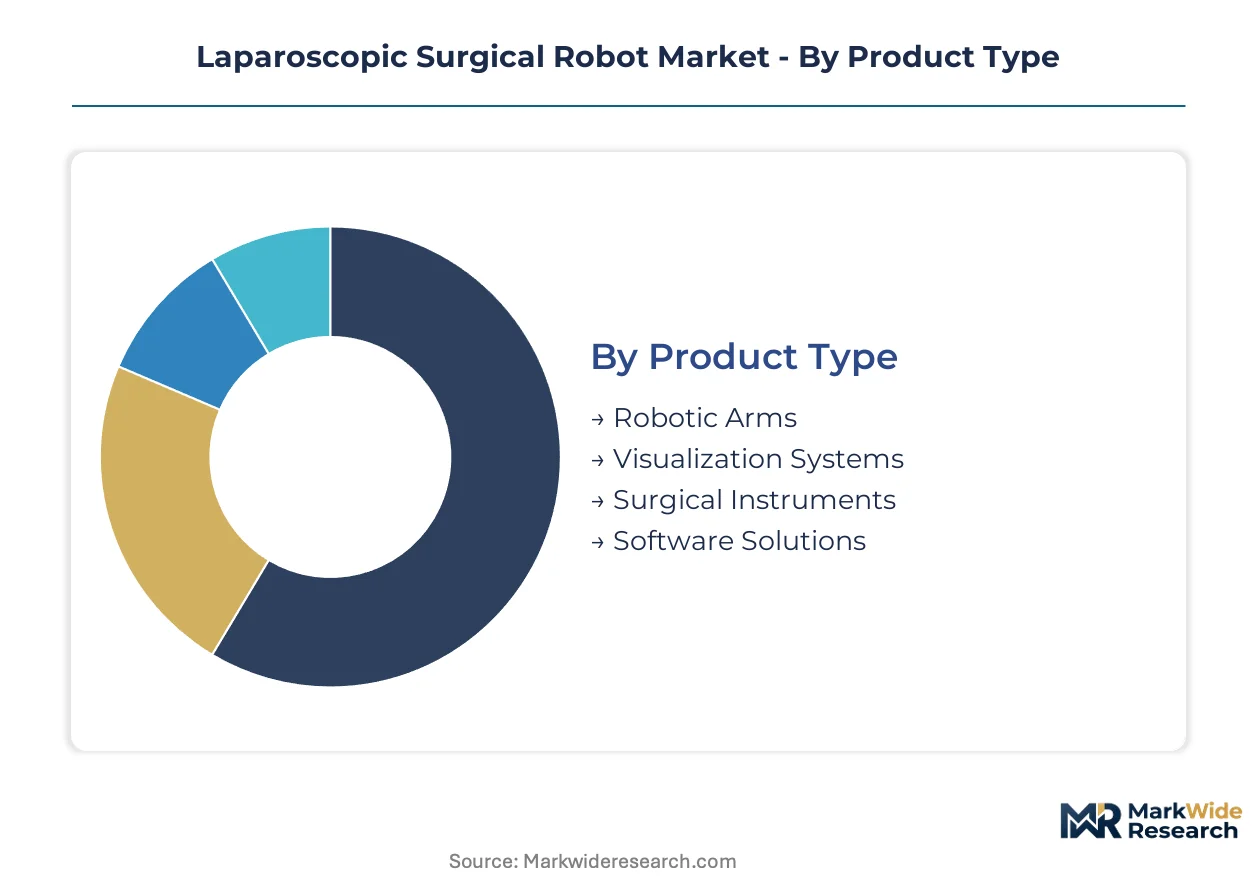
Segmentation in laparoscopic surgical robotics reveals how hardware commoditization, software monetization, and procedure-specific workflows reshape vendor competitive positioning. Distinct value pools emerge across product architectures, clinical applications, and institutional purchasing patterns.
Product Type:
Standardization dominates at the robotic arm level, while software layers enable deep customization for procedure-specific workflows.
- Robotic Arms:Electromechanical articulation systems with 6-7 degrees of freedom and harmonic drive actuators form the capital-intensive foundation of installed systems. Tertiary hospitals in the United States concentrate replacement demand as first-generation da Vinci systems reach end-of-life, though supply concentration in German and Japanese precision motor suppliers constrains pricing flexibility for competitors.
- Visualization Systems:Stereoscopic 4K-8K camera stacks with integrated fluorescence imaging capabilities command premium positioning in gynecologic and urologic service lines. Chinese hospitals under NMPA innovation approval channels are prioritizing domestic visualization alternatives to reduce import dependency.
- Surgical Instruments:Disposable staplers, graspers, and energy devices with RFID authentication chips generate recurring revenue streams.
- Software Solutions:Procedure analytics, simulation training modules, and remote mentoring platforms represent the fastest-expanding margin segment as hospitals seek outcome measurement tools.
Most installed capacity flows through Robotic Arms. Expansion is steepest in Software Solutions.
Application:
Procedure maturity and reimbursement density determine where robotic platforms achieve economic viability versus conventional laparoscopy.
- Hernia Repair:Inguinal and ventral hernia mesh placement with robotic assistance reduces chronic pain incidence through precise trocar positioning. German sickness funds have established specific DRG codes for robotic inguinal repair, accelerating adoption in Rhineland-Palatinate and Bavaria hospital networks.
- Gynecologic Surgery:Hysterectomy and myomectomy procedures represent the most mature robotic application channel with established fellowship training pipelines. Academic medical centers in the Netherlands leverage EU MDR post-market surveillance data to justify continued capital investment against conventional laparoscopy.
- Bariatric Surgery:Sleeve gastrectomy protocol standardization is displacing adjustable gastric band procedures.
- Urologic Procedures:Prostatectomy and partial nephrectomy remain volume anchors.
Revenue concentration sits with Gynecologic Surgery. Bariatric Surgery is climbing the fastest as metabolic surgical programs expand.
End User:
Purchasing authority and capital allocation timelines diverge sharply between integrated delivery networks and independent surgical facilities.
- Hospitals:Tertiary and quaternary centers with established minimally invasive surgery departments drive system procurement through value-analysis committees. Catholic health systems in the United States are consolidating to single-vendor enterprise agreements to standardize training logistics across multi-state footprints.
- Ambulatory Surgical Centers:Freestanding facilities with same-day discharge protocols seek compact, cart-based systems with reduced infrastructure requirements. India's PLI scheme for medical devices is attracting assembly investments to serve this price-sensitive segment with lower import duty exposure.
- Specialty Clinics:Gynecology and urology-focused practices with high procedural volume explore leasing models.
- Academic Institutions:Research hospitals prioritize platforms with open API architectures for surgical data science initiatives.
Capital deployment concentrates through Hospitals. Ambulatory Surgical Centers are gaining share fastest as site-of-service migration accelerates.
Technology:
Platform differentiation increasingly hinges on sensory restoration and motion scaling precision rather than mechanical articulation alone.
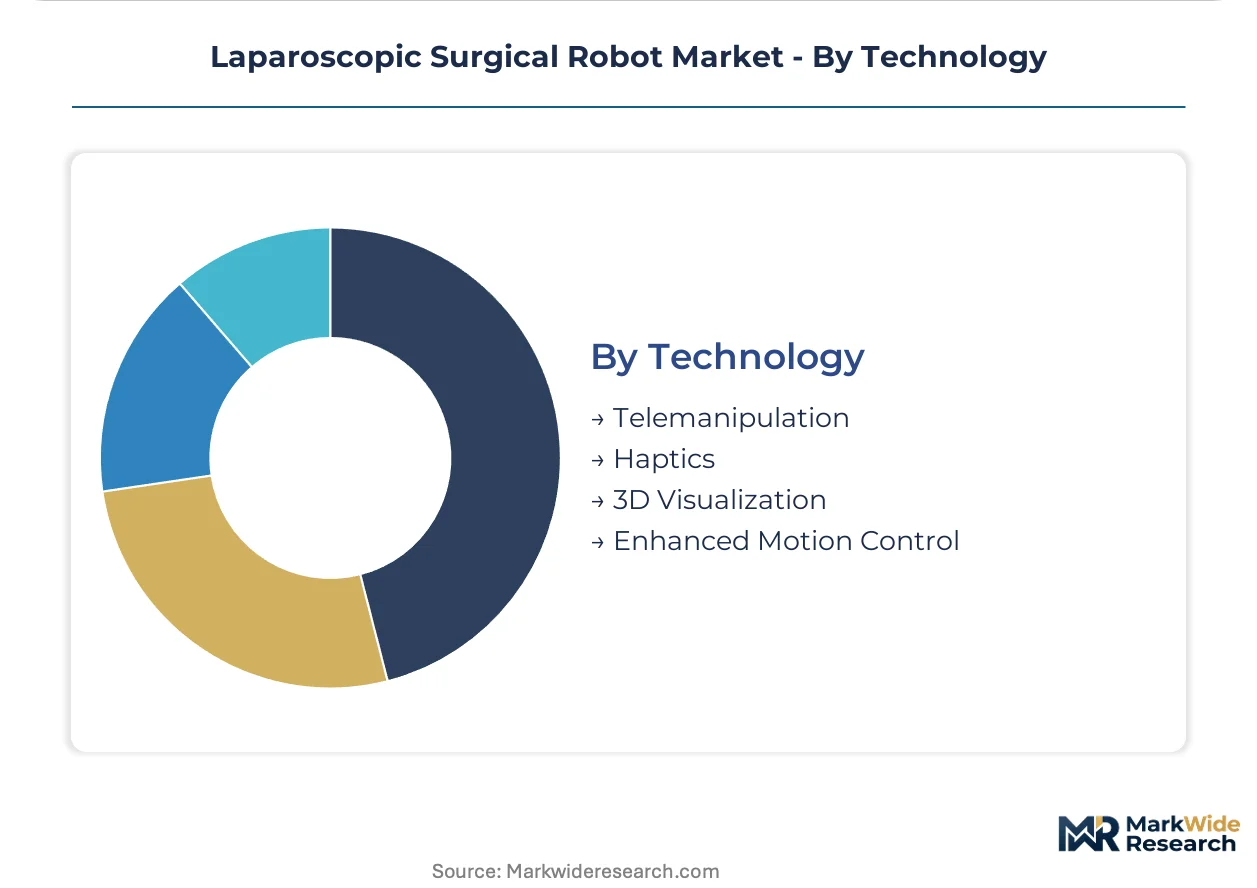
- Telemanipulation:Master-slave architectures with motion scaling and tremor filtration remain the core interaction paradigm. FDA premarket notification requirements for novel telemanipulation interfaces are intensifying submission complexity for second-generation entrants.
- Haptics:Force-sensing instrument shafts with tactile feedback restoration unify tissue assessment confidence with robotic precision. Fellowship programs at Heidelberg University Hospital and Mayo Clinic are integrating force-feedback training modules to accelerate surgeon onboarding.
- 3D Visualization:High-dynamic-range displays with depth perception optimization reduce visual fatigue.
- Enhanced Motion Control:Collision detection algorithms and virtual fixture boundaries improve safety margins.
Deployment volume runs through Telemanipulation. Haptics is expanding most quickly as training curricula mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Intuitive Surgical pioneered commercial robotic surgery in California during the late 1990s, establishing the technical and clinical foundation that subsequent entrants now contest. The industry's geographic footprint reflects this origin story while expanding through distinct national healthcare procurement systems.
United States
Catholic health systems drive enterprise-wide standardization across multi-state footprints, consolidating vendor relationships to simplify training logistics. FDA premarket notification requirements for surgical robotics intensify submission complexity for novel telemanipulation interfaces. Tertiary centers in California and Massachusetts anchor replacement demand as first-generation da Vinci systems reach end-of-life.
Germany
German sickness funds established specific DRG codes for robotic inguinal hernia repair, accelerating hospital adoption in Rhineland-Palatinate and Bavaria networks. EU MDR technical documentation requirements for Class III devices extend CE marking timelines and inflate compliance costs. High-volume bariatric centers in Heidelberg and Amsterdam restructure data collection infrastructure to satisfy post-market surveillance obligations.
China
NMPA innovation approval channels prioritize domestic visualization alternatives to reduce import dependency in tertiary hospitals. The country's dual carbon goals pressure manufacturers to demonstrate energy efficiency in surgical platform design. Shanghai and Beijing hospital clusters concentrate procurement authority for robotic surgery program expansion.
India
The PLI scheme for medical devices attracts component assembly investments to reduce import duties on finished systems serving price-sensitive segments. CDSCO regulatory pathways for novel surgical devices require local clinical trial data for market authorization. Maharashtra and Karnataka host emerging assembly operations targeting ambulatory surgical center demand.
Japan
METI industrial policy supports surgical robotics as a priority medical device category for export competitiveness. PMDA review timelines for software-enabled surgical platforms remain longer than FDA equivalents, delaying launch sequencing. Tokyo and Osaka academic medical centers concentrate fellowship training capacity for robotic procedure adoption.
Laparoscopic Surgical Robot Market Competitive Landscape
The competitive structure tilts toward installed-base incumbents with deep clinical data repositories. Two distinct tiers operate: dominant platform holders with decades of procedural evidence and modular challengers targeting cost-sensitive segments. Strategic moves concentrate on regulatory pre-clearance accumulation and training ecosystem lock-in rather than hardware specification races.
Among US-based platform developers, Intuitive Surgical, Stryker Corporation, and Medtronic occupy positions across the premium-system and integrated-navigation archetypes. Intuitive Surgical exemplifies the installed-base defender model through credentialing capacity constraints that limit competitor onboarding velocity. Stryker Corporation and Medtronic represent diversified medical technology conglomerates leveraging surgical navigation integration to anchor competitive positioning against pure-play robotics specialists.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Stryker Corporation |
| Medtronic |
| Smith & Nephew |
| Zimmer Biomet |
| Renishaw |
| Asensus Surgical |
| CMR Surgical |
| Titan Medical |
| Others |
Pricing and Supply Chain Analysis
Captive integration into precision motor manufacturing anchors supply security for robotic arm articulation subsystems while simultaneously defending premium pricing tiers against modular competitors. Intuitive Surgical's decades-long investment in harmonic drive actuator partnerships with German and Japanese suppliers creates both cost absorption capacity and pricing power insulation that second-generation entrants cannot replicate without equivalent scale.
Pricing Analysis
Bundled system-plus-consumable contracts dominate hospital procurement, separating capital equipment amortization from per-procedure instrument economics. Price differentiation rests on FDA clearance tier and installed-base training ecosystem depth, with tertiary academic centers exhibiting lowest price sensitivity and ambulatory surgical centers highest. Cost compression in disposable instrument tiers is intensifying because CMR Surgical's modular cart-based architecture eliminates dedicated OR infrastructure requirements. Catholic health systems with enterprise-wide standardization mandates accept premium positioning to simplify multi-state training logistics.
Supply Chain Analysis
Regional distribution centers in Illinois and California coordinate hub-and-spoke deployment patterns for North American hospital networks. Component sourcing concentrates in Germany and Japan for harmonic drive actuators, China for visualization camera stacks, and Switzerland for precision sensors. Single-source vulnerability in precision motor supply creates tariff exposure as trade policy shifts disrupt just-in-time delivery commitments. Distribution runs through manufacturer-direct field service organizations rather than third-party medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in laparoscopic surgical robotics hinges on software monetization outpacing hardware commoditization, with remote mentoring platforms and procedure analytics commanding recurring revenue multiples unavailable to capital equipment alone.
For Market Incumbents: Anchor competitive positioning through credentialing capacity expansion at Heidelberg University Hospital and Mayo Clinic fellowship programs, constraining competitor surgeon onboarding velocity. Deepen backward integration into surgical instrument manufacturing to capture consumable economics currently leaking to disposable suppliers. Defend against CMR Surgical's modular challenge by accelerating haptics-enabled system refresh cycles before cost-sensitive hospital segments consolidate purchasing decisions. For New Entrants and Emerging Players: Direct-to-ambulatory-surgical-center digital sales channels bypass incumbent field service infrastructure requirements and accelerate price-transparent procurement. Target India's PLI scheme assembly investments to serve Maharashtra and Karnataka clinic demand with reduced import duty exposure. Prioritize open API architectures for academic medical center research partnerships, creating data-sharing lock-in that precedes clinical adoption. For Investors and Strategic Acquirers: Roll-up economics work for visualization subsystem specialists because hospital procurement consolidation demands integrated platform solutions rather than point-product vendors. Five-to-ten year viability favors targets with NMPA innovation approval progress in China or established EU MDR technical documentation for Class III devices. Watch FDA Breakthrough Device Designation velocity as inflection indicator for time-to-revenue compression among qualified submissions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated review pathways shorten revenue realization timelines for novel telemanipulation interfaces. |
| Hospital System Partnership | Catholic health enterprise agreements standardize training logistics across multi-state footprints. |
| Software Companion Development | Remote mentoring platforms monetize academic medical center expertise across distributed networks. |
| CE Marking Pathway | EU MDR post-market surveillance compliance secures continued access to German DRG-reimbursed procedures. |
| Reimbursement Strategy | Specific DRG code establishment in German sickness funds validates robotic hernia repair economics. |
Research Methodology
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market's hospital procurement ecosystem. The research combines structured interviews with robotic surgery program directors, biomedical engineering leads, GPO contracts managers, and regulatory affairs specialists with secondary validation through FDA 510(k) filings, NMPA innovation approval databases, EU MDR notified body documentation, and hospital capital expenditure records. Bottom-up system installation tracking and top-down healthcare technology assessment triangulation ensure cross-verified demand estimation.
Granularity-level modeling disaggregates revenue across robotic arms, visualization systems, surgical instruments, and software solutions, with further segmentation by application maturity and end-user purchasing authority. CAGRs across the analysis window derive from installed-base replacement cycles, procedure volume elasticity to reimbursement changes, and geographic launch sequencing patterns. Forecast inputs incorporate bariatric surgery protocol standardization trajectories and 5G-enabled telesurgery infrastructure deployment timelines.
The model assumes a particular technology adoption path; alternative pathways for haptic feedback restoration would alter the outlook if force-sensing instrument shafts achieve faster training curriculum integration than projected. Forecasts reflect documented assumptions regarding regulatory clearance timelines and reimbursement decision schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Vibrating Mesh Nebulizer Market
Medical Devices
Central Venous Catheter Market
Medical Devices
Urology Guidewires Market
Medical Devices
Medical Device Trays Market
Medical Devices
Sinus Implants Market
Medical Devices
Additional Defibrillator Accessories (AED) Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Global Female Sterilization Devices Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
US External Counterpulsation Devices Market