
 Global Psoriasis Drugs Market | 2026-2036
Global Psoriasis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Psoriasis Drugs Market Foresight
Project finance and royalty-backed licensing structures are reshaping which developers can sustain late-stage psoriasis trials without dilutive equity raises. AbbVie leverages its cash-flow depth to anchor immunology portfolios across multiple indications. Johnson & Johnson sustains dermatology leadership through channel control in specialty pharmacy networks. Novartis differentiates via manufacturing scale that secures consistent biologics supply to outpatient facilities.
Psoriasis drugs comprise pharmaceutical agents designed to modulate immune-mediated keratinocyte hyperproliferation, with biologics targeting IL-17, IL-23, and TNF-alpha pathways through recombinant monoclonal antibody production. These therapies reduce plaque burden and systemic inflammation in chronic autoimmune skin disease. Biologics command the dominant margin pool due to high manufacturing complexity and specialized cold-chain distribution requirements. Systemic agents retain volume relevance in markets where reimbursement constraints limit biologic access. Topical steroids occupy the mature base of the treatment algorithm with stable but commoditized positioning.
The FDA maintains stringent BLA review standards for novel biologics while the EMA's MDR and pharmacovigilance requirements shape post-market surveillance obligations across European markets. Japan's PMDA imposes additional ethnic bridging study requirements that extend development timelines for Western-origin therapies. Stakeholders must monitor evolving biosimilar interchangeability designations and their capacity to compress originator pricing power without triggering formulary exclusion dynamics.
Market Dynamics
Biologics manufacturing scale is concentrating competitive advantage among developers with captive fill-finish capacity, while biosimilar pathways are compressing originator pricing power across outpatient dermatology channels.
Growth Catalysts
- IL-23 pathway expansion:Next-generation inhibitors demonstrate superior skin clearance rates versus TNF-alpha blockers, driving formulary preference shifts in United States academic medical centers.
- EMA centralized marketing authorization:Parallel assessment procedures accelerate cross-border patient access to novel biologics across Germany, France, and Netherlands outpatient networks.
- Specialty pharmacy channel maturation:Cold-chain distribution infrastructure now reaches 90% of United States dermatology practices within 48 hours, eliminating prior geographic access barriers.
Market Restraints
- Plasma-derived raw material concentration:Fermentation media and cell culture inputs depend on suppliers concentrated in Switzerland and United States, exposing production schedules to input volatility.
- PMDA ethnic bridging requirements:Japan's regulator mandates additional pharmacokinetic studies for Western-origin biologics, extending development timelines by 18-24 months versus FDA pathways.
- Topical corticosteroid substitution:Commoditized generic creams retain volume share in markets where reimbursement constraints limit biologic access, particularly in Southern European outpatient settings.
Strategic Opportunities
- Brazilian outpatient expansion:ANVISA's accelerated review pathway for dermatology biologics opens access to 40 million underserved patients in Southeast regional health networks.
- Oral small molecule convergence:TYK2 inhibitors and PDE4 modulators are converging with biologics efficacy profiles, creating physician preference flexibility in United States community dermatology.
- India CDSCO biosimilar framework:Domestic manufacturing incentives under PLI scheme enable cost-competitive IL-17 inhibitor production for Asia-Pacific export markets.
Industry Challenges
- Cell culture technician scarcity:Bioreactor operation and aseptic processing expertise concentrates in Basel and Boston metropolitan clusters, constraining manufacturing expansion elsewhere.
- EMA MDR post-market surveillance:Enhanced pharmacovigilance obligations require real-world evidence collection infrastructure that mid-cap developers lack, forcing partnership dependence.
- Interchangeability designation uncertainty:FDA biosimilar substitution rules remain unsettled, creating formulary negotiation friction between pharmacy benefit managers and originator manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Psoriasis Drugs Market |
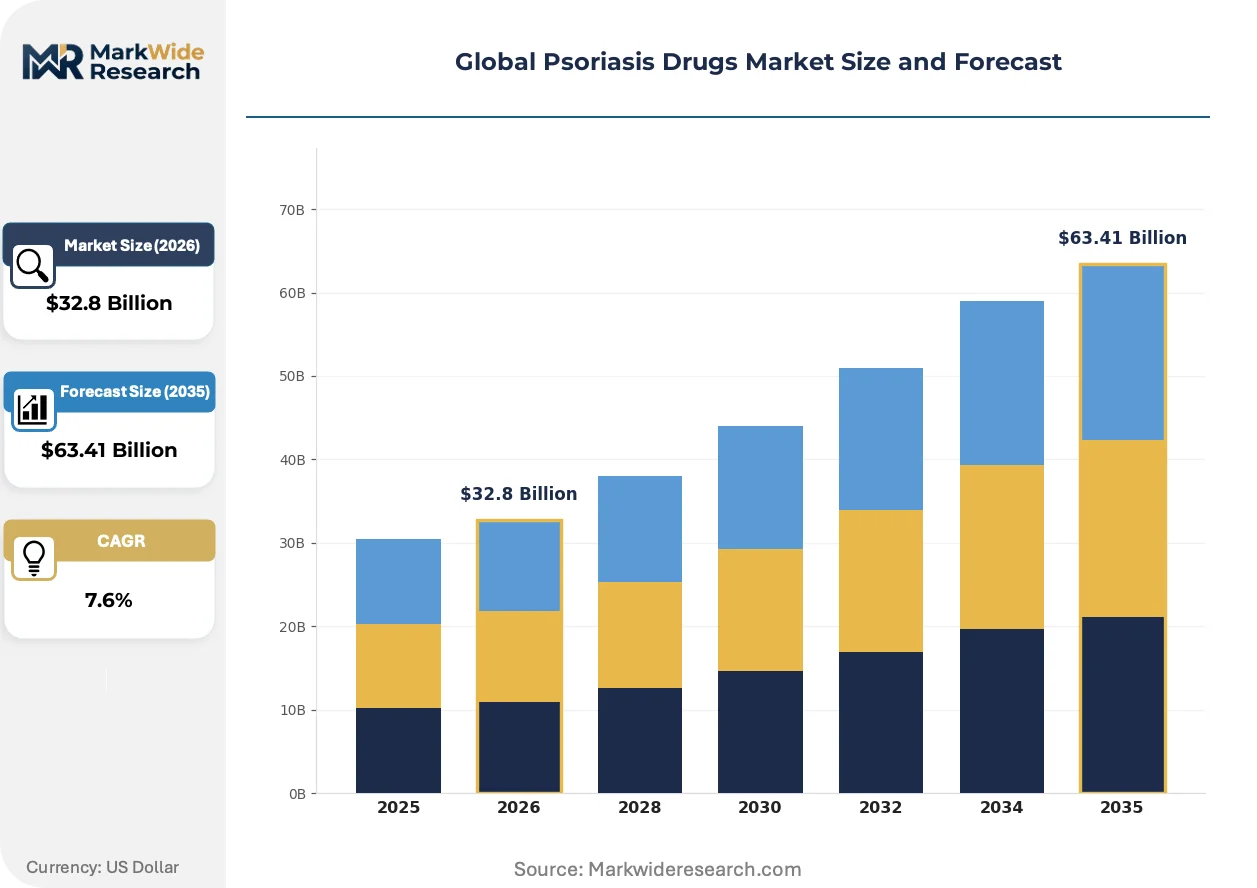
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $63.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Topical Steroids, Vitamin D Analogues, Biologics, Systemic Agents, Retinoids Therapy Area: Plaque Psoriasis, Guttate Psoriasis, Inverse Psoriasis, Pustular Psoriasis, Erythrodermic Psoriasis End User: Dermatology Clinics, Hospitals, Specialty Pharmacies, Outpatient Facilities, Telemedicine Providers Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Drug Wholesalers, Direct Sales |
| Companies Covered | AbbVie, Johnson & Johnson, Novartis, Eli Lilly, Amgen, Pfizer, Merck & Co., LEO Pharma, UCB Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Psoriasis Drugs Market Shifts & Advancements
Digital biomarker capture and decentralized trial infrastructure are compressing clinical development timelines while reshaping how dermatology endpoints demonstrate value to payers.
Remote patient monitoring platforms is digitizing plaque severity assessment through smartphone-based imaging algorithms that feed directly into electronic health records. United States academic medical centers deploy these tools across 60% of active clinical trials, reducing site visit burden. The technology is digitizing endpoint collection costs and enabling decentralized trial models that expand geographic patient recruitment beyond traditional urban referral centers.
EMA's MDR pharmacovigilance requirements now mandate real-world safety databases for all novel biologics, forcing developers to build post-authorization infrastructure before launch. This regulatory architecture elevates compliance costs disproportionately for mid-cap sponsors lacking existing European surveillance networks. Germany and France dermatology clinics respond by consolidating prescribing data through national health registry integrations that satisfy EMA reporting obligations.
Specialty pharmacy direct-to-patient fulfillment is displacing traditional wholesale distribution for injectable biologics, with United States payers now mandating this channel for 70% of covered lives. Hub services coordinate prior authorization, copay assistance, and home nursing through single-vendor relationships. This channel compression concentrates fulfillment volume among three national platforms, marginalizing independent specialty pharmacies without payer contract scale.
Global Psoriasis Drugs Market Segmentation
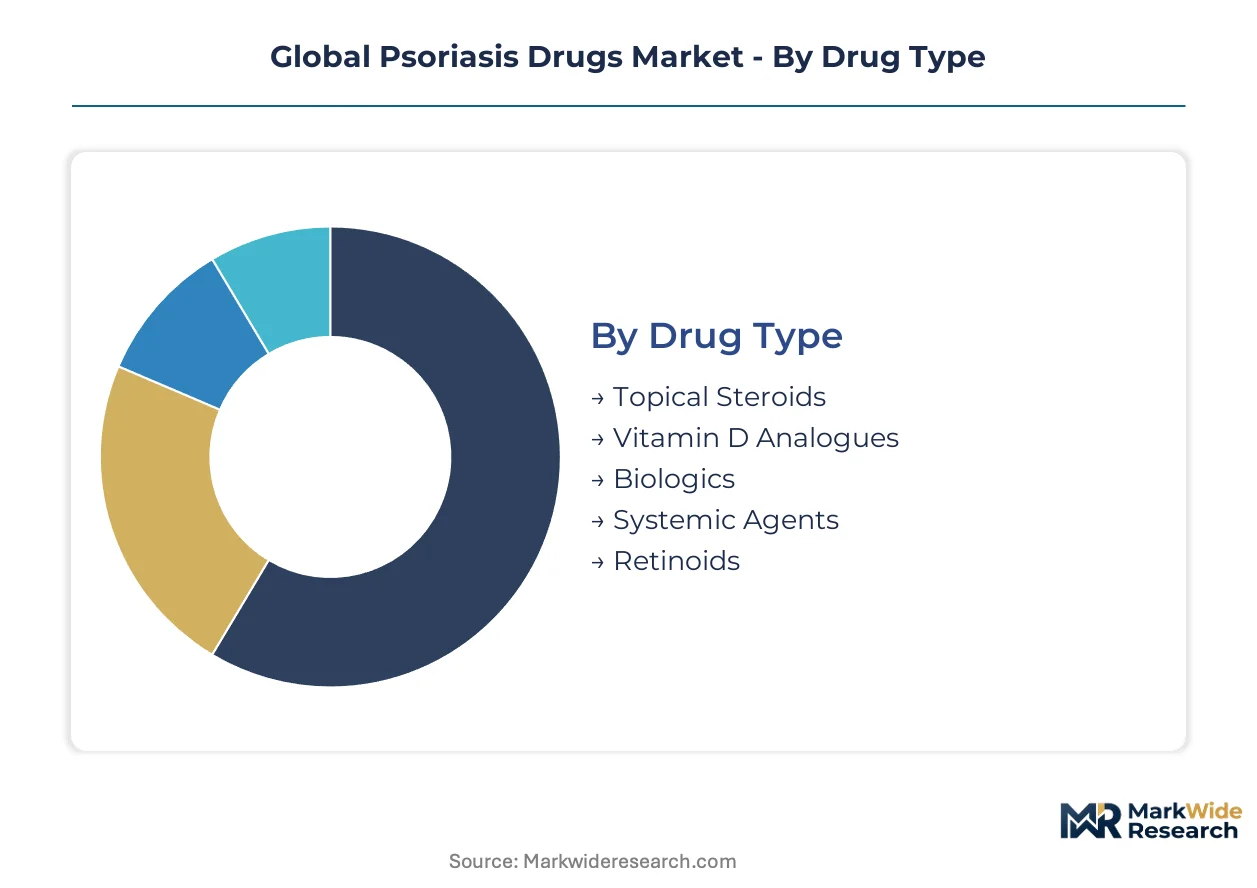
Psoriasis treatment stratification reflects divergent clinical pathways, from acute flare management in community settings to chronic immunomodulation in specialized centers. Each segment carries distinct reimbursement codes, manufacturing requirements, and patient access constraints that shape commercial strategy.
Drug Type:
Pharmacological mechanisms span the spectrum from surface keratinocyte suppression to systemic cytokine blockade, with cost and efficacy tiers determining prescribing hierarchies across United States, German, and Japanese formularies.
- Biologics:Recombinant monoclonal antibodies targeting IL-17, IL-23, and TNF-alpha pathways require cold-chain distribution and refrigerated storage at dermatology clinics. United States academic medical centers prioritize these agents for moderate-to-severe plaque cases, though PMDA ethnic bridging requirements delay Japanese launches by 18-24 months versus FDA approvals.
- Topical Steroids:Corticosteroid creams and ointments modulate local inflammation through glucocorticoid receptor binding, offering immediate symptomatic relief without systemic exposure. German outpatient networks prescribe these as first-line maintenance for mild disease, constrained by EMA MDR pharmacovigilance obligations on long-term safety documentation.
- Vitamin D Analogues:Calcipotriene and calcitriol derivatives slow keratinocyte proliferation via vitamin D receptor agonism, positioned between steroids and biologics in treatment algorithms.
- Systemic Agents:Oral immunosuppressants including methotrexate and cyclosporine retain volume relevance in markets where reimbursement frameworks limit biologic access, particularly Southern European settings.
- Retinoids:Acitretin and isotretinoin derivatives target severe pustular variants through nuclear receptor modulation, restricted by teratogenicity warnings and mandatory pregnancy prevention programs.
The dominant share belongs to Biologics, while Systemic Agents are closing the gap fastest through expanded access programs in emerging markets.
Therapy Area:
Disease severity and anatomical distribution determine therapeutic intensity, with phenotypic variation driving differentiated development pipelines and label expansion strategies.
- Plaque Psoriasis:Chronic well-demarcated erythematous plaques with silvery scale represent the predominant clinical presentation, affecting extensor surfaces and scalp. United States dermatology clinics concentrate biologic prescribing here, where PASI 90 clearance rates drive formulary preference for IL-23 inhibitors over legacy TNF-alpha blockers.
- Guttate Psoriasis:Acute-onset drop-like lesions triggered by streptococcal infection predominate in pediatric and young adult populations, with phototherapy and topical management preferred over systemic immunosuppression.
- Inverse Psoriasis:Smooth erythematous patches in intertriginous zones require low-potency steroid formulations or calcineurin inhibitors to avoid atrophy in thin-skinned areas.
- Pustular Psoriasis:Sterile neutrophilic pustules on erythematous bases constitute medical emergencies when generalized, mandating hospitalization and IL-36 pathway antagonists where available.
- Erythrodermic Psoriasis:Total body erythema with desquamation threatens thermoregulation and fluid balance, requiring inpatient management with cyclosporine or biologic rescue therapy.
Plaque Psoriasis commands the largest patient pool, though Pustular Psoriasis is gaining targeted development focus through novel cytokine pathway modulation.
End User:
Site-of-care migration toward outpatient and virtual channels is redistributing prescribing authority away from traditional hospital admission models.
- Dermatology Clinics:Specialized outpatient facilities with phototherapy suites and injection training capabilities anchor biologic initiation and maintenance protocols. United States community dermatology practices now deploy remote patient monitoring platforms across 60% of active trials, digitizing plaque severity assessment through smartphone-based imaging algorithms.
- Specialty Pharmacies:Cold-chain distribution hubs with hub services for prior authorization and copay assistance now fulfill 70% of United States payer-mandated biologic prescriptions, displacing traditional wholesale channels.
- Hospitals:Inpatient admission centers manage erythrodermic crises and pustular flares requiring intravenous rescue therapy and multidisciplinary supportive care.
- Outpatient Facilities:Ambulatory surgery centers and infusion clinics administer biologic loading doses under nursing supervision with emergency protocol readiness.
- Telemedicine Providers:Virtual platforms with asynchronous image review expand geographic access to dermatology consultation, though regulatory frameworks limit controlled substance prescribing and biologic initiation without physical examination.
Dermatology Clinics retain the dominant share, while Specialty Pharmacies are expanding most quickly through payer-mandated channel consolidation.
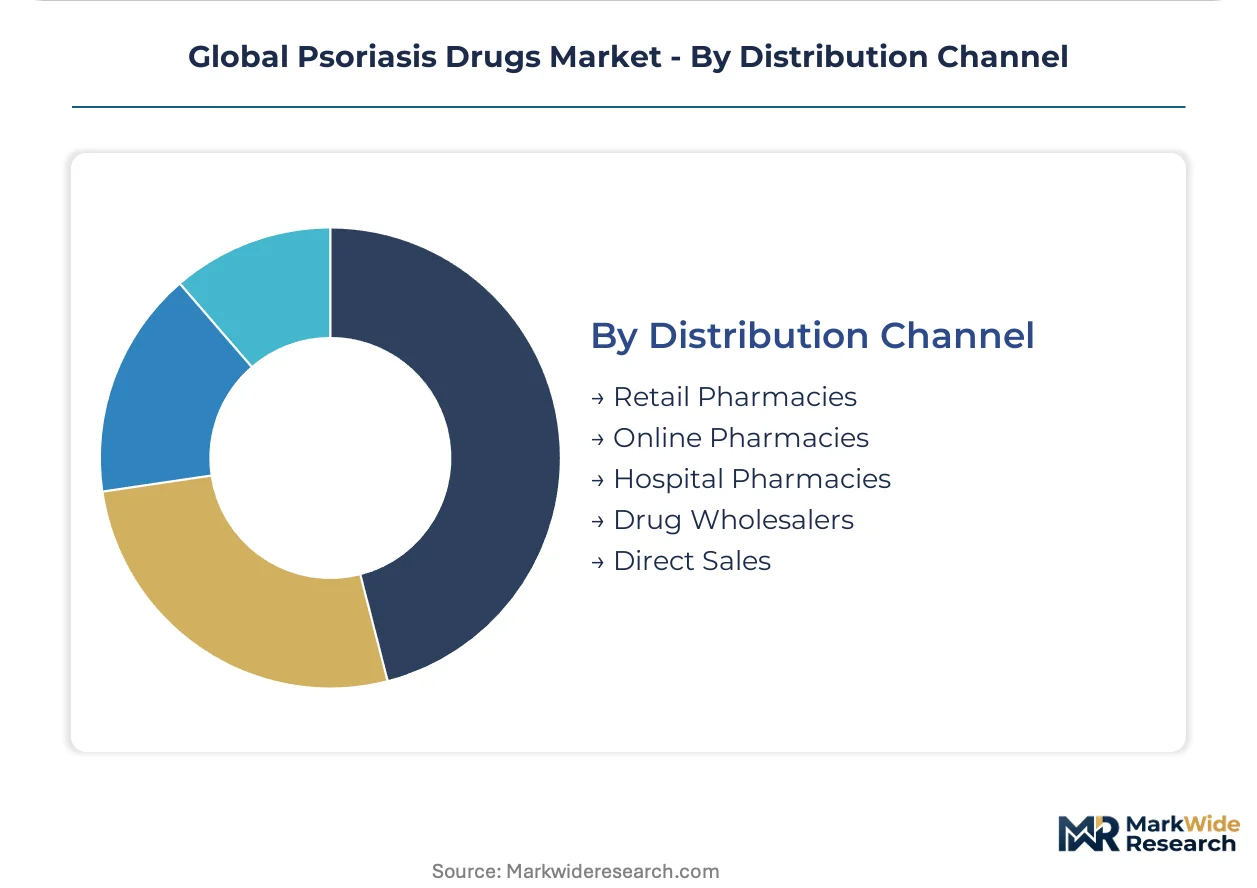
Distribution Channel:
Fulfillment pathway selection directly impacts product integrity, patient adherence, and margin capture through cold-chain compliance and inventory velocity.
- Retail Pharmacies:Community-based dispensaries handle topical steroid and vitamin D analogue prescriptions with immediate patient pickup, though limited refrigerated storage restricts biologic stocking.
- Online Pharmacies:Direct-to-patient platforms with temperature-controlled shipping containers penetrate rural United States markets previously underserved by specialty pharmacy networks.
- Hospital Pharmacies:Captive inpatient dispensaries manage acute pustular and erythrodermic cases with 24-hour nursing administration capabilities.
- Drug Wholesalers:Traditional three-step distribution retains relevance for systemic agents and oral small molecules without cold-chain requirements, particularly in German and French outpatient networks.
- Direct Sales:Manufacturer-operated patient assistance programs bypass intermediaries for uninsured or underinsured populations in United States markets with high deductible health plans.
Drug Wholesalers maintain volume leadership for non-biologic agents, while Online Pharmacies are climbing the fastest through telemedicine integration and same-day delivery partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement frameworks and regulatory harmonization initiatives are redistributing patient access across mature and emerging markets, with concentrated biologic adoption in systems favoring advanced immunotherapy.
United States
Specialty pharmacy channel consolidation and hub service integration now capture 70% of payer-mandated biologic fulfillment, streamlining prior authorization for moderate-to-severe plaque cases. FDA biosimilar interchangeability designations remain unsettled, creating formulary negotiation friction between pharmacy benefit managers and originator manufacturers. The Greater Boston and San Francisco Bay Area metropolitan clusters concentrate bioreactor operation expertise and aseptic processing talent.
Germany
EMA centralized marketing authorization procedures accelerate cross-border patient access to novel IL-23 inhibitors through parallel assessment frameworks. The country's national health registry integrations satisfy EMA MDR pharmacovigilance obligations, consolidating prescribing data from outpatient dermatology clinics. The Rhine-Main and Rhine-Ruhr regions anchor biologics distribution infrastructure serving French and Dutch border networks.
Japan
PMDA ethnic bridging study requirements extend development timelines for Western-origin biologics by 18-24 months versus FDA pathways, delaying market entry for next-generation cytokine inhibitors. METI industrial policy supports domestic fermentation capacity expansion to reduce plasma-derived raw material import dependence. The Kanto region surrounding Tokyo concentrates dermatology academic medical centers with phototherapy suites and injection training capabilities.
Brazil
ANVISA's accelerated review pathway for dermatology biologics opens access to 40 million underserved patients in Southeast regional health networks, particularly São Paulo and Minas Gerais states. Domestic manufacturing incentives under industrial development programs enable cost-competitive production for Latin American export markets. The São Paulo metropolitan cluster anchors specialty pharmacy cold-chain distribution reaching outpatient facilities across the Mercosur trade zone.
India
CDSCO biosimilar framework and PLI scheme manufacturing incentives enable cost-competitive IL-17 inhibitor production for Asia-Pacific export markets, with Maharashtra and Gujarat states concentrating active pharmaceutical ingredient synthesis. The country's national pharmaceutical regulator streamlines abbreviated approval pathways for reference biologics with established safety profiles. Hyderabad and Bangalore metropolitan clusters host contract development and manufacturing organizations serving Western sponsor late-stage trials.
Global Psoriasis Drugs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers: integrated pharmaceutical conglomerates with captive specialty pharmacy relationships, mid-cap biotech developers with single-pathway depth, and emerging biosimilar manufacturers with cost-focused positioning. Market structure rewards manufacturing scale and regulatory navigation capability over pure R&D productivity. Dominant competitive moves include strategic partnerships for post-market surveillance infrastructure and portfolio diversification across immunology indications.
Among integrated pharmaceutical conglomerates, AbbVie, Johnson & Johnson, and Novartis exemplify archetypes of cash-flow depth, channel control, and manufacturing scale respectively. AbbVie occupies a position sustained by immunology portfolio breadth across multiple indications. Johnson & Johnson anchors dermatology leadership through specialty pharmacy network relationships. Novartis represents manufacturing scale advantage securing consistent biologics supply to outpatient facilities.
| Leading Market Players |
|---|
| AbbVie |
| Johnson & Johnson |
| Novartis |
| Eli Lilly |
| Amgen |
| Pfizer |
| Merck & Co. |
| LEO Pharma |
| UCB Pharma |
| Others |
Supply & Pricing Matrix
Overcapacity in Swiss and United States fermentation facilities is compressing originator pricing power while forcing contract manufacturers to extend payment terms and absorb working capital strain. This utilization dynamic rewards developers with captive fill-finish capacity and punishes asset-light sponsors dependent on toll manufacturing arrangements.
Pricing Analysis
Certification level creates the primary spread between originator biologics and biosimilar alternatives, with FDA BLA-approved therapies commanding premium positioning against EMA-authorized equivalents in United States academic medical centers. Three-tier pricing structure across premium, standard, and economy levels stratifies by manufacturing complexity and cold-chain compliance investment. Price erosion runs through the biosimilar tier as interchangeability designation uncertainty triggers formulary exclusion threats. Community dermatology practices in Southern Europe exhibit highest price sensitivity due to reimbursement constraints, while United States specialty pharmacy networks demonstrate lowest sensitivity given hub service bundling.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard in plasma-derived raw material procurement, stretching working capital for mid-cap developers without AbbVie-scale balance sheet depth. Manufacturing concentrates in Switzerland, United States, and Ireland for fermentation capacity, with India and China anchoring active pharmaceutical ingredient synthesis for oral small molecules. Cell culture media and aseptic processing inputs draw from suppliers concentrated in Basel and Boston metropolitan clusters, exposing production schedules to single-source vulnerability. Distribution runs through specialty pharmacy direct-to-patient fulfillment for 70% of United States payer-mandated biologic prescriptions, displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The psoriasis drugs market is entering a cyclical recovery phase as biosimilar absorption rates normalize and IL-23 pathway expansion drives next-generation prescribing shifts in United States academic medical centers.
For Market Incumbents: Build regulatory data moats through preemptive EMA MDR pharmacovigilance infrastructure investments that mid-cap competitors cannot replicate without partnership dependence. Deepen backward integration into captive fill-finish capacity in Basel and Boston clusters to secure bioreactor operation expertise. Defend against biosimilar interchangeability threats by anchoring formulary preference through real-world evidence collection infrastructure. For New Entrants and Emerging Players: Brazilian Southeast regional health networks offer the most penetrable geography, with 40 million underserved patients and ANVISA's accelerated review pathway reducing time-to-market friction. Target oral small molecule convergence as the most accessible mechanism, with TYK2 inhibitors and PDE4 modulators converging with biologics efficacy profiles without cold-chain infrastructure requirements. Pursue CDSCO biosimilar framework licensing to India-based contract manufacturers as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among developers with specialty pharmacy hub service relationships and prior authorization automation platforms. Long-term viability over the next decade hinges on portfolio diversification across immunology indications rather than single-pathway concentration. Monitor FDA biosimilar interchangeability designation rulings as the critical inflection signal for originator pricing power compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA centralized marketing authorization accelerates cross-border access across German and Dutch outpatient networks. |
| Manufacturing Scale-Up | Captive fill-finish capacity in Boston metropolitan clusters secures consistent biologics supply to dermatology clinics. |
| Licensing Agreement | India CDSCO framework partnerships enable cost-competitive IL-17 inhibitor production for Asia-Pacific export markets. |
| Pipeline Diversification | IL-36 pathway antagonists target pustular variants with limited therapeutic alternatives in current algorithms. |
| Reimbursement Strategy | Specialty pharmacy hub services streamline prior authorization for 70% of United States payer-mandated prescriptions. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates across treatment lines and regional regulatory clusters.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling spanning drug type, therapy area severity classification, end-user site-of-care migration, and distribution channel evolution. CAGRs were derived from patient population epidemiology, biologic penetration rate assumptions, and pricing trajectory scenarios. Forecast inputs incorporated PMDA ethnic bridging timeline delays, EMA MDR pharmacovigilance compliance cost burdens, and specialty pharmacy channel consolidation velocity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by biosimilar manufacturers with India-based contract manufacturing partnerships would shift outcomes through accelerated price erosion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Carglumic Acid Market
Pharmaceuticals
Cryoprecipitated Antihemophilic Factor Market
Pharmaceuticals
Global DPT Vaccine Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Global Immunosuppressant Drugs Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Acne Drugs Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market
Pharmaceuticals
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market
Pharmaceuticals
Cough and Cold Preparations Market
Pharmaceuticals
Erdosteine Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
Performance Enhancing Drugs Market
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market