
 Carglumic Acid Market | 2026-2036
Carglumic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Carglumic Acid Market Analysis
Hospital procurement of carglumic acid is shifting toward integrated metabolic disorder management programs. Recordati Rare Diseases anchors European distribution through its orphan drug specialization. Biophore India Pharmaceuticals Pvt Ltd leverages active pharmaceutical ingredient manufacturing scale to supply formulation partners. Civentichem LLC sustains North American market presence through chemistry expertise in rare disease compounds.
Carglumic acid is a synthetic structural analogue of N-acetylglutamate, functioning as an allosteric activator of carbamoyl phosphate synthetase 1 to restore ammonia detoxification in patients with N-acetylglutamate synthase deficiency. The compound requires precise stereochemical control during synthesis to ensure pharmacological equivalence to endogenous activators. Tablet formulations dominate current prescribing patterns due to outpatient manageability, while injectable formats retain critical utility in acute hyperammonemia crises where enteral absorption is compromised. Homecare channels represent the fastest-growing end user segment as caregiver training programs enable subcutaneous administration outside institutional settings.
FDA orphan drug exclusivity frameworks shape competitive timelines for carglumic acid developers, while EMA's pediatric investigation plan requirements influence clinical trial design across European submissions. India's CDSCO accelerates access through its rare disease recognition pathway under evolving national health policy frameworks. Stakeholders must monitor regulatory convergence between pharmacovigilance standards and real-world evidence requirements as post-market commitments expand for metabolic disorder therapies.
Market Dynamics
Pediatric metabolic disorder management programs are consolidating procurement decisions around integrated care pathways, compressing traditional pharmaceutical distribution hierarchies into single-source hospital contracts.
Growth Catalysts
- Newborn screening mandates:State-level urea cycle disorder screening programs in the United States are expanding patient identification rates through tandem mass spectrometry protocols.
- EMA pediatric investigation plans:Regulatory frameworks are accelerating clinical trial designs that generate pediatric-specific dosing data for rare metabolic conditions.
- Orphan drug exclusivity:FDA frameworks extend market protection timelines, incentivizing developers to pursue N-acetylglutamate synthase deficiency indications.
Market Restraints
- Stereochemical synthesis complexity:Precise enantiomeric control during carbamoyl phosphate synthetase 1 activator production requires specialized contract manufacturing organizations with rare disease chemistry expertise.
- Active pharmaceutical ingredient concentration:Manufacturing capacity for synthetic N-acetylglutamate analogues clusters among Indian and European suppliers, creating geographic supply vulnerability.
- Hyperammonemia crisis substitution:Sodium benzoate and sodium phenylbutyrate retain first-line acute management protocols in many treatment algorithms.
Strategic Opportunities
- Homecare administration expansion:Caregiver training programs for subcutaneous carglumic acid delivery are opening outpatient revenue channels outside hospital pharmacy capture.
- China NMPA orphan pathways:Streamlined rare disease recognition procedures are reducing regulatory timelines for metabolic disorder therapies entering the world's second-largest pharmaceutical market.
- Real-world evidence integration:Post-market pharmacovigilance commitments are creating data assets that support label expansion into adjacent urea cycle disorders.
Industry Challenges
- Stereochemistry specialist scarcity:Synthetic organic chemists with chiral separation expertise for N-acetylglutamate analogues command premium compensation in competitive labor markets.
- Multi-jurisdiction compliance synchronization:Divergent pharmacovigilance reporting requirements between FDA, EMA, and NMPA create administrative burden for single-product rare disease sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carglumic Acid Market |
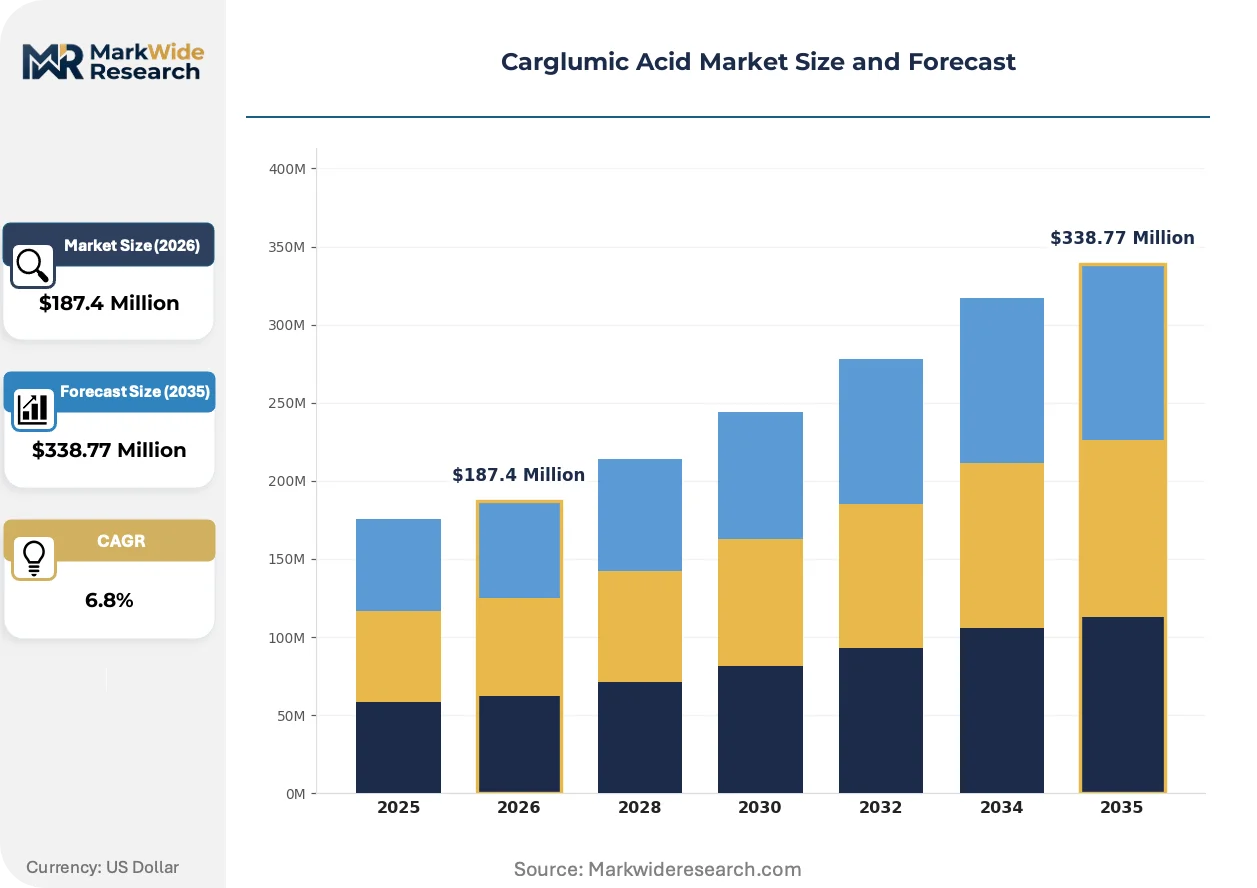
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Powder, Injectable, Oral Solution End User: Hospitals, Clinics, Homecare, Pharmacies Distribution Channel: Hospital Pharmacy, Retail Pharmacy, Online Pharmacy, Wholesalers Therapy Area: Inherited Metabolic Disorders, Urea Cycle Disorders, Liver Diseases, Others |
| Companies Covered | Recordati Rare Diseases, Apothecon Pharmaceuticals Pvt Ltd, Biophore India Pharmaceuticals Pvt Ltd, Dipharma Francis S.r.l., Manus Aktteva Biopharma LLP, Civentichem LLC, NURAY CHEMICALS, NOVITIUM PHARMA LLC, Lucane Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carglumic Acid Market Emerging Trajectories
Metabolic disorder therapeutics are converging around patient-centric delivery models that displace institutional dependence with home-based care infrastructure. Three interconnected developments are compressing traditional hospital-centric value chains.
Subcutaneous carglumic acid formulations are decentralizing acute hyperammonemia management from emergency departments to residential settings. Home nursing services and family caregiver certification programs are adopting these delivery systems at accelerating rates across North American and European markets. This shift is decentralizing revenue capture from hospital pharmacy departments to specialty pharmacy distributors with home infusion capabilities.
EMA's evolving rare disease framework is mandating pediatric investigation plans that reshape clinical development timelines for metabolic disorder therapies. Sponsors must now generate neonatal and infant pharmacokinetic data prior to marketing authorization, extending study durations but expanding addressable patient populations. European submissions for carglumic acid indications are responding with adaptive trial designs that integrate natural history data.
Hospital pharmacy procurement committees are consolidating metabolic disorder therapeutics into single-source agreements with integrated service providers. This behavioral shift displaces traditional wholesale distribution relationships in favor of direct manufacturer-to-health system contracts. The United States exhibits the most pronounced consolidation, with pediatric academic medical centers leading the transition toward value-based procurement structures.
Carglumic Acid Market Segmentation
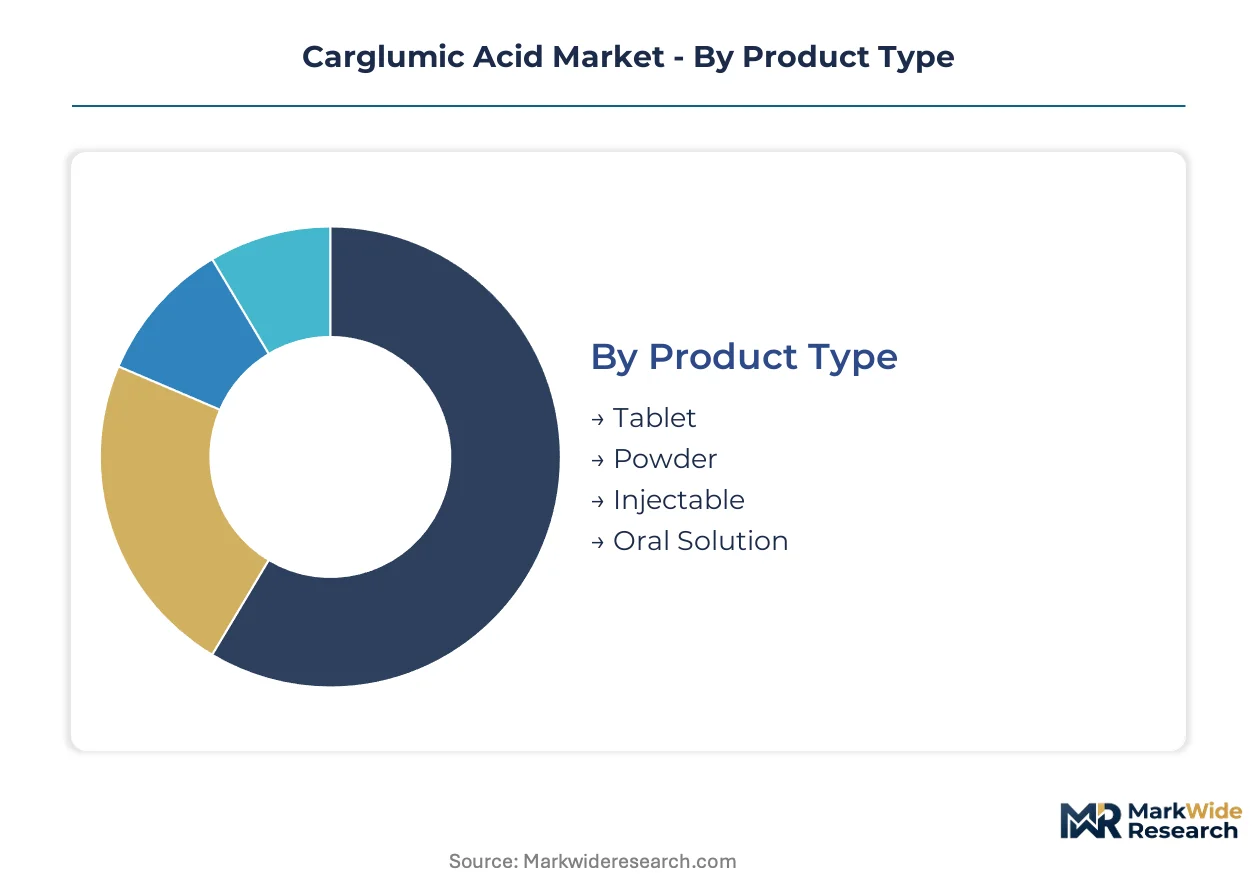
Carglumic acid formulations serve distinct clinical scenarios requiring precise matching of dosage form to patient condition and care setting. Segmentation reveals how manufacturing capabilities and distribution infrastructure align with acute versus chronic management pathways across metabolic disorder treatment protocols.
Product Type:
Specialized contract manufacturing organizations with chiral chemistry expertise concentrate production of N-acetylglutamate analogues across four distinct delivery formats.
- Tablet:Compressed solid dosage forms containing carglumic acid as the active pharmaceutical ingredient enable outpatient self-administration for chronic N-acetylglutamate synthase deficiency management. Hospital pharmacy procurement committees in the United States favor tablet formulations for discharge planning and homecare transitions, though tablet stability requirements necessitate controlled humidity storage infrastructure throughout distribution networks.
- Injectable:Parenteral solutions deliver carglumic acid via intravenous or subcutaneous routes during acute hyperammonemia crises when enteral absorption is compromised. Pediatric intensive care units and emergency departments in Germany and France maintain injectable inventory for rapid ammonia detoxification, with home nursing services increasingly adopting subcutaneous protocols for residential crisis management.
- Powder:Lyophilized or granulated active pharmaceutical ingredient requires reconstitution prior to administration, serving formulation partners and compounding pharmacies with flexibility for customized dosing.
- Oral Solution:Liquid formulations accommodate pediatric patients and adults with swallowing difficulties, particularly in neonatal metabolic disorder programs where precise weight-based titration is essential.
Tablet formulations absorb the bulk of installed capacity; injectable formats are expanding most quickly through homecare channel development.
End User:
Patient acuity and care setting determine procurement authority and reimbursement pathways for carglumic acid access.
- Hospitals:Academic medical centers and pediatric specialty hospitals anchor demand through integrated metabolic disorder management programs. These institutions consolidate purchasing decisions under single-source agreements with orphan drug specialists, displacing traditional wholesale relationships in favor of direct manufacturer contracts that bundle clinical support services with pharmaceutical supply.
- Homecare:Certified nursing services and family caregiver programs enable subcutaneous carglumic acid administration outside institutional settings. Reimbursement frameworks in the United States and Switzerland are expanding to cover home infusion nursing for urea cycle disorder patients, creating revenue capture opportunities for specialty pharmacy distributors with regional nursing networks.
- Clinics:Outpatient metabolic disorder centers manage stable patients through periodic monitoring and prescription renewal, relying on retail pharmacy networks for ongoing supply.
- Pharmacies:Community and specialty pharmacy channels serve chronic maintenance prescriptions, with limited formulary inclusion due to orphan drug distribution constraints.
Hospitals retain the dominant share of acute procurement volume; homecare channels are climbing the fastest as caregiver certification programs proliferate.
Distribution Channel:
Supply chain configuration for orphan metabolic therapeutics reflects regulatory custody requirements and patient access urgency.
- Hospital Pharmacy:Captive dispensing within health systems ensures cold chain integrity and immediate availability for hyperammonemia emergencies. Direct manufacturer-to-hospital contracts are consolidating procurement across pediatric academic medical centers in the United States, compressing traditional distributor margins into integrated service fees.
- Retail Pharmacy:Community pharmacies handle maintenance prescriptions for stable outpatients, though limited stocking and special ordering requirements create access delays in rural geographies.
- Online Pharmacy:Digital platforms facilitate prescription fulfillment for homecare patients with established diagnoses, subject to controlled substance-style verification protocols in jurisdictions with strict orphan drug tracking mandates.
- Wholesalers:Traditional pharmaceutical distributors retain residual volume for non-acute replenishment, though their role diminishes as hospital systems consolidate metabolic disorder therapeutics under direct agreements.
Hospital pharmacy channels command the greatest share of value capture; online pharmacy infrastructure is gaining share fastest through specialty pharmacy platform expansion.
Therapy Area:
Clinical indication determines dosing protocol, monitoring intensity, and regulatory exclusivity eligibility for carglumic acid developers.
- Urea Cycle Disorders:Primary indication for N-acetylglutamate synthase deficiency where carglumic acid restores carbamoyl phosphate synthetase 1 activity and ammonia detoxification. Newborn screening program expansion in the United States and pilot programs in Saudi Arabia are expanding diagnosed prevalence, creating demand concentration in pediatric metabolic centers with established enzyme replacement therapy protocols.
- Inherited Metabolic Disorders:Adjacent indications including organic acidemias and other defects of ammonia metabolism where off-label or expanded access use occurs. EMA pediatric investigation plans are generating neonatal pharmacokinetic data that may support formal label expansion, extending addressable populations beyond the core urea cycle disorder indication.
- Liver Diseases:Hepatic encephalopathy and acute liver failure represent potential expansion areas where ammonia accumulation parallels urea cycle dysfunction, though clinical evidence requirements remain substantial for regulatory acceptance.
- Others:Investigational and compassionate use programs explore carglumic acid utility in rare presentations of hyperammonemia without established enzymatic diagnosis.
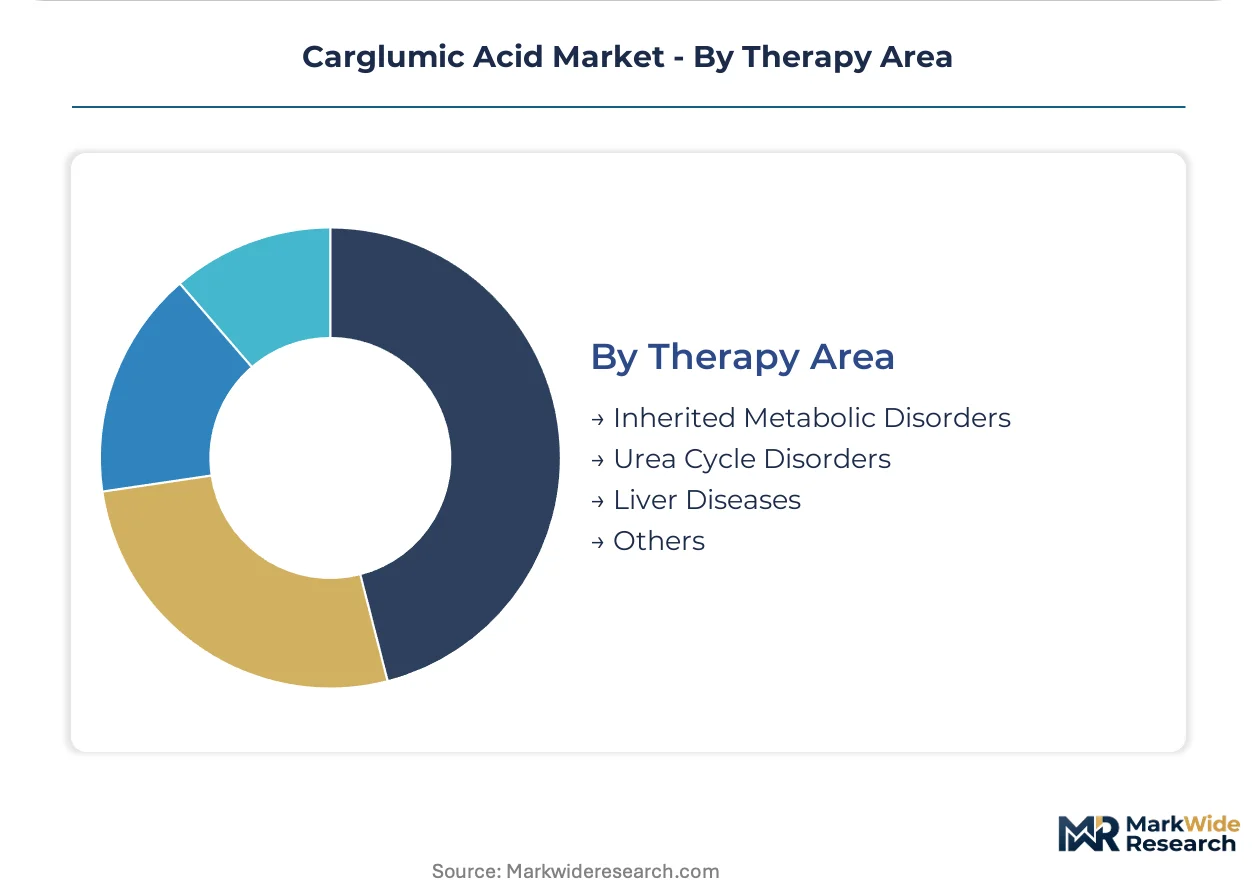
Urea cycle disorder treatment absorbs the bulk of clinical deployment; inherited metabolic disorder applications are expanding most quickly through adaptive trial design and real-world evidence accumulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for pharmaceutical manufacturing in India and China concentrate active pharmaceutical ingredient production for rare disease therapeutics. These zones offer tax holidays and streamlined customs procedures that attract synthetic chemistry specialists. The geographic dispersion of finished formulation capacity differs substantially from raw material concentration.
United States
Newborn screening expansion through state health departments drives patient identification for urea cycle disorders. FDA orphan drug exclusivity frameworks extend market protection timelines for metabolic disorder therapies. Pediatric academic medical centers in Boston and Philadelphia anchor demand through integrated metabolic management programs.
Germany
EMA pediatric investigation plans mandate neonatal pharmacokinetic data prior to marketing authorization for metabolic therapies. Federal Ministry of Health reimbursement policies cover home nursing for subcutaneous rare disease drug administration. The Rhine-Ruhr metropolitan region hosts specialized hospital pharmacy procurement consortia consolidating orphan drug purchasing.
China
NMPA streamlined rare disease recognition pathways accelerate regulatory timelines for metabolic disorder therapies entering commercial distribution. National Health Commission pilot programs expand newborn screening to additional provinces beyond the current coverage. Shanghai and Suzhou pharmaceutical industrial parks attract synthetic organic chemistry contract manufacturers.
India
CDSCO rare disease recognition under evolving national health policy frameworks accelerates access for imported metabolic therapeutics. Pharmaceutical export promotion schemes support active pharmaceutical ingredient manufacturing scale for N-acetylglutamate analogues. Hyderabad and Ahmedabad clusters concentrate chiral synthesis expertise for orphan drug intermediates.
Switzerland
Swissmedic regulatory frameworks align with EMA standards while maintaining independent marketing authorization procedures for metabolic disorder therapies. Cantonal health insurance mandates cover home infusion nursing for urea cycle disorder patients. The Basel pharmaceutical cluster anchors European distribution infrastructure for rare disease therapeutics.
Carglumic Acid Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with orphan drug commercialization expertise commanding premium positioning against API-scale suppliers. The vendor base concentrates around three strategic archetypes: European rare disease commercialization specialists with regulatory affairs depth, Indian pharmaceutical exporters with chiral chemistry manufacturing scale, and North American chemistry service providers with niche synthesis capabilities. Capacity expansion and direct-to-hospital contracting represent the dominant competitive moves reshaping distribution economics.
Among European-based commercialization specialists, Recordati Rare Diseases exemplifies the orphan drug distribution archetype through its metabolic disorder focus. Biophore India Pharmaceuticals Pvt Ltd occupies a position within the API manufacturing tier serving formulation partners with synthetic N-acetylglutamate analogue supply. Civentichem LLC represents the North American chemistry expertise segment sustaining market presence through specialized rare disease compound capabilities.
| Leading Market Players |
|---|
| Recordati Rare Diseases |
| Apothecon Pharmaceuticals Pvt Ltd |
| Biophore India Pharmaceuticals Pvt Ltd |
| Dipharma Francis S.r.l. |
| Manus Aktteva Biopharma LLP |
| Civentichem LLC |
| NURAY CHEMICALS |
| NOVITIUM PHARMA LLC |
| Lucane Pharma |
| Others |
Supply Flow & Price Mechanics
Pediatric academic medical centers in the United States anchor procurement volume through single-source hospital contracts, compressing traditional distributor margins and shifting pricing power toward manufacturers with integrated metabolic disorder service capabilities. This buyer concentration enables value-based contracting models that bundle clinical support with pharmaceutical supply.
Pricing Analysis
Short lead-time premiums command significant markups in acute hyperammonemia scenarios where emergency department inventory must be immediately available. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and geographic delivery cost. Pricing pressure stems from sodium benzoate and sodium phenylbutyrate substitution in first-line acute management protocols. Hospital pharmacy procurement committees exhibit lowest price sensitivity due to bundled service requirements, while retail pharmacy channels face highest sensitivity from limited formulary inclusion.
Supply Chain Analysis
Direct-to-hospital channels handle the majority of demand from pediatric metabolic centers, displacing traditional wholesale relationships. Manufacturing capacity for synthetic N-acetylglutamate analogues clusters in India and Europe, with Hyderabad and Ahmedabad anchoring chiral synthesis expertise. Raw material dependencies include specialized reagents for stereochemical control, rare disease chemistry contract manufacturing capacity, and controlled-humidity packaging infrastructure. Single-source vulnerability in stereochemistry specialist labor creates supply risk. Distribution runs through specialty pharmacy platforms with home infusion capabilities for the fastest-growing outpatient segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carglumic acid market functions as a cost-of-compliance story where FDA orphan drug exclusivity frameworks and EMA pediatric investigation plans create substantial regulatory moats that protect compliant incumbents while raising barriers for prospective entrants.
For Market Incumbents: Anticipate consolidation pressure from hospital procurement committees seeking single-source agreements with integrated clinical support services. Defend position through backward integration into chiral synthesis capacity in Indian pharmaceutical clusters. Counter sodium benzoate substitution threats by expanding real-world evidence programs that demonstrate carglumic acid superiority in acute hyperammonemia resolution timelines. For New Entrants and Emerging Players: Specialty pharmacy distributors with regional nursing networks represent the most viable channel partnership for bypassing established hospital procurement hierarchies. Target homecare administration expansion in Switzerland and select United States markets where reimbursement frameworks cover subcutaneous delivery outside institutional settings. Pursue white-space opportunities in China NMPA orphan pathways where streamlined rare disease recognition reduces regulatory timelines relative to saturated Western markets. For Investors and Strategic Acquirers: The window for entry favors contract manufacturing organizations with captive chiral chemistry expertise and existing relationships with orphan drug sponsors. Long-term viability hinges on capacity to serve expanding pediatric metabolic disorder indications beyond core urea cycle applications. Monitor EMA pediatric investigation plan completion rates as the critical signal for label expansion momentum and addressable market enlargement.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | NMPA orphan drug streamlining accelerates market access in China. |
| Manufacturing Scale-Up | Chiral synthesis capacity expansion in Hyderabad serves formulation partners. |
| Hospital System Partnership | Direct contracts with Boston pediatric centers displace wholesale channels. |
| Pipeline Diversification | EMA pediatric investigation plans generate neonatal pharmacokinetic data assets. |
| Licensing Agreement | API supply partnerships with European orphan drug specialists secure revenue. |
Methodological Framework
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for this analysis, cross-referenced with formulary database audits and hospital procurement records. Primary interviews with regulatory affairs leads, hospital procurement managers, and formulary directors at pediatric academic medical centers provided operational validation. Bottom-up and top-down triangulation reconciled patient identification rates from newborn screening programs with manufacturer-reported distribution volumes.
Bottom-up modeling anchored volume projections in diagnosed prevalence expansion and dosing protocol evolution, while top-down analysis tested aggregate market sizing against metabolic disorder therapeutic expenditure patterns. Segmentation dimensions included dosage form, therapy area, end user channel, and regional regulatory cluster. CAGRs were derived from patient population growth, screening program expansion, and pricing trajectory assumptions across the analysis window. Forecast inputs incorporated caregiver certification program proliferation rates and subcutaneous administration adoption curves.
Caveats apply where regulatory timeline delays, screening program funding discontinuations, or acute management protocol shifts toward alternative ammonia scavengers could materially shift the outlook. Forecasts reflect assumptions about reimbursement continuity and orphan drug exclusivity enforcement that warrant periodic reassessment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Meglitinide Market
Pharmaceuticals
Oncology Adjuvants Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Lactated Ringers Injection Market
Pharmaceuticals
Non-Sterile Compounding Pharmacy Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
OTC Dry Eye Drops Market
Pharmaceuticals
Mexico Dimenhydrinate Market
Pharmaceuticals
Tuberculosis Therapeutics Market
Pharmaceuticals
Global Lidocaine Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
BCL-2 (B-Cell Lymphoma 2) Inhibitors Market
Pharmaceuticals
Adapalene Products Market
Pharmaceuticals
Alirocumab Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market