
 Piperonyl Butoxide (PBO) Market | 2026-2036
Piperonyl Butoxide (PBO) Market Size, Share, and Industry Trends Forecast 2026-2036
Piperonyl Butoxide (PBO) Market Outlook
Residential insecticide demand is restructuring the end-use vertical mix as vector-borne disease awareness rises in tropical and subtropical zones. Sumitomo Chemical leverages its integrated pyrethroid-synergist supply chain to sustain cost advantages across Asian manufacturing hubs. Zhejiang Rayfull Chemicals anchors its position through specialized concentrate production for agricultural export markets.
Piperonyl butoxide is a methylene dioxyphenyl compound that functions as a synergist by inhibiting cytochrome P450 monooxygenase enzymes in insects, thereby potentiating pyrethrin and pyrethroid toxicity at typical application rates of one-tenth to one-fifth the active ingredient concentration. Agricultural insecticides dominate application volumes while public health formulations represent the fastest-expanding segment driven by malaria and dengue control programs. Wettable powder formats retain margin pools in professional pest control channels where storage stability and dosing precision command premium positioning.
EPA registration requirements under FIFRA govern synergist tolerances and residue limits in the United States, while REACH compliance in Europe mandates full toxicological dossiers for import authorization. India's Central Insecticides Board regulates PBO formulations under the Insecticides Act, creating divergent compliance burdens for multinational suppliers. Stakeholders must monitor evolving maximum residue limits in food commodities and the potential reclassification of PBO as an endocrine disruptor in key export jurisdictions.
Market Dynamics
EPA registration requirements under FIFRA and REACH compliance mandates are forcing reformulation investments across the PBO value chain as residue limits tighten in major export markets.
Growth Catalysts
- Vector-borne disease programs:Malaria and dengue control initiatives in tropical zones are expanding public health insecticide procurement volumes.
- REACH authorization pathways:European toxicological dossier requirements are accelerating investment in next-generation synergist safety data packages.
- Pyrethroid resistance management:Agricultural operators are rotating PBO-enhanced formulations to preserve pyrethroid efficacy against resistant pest populations.
Market Restraints
- Safrole feedstock volatility:Piperonal synthesis depends on constrained natural extract supplies subject to harvest fluctuations in Southeast Asia.
- Endocrine disruptor reclassification risk:European Chemicals Agency hazard assessments threaten import authorization disruptions for existing formulations.
- Bio-based synergist substitution:Botanical extract alternatives are capturing niche positioning in organic-certified agricultural segments.
Strategic Opportunities
- India agrochemical manufacturing scale-up:Central Insecticides Board registration harmonization is opening formulation export capacity for regional producers.
- Microencapsulation technology convergence:Controlled-release polymer systems are enabling extended-efficacy residential applications with reduced re-treatment frequency.
- E-commerce direct distribution:Professional pest control operators are sourcing concentrated technical grades through specialized chemical marketplaces bypassing traditional distributor tiers.
Industry Challenges
- Multi-jurisdiction registration synchronization:Divergent data requirements across EPA, ECHA, and India's Central Insecticides Board are extending product launch timelines.
- Analytical method standardization gaps:Residue testing protocol inconsistencies between food safety authorities are complicating maximum residue limit compliance demonstrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piperonyl Butoxide (PBO) Market |
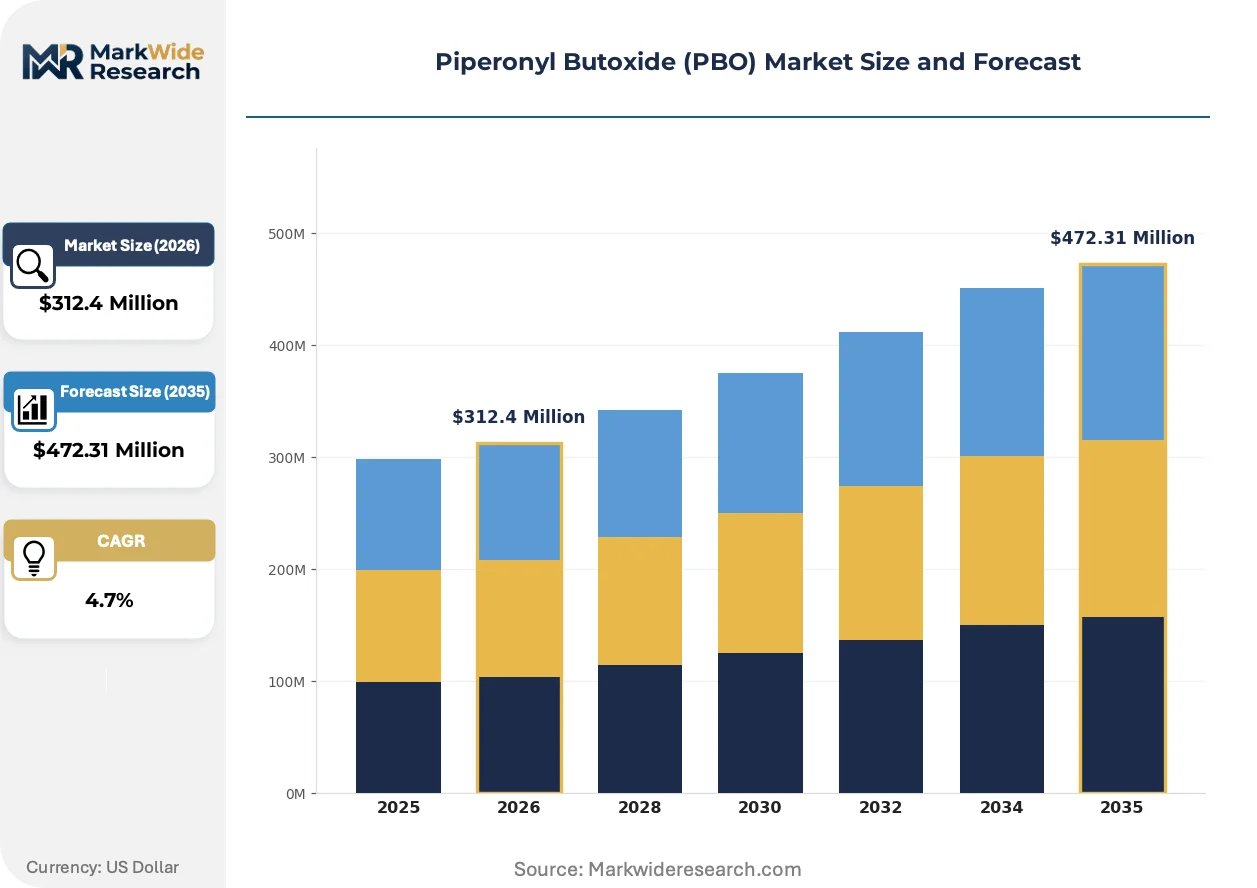
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Emulsifiable Concentrate, Granules, Wettable Powder Application: Agricultural Insecticides, Household Insecticides, Veterinary Products, Public Health Insecticides End User: Agriculture, Residential, Commercial, Industrial Distribution Channel: Online, Offline, Direct Sales, Retail |
| Companies Covered | Endura, Wujiang Shuguang Chemical, Sumitomo Chemical, Anthea, Shanghai Skyblue Chemical, Zhejiang Rayfull Chemicals, Alfa Aesar, Hem Corporation, Capot Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piperonyl Butoxide (PBO) Market Strategic Shifts
Formulation chemistry advances and regulatory data requirements are restructuring how PBO synergists are manufactured, tested, and positioned across agricultural and public health channels.
Encapsulated PBO delivery systems are electrifying application efficiency in professional pest control segments. These polymer-shell formulations release synergist on insect contact rather than immediate environmental exposure. Municipal vector control programs in Brazil and Southeast Asian countries are adopting these systems for indoor residual spraying campaigns. The technology is electrifying margin structures by reducing active ingredient load requirements per treated surface area.
REACH substance evaluation protocols under ECHA are mandating extended one-generation reproductive toxicity studies for PBO import authorization renewals. This dossier expansion is compressing registration timelines for legacy suppliers lacking contemporary toxicological data. Agricultural formulation exporters to Europe are restructuring supply chains to source PBO from manufacturers with completed extended toxicity packages.
Integrated vector management procurement frameworks are consolidating buyer power among national malaria control programs. Long-term framework agreements with WHO-prequalified suppliers are displacing spot-market purchasing for public health insecticides. This concentration is most visible in sub-Saharan African markets where Global Fund financing flows through centralized ministry of health tender processes.
Piperonyl Butoxide (PBO) Market Segmentation
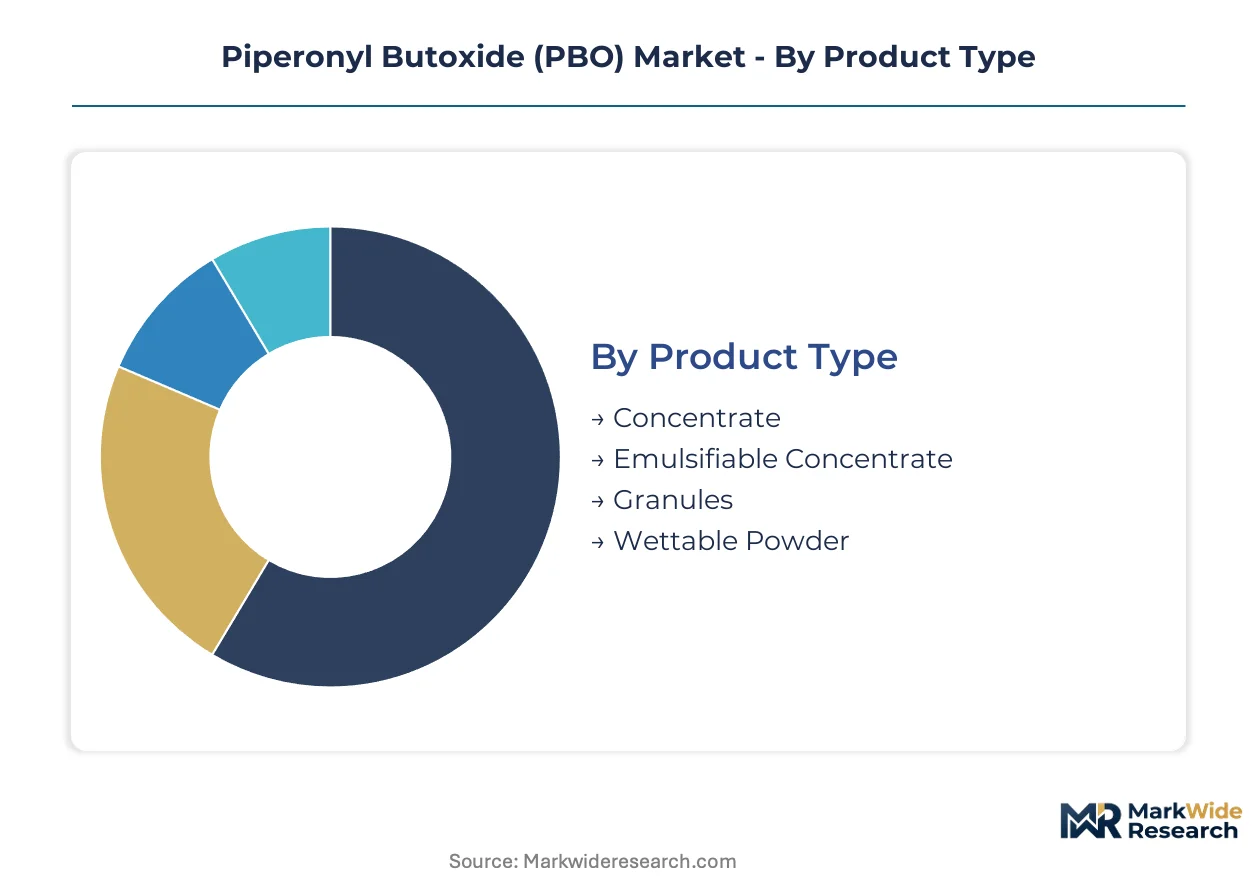
PBO formulations segment sharply by physical form and regulatory pathway, with each product type carrying distinct registration dossier requirements and margin profiles. Application concentration varies dramatically between agricultural commodity crops and vector-control public health programs, reshaping how manufacturers allocate technical grade capacity across end-use verticals.
Product Type:
Supply concentration in technical grade PBO manufacturing favors producers with backward integration into piperonal feedstocks, privileging concentrate formats that leverage captive intermediate supplies.
- Concentrate:High-purity technical grade PBO at 80-92% assay serves as the upstream feedstock for downstream formulation. Demand concentrates with Indian and Chinese agrochemical exporters who blend captive concentrate into emulsifiable concentrate and wettable powder derivatives for regional agricultural markets.
- Emulsifiable Concentrate:Oil-based formulations containing PBO dissolved in aromatic solvents with emulsifying agents enable tank-mix compatibility with pyrethroid actives. Agricultural spraying contractors in Brazil and Southeast Asia specify EC formats for aerial and ground application equipment where rapid dilution and spray uniformity reduce re-treatment costs.
- Granules:Clay-carrier granule formulations release PBO synergist through soil moisture activation, targeting subterranean pest complexes in turf and ornamental applications. Professional lawn care operators in the United States specify granule formats for perimeter barrier treatments where drift control and application precision command specification premiums.
- Wettable Powder:Micronized PBO adsorbed onto mineral carriers with dispersing agents creates stable aqueous suspensions. Storage stability and dosing precision in professional pest control channels sustain margin pools for WP formats despite handling inconvenience relative to liquid alternatives.
Concentrate absorbs the bulk of installed capacity; emulsifiable concentrate is expanding most quickly.
Application:
Cost tier differentiation separates commodity agricultural formulations from premium public health specifications with enhanced toxicological dossiers for WHO prequalification.
- Agricultural Insecticides:Tank-mix and pre-mix formulations combining PBO with pyrethroids or pyrethrins dominate volume consumption. Row crop operators in the United States, Brazil, and India rotate PBO-enhanced products into resistance management programs against Helicoverpa and Spodoptera species where metabolic detoxification threatens pyrethroid efficacy.
- Public Health Insecticides:WHO-prequalified indoor residual spraying and long-lasting insecticidal net formulations represent the steepest expansion trajectory. National malaria control programs in sub-Saharan Africa consolidate procurement through Global Fund financing, concentrating demand among suppliers with completed ECHA extended toxicity packages.
- Household Insecticides:Aerosol, coil, and vaporizer formulations for consumer residential markets incorporate PBO at sub-synergist levels for label positioning. Urban vector-borne disease awareness in tropical Asian and Latin American cities drives format innovation in household channels.
- Veterinary Products:Topical and premise spray formulations for livestock and companion animal ectoparasite control utilize PBO to potentiate pyrethrin actives. Regulatory divergence between EPA FIFRA tolerances for food animals and companion animals fragments formulation specifications across veterinary segments.
Agricultural insecticides command the largest production allocation; public health insecticides are climbing the fastest.
End User:
Customer type determines specification intensity, with commercial pest control operators demanding analytical certificates and batch traceability unavailable in residential consumer channels.
- Agriculture:Large-scale farming enterprises and agricultural cooperatives procure PBO formulations through distributor networks or direct manufacturer relationships. Volume concentration with row crop producers in the United States Corn Belt and Brazilian Cerrado sustains formulation capacity for commodity insecticide markets.
- Residential:Consumer households purchase finished insecticide products containing PBO through retail and e-commerce channels. Vector-borne disease awareness campaigns in tropical and subtropical zones restructure residential demand toward premium-positioned formulations with enhanced safety profiles.
- Commercial:Professional pest management companies and food processing facilities specify concentrated technical grades for dilution and application. Municipal vector control programs in Southeast Asian cities adopt commercial-grade formulations for integrated management of dengue and chikungunya vectors.
- Industrial:Warehousing, logistics, and manufacturing facilities utilize PBO-enhanced formulations for structural pest prevention and fumigation applications. Regulatory compliance with OSHA workplace exposure limits and EPA re-entry intervals constrains industrial application protocols.
Agriculture absorbs the bulk of installed capacity; commercial is expanding most quickly.
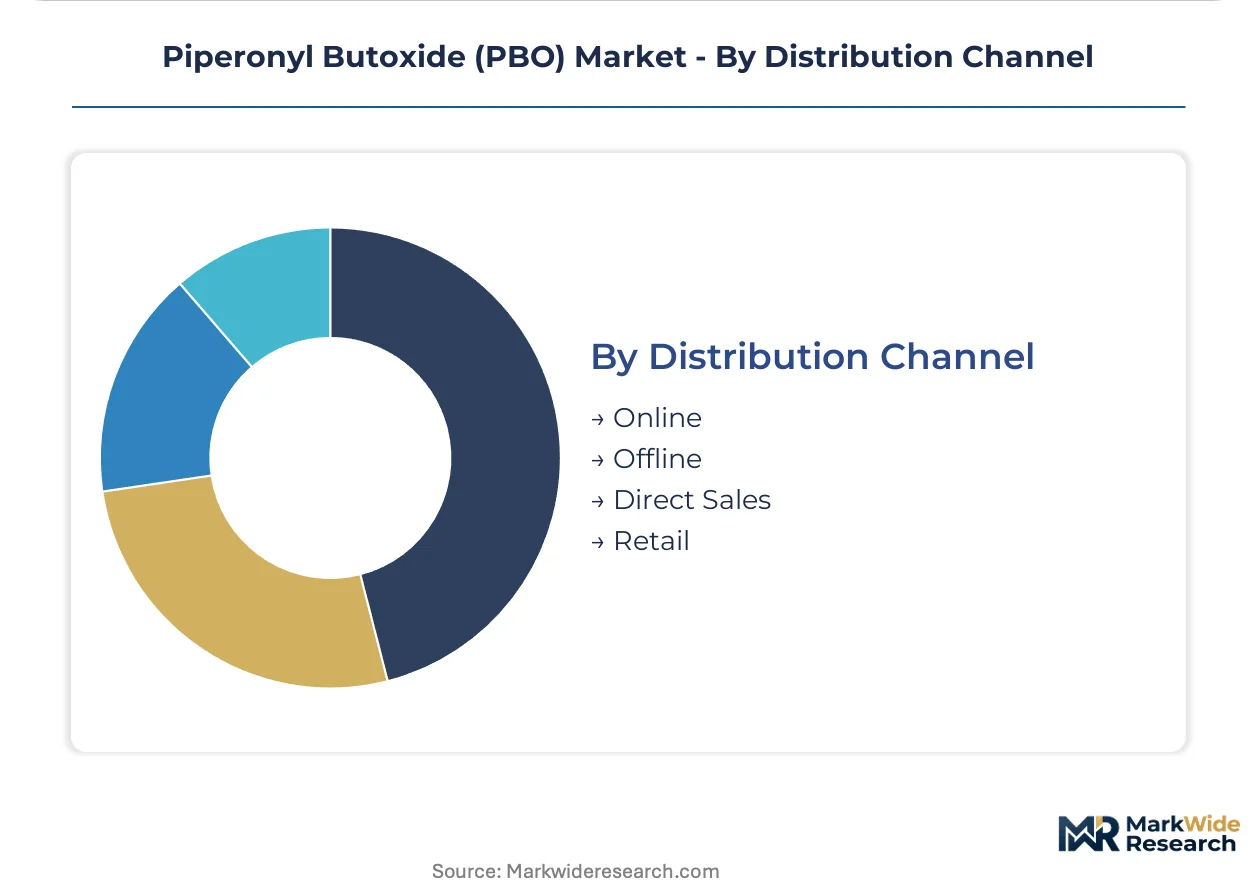
Distribution Channel:
Geography of demand concentration shapes channel selection, with remote agricultural regions dependent on distributor infrastructure while urban pest control operators leverage direct procurement.
- Offline:Agricultural supply cooperatives and specialty chemical distributors maintain formulation inventory for immediate farmer access. Rural penetration in India and Southeast Asia depends on offline distributor networks with technical advisory capabilities.
- Direct Sales:Large-scale agricultural enterprises and municipal vector control programs procure technical grade and formulated products through manufacturer direct relationships. Long-term framework agreements with national malaria control programs displace spot purchasing in public health segments.
- Online:Specialized chemical marketplaces and manufacturer e-commerce platforms enable professional pest control operators to source concentrated technical grades. E-commerce penetration concentrates in North American and European markets where regulatory familiarity reduces purchase friction.
- Retail:Mass merchandisers, home improvement centers, and agricultural supply stores stock consumer-format household insecticides. Retail shelf space allocation responds to seasonal vector activity patterns in tropical and subtropical climate zones.
Offline absorbs the bulk of installed capacity; direct sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate Indian PBO formulation capacity through tax incentives and export processing infrastructure. China's Yangtze River Delta chemical parks anchor East Asian synergist manufacturing with integrated piperonal feedstock access.
United States
EPA FIFRA registration timelines drive reformulation investments among agricultural insecticide blenders in the Corn Belt. The agency's residue limit tightening for food commodities pressures domestic formulators to source technical grades with enhanced toxicological dossiers. Manufacturing clusters in Texas and Louisiana process imported concentrate into emulsifiable concentrate and wettable powder derivatives for North American distribution.
China
Zhejiang and Jiangsu provinces dominate technical grade PBO output through captive piperonal synthesis from safrole-derived feedstocks. MEE environmental compliance inspections have shuttered smaller synthesis operations, concentrating capacity with state-permitted chemical park tenants. Ningbo and Taizhou export hubs ship concentrate to Indian and Brazilian formulators under long-term supply contracts.
India
Gujarat's Dahej and Ankleshwar chemical zones attract PBO concentrate imports for downstream formulation under the Central Insecticides Act registration pathway. The country's PLI scheme for agrochemical manufacturing is drawing technical grade investment from domestic pyrethroid producers. Mumbai-based exporters leverage Central Insecticides Board harmonization to supply WHO-prequalified public health formulations across sub-Saharan Africa.
Brazil
São Paulo state agricultural distributors specify PBO-enhanced pyrethroid formulations for soybean and cotton resistance management against Helicoverpa armigera. ANVISA residue monitoring for export commodities drives specification premiums among domestic blenders. The Cerrado mechanized farming belt concentrates demand for aerial application-compatible emulsifiable concentrate formats.
Germany
REACH authorization dossier requirements under ECHA compress import windows for legacy PBO suppliers lacking extended reproductive toxicity data. BASF and Bayer formulation operations in Ludwigshafen and Leverkusen source technical grades exclusively from manufacturers with completed substance evaluation packages. The country's agricultural cooperatives rotate PBO-synergized products into integrated pest management protocols for wheat and rapeseed protection.
Piperonyl Butoxide (PBO) Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated pyrethroid producers capturing agricultural formulation volumes while independent concentrate suppliers serve public health procurement channels. The vendor base organizes into three archetypes: backward-integrated Japanese and Chinese chemical conglomerates, Indian formulators with regional registration expertise, and European distributors with REACH compliance infrastructure. Competitive positioning depends on toxicological data package completeness and multi-jurisdiction registration synchronization speed. M&A activity concentrates among Indian agrochemical blenders acquiring Central Insecticides Board approvals, while capacity expansion focuses on Chinese technical grade producers scaling piperonal synthesis operations.
Within the integrated chemical conglomerate tier, Sumitomo Chemical exemplifies backward control over pyrethroid-synergist supply chains. Zhejiang Rayfull Chemicals occupies a position among Chinese concentrate specialists serving export formulation markets. Endura represents European distribution-centric positioning with REACH authorization pathway expertise. These three anchors illustrate how geographic origin and corporate structure shape competitive access to regulated agricultural and public health procurement channels.
| Leading Market Players |
|---|
| Endura |
| Wujiang Shuguang Chemical |
| Sumitomo Chemical |
| Anthea |
| Shanghai Skyblue Chemical |
| Zhejiang Rayfull Chemicals |
| Alfa Aesar |
| Hem Corporation |
| Capot Chemical |
| Others |
Value Chain & Pricing Dynamics
Synthetic organic chemist clusters in Zhejiang and Jiangsu provinces anchor PBO production cost structures, with labor-cost differentials between coastal China and inland India generating three-tier pricing spreads across technical grade, formulated concentrate, and finished insecticide product tiers.
Pricing Analysis
Short lead-time premiums command pricing separation between spot inventory positions and contract-scheduled deliveries. Contract-based long-term offtake dominates procurement relationships, with price differentiation resting on REACH dossier completeness and WHO prequalification status. Cost compression in economy-grade technical supplies is intensifying because Indian formulators are scaling captive blending capacity. Agricultural cooperatives in Brazil and the United States Corn Belt exhibit highest price sensitivity, while national malaria control programs in sub-Saharan Africa demonstrate lowest sensitivity due to Global Fund financing pass-through.
Supply Chain Analysis
REACH authorization and WHO prequalification requirements gate supplier participation, filtering raw material flows through certified manufacturers. China, India, and Japan concentrate technical grade output, with supply chains drawing from safrole-derived piperonal, pyrethroid active ingredients, and specialized emulsifying agents. Single-source vulnerability in Southeast Asian safrole harvests threatens feedstock continuity. Distribution runs through agrochemical distributor networks in rural agricultural regions and direct manufacturer relationships for municipal vector control programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is reshaping competitive positioning as ECHA extended toxicity dossier requirements force smaller suppliers without contemporary safety data packages to exit authorization pathways.
For Market Incumbents: Hedge registration exposure by securing backward integration into piperonal synthesis or acquiring completed REACH reproductive toxicity packages from legacy suppliers facing renewal deadlines. Sumitomo Chemical's captive pyrethroid-synergist chain demonstrates how upstream control over feedstock and intermediate synthesis defends margin pools against formulation-only competitors.
For New Entrants and Emerging Players: E-commerce direct distribution routes offer lowest-friction market entry for professional pest control operators seeking concentrated technical grades with batch traceability. White-space targets include microencapsulation formulation services for Brazilian municipal vector programs and WHO-prequalification pathway consulting for Indian exporters. A specialized chemical marketplace positioning bypasses traditional distributor tier economics.
For Investors and Strategic Acquirers: Re-rating potential sits with Indian formulators holding Central Insecticides Board approvals and established sub-Saharan African export relationships given PLI scheme manufacturing incentives. Long-term viability over the next decade favors suppliers with synchronized EPA-ECHA-India registration portfolios. The signal to watch is ECHA substance evaluation timeline acceleration for PBO import authorization renewals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive piperonal synthesis from safrole feedstocks secures margin control against harvest volatility. |
| REACH Dossier Expansion | Extended reproductive toxicity data packages unlock European import authorization renewals for concentrate suppliers. |
| Microencapsulation Technology Licensing | Controlled-release polymer systems enable premium positioning in Brazilian indoor residual spraying procurement. |
| Central Insecticides Board Registration Harmonization | Streamlined approval pathways accelerate Indian formulation export capacity for African public health markets. |
| Long-term Framework Agreement | WHO-prequalified supply contracts with Global Fund financing displace spot purchasing in malaria control programs. |
Study Parameters
Multi-period observation of EPA registration timelines, REACH authorization pathways, and Central Insecticides Board approval queues anchored the trend analysis, supplemented by interviews with agrochemical plant managers, procurement leads at downstream formulation blenders, distribution channel partners, and technical R&D directors at synergist manufacturers. Secondary validation drew from customs and trade data, SEC 10-K filings, ECHA substance evaluation dossiers, and FAO pesticide residue monitoring reports. Bottom-up technical grade capacity assessments triangulated against top-down agricultural and public health insecticide consumption models.
Input-output matrices mapped piperonal feedstock availability through technical grade, concentrate, and formulated product stages across the projection horizon. Segmentation dimensions modeled include product form tier, end-use application vertical, regional regulatory cluster, and customer type. CAGRs were derived from elasticity-adjusted demand projections incorporating pyrethroid resistance rotation patterns and vector-borne disease program funding flows. Forecast inputs integrated safrole harvest yield variability and multi-jurisdiction registration synchronization timelines.
The model holds under stable regulatory authorization frameworks; deviation in ECHA endocrine disruptor reclassification or EPA residue limit tightening would shift demand trajectories. A model refresh is warranted upon material change in WHO prequalification procurement consolidation patterns or Indian PLI scheme capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Silicone Additives Market
Additives
Sodium Stearyl Fumarate Market
Additives
Battery Additives Market
Additives
United Kingdom Sodium Reduction Ingredient Market
Additives
North America Fuel Additives Market
Additives
Competitive Inhibitors Market
Additives
Rheological Additives Market
Additives
Foundry Additives Market
Additives
Oxygen Scavengers Market
Additives
Polyols and Sorbitols Products Market
Additives
Global Feed Acidulants Market
Additives
Surface Modifiers Market
Additives
Plastic Fillers Market
Additives
Impact Modifier Market
Additives
Tire Additives Market
Additives
South America Concrete Admixtures Market