
 Anti-Pollution Ingredients Market | 2026-2036
Anti-Pollution Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Pollution Ingredients Market Analysis
Biotechnology-derived fermentation processes is rewriting how active molecules are manufactured for pollution-defense formulations. BASF SE leverages its integrated biotechnology platforms to produce high-purity antioxidants at scale. Croda International anchors its portfolio in lipid-based delivery systems that enhance skin barrier function against particulate matter. Evonik Industries specializes in silica-derived filtration agents that form protective films on epidermal surfaces.
Anti-pollution ingredients comprise bioactive compounds, mineral shields, and polymeric films formulated to neutralize free radicals, block particulate adhesion, and repair pollutant-induced skin barrier damage; these materials typically incorporate molecular weights below 500 Daltons for dermal penetration or exceed 50 nanometers for surface deposition. Antioxidants dominate value contribution due to premium pricing of stabilized vitamin C and polyphenol derivatives, while filtration agents represent the fastest-expanding category as consumers seek tangible physical barriers against urban particulate matter. Skincare commands the largest application share, though haircare actives are gaining structural importance as scalp health claims proliferate across premium product lines.
REACH in Europe mandates full ingredient disclosure and toxicity profiling for cosmetic actives, compelling reformulation away from certain synthetic chelators. The US FDA maintains its color additive and cosmetic ingredient safety review protocols, while China's NMPA implements updated cosmetic supervision regulations that require domestic safety assessment filing for imported anti-pollution claims. Stakeholders must monitor diverging regulatory timelines for novel biotech-derived actives across these three jurisdictions to preserve market access and claim substantiation.
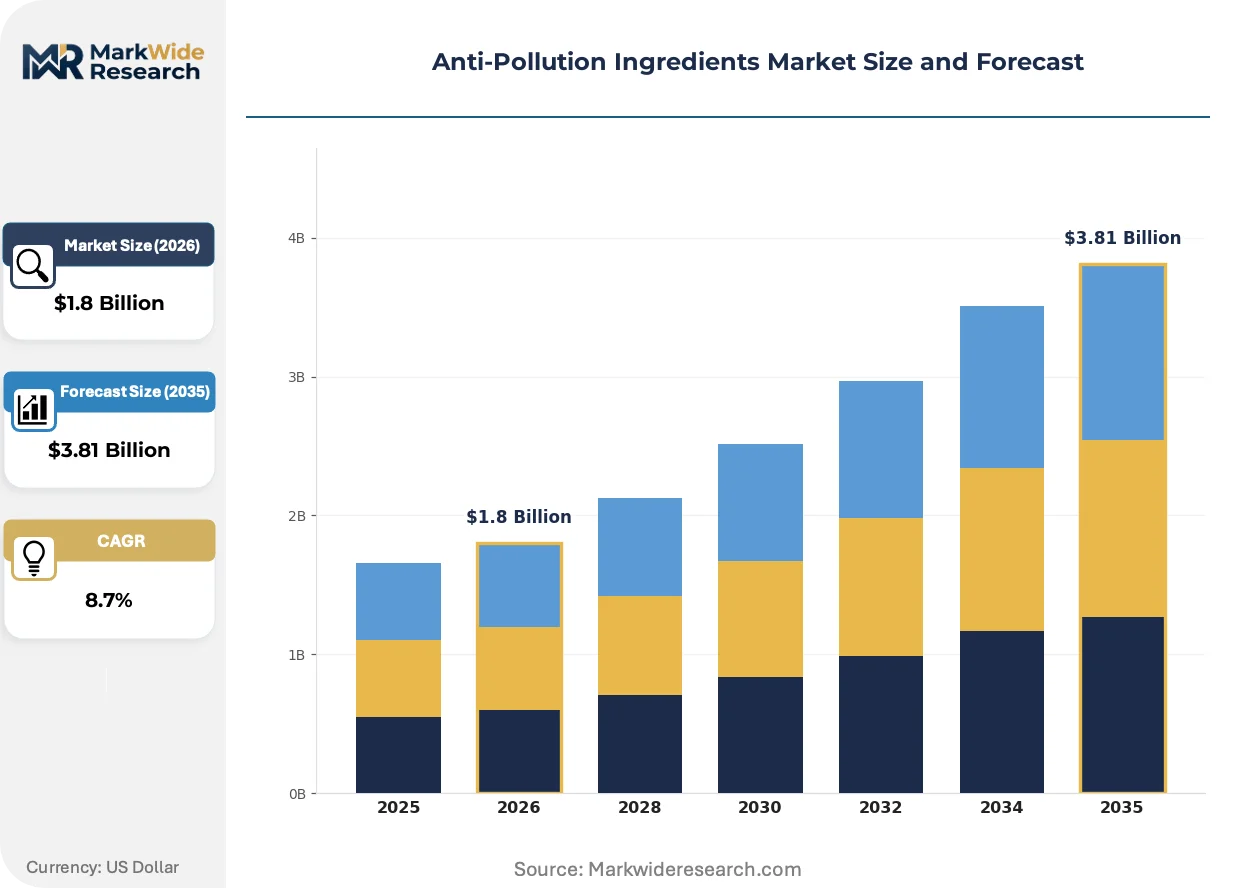
Market Dynamics
Biotechnology platforms are restructuring active ingredient manufacturing, displacing conventional chemical synthesis with fermentation-derived antioxidants that bypass petroleum feedstock volatility and REACH-mandated toxicity profiling burdens.
Growth Catalysts
- Urban air quality degradation:Fine particulate matter concentrations in Chinese megacities drive consumer willingness to pay for protective skincare formulations containing chelating agents and film-forming polymers.
- REACH disclosure mandates:Full ingredient transparency requirements across Europe accelerate reformulation toward bio-derived actives with established safety dossiers.
- Scalp health category expansion:Haircare brands extend pollution-defense claims from facial skincare to pre-shampoo treatments and leave-in conditioners, opening incremental formulation volumes.
Market Restraints
- Feedstock cost volatility:Sugar-based fermentation media prices fluctuate with Brazilian ethanol policy and global corn harvests, squeezing contract margins for biotech-derived antioxidant producers.
- Filtration agent supply concentration:High-purity silica nanoparticle production clusters among German and Japanese specialty chemical manufacturers, creating single-source vulnerability for protective film formulations.
- Dermal penetration limits:Molecular weight thresholds below 500 Daltons restrict antioxidant delivery efficacy, capping performance claims for topical pollution neutralization.
Strategic Opportunities
- India's emerging urban centers:Delhi and Mumbai air quality crises outpace local skincare innovation, creating first-mover advantage for imported anti-pollution formulations with NMPA-equivalent safety documentation.
- Blue light defense convergence:Digital screen exposure claims merge with particulate protection, enabling dual-function ingredient positioning in post-pandemic remote-work skincare routines.
- Direct-to-physician channel development:Dermatology clinic dispensing of medical-grade pollution-defense serums bypasses retail margin compression while building clinical validation for mass-market line extensions.
Industry Challenges
- Bioprocess scale-up talent scarcity:Industrial microbiologists capable of optimizing 10,000-liter fermentation runs for cosmetic-grade purity command premium compensation, constraining mid-tier manufacturer expansion.
- Multi-jurisdiction dossier compilation:Divergent safety assessment timelines between REACH, FDA cosmetic ingredient review, and NMPA filing requirements delay unified product launches by 18-24 months.
- Legacy emulsion system incompatibility:Silica-derived filtration agents require reformulation of existing moisturizer bases to prevent aggregation and sensory degradation, raising R&D overhead for established product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Pollution Ingredients Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Antioxidants, Filtration Agents, Moisturizers, Exfoliants Application: Skincare, Haircare, Makeup, Fragrance Source: Natural, Synthetic, Plant-Based, Mineral-Based Form: Creams, Oils, Gels, Powders |
| Companies Covered | Clariant, Evonik Industries, BASF SE, Lubrizol Corporation, Solvay, Croda International, Lonza Group, Solabia Group, Ashland Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Pollution Ingredients Market Emerging Trajectories
Active delivery architectures are undergoing fundamental redesign as brands seek measurable protection against increasingly characterized urban pollutant mixtures. Three interconnected developments are restructuring competitive capabilities.
Fermentation-derived biosurfactants are migrating from niche organic positioning to mainstream pollution-defense formulations. These glycolipid molecules function as both mild cleansers and particulate dispersion agents. Mass-market skincare lines in South Korea and France now specify biosurfactant content above 2% by weight. This migration is compressing demand for petroleum-derived sulfates while establishing new supplier qualification hurdles around fermentation consistency.
REACH authorization requirements for synthetic chelators are forcing systematic substitution toward plant-derived alternatives. ECHA's 2024 updated candidate list restrictions on EDTA derivatives compel reformulation of antioxidant stabilization systems. Color cosmetic manufacturers serving the European market respond fastest, accelerating phytochemical screening programs to identify polyphenol complexes with comparable metal-ion sequestration capacity.
Ingredient buyers now require quantified pollution-protection metrics rather than generic antioxidant claims. Contract manufacturers serving prestige skincare brands substitute traditional ORAC assays with standardized particulate adhesion tests using diesel exhaust surrogates. This behavioral shift concentrates purchase decisions among suppliers with in-house toxicology and clinical validation capabilities, marginalizing commodity antioxidant traders in the German and Japanese procurement landscapes.
Anti-Pollution Ingredients Market Segmentation
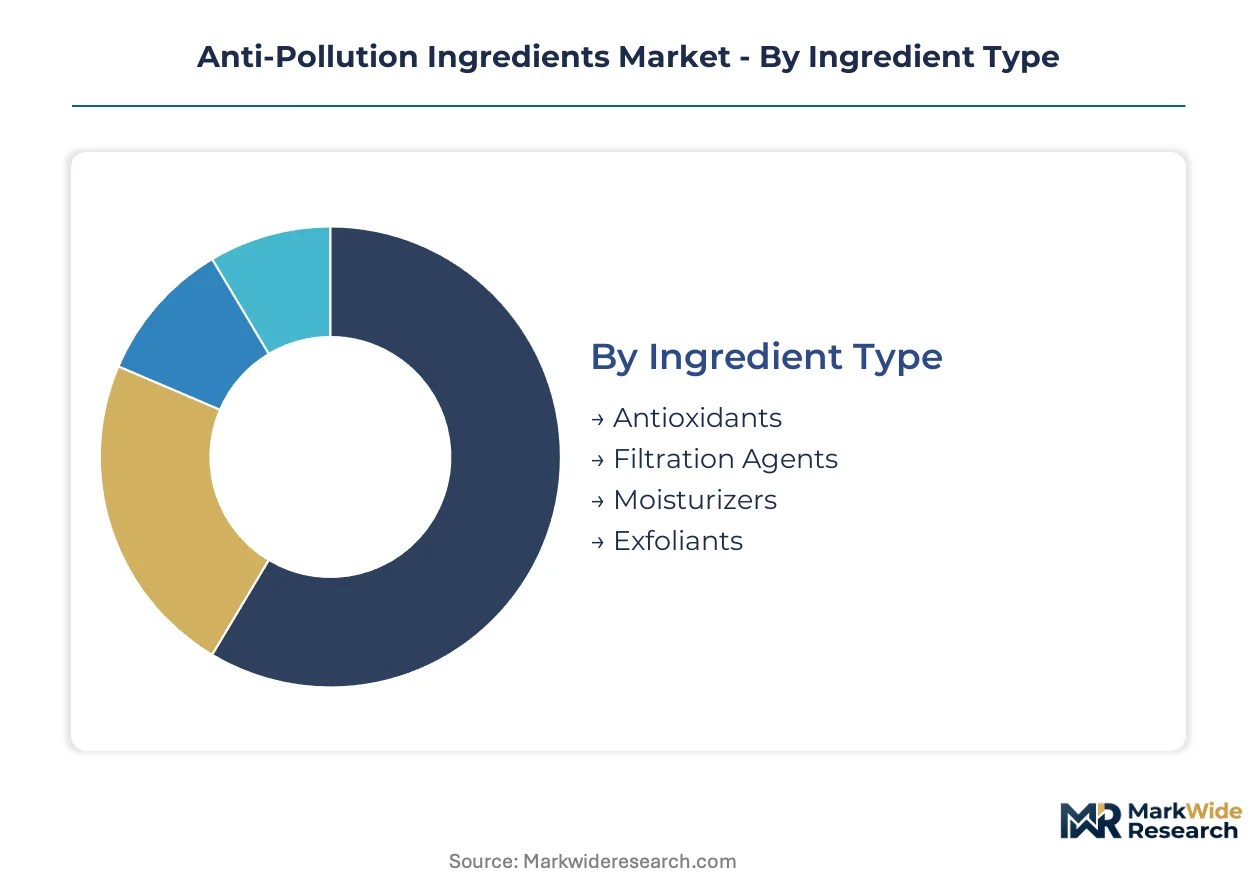
Ingredient categorization determines formulation compatibility with existing emulsion systems and regulatory dossier requirements. Application-based segmentation reveals divergent performance claims substantiation protocols across facial skincare versus scalp treatments. Source and form classifications directly impact REACH disclosure burdens and consumer clean-beauty positioning strategies.
Ingredient Type:
After-sales technical service intensity varies sharply across ingredient categories, with fermentation-derived actives demanding sustained bioprocess troubleshooting support versus commodity mineral shields.
- Antioxidants:Stabilized vitamin C derivatives and polyphenol complexes neutralize free radicals from particulate matter exposure. Demand concentrates in premium Chinese urban skincare formulations where consumers pay for proven oxidative stress reduction. These actives command the highest ingredient supplier margins due to complex stabilization requirements.
- Filtration Agents:Silica nanoparticles and polymeric films form physical barriers against particulate adhesion to epidermal surfaces. Adoption accelerates in South Korean and French mass-market lines seeking tangible protection metrics. Supply concentrates among German and Japanese specialty chemical manufacturers, creating qualification bottlenecks for new entrants.
- Moisturizers:Barrier-repair lipids and humectants counteract pollutant-induced transepidermal water loss.
- Exfoliants:Mild acids and enzymatic agents remove particulate-bound surface cells without compromising barrier function.
By volume, moisturizers lead due to universal formulation incorporation. By growth pace, filtration agents are climbing the fastest as particulate protection claims proliferate.
Application:
Cost tier stratification separates medical-grade dermatology clinic dispensing from mass retail and economy private-label positioning.
- Skincare:Daily moisturizers, serums, and sunscreens embed pollution-defense actives at functional concentrations above 2% by weight. Chinese megacity consumers drive premium adoption, while European reformulation responds to REACH-mandated disclosure timelines. Facial applications dominate absolute volume.
- Haircare:Pre-shampoo treatments and leave-in conditioners extend pollution claims to scalp health, opening incremental formulation volumes previously captured by facial skincare alone. South Korean brands lead structural innovation in this extension category.
- Makeup:Color cosmetics integrate mineral shields and antioxidants for all-day urban protection claims.
- Fragrance:Limited incorporation of volatile-neutralizing actives addresses odor pollution associations in high-density Asian cities.
By volume, skincare leads. By growth pace, haircare is expanding most quickly as scalp health claims gain regulatory clearance.
Source:
Customer procurement patterns bifurcate between clean-beauty-certified natural positioning and performance-optimized synthetic portfolios.
- Natural:Unprocessed botanical extracts appeal to organic certification requirements in European and North American niche segments. Supply volatility from agricultural harvests constrains scale.
- Synthetic:Petroleum-derived chelators and stabilized molecules offer batch consistency and REACH toxicity profiling efficiency. ECHA candidate list restrictions on EDTA derivatives accelerate substitution pressure.
- Plant-Based:Fermentation-derived biosurfactants and polyphenols merge renewable feedstock positioning with biotechnology manufacturing precision.
- Mineral-Based:High-purity silica and clay derivatives provide physical filtration without dermal penetration concerns.
By volume, synthetic leads. By growth pace, plant-based is gaining share fastest as fermentation platforms mature.
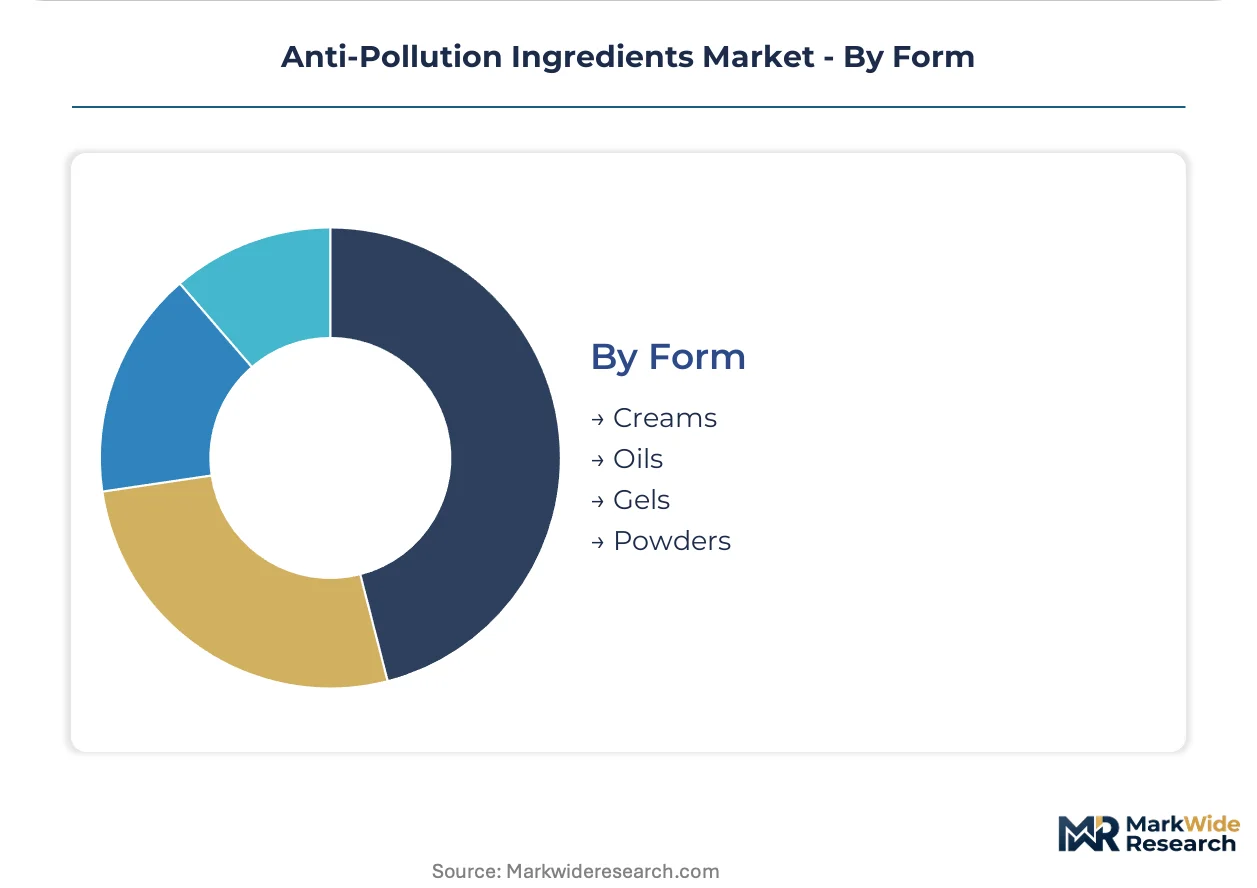
Form:
Supply chain concentration in emulsion manufacturing clusters determines regional availability of compatible delivery vehicles.
- Creams:Oil-in-water emulsions dominate facial moisturizer applications, requiring reformulation to prevent silica nanoparticle aggregation.
- Oils:Anhydrous systems suit antioxidant stabilization without aqueous degradation pathways.
- Gels:Hydroalcoholic and hydrogel bases enable lightweight texture preferences in humid Asian climates.
- Powders:Loose and pressed formats incorporate mineral shields for makeup applications with extended wear claims.
By volume, creams lead. By growth pace, gels are expanding most quickly due to texture innovation in Southeast Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialty chemical exporters supply filtration agents and fermentation-derived actives to formulators in China, South Korea, and France. Trade corridors concentrate high-purity silica nanoparticles and stabilized antioxidants through Rotterdam and Shanghai ports.
China
Urban air quality crises in Beijing, Shanghai, and Guangzhou drive premium consumer willingness to pay for particulate protection. NMPA cosmetic supervision regulations mandate domestic safety assessment filing for imported anti-pollution claims. Yangtze River Delta formulators cluster in Shanghai and Suzhou, integrating German silica nanoparticles into mass-market skincare lines.
Germany
REACH authorization requirements for synthetic chelators accelerate reformulation toward bio-derived actives with established safety dossiers. ECHA's updated candidate list restrictions on EDTA derivatives compel systematic substitution programs. Industrial biotechnology platforms concentrate in Ludwigshafen and Leverkusen, producing fermentation-derived antioxidants at pharmaceutical-grade purity.
South Korea
Scalp health category expansion extends pollution-defense claims from facial skincare to pre-shampoo treatments. MFDS cosmetic safety standards require substantiation for barrier-repair and particulate-blocking claims. Seoul-based brands lead structural innovation in lightweight gel formulations for humid Asian climates.
France
Clean-beauty certification requirements in European niche segments elevate demand for plant-derived polyphenol complexes. ANSM enforces full ingredient disclosure and toxicity profiling for cosmetic actives. Cosmetic formulators cluster in Paris and Grasse, merging biosurfactant content with heritage fragrance expertise.
United States
FDA cosmetic ingredient review protocols maintain safety thresholds for synthetic filtration agents while biotech-derived actives await unified assessment timelines. EPA evolving oversight of cosmetic ingredients tightens environmental release standards. New Jersey and California formulation labs develop dual-function blue light and particulate protection systems for remote-work skincare routines.
Anti-Pollution Ingredients Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct capability tiers. German and Swiss conglomerates with integrated biotechnology platforms dominate antioxidant manufacturing, while Japanese and French specialists concentrate high-purity silica nanoparticle production. Strategic moves center on fermentation capacity expansion and REACH-compliant safety dossier compilation. Partnership structures between raw material suppliers and contract manufacturers determine formulation access in premium skincare segments.
Among diversified chemical conglomerates, BASF SE anchors the integrated biotechnology platform tier, Croda International exemplifies lipid-based delivery system specialization, and Evonik Industries occupies a position in silica-derived protective films. These three entities represent divergent competitive archetypes: fermentation-scale manufacturing, functional ingredient formulation, and inorganic materials engineering. Each sits within distinct regulatory compliance burdens and customer qualification protocols across REACH, FDA, and NMPA jurisdictions.
| Leading Market Players |
|---|
| Clariant |
| Evonik Industries |
| BASF SE |
| Lubrizol Corporation |
| Solvay |
| Croda International |
| Lonza Group |
| Solabia Group |
| Ashland Global |
| Others |
Supply Flow & Price Mechanics
Ludwigshafen's fermentation capacity expansions determine downstream pricing leverage for biotechnology-derived antioxidants, with German chemical clusters anchoring global supply of high-purity actives while Asian formulators absorb transport and tariff premiums into landed costs.
Pricing Analysis
Next-generation fermentation-derived biosurfactants command substantial premiums over petroleum-derived sulfates and first-generation plant extracts, with price differentiation driven by REACH-compliant safety dossiers and pharmaceutical-grade purity certification. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade antioxidants for dermatology dispensing from mass-market skincare actives and commodity mineral shields. Pricing pressure stems from Brazilian ethanol policy volatility squeezing sugar-based fermentation media margins, with contract manufacturers showing highest price sensitivity while prestige skincare brands absorb premiums for substantiated particulate protection claims.
Supply Chain Analysis
Sugar cane and corn feedstock markets in Brazil and the American Midwest anchor fermentation input costs for biotechnology platforms, with German and Japanese specialty chemical manufacturers concentrating high-purity silica nanoparticle production. Raw material dependencies include fermentation media, petroleum-derived chelator precursors, and refined mineral feedstocks for barrier-film formulations. Single-source vulnerability in silica nanoparticle supply creates qualification bottlenecks for protective film formulations. Distribution runs through Rotterdam and Shanghai port clusters serving Yangtze River Delta and European formulator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial microbiologists capable of optimizing pharmaceutical-grade fermentation runs represent the critical talent bottleneck constraining mid-tier manufacturer expansion, with bioprocess scale-up expertise determining competitive positioning across the analysis window.
For Market Incumbents: Entrench market position through captive fermentation capacity additions in German biotechnology clusters and preemptive REACH-compliant safety dossier compilation for novel actives. Synthetic chelator substitution pressure from ECHA candidate list restrictions demands accelerated phytochemical screening programs to preserve European market access. Backward integration into sugar-based fermentation media supply hedges Brazilian ethanol policy volatility. For New Entrants and Emerging Players: Pursue white-space opportunities in India's emerging urban centers where Delhi and Mumbai air quality crises outpace local formulation innovation, leveraging NMPA-equivalent safety documentation for first-mover advantage in premium anti-pollution skincare. Direct-to-physician channel development for medical-grade pollution-defense serums offers margin protection absent in retail compression. Haircare scalp health extensions represent the most penetrable application segment with lower incumbent saturation. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core cosmetic ingredient portfolios, particularly lipid-based delivery system specialists and fermentation platform operators with underutilized capacity. Long-term viability hinges on biotechnology manufacturing precision displacing petroleum-derived synthesis. Watch for ECHA authorization timeline accelerations as inflection indicators for synthetic chelator substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | BASF SE's integrated biotechnology platforms in Ludwigshafen anchor pharmaceutical-grade antioxidant supply security. |
| REACH-Compliant Dossier Compilation | ECHA candidate list restrictions on EDTA derivatives compel systematic substitution toward bio-derived actives with established safety profiles. |
| Direct-to-Physician Channel Development | Dermatology clinic dispensing of medical-grade serums builds clinical validation for mass-market line extensions. |
| Backward Integration into Feedstock Supply | Captive sugar-based fermentation media sourcing hedges Brazilian ethanol policy volatility squeezing contract margins. |
| Joint Venture in Asian Manufacturing | Shanghai and Suzhou formulator clusters integrate German silica nanoparticles into mass-market skincare lines serving Chinese megacity demand. |
Methodological Framework
Cross-validation between primary interviews with fermentation platform engineers, cosmetic formulator R&D directors, and regulatory affairs specialists and secondary validation from ECHA candidate list updates, NMPA cosmetic supervision regulations, and customs trade data anchors the qualitative findings. Bottom-up triangulation across ingredient supplier production disclosures and top-down reconciliation against end-product formulation volumes ensures segmentation integrity.
Calibration against historical capacity utilization rates and patent filing trajectories informs the analytical framework across the projection horizon. Segmentation dimensions modeled include ingredient type, application, source, and form classifications alongside regional regulatory cluster variations. CAGRs derive from normalized growth rate convergence across demand-side uptake curves and supply-side capacity expansion timelines, with biotechnology platform maturation curves and urban air quality degradation indices serving as industry-specific forecast inputs.
Sensitivities concentrate around ECHA authorization timeline accelerations, Brazilian ethanol policy shifts, and NMPA filing requirement changes that could compress or extend unified product launch windows. Cross-checking against customs trade data for high-purity silica nanoparticles and fermentation-derived antioxidant volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Packaging Coating Additives Market
Additives
Feed Additive Nosiheptide Premix Market
Additives
Canada Anti-Caking Market
Additives
Global Chelated Trace Minerals Market
Additives
Anti-Settling Agents Market
Additives
Sodium Stearyl Fumarate Market
Additives
PVC Plasticizers and Stabilizers Market
Additives
North America Pectin Market
Additives
Refinery Process Additives Market
Additives
Carboxymethylcellulose (CMC) Market
Additives
Global Glass Additives Market
Additives
Printing Ink Additives Market
Additives
Choline Chloride Market
Additives
Global UV Stabilizers Market
Additives
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market
Additives
North America Paints and Coatings Additives Market