
 Octane Improver Fuel Additives Market | 2026-2036
Octane Improver Fuel Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Octane Improver Fuel Additives Market Outlook
Specialized fuel chemist and refinery process engineering talent is redrawing competitive boundaries across the octane improver value chain. BASF SE leverages its integrated C4 chemistry platform to sustain captive supply of isooctane precursors. Afton Chemical anchors North American distribution through direct refinery relationships. Innospec competes on detergent-compatible octane booster formulations that meet Top Tier gasoline specifications.
Octane improver fuel additives are oxygenated or aromatic compounds blended into gasoline to raise Research Octane Number and Motor Octane Number, typically formulated at 5-15% treat rates depending on base fuel quality and target specification. Their primary purpose is to prevent engine knock in high-compression and turbocharged direct-injection engines while enabling more aggressive ignition timing for power recovery. Ethanol dominates volume flows given its renewable fuel standard mandate status and established infrastructure across major consuming markets. Fuel Retailers represent the fastest-growing end-user channel as branded gasoline programs differentiate on octane tiering. Performance Enhancement applications command the widest margin pools where premium and super-premium gasoline grades justify additive cost recovery.
EPA regulates gasoline volatility and benzene content under the Clean Air Act, directly constraining aromatic octane booster blending limits while creating demand for oxygenated alternatives. REACH and the EU Fuel Quality Directive govern aromatic compound classification and sulfur limits in European gasoline pools. California Air Resources Board operates the Low Carbon Fuel Standard, which assigns carbon intensity scores that favor bio-based octane improvers over fossil-derived aromatics. Stakeholders must monitor LCFS credit price trajectories and state-level clean fuel program expansions to anticipate which chemistries will capture incremental octane demand.
Market Dynamics
Engine downsizing and turbocharging penetration is forcing refiners to source higher-octane blending components, tightening the supply-demand balance for oxygenated improvers while aromatic alternatives face regulatory compression.
Growth Catalysts
- EPA Tier 3 sulfur standards:These specifications constrain benzene and aromatic content in US gasoline pools, redirecting formulation demand toward ethanol and isooctane precursors that deliver octane without sulfur penalty.
- Fuel Retailer channel expansion:Branded gasoline programs at major retail chains are tiering octane offerings to capture margin premiums, accelerating additive procurement for super-premium grade differentiation.
- Direct-injection turbocharged engines:Powertrain architectures with compression ratios above 10:1 require Research Octane Number ratings of 95+ to prevent knock, embedding octane improvers as essential formulation components.
Market Restraints
- Feedstock cost volatility:Butane and isobutylene prices fluctuate with natural gas liquids markets, compressing margins for alkylate-derived octane boosters during upstream price spikes.
- REACH aromatic classification:ECHA hazard designations for toluene and xylene blends impose handling restrictions and substitution pressures across European refining operations.
- Ethanol blend wall constraints:Infrastructure limitations at 10% by volume in legacy vehicle fleets cap oxygenate-based octane contribution in certain distribution networks.
Strategic Opportunities
- California LCFS credit markets:Carbon intensity scoring under CARB rules favors bio-based octane improvers, creating premium pricing capture for renewable ethanol and next-generation biobutanol pathways.
- Top Tier gasoline certification:Detergent-compatible octane booster formulations that meet this retail standard unlock placement at major oil company branded stations.
- Refinery alkylation unit retrofits:Upgrades at complex US Gulf Coast facilities are expanding merchant supply of isooctane for non-integrated blenders seeking high-purity octane sources.
Industry Challenges
- Specialized fuel chemist scarcity:Formulation expertise spanning combustion kinetics and regulatory compliance is concentrating at integrated majors, constraining independent additive house R&D bandwidth.
- Multi-jurisdiction certification timelines:Parallel EPA, CARB, and state-level fuel registration processes extend product commercialization cycles by 18-24 months for novel oxygenate chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Octane Improver Fuel Additives Market |
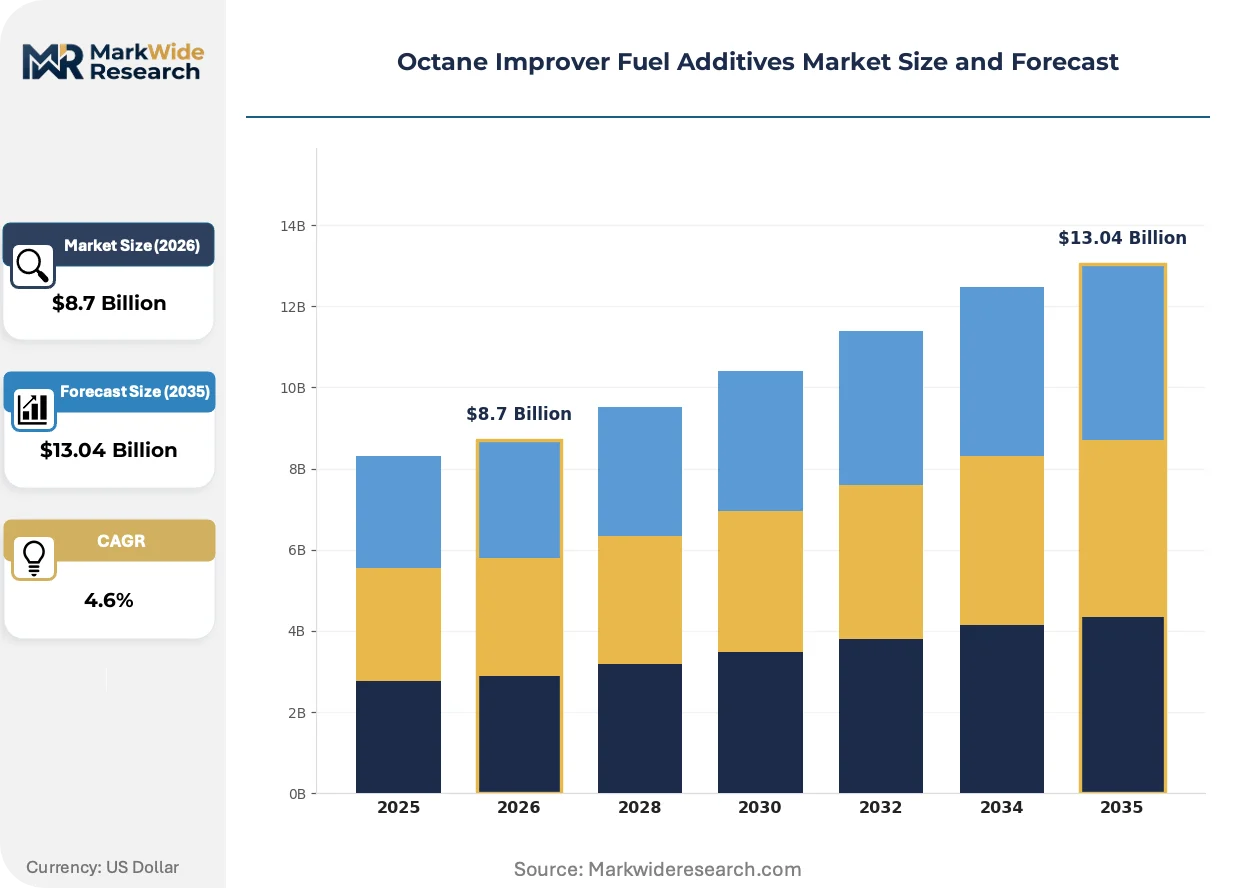
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethanol, Methanol, Toluene, Isooctane End User: Automotive OEMs, Fuel Retailers, Aftermarket Providers, Engine Manufacturers Application: Performance Enhancement, Engine Cleaning, Emission Reduction, Fuel Efficiency Distribution Channel: Online Retail, Distributors, Direct Sales, Others |
| Companies Covered | The Lubrizol Corporation, Afton Chemical, BASF SE, TotalEnergies, Dorf Ketal, Innospec, Infineum International Ltd., LyondellBasell Industries Holdings B.V., Chevron Oronite Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Octane Improver Fuel Additives Market Strategic Shifts
Formulation science is splitting between legacy aromatic pathways and oxygenate-dominated alternatives as regulatory carbon accounting and engine hardware requirements diverge.
Isooctane production from renewable feedstocks is bifurcating the high-octane segment. Biobased alkylate derived from agricultural residues delivers identical combustion performance to fossil-derived equivalents. European refiners and US West Coast blenders are securing offtake agreements at pace. This pathway is bifurcating premium gasoline formulation into carbon-intensity-graded tiers that command divergent pricing.
REACH authorization procedures for aromatic hydrocarbons are tightening supply access. ECHA sunset dates for certain toluene derivatives are forcing reformulation investments across EU refining. German and Dutch blenders are accelerating ethanol and ETBE substitution to preempt authorization withdrawal risks.
Performance fuel retailing is consolidating around certification-driven brand equity. Major oil companies are unbundling additive packages from base fuel supply, contracting directly with additive houses for proprietary detergent-octane combinations. This restructuring is most visible in US metropolitan markets where Top Tier signage commands pump price premiums of eight to twelve cents per gallon.
Octane Improver Fuel Additives Market Segmentation
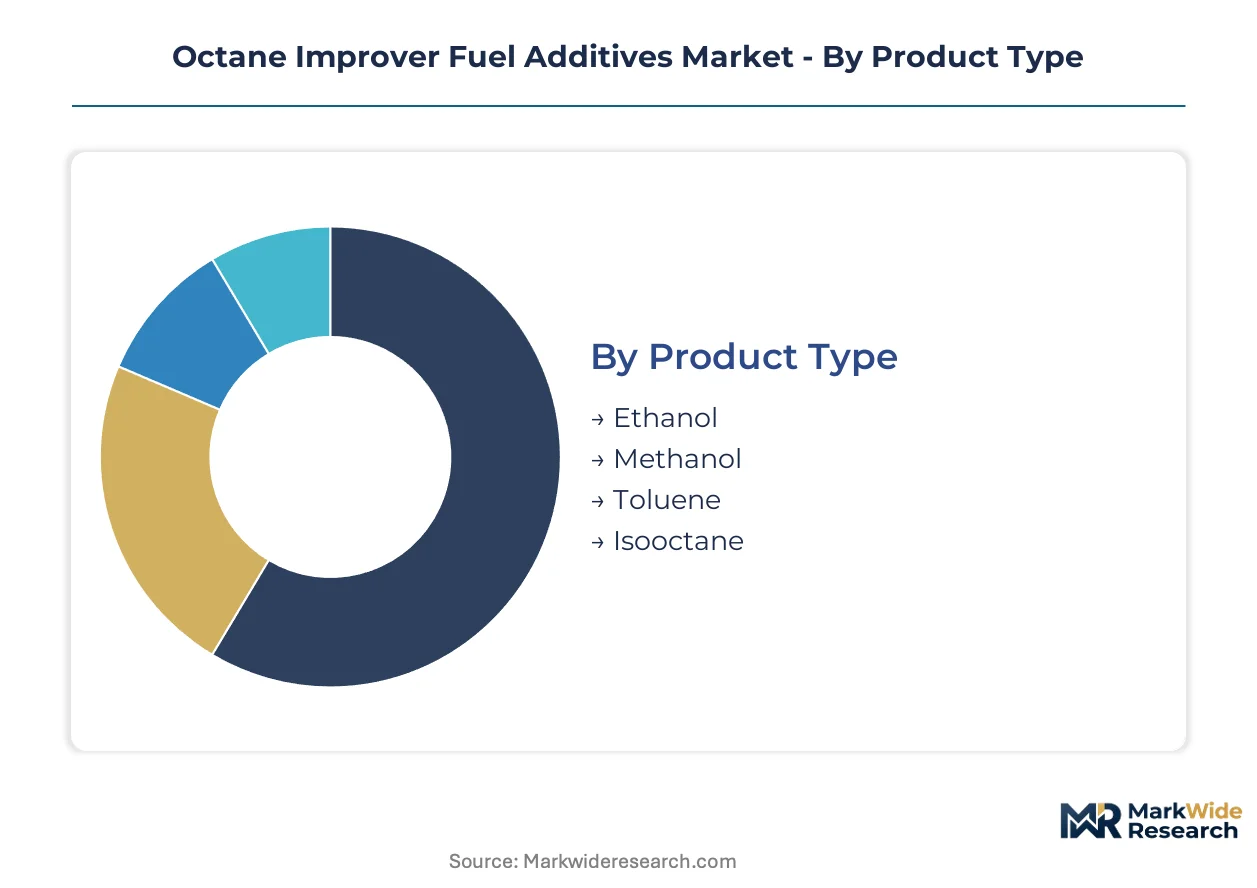
Octane improver formulation economics vary sharply across product chemistries and procurement channels. Margin capture depends on regulatory positioning, treat rate economics, and the ability to meet certification standards that unlock branded gasoline placement.
Product Type:
Margin pools concentrate in oxygenated compounds that satisfy renewable fuel mandates while delivering high-octane lift per volume.
- Ethanol:Fermentation-derived oxygenate delivering 113 Research Octane Number at 10% treat rates. US and Brazilian refiners prioritize ethanol for its renewable fuel standard compliance and established blending infrastructure. EPA volatility waivers and LCFS credit eligibility sustain premium positioning against fossil alternatives.
- Isooctane:Highly branched paraffin produced via alkylation or renewable fermentation pathways. German and US Gulf Coast refiners source isooctane for its zero-oxygen content and compatibility with high-RON gasoline pools where benzene limits constrain aromatic alternatives.
- Methanol:Synthesis gas-derived alcohol with corrosive handling requirements limiting its gasoline blending share. Chinese industrial producers supply methanol for niche racing fuel applications.
- Toluene:Aromatic octane booster facing regulatory compression under REACH authorization and EPA benzene content caps. European blenders are accelerating substitution timelines.
The dominant share belongs to Ethanol, while Isooctane is closing the gap fastest as biobased production pathways scale.
End User:
Procurement authority is fragmenting as fuel retailers unbundle additive packages from base fuel supply.
- Fuel Retailers:Branded gasoline programs at major chains now contract directly with additive houses for proprietary detergent-octane combinations. Top Tier certification requirements and pump price premiums of eight to twelve cents per gallon in US metropolitan markets justify dedicated additive procurement teams.
- Automotive OEMs:Engine manufacturers specify minimum octane ratings for turbocharged direct-injection powertrains, influencing refinery blending decisions through warranty compliance requirements. German and Japanese OEMs are tightening octane recommendations for downsized engines.
- Aftermarket Providers:Independent distributors serve performance enthusiasts and legacy fleet operators with bottled octane boosters for occasional high-load operation.
- Engine Manufacturers:Industrial engine builders specify fuel quality for stationary and marine applications where knock resistance affects durability warranties.
Fuel Retailers command the steepest expansion trajectory as branded differentiation intensifies, while Automotive OEMs retain specification influence through powertrain calibration requirements.
Application:
Commercial value scales with the ability to bundle multiple performance claims into certified additive packages.
- Performance Enhancement:Octane improvers enabling aggressive ignition timing and power recovery in high-compression engines. Premium and super-premium gasoline grades absorb additive costs most readily.
- Engine Cleaning:Detergent-compatible formulations meeting Top Tier deposit control standards while delivering octane lift.
- Emission Reduction:Oxygenated improvers supporting complete combustion and reduced particulate formation in direct-injection engines.
- Fuel Efficiency:Octane quality enabling downsized engine operation at optimal compression ratios without knock-limited fuel enrichment.
Performance Enhancement captures the dominant value share, though Engine Cleaning is climbing fastest as certification standards merge octane and detergent requirements.
Distribution Channel:
Channel economics favor direct relationships where formulation expertise and regulatory registration support justify bypassing intermediaries.
- Direct Sales:Additive houses maintain technical service teams at major refinery and retail chain headquarters. California and Texas markets show highest direct procurement penetration.
- Distributors:Regional chemical distributors serve mid-size blenders lacking volume thresholds for direct manufacturer relationships.
- Online Retail:E-commerce platforms reach performance enthusiasts and small fleet operators with packaged octane boosters.
- Others:Cooperative procurement arrangements among independent fuel marketers.
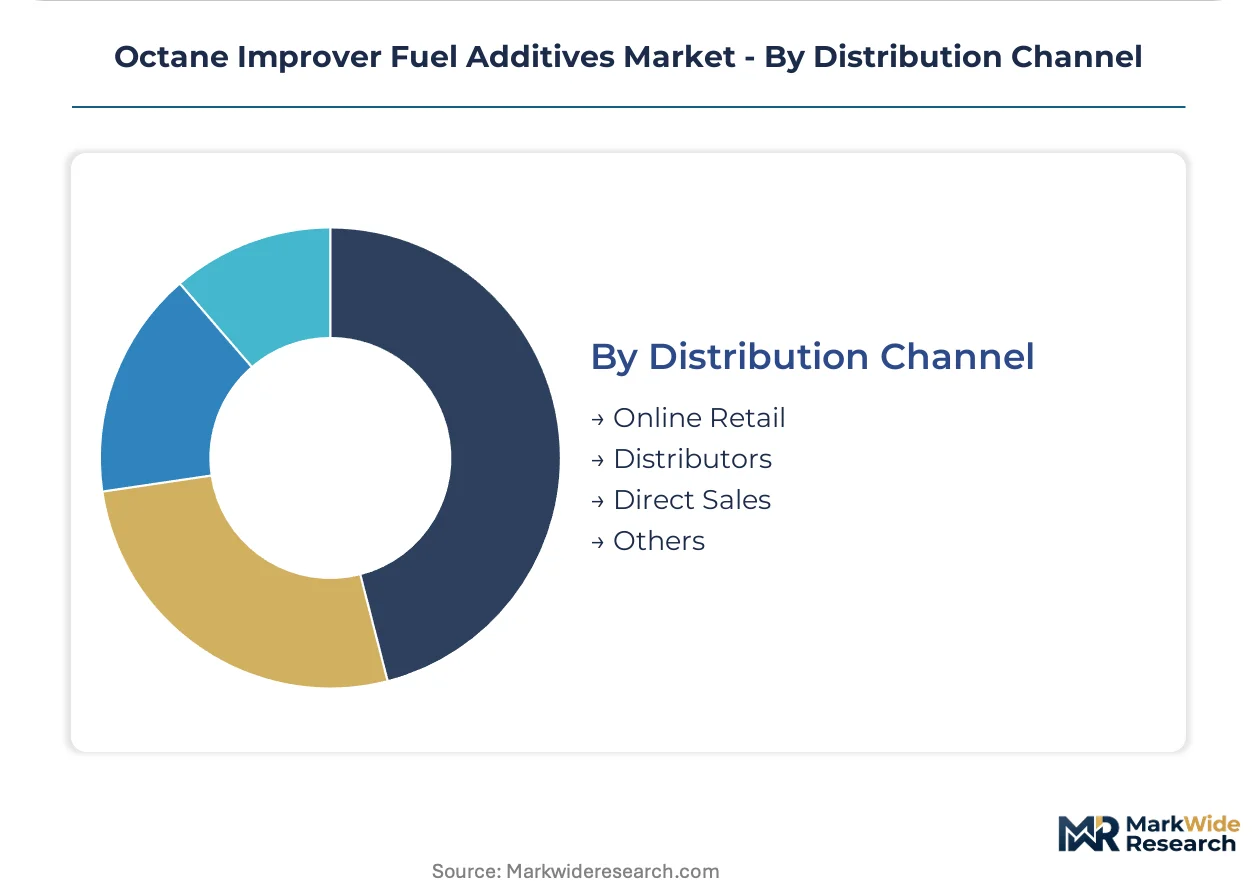
Direct Sales holds the dominant position, while Online Retail is expanding most quickly in the aftermarket segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 3 standards and California's LCFS are tightening fuel quality benchmarks across the United States, while REACH authorization pressures and engine downsizing trends concentrate additive demand in Germany and China. Refinery upgrades and performance fuel retailing command premium positioning in these three markets.
United States
Fuel retailers at major chains tier octane offerings to capture margin premiums of eight to twelve cents per gallon. EPA volatility waivers and LCFS credit eligibility sustain ethanol positioning against fossil alternatives. Texas and California markets show highest direct procurement penetration from additive houses.
China
Engine downsizing and turbocharging penetration force refiners to source higher-octane blending components. MIIT fuel quality standards and dual carbon goals redirect formulation toward oxygenated improvers. Yangtze River Delta refiners are securing offtake agreements for biobased alkylate at pace.
Germany
Automotive OEMs specify minimum octane ratings for turbocharged direct-injection powertrains through warranty compliance requirements. ECHA sunset dates for certain toluene derivatives force reformulation investments across EU refining. Bavarian and North Rhine-Westphalian blenders accelerate ethanol and ETBE substitution.
Brazil
Established fermentation infrastructure and renewable fuel mandates prioritize ethanol for octane contribution. ANVISA and national biofuel programs sustain premium positioning for oxygenated alternatives. São Paulo state refiners leverage captive sugarcane supply chains for cost-competitive blending.
Japan
METI fuel quality directives and automotive OEM calibration requirements embed octane improvers as essential formulation components. Kanto and Kansai refining clusters source high-purity isooctane for super-premium gasoline grades where benzene limits constrain aromatic alternatives.
Octane Improver Fuel Additives Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that competes on detergent-compatible formulations and direct refinery relationships. BASF SE leverages integrated C4 chemistry platforms to sustain captive supply of isooctane precursors, while Afton Chemical anchors North American distribution through direct refinery relationships. Innospec competes on detergent-compatible octane booster formulations that meet Top Tier gasoline specifications. Strategic moves concentrate on refinery alkylation unit retrofits and Top Tier certification capture.
Within the integrated chemistry tier, BASF SE and TotalEnergies represent archetypes of backward integration into precursor supply chains. Among North American specialists, Afton Chemical exemplifies the direct refinery relationship model that bypasses distributor intermediaries.
| Leading Market Players |
|---|
| The Lubrizol Corporation |
| Afton Chemical |
| BASF SE |
| TotalEnergies |
| Dorf Ketal |
| Innospec |
| Infineum International Ltd. |
| LyondellBasell Industries Holdings B.V. |
| Chevron Oronite Company |
| Others |
Value Chain & Pricing Dynamics
Ethanol substitution for aromatic octane boosters simultaneously redraws supply geography toward US Midwest and Brazilian cane belt production zones while compressing pricing premiums for fossil-derived alternatives. This chemistry shift concentrates procurement power among integrated biorefiners and fragments margin capture for traditional petrochemical pathways.
Pricing Analysis
Long-term offtake agreements dominate procurement between major fuel retailers and additive houses, locking in volume commitments that insulate against butane and isobutylene spot volatility. Price differentiation hinges on Top Tier certification status and renewable fuel standard credit eligibility, with California LCFS-qualified biobased isooctane commanding sustained premiums. Cost compression in aromatic-derived boosters is intensifying because REACH sunset dates accelerate substitution timelines. Mid-size independent blenders exhibit highest price sensitivity, lacking volume thresholds for direct manufacturer relationships that secure preferential contract terms.
Supply Chain Analysis
Strait of Hormuz transit underwrites naphtha feedstock flows to Asian aromatics producers, creating exposure that European and US blenders increasingly circumvent through domestic ethanol and biobased alkylate sourcing. Manufacturing concentrates in the United States, Brazil, and Germany, where fermentation infrastructure and refinery alkylation capacity anchor supply. Raw material flows draw from corn and sugarcane agricultural networks, C4 petrochemical streams, and natural gas liquids fractionation. Single-source vulnerability concentrates in biobased alkylate offtake agreements, where limited producers control premium-grade supply. Distribution runs through direct technical service teams at refinery headquarters, bypassing regional chemical distributors for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The octane improver market is exiting a regulatory-driven trough as engine downsizing cycles and LCFS credit price recovery restore formulation demand. Refinery upgrade timelines and automotive OEM calibration requirements provide cyclical visibility through the recovery phase.
For Market Incumbents: Fortify captive supply positions through backward integration into C4 precursor production or exclusive biobased alkylate offtake agreements. Deepen direct refinery relationships with embedded technical service teams that raise switching costs for additive procurement. Counter emerging biobased specialists by accelerating Top Tier certification capture at major retail chains before channel access tightens.
For New Entrants and Emerging Players: Differentiate on carbon-intensity scoring by securing agricultural residue feedstock contracts for renewable isooctane pathways that qualify for California LCFS premiums. Target the US Gulf Coast refinery segment, where alkylation unit retrofits create merchant demand for non-integrated high-purity octane sources. Pursue co-development agreements with automotive OEMs seeking warranty-compliant super-premium gasoline formulations for turbocharged powertrains.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty chemical platforms that consolidated detergent additive houses during the last decade. Five-to-ten year viability hinges on regulatory durability for renewable fuel mandates and the pace of electrification-driven gasoline demand erosion. Monitor LCFS credit price trajectories and state-level clean fuel program expansions as the primary inflection signal for biobased octane improver valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C4 Chemistry | BASF SE's captive isobutylene supply secures cost position for high-purity isooctane production. |
| Top Tier Certification Capture | Innospec's detergent-compatible formulations unlock placement at Chevron and Shell branded stations. |
| Biobased Alkylate Scale-Up | Renewable fermentation pathways from agricultural residues deliver LCFS credit eligibility for West Coast blenders. |
| Direct Refinery Relationship Expansion | Afton Chemical's embedded technical teams at Texas and California facilities raise competitor switching costs. |
| Alkylation Unit Retrofit Partnerships | US Gulf Coast facility upgrades expand merchant supply access for non-integrated gasoline blenders. |
Study Parameters
A spread of perspectives from refinery process engineers, fuel retailer procurement directors, automotive OEM calibration specialists, and additive house R&D chemists converged on the working assumptions for supply-demand balances. Primary fieldwork combined structured interviews with downstream blenders and upstream precursor producers, validated against customs data on isobutylene and ethanol trade flows, EPA fuel registration databases, and SEC filings from integrated chemical majors. Bottom-up treat rate modeling across gasoline pool specifications was triangulated with top-down refinery capacity utilization data.
Segmentation dimensions modeled span oxygenate versus aromatic chemistry pathways, fuel retailer versus automotive OEM procurement channels, and performance enhancement versus emission reduction application claims. CAGRs were derived from elasticity-adjusted demand projections across the analysis window, incorporating MIIT fuel quality standards in China, EPA Tier 3 sulfur benchmarks, and ECHA authorization timelines as regulatory velocity inputs. Price forecasting integrated LCFS credit market dynamics and renewable fuel standard mandate trajectories.
Forecasts assume regulatory continuity in EPA, CARB, and REACH regimes; material policy shifts would require re-modeling octane improver demand curves and substitution elasticities. Practitioners should keep alternative scenarios live as electrification penetration rates and biobased production cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
LAMEA Driveline Additives Market
Additives
Indonesia Feed Additives Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Iso-Butyric Acid Market
Additives
Global Coalescing Agent Market
Additives
Oxygen Scavengers Market
Additives
Additives for Metalworking Fluids Market
Additives
Fluid Loss Additives Market
Additives
Calcium Tartrate Market
Additives
Tackifier Market
Additives
Sodium Potassium Tartrate Market
Additives
Global Propyl Acetate Market
Additives
Canada Water Enhancer Market
Additives
Impact Modifier Market
Additives
Germany Sodium Reduction Ingredient Market
Additives
Paint Additives Market