
 Alkyl Ketene Dimers (AKD) Wax Market | 2026-2036
Alkyl Ketene Dimers (AKD) Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Alkyl Ketene Dimers (AKD) Wax Market Outlook
A shift from single-source to multi-source procurement is recalibrating how paper mills secure AKD wax supply. Kemira Oyj leverages its Nordic manufacturing base to sustain long-term contracts with European packaging producers. Solenis competes through integrated chemical service models that bundle AKD with process aids. BASF SE anchors its position via backward integration into fatty acid feedstocks, reducing raw material cost volatility.
Alkyl ketene dimers are waxy reactive sizing agents synthesized from fatty acid chlorides and tertiary amines, typically delivered as emulsions or solid pastilles with melting points between 45°C and 55°C. They hydrolyze on cellulose fibers to form beta-keto ester bonds that render paper and paperboard resistant to liquid penetration. Modified AKD variants command premium positioning due to enhanced emulsion stability and reduced cure times in high-speed paper machines. Solid AKD dominates volume flows for bulk integrated mills, while emulsified grades capture margin pools in specialty packaging applications requiring rapid on-machine sizing.
EPA effluent guidelines constrain AKD manufacturing discharge profiles in the United States, pushing producers toward closed-loop emulsion systems. REACH registration requirements in Europe mandate full toxicological dossiers for fatty acid chloride precursors, elevating compliance costs for importers. China's MEE enforces volatile organic compound limits on chemical processing facilities, favoring domestic producers with upgraded emission controls. Stakeholders must monitor how evolving bio-based content thresholds in EU packaging regulations reshape feedstock sourcing strategies for hydrogenated versus plant-derived AKD grades.
Market Dynamics
Paper mills are consolidating AKD wax procurement around multi-source supply frameworks to mitigate feedstock volatility and secure emulsion stability guarantees from specialty chemical distributors.
Growth Catalysts
- REACH registration mandates:Full toxicological dossiers for fatty acid chloride precursors in Europe are filtering out marginal importers and concentrating volume among compliant producers with established ECHA registrations.
- Packaging grade expansion:Specialty paperboard producers in India are specifying modified AKD variants with reduced cure times to match high-speed corrugator throughput requirements.
- Closed-loop emulsion systems:EPA effluent guidelines in the United States are pushing integrated mills toward captive emulsion production, expanding demand for solid pastille AKD over merchant emulsion supply.
Market Restraints
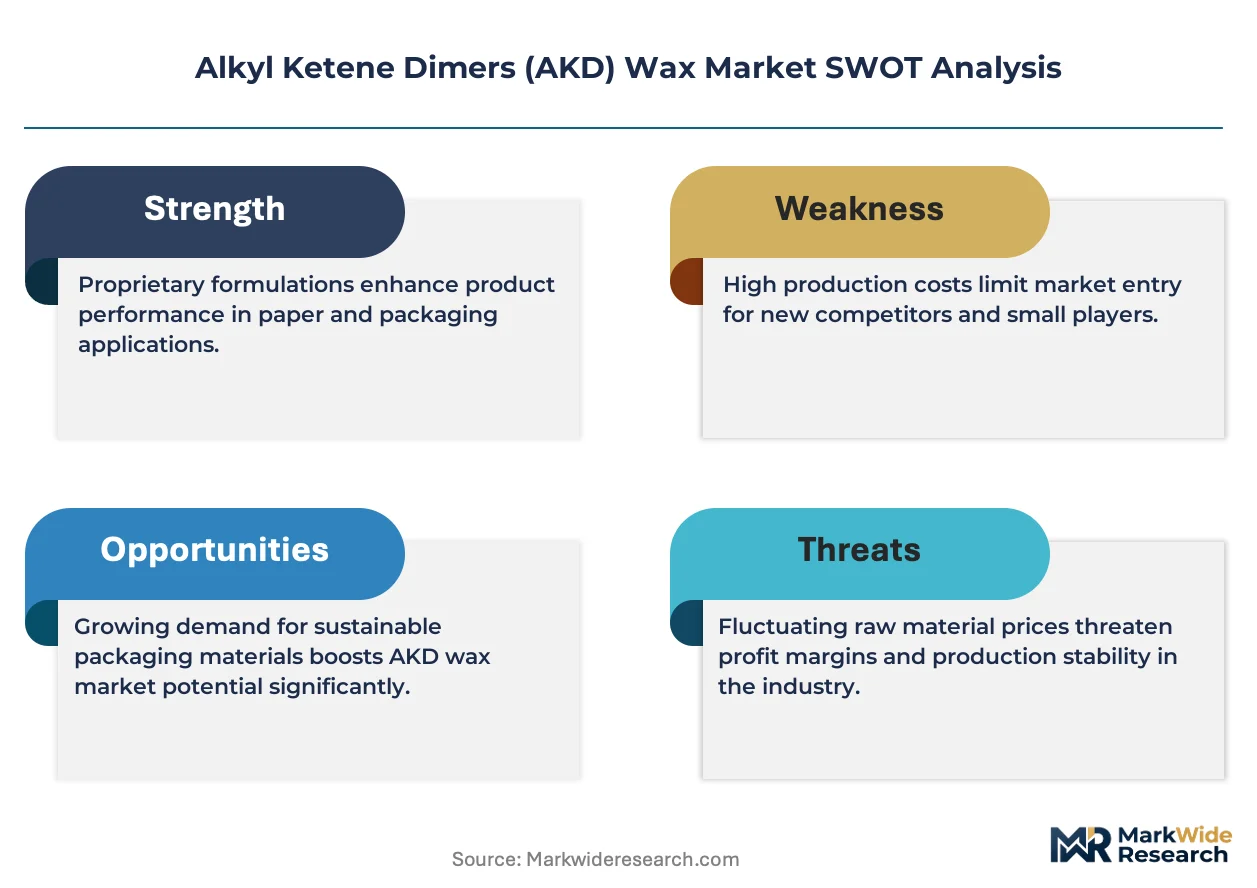
- Hydrogenated tallow feedstock volatility:Crude fat pricing swings and biofuel diversion of animal fats are compressing margins for AKD producers without backward integration into fatty acid supply.
- MEE emission enforcement:China's volatile organic compound limits on chemical processing facilities are raising capital requirements for domestic producers without upgraded scrubber and recovery systems.
- ASA substitution in alkaline sizing:Alkenyl succinic anhydride competes directly with AKD in certain packaging grades, particularly where rapid sizing development and lower cure sensitivity outweigh AKD's superior hydrophobicity.
Strategic Opportunities
- Bio-based content thresholds:EU packaging regulations are creating premium positioning for plant-derived AKD grades synthesized from palm or rapeseed fatty acids versus hydrogenated tallow variants.
- India's PLI scheme for paper:Production-linked incentives for domestic paper manufacturing are attracting AKD emulsion capacity investments to serve Maharashtra and Gujarat mill clusters.
- Digital print compatibility:Modified AKD chemistries with controlled surface energy are capturing demand from inkjet-treated packaging substrates requiring precise liquid interaction management.
Industry Challenges
- Emulsion stability expertise:Formulating AKD into shelf-stable, low-viscosity dispersions requires specialized colloid chemistry capabilities that paper mills struggle to develop in-house.
- Cure monitoring integration:High-speed machines demand real-time beta-keto ester bond verification systems that legacy paper machine control architectures cannot accommodate without substantial DCS upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkyl Ketene Dimers (AKD) Wax Market |
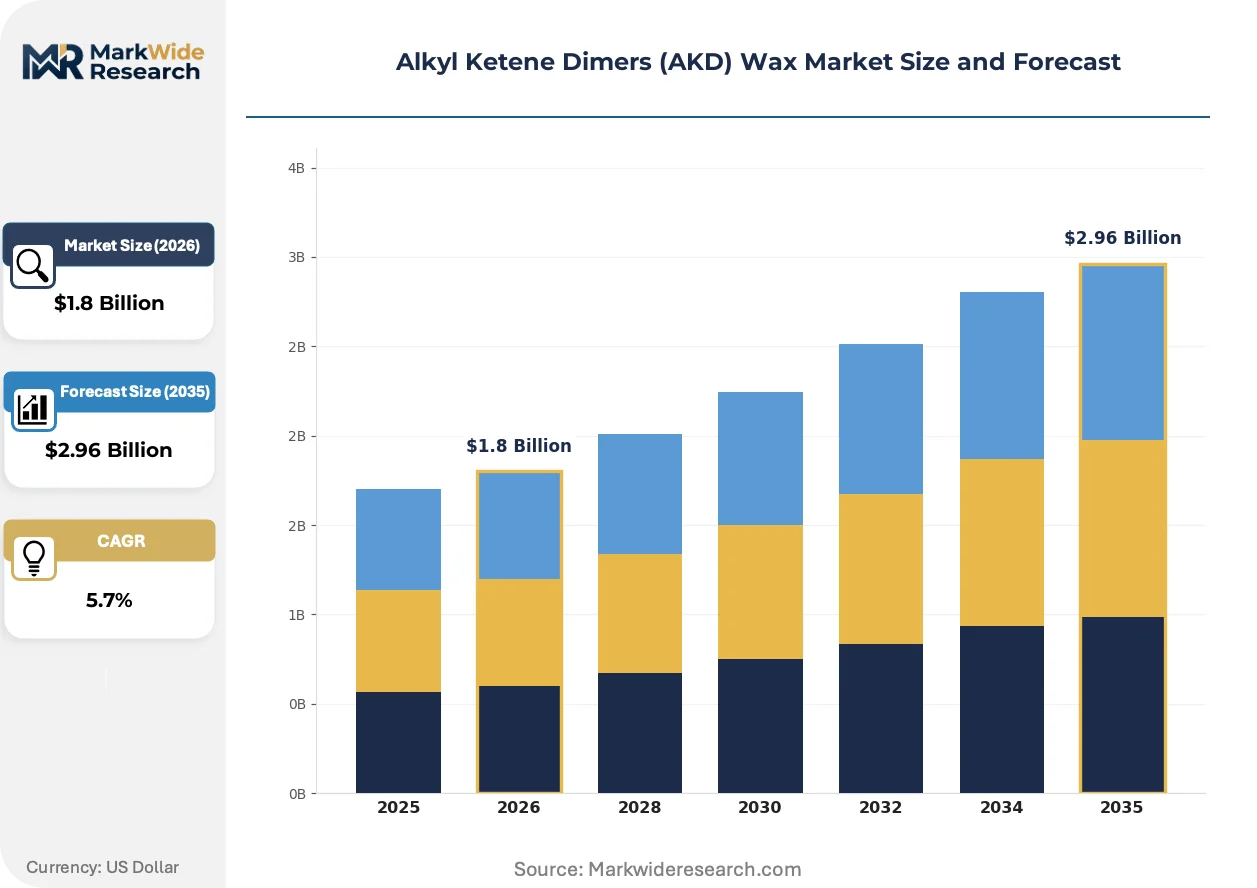
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified AKD, Hydrogenated AKD, Emulsified AKD, Solid AKD Application: Coatings, Paper & Packaging, Textiles, Adhesives End User: Packaging Industry, Textile Industry, Construction Sector, Automotive Sector Delivery Mode: Bulk Delivery, Bagged Delivery, Drummed Delivery, Customized Delivery |
| Companies Covered | SEIKO PMC, Aries Chemical, Inc., Solenis, GO YEN Chemical Industries Co., Ltd., Oleon NV, Kemira Oyj, Arakawa Chemical Industries, Amazon Chemicals Limited, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkyl Ketene Dimers (AKD) Wax Market Strategic Shifts
AKD wax chemistry is fragmenting into application-specific variants as paper mills reject universal sizing agents in favor of performance-optimized formulations tuned to exact machine speeds and end-use specifications.
Modified AKD emulsions incorporating cationic starch stabilizers are converging with high-speed packaging paper production in China and India. Integrated mills running above 1,500 meters per minute are adopting these variants to compress cure times from hours to minutes. This convergence is displacing conventional unmodified AKD in volume applications where machine efficiency penalties outweigh raw material cost savings.
China's MEE enforcement of GB 31572 standards for volatile organic compound emissions is forcing AKD manufacturers to install thermal oxidizers and solvent recovery systems. Producers in Shandong and Jiangsu provinces are consolidating around facilities with captive hydrogenation capacity to control both emission profiles and feedstock quality. The regulatory pressure is accelerating technical obsolescence of batch-process AKD plants lacking continuous reactor technology.
Buyer concentration among multinational packaging groups is compressing supplier rosters and extending contract durations. Paper mills in Germany and Finland are negotiating three-to-five-year AKD supply agreements with fixed-volume tiers and indexed pricing mechanisms. This shift toward consolidated procurement with performance guarantees is marginalizing smaller emulsion blenders lacking technical service depth or multi-site supply capability.
Alkyl Ketene Dimers (AKD) Wax Market Segmentation
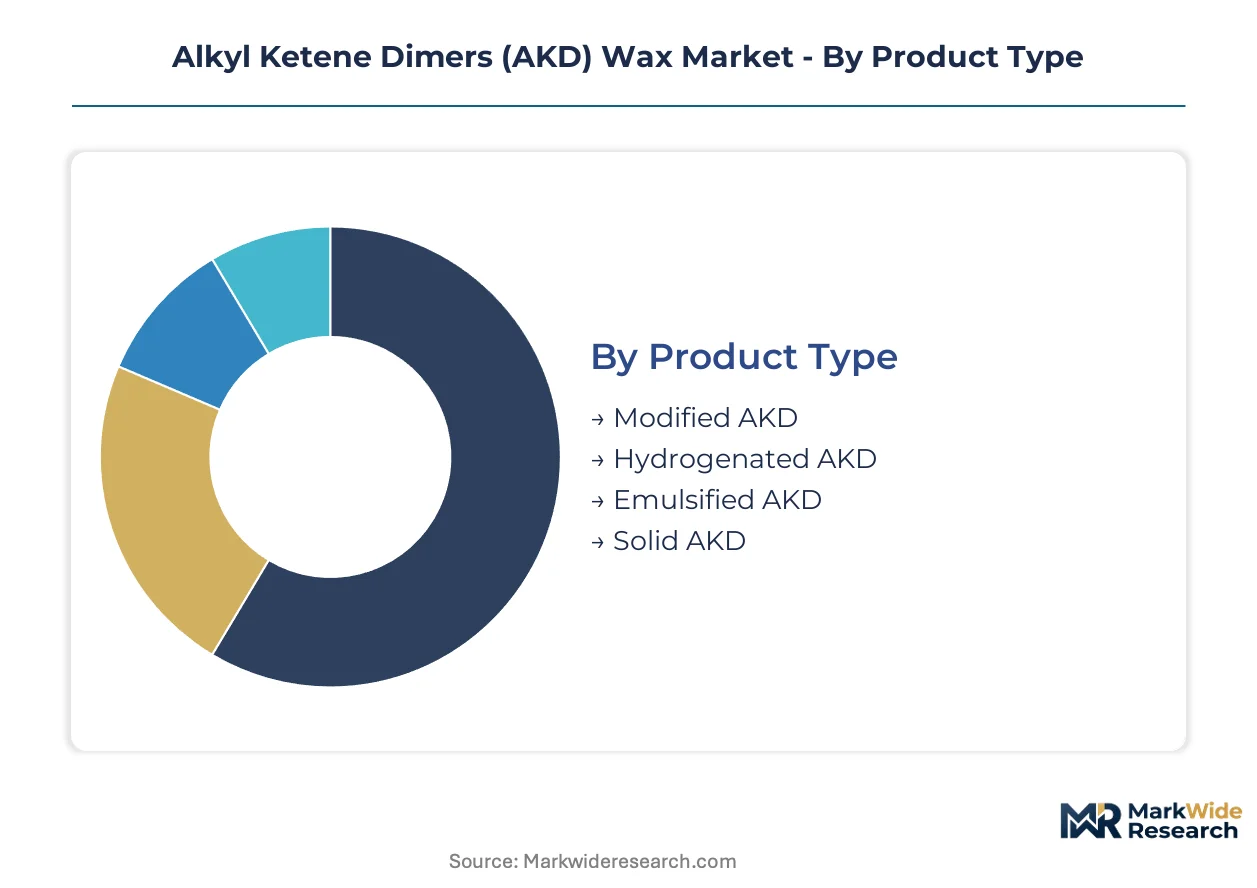
AKD wax procurement patterns diverge sharply across product grades and delivery modes, with integrated mills favoring solid pastilles while specialty converters demand emulsion stability guarantees. Understanding these segment boundaries clarifies where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
Supply concentration among Nordic and German producers favors modified and hydrogenated grades with captive fatty acid hydrogenation capacity.
- Modified AKD:Cationic starch-stabilized emulsions engineered for reduced cure times below 15 minutes. Demand concentrates in Chinese and Indian packaging paper mills running corrugators above 1,500 meters per minute, where machine efficiency penalties from extended curing outweigh raw material premiums.
- Hydrogenated AKD:Saturated alkyl chains from tallow or palm fatty acid feedstocks deliver superior hydrophobicity and oxidation resistance. European producers leverage backward integration into hydrogenation assets to secure long-term contracts with German and Finnish packaging groups seeking supply security.
- Emulsified AKD:Ready-to-use aqueous dispersions with 15-30% active content for mills lacking captive emulsion capacity.
- Solid AKD:Waxy pastilles with 45-55°C melting points shipped in bulk to integrated mills with in-house dispersion systems.
Today's leader: Modified AKD. Tomorrow's challenger: Hydrogenated AKD.
Application:
Cost tier differentiation separates commodity paper sizing from specialty coating applications requiring precise surface energy control.
- Paper & Packaging:Internal sizing of linerboard, corrugated medium, and folding boxboard to achieve Cobb values below 25 g/m². Demand clusters in Maharashtra and Gujarat mill clusters benefiting from India's PLI scheme for domestic paper manufacturing.
- Coatings:Surface sizing and barrier coatings for food-contact paperboard requiring controlled liquid interaction. Modified AKD chemistries with tuned surface energy capture demand from inkjet-treated packaging substrates where print quality depends on precise wettability management.
- Textiles:Water-repellent finishing for technical fabrics and nonwoven applications.
- Adhesives:Hydrophobic additive in hot-melt and pressure-sensitive formulations.
Paper & Packaging commands volume dominance. Coatings deliver the steepest expansion trajectory.
End User:
Customer type fragmentation creates divergent procurement patterns between multinational packaging groups and fragmented textile converters.
- Packaging Industry:Corrugated box manufacturers and folding carton producers specifying AKD for liquid resistance in beverage and food applications. Buyer concentration among European multinational groups compresses supplier rosters toward three-to-five-year contracts with indexed pricing.
- Textile Industry:Technical fabric mills applying AKD for durable water repellency in automotive and industrial applications.
- Construction Sector:Gypsum board and building paper manufacturers requiring moisture resistance.
- Automotive Sector:Interior trim and filtration media producers.
Packaging Industry anchors current procurement volumes. Textile Industry represents the fastest-climbing alternative demand pool.
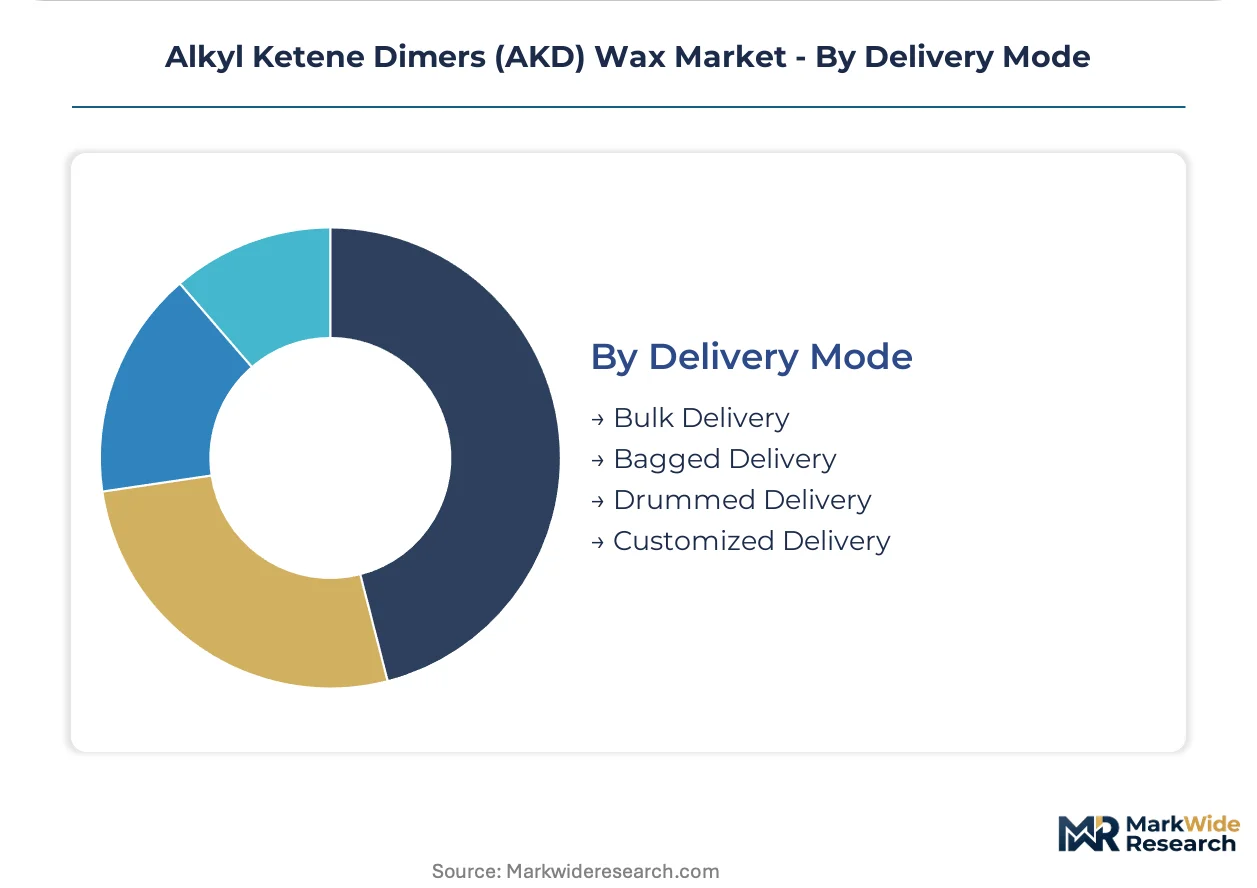
Delivery Mode:
Volume scale and supply chain proximity determine whether mills accept bulk tanker delivery or require packaged flexibility.
- Bulk Delivery:Heated tanker trucks and rail cars delivering molten AKD direct to mill storage tanks. Integrated mills with captive emulsion capacity in Shandong and Jiangsu provinces favor this mode to minimize handling costs and thermal degradation.
- Bagged Delivery:25kg polyethylene-lined bags for smaller mills and intermittent users.
- Drummed Delivery:200kg steel drums for specialty chemical distributors serving fragmented converter markets.
- Customized Delivery:Temperature-controlled logistics with just-in-time scheduling for high-speed machines with minimal inventory buffers.
Bulk Delivery dominates tonnage flows. Customized Delivery captures premium margins from just-in-time packaging lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province's integrated mill clusters dominate AKD wax consumption, with Chinese producers installing thermal oxidizers to meet MEE emission standards while expanding captive emulsion capacity for high-speed packaging lines.
China
Packaging paper mills in Shandong and Jiangsu provinces drive AKD demand for corrugator speeds exceeding 1,500 meters per minute. MEE enforcement of GB 31572 VOC limits forces manufacturers to install continuous reactor technology and solvent recovery systems. Domestic producers with captive hydrogenation capacity in these coastal provinces are consolidating market position as batch-process plants face technical obsolescence.
United States
Integrated paper mills in Wisconsin and the Southeast are shifting toward solid pastille procurement for captive emulsion production. EPA effluent guidelines constrain manufacturing discharge profiles, pushing producers toward closed-loop systems. Bulk delivery infrastructure around the Great Lakes and Gulf Coast supports direct molten AKD supply to major packaging producers seeking supply security.
Germany
REACH registration requirements for fatty acid chloride precursors filter out marginal importers and concentrate volume among ECHA-compliant producers. Packaging groups in Bavaria and North Rhine-Westphalia negotiate three-to-five-year supply agreements with indexed pricing. Nordic producers leverage proximity to serve these mills with hydrogenated grades featuring backward-integrated feedstock control.
India
Maharashtra and Gujarat mill clusters benefit from PLI scheme incentives for domestic paper manufacturing, attracting AKD emulsion capacity investments. Specialty paperboard producers specify modified AKD variants with sub-15-minute cure times to match high-speed corrugator throughput. Local distributors are expanding technical service capabilities to support fragmented converter markets.
Japan
Precision packaging applications in the Kanto and Kansai regions demand modified AKD chemistries with controlled surface energy for inkjet-treated substrates. METI industrial standards emphasize emission control and process efficiency, favoring suppliers with integrated quality management systems. Domestic chemical producers maintain strong positions in specialty grades requiring rapid on-machine sizing development.
Alkyl Ketene Dimers (AKD) Wax Market Competitive Environment
Global majors compete with regional champions across emulsion technology and feedstock integration, producing a tiered structure where Nordic and German producers anchor premium positioning through hydrogenation assets while Asian specialists capture volume in high-growth packaging corridors. Three archetypes dominate: integrated chemical conglomerates with backward feedstock control, specialty emulsion blenders with technical service depth, and regional distributors bridging fragmented mill networks. Competitive moves concentrate on multi-year contract extensions with performance guarantees and geographic expansion into India and Southeast Asia.
Among the integrated chemical majors, BASF SE exemplifies the feedstock-integrated archetype through its position in fatty acid chemistry, while Kemira Oyj anchors the Nordic supply corridor with long-term European packaging relationships. Solenis occupies a distinctive position bundling AKD with process aid portfolios, representing the service-integrated model that competes through technical partnership rather than commodity supply.
| Leading Market Players |
|---|
| SEIKO PMC |
| Aries Chemical, Inc. |
| Solenis |
| GO YEN Chemical Industries Co., Ltd. |
| Oleon NV |
| Kemira Oyj |
| Arakawa Chemical Industries |
| Amazon Chemicals Limited |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Multi-source procurement mandates from European packaging groups are forcing AKD wax suppliers to absorb feedstock volatility through indexed contract mechanisms, compressing margins for non-integrated producers while rewarding those with captive hydrogenation assets.
Pricing Analysis
Fatty acid chloride feedstock costs pass through directly to AKD wax pricing, with hydrogenated tallow volatility creating margin compression for distributors lacking backward integration. Three-tier pricing structure across modified premium grades, standard hydrogenated variants, and economy solid pastilles reflects cure-time performance and emulsion stability guarantees. Pricing pressure stems from crude fat diversion to biofuel markets, tightening supply for tallow-derived inputs. Specialty packaging mills in Germany and Finland show lowest price sensitivity due to multi-year contract security requirements, while fragmented Indian converters drive hardest bargain on spot emulsion purchases.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke delivery patterns for molten AKD bulk shipments. Supply concentrates in Germany, China, and Finland, with Shandong province mills drawing from domestic hydrogenation capacity to minimize tariff exposure. Fatty acid feedstocks rest on tallow, palm, and rapeseed oil dependencies, with biofuel competition creating structural supply risk. Distribution runs through heated tanker networks for integrated mills, while specialty distributors serve fragmented converters via temperature-controlled drum logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AKD wax procurement presents a geographic-arbitrage opportunity: India's PLI scheme offers cost-advantaged emulsion production against REACH compliance burdens elevating European manufacturing costs.
For Market Incumbents: Cement market position through captive hydrogenation capacity additions in Shandong and Jiangsu provinces, where MEE emission standards are filtering out batch-process competitors. Extend technical service depth to secure three-to-five-year indexed contracts with German packaging groups, insulating against ASA substitution threats in alkaline sizing applications. For New Entrants and Emerging Players: Begin with modified AKD emulsion production targeting Maharashtra and Gujarat mill clusters, where PLI incentives are attracting packaging capacity and local technical service gaps persist. Penetrate through distributor partnerships offering just-in-time delivery guarantees that incumbent multinational suppliers struggle to match at comparable cost. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap emulsion blenders possessing regional logistics networks and pending ECHA registrations, positioned for acquisition by feedstock-integrated majors seeking European market access. Watch for MEE enforcement intensity in Shandong as inflection signal for Chinese producer consolidation pace.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Acid Hydrogenation | Captive feedstock control insulates BASF and Kemira from tallow price volatility. |
| Modified AKD Emulsion Capacity Expansion | Sub-15-minute cure variants capture premium positioning in Chinese high-speed packaging corridors. |
| Long-term Supply Agreement Extension | Three-to-five-year indexed contracts with Finnish packaging groups lock in volume security. |
| Green Manufacturing Transition | Plant-derived AKD grades from palm and rapeseed feedstocks align with EU packaging bio-content thresholds. |
| Joint Venture for Regional Distribution | Local partnerships in Maharashtra bridge technical service gaps for fragmented Indian converter markets. |
Study Parameters
Coverage spans China, Germany, India, and the United States, with primary inputs from each market triangulated against secondary validation. Interviews with paper mill procurement directors, specialty chemical distributors, AKD plant managers, and technical R&D heads combined with customs trade data, SEC filings from integrated chemical majors, MEE emission compliance records, and ECHA registration databases. Bottom-up volume estimates from mill consumption patterns and top-down producer capacity assessments were cross-referenced for convergence.
Rate-of-change decomposition across the analysis window separated volume growth from price trajectory components. Segmentation dimensions modeled include product grade tier, end-use application, delivery mode, and regional production hub clustering. CAGRs were derived from producer shipment data and downstream demand forecasting, with specific inputs from corrugator speed evolution in Asian packaging mills and REACH registration timelines affecting European import capacity.
Several conditions sit outside the modeled scope, including potential ASA substitution acceleration, abrupt biofuel policy shifts affecting tallow availability, and unanticipated MEE enforcement intensity variations. Forecasts reflect documented assumptions around PLI scheme continuation and emission standard implementation pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Polyols and Sorbitols Products Market
Additives
Rheological Additives Market
Additives
Global Feed Acidifiers Market
Additives
Global Carboxylic Acids Based Esters Market
Additives
United Kingdom Sodium Reduction Ingredient Market
Additives
Saudi Arabia Feed Additives Market
Additives
Enzyme Stabilizer Market
Additives
Rosin Ester Market
Additives
Global Chelated Trace Minerals Market
Additives
Silicone Additives Market
Additives
Plasticizers Market
Additives
Global Acidulants Market
Additives
Metal Deactivators Market
Additives
Chitosan Powder Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Conditioning Agent Market