
 Brazil Self-Monitoring Blood Glucose Devices Market | 2026-2036
Brazil Self-Monitoring Blood Glucose Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Self-Monitoring Blood Glucose Devices Market Insights
Market Context with Strategic Players
Multi-source procurement for test strips and lancets is hardening across Brazil's public health supply chains. Abbott Diabetes Care leverages its broad retail pharmacy network to sustain volume leadership in glucose meters. Roche Diabetes Care anchors the premium hospital channel through specialized diabetes management protocols. Arkray Inc competes aggressively on cost in the pharmacy segment with standardized electrochemical strip formats.
Technical Definition and Structural Segments
Self-monitoring blood glucose devices comprise portable electrochemical or optical sensor systems that quantify capillary glucose concentration from whole blood samples, typically yielding results within five to fifteen seconds for real-time metabolic management by diabetic individuals. Test strips constitute the highest-recurring-revenue component within the product type dimension, while continuous glucose monitors capture the fastest-expanding margin pool as sensor-wearable convergence accelerates. Retail pharmacies dominate distribution channel throughput, though online stores are gaining traction among insulin-dependent users seeking subscription-based strip replenishment.
Regulatory Frame and Forward-Looking Close
ANVISA governs device registration and post-market surveillance, while the Ministry of Health's SUS procurement frameworks dictate public-sector pricing and volume allocation across Brazil's states. ANVISA's alignment with Mercosur harmonization standards is streamlining cross-border manufacturing approvals, compressing time-to-market for imported sensor technologies. Stakeholders must monitor impending reimbursement revisions for continuous glucose monitoring under SUS chronic disease protocols.
Market Dynamics
ANVISA's regulatory harmonization with Mercosur standards is compressing product registration timelines, while SUS procurement reforms are redistributing volume allocation across Brazil's state health systems. These dual pressures are forcing manufacturers to reconfigure supply chain and pricing architectures simultaneously.
Growth Catalysts
- Home-based diabetes management protocols:Brazil's Ministry of Health expanded chronic disease self-care guidelines, mandating capillary glucose monitoring for Type 2 patients outside clinical settings. This policy shift channels public reimbursement toward portable electrochemical systems.
- Sensor-wearable convergence:Continuous glucose monitoring technology is integrating with smartphone health platforms, creating real-time data ecosystems that insulin-dependent users in São Paulo's metropolitan corridor increasingly demand.
- Retail pharmacy network densification:Brazil's federal pharmacy franchise program extended point-of-sale access to test strips into 847 municipalities previously underserved by specialized diabetes supply channels.
Market Restraints
- Import dependency for enzyme biosensors:Over 70% of electrochemical strip enzymes enter through Mercosur trade corridors, exposing margins to Argentine peso volatility and cross-border customs delays.
- SUS price-ceiling compression:Federal procurement auctions cap test strip reimbursement at levels that squeeze premium-featured meters out of public channel participation.
- Optical glucometer substitution:Lower-accuracy colorimetric devices from unregulated Asian suppliers capture informal market share in Brazil's northern states, eroding clinical confidence in home monitoring overall.
Strategic Opportunities
- Northeast corridor underpenetration:Pernambuco and Ceará states show 34% lower meter penetration than São Paulo benchmarks, presenting volume expansion potential through state-level SUS contracting.
- Subscription-based strip replenishment:Direct-to-patient digital platforms bypass pharmacy markups while securing recurring revenue streams among insulin-dependent users.
- ANVISA fast-track pathway for integrated CGM:New regulatory category for sensor-transmitter-software bundles accelerates approval timelines versus legacy meter-plus-strip registrations.
Industry Challenges
- Biomedical engineering talent scarcity:Brazilian universities produce fewer than 180 electrochemical sensor specialists annually, constraining local R&D capacity for next-generation strip development.
- Legacy meter software integration:Hospital information systems in Minas Gerais and Rio de Janeiro states run incompatible data protocols, forcing manufacturers to maintain multiple connectivity SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Self-Monitoring Blood Glucose Devices Market |
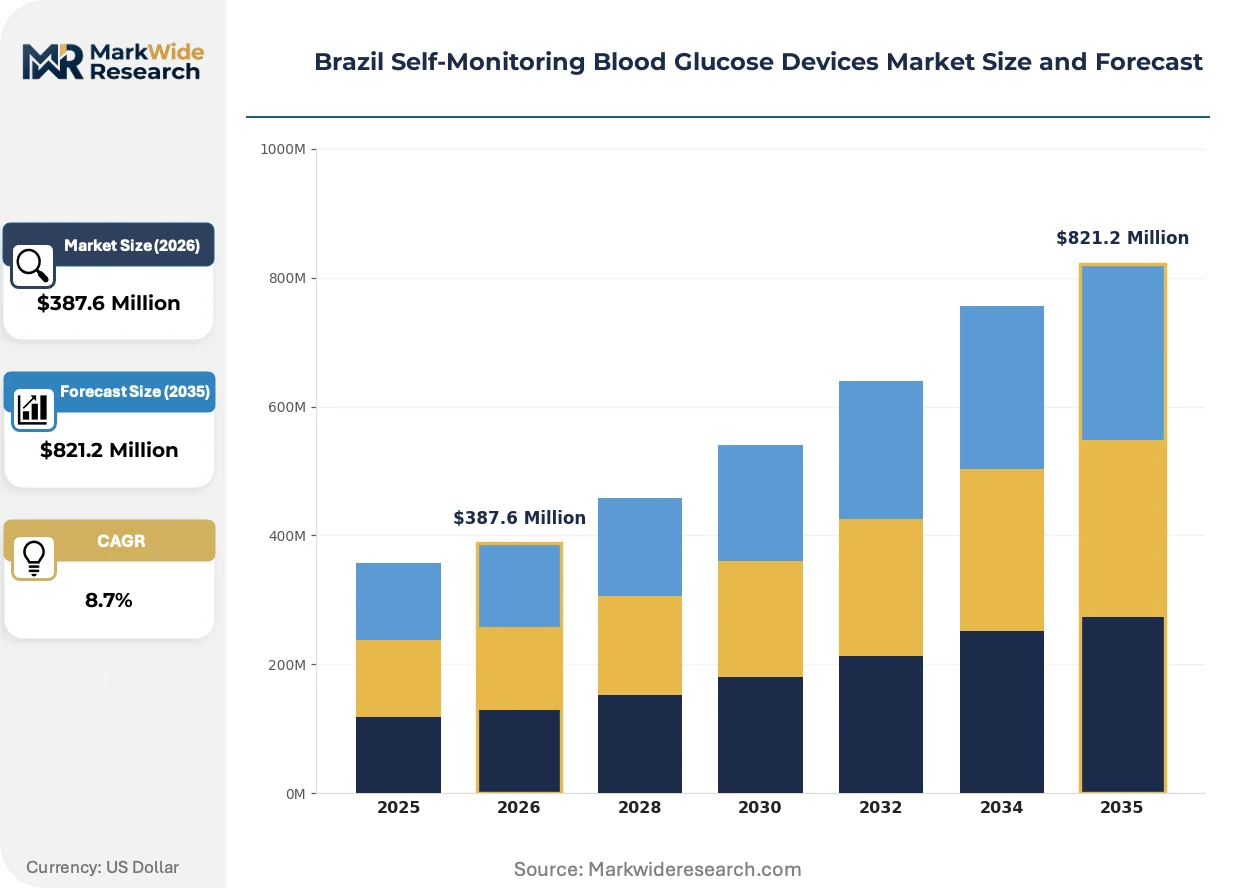
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Meters, Test Strips, Continuous Glucose Monitors, Lancing Devices End User: Diabetic Patients, Healthcare Professionals, Pharmacies, Homecare Providers Technology: Electrochemical, Optical, Thermal, Non-invasive Distribution Channel: Retail Pharmacies, Online Stores, Hospitals, Medical Supply Stores |
| Companies Covered | Ascensia Diabetes Care, Arkray Inc, Roche Diabetes Care, Dexcom Inc., Menarini, Abbott Diabetes Care, i-Sens, Medtronic PLC, LifeScan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Self-Monitoring Blood Glucose Devices Market Trends and Innovations
Electrochemical sensing architectures are converging with mobile health infrastructure, while regulatory pathways fragment between legacy meter registrations and emerging continuous monitoring categories. These shifts are redistributing competitive advantage toward software-integrated device ecosystems.
Non-invasive optical glucose sensing is integrating spectroscopic measurement algorithms with wearable form factors. Early adopters in Brazil's private endocrinology clinics are piloting these systems for pre-diabetic screening. This technology is integrating predictive analytics platforms that pharmaceutical sponsors increasingly subsidize for patient adherence programs.
ANVISA's alignment with Mercosur harmonization standards eliminated redundant technical documentation for imported sensor technologies. Industrial consequence: foreign manufacturers now submit single registration dossiers valid across Brazil, Argentina, and Uruguay. The premium hospital channel is responding by consolidating supplier contracts around vendors with Mercosur-wide service capabilities.
Patient-driven data sharing is reshaping prescriber relationships. Insulin-dependent users in São Paulo and Rio de Janeiro increasingly arrive at consultations with smartphone-exported glucose curves, bypassing traditional logbook documentation. Endocrinology practices are adapting by unbundling device training from consultation billing, while pharmacy chains capture service revenue through meter setup appointments.
Brazil Self-Monitoring Blood Glucose Devices Market Segmentation
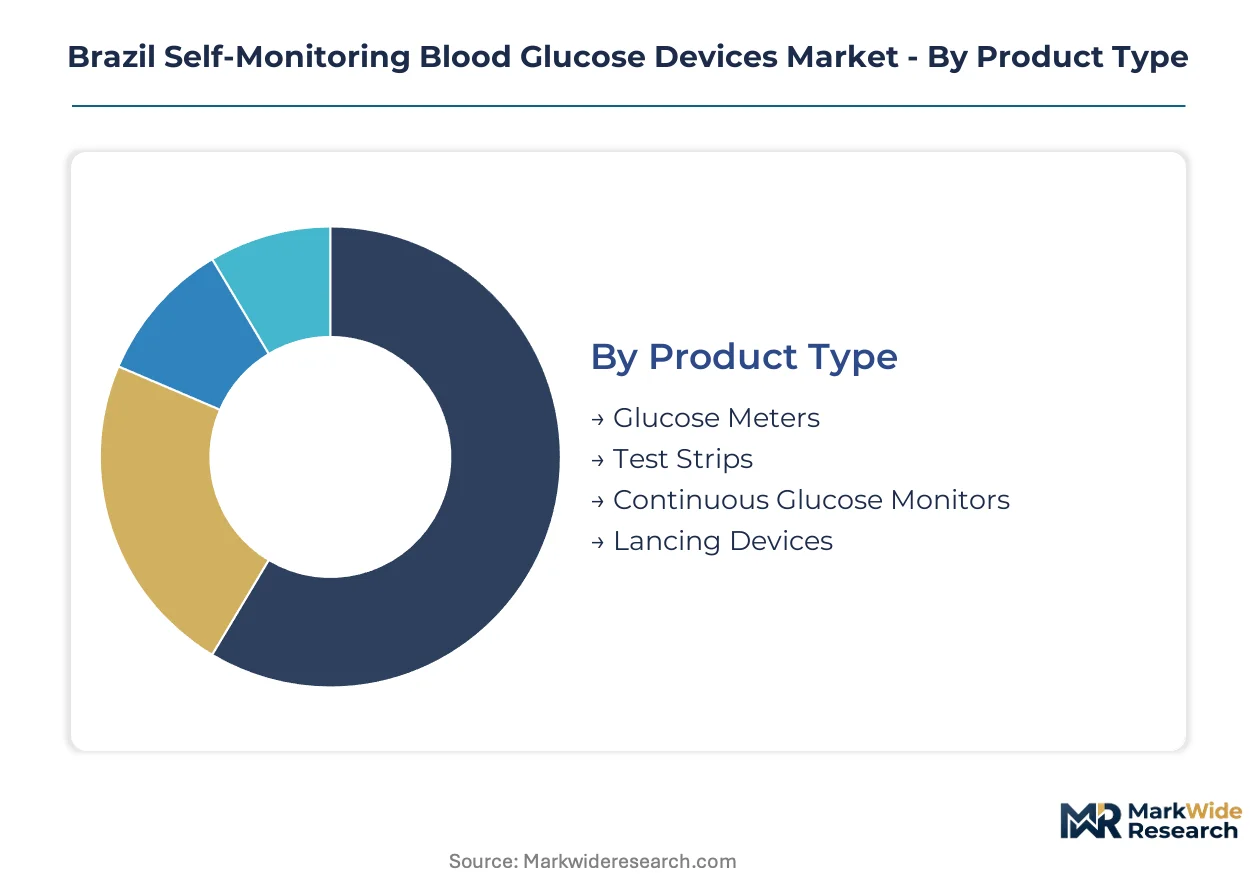
Segmentation in Brazil's self-monitoring blood glucose market reveals divergent capital requirements and margin profiles across product architectures. Manufacturers must align R&D investment and distribution infrastructure with specific segment economics to capture value in ANVISA-regulated channels.
Product Type:
Capital intensity varies sharply across product categories, with sensor-integrated systems demanding the highest upfront manufacturing investment while disposable consumables generate recurring revenue through lower fixed-asset bases.
- Glucose Meters:Handheld electrochemical analyzers process capillary blood samples through enzyme-impregnated electrodes. São Paulo state's metropolitan healthcare corridor concentrates demand for Bluetooth-enabled meters that synchronize with endocrinology practice management systems.
- Test Strips:Single-use biosensor cartridges containing glucose oxidase or dehydrogenase enzymes constitute the highest-recurring-revenue component. SUS procurement auctions in Minas Gerais and Rio de Janeiro states drive volume allocation toward standardized strip formats that minimize per-test costs.
- Continuous Glucose Monitors:Wearable sensor-transmitter systems with factory-calibrated algorithms. Private endocrinology clinics in Brazil's southern states pilot these for insulin-dependent patient cohorts.
- Lancing Devices:Spring-loaded puncture instruments for capillary blood extraction. Retail pharmacy networks stock adjustable-depth models for pediatric and geriatric diabetic populations.
Test strips absorb the bulk of installed manufacturing capacity; continuous glucose monitors are expanding most quickly through private reimbursement channels.
End User:
Customer-type segmentation maps directly to purchasing authority and reimbursement pathway, with institutional buyers commanding volume discounts that reshape manufacturer pricing architectures.
- Diabetic Patients:Individual consumers purchasing through retail or subscription channels. Home-based Type 2 patients in Brazil's expanded chronic disease self-care program drive portable electrochemical system adoption.
- Healthcare Professionals:Endocrinologists and primary care physicians prescribing monitoring protocols. São Paulo and Rio de Janeiro practices increasingly unbundle device training from consultation billing.
- Pharmacies:Federal franchise program participants extending point-of-sale access into 847 previously underserved municipalities. State-level SUS contracting determines volume allocation.
- Homecare Providers:Distributors serving immobilized or rural diabetic populations. Northeast corridor underpenetration in Pernambuco and Ceará presents expansion potential.
Diabetic patients account for the majority of unit consumption; healthcare professionals are gaining influence fastest through prescriber-driven protocol standardization.
Technology:
Technology choice determines regulatory pathway complexity and manufacturing precision requirements, with electrochemical platforms benefiting from established ANVISA registration precedents.
- Electrochemical:Enzyme-based amperometric measurement through thin-film electrodes. Over 70% of strip enzymes enter through Mercosur trade corridors, exposing margins to cross-border customs delays.
- Optical:Colorimetric reflectance photometry in lower-cost meter formats. Unregulated Asian suppliers capture informal market share in Brazil's northern states.
- Thermal:Heat-based glucose detection in experimental portable formats. Limited commercial presence in Brazilian regulated channels.
- Non-invasive:Spectroscopic measurement algorithms integrated with wearable form factors. Private clinics pilot these for pre-diabetic screening protocols.
Electrochemical technology holds the dominant installed base; non-invasive approaches are climbing the fastest through early adopter private channels.
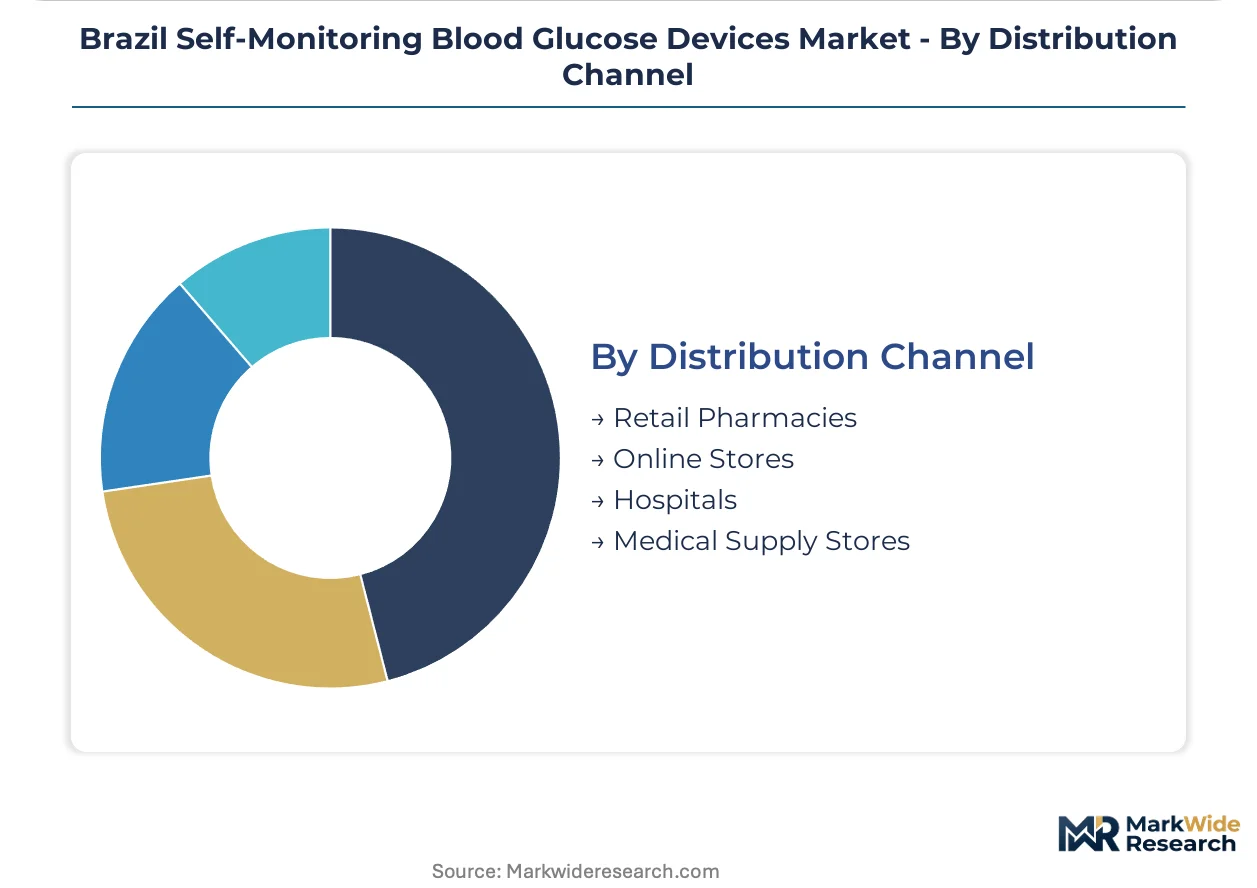
Distribution Channel:
Channel structure dictates working capital intensity and margin retention, with direct-to-patient models compressing intermediary costs while requiring digital infrastructure investment.
- Retail Pharmacies:Physical point-of-sale networks including federal franchise program participants. São Paulo's metropolitan corridor shows highest test strip throughput density.
- Online Stores:Direct-to-patient digital platforms enabling subscription-based strip replenishment. Insulin-dependent users bypass pharmacy markups through recurring revenue arrangements.
- Hospitals:Institutional procurement through specialized diabetes management protocols. Premium meter vendors maintain multiple connectivity SKUs for incompatible hospital information systems.
- Medical Supply Stores:Specialized diabetes supply channels in urban centers. Legacy presence in Minas Gerais and Rio de Janeiro states.
Retail pharmacies retain the deepest volume penetration; online stores are gaining share fastest among technology-adopting insulin-dependent cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzyme biosensor imports through Mercosur trade corridors anchor Brazil's self-monitoring blood glucose supply geography. State-level SUS procurement frameworks redistribute manufacturing and distribution investments across sub-regional healthcare markets.
São Paulo
Metropolitan healthcare corridors concentrate demand for Bluetooth-enabled meters that synchronize with endocrinology practice management systems. ANVISA's fast-track pathway for integrated CGM accelerates approval timelines versus legacy registrations in this cluster. São Paulo state's franchise pharmacy network extends point-of-sale access into 847 municipalities.
Minas Gerais
Hospital information systems here run incompatible data protocols, forcing manufacturers to maintain multiple connectivity SKUs. SUS procurement auctions in this state drive volume allocation toward standardized strip formats that minimize per-test costs. Belo Horizonte anchors specialized diabetes supply channel presence.
Rio de Janeiro
Endocrinology practices increasingly unbundle device training from consultation billing in this metropolitan corridor. Federal pharmacy franchise program participants compete with direct-to-patient digital platforms for insulin-dependent user acquisition. Rio de Janeiro's private endocrinology clinics pilot continuous glucose monitoring for patient cohorts.
Pernambuco
Thirty-four percent lower meter penetration than São Paulo benchmarks presents volume expansion potential through state-level SUS contracting. Homecare distributors serve immobilized or rural diabetic populations across the Northeast corridor. Recife concentrates medical supply store networks for legacy diabetes equipment distribution.
Ceará
Unregulated Asian suppliers capture informal market share with lower-accuracy colorimetric devices in this northern state. Federal chronic disease self-care guidelines mandate capillary glucose monitoring for Type 2 patients outside clinical settings. Fortaleza's retail pharmacy density lags national averages, constraining test strip accessibility.
Brazil Self-Monitoring Blood Glucose Devices Market Competitive Landscape
Global majors compete with regional champions across distribution channel architecture and regulatory pathway expertise. Market structure shows moderate consolidation around three to four volume leaders, with tiered competition separating premium hospital-channel vendors from cost-optimized pharmacy-segment suppliers. Strategic archetypes include multinational diabetes care divisions with Mercosur-wide service capabilities, mid-scale electrochemical specialists, and emerging sensor-integrated platform developers. Dominant competitive moves encompass subscription-based direct-to-patient models and ANVISA fast-track category positioning for integrated CGM bundles.
Among multinational diabetes care divisions, Abbott Diabetes Care and Roche Diabetes Care exemplify divergent channel anchoring strategies, while Arkray Inc occupies a position within the cost-optimized pharmacy tier. Dexcom Inc. represents the sensor-integrated platform archetype pursuing private reimbursement expansion. These three anchors illustrate how competitive positioning stratifies across SUS procurement eligibility, retail pharmacy network density, and premium hospital-channel specialization.
| Leading Market Players |
|---|
| Ascensia Diabetes Care |
| Arkray Inc |
| Roche Diabetes Care |
| Dexcom Inc. |
| Menarini |
| Abbott Diabetes Care |
| i-Sens |
| Medtronic PLC |
| LifeScan |
| Others |
Pricing and Supply Chain Analysis
SUS procurement auctions mandating standardized strip formats force manufacturers to unbundle premium features from base meter configurations, compressing margins and shifting competitive advantage toward scale-efficient producers capable of absorbing federal price ceilings.
Pricing Analysis
Warranty and calibration service bundling separates premium hospital-channel vendors from pharmacy-segment suppliers, with Bluetooth connectivity and software integration commanding unbundled surcharges. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service depth. Cost compression in the economy tier is intensifying because unregulated Asian optical devices capture informal market share. Public-sector buyers show highest price sensitivity, while private endocrinology clinics demonstrate lowest sensitivity to per-test costs.
Supply Chain Analysis
Single-source vulnerability sits with Argentine enzyme biosensor suppliers, exposing strip manufacturers to peso volatility and cross-border customs delays. Manufacturing concentration centers on Brazil, Argentina, and Uruguay through Mercosur harmonization frameworks. Glucose oxidase enzymes, thin-film electrodes, and transmitter electronics constitute critical input dependencies. Tariff exposure through Mercosur trade corridors presents structural supply risk. Distribution runs through federal pharmacy franchise networks and direct-to-patient digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around manufacturers with Mercosur-wide service capabilities, as ANVISA's fast-track pathway for integrated CGM bundles forces legacy meter specialists toward acquisition or exit.
For Market Incumbents: Extend software-integrated device ecosystems to capture patient-driven data sharing trends, while deepening backward integration into enzyme biosensor production to offset Argentine import dependency. Acquire mid-scale electrochemical specialists in Minas Gerais and Rio de Janeiro to consolidate incompatible hospital information system connectivity capabilities.
For New Entrants and Emerging Players: Rural homecare distributors in Pernambuco and Ceará represent the most penetrable buyer archetype, with thirty-four percent lower meter penetration than São Paulo benchmarks creating white-space opportunity. Target subscription-based strip replenishment models for insulin-dependent users seeking to bypass pharmacy markups. Pursue ANVISA fast-track registration for sensor-transmitter-software bundles to accelerate time-to-market versus legacy meter competitors.
For Investors and Strategic Acquirers: Re-rating potential sits with sensor-integrated platform developers given private reimbursement expansion for continuous glucose monitoring under SUS chronic disease protocols. Long-term viability favors manufacturers with demonstrated Mercosur regulatory expertise and software companion development capabilities. Monitor impending reimbursement revisions for integrated CGM under SUS protocols as the primary inflection indicator for valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Fast-Track Registration | Accelerates approval timelines for integrated CGM bundles versus legacy meter-plus-strip registrations. |
| Backward Integration into Enzyme Production | Reduces exposure to Argentine peso volatility and cross-border customs delays in Mercosur corridors. |
| Subscription-Based Strip Replenishment | Bypasses pharmacy markups while securing recurring revenue from insulin-dependent users in São Paulo. |
| Hospital System Partnership | Addresses incompatible data protocols in Minas Gerais and Rio de Janeiro through customized connectivity SKUs. |
| Software Companion Development | Captures patient-driven data sharing trends through smartphone-exported glucose curve integration. |
Research Methodology
ANVISA registration databases, SUS procurement auction records, and Mercosur trade statistics formed the secondary backbone, supplemented by primary interviews with endocrinologists, biomedical engineers, hospital purchasing committees, and pharmacy franchise operators. Bottom-up and top-down triangulation validated segment-level volume estimates against federal chronic disease program enrollment data and state-level meter penetration surveys.
Bottom-up modeling anchored forecasts to installed base expansion and replacement cycles across glucose meters, test strips, continuous glucose monitors, and lancing devices, while top-down analysis cross-checked aggregate market value against SUS reimbursement expenditure trends. Segmentation dimensions included product architecture, end-user purchasing authority, electrochemical versus optical versus non-invasive technology platforms, and distribution channel working capital intensity. CAGRs were derived from regression analysis of historical procurement volumes and policy-driven demand inflections, with sensor-wearable convergence and retail pharmacy network densification as key forecast inputs.
Revisions become necessary when ANVISA regulatory harmonization timelines shift, SUS reimbursement protocols for continuous glucose monitoring are restructured, or Mercosur trade corridor stability deteriorates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Korea Continuous Glucose Monitoring Devices Market
Diabetes Care
Asia Pacific Blood Glucose Monitoring Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
Japan Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Diabetic Foot Ulcer Treatment Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
United States Blood Glucose Monitoring Market
Diabetes Care
Continuous Glucose Monitoring Market
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
Asia-Pacific Insulin Delivery Devices Market