
 Nylon Cable Ties Market | 2026-2036
Nylon Cable Ties Market Size, Share, and Industry Trends Forecast 2026-2036
Nylon Cable Ties Market Intelligence
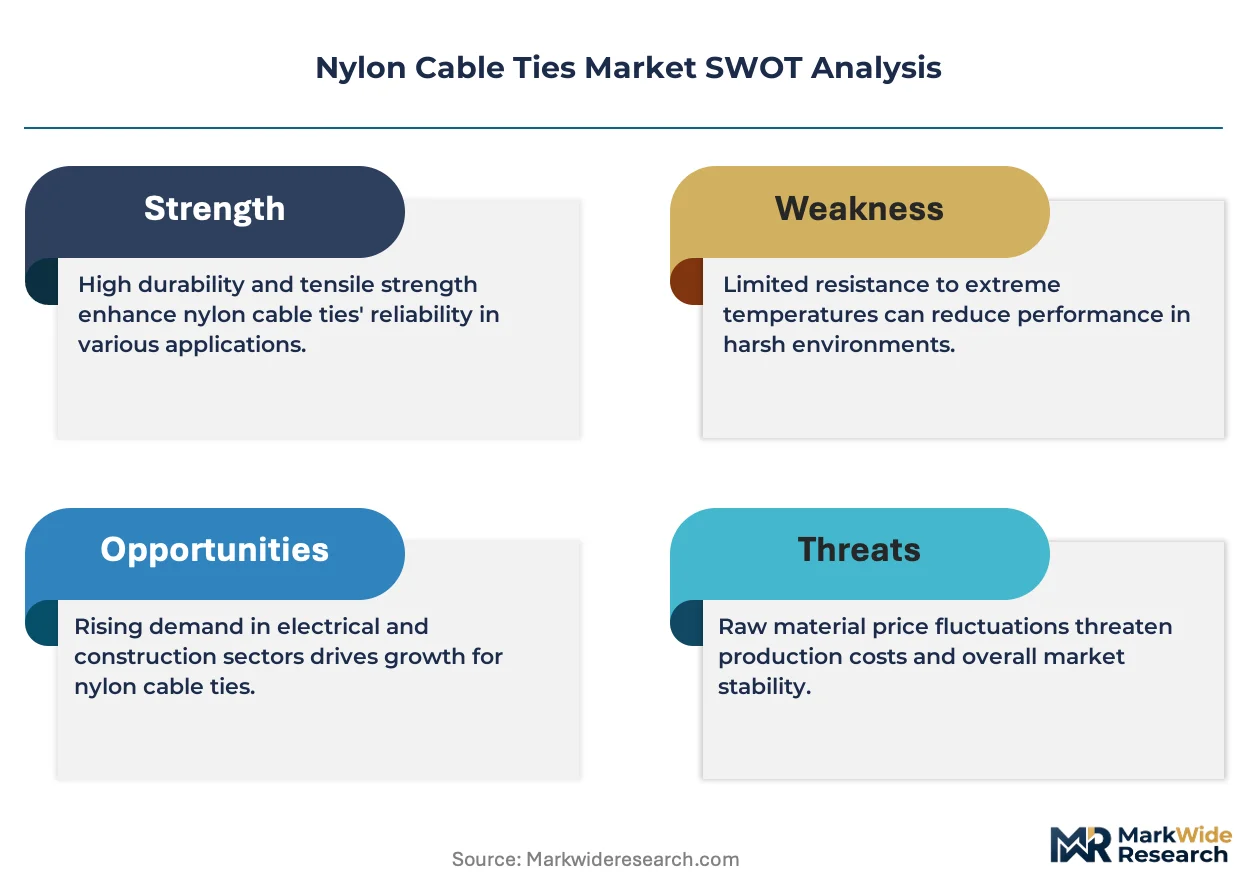
Polypropylene alternatives in low-load bundling applications is recalibrating unit economics for commodity-grade fasteners. HellermannTyton leverages captive resin compounding to sustain margin stability across European automotive contracts. Panduit Corporation anchors its position through specification control in North American data center builds. Changhong Plastics Group dominates cost-competitive volume tiers through integrated nylon polymerization in Zhejiang province.
Nylon cable ties are injection-molded polyamide fastening devices featuring one-way ratchet pawl mechanisms, typically rated for tensile loads from 18 to 250 pounds depending on width and wall thickness, designed for organized wire harness retention and temporary or permanent bundling across industrial, commercial, and residential installations. The UV Resistant product type commands premium positioning in outdoor infrastructure and solar farm deployments where ASTM D4329 exposure standards apply. Heavy Duty variants occupy the deepest margin pool in marine and oilfield segments where metal-detection requirements and salt-spray resilience justify specification-grade pricing. Electronics application demand leads absolute volume as server rack density and 5G small-cell proliferation multiply termination points per installation.
REACH restrictions on phthalate plasticizers and RoHS substance thresholds shape material formulation decisions for European market access, while UL 94 V-2 and V-0 flammability ratings gate entry into North American electrical enclosure specifications. China's GB standards for polyamide mechanical properties create a parallel compliance track for domestic procurement by state-grid contractors and EV battery pack assemblers. Stakeholders must monitor bio-based polyamide pilot programs and recycled-content mandates as these forces redefine acceptable feedstock credentials ahead of procurement specification revisions.
Market Dynamics
Data center infrastructure buildouts are compressing specification cycles for flame-retardant cable management, forcing resin compounders to validate polyamide grades against simultaneous UL 94 V-0 and GB standard requirements before procurement windows close.
Growth Catalysts
- 5G small-cell densification:Telecommunications carriers are multiplying termination points per square kilometer, multiplying unit volume demand for miniature cable ties in outdoor enclosures.
- REACH phthalate restrictions:ECHA's tightening plasticizer thresholds are accelerating formulation shifts toward bio-based polyamide pilot programs in European supply chains.
- EV battery pack assembly:Domestic manufacturing scale-up in China is concentrating procurement for high-temperature-resistant bundling solutions around state-grid contractors.
Market Restraints
- Caprolactam price volatility:Nylon 6 feedstock costs swing with benzene derivative markets, compressing margin stability for non-integrated molders.
- Zhejiang supply concentration:Integrated polymerization capacity clusters in one Chinese province create geographic risk exposure for global volume tiers.
- Polypropylene substitution:Lower-load bundling applications in residential construction are migrating to cheaper thermoplastic alternatives.
Strategic Opportunities
- India manufacturing corridors:PLI scheme incentives for electronics assembly are creating virgin demand for specification-grade fasteners in Noida and Sri City clusters.
- Solar farm UV exposure:ASTM D4329-certified UV Resistant grades command premium positioning in utility-scale photovoltaic installations.
- Recycled-content mandates:EU Green Deal procurement specifications are opening specification windows for post-industrial polyamide feedstocks.
Industry Challenges
- Dual certification timelines:Simultaneous UL and GB validation protocols extend product qualification cycles by 8-14 months.
- Metal-detection integration:Oilfield and marine segments require embedded ferromagnetic additives, complicating injection molding process control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nylon Cable Ties Market |
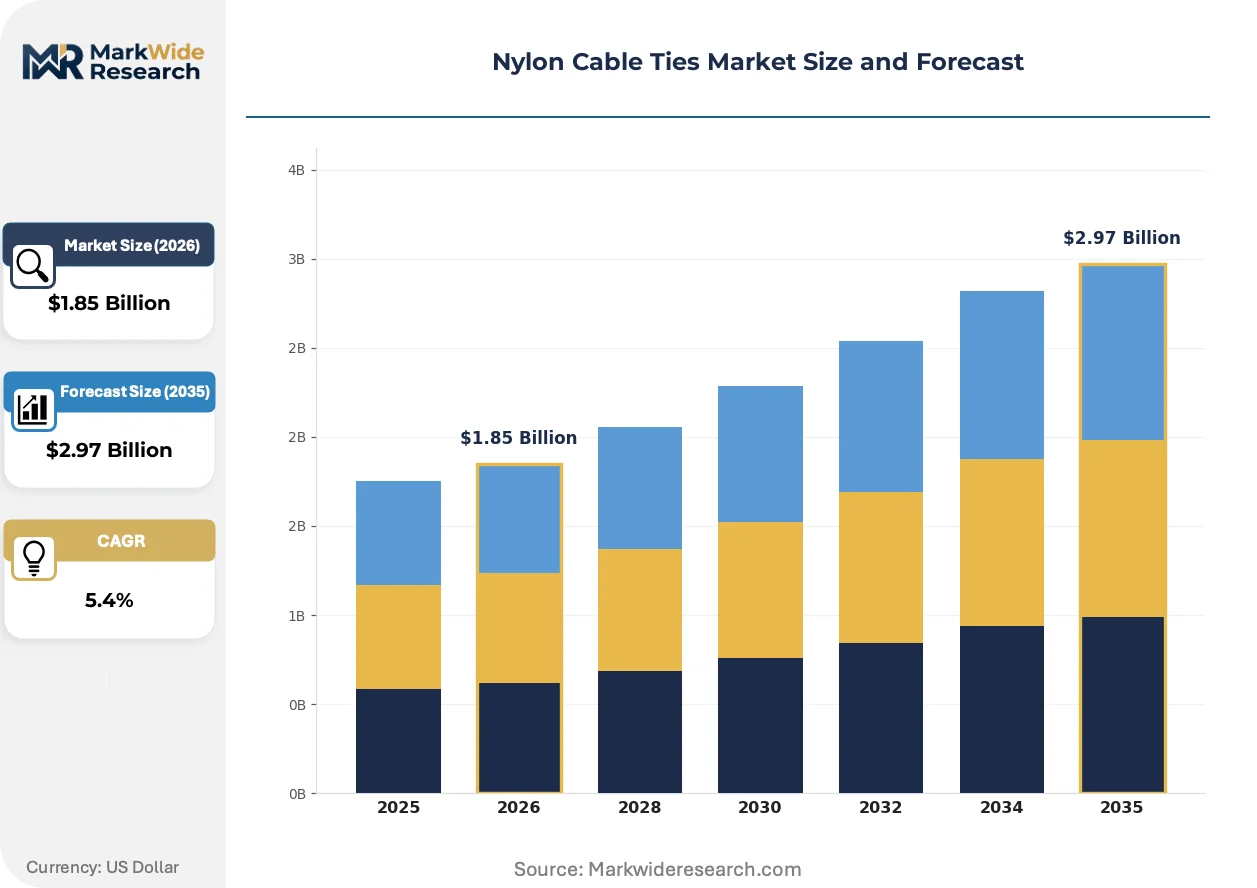
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Colored, UV Resistant, Heavy Duty Application: Electronics, Automotive, Construction, Agriculture Material: Nylon 6, Nylon 66, Polypropylene, PET Size: 4 Inch, 8 Inch, 11 Inch, 14 Inch |
| Companies Covered | ABB, 3M Company, HellermannTyton, Hont Electrical, KSS, Panduit Corporation, Avery Dennison Corporation, Changhong Plastics Group, Advanced Cable Ties, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nylon Cable Ties Market Strategic Shifts & Innovations
Material science advances and procurement specification tightening are converging to redefine acceptable performance credentials across industrial, infrastructure, and consumer applications.
Re-engineered polyamide compounds with enhanced hydrolysis resistance are absorbing moisture-sensitive deployment requirements in electric vehicle battery compartments. Automotive tier-one suppliers are qualifying these grades ahead of platform launches. The technology is absorbing volume that previously defaulted to metal clamp alternatives.
EU F-Gas Regulation phase-down schedules are indirectly pressuring enclosure sealing standards, tightening IP rating requirements for cable entry points in HVAC and refrigeration equipment. This elevates specification stakes for tie materials that maintain mechanical properties across thermal cycling. European OEMs are consolidating supplier panels around compounders with in-house flammancy testing.
Direct procurement relationships between hyperscale data center operators and specialized fastener distributors are compressing traditional channel structures. Specification control is migrating from electrical contractors to facility engineering teams. This pattern is most visible in Northern Virginia and Frankfurt cloud campus developments.
Nylon Cable Ties Market Segmentation
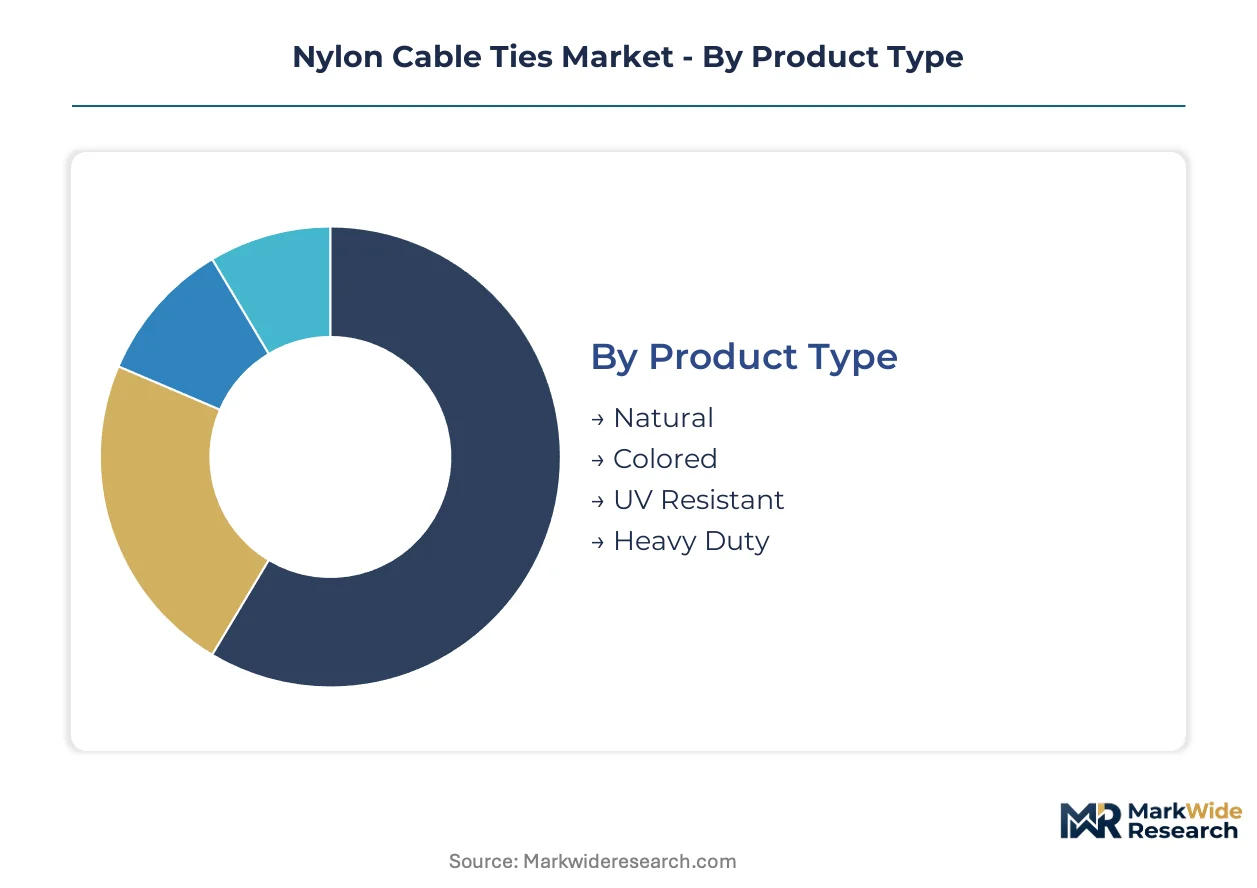
Nylon cable ties segment across performance tiers that separate commodity bundling from specification-critical infrastructure. Procurement patterns diverge sharply between cost-driven volume applications and compliance-heavy industrial deployments.
Product Type:
Volume concentrates in standard grades while premium tiers capture margin through certification requirements.
- Natural:Unpigmented polyamide 6 formulations serve general-purpose indoor bundling where color coding is unnecessary. Demand concentrates in residential electrical retrofits and light commercial installations across India and Southeast Asia as construction activity accelerates.
- Colored:Pigmented grades enable circuit identification and safety zone demarcation in complex harness assemblies. Data center operators in Northern Virginia and Frankfurt specify color-matched tie sets to reduce technician error rates during server rack expansions.
- UV Resistant:Carbon-black stabilized compounds meeting ASTM D4329 exposure standards command premium positioning in outdoor infrastructure.
- Heavy Duty:Thickened-wall variants with metal-detection additives serve marine and oilfield segments where mechanical failure carries catastrophic liability.
Mature deployment sits with Natural ties in established construction markets. Newer deployment is concentrated in UV Resistant grades for utility-scale solar installations.
Application:
End-use fragmentation reflects divergent specification intensity across industrial verticals.
- Electronics:Miniature ties rated for 18-50 pound tensile loads dominate server rack density multiplication and 5G small-cell termination points. Hyperscale operators in Singapore and Dublin consolidate procurement around flame-retardant certified grades as rack power densities climb.
- Automotive:High-temperature-resistant formulations withstand engine bay thermal cycling and battery compartment hydrolysis exposure. EV platform launches in China and Germany are qualifying hydrolysis-stabilized polyamide grades previously served by metal clamps.
- Construction:Standard-duty ties secure temporary electrical and HVAC installations during building commissioning.
- Agriculture:UV-stabilized variants support greenhouse trellising and irrigation line management in high-sunlight environments.
Procurement sophistication clusters in Electronics. Specification-grade conversion is climbing fastest in Automotive.
Material:
Feedstock selection governs thermal performance ceilings and regulatory compliance pathways.
- Nylon 6:Caprolactam-derived polymer offers cost-efficient mechanical properties for general bundling applications. Zhejiang province integrated polymerization capacity supplies global volume tiers, though benzene derivative cost volatility compresses margin stability for non-integrated molders.
- Nylon 66:Higher melting point and tensile strength serve elevated-temperature automotive and electrical enclosure applications. REACH phthalate restrictions and RoHS substance thresholds favor this grade in European market access scenarios.
- Polypropylene:Lower-density thermoplastic displaces nylon in residential construction bundling where load requirements permit.
- PET:Polyester alternative addresses specific chemical resistance requirements in select industrial environments.
Volume leadership resides with Nylon 6. Performance differentiation is expanding most quickly in Nylon 66.
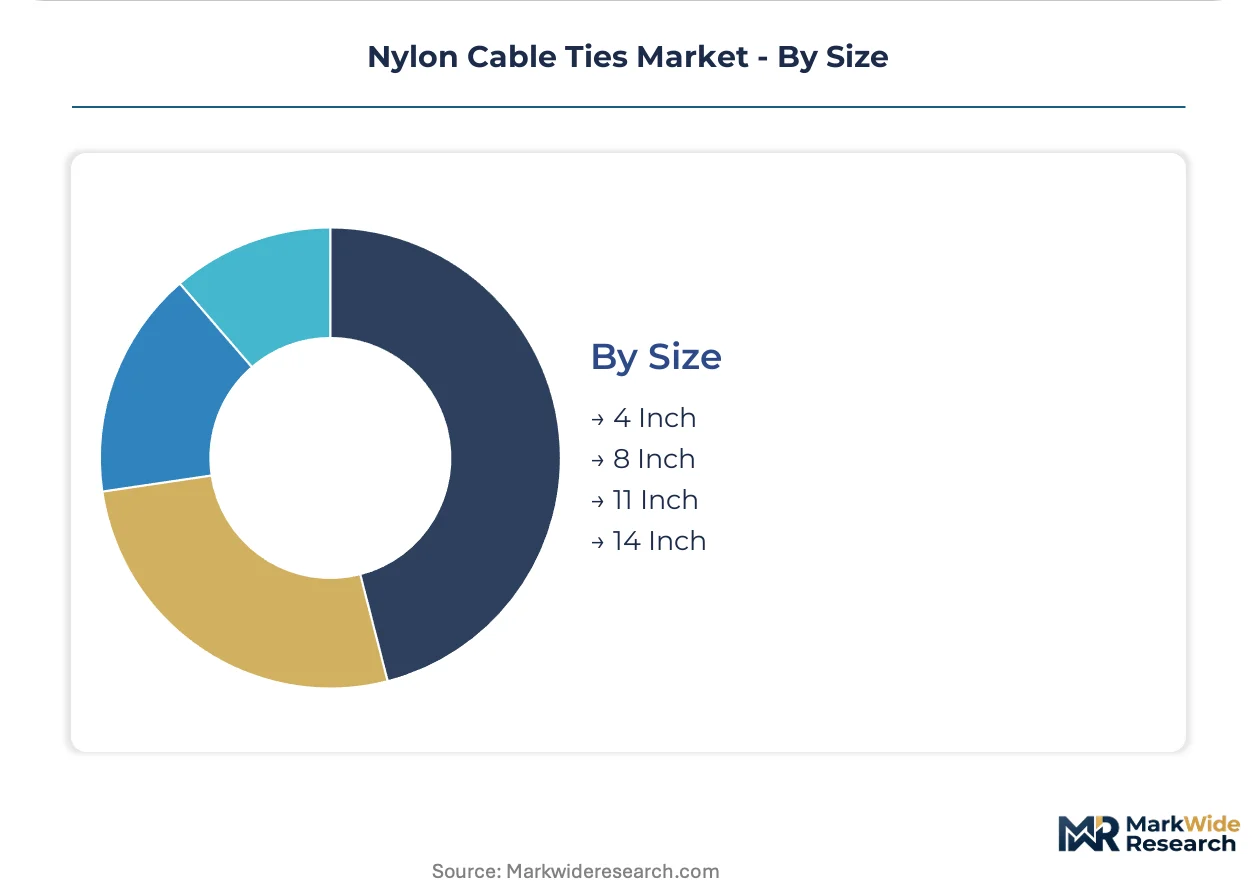
Size:
Length specification correlates directly with bundling diameter capacity and installation labor efficiency.
- 4 Inch:Miniature format serves dense electronics harnessing and telecommunications patch panel management.
- 8 Inch:Mid-range length dominates general commercial electrical installations and light industrial maintenance inventories.
- 11 Inch:Extended capacity handles construction-grade cable bundles and agricultural irrigation line organization.
- 14 Inch:Maximum standard length addresses heavy-duty industrial and infrastructure applications requiring substantial bundling diameter.
Inventory turnover concentrates in 8 Inch specifications. Demand expansion is steepest in 4 Inch formats for electronics miniaturization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Noida and Sri City special economic zones concentrate electronics manufacturing incentives under India's PLI scheme, drawing specification-grade fastener procurement toward these corridors.
United States
Northern Virginia hyperscale data center buildouts multiply server rack density requirements, compressing procurement cycles for flame-retardant cable management. OSHA electrical safety standards and UL 94 flammability ratings gate market access for enclosure-grade products. Dallas-Fort Worth metroplex hosts distribution consolidation for construction-grade volume tiers.
China
Electric vehicle battery pack assembly lines in Zhejiang province scale domestic procurement for high-temperature-resistant bundling solutions. GB standards for polyamide mechanical properties create parallel compliance tracks for state-grid contractors. Changhong Plastics Group anchors integrated polymerization capacity in Shaoxing, supplying cost-competitive volume tiers globally.
Germany
Automotive tier-one suppliers qualify hydrolysis-stabilized polyamide grades for EV platform launches ahead of 2025 model year introductions. REACH phthalate restrictions and RoHS substance thresholds favor Nylon 66 formulations in European market access scenarios. Stuttgart industrial corridor concentrates specification control for automotive harness applications.
India
Electronics assembly clusters in Noida and Sri City generate virgin demand for specification-grade fasteners under PLI scheme incentives. BIS certification requirements for electrical accessories shape import substitution patterns. Tamil Nadu's Sri City SEZ attracts cable management distributors serving smartphone and server component manufacturers.
Japan
Precision electronics manufacturing in Kanto region sustains demand for miniature ties rated for dense telecommunications harnessing. METI energy efficiency standards for data centers elevate specification requirements for cable entry management. Yokohama industrial zone hosts compounders validating polyamide grades against JIS mechanical property standards.
Nylon Cable Ties Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with specification-grade infrastructure applications favoring established compounders while commodity construction tiers fragment toward regional molders. Three archetypes dominate: integrated resin compounders with captive polymerization, specification-controlled distributors serving hyperscale data center operators, and cost-optimized volume manufacturers clustered in Chinese chemical hubs. Capacity expansion and backward integration into resin supply represent the primary competitive vectors as feedstock volatility compresses margin stability for non-integrated players.
Among diversified industrial conglomerates, ABB and 3M Company occupy positions spanning electrical infrastructure and adhesive technologies respectively, their broad portfolios exemplifying how cable management serves as a penetration point into larger facility contracts. HellermannTyton anchors the specialist tier, its name signaling European origin and focused fastening expertise that represents the specification-grade archetype in automotive and data center verticals.
| Leading Market Players |
|---|
| ABB |
| 3M Company |
| HellermannTyton |
| Hont Electrical |
| KSS |
| Panduit Corporation |
| Avery Dennison Corporation |
| Changhong Plastics Group |
| Advanced Cable Ties |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap molders across Germany and Japan anchor specification-grade pricing discipline through generational investment in captive compounding assets, insulating them from benzene derivative volatility while forcing commodity-tier competitors into spot-market capitulation.
Pricing Analysis
Short lead-time premiums of 15-25% separate emergency procurement from contract-scheduled deliveries in data center buildouts, with hyperscale operators in Northern Virginia and Frankfurt absorbing expedited pricing to maintain construction milestones. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification burden—UL 94 V-0 and GB standard dual-qualified grades command 40-60% uplifts over natural indoor grades. Price erosion runs through construction-tier natural ties as polypropylene substitution accelerates in residential bundling. Electronics procurement teams exhibit lowest price sensitivity, prioritizing flame-retardant certification and lot traceability over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from automotive tier-one suppliers in Stuttgart and Wolfsburg force compounders to qualify secondary resin streams from Belgium and the Netherlands alongside Zhejiang primary supply. Raw material dependencies center on caprolactam monomer, carbon black UV stabilizers, and ferromagnetic detection additives. Geographic supply concentration clusters in China, Germany, and the United States, with Shaoxing polymerization complexes feeding global volume tiers. Tariff exposure on Chinese-engineered resin compounds threatens margin stability for non-integrated European molders. Distribution runs through specialized electrical distributors serving contractor channels, bypassing general industrial supply houses for specification-grade tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated polymerization capacity in Zhejiang province constrains global supply elasticity, with benzene derivative cost swings transmitting directly to non-captive molders and propping pricing power for backward-integrated specialists.
For Market Incumbents: Acquire captive resin compounding assets in European automotive corridors to defend margin stability against REACH formulation shifts and polypropylene substitution in residential tiers. Prioritize dual UL-GB certification pipelines for data center procurement windows. Channel control through direct hyperscale relationships in Northern Virginia compresses distributor intermediation. For New Entrants and Emerging Players: EU Green Deal recycled-content mandates in Europe open a window for post-industrial polyamide feedstock specialists to penetrate specification-grade procurement panels ahead of incumbent reformulation cycles. Target India's PLI scheme electronics clusters in Noida and Sri City for virgin demand capture. Lead with BIS certification and local inventory positioning against import-dependent competitors. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap compounders with stranded automotive contracts in Germany as EV platform transitions disqualify legacy hydrolysis-unstabilized grades. Long-term viability hinges on bio-based polyamide pilot program conversion and state-grid contractor relationships in China. Watch caprolactam contract pricing spreads as inflection signal for integrated vs. non-integrated margin divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | HellermannTyton's captive supply insulates European automotive contracts from benzene volatility. |
| Dual Certification Investment | Simultaneous UL 94 V-0 and GB validation opens procurement at hyperscale data center operators. |
| Recycled-Content Feedstock Transition | Post-industrial polyamide qualification aligns with EU Green Deal procurement specification tightening. |
| Direct Hyperscale Distribution | Panduit's facility engineering relationships in Northern Virginia bypass electrical contractor channels. |
| High-Temperature Grade Development | Hydrolysis-stabilized compounds displace metal clamps in Chinese EV battery pack assembly. |
Research Approach
Multi-period observation of caprolactam contract pricing, resin import volumes, and certification pipeline backlogs anchored the trend analysis, supplemented by interviews with plant managers at integrated polymerization facilities, procurement leads at automotive tier-one suppliers, distribution channel partners in electrical supply, and technical R&D directors at compounders. Secondary validation drew from customs trade data, SEC 10-K filings of diversified industrial conglomerates, ECHA REACH substance restriction updates, and GB standards revision notices. Bottom-up demand modeling across application segments triangulated against top-down resin consumption estimates.
Input-output matrices mapped polyamide grade production capacity against end-use demand coefficients across the projection horizon, with segmentation dimensions spanning product type, application vertical, material grade, and regional manufacturing hub. CAGRs derived from elasticity-adjusted demand curves incorporating substitution effects from polypropylene and metal clamp alternatives. Forecast inputs included EV platform launch schedules, data center capex disclosures from hyperscale operators, and PLI scheme incentive disbursement patterns.
The model assumes a particular technology adoption path for hydrolysis-stabilized polyamide compounds; alternative pathways involving metal clamp retention or bio-based feedstock breakthroughs would alter the outlook. Forecasts reflect underlying assumptions about REACH enforcement intensity and Chinese state-grid procurement localization. Deviation in caprolactam pricing volatility or Zhejiang supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tabbing Tapes Market
Tapes
Correction Tapes Market
Tapes
Smart Card Tapes Market
Tapes
Asia-Pacific Packaging Tapes Market
Tapes
Tape Stretching Line Market
Tapes
Foam Tape Market
Tapes
Vinyl Electrical Tapes Market
Tapes
Flocking Tape Market
Tapes
Holographic Tear Tape Market
Tapes
Fine Line Striping Tape Market
Tapes
Tissue Tapes Market
Tapes
India Masking Tapes Market
Tapes
Aerospace Tapes Market
Tapes
Unsupported Single Coated Tape Market
Tapes
Removal Strips Market
Tapes
Global Seam Sealing Tapes Market