
 Lithium Ion Battery and Material Recycling Market | 2026-2036
Lithium Ion Battery and Material Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Ion Battery and Material Recycling Market Insights
The capital-intensity divergence between pyrometallurgical incumbents and hydrometallurgical challengers is unwinding competitive stability across the recycling value chain. Umicore leverages integrated smelting-refining complexes in Belgium and Poland to sustain cathode precursor supply contracts with European automotive OEMs. Redwood Materials anchors domestic North American capacity through closed-loop partnerships with cell manufacturers in Nevada and Tennessee. Brunp Recycling dominates black mass processing scale in southern China, extending backward integration into mining partnerships in Africa and Southeast Asia.
Lithium ion battery and material recycling encompasses the collection, disassembly, and chemical recovery of spent cells, modules, packs, and components to extract cobalt, lithium, nickel, and graphite for re-entry into battery manufacturing supply chains. Hydrometallurgical routes now achieve lithium recovery rates exceeding 90% through sulfuric acid leaching followed by solvent extraction and crystallization, displacing pyrometallurgical methods for cathode-active-material recovery. Cell-level recycling commands the deepest value pools as direct cathode regeneration preserves crystalline structure and avoids intermediate refining steps, while biotechnological methods remain nascent with limited commercial scale. Module and pack disassembly segments grow fastest alongside the first wave of end-of-life electric vehicle batteries reaching recyclers in volume.
EPA hazardous waste rules under RCRA govern spent battery collection and transport in the United States, while the EU Battery Regulation mandates minimum recycled content percentages and full supply chain due diligence disclosure. China's SAMR enforces GB standards for recycled battery material purity, creating divergent compliance obligations for multinational recyclers serving multiple jurisdictions. Stakeholders must monitor how Extended Producer Responsibility frameworks evolve from reporting requirements into enforceable collection quotas and recycled-content mandates.
Market Dynamics
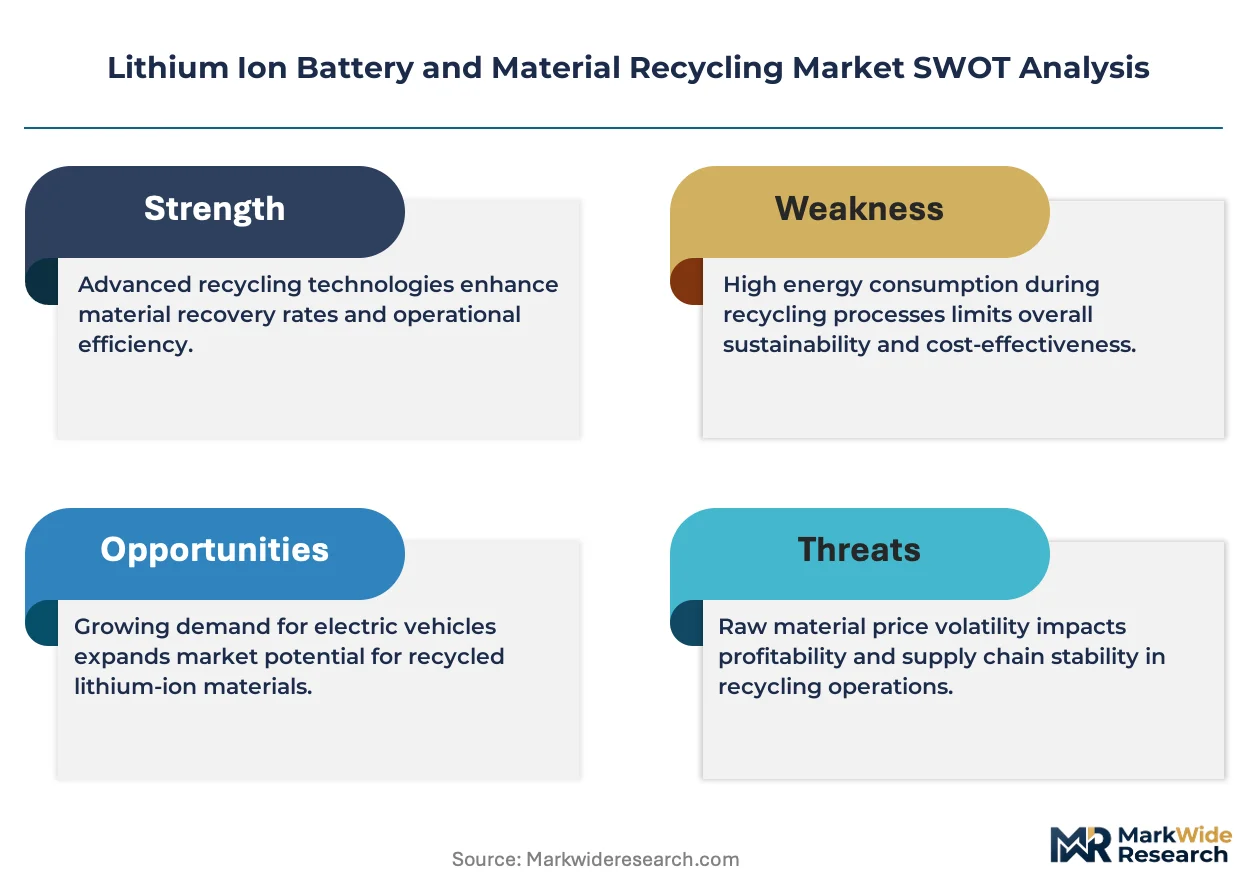
Pyrometallurgical incumbents face margin compression as hydrometallurgical challengers achieve commercial-scale lithium recovery above 90%, forcing capital reallocation across the recycling value chain.
Growth Catalysts
- EU Battery Regulation:Mandated minimum recycled content thresholds and full supply chain due diligence disclosure create enforceable demand pull for cathode precursor materials across European automotive OEMs.
- First-wave EV battery retirements:End-of-life electric vehicle batteries reaching recyclers in volume expand feedstock availability for cell-level direct regeneration processes.
- Automotive electrification mandates:Tightening OEM electrification targets in China, Germany, and the United States concentrate collection infrastructure investment and refining capacity clustering.
Market Restraints
- Black mass supply concentration:Processing scale clusters in southern China through Brunp Recycling's dominance, creating geographic single-source risk for European and North American refiners.
- RCRA hazardous waste classification:EPA rules governing spent battery collection and transport impose cost and liability burdens that deter distributed collection network development in the United States.
- Lithium price volatility:Spodumene and brine extraction cost swings compress recycling economics during periods of primary supply abundance, undermining project financing certainty.
Strategic Opportunities
- North American closed-loop partnerships:Nevada and Tennessee cell manufacturing clusters enable domestic black mass-to-precursor supply chains that bypass trans-Pacific logistics exposure.
- Biotechnological leaching methods:Bioleaching using acidophilic bacteria for metal recovery offers energy and reagent cost advantages still awaiting commercial scale validation.
- Extended Producer Responsibility enforcement:Collection quota evolution from reporting requirements into binding obligations opens service contract opportunities for logistics and disassembly specialists.
Industry Challenges
- Battery passport data interoperability:Cross-platform state-of-health tracking and chemistry disclosure standards remain fragmented across OEM proprietary systems, complicating automated sorting and routing decisions.
- High-voltage technician certification:Safe handling of 400-800V battery packs requires specialized training pipelines that lag behind retirement volume growth in most jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Ion Battery and Material Recycling Market |
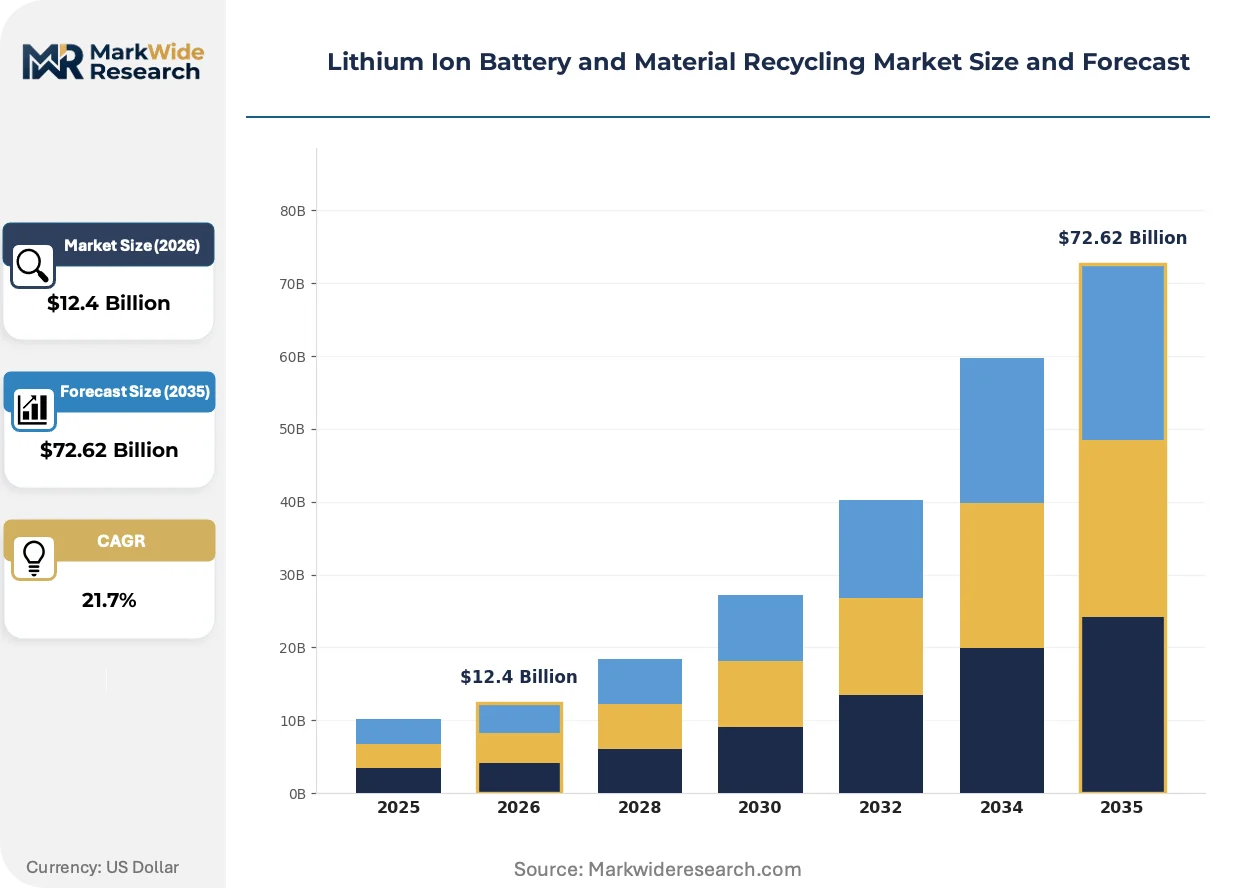
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $72.62 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell, Module, Pack, Components Recycling Method: Pyrometallurgical, Hydrometallurgical, Biotechnological, Mechanical End User: Automotive OEMs, Consumer Electronics, Industrial Applications, Energy Storage Material Type: Cobalt, Lithium, Nickel, Graphite |
| Companies Covered | Umicore, Glencore, Li-Cycle Holdings Corp., Redwood Materials, GEM Co., Ltd., Cirba Solutions, Brunp Recycling, American Battery Technology Company, Ecobat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Ion Battery and Material Recycling Market Trends and Innovations
Recovery technology pathways are diverging as direct cathode regeneration challenges intermediate refining economics, while regulatory frameworks harden compliance obligations across multiple jurisdictions simultaneously.
Direct cathode regeneration is bifurcating the value recovery landscape. This technology preserves crystalline structure in spent lithium iron phosphate and nickel-cobalt-manganese oxides without full dissolution and re-precipitation. Automotive OEMs and cell manufacturers in Germany and South Korea are piloting closed-loop feedstock agreements that bypass traditional smelter-refiner intermediaries. The structural consequence is margin compression for pyrometallurgical incumbents whose integrated complexes cannot accommodate low-temperature electrochemical restoration processes.
REACH substance restrictions and the EU Battery Regulation's due diligence mandates are tightening material provenance requirements. Industrial consequence includes mandatory third-party auditing of cobalt and lithium supply chains and disclosure of carbon intensity metrics for recycled content claims. Cathode precursor producers serving European automotive contracts face the steepest compliance cost escalation, driving investment in blockchain-traceable collection networks and in-region refining capacity.
Cell manufacturers are consolidating procurement around certified recycled content specifications rather than spot-market black mass purchases. This behavioral shift replaces commodity trading relationships with long-term offtake agreements tied to battery passport verification. The channel disruption is most visible in China, where SAMR-enforced GB standards for recycled material purity have created tiered supplier qualification systems that exclude informal collectors from legitimate supply chains.
Lithium Ion Battery and Material Recycling Market Segmentation
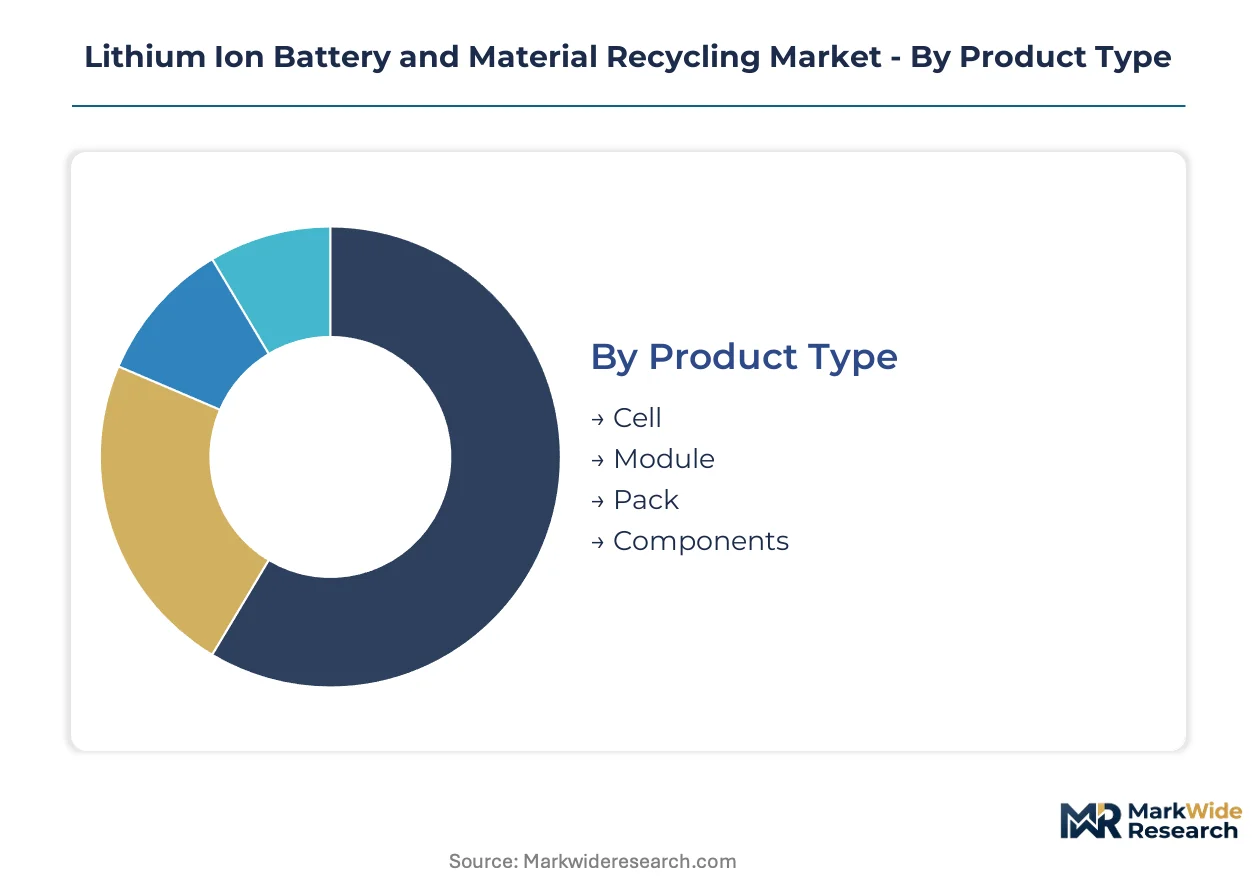
Segmentation in battery recycling determines capital allocation, compliance pathways, and partnership structures. Recovery economics vary dramatically by product scale and material chemistry, while regulatory frameworks create divergent demand profiles across end-use verticals.
Product Type:
EU Battery Regulation mandates distinct handling protocols for each product tier, with cell-level recovery commanding the strictest material provenance requirements.
- Cell:Individual electrochemical units contain concentrated cathode-active materials. Direct regeneration processes in Germany and South Korea preserve crystalline structure, bypassing intermediate refining and capturing premium value pools from automotive OEM closed-loop contracts.
- Module:Aggregated cells with integrated battery management systems. First-wave electric vehicle retirements in Nevada and Tennessee are expanding feedstock availability for automated disassembly lines serving North American cell manufacturing clusters.
- Pack:Complete battery enclosures with thermal management and structural housing. High-voltage handling requirements and 400-800V safety protocols limit processing to certified facilities in China, Germany, and the United States.
- Components:Separators, current collectors, and electrolyte residues. Secondary material streams require specialized purification to meet SAMR GB standards for recycled content purity in Chinese supply chains.
Established volume favors Pack; emerging adoption favors Cell.
Recycling Method:
Capital intensity and energy consumption create tiered processing economics across technology pathways.
- Pyrometallurgical:High-temperature smelting in integrated complexes. Umicore's Belgium and Poland facilities sustain cathode precursor supply contracts through energy-intensive cobalt and nickel recovery, though lithium losses exceed hydrometallurgical alternatives.
- Hydrometallurgical:Acid leaching with solvent extraction achieves lithium recovery rates above 90%. Sulfuric acid routes displace pyrometallurgical dominance for cathode-active-material recovery, forcing margin compression on incumbents.
- Biotechnological:Bioleaching using acidophilic bacteria offers energy and reagent cost advantages. Commercial scale validation remains pending, with pilot programs concentrated in academic-industrial partnerships.
- Mechanical:Physical shredding and separation without chemical dissolution. Pre-processing stage for black mass generation, with Brunp Recycling's southern China scale dominating upstream feedstock supply.
Hydrometallurgical routes are gaining share fastest; pyrometallurgical capacity retains incumbent lock-in with European automotive contracts.
End User:
Procurement behavior diverges between long-term offtake agreements and spot-market purchasing across customer categories.
- Automotive OEMs:Electrification mandates in China, Germany, and the United States concentrate demand for certified recycled content. Battery passport verification requirements are replacing commodity trading relationships with multi-year precursor supply contracts.
- Consumer Electronics:Portable device manufacturers face less stringent recycled content thresholds. Collection infrastructure for smartphones and laptops remains fragmented compared to electric vehicle battery networks.
- Industrial Applications:Forklifts, power tools, and medical equipment generate dispersed retirements. Reverse logistics costs constrain economics without OEM-managed take-back programs.
- Energy Storage:Stationary battery systems are approaching initial retirement waves. Grid-scale installations in the United States and China will expand feedstock availability for lithium iron phosphate recovery.
Automotive OEMs anchor current demand; Energy Storage represents the steepest expansion trajectory as utility-scale installations mature.
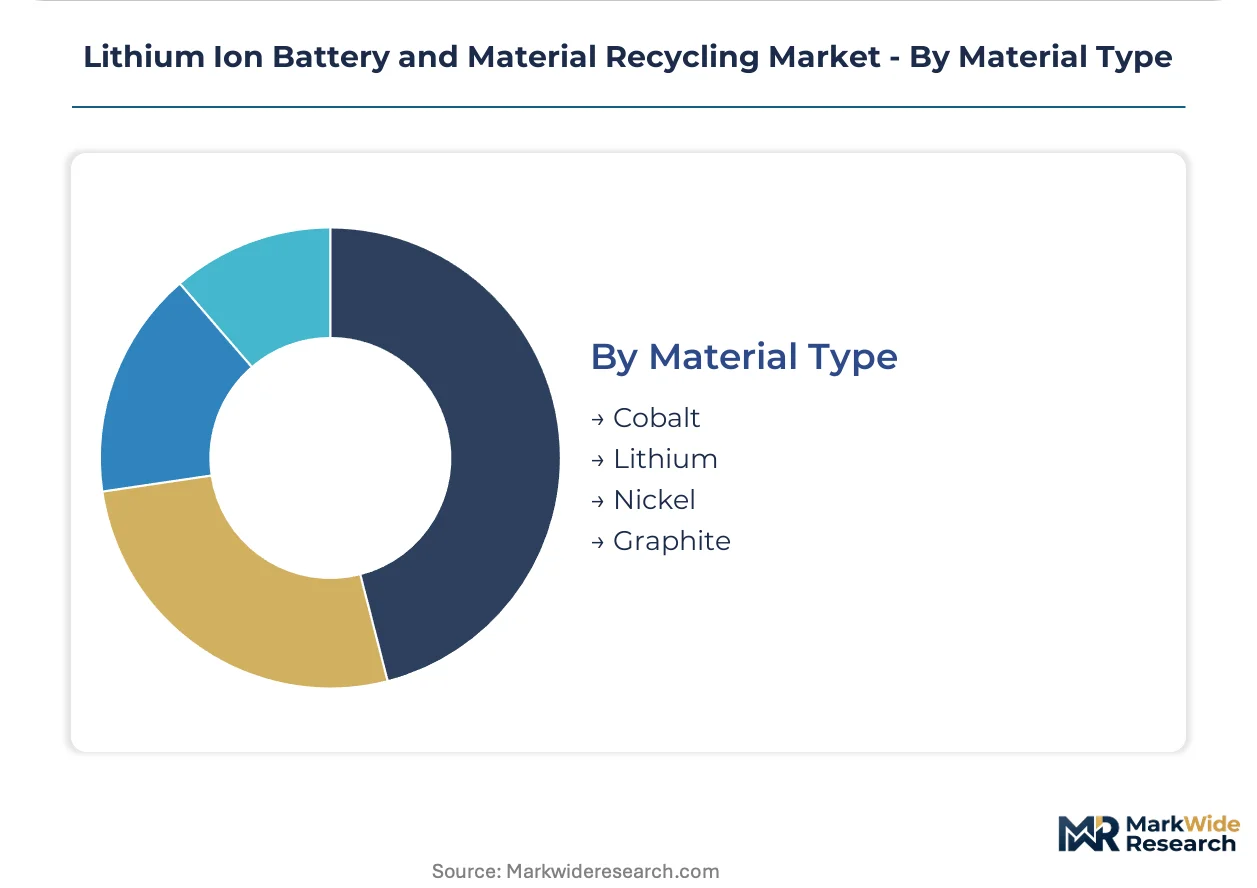
Material Type:
Price volatility and supply concentration shape recovery priority across elemental categories.
- Cobalt:Democratic Republic of Congo sourcing concentration drives due diligence mandates under EU Battery Regulation. REACH substance restrictions and third-party auditing requirements escalate compliance costs for European cathode precursor producers.
- Lithium:Spodumene and brine extraction cost swings compress recycling economics during primary supply abundance. Hydrometallurgical recovery rates above 90% are displacing pyrometallurgical lithium losses.
- Nickel:High-purity requirements for nickel-cobalt-manganese cathodes favor integrated smelter-refiner complexes. Indonesia's production expansion is altering primary supply dynamics.
- Graphite:Anode material recovery lags cathode metals in technology maturity. Synthetic and natural graphite streams require distinct processing routes with limited commercial scale regeneration.
Cobalt and Lithium dominate value capture; Graphite processing is climbing the fastest as anode regeneration technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in recycled battery materials tilt toward net-import dependence in Europe and North America against China's dominant export position in black mass and refined cathode precursors. Germany, the United States, South Korea, Japan, and Belgium concentrate the infrastructure investment responding to this imbalance.
United States
Domestic cell manufacturing clusters in Nevada and Tennessee are absorbing retired EV batteries from California and Texas fleets. EPA RCRA hazardous waste rules govern interstate transport, while the Inflation Reduction Act's domestic content bonuses accelerate refinery construction. Redwood Materials anchors closed-loop partnerships in the Mountain West.
Germany
Automotive OEM electrification mandates from BMW, Mercedes-Benz, and Volkswagen concentrate demand for certified recycled cathode materials. The EU Battery Regulation's minimum recycled content thresholds and due diligence mandates take direct legal effect here. Umicore operates integrated smelting-refining complexes in Belgium and Poland serving German precursor contracts.
China
Brunp Recycling dominates black mass processing scale in southern China, extending backward integration into mining partnerships in Africa and Southeast Asia. SAMR-enforced GB standards for recycled material purity create tiered supplier qualification systems. Yangtze River Delta and Pearl River Delta clusters concentrate both cell manufacturing and recycling capacity.
South Korea
LG Energy Solution and Samsung SDI are piloting direct cathode regeneration processes that preserve crystalline structure in spent nickel-cobalt-manganese oxides. METI-coordinated standards alignment with Japanese recyclers facilitates cross-border feedstock flows. Seoul Capital Area laboratories anchor bioleaching pilot programs with academic partners.
Belgium
Umicore's Hoboken integrated complex represents Europe's largest pyrometallurgical refining capacity for cobalt and nickel recovery. REACH substance restrictions and the EU Battery Regulation's carbon intensity disclosure requirements escalate compliance costs for cathode precursor production. Antwerp-Brussels logistics corridors handle black mass imports from French and Dutch collection networks.
Lithium Ion Battery and Material Recycling Market Competitive Landscape
Concentration sits with integrated smelter-refiners and hydrometallurgical specialists competing for automotive OEM offtake contracts. Pyrometallurgical incumbents defend European market share through long-term precursor supply agreements, while hydrometallurgical challengers capture lithium recovery premiums above 90%. Three archetypes define competitive positioning: vertically integrated mining-to-refining conglomerates, pure-play recycling technology specialists, and cell manufacturer captive recyclers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with closed-loop agreements replacing spot-market black mass trading.
Within the integrated refiner tier, Umicore and Glencore exemplify pyrometallurgical scale advantages in cobalt and nickel recovery. Among pure-play specialists, Li-Cycle Holdings Corp., Redwood Materials, and Brunp Recycling occupy positions defined by hydrometallurgical lithium recovery rates and geographic proximity to cell manufacturing clusters. GEM Co., Ltd. represents the backward-integrated archetype with mining partnerships extending into Africa. Cirba Solutions and American Battery Technology Company anchor North American capacity buildout. Ecobat occupies a position in lead-acid battery recycling infrastructure now repurposing for lithium-ion feedstock handling.
| Leading Market Players |
|---|
| Umicore |
| Glencore |
| Li-Cycle Holdings Corp. |
| Redwood Materials |
| GEM Co., Ltd. |
| Cirba Solutions |
| Brunp Recycling |
| American Battery Technology Company |
| Ecobat |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles at European cathode precursor facilities expose pricing power asymmetries between integrated pyrometallurgical refiners and hydrometallurgical challengers. This lead-time compression concentrates margin capture with processors achieving lithium recovery thresholds above hydrometallurgical benchmarks, while spot-market black mass purchasers absorb feedstock volatility.
Pricing Analysis
Configured-to-order direct cathode regeneration commands substantial premiums over standard black mass spot pricing. Contract-based long-term offtake agreements dominate procurement between automotive OEMs and certified recyclers, with price differentiation anchored in battery passport verification tiers and carbon intensity disclosure grades. Pricing pressure stems from hydrometallurgical lithium recovery rate improvements compressing pyrometallurgical incumbent margins. Tier 1 automotive OEMs exhibit lowest price sensitivity due to regulatory compliance mandates, while industrial applications buyers face acute cost constraints without OEM-managed take-back programs.
Supply Chain Analysis
Port congestion on trans-Pacific routes elevates inbound logistics costs for European and North American refiners sourcing black mass from Asian collection networks. Geographic supply concentration clusters in China, South Korea, and Germany, with raw material dependencies spanning cobalt from the Democratic Republic of Congo, lithium from Australian spodumene operations, and nickel from Indonesian production expansion. Single-source vulnerability in southern China's black mass processing scale creates structural supply chain risk. Distribution runs through closed-loop partnerships between cell manufacturers and captive recyclers, displacing spot-market commodity trading relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lithium ion battery and material recycling market represents a high-growth disruption driven by EU Battery Regulation enforcement mandating minimum recycled content thresholds and full supply chain due diligence disclosure across European automotive OEM procurement.
For Market Incumbents: Fortify integrated smelting-refining complexes through hydrometallurgical retrofit investments targeting lithium recovery rate parity with challengers. Defend European automotive contracts by accelerating battery passport-verified collection network buildout ahead of binding collection quota enforcement. Margin compression from direct cathode regeneration pilots in Germany and South Korea demands preemptive capacity repositioning in Nevada and Tennessee cell manufacturing clusters. For New Entrants and Emerging Players: Anchor in North American closed-loop partnership opportunities bypassing trans-Pacific black mass logistics exposure. Target energy storage sector feedstock availability as utility-scale lithium iron phosphate installations mature, offering lower competitive density than automotive OEM certified content tiers. Pursue biotechnological leaching validation through academic-industrial partnerships to differentiate on energy and reagent cost structures. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because electrification mandates across multiple jurisdictions create irreversible demand pull for certified recycled cathode materials. Acquisition target archetypes include pure-play hydrometallurgical specialists with proven lithium recovery scale and logistics platforms with EPA RCRA-certified high-voltage handling capabilities. Monitor EU Battery Regulation enforcement evolution from reporting requirements into binding collection quotas as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrometallurgical Capacity Expansion | Li recovery rates above 90% displace pyrometallurgical economics in cathode-active-material processing. |
| Backward Integration into Mining Partnerships | African and Southeast Asian cobalt-lithium sourcing secures feedstock against black mass supply concentration. |
| Battery Passport Verification Infrastructure | Blockchain-traceable collection networks satisfy EU Battery Regulation due diligence mandates for OEM contracts. |
| Direct Cathode Regeneration Pilot Scale-Up | Low-temperature electrochemical restoration preserves crystalline structure, bypassing intermediate refining steps. |
| High-Voltage Technician Certification Programs | 400-800V safety protocols enable pack-level processing as first-wave EV retirements accelerate feedstock volume. |
Research Methodology
Cross-validation between primary interviews with recycling plant managers, automotive OEM procurement leads, and cathode precursor technical directors anchors the qualitative findings against secondary validation from EPA hazardous waste filings, EU Battery Regulation implementation guidance, and SAMR GB standards documentation. Bottom-up feedstock volume modeling triangulates with top-down automotive electrification mandate trajectories across China, Germany, and the United States.
Sensitivity analysis across lithium price volatility bands and hydrometallurgical recovery rate improvement scenarios tests forecast robustness over the projection horizon. Segmentation dimensions span product tier, recycling technology pathway, end-user vertical, and material chemistry, with CAGRs derived from feedstock availability curves tied to first-wave EV battery retirement timing. Industry-specific inputs include cell manufacturing capacity buildout in Nevada and Tennessee and EU Battery Regulation enforcement phase-in schedules.
Underlying assumptions cover sustained automotive electrification mandate tightening and hydrometallurgical lithium recovery rate maintenance above pyrometallurgical alternatives, with deviation risk concentrated in primary lithium supply abundance compressing recycling economics and black mass trade flow disruptions from geographic single-source concentration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Battery Scrap Market
Battery Recycling
Lithium Ion Battery Recovery Market
Battery Recycling
Electric Vehicle Battery Reuse and Recycling Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Battery Recycling Market
Battery Recycling
North America Lithium-Ion Battery Recycling Market
Battery Recycling
Nickel-Cadmium Battery Recycling Market
Battery Recycling
EV Battery Reuse Market
Battery Recycling
Prepaid Battery Recycling Market
Battery Recycling
Solar Components Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Process Market
Battery Recycling
Global Lead-Acid Battery Scrap Market
Battery Recycling
Lithium Ion Battery Recycling Market
Battery Recycling
Second-Life EV Battery Market
Battery Recycling
Battery Materials Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Solution Market