
 Edge Protector Market | 2026-2036
Edge Protector Market Size, Share, and Industry Trends Forecast 2026-2036
Edge Protector Market Foresight
E-commerce fulfillment centers is unwinding the traditional dominance of brick-and-mortar retail procurement in edge protector demand. Smurfit Kappa leverages its integrated containerboard-to-converted-products chain across European distribution networks. Sonoco Products sustains technology leadership in molded fiber corner protection for appliance shipping. VPK Packaging Group anchors its position through captive recycled paper supply and dedicated converting assets in the Benelux region.
An edge protector is a rigid or semi-rigid profile—typically manufactured from laminated recycled paperboard, extruded polyethylene, or molded polyurethane foam with calipers ranging from 2 mm to 15 mm—engineered to shield corners, edges, and surfaces of palletized goods from strapping damage, impact, and compression during transit and storage. Plastic edge protectors lead volume due to moisture resistance in cold-chain logistics, while molded fiber variants represent the fastest-expanding category as brand owners eliminate single-use plastics from their packaging specifications. Margin pools concentrate in custom-printed, color-coded profiles that integrate with automated palletizing systems and customer-specific inventory protocols.
REACH restricts phthalate plasticizers in PVC-based profiles across the European Union, while the EU Green Deal's packaging and packaging waste regulation mandates recyclability and minimum recycled content thresholds that favor paper-based edge protectors. Germany's national packaging act implements extended producer responsibility fees that penalize non-recyclable materials, redirecting converter investments toward fiber-based product lines. Stakeholders must monitor how pending revisions to the EU's packaging waste framework recalibrate material cost structures and determine whether paper-based substitutes can achieve comparable compression strength in heavy-load applications.
Market Dynamics
E-commerce fulfillment networks are dismantling traditional procurement hierarchies in edge protector demand. The EU Green Deal's packaging waste directives are forcing converters to abandon PVC-based profiles for fiber-based alternatives, while automated palletizing systems require precision-matched corner board specifications.
Growth Catalysts
- EU Packaging Waste Regulation:Mandatory recyclability thresholds under the EU Green Deal are redirecting converter capex toward molded fiber production lines. Brand owners face extended producer responsibility fees that favor paper-based substitutes.
- Cold-chain logistics expansion:Pharmaceutical and fresh-food distributors require moisture-resistant edge protection for temperature-controlled shipments. Extruded polyethylene profiles dominate this specification tier.
- Automated palletizing integration:German automotive parts suppliers specify color-coded, dimensionally precise corner boards that sync with robotic handling systems. Custom printing capabilities command premium positioning.
Market Restraints
- Recycled pulp cost volatility:Old corrugated container prices fluctuate with Chinese import policy shifts. Fiber-based edge protector margins compress when OCC benchmarks spike above $150 per ton.
- Compression strength gap:Molded fiber variants fail to match extruded plastic load-bearing capacity above 2,000 kg pallet weight. Heavy machinery shippers retain polyethylene specifications despite sustainability preferences.
- REACH compliance burden:Phthalate restrictions in PVC formulations require reformulation investments. Small-scale converters lack technical resources to certify alternative plasticizer systems.
Strategic Opportunities
- Benelux captive supply integration:VPK Packaging Group's model of recycled paper collection through dedicated converting assets offers replicable architecture. Vertically integrated entrants capture margin pools currently lost to merchant market purchases.
- India e-commerce infrastructure buildout:Flipkart and Amazon India fulfillment centers lack standardized edge protection protocols. First-movers establishing specification relationships with these platforms secure long-term volume commitments.
- Digital printing convergence:UV-cured inkjet systems enable lot-specific barcoding and brand messaging on corner boards. Food and beverage manufacturers adopt this for inventory traceability and shelf presence.
Industry Challenges
- Automation engineering talent scarcity:Converting lines integrating servo-driven cutoff and scoring systems require mechatronics specialists. European technical universities produce insufficient graduates for packaging machinery deployment.
- Legacy ERP integration friction:Custom-printed edge protectors with customer-specific dimensional codes demand real-time order-to-production data flows. Mid-tier converters struggle to synchronize shop-floor execution with e-commerce customer portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge Protector Market |
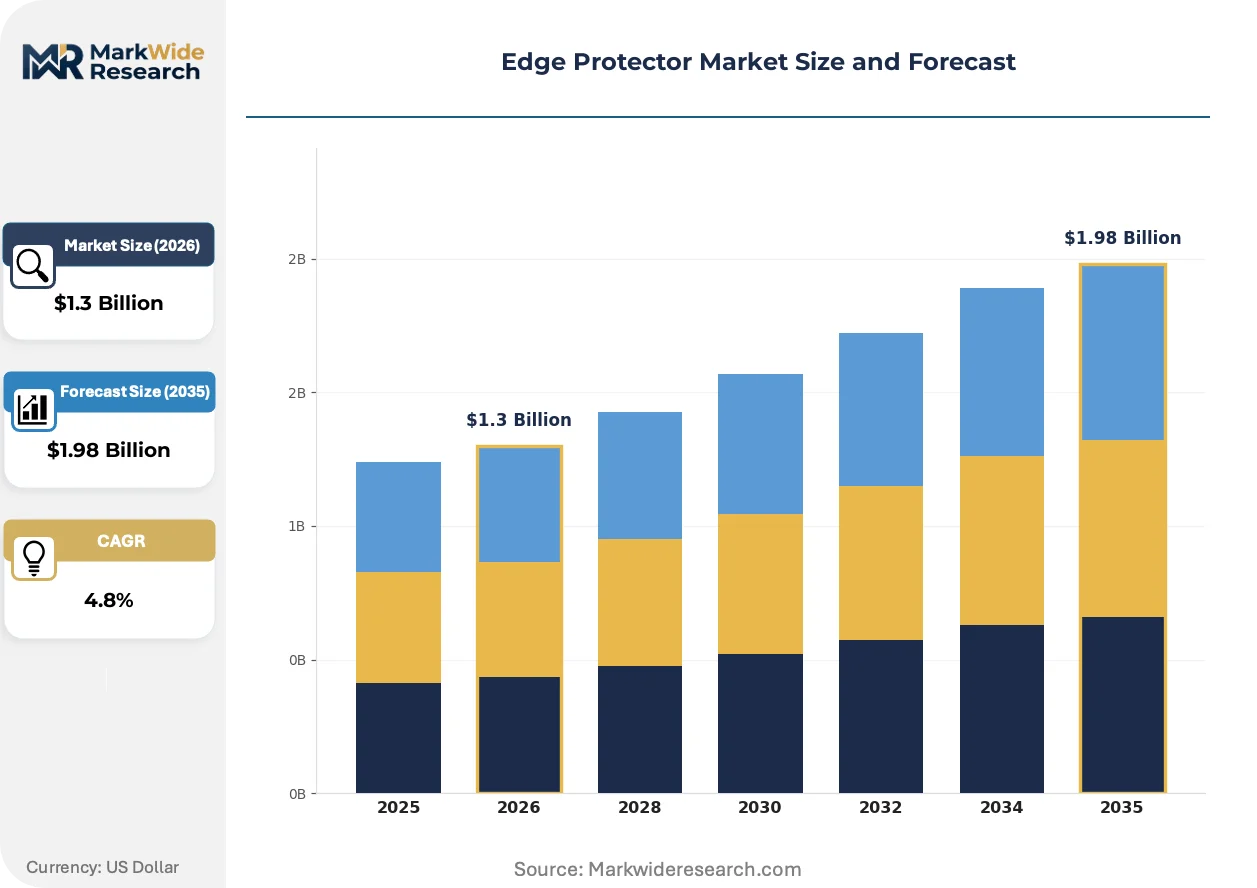
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $1.98 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Rubber, Plastic, Metal Application: Packaging, Furniture, Construction, Automotive End User: Manufacturers, Retailers, Contractors, Consumers Distribution Channel: Online, Direct Sales, Wholesalers, Distributors |
| Companies Covered | VPK Packaging Group, Signode, Sonoco Products, Primapack SAE, Kunert Group, Smurfit Kappa, Cascades Inc., Crown Holdings, Packaging Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge Protector Market Shifts & Advancements
Material science advances and regulatory stringency are bifurcating the edge protector landscape into commodity fiber volumes and engineered plastic specialties. Digital production technologies are collapsing minimum order quantities while tightening dimensional tolerances.
Water-based barrier coatings for molded fiber edge protectors are fragmenting the moisture-resistance advantage historically held by polyethylene. Food exporters and pharmaceutical distributors in the Netherlands and Belgium are piloting these bio-based alternatives for ambient shipments. The technology is fragmenting application-specific market boundaries that separated paper and plastic segments.
REACH authorization requirements for phthalate plasticizers are accelerating PVC formulation turnover across EU converting operations. ECHA's substance evaluation timeline is forcing compounders to validate citrate and trimellitate alternatives before 2026 sunset dates. German automotive suppliers are pre-qualifying fiber-based corner boards to eliminate regulatory exposure in their packaging specifications.
Direct-to-fulfillment-center contracting is displacing traditional distributor intermediaries in edge protector procurement. Amazon's Vendor Central platform and similar B2B marketplaces enable converters to capture specification data and volume commitments without regional stockist networks. This pattern concentrates most visibly in Poland and the Czech Republic, where greenfield fulfillment hubs lack established packaging supply relationships.
Edge Protector Market Segmentation
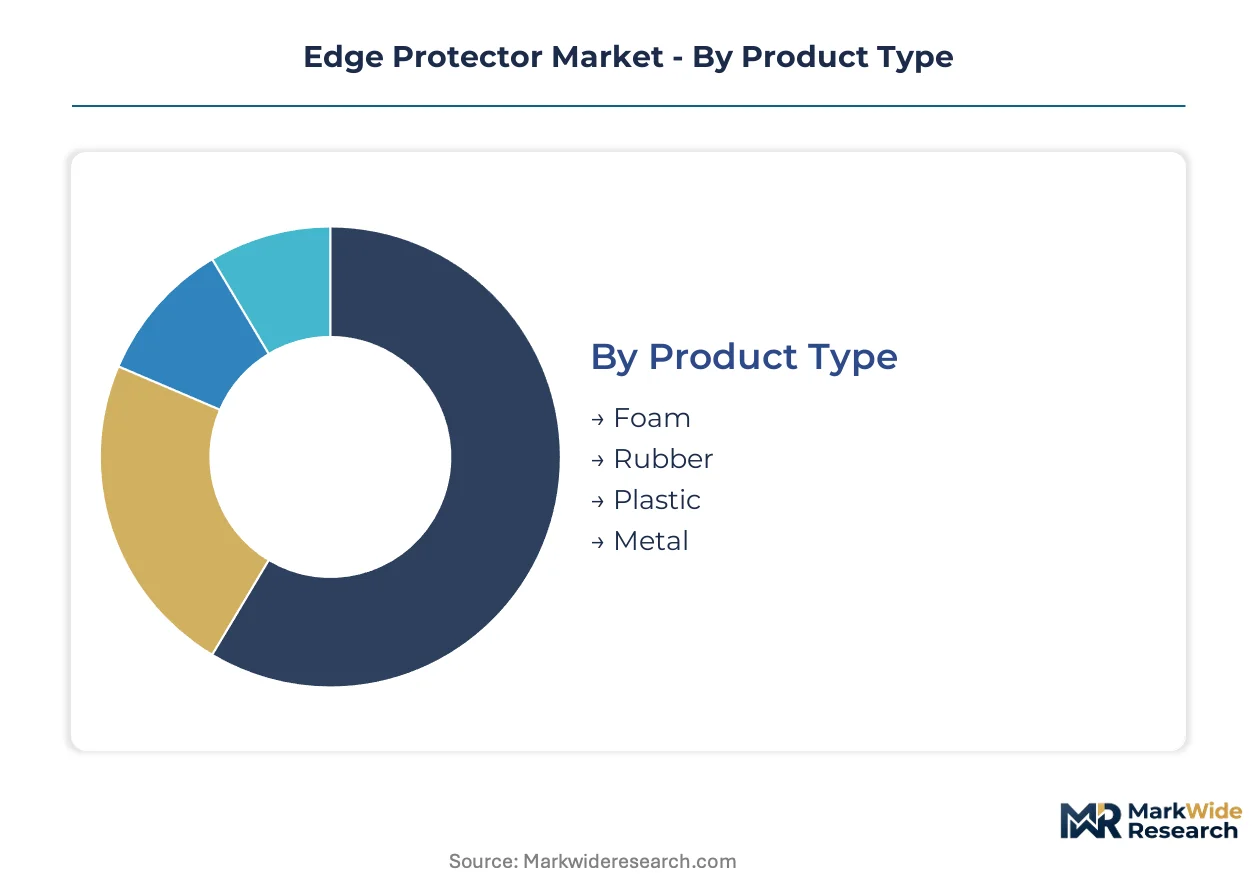
Edge protector procurement patterns diverge sharply across material specifications and fulfillment channels. E-commerce fulfillment centers and automotive tier-one suppliers drive specification fragmentation that rewards converters with flexible production architectures.
Product Type:
Fiber-based substitutes are eroding the historical dominance of petroleum-derived materials in EU-regulated applications, yet moisture resistance and load-bearing requirements sustain plastic specifications in cold-chain and heavy-machinery segments.
- Plastic:Extruded polyethylene and polypropylene profiles deliver moisture resistance and compression strength above 2,000 kg pallet loads. Cold-chain logistics operators in Germany and the Netherlands specify these for pharmaceutical and fresh-food distribution where fiber alternatives fail.
- Foam:Molded polyurethane and expanded polystyrene corner protectors cushion high-value electronics and appliance shipments. REACH phthalate restrictions are forcing compounders to validate citrate plasticizer alternatives before authorization sunset dates.
- Rubber:Elastomeric edge guards serve construction equipment and outdoor furniture with UV-stable formulations. Limited recyclability under EU packaging waste directives constrains expansion in European markets.
- Metal:Steel and aluminum corner protectors reinforce extreme heavy-load applications in industrial machinery and construction materials. Premium pricing and corrosion susceptibility restrict deployment to specialized logistics corridors.
Plastic retains volume leadership across temperature-controlled supply chains; foam holds the steepest expansion curve as brand owners eliminate single-use plastics from packaging specifications.
Application:
Cost tier stratification separates commodity packaging volumes from precision-engineered industrial specifications where dimensional tolerances command premium positioning.
- Packaging:Corner boards and edge guards for palletized goods dominate absolute volume. Amazon and Flipkart fulfillment centers specify color-coded, barcode-integrated profiles that synchronize with automated palletizing systems.
- Automotive:German parts suppliers demand millimeter-precise corner protection for just-in-time delivery sequences. Custom printing capabilities with lot-specific traceability codes capture margin pools unavailable in commodity segments.
- Furniture:Flat-pack and upholstered goods require surface-scratch prevention during last-mile delivery. E-commerce furniture volumes in Poland and Czech Republic are accelerating specification standardization.
- Construction:Heavy building materials and prefabricated components need impact-resistant edge protection on job sites. Contractors prioritize durability over recyclability in this specification tier.
Packaging commands absolute volume concentration; automotive delivers the highest margin per unit through precision and traceability requirements.
End User:
Procurement authority is shifting from centralized packaging departments to fulfillment operations managers with distinct specification priorities and vendor relationship preferences.
- Manufacturers:Industrial producers of appliances, electronics, and automotive components specify edge protectors at the packaging design stage. Direct contracting with converters is displacing distributor intermediaries in high-volume relationships.
- Retailers:Omnichannel retailers balance in-store display protection with e-commerce shipment durability. Private-label specification programs are consolidating vendor bases across European distribution networks.
- Contractors:Construction and renovation professionals purchase edge protection for temporary site applications. Price sensitivity and fragmented purchasing patterns sustain wholesaler channel relevance.
- Consumers:DIY furniture assembly and home moving drive small-quantity demand through online marketplaces. Digital printing enables brand messaging and assembly instructions on consumer-facing corner boards.
Manufacturers concentrate procurement volume through direct converter relationships; retailers are gaining specification influence fastest as e-commerce fulfillment becomes their core operation.
Distribution Channel:
Channel configuration determines margin capture and customer data access, with digital platforms collapsing traditional geographic exclusivity arrangements.
- Direct Sales:Converter-to-manufacturer relationships capture specification data and volume commitments without intermediary markups. Amazon Vendor Central and similar B2B platforms enable this pattern in Poland and Czech Republic greenfield fulfillment hubs.
- Distributors:Regional stockists maintain inventory proximity for time-sensitive construction and MRO applications. Legacy ERP integration friction limits their ability to serve custom-printed, short-leadtime requirements.
- Online:E-commerce marketplaces aggregate small-lot demand from consumers and small contractors. UV-cured inkjet production technologies enable lot-specific barcoding without plate-change costs.
- Wholesalers:Building supply and industrial distributors serve contractor segments with commodity edge protection. Price transparency from digital channels is compressing their traditional markup structures.
Direct sales channels capture the highest value relationships; online platforms are expanding fastest by aggregating fragmented demand and enabling digital production integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-commerce fulfillment operators in Germany's industrial corridor drive the highest specification density for automated palletizing-compatible corner boards. Automotive tier-one suppliers in Stuttgart and Munich anchor precision-engineered demand, while cold-chain distributors in the Netherlands sustain plastic profile volumes.
Germany
Automotive parts suppliers in Baden-Württemberg specify millimeter-precise corner boards for just-in-time sequences. The national packaging act implements extended producer responsibility fees that penalize non-recyclable materials. Berlin-Brandenburg logistics hubs are piloting fiber-based alternatives for heavy-load applications previously reserved for polyethylene.
Netherlands
Pharmaceutical distributors in Rotterdam require moisture-resistant edge protection for temperature-controlled exports. REACH authorization timelines for phthalate plasticizers are accelerating PVC formulation turnover. Food exporters in the Randstad region are adopting water-based barrier coatings for molded fiber corner boards in ambient shipments.
Poland
Amazon and Allegro fulfillment centers in Warsaw and Wrocław lack standardized edge protection protocols. EU Green Deal packaging waste directives mandate recyclability thresholds that favor paper-based substitutes. The Silesian industrial zone is attracting converter investments for captive recycled paper supply.
Belgium
Benelux distribution networks concentrate demand for color-coded, barcode-integrated profiles. The EU's pending packaging waste framework revisions are recalibrating material cost structures. Antwerp's port logistics corridor is consolidating procurement through direct converter relationships that bypass traditional distributor intermediaries.
United States
Packaging Corporation of America and Cascades Inc. serve automotive and appliance manufacturers with integrated containerboard-to-converted-products chains. FDA regulations on pharmaceutical distribution packaging influence moisture-resistance specifications. The Southeast logistics corridor spanning Georgia and the Carolinas is expanding automated palletizing capacity that demands precision-matched corner board dimensions.
Edge Protector Market Competitive Landscape
Player mix skews toward integrated paperboard converters with captive recycled fiber supply. The vendor base concentrates around three strategic tiers: multinational packaging conglomerates with continental distribution networks, regional specialists with dedicated converting assets in industrial corridors, and mid-scale operators serving custom-printed short-run requirements. Competitive dynamics center on backward integration into OCC collection streams and digital printing capabilities for lot-specific barcoding.
Within the integrated conglomerate tier, Smurfit Kappa and VPK Packaging Group exemplify the model of containerboard production feeding dedicated edge protector converting lines. Sonoco Products occupies a position bridging molded fiber technology leadership with appliance shipping specifications. These three anchors demonstrate how control over recycled paper supply and automated production assets determines margin capture in specification-intensive segments.
| Leading Market Players |
|---|
| VPK Packaging Group |
| Signode |
| Sonoco Products |
| Primapack SAE |
| Kunert Group |
| Smurfit Kappa |
| Cascades Inc. |
| Crown Holdings |
| Packaging Corporation of America |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with OCC indexation lock in supply access for German automotive suppliers while insulating converters from pulp price spikes above $150 per ton. These arrangements bind fiber-based edge protector producers to German paper mills and simultaneously freeze margin visibility across the EU Green Deal compliance window.
Pricing Analysis
Cost-plus contracts indexed to old corrugated container benchmarks dominate procurement between Smurfit Kappa and German automotive tier-ones. Three-tier pricing structure across premium, standard, and economy levels separates custom-printed color-coded profiles for automated palletizing from commodity unprinted fiber boards. Pricing pressure stems from REACH compliance investments in PVC formulation reformulation that small converters cannot absorb. Brand owners in e-commerce fulfillment exhibit lowest price sensitivity due to extended producer responsibility fee exposure, while construction contractors purchasing through wholesalers retain acute cost consciousness.
Supply Chain Analysis
Benelux port congestion at Antwerp and Rotterdam underwrites logistics vulnerability for pharmaceutical distributors requiring moisture-resistant polyethylene profiles. Manufacturing concentrates in Germany, the Netherlands, and Belgium where integrated containerboard-to-converted-products chains cluster. Recycled pulp supply draws from German OCC collection networks and Dutch post-consumer fiber streams. Single-source vulnerability sits with Chinese import policy shifts that spike benchmark prices. Distribution runs through direct converter relationships in Poland and Czech Republic greenfield hubs, bypassing traditional regional stockists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Amazon Vendor Central and comparable B2B platforms are transforming edge protector procurement into a two-sided marketplace where specification data becomes the scarce asset. Interoperability between converter ERP systems and fulfillment center inventory protocols now determines vendor selection.
For Market Incumbents: Consolidate backward integration into OCC collection streams in the Silesian industrial zone to match VPK Packaging Group's captive supply model. Acquire digital printing capabilities for lot-specific barcoding to defend against mid-scale custom-printed specialists. The EU Green Deal's pending packaging waste framework revisions threaten non-integrated converters with stranded asset risk.
For New Entrants and Emerging Players: Differentiate on water-based barrier coating technology for molded fiber edge protectors that fragments the moisture-resistance advantage of polyethylene in ambient pharmaceutical shipments. Target India e-commerce infrastructure buildout where Flipkart and Amazon India fulfillment centers lack standardized protocols. Establish specification relationships through direct technical collaboration with platform engineering teams rather than distributor intermediaries.
For Investors and Strategic Acquirers: Regional specialists with dedicated converting assets in industrial corridors and captive recycled paper supply represent the optimal acquisition archetype. Long-term viability hinges on fiber-based product line conversion ahead of EU packaging waste regulation enforcement. Monitor ECHA substance evaluation timelines for phthalate authorization sunset dates as the inflection signal for PVC-to-fiber substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Collection | VPK Packaging Group's Benelux model captures margin pools lost to merchant market purchases. |
| Digital Printing Capability Acquisition | UV-cured inkjet systems enable lot-specific barcoding for Amazon Vendor Central integration. |
| Water-Based Barrier Coating Development | Food exporters in the Netherlands pilot bio-based alternatives fragmenting plastic-paper segment boundaries. |
| Direct-to-Fulfillment-Center Contracting | Poland and Czech Republic greenfield hubs lack established supply relationships, collapsing distributor intermediaries. |
| REACH-Compliant Formulation Certification | Citrate and trimellitate plasticizer validation eliminates regulatory exposure for German automotive suppliers. |
Research Methodology
Initial hypotheses were tested against primary input from converter operations managers, automotive packaging engineers, e-commerce fulfillment procurement leads, and recycled paper supply traders and refined through secondary validation. Primary fieldwork encompassed technical discussions with servo-driven converting line manufacturers and ERP integration specialists. Secondary sources included EU packaging waste directive regulatory filings, ECHA substance evaluation timelines, OCC price benchmark databases, and customs trade data for fiberboard imports. Bottom-up demand modeling across e-commerce fulfillment centers and automotive tier-ones was triangulated against top-down macroeconomic indicators.
Variance decomposition across material type, application specification, and distribution channel isolates drivers of price and volume movements throughout the forecast period. Segmentation dimensions encompassed plastic, foam, rubber, and metal product categories; packaging, automotive, furniture, and construction applications; and direct sales, distributor, online, and wholesaler channels. CAGRs were derived from regression analysis of historical procurement patterns and forward projection of EU regulatory compliance timelines. Industry-specific inputs included Amazon fulfillment center buildout schedules and German automotive production forecasts.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or alternative phthalate authorization pathways would require recalibration. Forecasts reflect documented assumptions regarding OCC price volatility and automation adoption rates in Benelux logistics corridors. Practitioners should keep alternative scenarios live as ECHA substance evaluation timelines and India e-commerce infrastructure buildout evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Cones Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia Pacific Gas Detector Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
US Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Driving Protection Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplementary Protectors Market
Safety Equipment and Personal Protective Equipment (PPE)
Crash Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Emergency Showers Market