
 Global above-The-Neck PPE Market | 2026-2036
Global above-The-Neck PPE Market Size, Share, and Industry Trends Forecast 2026-2036
Global above-The-Neck PPE Market Foresight
Smart sensor integration into hard hats and respirators is fragmenting the traditional above-the-neck PPE technology stack, splitting the market between connected safety platforms and conventional passive equipment. 3M leverages its filtration science leadership to anchor premium respirator lines across industrial channels. Honeywell International competes through vertical integration from material science to distribution, sustaining margin control across North American and European safety markets. MSA Safety specializes in connected gas detection and helmet systems, differentiating on real-time worker monitoring capabilities.
Above-the-neck PPE encompasses protective equipment worn on the head, face, eyes, ears, and respiratory system, typically constructed from polycarbonate, thermoplastic elastomers, or silicone rubber composites and engineered to meet impact resistance, optical clarity, and airborne hazard filtration specifications. Its primary commercial purpose is preventing occupational injuries from falling objects, chemical splashes, welding arcs, excessive noise, and inhalable contaminants across hazardous work environments. Respirators and hard hats command the largest installed base, while welding helmets and smart-enabled face shields represent the fastest-expanding margin pools as metalworking and advanced manufacturing adopt automated protection systems. Polycarbonate lens systems dominate safety goggles and face shields due to optical-grade clarity and ballistic impact ratings, though silicone sealing components are gaining share in full-face respirator designs for chemical manufacturing applications.
OSHA 1910.133 eye and face protection standards, EU PPE Regulation 2016/425, and ISO 16321-1 for eye and face protectors collectively shape product certification pathways, testing protocols, and market access requirements across major economies. NIOSH approval processes for respirators and CE marking obligations under the EU framework create compliance barriers that favor established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor divergence between regional smart PPE data governance rules and traditional safety equipment standards as connectivity features trigger cybersecurity and privacy compliance obligations alongside conventional hazard protection certifications.
Market Dynamics
Smart sensor integration into hard hats and respirators is fragmenting the traditional above-the-neck PPE technology stack, splitting procurement decisions between connected safety platforms and conventional passive equipment across industrial facilities worldwide.
Growth Catalysts
- OSHA 1910.133 enforcement tightening:US industrial facilities face elevated compliance audits for eye and face protection, accelerating replacement cycles for aging safety goggles and face shields in manufacturing plants.
- Polycarbonate lens substitution:Optical-grade clarity and ballistic impact ratings drive material conversion from acrylic to polycarbonate across construction and metalworking end-uses.
- Welding automation expansion:Automated protection systems for welding arcs generate demand for auto-darkening helmets and integrated respiratory units in automotive and shipbuilding clusters.
Market Restraints
- Silicone rubber input volatility:Full-face respirator sealing components depend on petrochemical-derived silicone, exposing margins to crude-linked price swings.
- NIOSH approval bottlenecks:Respirator certification timelines extend 12-18 months, freezing new entrants from commercial launch regardless of technical readiness.
- Passive equipment commoditization:Unbranded hard hats from concentrated Asian manufacturing erode pricing power in standard-impact protection categories.
Strategic Opportunities
- India construction safety mandate gaps:Infrastructure buildout under BIS standards creates vacuum for certified hard hat and respirator suppliers as domestic manufacturing lags demand.
- EU AI Act compliance services:Connected PPE data governance obligations generate adjacent revenue streams for cybersecurity and privacy certification support.
- Direct-to-facility platform distribution:Industrial procurement teams bypass traditional safety distributors through integrated e-procurement systems specifying real-time inventory availability.
Industry Challenges
- Embedded systems engineering scarcity:Connected helmet and respirator development requires firmware and IoT security expertise absent from legacy PPE engineering teams.
- Dual certification complexity:Smart-enabled face shields must simultaneously satisfy ISO 16321-1 impact standards and regional data protection frameworks, extending development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global above-The-Neck PPE Market |
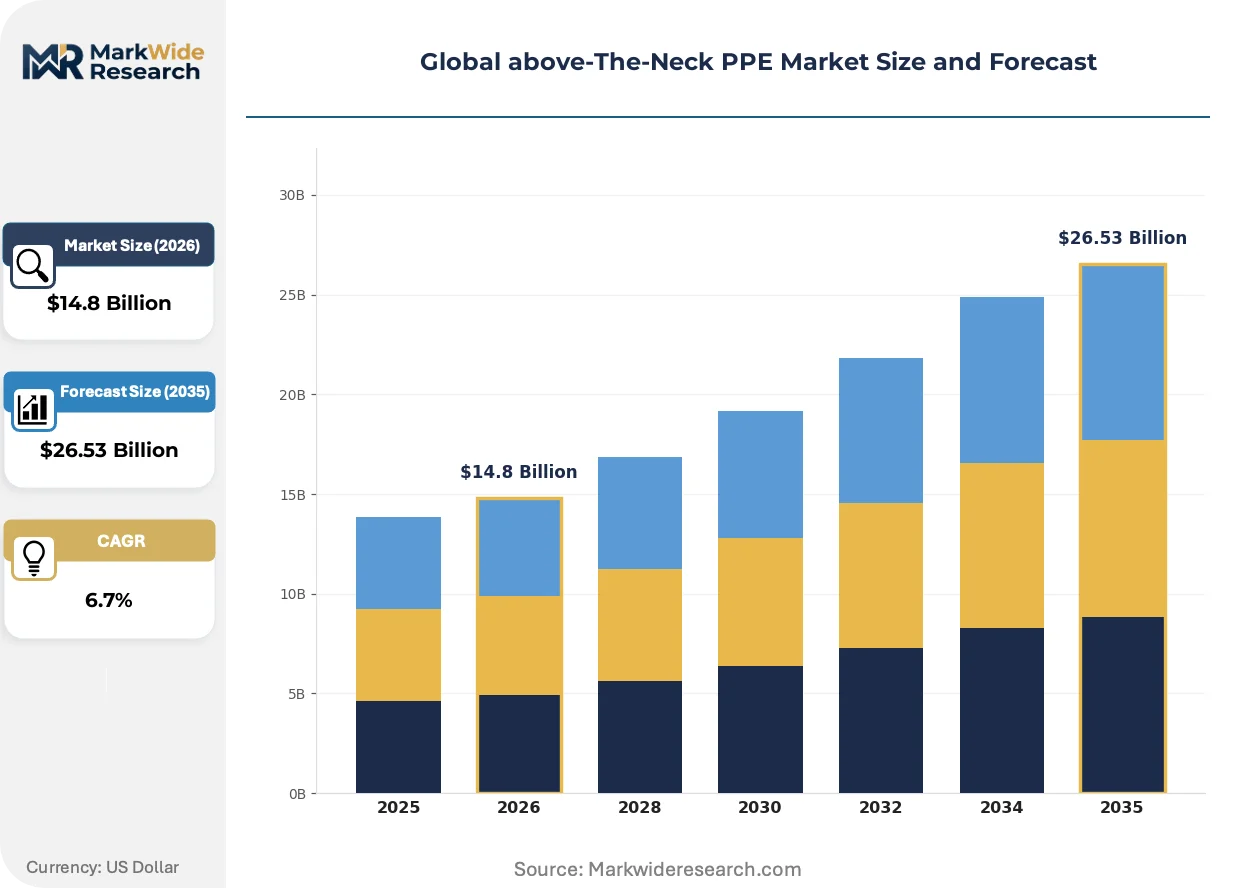
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Face Shields, Safety Goggles, Respirators, Welding Helmets, Ear Muffs, Hard Hats Material: Polycarbonate, Thermoplastic, Silicone, Neoprene, Nylon, PVC End User Industry: Construction, Chemical Manufacturing, Metalworking, Electrical Services, Mining, Oilfield Services Distribution Channel: Direct Sales, Online Retailers, Distributors, Safety Equipment Wholesalers, Specialty Stores |
| Companies Covered | 3M, Honeywell International, Delta Plus Group, MSA Safety, DuPont, Ansell Ltd., Kimberly-Clark, Lakeland Industries, Alpha Pro Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global above-The-Neck PPE Market Shifts & Advancements
Real-time worker monitoring capabilities are migrating from specialized gas detection applications into mainstream above-the-neck equipment, compressing the technology adoption cycle across hazardous work environments.
Gas detection sensor miniaturization is migrating from standalone portable units into integrated hard hat and respirator architectures. Oil and gas operators in the US Gulf Coast and North Sea facilities pilot these systems for lone-worker safety protocols. The technology is migrating from premium-tier offerings toward mid-market construction and utilities procurement specifications, collapsing the price band for basic connected protection.
EU PPE Regulation 2016/425 amendment discussions are incorporating cybersecurity requirements for connected safety equipment. Manufacturers must now document data protection by design alongside mechanical hazard testing. Full-face respirator and smart helmet categories face the steepest compliance recertification burdens, with German and French notified bodies expanding audit scopes.
Industrial buyers now unbundle after-sales service from equipment procurement, contracting calibration and maintenance separately through third-party providers. Traditional safety distributors lose captive service revenue as facilities in Germany and Japan source technical support from specialized metrology firms. Metalworking and chemical manufacturing verticals lead this disintermediation pattern, treating PPE as capital equipment with independent lifecycle management.
Global above-The-Neck PPE Market Segmentation
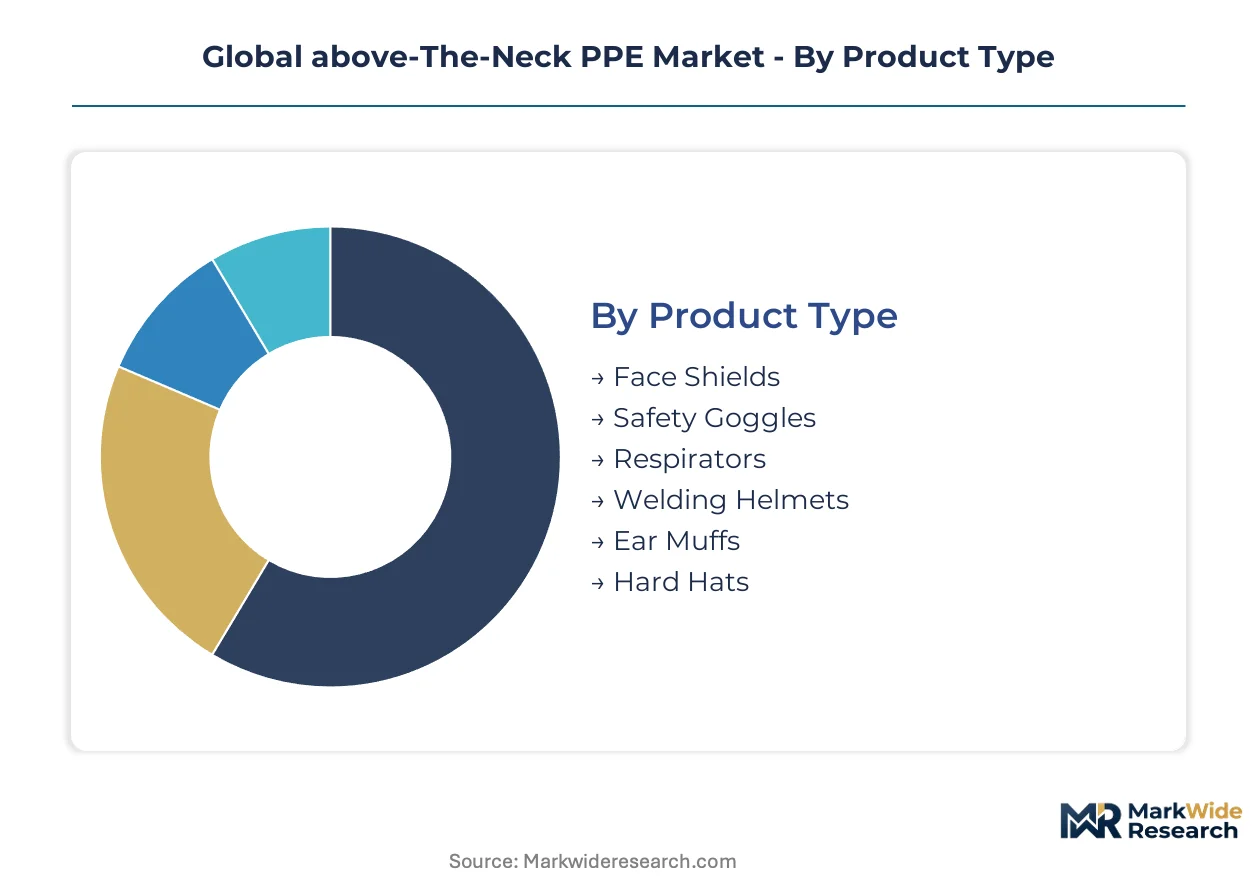
Segmentation in above-the-neck PPE reveals how hazard specificity drives procurement patterns across industrial verticals. Material selection and distribution channel choices further stratify competitive positioning between premium certified suppliers and volume-oriented manufacturers.
Product Type:
Use-case spectrum spans passive impact protection through active hazard filtration to integrated sensory defense systems across industrial facilities worldwide.
- Respirators:Engineered with silicone face seals and NIOSH-certified filtration media to block inhalable particulates and organic vapors. Demand concentrates in US chemical manufacturing corridors under OSHA 1910.134 enforcement tightening, with full-face units gaining preference for dual eye-respiratory protection.
- Hard Hats:Constructed from high-density polyethylene or ABS shells with suspension systems meeting ANSI Z89.1 impact standards. Procurement accelerates across India and Brazil infrastructure buildouts as national safety mandates extend to informal construction labor pools.
- Face Shields:Polycarbonate visors with adjustable headgear for chemical splash and projectile protection.
- Safety Goggles:Indirect-vented designs with anti-fog coatings for laboratory and healthcare environments.
- Welding Helmets:Auto-darkening filter technology with adjustable shade levels for arc protection.
- Ear Muffs:Over-the-head acoustic attenuation devices rated for decibel reduction in manufacturing plants.
The dominant share belongs to Respirators, while Welding Helmets are closing the gap fastest.
Material:
Cost tier differentiation separates optical-grade performance specifications from commodity impact resistance across procurement categories.
- Polycarbonate:Optical-grade thermoplastic with ballistic impact ratings and UV stabilization for lens applications. Safety goggle and face shield demand in German automotive manufacturing favors this material for clarity under precision assembly conditions.
- Silicone:Biocompatible elastomer with temperature stability for respirator face seals and cushioning components. Full-face respirator manufacturers in France and Italy specify medical-grade formulations to meet EU PPE Regulation skin contact requirements.
- Thermoplastic:Injection-moldable polymers for hard hat shells and structural components.
- Neoprene:Chemical-resistant synthetic rubber for gasket and seal applications in industrial environments.
- Nylon:High-strength synthetic fiber for suspension systems and strap assemblies.
- PVC:Cost-competitive polymer for disposable and limited-use protective equipment.
Polycarbonate commands premium positioning, though Silicone is expanding most quickly into connected respirator architectures.
End User Industry:
Application intensity varies from episodic compliance-driven procurement to continuous-wear operational requirements across hazard exposure profiles.
- Construction:Hard hats and basic eye protection dominate procurement volumes with high turnover rates from damage and loss. China and India infrastructure spending drives replacement cycles as project density increases safety officer staffing ratios.
- Oilfield Services:Integrated respiratory and gas detection systems for hydrogen sulfide and volatile organic compound exposure. US Gulf Coast operators specify connected hard hats with lone-worker monitoring under BSEE safety management system requirements.
- Chemical Manufacturing:Full-face respirators and chemical-resistant face shields for process equipment maintenance.
- Metalworking:Welding helmets and impact-resistant eye protection for fabrication and finishing operations.
- Mining:Heavy-duty hard hats with integrated cap lamps and hearing protection for underground operations.
- Electrical Services:Arc-rated face shields and insulated hard hats for live circuit work.
Construction holds volume leadership, yet Oilfield Services is gaining share fastest through smart PPE upgrade cycles.
Distribution Channel:
Customer type fragmentation splits procurement between integrated facility management platforms and traditional safety supply relationships.
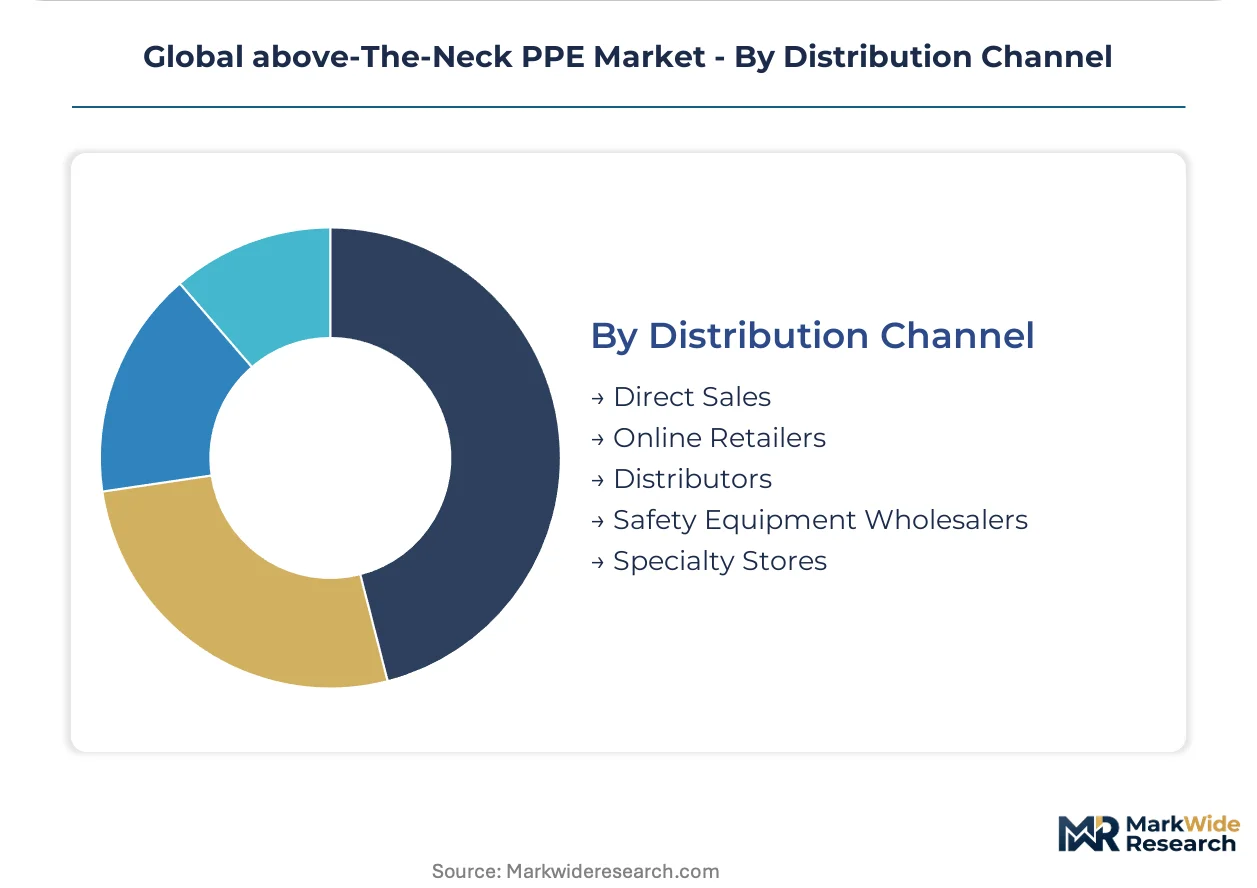
- Distributors:Multi-brand safety suppliers with technical consultation services and inventory management programs. German industrial facilities rely on specialized distributors for CE-marked product verification and documentation compliance.
- Direct Sales:Manufacturer-to-facility contracts for high-volume standardized procurement with custom branding. Japanese automotive OEMs favor direct relationships for just-in-time delivery of color-coded hard hat programs across assembly plants.
- Online Retailers:E-commerce platforms with specification filtering and bulk pricing for mid-market buyers.
- Safety Equipment Wholesalers:Regional stocking distributors serving local contractor markets.
- Specialty Stores:Retail outlets targeting professional trades with immediate product availability.
Distributors retain the largest share, though Direct Sales is climbing the fastest as procurement platforms consolidate supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in above-the-neck PPE tilt toward net-exporting manufacturing clusters in Asia against import-dependent industrial economies in Europe and North America. China and India ship respirators and hard hats to construction sites across the Middle East and Africa. Germany and the United States source specialized welding helmets and connected safety systems from domestic fabricators with premium certification capabilities.
United States
OSHA enforcement tightening accelerates replacement cycles for aging eye and face protection across manufacturing plants. BSEE safety management system requirements drive connected hard hat adoption among Gulf Coast oilfield operators. Houston and New Orleans industrial corridors pilot integrated gas detection helmets for lone-worker protocols.
Germany
Automotive OEMs specify polycarbonate safety goggles for precision assembly conditions under optical clarity requirements. EU PPE Regulation 2016/425 amendment discussions incorporate cybersecurity obligations for connected equipment, expanding audit scopes at notified bodies. Stuttgart and Wolfsburg manufacturing clusters demand CE-marked documentation verification through specialized distributors.
China
Domestic manufacturing clusters expand production capacity for hard hats and respirators as infrastructure buildout accelerates safety equipment procurement. GB standards alignment with ISO 16321-1 streamlines export certification for polycarbonate lens systems. Yangtze River Delta factories supply construction projects across Belt and Road corridors in Southeast Asia and Africa.
India
Bureau of Indian Standards safety mandate gaps create vacuum for certified hard hat suppliers as domestic manufacturing lags demand from infrastructure spending. CDSCO medical-grade silicone regulations influence respirator face seal formulations for chemical manufacturing applications. Mumbai and Delhi construction sites drive replacement cycles as project density increases safety officer staffing ratios.
Brazil
ANVISA regulatory frameworks for occupational health equipment shape import requirements for full-face respirators in chemical manufacturing corridors. Petrobras safety protocols drive demand for integrated respiratory and gas detection systems in offshore operations. São Paulo and Rio de Janeiro industrial zones source premium welding helmets for shipbuilding and automotive fabrication clusters.
Global above-The-Neck PPE Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers: diversified industrial conglomerates with captive material science capabilities, specialized safety equipment manufacturers with deep regulatory affairs infrastructure, and volume-oriented fabricators concentrated in Asian manufacturing basins. The competitive landscape rewards backward integration into filtration media and polymer compounding, while connected PPE development requires firmware engineering partnerships absent from legacy player skill sets. M&A activity concentrates on sensor technology acquisitions and regional distribution network consolidation.
Within the diversified industrial tier, 3M and Honeywell International anchor premium positioning through material science leadership and vertical control from polymer production to distribution channels. MSA Safety exemplifies the specialized safety archetype, occupying a position defined by real-time worker monitoring capabilities and gas detection system integration. These three entities represent distinct competitive vectors: filtration science dominance, supply chain integration, and connected platform specialization.
| Leading Market Players |
|---|
| 3M |
| Honeywell International |
| Delta Plus Group |
| MSA Safety |
| DuPont |
| Ansell Ltd. |
| Kimberly-Clark |
| Lakeland Industries |
| Alpha Pro Tech |
| Others |
Supply & Pricing Matrix
China's concentrated silicone rubber and polycarbonate resin production anchors margin capture at the material-compounding tier, while downstream pricing power fragments between NIOSH-certified premium respirator suppliers and commoditized hard hat fabricators competing on volume scale.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on NIOSH certification grade and after-sales service bundling, with certified full-face respirators commanding substantial premiums over unbranded alternatives. Cost compression in standard-impact hard hats is intensifying because Yangtze River Delta manufacturers flood export channels with basic ABS-shell units. Volume-sensitive construction contractors exhibit highest price sensitivity, whereas oilfield operators purchasing connected gas-detection helmets demonstrate lowest sensitivity due to BSEE compliance mandates.
Supply Chain Analysis
Export-control restrictions on embedded sensor technologies and firmware architectures limit component flows from US and EU suppliers to Asian assembly operations. Manufacturing concentrates in China, India, and Vietnam for injection-molded shells and suspension systems, while Germany and the United States retain specialized production of auto-darkening welding filters and connected helmet electronics. Raw material dependencies center on petrochemical-derived silicone for respirator seals, optical-grade polycarbonate for lens systems, and rare-earth elements for gas detection sensors. Single-source vulnerability in NIOSH-approved filtration media creates structural risk. Distribution runs through multi-brand safety distributors with technical consultation capabilities, though direct-to-facility e-procurement platforms are gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering and IoT security expertise gaps separate connected PPE developers from legacy equipment manufacturers, concentrating value capture among technology-augmented safety specialists rather than conventional fabricators.
For Market Incumbents: Pre-empt sensor technology obsolescence by acquiring embedded systems engineering capabilities outside traditional PPE R&D competencies. Backward integration into optical-grade polycarbonate compounding defends margin position against resin price volatility. Certification investment in EU AI Act compliance documentation creates switching costs as notified bodies expand cybersecurity audit scopes for connected helmets. For New Entrants and Emerging Players: Mid-market commercial construction in India represents the most penetrable entry point, as BIS safety mandate enforcement outpaces domestic certified hard hat manufacturing capacity. Specialized welding helmet distribution for automated metalworking facilities in Brazil offers secondary white-space access. Go-to-market execution should leverage direct e-procurement platform relationships bypassing established distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap connected safety platform developers with proven lone-worker monitoring deployments and regulatory affairs infrastructure spanning both OSHA and EU PPE Regulation frameworks. Long-term viability favors entities bridging mechanical hazard certification with data governance compliance capabilities. Watch NIOSH approval timeline compression as the inflection signal indicating regulatory adaptation to smart PPE innovation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Technology Acquisition | Embedded gas detection firmware expertise addresses capability gaps in legacy engineering teams. |
| Backward Integration into Filtration Media | In-house NIOSH-certified filter production reduces certification timeline exposure and margin volatility. |
| EU AI Act Compliance Certification | Data protection by design documentation satisfies expanding notified body audit requirements in Germany and France. |
| Direct-to-Facility Platform Partnership | E-procurement integration captures procurement team demand bypassing traditional safety distributor markups. |
| Regional Distribution Network Consolidation | Specialized distributor acquisition in India and Brazil secures BIS and ANVISA compliance verification capabilities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with safety officers at construction and oilfield facilities, procurement managers at industrial OEMs, regulatory affairs directors at notified bodies, and channel partners at multi-brand distributors. Secondary validation drew from OSHA enforcement data, EU PPE Regulation amendment documentation, NIOSH certification databases, and customs trade records for polycarbonate and silicone rubber flows. Bottom-up volume modeling across product type, material grade, and end-use industry segments was cross-checked against top-down macroeconomic indicators and infrastructure spending projections.
Calibration against historical replacement cycle patterns and regulatory enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product category, certification tier, connectivity capability, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating hazard exposure profiles and mandate compliance deadlines. Industry-specific forecast inputs encompassed welding automation adoption rates in automotive manufacturing and lone-worker safety protocol expansion in upstream oil and gas operations.
Practitioners should monitor NIOSH approval backlog duration and EU cybersecurity recertification burden for early signals of competitive repositioning. Forecasts reflect documented assumptions regarding OSHA enforcement continuity and BIS mandate implementation timelines. Material shifts in petrochemical input pricing or export-control expansion on sensor technologies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Static Safety Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Fatigue Mats Market
Safety Equipment and Personal Protective Equipment (PPE)
Emergency Showers Market
Safety Equipment and Personal Protective Equipment (PPE)
Arc Flash Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respiratory Protection Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Surface Protection Services Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Respiratory Protective Equipment (RPE) Market