
 Non-Powered Air Purifying Respirator Market | 2026-2036
Non-Powered Air Purifying Respirator Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Powered Air Purifying Respirator Market Analysis
Preventive maintenance contracts for filter replacement and fit-testing services is expanding the recurring revenue base for respirator suppliers. 3M leverages its global distribution network to sustain aftermarket attach rates across industrial accounts. MSA Safety Incorporated anchors North American demand through integrated gas detection and respiratory system bundles. Drägerwerk AG & Co. KGaA differentiates via occupational health service partnerships that extend beyond hardware sales.
A non-powered air purifying respirator relies on the wearer's breathing to draw ambient air through a filter cartridge or canister, with half-mask and full-face configurations rated to NIOSH 42 CFR 84 or EN 14387 standards depending on target particulate or vapor hazards. Its primary purpose is to protect workers and emergency personnel from airborne contaminants in environments where oxygen levels remain adequate but atmospheric pollutants exceed permissible exposure limits. Full-face designs command premium positioning due to integrated eye protection and higher assigned protection factors, while disposable half-masks dominate volume in construction and agriculture applications where turnover rates run high. Combination filters represent the fastest-growing filter type as multi-hazard workplaces proliferate in chemical manufacturing and pharmaceutical processing.
NIOSH certification requirements in the United States and CE marking under the EU Personal Protective Equipment Regulation both mandate rigorous laboratory testing for filtration efficiency, breathing resistance, and field performance, effectively restricting market access to technically qualified manufacturers. OSHA's Respiratory Protection Standard further compels employers to implement written programs, medical evaluations, and annual fit testing, embedding respirator procurement within broader compliance expenditures. Stakeholders must monitor evolving harmonization between NIOSH and EN standards, as regulatory convergence would reshape competitive barriers for multinational suppliers serving dual-certificate customers.
Market Dynamics
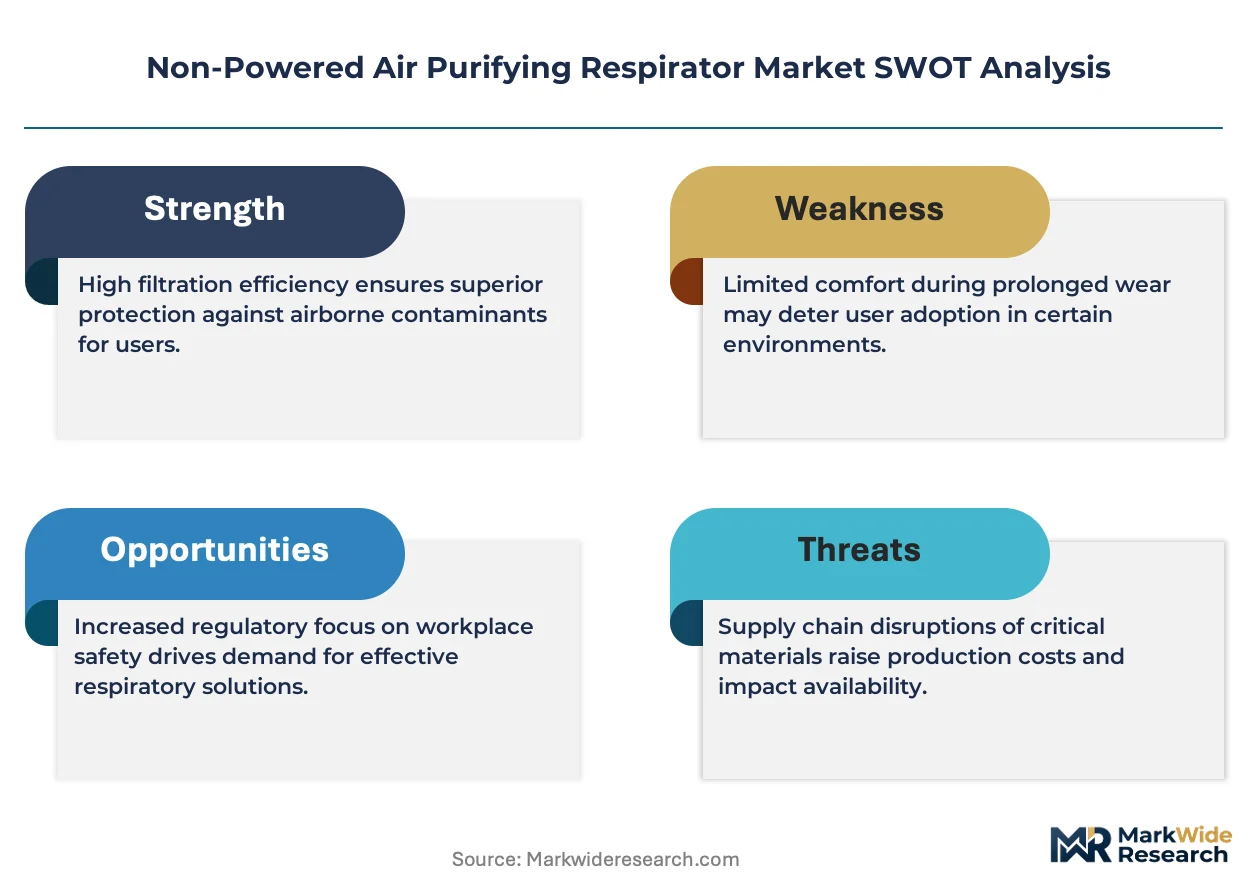
Filter cartridge standardization is compressing supplier margins while expanding interoperability, forcing manufacturers to differentiate through fit-testing services and connected compliance platforms rather than proprietary lock-in.
Growth Catalysts
- OSHA Respiratory Protection Standard:Mandatory written programs and annual fit-testing requirements embed recurring service revenue into hardware procurement cycles across US industrial facilities.
- Healthcare-acquired infection protocols:Tightened hospital sterilization mandates in China and India are expanding N95 and P100 half-mask deployment among nursing staff and surgical support personnel.
- Combination filter media:Multi-layer pleated designs addressing simultaneous particulate, organic vapor, and acid gas hazards reduce inventory complexity for chemical processing operators.
Market Restraints
- Electrostatic meltblown polypropylene concentration:Filter media supply clusters in China's Yangtze River Delta and Pearl River Delta, exposing buyers to single-region disruption risk.
- NIOSH certification timeline:12-18 month approval cycles for new cartridge designs delay product launches and freeze R&D amortization schedules.
- Powered air purifying respirators:Battery-driven positive-pressure units command higher protection factors and reduce breathing fatigue, capturing share in heavy-exposure metalworking and abrasive blasting.
Strategic Opportunities
- Vietnam and Indonesia manufacturing:Industrial workforce expansion in electronics assembly and shipbuilding creates first-time buyer populations lacking established supplier relationships.
- CE marking under EU PPE Regulation:Module B+C2 conformity assessment routes streamline market entry for manufacturers holding ISO 9001 quality certifications.
- Telemedicine-integrated fit-testing:Remote facial scanning algorithms and video-guided seal checks reduce compliance costs for distributed construction and agricultural workforces.
Industry Challenges
- Quantitative fit test operator certification:OSHA 29 CFR 1910.134 Appendix A mandates specialized training for PortaCount and condensation nuclei counter operation, constraining service scalability.
- Legacy respirator inventory integration:Facilities managing mixed fleets of NIOSH 42 CFR 84 and EN 14387 certified units face dual training, spare parts, and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Powered Air Purifying Respirator Market |
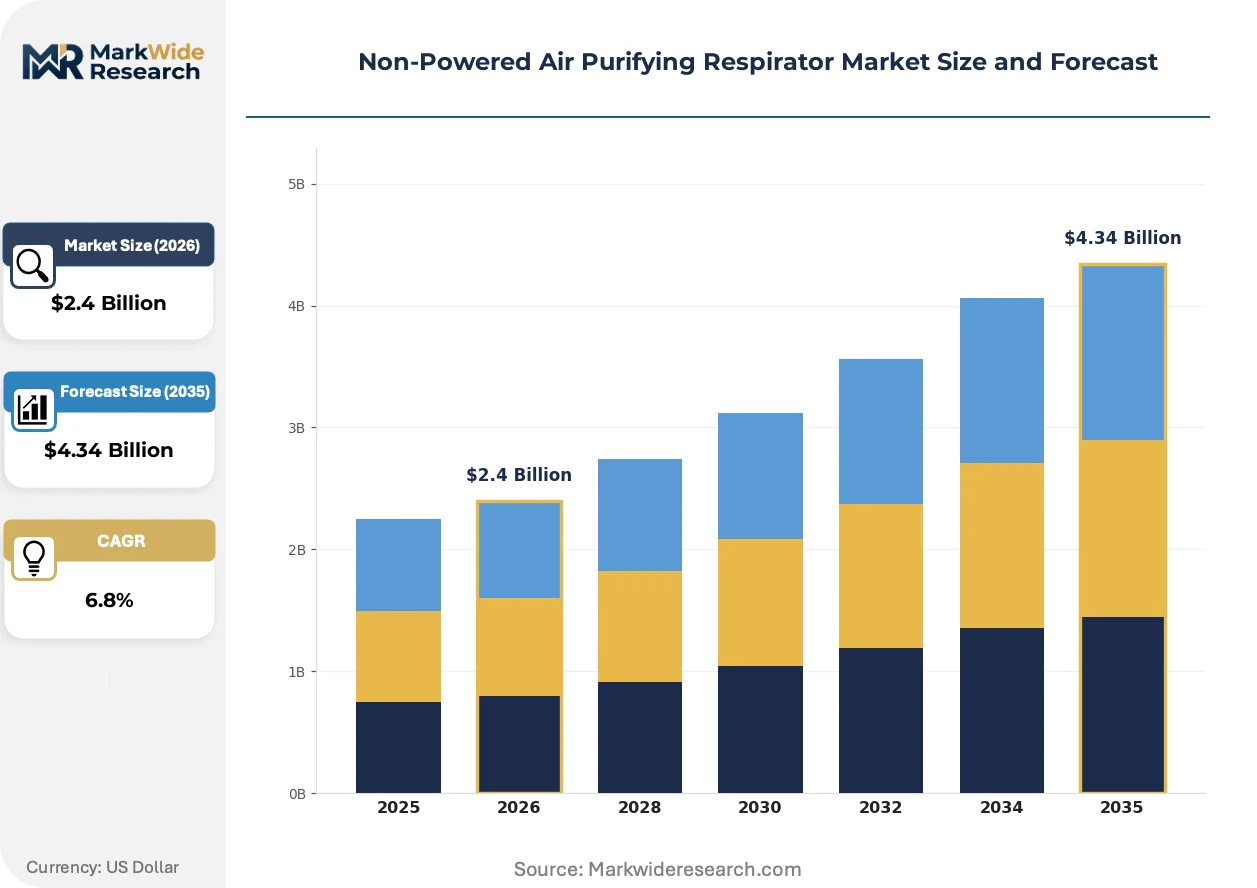
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Half Mask, Full Face, Disposable, Reusable Filter Type: Particulate, Chemical, Combination, Organic Vapor Application: Construction, Healthcare, Manufacturing, Agriculture End User: Industrial Workers, Healthcare Professionals, First Responders, General Public |
| Companies Covered | 3M, Honeywell International Inc., DuPont, MSA Safety Incorporated, Drägerwerk AG & Co. KGaA, Alpha Pro Tech, Delta Plus Group, Avon Protection, ILC Dover LP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Powered Air Purifying Respirator Market Emerging Trajectories
Connected compliance architectures and filter media chemistry advances are redefining how respiratory protection programs demonstrate ROI to safety officers and procurement teams.
Electrospun nanofiber membranes are unifying particulate capture and vapor adsorption in single-cartridge architectures. Pharmaceutical cleanroom operators in Basel and Research Triangle Park are piloting these designs to reduce changeout frequency and cross-contamination risk. The technology is unifying previously separate PPE procurement categories, compressing supplier counts and elevating filtration efficiency as the primary vendor selection criterion.
REACH chemical safety frameworks in Europe are mandating substance-by-substance exposure assessment for workplace respiratory hazards. Manufacturers must now document filter capacity against specific volatile organic compounds rather than generic vapor classes. German chemical processors and Dutch petrochemical refineries are responding by demanding cartridge labeling with standardized breakthrough indicators and digital batch traceability.
Hospital systems are consolidating respiratory protection procurement through group purchasing organizations that bundle fit-testing, medical evaluation, and cartridge replenishment into per-employee annual contracts. This displaces transactional spot-buying of disposable half-masks. The shift is most visible in Texas and Florida healthcare networks where integrated delivery systems cover both inpatient and home health worker populations.
Non-Powered Air Purifying Respirator Market Segmentation
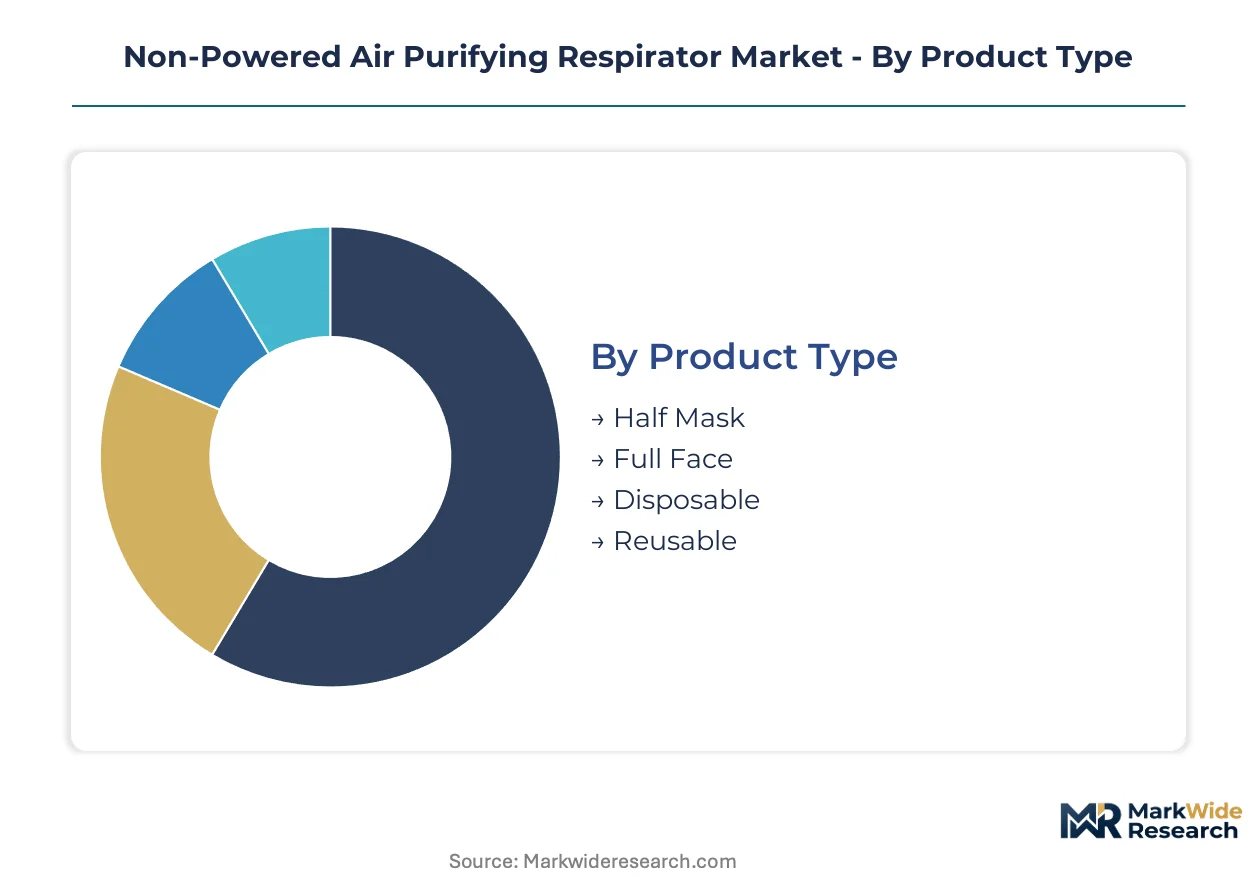
Respirator procurement patterns diverge sharply across use environments, with standalone industrial applications demanding durability and serviceability while embedded healthcare protocols prioritize disposable simplicity and rapid inventory turnover.
Product Type:
Standalone respiratory units dominate heavy industrial exposure settings, whereas embedded lightweight configurations integrate into broader PPE ensembles for intermittent hazard contact.
- Half Mask:These elastomeric facepieces seal across the nose and mouth, accommodating replaceable filter cartridges on dual port mounts. Demand clusters in construction crews across Texas and Florida where OSHA 29 CFR 1910.134 compliance mandates annual fit-testing programs that favor reusable hardware over disposable alternatives.
- Full Face:Integral eye protection and higher assigned protection factors characterize these designs, with five-point harness systems and speaking diaphragms for confined space communication. Chemical processing operators in Germany's Rhine-Ruhr industrial belt specify these units for simultaneous vapor and splash protection under REACH substance-specific exposure assessments.
- Disposable:Lightweight non-woven polypropylene constructions with fixed filtration media serve high-turnover environments where decontamination costs exceed replacement economics.
- Reusable:Silicone or thermoplastic elastomer facepieces withstand repeated cleaning and cartridge exchange, anchoring procurement in facilities with established respiratory protection programs and centralized maintenance capabilities.
Volume placements concentrate in Half Mask configurations; the faster expansion belongs to Full Face designs as multi-hazard workplaces proliferate.
Filter Type:
Cost tiering separates basic particulate capture from premium multi-threat architectures, with mid-range chemical cartridges occupying a narrowing band as combination media improve.
- Particulate:Mechanical and electrostatic capture mechanisms target dusts, mists, and fumes through meltblown polypropylene media rated to NIOSH 42 CFR 84 N95, N99, or N100 specifications. Agricultural operations in California's Central Valley deploy these filters for pesticide drift and harvest dust exposure during seasonal labor peaks.
- Chemical:Activated carbon beds adsorb specific gas and vapor hazards, with capacity determined by carbon type, weight, and impregnation chemistry. Demand from semiconductor fabrication facilities in South Korea requires specialty impregnations for acid gas and ammonia breakthrough protection.
- Combination:Stacked particulate and adsorption layers address simultaneous aerosol and vapor threats in single-cartridge architectures, reducing inventory complexity for maintenance departments.
- Organic Vapor:Petroleum-based activated carbon formulations target solvent vapors from hydrocarbon sources, with service life determined by contaminant concentration, humidity, and breathing rate.
Procurement volume tilts toward Particulate filters; Combination media are climbing the fastest as workplace hazard assessments increasingly identify multiple concurrent exposures.
Application:
Customer type segmentation reveals divergent buying behaviors, with institutional procurement teams negotiating multi-year service contracts while individual tradesmen favor spot purchases through distributor channels.
- Construction:Silica dust from concrete cutting, demolition debris, and spray foam insulation drives respirator deployment across residential and commercial building sites. Unionized trades in New York State mandate N95 minimum protection for members working with engineered stone, where crystalline silica content exceeds natural stone alternatives.
- Healthcare:N95 and P100 half-masks protect nursing staff and surgical support personnel from airborne pathogens during aerosol-generating procedures. Hospital systems in China's Jiangsu and Zhejiang provinces are expanding N95 inventory minimums following revised hospital-acquired infection protocols.
- Manufacturing:Metalworking fluids, welding fumes, and solvent vapors create multi-hazard environments requiring cartridge rotation schedules and changeout tracking systems.
- Agriculture:Seasonal pesticide application and grain handling operations generate intermittent high-concentration exposures where disposable units often outlast their economic service life.
Contract volume concentrates in Construction; Healthcare is gaining share fastest as infection control budgets expand in developing health systems.
End User:
Supply concentration varies by user sophistication, with industrial accounts demanding technical support and fit-testing services while general public sales flow through retail channels with minimal aftermarket attachment.
- Industrial Workers:Employers bear legal responsibility for respiratory protection program administration, medical clearance, and training documentation under OSHA and equivalent national frameworks. Petrochemical refineries along the US Gulf Coast operate dedicated on-site fit-testing facilities with quantitative PortaCount instrumentation.
- Healthcare Professionals:Institutional procurement through group purchasing organizations bundles hardware, consumables, and compliance services into per-employee annual contracts, displacing transactional purchasing.
- First Responders:Fire departments and hazardous materials teams require SCBA-compatible facepieces and rapid-donning capabilities for emergency response scenarios.
- General Public:Wildfire smoke events and pandemic preparedness have expanded retail availability of N95 disposables, though fit quality and user training remain inconsistent.
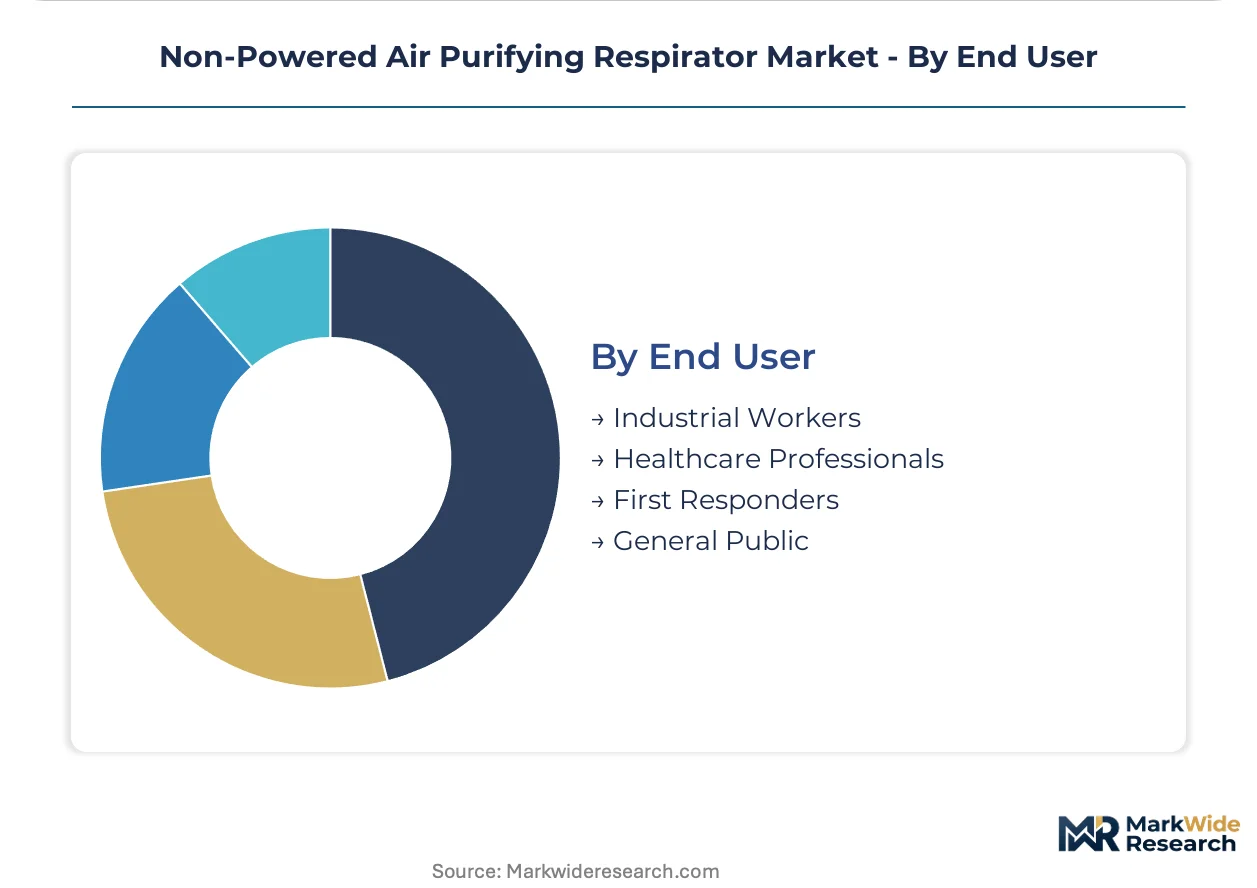
Shipment volume concentrates among Industrial Workers; Healthcare Professionals are expanding most quickly as hospital-acquired infection protocols tighten worldwide.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Filter media manufacturing clusters in China's Yangtze and Pearl River deltas supply raw materials to conversion facilities worldwide, while end-use demand concentrates in industrial corridors across multiple continents where respiratory protection regulations tighten.
United States
Petrochemical refineries along the Gulf Coast operate dedicated on-site fit-testing facilities with quantitative instrumentation. OSHA's Respiratory Protection Standard mandates written programs and annual fit-testing across industrial facilities. Construction crews in Texas deploy reusable half-masks for silica dust compliance as unionized trades mandate N95 minimums for engineered stone work.
Germany
Chemical processing operators in the Rhine-Ruhr industrial belt specify full-face units for simultaneous vapor and splash protection. REACH substance-specific exposure assessments now mandate cartridge labeling with standardized breakthrough indicators. Pharmaceutical cleanroom operators in Basel-adjacent facilities pilot electrospun nanofiber membranes to reduce changeout frequency.
China
Hospital systems in Jiangsu and Zhejiang provinces expand N95 inventory minimums following revised hospital-acquired infection protocols. The national pharmaceutical regulator tightens sterilization mandates for nursing staff protection. Domestic manufacturing capacity for meltblown polypropylene media scales in parallel with industrial worker populations across the Yangtze River Delta.
India
Developing health systems expand infection control budgets fastest among major economies. The country's national pharmaceutical regulator aligns hospital-acquired infection protocols with international standards. Healthcare procurement teams in metropolitan hospital networks negotiate group purchasing contracts bundling hardware and compliance services.
South Korea
Semiconductor fabrication facilities demand specialty impregnations for acid gas and ammonia breakthrough protection. The national industrial standards body enforces rigorous laboratory testing for filtration efficiency and breathing resistance. Electronics assembly workforce expansion creates first-time buyer populations in emerging industrial corridors.
Non-Powered Air Purifying Respirator Market Vendor Landscape
Top-tier vendors anchor premium positioning through integrated service bundles, while mid-tier specialists compete on cartridge interoperability and regional compliance expertise. The vendor base spans diversified industrial conglomerates with global distribution networks, dedicated respiratory protection houses with occupational health service partnerships, and regional fabricators serving price-sensitive construction markets. Three archetypes dominate: full-system integrators bundling gas detection and respiratory hardware; filter technology specialists advancing multi-layer media chemistry; and compliance service providers embedding fit-testing and medical evaluation into recurring contracts. Competitive moves center on strategic partnerships extending beyond hardware sales and portfolio diversification into connected compliance platforms.
Among diversified industrial technology providers, 3M, Honeywell International Inc., and MSA Safety Incorporated occupy positions exemplifying scale-driven distribution leverage and integrated safety system bundling. 3M leverages global aftermarket attach rates across industrial accounts. Honeywell International Inc. represents the conglomerate archetype spanning multiple protective equipment categories. MSA Safety Incorporated anchors North American demand through gas detection and respiratory system integration. These entities sit within the premium tier where recurring service revenue embeds into hardware procurement cycles.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| DuPont |
| MSA Safety Incorporated |
| Drägerwerk AG & Co. KGaA |
| Alpha Pro Tech |
| Delta Plus Group |
| Avon Protection |
| ILC Dover LP |
| Others |
Supply Flow & Price Mechanics
Electrospun nanofiber membrane adoption is compressing cartridge changeout frequency while concentrating filter media production in China's Yangtze River Delta, simultaneously reducing lifecycle costs for buyers and amplifying supplier pricing power among certified manufacturers. This technology transition rewards scale players with NIOSH and CE dual certifications while squeezing margin recovery from smaller regional fabricators lacking R&D amortization depth.
Pricing Analysis
Margin tightening in standard half-mask tiers reflects cartridge standardization and interoperability gains that commoditize basic particulate capture. Three-tier pricing structure across premium full-face systems, standard elastomeric half-masks, and economy disposable configurations separates buyers by program sophistication and compliance service bundling. Cost-down pressure on disposable N95 volumes accelerates because hospital group purchasing organizations consolidate procurement into annual per-employee contracts. Construction tradesmen spot-buying through distributor channels exhibit highest price sensitivity; petrochemical operators bundling gas detection and respiratory systems show lowest sensitivity due to integrated safety budget allocation.
Supply Chain Analysis
Direct-to-industrial channels handle multinational account demand while authorized distributor networks serve fragmented construction and agricultural buyers. Filter media manufacturing clusters in China, Germany, and the United States anchor upstream supply, with meltblown polypropylene and activated carbon beds drawing from petrochemical feedstocks concentrated in the US Gulf Coast and Middle East. Single-source vulnerability in electrostatic media production exposes buyers to Yangtze River Delta disruption risk from environmental compliance shutdowns or energy rationing. Distribution runs through integrated safety distributors with fit-testing service capabilities, privileging vendors with aftermarket attach rate infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as NIOSH certification timelines and R&D amortization requirements force sub-scale regional fabricators toward exit or acquisition. Filter cartridge standardization eliminates proprietary lock-in advantages, compressing returns for undifferentiated hardware-only suppliers.
For Market Incumbents: Anchor defensive positioning through backward integration into electrospun nanofiber membrane production and captive supply of meltblown media. Incumbents should deepen compliance service bundling to offset hardware margin compression from cartridge interoperability, leveraging existing fit-testing infrastructure as a switching cost against emerging entrants lacking PortaCount operator certification networks. For New Entrants and Emerging Players: Enter via telemedicine-integrated fit-testing platforms targeting distributed agricultural and construction workforces underserved by quantitative testing infrastructure. Vietnam and Indonesia manufacturing corridors offer first-time buyer populations lacking established supplier relationships, with electronics assembly and shipbuilding expansion creating demand for combination filter solutions without incumbent switching costs. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking respiratory protection program capabilities. Long-term viability hinges on service revenue attach rates rather than hardware shipment volumes. Investors should monitor NIOSH-EN regulatory harmonization progress as the critical inflection signal—convergence would elevate acquisition premiums for dual-certified manufacturers while stranding single-certificate assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media | Captive supply of electrospun nanofiber membranes insulates margins from Yangtze River Delta concentration risk. |
| Compliance Service Bundling | Annual fit-testing and medical evaluation contracts embed recurring revenue that survives hardware commoditization. |
| Telemedicine-Integrated Fit-Testing | Remote seal verification algorithms reduce compliance costs for distributed construction and agricultural workforces. |
| Dual Certification Investment | Simultaneous NIOSH 42 CFR 84 and EN 14387 approval expands addressable market across US and EU procurement teams. |
| Combination Filter R&D | Multi-layer architectures addressing particulate, organic vapor, and acid gas hazards reduce customer inventory complexity. |
Methodological Framework
Regulatory filings, customs trade databases, and hospital procurement records formed the secondary backbone, supplemented by primary interviews with respiratory protection program managers, biomedical engineers at hospital purchasing committees, industrial hygienists, and aftermarket service heads at integrated safety distributors. Bottom-up and top-down triangulation validated shipment estimates against fit-testing service revenue and filter cartridge replenishment patterns.
Bottom-up modeling built from product-type, filter-type, application, and end-user segmentation dimensions, with volume and value outputs cross-referenced against top-down macroeconomic indicators and industrial employment trends across the analysis window. CAGRs derived from regression analysis of historical certification timelines, regulatory enforcement intensity, and healthcare infection control budget expansion. Industry-specific forecast inputs included OSHA inspection frequency data and REACH substance-by-substance exposure assessment rollout pace.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden NIOSH certification backlog accumulation or electrostatic media supply disruption. Periodic stress-testing of base assumptions is recommended, particularly regarding harmonization between US and EU respiratory protection standards and the pace of hospital-acquired infection protocol adoption in developing health systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Shock Trouser Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safety and Eyewash Shower Market
Safety Equipment and Personal Protective Equipment (PPE)
Biometric Gun Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Edge Protector Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Smart PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Smart Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Law Enforcement Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia Pacific Gas Detector Market
Safety Equipment and Personal Protective Equipment (PPE)
Firefighter Tape Market