
 Disposable Protective Apparel Market | 2026-2036
Disposable Protective Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Protective Apparel Market Outlook
The EU Green Deal's textile sustainability targets is pivoting European healthcare procurement toward recyclable and bio-based disposable garments. DuPont de Nemours, Inc. anchors its position through advanced material science in microporous film laminates. Kimberly-Clark Worldwide, Inc. dominates hospital supply channels across North America with vertically integrated nonwoven production. Lakeland Industries, Inc. specializes in chemical-resistant coveralls for industrial end users.
Disposable protective apparel encompasses single-use garments engineered from spunbond-meltblown-spunbond (SMS) composites, polypropylene, polyethylene, or microporous film laminates, manufactured through extrusion and thermal bonding processes to achieve specific barrier properties against fluids, particulates, and chemical agents. These garments serve primarily to prevent cross-contamination between workers and hazardous environments in healthcare, industrial, and laboratory settings. Coveralls command the largest product volume due to full-body protection requirements in chemical handling and pharmaceutical manufacturing, while gowns capture premium pricing in surgical and infection control applications. SMS material formulations are displacing basic polypropylene in clinical settings where AAMI Level 3 and Level 4 liquid barrier ratings determine procurement eligibility.
OSHA enforces permissible exposure limits that mandate employer-provided protective equipment across U.S. manufacturing and healthcare facilities, while the FDA regulates surgical gowns and isolation gowns as Class I or Class II medical devices requiring 510(k) clearance for fluid barrier claims. The EU Medical Device Regulation (MDR) imposes stricter clinical evaluation and post-market surveillance obligations on apparel suppliers serving European healthcare systems. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York that threaten to impose end-of-life collection costs on single-use garment manufacturers.
Market Dynamics
Hospital infection control protocols are hardening around single-use garment mandates, while OSHA and EU MDR compliance timelines compress product development cycles for manufacturers serving regulated end-uses.
Growth Catalysts
- OSHA Permissible Exposure Limits:U.S. manufacturing facilities must provide employer-funded protective equipment, creating institutional procurement pull across chemical handling and pharmaceutical operations.
- SMS Composite Advancement:Spunbond-meltblown-spunbond laminates achieve AAMI Level 4 liquid barrier ratings, displacing basic polypropylene in surgical and isolation gown applications where fluid protection determines contract eligibility.
- China Hospital Expansion:Provincial healthcare infrastructure investment concentrates procurement volume in tertiary care facilities adopting international infection control standards.
Market Restraints
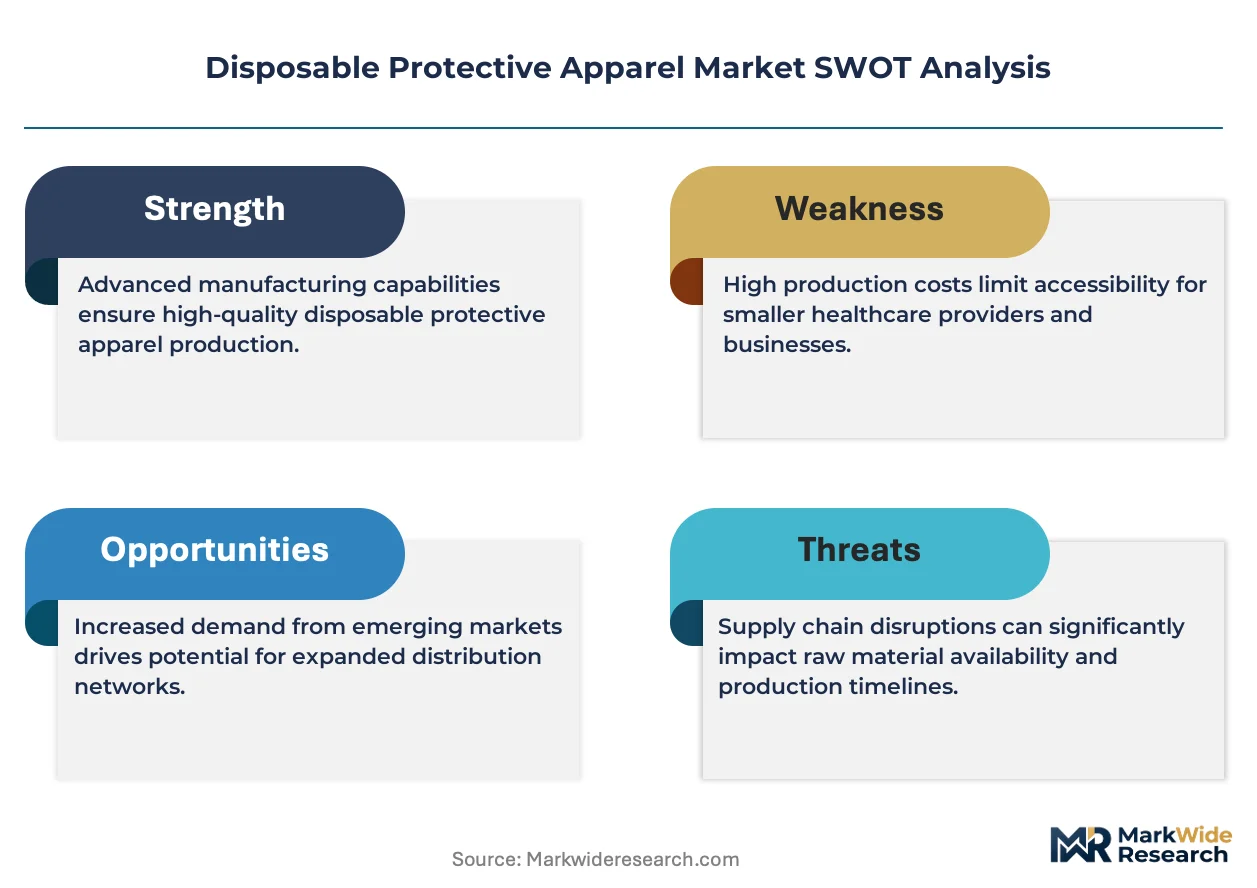
- Polypropylene Feedstock Volatility:Propylene monomer prices track naphtha and natural gas liquids, compressing margin stability for nonwoven converters without backward integration into resin supply.
- EU Extended Producer Responsibility:California and New York state legislation threatens to impose end-of-life collection and recycling costs on single-use garment manufacturers, raising total cost of ownership calculations.
- Reusable Garment Substitution:Industrial laundries and plasma sterilization systems compete for chemical plant and automotive manufacturing accounts where barrier durability permits multiple-use cycles.
Strategic Opportunities
- India Healthcare Infrastructure:Central government hospital procurement programs and private chain expansion create underpenetrated demand for AAMI-rated surgical gowns as accreditation standards tighten.
- Bio-Based Material Convergence:Polylactic acid and cellulose-derived nonwovens combined with compostable film laminates address EU Green Deal textile sustainability targets in European healthcare procurement.
- E-Procurement Platform Penetration:Group purchasing organizations and hospital supply aggregators consolidate vendor selection, creating channel access for certified manufacturers outside legacy distribution relationships.
Industry Challenges
- 510(k) Clearance Timelines:FDA fluid barrier claims for surgical gowns require substantial equivalence demonstrations, extending product launch schedules and freezing R&D investment returns.
- Barrier Testing Expertise Scarcity:AAMI and ASTM test method proficiency for synthetic blood penetration and viral resistance limits quality assurance staffing pools available to mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Protective Apparel Market |
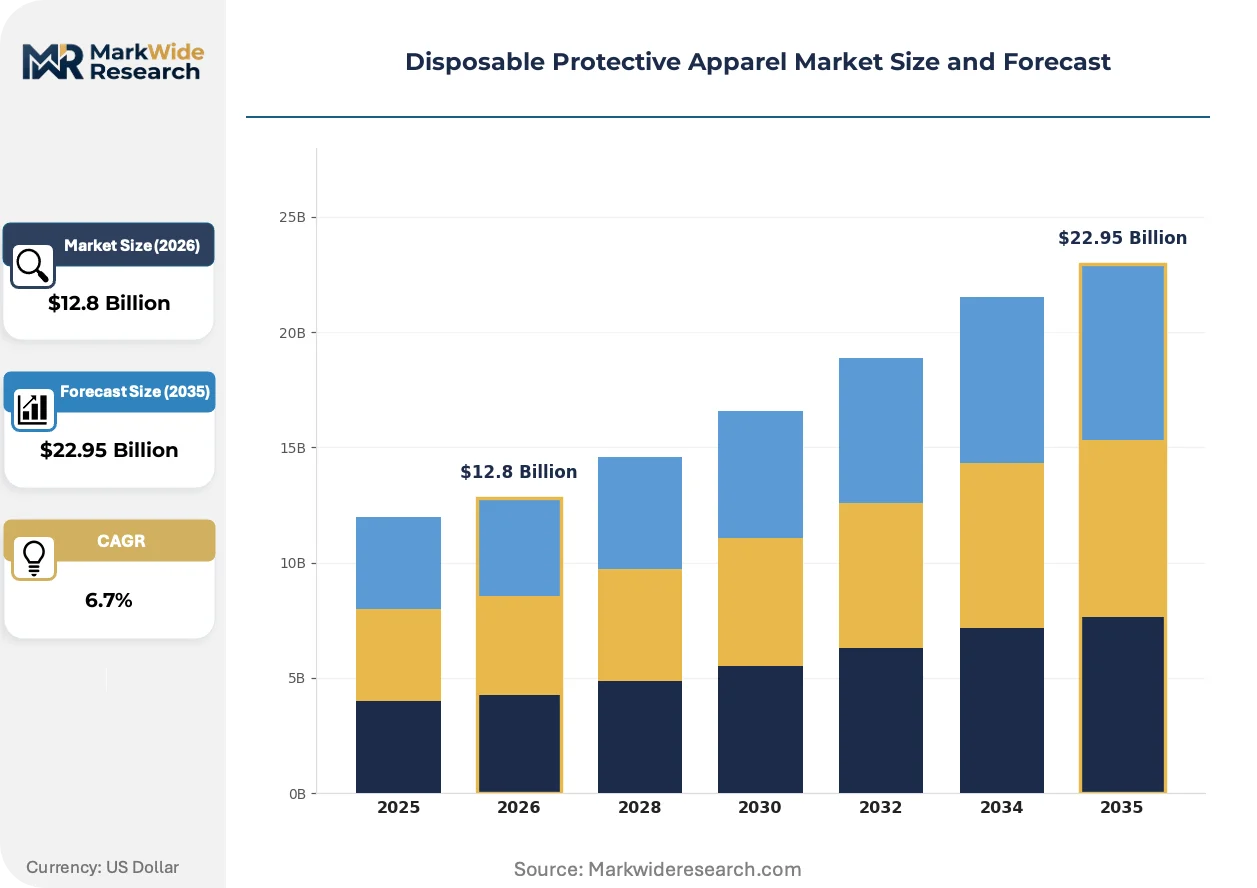
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gowns, Coveralls, Aprons, Caps Material: Polypropylene, Polyethylene, SMS, Microporous Film End User: Healthcare, Industrial, Laboratory, Food Service Application: Infection Control, Hazardous Material Handling, Cleanroom, General Protection |
| Companies Covered | 3M Company, DuPont de Nemours, Inc., Kimberly-Clark Worldwide, Inc., Lakeland Industries, Inc., Ansell Ltd., Honeywell International Inc., Alpha Pro Tech, Ltd., Cardinal Health, International Enviroguard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Protective Apparel Market Strategic Shifts
Material science breakthroughs and regulatory compliance automation are compressing product lifecycles while reshaping how protective apparel is specified, tested, and procured across healthcare and industrial channels.
Microporous film laminates bonded to spunbond nonwovens deliver breathable chemical resistance exceeding polyethylene coatings. Pharmaceutical cleanroom operators and chemical handling facilities in Germany and the United States are specifying these composites for ISO Class 5 and Class 6 environments. This construction is rewriting barrier-to-breathability tradeoffs that previously forced buyers to choose between comfort and protection.
EU Medical Device Regulation post-market surveillance obligations now require clinical evaluation documentation and periodic safety updates for gowns classified as Class II devices. European notified bodies have extended review queues, forcing manufacturers to pre-position technical files ahead of contract tenders. Surgical gown suppliers serving EU hospital systems are absorbing compliance costs into premium pricing tiers while consolidating product ranges to reduce surveillance burden.
Hospital supply chain directors are consolidating vendor panels around dual-source strategies that balance cost control with pandemic-era disruption lessons. Group purchasing organizations in the United States now mandate AAMI Level 3 minimum ratings for standard isolation gowns, displacing unrated commodity alternatives. This specification hardening concentrates procurement volume among manufacturers with vertically integrated testing and certification capabilities.
Disposable Protective Apparel Market Segmentation
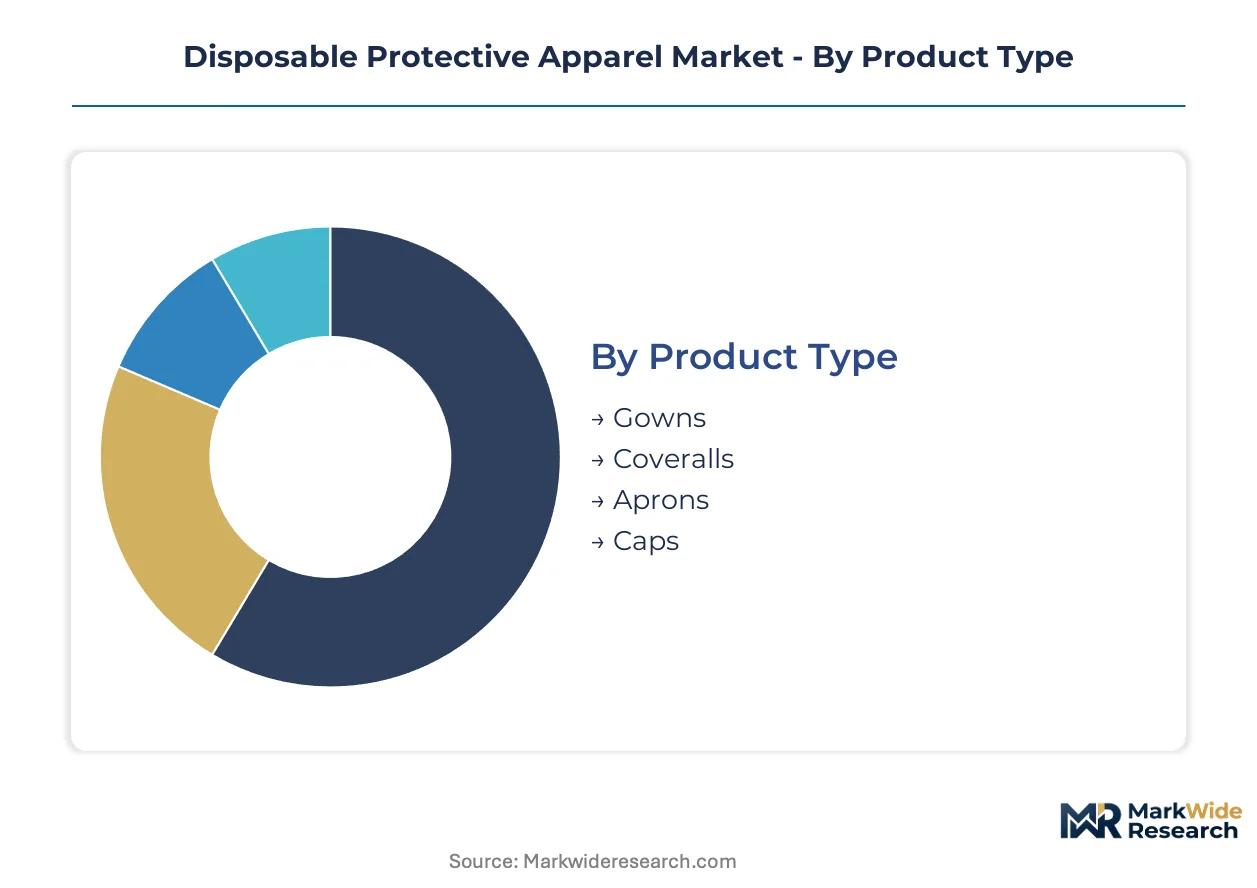
Segmentation in disposable protective apparel reveals how procurement specifications diverge across regulatory environments and end-use risk profiles. Material selection and barrier rating requirements create distinct competitive arenas where technical certification, not commodity pricing, determines contract eligibility.
Product Type:
Buyer differentiation hinges on body coverage requirements and fluid exposure risk levels.
- Coveralls:Full-body garments constructed from microporous film laminates or SMS composites deliver ISO Class 5-6 particulate protection for pharmaceutical cleanrooms and chemical handling operations in Germany and the United States. OSHA permissible exposure limits for chemical manufacturing facilities mandate employer-funded procurement, institutionalizing volume demand.
- Gowns:Surgical and isolation variants engineered with spunbond-meltblown-spunbond laminates achieve AAMI Level 3 and Level 4 liquid barrier ratings required for operating theater accreditation in tertiary care hospitals across China and the United States. FDA 510(k) clearance for fluid barrier claims creates regulatory moats around certified suppliers.
- Aprons:Waist-tied polyethylene or polypropylene front protection serves food service and light industrial applications where splash resistance suffices without full coverage requirements.
- Caps:Bouffant and surgical head coverings from spunbond nonwovens prevent particulate shedding in cleanroom and surgical environments; compliance with hospital infection control protocols drives replacement frequency.
Volume sits with coveralls; growth tilts toward gowns.
Material:
Barrier-to-breathability tradeoffs and regulatory compliance tiers determine material selection authority.
- SMS:Spunbond-meltblown-spunbond trilaminate construction achieves AAMI Level 4 synthetic blood penetration resistance while maintaining moisture vapor transmission rates above 2500 g/m²/24hr, displacing basic polypropylene in surgical gown specifications where liquid barrier ratings determine procurement eligibility in U.S. hospital systems.
- Microporous Film:Polyethylene film bonded to spunbond polypropylene substrates delivers breathable chemical resistance exceeding 60 minutes against ASTM F739 test chemicals, commanding specification in German pharmaceutical cleanrooms and U.S. chemical manufacturing facilities where OSHA mandates employer-provided protection against hazardous material exposure.
- Polypropylene:Spunbond monolayer construction offers economical particulate and limited fluid protection for general isolation and visitor gown applications where AAMI ratings are not contractually required.
- Polyethylene:Cast film or coated nonwoven constructions provide impermeable liquid barriers for chemical splash protection and food service hygiene at lower unit costs than laminated alternatives.
Procurement volume concentrates in SMS for healthcare; microporous film captures premium industrial positioning.
End User:
Regulatory enforcement intensity and accreditation standards create divergent purchasing behaviors across sectors.
- Healthcare:Hospital infection control protocols hardening around single-use garment mandates drive demand for AAMI-rated gowns and coveralls; EU MDR post-market surveillance obligations and FDA 510(k) requirements compress vendor qualification timelines for suppliers serving tertiary care facilities in the United States and Germany.
- Industrial:Chemical manufacturing, automotive painting, and electronics assembly operations specify OSHA-compliant protective apparel with documented permeation resistance against specific chemical agents; permissible exposure limit enforcement creates institutional procurement pull across U.S. manufacturing facilities.
- Laboratory:Research and diagnostic facilities require biosafety level-appropriate garments combining particulate filtration with chemical resistance; BSL-3 and BSL-4 containment protocols in U.S. federal research centers mandate validated barrier performance.
- Food Service:FDA Food Code compliance and HACCP protocol adherence drive replacement frequency for aprons, sleeves, and hair containment products in commercial kitchen and processing environments where cross-contamination prevention is operationally critical.
Healthcare commands revenue concentration; industrial applications show steepest expansion trajectory as OSHA enforcement tightens.
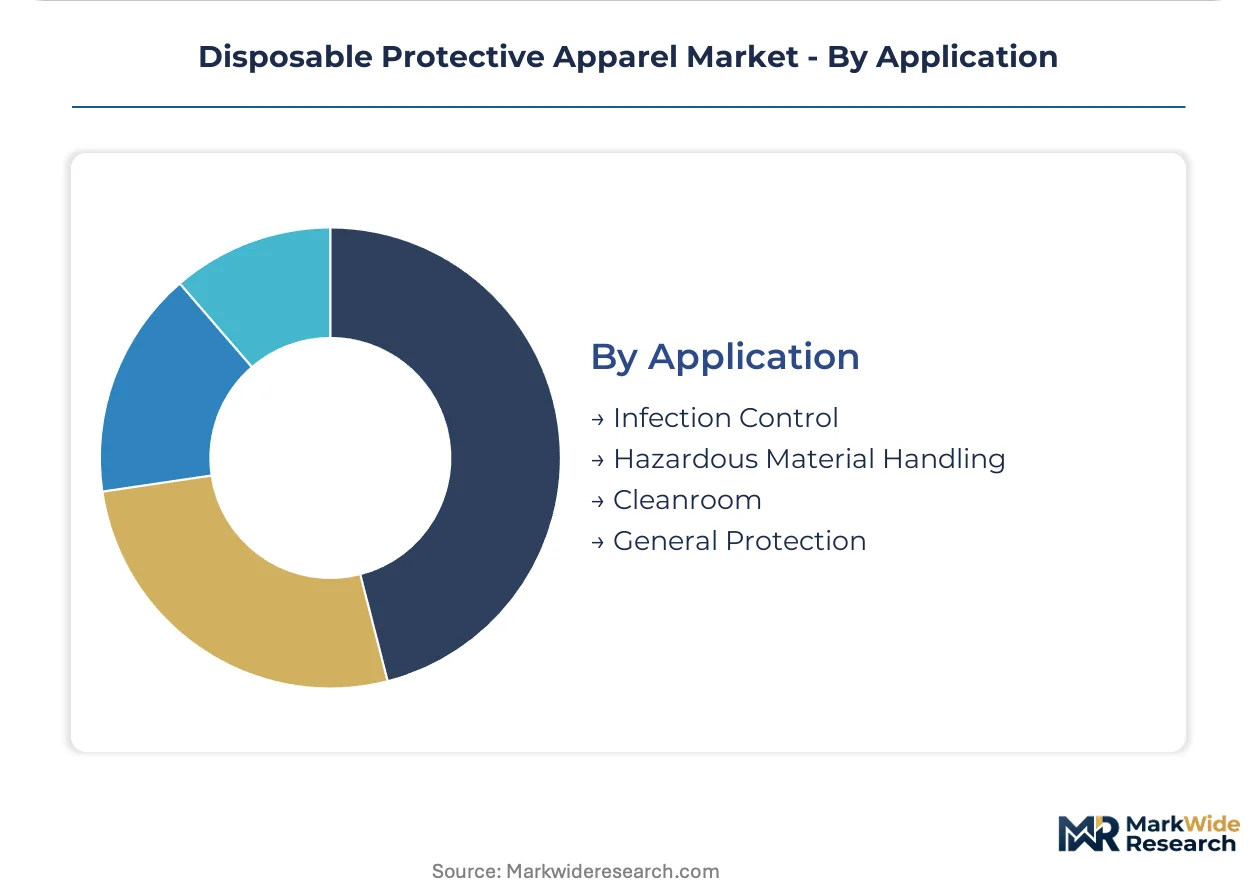
Application:
Risk severity and regulatory scrutiny levels determine specification stringency and pricing tolerance.
- Infection Control:Surgical site infection prevention protocols in U.S. and Chinese hospitals mandate AAMI Level 3 minimum ratings for isolation gowns; group purchasing organizations have displaced unrated commodity alternatives through specification hardening that concentrates procurement among vertically integrated manufacturers with captive testing capabilities.
- Hazardous Material Handling:Chemical plant operators and pharmaceutical manufacturers specify ASTM F739-tested garments with documented permeation breakthrough times against specific industrial chemicals; OSHA enforcement in U.S. manufacturing creates compliance-driven demand impervious to cost-cutting pressures.
- Cleanroom:ISO 14644-1 Class 5-8 environments in semiconductor fabrication and sterile pharmaceutical manufacturing require low-linting garments with electrostatic discharge properties; particle shedding specifications in German and U.S. facilities exclude commodity nonwoven alternatives.
- General Protection:Visitor gowns, basic isolation, and non-critical applications accept unrated polypropylene garments where barrier performance is not contractually specified; price sensitivity dominates purchasing decisions in this undifferentiated tier.
Contract value clusters in infection control; specification expansion is gaining share fastest in hazardous material handling as industrial safety enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European demand for chemical-resistant protective apparel, while hospital procurement clusters in the United States, China, and Germany concentrate global volume.
United States
Hospital infection control protocols and OSHA enforcement drive institutional procurement across tertiary care facilities. The FDA regulates surgical gowns as Class I or Class II medical devices requiring 510(k) clearance for fluid barrier claims. Houston's petrochemical complex and the Boston-Washington healthcare corridor generate concentrated demand for both industrial and clinical protective garments.
China
Provincial healthcare infrastructure investment and pharmaceutical manufacturing expansion create dual demand streams. The National Medical Products Administration enforces GB standards for medical protective equipment while tightening post-market surveillance. Shanghai's Pudong district and the Yangtze River Delta pharmaceutical cluster dominate high-specification garment procurement.
Germany
Pharmaceutical cleanroom operations and automotive painting facilities specify ISO Class 5-6 protective apparel with documented barrier performance. The EU Medical Device Regulation imposes clinical evaluation and post-market surveillance obligations on gown suppliers serving European healthcare systems. The Rhine-Main and Stuttgart industrial regions concentrate chemical-resistant coverall demand from BASF and Merck manufacturing sites.
India
Central government hospital procurement programs and private healthcare chain expansion generate underpenetrated demand for AAMI-rated surgical gowns. The Central Drugs Standard Control Organization tightens accreditation standards for medical device imports. Maharashtra's pharmaceutical manufacturing belt around Mumbai and Pune drives specification-grade protective apparel adoption.
Japan
Semiconductor fabrication and biosafety laboratory operations require low-linting garments with electrostatic discharge properties. The Ministry of Economy, Trade and Industry enforces JIS standards for industrial protective equipment. The Kansai region's Osaka-Kyoto pharmaceutical cluster and Kyushu's semiconductor fabs concentrate premium protective apparel procurement.
Disposable Protective Apparel Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification capability and material science differentiation. The market structures around three tiers: multinational conglomerates with vertically integrated nonwoven production, mid-scale specialists with captive testing laboratories, and regional converters dependent on outsourced resin supply. Two competitive moves dominate: backward integration into SMS composite manufacturing to secure AAMI rating consistency, and strategic partnerships with group purchasing organizations to lock hospital supply channel access.
Within the multinational conglomerate tier, DuPont de Nemours, Inc. and Kimberly-Clark Worldwide, Inc. exemplify divergent strategic positions. DuPont anchors premium industrial positioning through advanced material science capabilities, while Kimberly-Clark occupies a position across hospital supply channel dominance in North America. Lakeland Industries, Inc. represents the specialist archetype, sitting within chemical-resistant coverall segments where ASTM F739 testing proficiency creates qualification barriers.
| Leading Market Players |
|---|
| 3M Company |
| DuPont de Nemours, Inc. |
| Kimberly-Clark Worldwide, Inc. |
| Lakeland Industries, Inc. |
| Ansell Ltd. |
| Honeywell International Inc. |
| Alpha Pro Tech, Ltd. |
| Cardinal Health |
| International Enviroguard |
| Others |
Value Chain & Pricing Dynamics
Propylene monomer spot prices on the US Gulf Coast and Rotterdam exchanges cascade through spunbond-meltblown-spunbond composite converters, stratifying final garment pricing across AAMI certification tiers that hospital procurement committees use to screen vendor eligibility.
Pricing Analysis
AAMI barrier rating achievement anchors value-based pricing, with Level 4 surgical gowns commanding substantial premiums over unrated polypropylene isolation alternatives due to FDA 510(k) clearance investments and validated viral penetration resistance. Certification grade and captive testing capability serve as the primary price differentiation drivers, while polypropylene feedstock volatility is compressing margins for non-integrated converters without resin supply control. Cost-conscious long-term care facilities and visitor screening programs exhibit highest price sensitivity, whereas tertiary care hospitals in Germany and the United States prioritize barrier performance over unit economics.
Supply Chain Analysis
Spunbond nonwoven supply rests on petrochemical complexes concentrated in the United States, China, and Saudi Arabia, with meltblown layer production drawing from specialized resin grades subject to pharmaceutical-grade purity specifications. Polypropylene pellet, calcium carbonate masterbatch, and proprietary bonding agents constitute the critical input trinity, while single-source dependence on German and Japanese meltblown equipment manufacturers creates procurement vulnerability for mid-scale converters. Distribution runs through group purchasing organizations and hospital supply aggregators that consolidate vendor panels around dual-source qualification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SMS laminate technology is displacing basic polypropylene across infection control applications, compressing product lifecycles for legacy garment architectures while rewarding manufacturers with integrated composite production.
For Market Incumbents: Cement AAMI Level 4 rating consistency through backward integration into meltblown web production, eliminating batch-to-batch barrier variation that disqualifies competitors from GPO contracts. Lock hospital channel access through multi-year supply agreements with penalty clauses for stockout events, insulating against emerging regional converters in India and Southeast Asia. For New Entrants and Emerging Players: E-procurement platform certification offers the most penetrable route for qualified manufacturers outside legacy distribution relationships, bypassing incumbent-controlled GPO gatekeeping. Target India's central government hospital procurement programs where AAMI standard adoption is tightening faster than domestic supply capacity can respond, positioning on cost-competitive SMS alternatives to imported premium brands. For Investors and Strategic Acquirers: The window for entry favors mid-scale specialists with captive ASTM F739 testing laboratories and established chemical-resistant coverall positions in OSHA-regulated industrial segments. Watch for EU MDR notification body queue lengths as the inflection signal—extended review timelines will force consolidation among European gown suppliers unable to absorb compliance cost burdens independently.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SMS Composite Manufacturing | In-house meltblown production secures AAMI rating consistency for surgical gown contracts. |
| Group Purchasing Organization Partnership | Dual-source qualification with Premier and Vizient locks access to US hospital procurement volume. |
| Bio-Based Material Certification | Polylactic acid nonwoven validation addresses EU Green Deal textile sustainability procurement mandates. |
| ASTM F739 Testing Laboratory Investment | Captive permeation testing capability creates qualification barriers in chemical-resistant coverall segments. |
| India Manufacturing Footprint Establishment | Domestic production near Maharashtra pharmaceutical belt reduces landed cost for central government tenders. |
Study Parameters
Independent corroboration across hospital procurement managers, GPO contracts specialists, nonwoven technical directors, and OSHA compliance officers underwrites the qualitative findings, with secondary validation drawing from FDA 510(k) clearance databases, EU MDR notified body registers, and customs trade records for polypropylene resin and spunbond fabric shipments. Bottom-up demand modeling across end-use segments triangulates against top-down market sizing from resin consumption and garment production capacity estimates.
Rate-of-change decomposition across the projection horizon segments volume trajectories by product type, material formulation, end-user sector, and regional regulatory cluster, with CAGR derivation anchored in propylene monomer price elasticity, hospital infrastructure investment pipelines, and industrial safety enforcement intensity indices. Modeled inputs include AAMI standard adoption curves, EU MDR compliance cost absorption rates, and India healthcare accreditation tightening schedules.
The model holds under stable polypropylene feedstock pricing and continued OSHA permissible exposure limit enforcement; deviation in naphtha-cracker margin collapse or federal regulatory rollback would shift volume and value projections. Feedstock volatility, notification body capacity constraints, and state-level extended producer responsibility legislation comprise the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Machine Safeguarding Solution Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Power Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium Motorcycle Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Law Enforcement Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Smart PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Shock Trouser Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Surgical Mask and Respirators Market