
 In Room Safes Market | 2026-2036
In Room Safes Market Size, Share, and Industry Trends Forecast 2026-2036
In Room Safes Market Analytics
Buyer concentration across the hospitality sector is broadening as boutique hotel chains and serviced apartment operators join established luxury brands in specifying electronic in-room safes. ASSA ABLOY Hospitality leverages its electronic lock ecosystem to bundle safe procurement with access control contracts. Safemark Systems anchors the North American hotel supply channel through direct-installation service agreements with major property management groups. Gunnebo AB competes in Europe with steel-construction safes certified to national burglary-resistance grades.
An in-room safe is a lockable security container installed within guest accommodations to protect valuables, typically constructed from cold-rolled steel with electronic keypad or biometric entry mechanisms and bolt-down mounting hardware. The unit serves the commercial purpose of reducing property liability exposure while supporting guest satisfaction metrics tracked by hospitality operators. Electronic keypad safes occupy the largest volume share across the Type dimension, though Smart-connected units with audit-trail capability command the highest per-unit margins. Steel dominates the Material segment due to fire-resistance ratings required by hotel insurers, while Alloy variants gain share in cruise ship installations where weight constraints override cost considerations.
Underwriters Laboratories and the European Committee for Standardization shape product compliance through burglary-resistance and fire-endurance testing protocols that determine insurance premium structures for hospitality operators. The EU Green Deal and REACH chemical restrictions increasingly influence steel finishing processes and electronic component sourcing across manufacturing supply chains. Stakeholders must monitor how smart safe integration with property management platforms alters procurement criteria and service revenue models.
Market Dynamics
Smart safe integration with property management platforms is restructuring procurement criteria across hospitality chains, compressing vendor selection cycles while elevating software compatibility requirements alongside physical security specifications.
Growth Catalysts
- EU Green Deal compliance mandates:REACH chemical restrictions on steel finishing processes are accelerating manufacturer investment in water-based coating technologies, creating first-mover certification advantages for compliant suppliers.
- Biometric access adoption:Premium resort properties in Thailand and Vietnam are specifying fingerprint-enabled safes as standard amenities, elevating guest security expectations across Southeast Asian hospitality.
- Hotel construction pipelines:Indonesia's hospitality development zones are driving concentrated demand for electronic keypad units with audit-trail capability in new-build properties.
Market Restraints
- Cold-rolled steel price volatility:Input cost fluctuations for fire-rated steel sheet constrain margin stability for manufacturers serving price-sensitive mid-tier hotel segments.
- Electronic component supply concentration:Semiconductor sourcing dependencies in East Asian foundries create delivery timeline risks for keypad and biometric module assembly.
- Legacy mechanical safe substitution:Budget hostel operators in emerging markets continue specifying key-entry units, limiting premium electronic safe penetration in the lowest accommodation tiers.
Strategic Opportunities
- Cruise ship weight-constrained applications:Aluminum alloy safe construction for maritime hospitality represents an underpenetrated niche where fire-rating trade-offs enable significant fuel cost savings.
- Remote monitoring convergence:Integration of IoT connectivity with housekeeping management systems creates new recurring revenue streams through subscription-based audit and maintenance services.
- Serviced apartment expansion:Extended-stay operators in Vietnam are specifying residential-grade safes with larger internal volumes, diverging from traditional hotel form factors.
Industry Challenges
- Cybersecurity certification complexity:Smart-connected safes must satisfy overlapping hospitality data protection standards and electronic lock encryption protocols, extending product validation timelines.
- Legacy PMS integration friction:Property management software from established vendors lacks standardized APIs for safe audit data, requiring costly custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Room Safes Market |
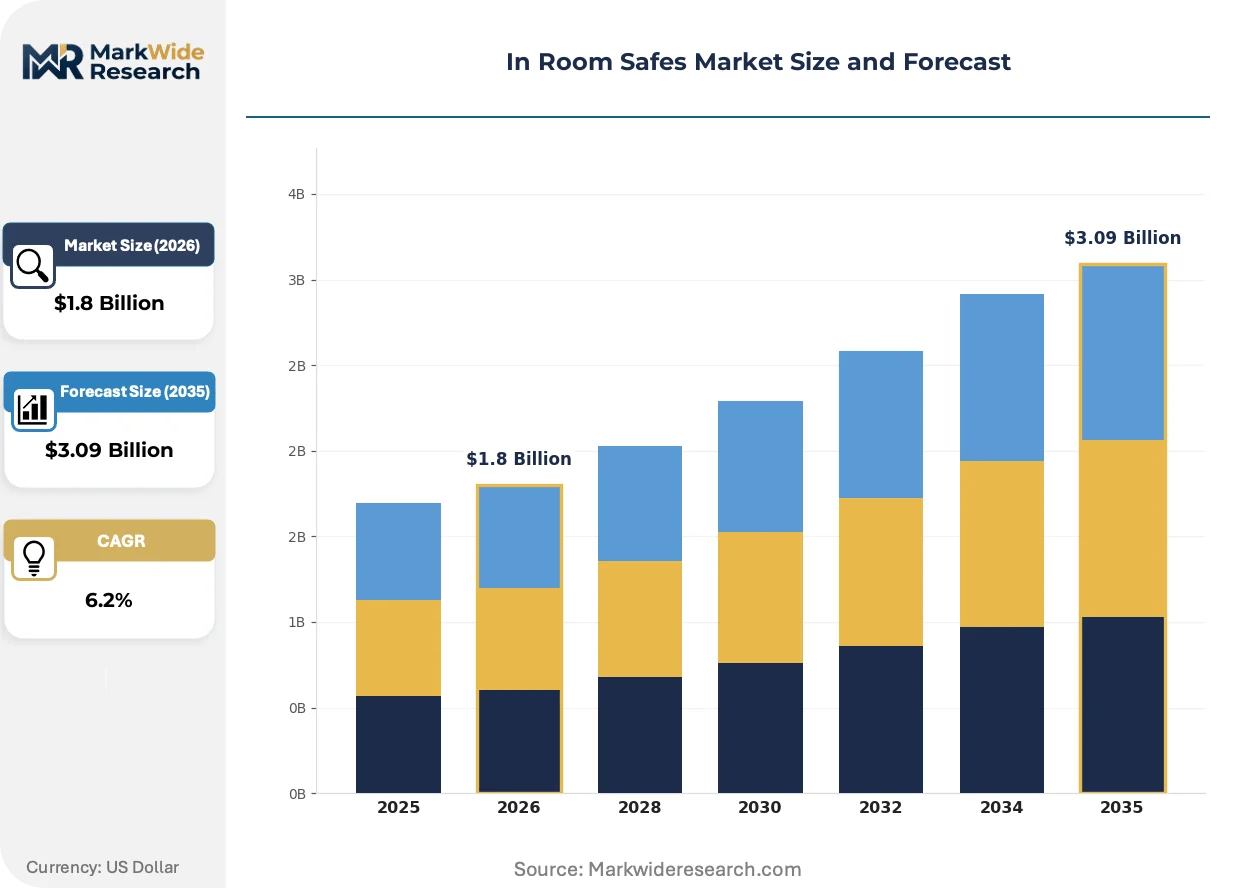
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.09 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electronic, Keypad, Manual, Smart Material: Steel, Plastic, Alloy, Aluminum End User: Hotels, Resorts, Hospitals, Cruise Ships Installation: Built-in, Portable, Wall-Mounted, Floor-Mounted |
| Companies Covered | Safemark Systems, ASSA ABLOY Hospitality, Global Safe Corporation, Indel B, Gunnebo AB, Dometic Group, Onity Inc., JVD Group, Minibar Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Room Safes Market Evolving Landscape
Safe hardware architecture is fragmenting into interoperable subsystems, enabling hospitality operators to upgrade biometric modules or connectivity features without full unit replacement. This componentization is compressing capital refresh cycles while expanding aftermarket service attach rates.
Biometric sensor technology is modularizing across the product stack. Fingerprint recognition modules now function as swappable cartridges within steel enclosures. Mid-scale hotel chains in Malaysia and the Philippines are adopting this format to phase upgrades across property portfolios. The approach is modularizing vendor relationships, allowing operators to source biometric engines separately from safe chassis manufacturers.
REACH chemical restrictions are forcing reformulation of powder-coat finishing processes across European manufacturing facilities. ECHA substance candidate list updates are disqualifying legacy chromate pretreatments used for corrosion resistance. Fire-rated steel safe producers are responding with trivalent chromium and zirconium-based alternatives, though these require requalification under Underwriters Laboratories burglary-resistance protocols.
Specification authority is migrating from procurement departments to IT directors as connected safes join broader access control ecosystems. Hotel operators in Thailand are bundling safe connectivity with electronic lock and energy management contracts, consolidating vendor relationships. This behavioral shift is visible most acutely in new-build properties where infrastructure decisions precede individual equipment purchases.
In Room Safes Market Segmentation
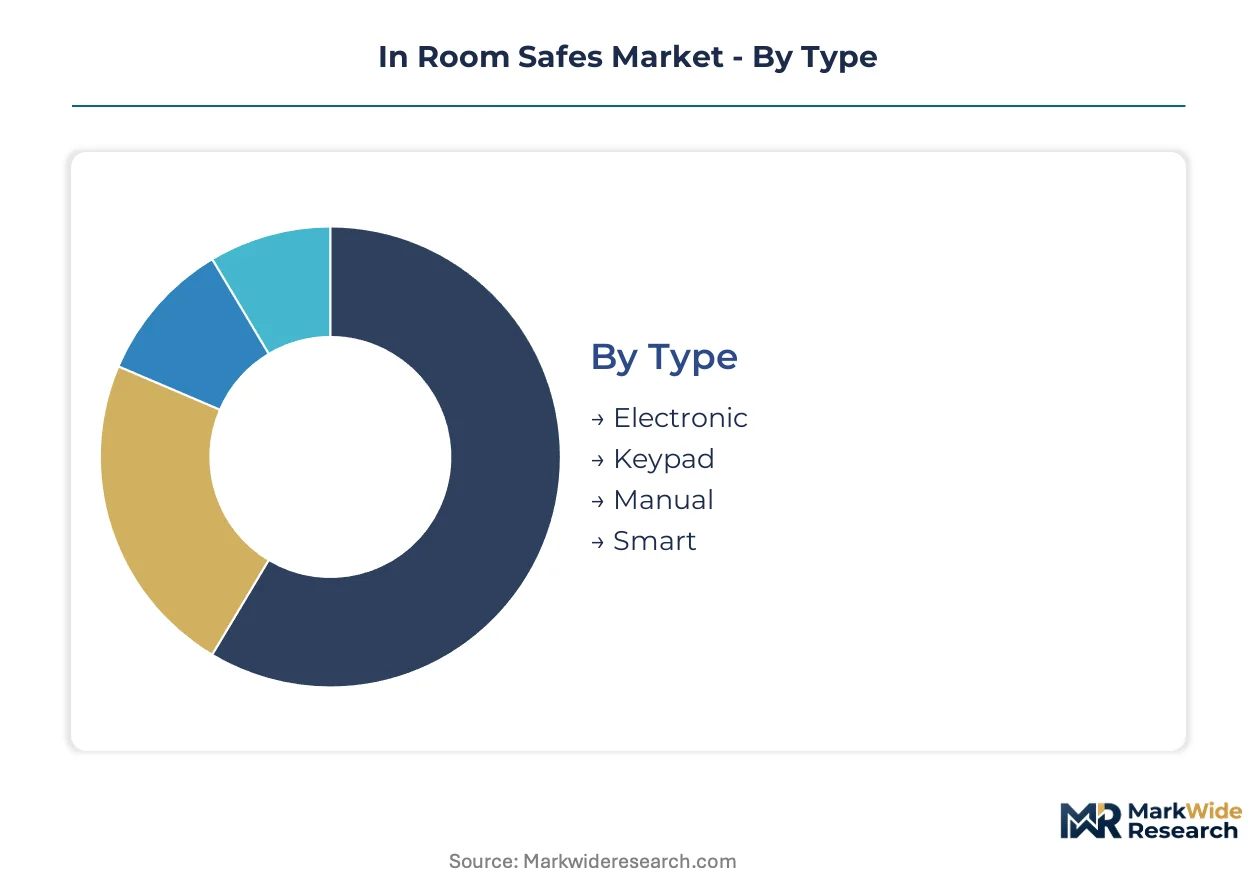
Segmentation in the in-room safes market reveals how procurement criteria fragment across hospitality asset classes and installation constraints. Understanding these divisions exposes where margin concentrates and which specifications are becoming non-negotiable in contract negotiations.
Type:
Supply concentration among electronic lock manufacturers is pushing safe technology toward integrated access ecosystems rather than standalone units.
- Electronic:Units with motorized locking bolts and LED feedback dominate new-build hotel specifications across Thailand and Vietnam. Hospitality procurement teams bundle these with door lock contracts from ASSA ABLOY and competing access control vendors, compressing standalone safe supplier margins.
- Keypad:Numeric entry systems with audit-trail memory represent the volume anchor for mid-tier properties in Indonesia where construction activity remains elevated. These units balance guest convenience against capital cost constraints in properties targeting three-star ratings.
- Manual:Traditional key-entry mechanisms persist in budget hostel segments across emerging markets where electronic infrastructure is unreliable or capital budgets are minimal.
- Smart:IoT-enabled units with remote monitoring capability command premium positioning in Singapore and Dubai luxury properties where integration with property management platforms drives procurement decisions.
Today's leader: Electronic. Tomorrow's challenger: Smart.
Material:
Cost tier differentiation separates insurance-grade specifications from weight-optimized alternatives in maritime applications.
- Steel:Cold-rolled construction with fire-resistance certification anchors the premium tier, required by underwriters for properties in the US and EU. REACH-compliant finishing processes are becoming a procurement filter for European hospitality chains.
- Alloy:Aluminum-magnesium blends reduce unit weight by 40% for cruise ship installations where fuel economics override raw material cost premiums. Royal Caribbean and Carnival procurement specifications increasingly mandate this construction.
- Plastic:Polymer housings serve temporary hospitality installations and budget serviced apartments where theft resistance requirements are minimal.
- Aluminum:Pure aluminum extrusions occupy a niche in ultra-lightweight applications for private aviation and yacht hospitality segments.
Steel commands the premium tier. Alloy is gaining share fastest in maritime hospitality.
End User:
Application-specific requirements are fragmenting product architecture across asset classes with diverging security and connectivity needs.
- Hotels:Urban full-service properties in Bangkok and Jakarta drive demand for audit-capable electronic units integrated with housekeeping management systems. These installations prioritize liability reduction over absolute burglary resistance.
- Cruise Ships:Maritime operators specify weight-constrained alloy construction with corrosion-resistant finishes for salt-air environments. Vessel refit cycles create predictable replacement demand distinct from land-based hospitality.
- Resorts:Premium beach and mountain properties in Vietnam and the Philippines emphasize biometric access as a guest amenity differentiator, elevating security expectations.
- Hospitals:Healthcare facilities in the US specify medication safes with dual-access protocols and temperature monitoring, diverging from hospitality-focused product lines.
Hotels anchor volume demand. Cruise ships represent the steepest expansion trajectory for specialized suppliers.
Installation:
Volume concentration favors built-in specifications in new construction, while retrofit activity sustains demand for flexible mounting alternatives.
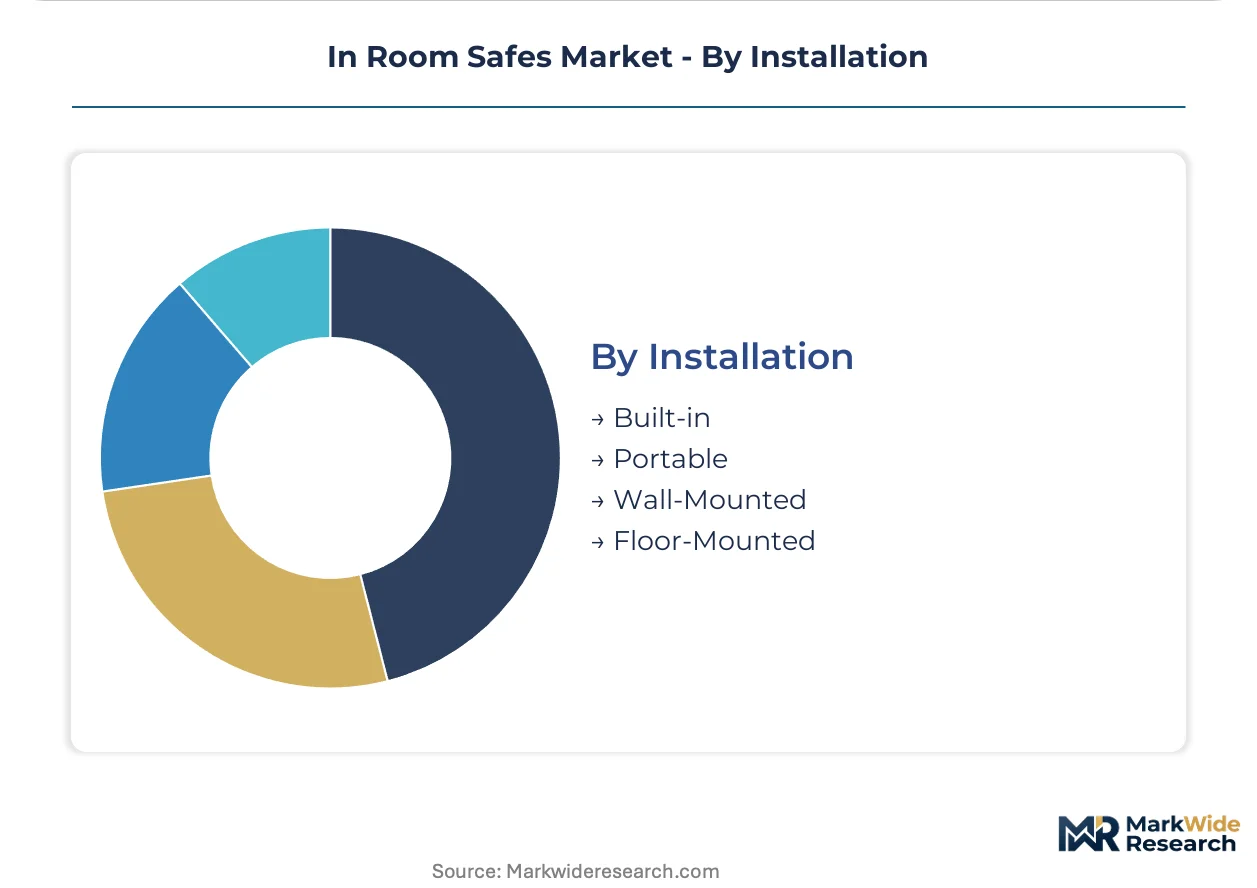
- Built-in:Recessed wall installations dominate luxury hotel new-builds in Indonesia and Thailand where architectural integration supports premium positioning. These units require coordination with general contractors during rough-in phases.
- Portable:Freestanding units with tethering hardware serve extended-stay serviced apartments in Vietnam where guest turnover and furniture reconfiguration are frequent.
- Wall-Mounted:Surface-mounted steel enclosures address retrofit applications in European historic properties where structural modification is restricted.
- Floor-Mounted:Bolt-down configurations anchor high-value storage in resort villas and private hospital suites where single-point security is insufficient.
Built-in specifications lead new construction. Portable units are expanding most quickly in serviced apartment conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand and Vietnam are pulling ahead of Indonesia in biometric-enabled safe installations, while the United States and Germany maintain stricter certification requirements that sustain premium steel construction demand.
Thailand
Bangkok hospitality construction and Phuket resort expansions are driving fingerprint-enabled safe specifications. The country's Ministry of Industry enforces TISI standards for electronic security equipment. Pattaya and Hua Hin hotel clusters are retrofitting legacy key-entry units with modular biometric cartridges.
Vietnam
Da Nang and Nha Trang resort developments are specifying audit-trail capable safes as standard amenities. The Ministry of Science and Technology administers QCVN technical regulations for electronic access devices. Ho Chi Minh City serviced apartment operators are sourcing larger-volume residential-grade safes for extended-stay properties.
Indonesia
Bali and Jakarta hospitality zones are absorbing electronic keypad units for new-build properties. BSN national standards govern burglary-resistance testing protocols. Lombok and Batam development corridors are creating concentrated demand for built-in wall installations during rough-in construction phases.
United States
Urban full-service properties in New York and Los Angeles are integrating safes with property management platforms. Underwriters Laboratories burglary-resistance and fire-endurance certifications determine insurance premium structures. Miami and Las Vegas hospitality clusters are prioritizing smart-connected units with remote monitoring capability.
Germany
Munich and Frankfurt hotel operators are specifying REACH-compliant steel finishing processes. ECHA substance restrictions are disqualifying legacy chromate pretreatments for corrosion resistance. Hamburg and Cologne procurement teams are bundling safe contracts with electronic lock and energy management systems.
In Room Safes Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the in-room safes market, creating a tiered structure where scale advantages clash with customization agility. Electronic lock manufacturers leverage access control ecosystems to bundle safe procurement, compressing margins for standalone suppliers. Three archetypes dominate: hospitality-focused security specialists, diversified building technology conglomerates, and maritime hospitality equipment providers. M&A activity concentrates around electronic lock integration capabilities, while geographic expansion targets Southeast Asian construction corridors.
Within the hospitality security specialist tier, Safemark Systems and ASSA ABLOY Hospitality occupy positions shaped by their respective channel strategies—direct-installation service agreements versus bundled access control contracts. Gunnebo AB sits within the steel-construction archetype, representing European manufacturers certified to national burglary-resistance grades. These three companies exemplify how vendor selection criteria are migrating from procurement departments toward IT directors as connectivity integration reshapes competitive positioning.
| Leading Market Players |
|---|
| Safemark Systems |
| ASSA ABLOY Hospitality |
| Global Safe Corporation |
| Indel B |
| Gunnebo AB |
| Dometic Group |
| Onity Inc. |
| JVD Group |
| Minibar Systems |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in European steel finishing anchor supply-side discipline, while private-equity-rolled-up hospitality security platforms compress pricing power through bundled access control contracts. This ownership fragmentation creates divergent margin strategies across certification tiers and geographic markets.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for electronic keypad units, forcing incumbent manufacturers to absorb cold-rolled steel volatility rather than pass through costs. Three-tier pricing structure across premium biometric, standard electronic, and economy manual tiers separates UL-certified fire-rated construction from uncertified hostel-grade alternatives. Cost compression in mid-tier electronic units is intensifying because semiconductor sourcing dependencies constrain component substitution. Budget hostel operators in emerging markets exhibit highest price sensitivity, while Singapore luxury properties accept premium positioning for IoT-enabled audit capability.
Supply Chain Analysis
Direct-to-hotel procurement channels handle new-build property demand in Thailand and Vietnam, while distributor networks serve European retrofit applications. Manufacturing concentrates in China, Germany, and Italy for steel chassis fabrication, with final assembly migrating to Malaysia and Mexico for regional tariff optimization. Supply chains draw from East Asian semiconductor foundries for biometric modules and Nordic suppliers for low-power connectivity chipsets. Single-source vulnerability in fire-rated steel sheet creates delivery timeline risks during commodity price spikes. Distribution runs through hospitality-focused security specialists and diversified building technology conglomerates competing for bundled access control contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The in-room safes market functions as a regulatory compounder where REACH chemical restrictions and EU Green Deal mandates are accelerating supplier consolidation around compliant finishing technologies.
For Market Incumbents: Extend certification advantages in REACH-compliant steel finishing to capture European hospitality procurement filters before mid-tier competitors qualify alternative coatings. Deepen backward integration into electronic lock ecosystems to defend against bundled access control contracts from ASSA ABLOY Hospitality and competing conglomerates. Capacity additions in Vietnam represent the priority defensive lever for Southeast Asian construction corridors. For New Entrants and Emerging Players: The price-point gap between premium biometric and economy manual tiers creates entry space for modular upgrade platforms serving mid-scale hotel chains in Malaysia and the Philippines. Cruise ship alloy construction represents the most penetrable niche where weight constraints override incumbent steel-certification advantages. A direct-installation service model targeting Vietnam serviced apartment conversions offers the clearest go-to-market angle against established distribution relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among steel-construction specialists lacking electronic lock integration capabilities, creating acquisition targets for private-equity platforms seeking hospitality security roll-ups. Long-term viability across the projection horizon hinges on software compatibility with property management platforms rather than hardware durability alone. The signal to monitor is IT director specification authority surpassing procurement department control in new-build contract decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Module Integration | Fingerprint-enabled cartridges from Swedish sensor suppliers differentiate premium resort specifications in Thailand. |
| REACH-Compliant Finishing Investment | Trivalent chromium alternatives to chromate pretreatments unlock European hospitality procurement compliance. |
| Property Management Platform Partnership | API development with Oracle and Opera PMS vendors reduces middleware friction for smart-connected deployments. |
| Maritime Alloy Construction Scale-Up | Aluminum-magnesium blends for Royal Caribbean and Carnival specifications capture fuel-cost-driven demand. |
| Remote Monitoring Subscription Launch | IoT audit-trail services with housekeeping management integration create recurring revenue from installed base. |
Research Methodology
Direct dialogue with hotel procurement directors, electronic lock system integrators, steel finishing plant managers, and hospitality IT directors grounded qualitative findings in operational reality. Secondary validation drew from Underwriters Laboratories certification databases, ECHA substance restriction updates, BSI and TISI national standards filings, and hospitality construction pipeline tracking. Bottom-up property-level demand estimates triangulated against top-down hospitality sector capital expenditure analysis.
Segmented outputs across type, material, end-user, and installation dimensions fed analytical frameworks spanning the projection horizon. Modeled CAGRs derived from construction activity correlations, replacement cycle assumptions, and technology substitution curves for biometric versus keypad entry systems. Forecast inputs incorporated cold-rolled steel price elasticity coefficients and semiconductor delivery timeline distributions.
Caveats apply where REACH substance list expansions, hospitality data protection standard revisions, or property management software API standardization could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Cargo Security Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above the Waist PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Protective Coating Market
Safety Equipment and Personal Protective Equipment (PPE)
Functional Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplementary Protectors Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Static Safety Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Power Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Prefilled Safety Device Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium High Security Doors Market