
 Industrial Protective Clothing Market | 2026-2036
Industrial Protective Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Protective Clothing Market Analysis
Chinese aramid fiber production is hardening as domestic suppliers expand metalfiber spinning capacity. DuPont sustains technology leadership in North American thermal protection through proprietary para-aramid platforms. W. L. Gore & Associates differentiates via membrane-laminated fabrics that block hazardous particulates while managing heat stress. Sioen Industries NV anchors European supply for chemical-resistant outerwear through integrated coating operations in Belgium.
Industrial protective clothing denotes engineered garments designed to shield workers from thermal, chemical, mechanical, and electrical hazards, typically constructed from flame-resistant fibers such as Nomex or Kevlar with fabric weights ranging from 150 to 450 gsm depending on hazard severity. These garments serve critical functions in preventing burn injuries, chemical permeation, and arc flash exposure across hazardous work environments. Coveralls command the largest product volume due to full-body coverage requirements in oil and gas turnarounds, while gloves represent the fastest-growing category as hand protection standards tighten in manufacturing. Material selection increasingly favors Kevlar blends for cut resistance in metal fabrication, whereas polyethylene-based barriers gain traction in chemical splash protection where disposable protocols dominate.
OSHA 1910.269 mandates arc-rated clothing for electrical utility workers, compelling end users to maintain certified garment inventories or face enforcement penalties. EU PPE Regulation and EN ISO 11612 standards shape product access across European manufacturing and construction sectors by requiring third-party certification for thermal protective properties. ASTM F1506 and NFPA 2112 govern North American flame-resistant apparel specifications, creating compliance moats for suppliers with accredited testing infrastructure. Stakeholders must monitor evolving state-level heat illness prevention rules in the US, as California and Washington explore garment breathability mandates that could reshape material specifications and certification costs.
Market Dynamics
EU PPE Regulation enforcement is compressing certification timelines for thermal protective garments, forcing suppliers to accelerate testing infrastructure investment or surrender shelf space to accredited competitors.
Growth Catalysts
- OSHA 1910.269 enforcement:Electrical utilities in the US Gulf Coast corridor face inspection surges, compelling bulk arc-rated coverall procurement ahead of turnaround cycles.
- Metalfiber spinning advances:Chinese domestic suppliers harden aramid fiber production capacity, reducing import dependency for flame-resistant fabric mills.
- Foundry modernization:European metal casting facilities replace cotton barriers with advanced aramid blends to satisfy EN ISO 11612 thermal protection mandates.
Market Restraints
- Para-aramid supply concentration:DuPont and Teijin control proprietary fiber platforms, creating input bottlenecks for independent garment manufacturers.
- Petrochemical feedstock volatility:Synthetic fiber costs fluctuate with polyethylene and meta-aramid precursor pricing, squeezing margin predictability.
- Heat stress trade-offs:Heavier fabric weights required for arc flash protection compromise breathability, limiting wear-time in high-temperature environments.
Strategic Opportunities
- California heat illness rulemaking:Proposed garment breathability standards create first-mover advantage for membrane-laminated fabric suppliers with pre-certified product lines.
- Chemical splash disposables:Polyethylene-based barriers gain traction in batch chemical processing where single-use protocols reduce cross-contamination liability.
- Smart textile integration:Embedding temperature sensors into thermal protective garments enables real-time heat stress monitoring for foundry and refinery operators.
Industry Challenges
- NFPA 2112 recertification timelines:Third-party testing backlogs delay product launches, forcing manufacturers to carry excess inventory of pre-certified stock.
- Multihazard garment engineering:Balancing chemical resistance, flame retardancy, and ergonomic mobility requires iterative prototyping that extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Protective Clothing Market |
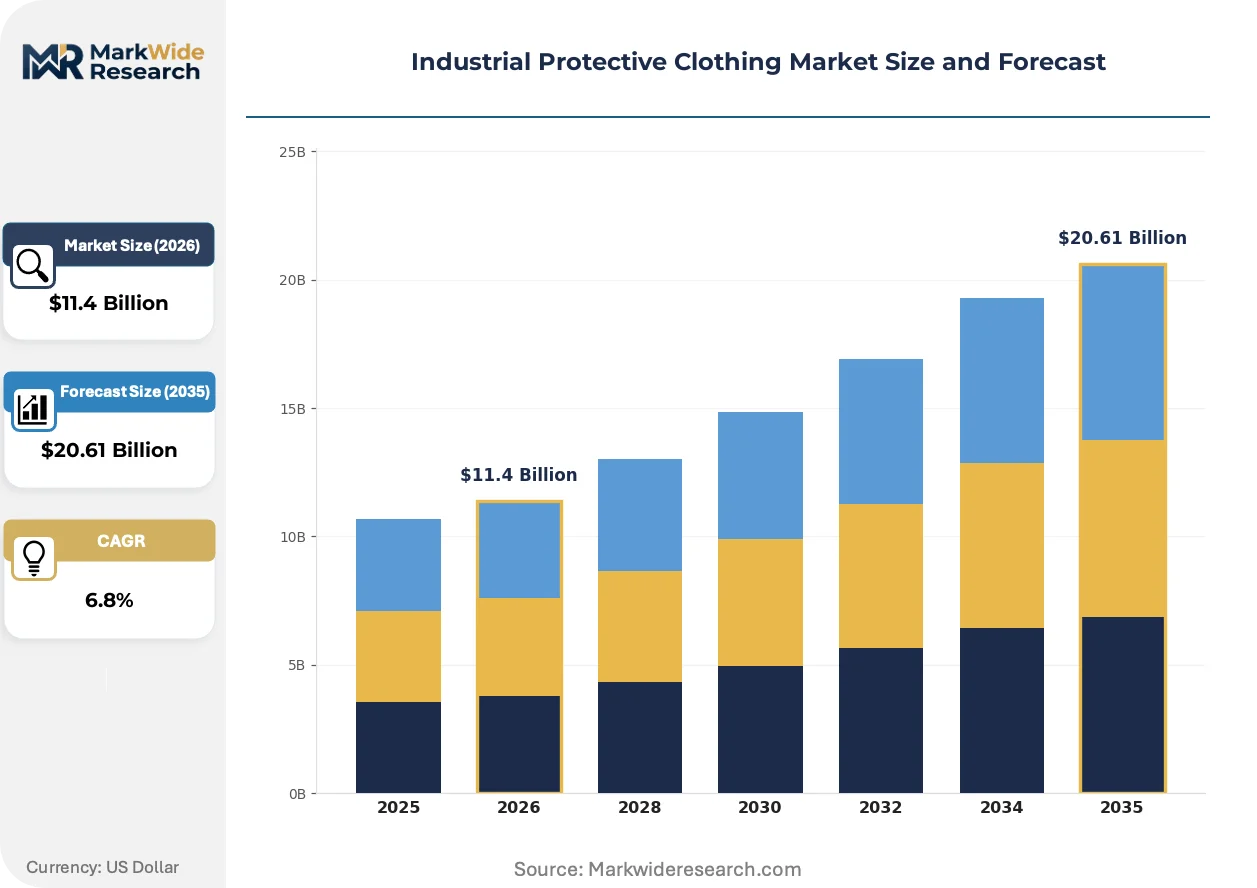
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coveralls, Jackets, Gloves, Helmets Material: Nomex, Kevlar, Cotton, Polyethylene End User: Manufacturing, Construction, Oil & Gas, Mining Regulatory Compliance: ISO, ASTM, OSHA, EN Standards |
| Companies Covered | 3M, DuPont, Ansell Ltd., Lakeland Industries, Inc., Honeywell International Inc., PBI Performance Products, Inc., Sioen Industries NV, TenCate Protective Fabrics, W. L. Gore & Associates, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Protective Clothing Market Emerging Trajectories
Material science convergence with wearable sensor platforms is redefining protective garment value propositions beyond passive hazard blocking toward active worker monitoring.
Phase-change material integration is electrifying thermal management capabilities in heavy industrial coveralls. Oil and gas operators on the US Gulf Coast pilot garments with embedded microencapsulated paraffin wax that absorbs excess body heat during turnaround operations. This technology is compressing the performance gap between passive insulation and active cooling systems.
REACH restriction proposals on per- and polyfluoroalkyl substances are reshaping chemical-resistant coating formulations across European manufacturing. Suppliers reformulate durable water-repellent finishes to maintain EN 13034 chemical splash protection without fluorinated chemistry. German chemical processing facilities now demand transitional certification pathways that bridge legacy and next-generation barrier technologies.
Refinery procurement departments consolidate vendor relationships around full-service rental and laundering programs. Large integrated operators in Texas and Louisiana abandon garment ownership models in favor of subscription-based coverall services that bundle inventory management, industrial cleaning, and compliance tracking. This shift concentrates purchasing power among national rental chains with certified thermal processing capabilities.
Industrial Protective Clothing Market Segmentation
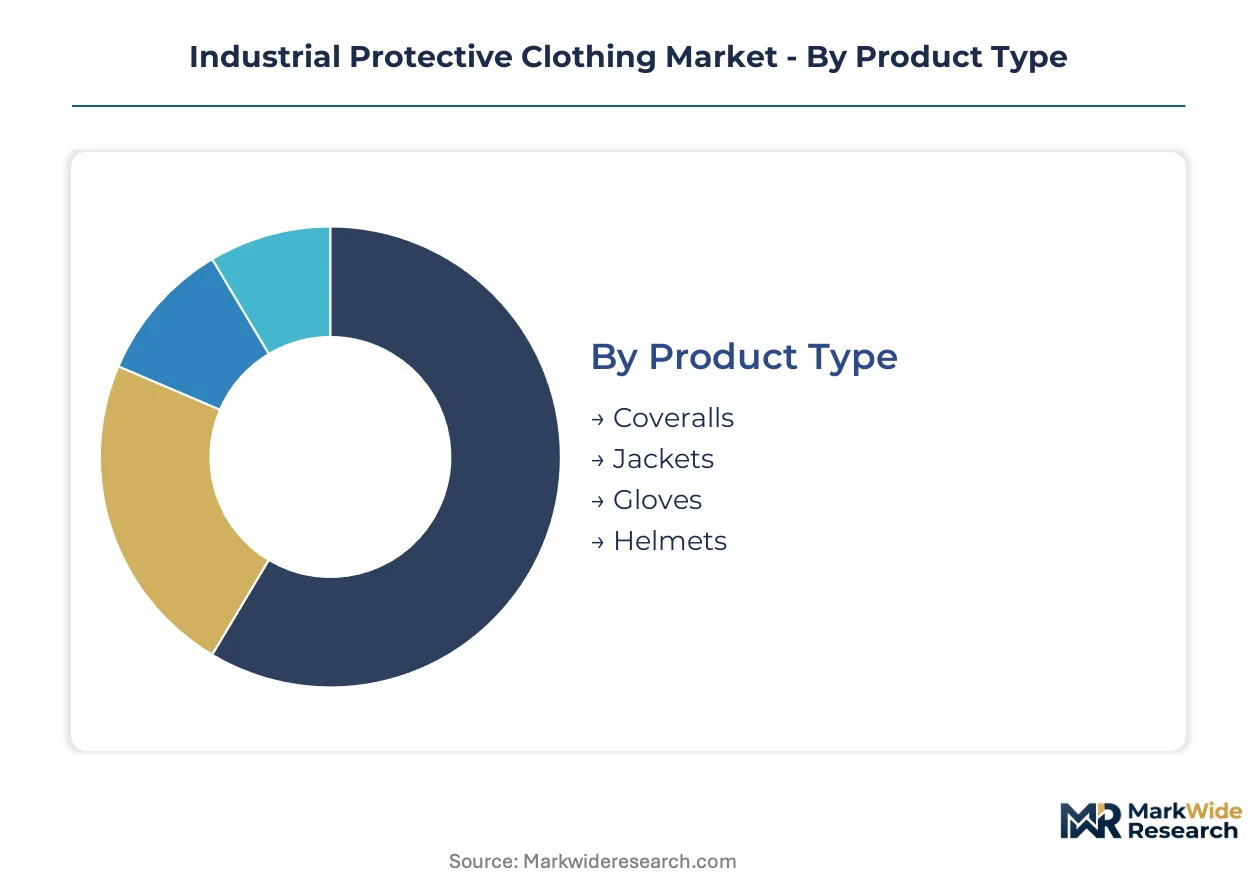
Segmentation in industrial protective clothing reveals how hazard specificity, material performance, and regulatory jurisdiction shape procurement patterns. Buyers select garments based on multihazard exposure profiles rather than single-risk assessments, forcing suppliers to engineer across thermal, chemical, and mechanical protection domains simultaneously.
Product Type:
Replacement cycles vary sharply across garment categories, with heavy-use items demanding annual refresh schedules while durable outerwear extends across multi-year horizons.
- Coveralls:Full-body garments constructed from 200-450 gsm aramid blends deliver integrated protection against arc flash and flash fire hazards. Demand concentrates in Texas and Louisiana refinery turnarounds where OSHA 1910.269 mandates arc-rated coverage for electrical maintenance crews.
- Gloves:Cut-resistant hand protection utilizing Kevlar composite yarns addresses mechanical hazards in metal fabrication. German automotive stamping plants drive specification tightening as EN 388 mechanical protection standards elevate puncture resistance requirements.
- Jackets:Upper-body thermal barriers with modifiable insulation layers serve construction and utility applications. Jacket procurement tracks seasonal weather patterns in northern climates.
- Helmets:Head protection with integrated face shields and communication mounts serves electrical and foundry environments. Helmet replacement follows impact damage protocols rather than calendar schedules.
Coveralls sits at the top of the volume ranking, with gloves climbing the fastest.
Material:
Cost tiers separate synthetic fiber platforms from natural alternatives, with performance premiums widening as hazard severity intensifies.
- Nomex:Meta-aramid fiber from DuPont provides inherent flame resistance without chemical treatment degradation. US Gulf Coast petrochemical operators specify Nomex blends for refinery maintenance where thermal exposure combines with chemical splash risk.
- Kevlar:Para-aramid construction delivers exceptional cut and abrasion resistance for metal handling and glass manufacturing. Chinese domestic spinning capacity expansion is reducing import premiums for Asian garment producers.
- Cotton:Natural fiber with flame-retardant chemical treatments serves cost-sensitive applications with lower thermal exposure. Cotton barriers face displacement in European foundries upgrading to EN ISO 11612-compliant aramid systems.
- Polyethylene:Disposable barrier fabrics block chemical permeation in batch processing environments. Polyethylene demand accelerates in pharmaceutical manufacturing where single-use protocols prevent cross-contamination.
Nomex commands the premium tier by volume, with polyethylene expanding most quickly in disposable segments.
End User:
Customer type determines contract structure, with integrated operators favoring rental programs and smaller contractors purchasing outright.
- Manufacturing:Diverse hazard profiles across automotive, electronics, and food processing drive segmented procurement strategies. Manufacturing buyers balance cut protection, chemical resistance, and electrostatic discharge requirements.
- Oil & Gas:Integrated majors in Texas and Louisiana consolidate vendor relationships around full-service rental and laundering programs. Turnaround cycles generate surge demand for arc-rated coveralls ahead of scheduled maintenance windows.
- Construction:Project-based purchasing with fragmented contractor bases limits long-term contract penetration. High-visibility and thermal protection specifications vary by trade and climate zone.
- Mining:Underground operations demand flame-resistant apparel with moisture management for extended wear times. Mining procurement emphasizes durability under abrasive conditions.
Oil & Gas anchors contract value, with manufacturing showing the steepest specification diversification.
Regulatory Compliance:
Geographic jurisdiction dictates certification pathway, with cross-border suppliers maintaining parallel testing portfolios.
- OSHA:US federal enforcement of 1910.269 compels electrical utilities to maintain certified arc-rated garment inventories. OSHA inspection surges in the Gulf Coast corridor accelerate replacement procurement ahead of compliance deadlines.
- EN Standards:European Norm specifications including EN ISO 11612 and EN 13034 govern thermal and chemical protection claims. German chemical processing facilities demand transitional certification as REACH restrictions reshape coating formulations.
- ASTM:North American consensus standards including F1506 specify flame-resistant apparel performance. ASTM compliance creates testing infrastructure moats for accredited suppliers.
- ISO:International standards enable cross-border product acceptance for multinational operators. ISO certification reduces market entry friction for suppliers targeting multiple jurisdictions.
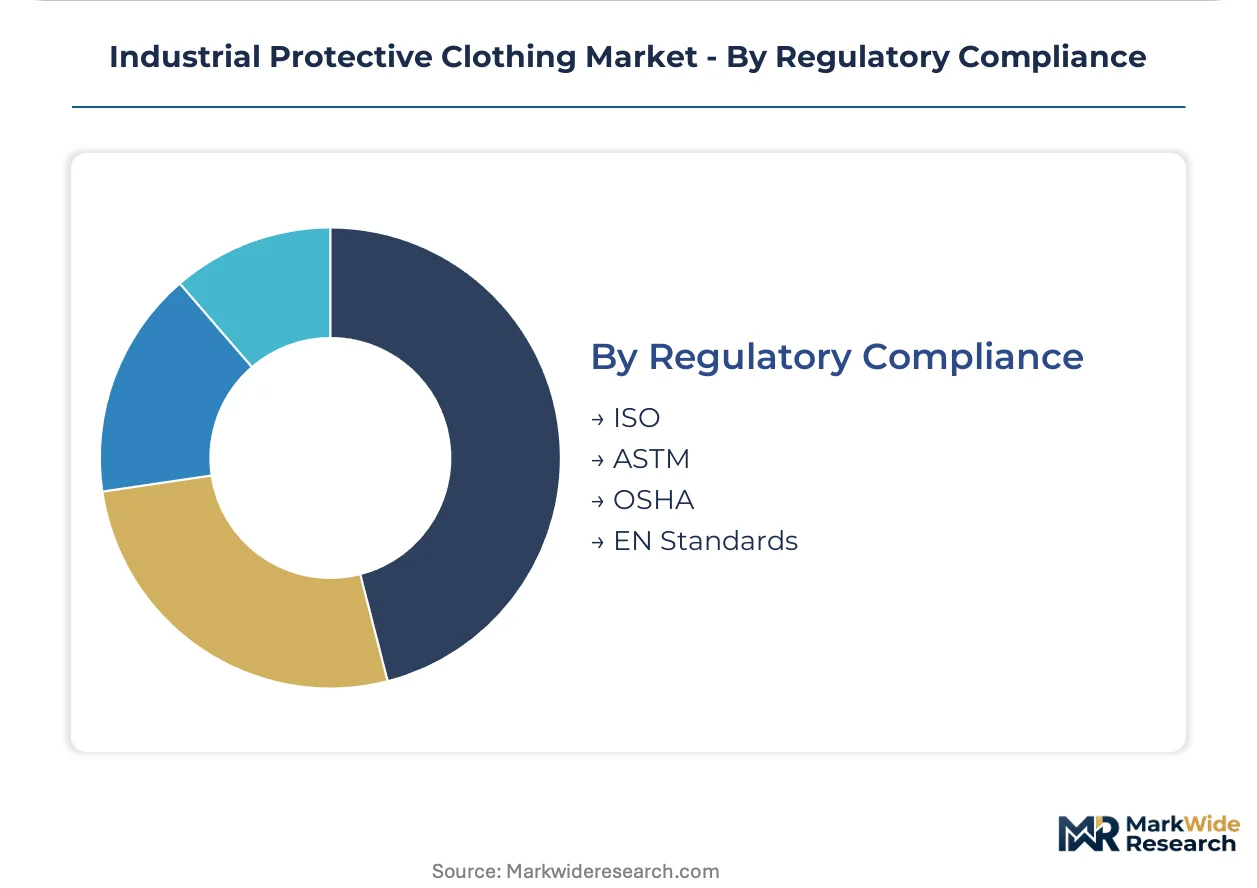
OSHA and EN Standards dominate procurement specifications, with ISO gaining traction among multinational end users seeking harmonized compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production footprints as manufacturers seek compliance-cost advantages across jurisdictions with divergent certification burdens and enforcement intensity.
United States
OSHA 1910.269 enforcement surges in the Gulf Coast petrochemical corridor drive arc-rated coverall procurement ahead of refinery turnaround cycles. The agency's inspection intensification in Texas and Louisiana compels electrical utilities to maintain certified garment inventories or face penalty exposure. Houston anchors regional demand concentration where integrated majors consolidate vendor relationships around full-service rental programs.
Germany
Chemical processing facilities in the Rhine-Ruhr industrial belt expand flame-resistant uniform programs under EU PPE Regulation compliance mandates. ECHA REACH restriction proposals on fluorinated substances reshape coating formulations for durable water-repellent finishes. Foundries in North Rhine-Westphalia replace cotton barriers with advanced aramid blends to satisfy EN ISO 11612 thermal protection standards.
China
Domestic metalfiber spinning capacity expansion hardens aramid fiber production and reduces import dependency for flame-resistant fabric mills. The country's national standardization regulator advances GB standards for thermal protective apparel that align with international benchmarks. Yangtze River Delta manufacturing clusters absorb technology transfers from multinational fiber platforms to localize para-aramid supply chains.
Belgium
Sioen Industries NV anchors European chemical-resistant outerwear supply through integrated coating operations serving German and French industrial markets. EU PPE Regulation enforcement compresses certification timelines and accelerates testing infrastructure investment among accredited suppliers. Antwerp's port logistics infrastructure supports distribution efficiency for hazardous environment apparel across the Benelux region.
Japan
METI industrial safety guidelines elevate thermal protection specifications for automotive stamping and electronics manufacturing operations. JIS standards for flame-resistant apparel create compliance moats for suppliers with accredited domestic testing infrastructure. Osaka-Kansai manufacturing clusters drive specification tightening for cut-resistant hand protection as automotive production quality standards intensify.
Industrial Protective Clothing Market Vendor Landscape
North American producers anchor the premium fiber tier; European specialists hold integrated coating and membrane-lamination capabilities. The vendor base separates into three strategic archetypes: proprietary fiber platforms with captive raw material control, integrated garment-coating operations with regional distribution density, and membrane technology licensors with barrier-science differentiation. Competitive moves concentrate on M&A to secure testing infrastructure accreditation and capacity expansion in high-enforcement geographies.
Within the proprietary fiber tier, DuPont and Teijin occupy positions defined by para-aramid and meta-aramid platform control. W. L. Gore & Associates exemplifies the membrane-lamination archetype with barrier technologies that manage heat stress while blocking hazardous particulates. These three anchors represent the structural concentration where input bottlenecks and certification moats intersect.
| Leading Market Players |
|---|
| 3M |
| DuPont |
| Ansell Ltd. |
| Lakeland Industries, Inc. |
| Honeywell International Inc. |
| PBI Performance Products, Inc. |
| Sioen Industries NV |
| TenCate Protective Fabrics |
| W. L. Gore & Associates, Inc. |
| Others |
Supply Flow & Price Mechanics
Refinery procurement consolidation around full-service rental programs in Texas and Louisiana is compressing direct garment sales channels and forcing independent manufacturers toward certified laundering partnerships or margin sacrifice. This demand-side restructuring elevates pricing power for national rental chains with thermal processing infrastructure while squeezing spot-market suppliers.
Pricing Analysis
Distributor margins of 25-35 percent separate premium Nomex blends from standard aramid alternatives in the US Gulf Coast corridor. Pricing stratifies across certification tiers, with ASTM F1506 arc-rated garments commanding 40-60 percent premiums over untreated cotton barriers. Cost compression in the polyethylene disposable segment intensifies as Chinese domestic spinning capacity reduces import premiums. Small contractors in construction exhibit highest price sensitivity, whereas integrated oil and gas operators prioritize compliance assurance over unit economics.
Supply Chain Analysis
Para-aramid fiber supply rests on proprietary platforms controlled by DuPont in the United States and Teijin in Japan, creating input bottlenecks for independent garment producers. Raw material dependencies include meta-aramid precursors, flame-retardant chemical treatments, and membrane lamination substrates. Single-source vulnerability concentrates in high-performance fiber spinning, where technology transfer barriers limit new entrant supply access. Distribution runs through industrial safety distributors, direct OEM contracts, and emerging subscription-based rental programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. EN ISO 11612 specification tightening across European foundries and chemical processing facilities is elevating procurement standards toward premium aramid platforms.
For Market Incumbents: To counter para-aramid supply concentration, secure backward integration into fiber spinning or captive supply agreements with Teijin or domestic Chinese suppliers. Accelerate testing infrastructure accreditation to compress NFPA 2112 recertification timelines and defend shelf space against accredited competitors. For New Entrants and Emerging Players: Capture the chemical splash disposable segment in pharmaceutical manufacturing where single-use protocols and cross-contamination liability drive specification shifts. Target membrane-laminated fabric niches in California ahead of anticipated heat illness breathability mandates. Lead with pre-certified product lines to bypass third-party testing backlogs. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated coating and membrane-lamination specialists holding EU PPE Regulation accreditation and established German chemical processing relationships. Over the projection horizon, prioritize targets with certified thermal processing capabilities and rental program infrastructure. Watch California OSHA rulemaking progress as an inflection signal for breathability-driven material substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Spinning | Captive para-aramid supply reduces input cost volatility for garment manufacturers. |
| Testing Infrastructure Accreditation | EU PPE Regulation compliance compresses certification timelines for thermal protective garments. |
| Membrane-Laminated Fabric Development | Pre-certified heat stress management products capture California regulatory anticipation. |
| Full-Service Rental Program Expansion | Subscription models consolidate purchasing power among Gulf Coast petrochemical operators. |
| Smart Textile Sensor Integration | Embedded temperature monitoring differentiates thermal protection beyond passive hazard blocking. |
Methodological Framework
Multiple input streams — primary interviews with plant safety managers, procurement leads at integrated oil and gas operators, and technical directors at fiber manufacturers, alongside secondary validation through OSHA enforcement databases, EU PPE Regulation certification registries, and customs trade data — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored volume and value outputs across product type, material platform, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth trajectory analysis incorporating refinery turnaround cycle timing, EN standard adoption curves, and fiber capacity expansion announcements. Industry-specific forecast inputs included arc-rated garment inventory refresh rates and chemical splash disposable protocol penetration in pharmaceutical manufacturing.
Regulatory enforcement intensity shifts, fiber supply disruption events, and state-level heat illness rulemaking acceleration are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding certification timeline stability and petrochemical feedstock cost trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Personal Protective Equipment Kit Market
Safety Equipment and Personal Protective Equipment (PPE)
Edge Protector Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
Driving Protection Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Non-Powered Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Gowns Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Biometric Gun Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
PPE Detection Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsic Safety Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
Respiratory Protective Equipment Market