
 Protective Eye Wear Market | 2026-2036
Protective Eye Wear Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Eye Wear Market Analytics
Asset-light leasing models for industrial safety equipment are reshaping competitive dynamics in protective eye wear. 3M Company leverages its captive distribution network to bundle eyewear with respiratory and hearing protection, sustaining recurring revenue streams. Honeywell International Inc. anchors its position through vertical integration into polycarbonate lens molding. MSA Safety differentiates via connected safety platforms that integrate smart eyewear into broader worker monitoring systems.
Protective eye wear encompasses vision safeguarding devices engineered to ANSI Z87.1 or EN 166 impact standards, typically fabricated from polycarbonate, Trivex, or treated glass with anti-fog and UV-blocking coatings, designed to prevent ocular injury from projectile debris, chemical splash, or optical radiation in occupational and recreational environments. Safety glasses occupy the largest volume position across product types, though welding helmets command premium pricing due to auto-darkening filter technology and integrated respiratory compatibility. The construction application segment leads absolute demand, while healthcare shows the fastest structural expansion driven by infection control protocols and laser surgery eye protection requirements.
OSHA enforces 29 CFR 1910.133 eye and face protection standards in the United States, mandating employer-provided equipment and training that sustains baseline demand regardless of economic cycles. The EU's PPE Regulation 2016/425 and CE marking requirements create parallel compliance obligations across European member states, with notified bodies conducting ongoing conformity surveillance. Stakeholders must monitor evolving harmonized standards for blue-light filtering and augmented reality integration as these capabilities migrate from consumer to industrial protective applications.
Market Dynamics
ANSI Z87.1 compliance mandates are compressing replacement cycles and forcing suppliers to maintain dual-certification inventories across North American and European standards, reshaping working capital requirements and margin structures throughout the value chain.
Growth Catalysts
- OSHA Enforcement Intensification:29 CFR 1910.133 audits are accelerating employer-provided equipment refresh rates, particularly in construction and manufacturing verticals where penalty exposure drives preemptive procurement.
- Polycarbonate Lens Maturation:Superior impact resistance and weight reduction versus treated glass is displacing legacy materials in industrial settings, creating upgrade demand even among equipped workforces.
- Healthcare Infection Protocols:Laser surgery suites and infectious disease wards are mandating dedicated eye protection beyond standard safety glasses, opening clinical application expansion.
Market Restraints
- Petrochemical Feedstock Volatility:Polycarbonate resin prices fluctuate with benzene and phosgene input costs, compressing lens fabricator margins during upstream spikes.
- Asian Molding Concentration:Optical-grade polycarbonate injection capacity clusters in coastal China, exposing supply chains to port congestion and tariff friction.
- Prescription Compatibility Limits:High-wrap frame designs required for side-impact protection conflict with corrective lens curvature tolerances, restricting addressable population.
Strategic Opportunities
- Connected Safety Convergence:Integration of heads-up displays and proximity sensors into ANSI-certified frames is digitizing worker monitoring, commanding 40-60% price premiums over passive eyewear.
- EU PPE Regulation Expansion:2016/425 harmonized standards for blue-light filtering create certification pathways for digital eye strain applications in office and industrial hybrid environments.
- Equipment-as-a-Service Models:Leasing programs bundling eye wear with fit testing and replacement logistics are penetrating mid-market construction contractors seeking to convert capex to opex.
Industry Challenges
- Dual-Certification Testing Burden:Simultaneous ANSI Z87.1 and EN 166 validation requires redundant laboratory partnerships, extending product launch timelines by 8-14 months.
- Optical Prescription Integration Complexity:Fitting corrective lenses into high-impact frames while maintaining peripheral coverage standards demands specialized optician training that remains scarce in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Eye Wear Market |
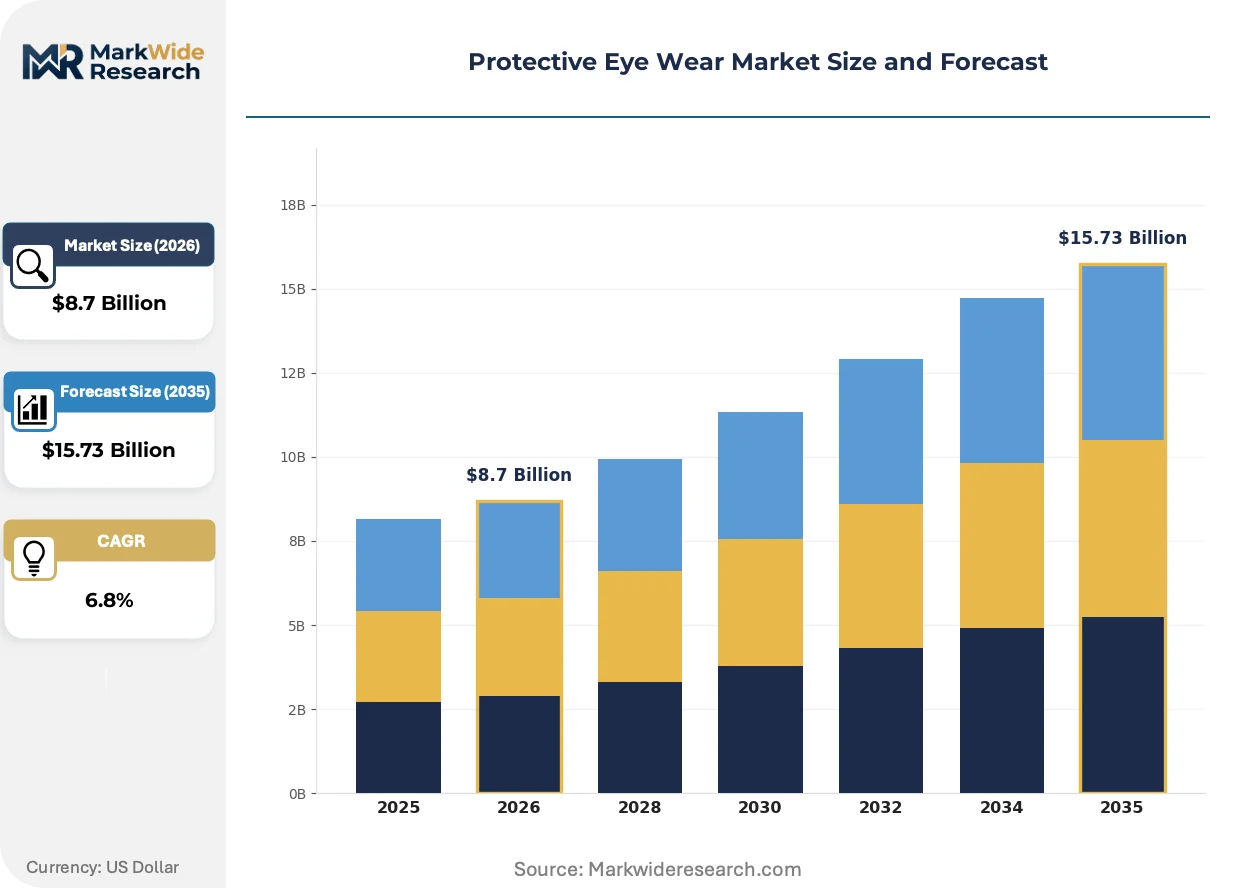
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Glasses, Goggles, Face Shields, Welding Helmets Application: Construction, Manufacturing, Laboratory, Healthcare Customer Type: Industrial Workers, Medical Professionals, DIY Enthusiasts, Sporting Participants Material: Polycarbonate, Metal, Plastic, Glass |
| Companies Covered | 3M Company, Honeywell International Inc., MSA Safety, Bollé Safety, Uvex Safety Group, Pyramex Safety Products, LLC, Radians, Inc., MCR Safety, Gateway Safety Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Eye Wear Market Evolving Landscape
Smart sensor integration and augmented reality overlays are transforming protective eye wear from passive barriers into active worker-safety nodes, while regulatory harmonization efforts are compressing the certification landscape across Atlantic markets.
Auto-darkening filter technology is digitizing welding helmet functionality, replacing fixed-shade passive lenses with liquid crystal arrays that respond to arc intensity in under 0.1 milliseconds. Shipbuilding and pipeline construction contractors are specifying these systems to reduce neck strain from repetitive helmet lifting and to enable precision tack welding without visibility interruption. The technology is digitizing quality control workflows by enabling continuous visual monitoring rather than stop-start inspection cycles.
REACH restrictions on bisphenol-A in consumer products are extending scrutiny to polycarbonate lens formulations, pressuring manufacturers to validate BPA-free alternatives or secure derogations for occupational PPE categories. German notified bodies under EU 2016/425 are requiring enhanced substance documentation for CE marking renewals, particularly for products with prolonged skin contact. Lens molders are responding by accelerating bio-based copolymer development programs and building regulatory affairs capabilities in Brussels.
Buyer consolidation among national construction aggregates is compressing supplier rosters and shifting procurement toward integrated safety contractors managing full PPE portfolios. General contractors on federal infrastructure projects are mandating single-source safety providers to streamline compliance documentation and reduce subcontractor qualification overhead. This concentration is most visible in United States Department of Transportation-funded bridge and highway work, where prime contractors face heightened liability exposure from tier-2 and tier-3 subcontractor incidents.
Protective Eye Wear Market Segmentation
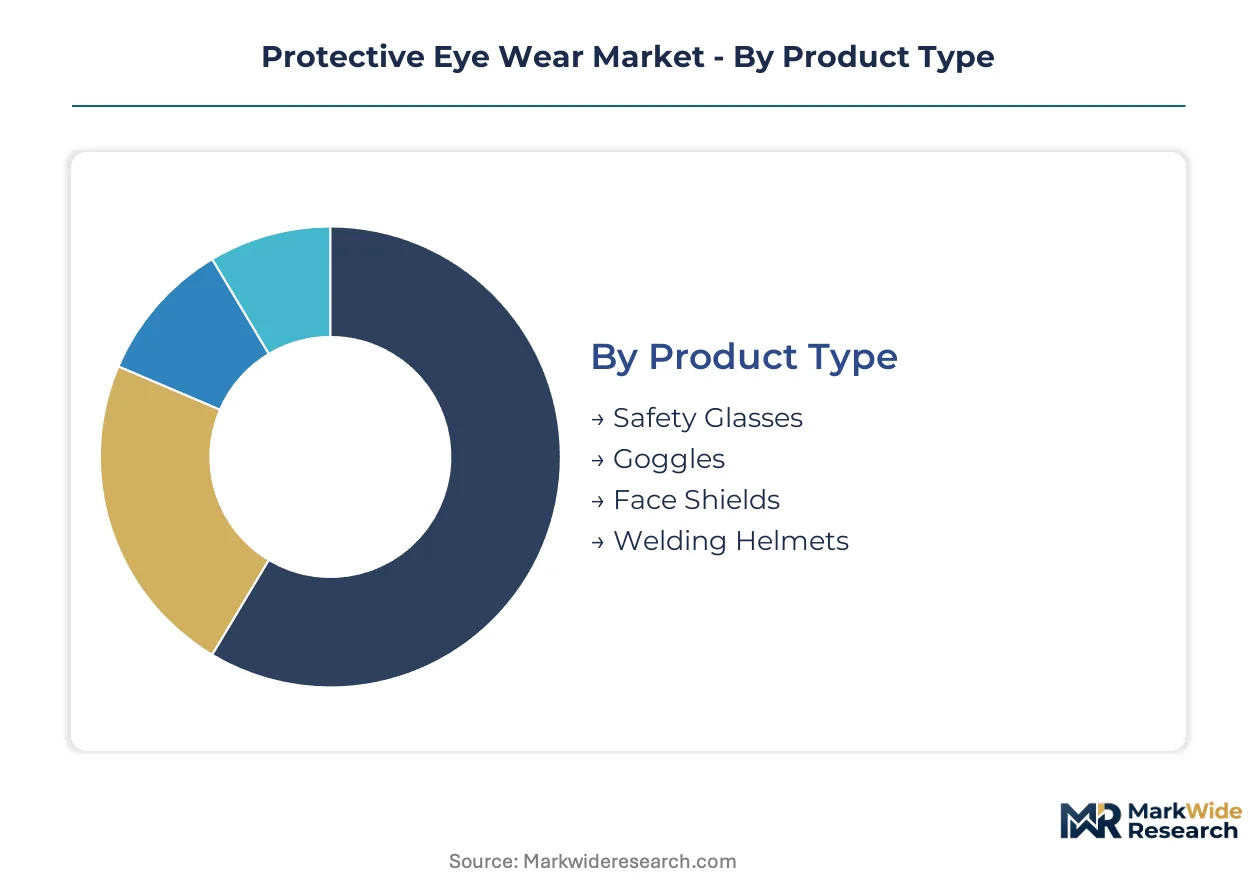
Protective eye wear segmentation reveals distinct procurement patterns across industrial and non-industrial channels. ANSI Z87.1 certification tiers and prescription compatibility requirements create divergent margin profiles that reshape supplier resource allocation.
Product Type:
Mature categories dominate procurement volumes while emerging formats capture technology premiums and compliance-driven replacement cycles.
- Safety Glasses:ANSI Z87.1-certified frames with polycarbonate, Trivex, or treated glass lenses provide baseline impact protection against projectile debris. Construction site managers in the United States mandate these for all subcontractors, with OSHA 29 CFR 1910.133 audits accelerating refresh rates regardless of economic cycles.
- Welding Helmets:Auto-darkening filter technology using liquid crystal arrays responds to arc intensity in under 0.1 milliseconds, replacing fixed-shade passive lenses. Shipbuilding and pipeline contractors specify these systems to reduce neck strain from repetitive helmet lifting and enable continuous visual monitoring during precision tack welding.
- Goggles:Sealed perimeter designs with indirect ventilation protect against chemical splash and fine particulate in laboratory and manufacturing environments.
- Face Shields:Extended coverage polycarbonate visors mount to hard hats for grinding, chemical handling, and bloodborne pathogen protection in healthcare settings.
Safety glasses handle the majority of throughput; welding helmets are the fastest mover on share.
Application:
Cost tier differentiation separates capex-intensive industrial procurement from opex-driven healthcare and laboratory channels.
- Construction:General contractors on United States Department of Transportation-funded infrastructure mandate single-source safety providers to streamline compliance documentation and reduce subcontractor qualification overhead from tier-2 and tier-3 incidents.
- Healthcare:Infection control protocols and laser surgery eye protection requirements are opening clinical application expansion beyond standard safety glasses. Laser surgery suites and infectious disease wards mandate dedicated eye protection with specific optical density ratings.
- Manufacturing:Metal fabrication and assembly lines require side-impact protection with prescription compatibility, creating demand for high-wrap frame designs.
- Laboratory:Chemical splash resistance and UV-blocking specifications drive goggle and face shield procurement in research and quality control environments.
Construction captures the largest procurement volumes; healthcare is expanding most quickly on structural protocol mandates.
Customer Type:
Volume concentration sits with institutional buyers while margin expansion follows specialized professional segments.
- Industrial Workers:Employer-provided equipment programs under OSHA enforcement sustain baseline demand through mandatory fit testing and replacement logistics.
- Medical Professionals:Laser surgery specialists and infectious disease practitioners require certified protection with optical clarity standards beyond industrial baselines.
- DIY Enthusiasts:Home improvement retailers stock ANSI Z87.1-certified options for consumer purchase, though compliance verification remains inconsistent.
- Sporting Participants:Ballistic-rated eyewear for shooting sports and racquet sports occupies a niche with limited regulatory overlap with occupational standards.
Industrial workers represent the dominant volume base; medical professionals are climbing the fastest on infection control investment.
Material:
Supply concentration in optical-grade resin molding creates geographic dependencies that reshape working capital requirements.
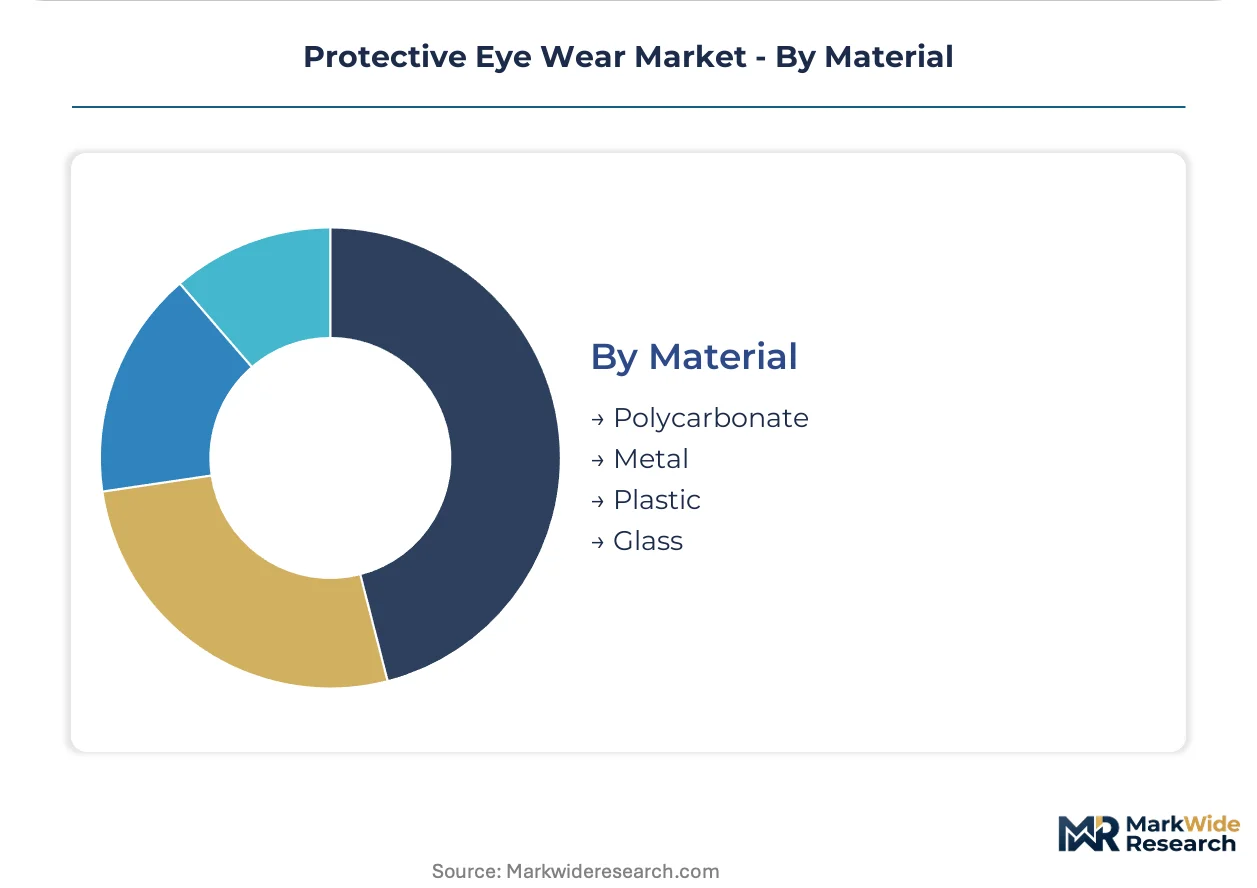
- Polycarbonate:Superior impact resistance and 40% weight reduction versus treated glass has displaced legacy materials across industrial settings. Petrochemical feedstock volatility in benzene and phosgene inputs compresses fabricator margins during upstream price spikes.
- Glass:Scratch resistance and optical clarity retention persist in specialty applications despite fragility and weight penalties.
- Plastic:Acetate and nylon frames serve price-sensitive channels with limited impact certification requirements.
- Metal:Titanium and stainless steel frame components provide durability in high-temperature welding and foundry environments.
Polycarbonate handles the majority of lens throughput; metal frames are gaining share fastest in specialized high-temperature applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums for ANSI Z87.1-certified eyewear in the United States sit 15-25% above comparable EN 166-rated products in Germany, reflecting divergent liability frameworks and insurance-driven replacement cycles.
United States
OSHA 29 CFR 1910.133 enforcement intensification accelerates employer-provided equipment refresh rates in construction and manufacturing. Federal infrastructure spending through the Department of Transportation mandates single-source safety providers on bridge and highway contracts. Houston and Dallas construction corridors drive concentrated procurement volumes for integrated PPE bundles.
Germany
REACH restrictions on bisphenol-A extend scrutiny to polycarbonate lens formulations, pressuring manufacturers to validate BPA-free alternatives. EU 2016/425 notified bodies require enhanced substance documentation for CE marking renewals. The Ruhr industrial belt and Bavarian manufacturing clusters anchor optical-grade injection molding capacity for continental supply.
China
Optical-grade polycarbonate injection capacity clusters in coastal provinces, exposing supply chains to port congestion and tariff friction. GB standards for occupational eye protection align gradually with international impact certification tiers. The Yangtze River Delta and Pearl River Delta house dominant lens fabrication facilities serving export markets.
Japan
METI industrial safety guidelines emphasize smart eyewear integration into connected worker monitoring systems. JIS standards for impact resistance maintain technical parity with ANSI and EN benchmarks. The Chubu region around Nagoya concentrates precision molding expertise for high-clarity optical components.
India
Bureau of Indian Standards certification requirements for industrial PPE expand addressable market for imported ANSI and EN certified products. Construction sector growth in infrastructure and commercial real estate drives baseline demand. Maharashtra and Gujarat industrial corridors absorb volume shipments for petrochemical and automotive manufacturing applications.
Protective Eye Wear Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in lens resin and frame molding. The vendor base stratifies between diversified industrial conglomerates bundling eyewear with respiratory and hearing protection, and focused safety equipment manufacturers competing on certification breadth. Three archetypes dominate: integrated PPE platforms, optical component specialists, and connected safety technology developers. Consolidation pressure operates through buyer aggregation among national construction contractors and captive distribution network expansion by incumbent conglomerates.
Among diversified industrial platforms, 3M Company and Honeywell International Inc. represent the bundled-safety archetype, leveraging captive distribution to convert discrete product sales into recurring revenue streams. MSA Safety occupies a position exemplifying the connected safety convergence, anchoring its market presence through integration of smart eyewear into broader worker monitoring systems rather than standalone product competition. These three entities illustrate the strategic divergence between scale-driven platform economics and technology-differentiated specialization.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| MSA Safety |
| Bollé Safety |
| Uvex Safety Group |
| Pyramex Safety Products, LLC |
| Radians, Inc. |
| MCR Safety |
| Gateway Safety Inc. |
| Others |
Value Network & Pricing Analysis
The Shanghai-Ningbo container corridor's freight volatility feeds directly into polycarbonate lens landed costs, amplifying price spreads between standard ANSI Z87.1-certified safety glasses and configured-to-order prescription-integrated frames while compressing margins for distributors without captive molding capacity.
Pricing Analysis
Configured-to-order prescription-compatible frames command 35-50% premiums over standard non-corrective safety glasses. Three-tier pricing structure across premium smart-eyewear, standard ANSI-certified, and economy uncertified channels reflects certification investment and sensor integration levels. Cost compression in the economy tier is intensifying because Asian molders are absorbing benzene feedstock spikes to maintain volume share. General contractors on federal infrastructure projects show the lowest price sensitivity due to liability-driven procurement mandates, while secondary market construction subcontractors exhibit acute sensitivity to per-unit replacement costs.
Supply Chain Analysis
Benzene and phosgene feedstock costs from Gulf Coast petrochemical complexes and Rotterdam refining hubs anchor polycarbonate resin pricing for lens fabricators. Optical-grade injection capacity concentrates in coastal China, South Korea, and the German Ruhr industrial belt. Supply chain risk centers on single-source vulnerability at the phosgene intermediate level, where European REACH documentation requirements are disqualifying secondary suppliers. Distribution runs through integrated safety equipment distributors and direct procurement channels to national construction aggregates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction sector capital expenditure cycles are recovering from trough levels, with federal infrastructure disbursements and OSHA enforcement intensification providing cyclical lift that sustains replacement demand regardless of private construction starts.
For Market Incumbents: Entrench market position through captive supply of optical-grade polycarbonate resin and accelerated certification for blue-light filtering under EU 2016/425 harmonized standards. Threat exposure from connected safety platform developers demands counter-investment in heads-up display integration. Backward integration into lens molding insulates margin structures from petrochemical feedstock volatility. For New Entrants and Emerging Players: Mid-market healthcare facilities in secondary US metropolitan areas represent the most penetrable entry point, as infection control protocol mandates outpace established supplier service capacity. Laser surgery suite protection equipment offers technology differentiation with lower certification burden than industrial ANSI tiers. Go-to-market execution should prioritize GPO contracts managers at regional hospital systems over national accounts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core PPE assets amid portfolio rationalization pressures. Long-term viability hinges on regulatory compliance capabilities rather than manufacturing scale alone. The inflection signal to watch is acceleration in EU notified body enforcement actions against BPA-containing polycarbonate formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Safety Platform Integration | MSA Safety's worker monitoring systems demonstrate 40-60% price premiums for sensor-embedded ANSI-certified frames. |
| Dual-Certification Investment | Simultaneous ANSI Z87.1 and EN 166 validation opens Department of Transportation and EU infrastructure contract access. |
| Prescription Lens Compatibility Program | Specialized optician training partnerships address the scarce fitting capacity constraining high-wrap frame adoption. |
| Equipment-as-a-Service Launch | Leasing models converting capex to opex penetrate mid-market contractors facing working capital pressure. |
| BPA-Free Copolymer Development | German notified body documentation requirements under REACH are accelerating bio-based formulation programs. |
Research Methodology
Initial hypotheses were tested against primary input from safety equipment procurement directors, construction site managers, optical lens molders, and OSHA compliance officers and refined through secondary validation against SEC 10-K filings, customs trade data, ANSI standards documentation, and EU notified body certification records. Bottom-up demand modeling from end-use segment interviews was triangulated with top-down market sizing from trade association shipment data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application vertical, prescription compatibility tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to normalized baseline values, incorporating polycarbonate resin price indices, construction employment statistics, and healthcare capital expenditure surveys as industry-specific inputs.
Stress conditions across benzene feedstock spikes, port congestion duration, and OSHA penalty escalation schedules were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and certification standard stability. Cross-checking against Bureau of Labor Statistics occupational injury incidence data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Saudi Arabia Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
In Room Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Guns Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Electronic Siren Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplied Air Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Diving and Survival Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Fit Tester Market