
 Global Surgical Mask and Respirators Market | 2026-2036
Global Surgical Mask and Respirators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Mask and Respirators Market Foresight
The EU Green Deal is recalibrating procurement criteria across European healthcare systems toward lower-carbon personal protective equipment. 3M Company leverages its filtration science portfolio to sustain premium positioning in N95 and elastomeric lines. Honeywell International Inc. anchors industrial safety channels with certified respiratory systems for construction and pharmaceutical manufacturing.
Surgical masks and respirators are barrier devices constructed from multi-layer nonwoven polypropylene with melt-blown filtration media, designed to block airborne particles and biological aerosols from reaching the respiratory tract. N95 respirators and surgical masks command the largest volume pools in medical settings, while powered air-purifying respirators capture expanding margins in pharmaceutical manufacturing where contamination control standards are most stringent. Distribution through direct hospital supply contracts captures stable recurring revenue, whereas online retailers compete on price transparency for industrial and dental clinic buyers.
FDA clearance pathways in the United States and CE marking under the EU Medical Device Regulation govern market access, with NIOSH certification remaining the benchmark for occupational respiratory protection. India's CDSCO and BIS standards are converging toward international filtration benchmarks, accelerating formal quality upgrading in domestic production. Stakeholders must monitor how national stockpile mandates and hospital sustainability scorecards reshape volume allocation between disposable and reusable platforms.
Market Dynamics
Hospital procurement departments in the United States are expanding stockpile mandates while the EU Medical Device Regulation tightens conformity assessment pathways, creating a bifurcated demand structure between emergency preparedness and premium certification tiers.
Growth Catalysts
- NIOSH Certification Mandates:US hospital systems now require N95 respirators with active NIOSH approval for pandemic stockpiles, pulling volume toward certified domestic manufacturers and away from uncertified imports.
- Pharmaceutical Cleanroom Expansion:Contamination control standards in sterile drug manufacturing are tightening globally, driving specification upgrades to powered air-purifying respirators with HEPA filtration integration.
- India's Tier-1 Infrastructure Buildout:Delhi, Mumbai, and Bangalore hospital networks are scaling ICU capacity, concentrating surgical mask demand in metropolitan procurement clusters with formal quality requirements.
Market Restraints
- Melt-Blown Polypropylene Concentration:Filtration media supply concentrates among Asian petrochemical converters, exposing finished goods manufacturers to feedstock price volatility and single-source risk.
- EU MDR Transition Friction:The Medical Device Regulation's stricter notified body requirements extend CE marking timelines for new respirator entrants, compressing margin recovery windows.
- Reusable Elastomeric Substitution:Industrial buyers in construction and chemical processing are pivoting toward washable half-mask respirators, eroding disposable N95 volume in non-medical channels.
Strategic Opportunities
- Brazil's ANVISA Formalization:Regulatory upgrading in Latin America's largest healthcare market creates entry windows for manufacturers with established ISO 13485 quality systems and in-country registration capabilities.
- E-Commerce Channel Penetration:Online retailers are capturing price-transparent industrial and dental clinic buyers, disintermediating traditional distribution and enabling direct-to-practice subscription models.
- Biodegradable Nonwoven Convergence:PLA and PHA bio-polymers are crossing performance thresholds for surgical mask outer layers, aligning with EU Green Deal procurement criteria for lower-carbon PPE.
Industry Challenges
- Filtration Engineer Scarcity:Melt-blown process optimization and electrostatic charging expertise concentrates among aging specialists, constraining quality scaling for new market entrants.
- Legacy ERP Integration:Hospital supply chain software requires customized EDI protocols for automated reordering, extending sales cycle complexity for mid-tier manufacturers without IT integration teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Mask and Respirators Market |
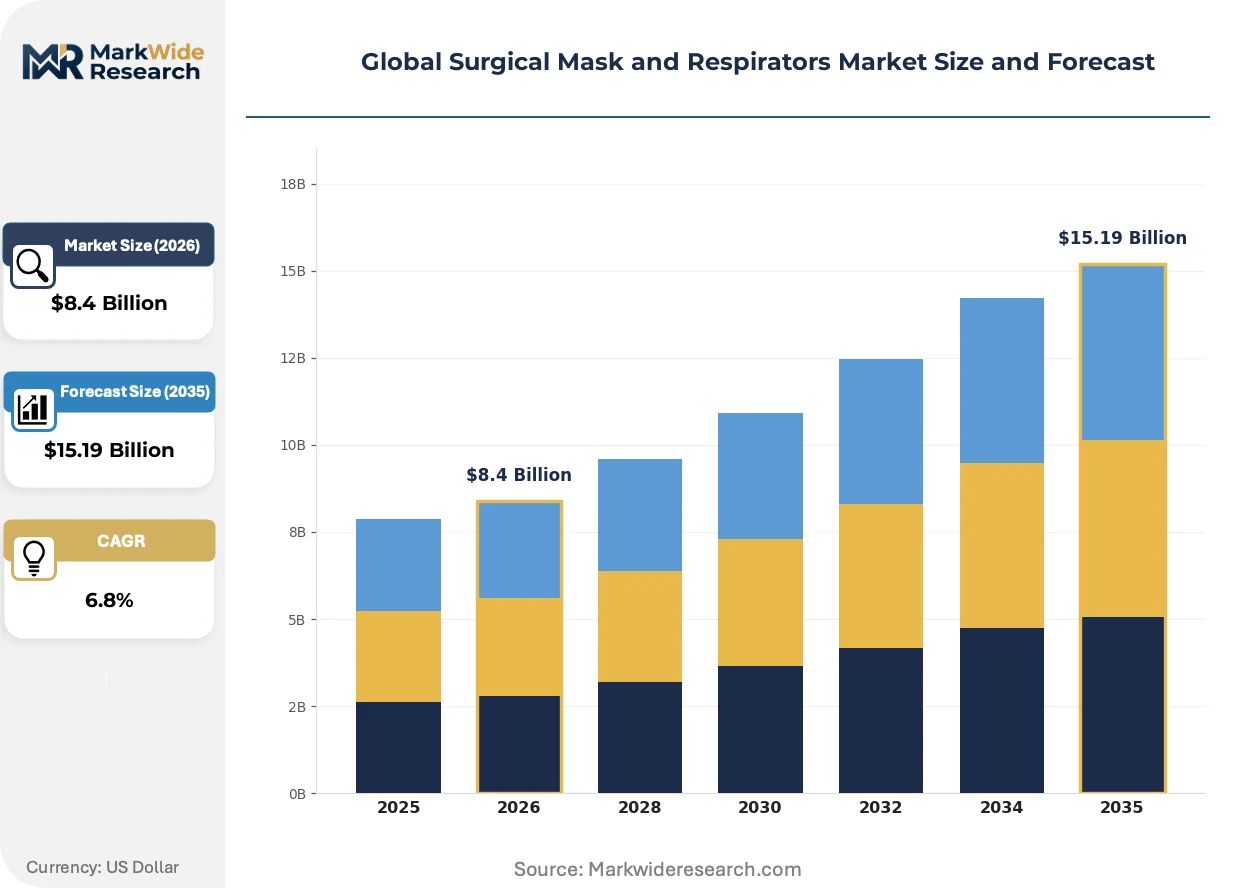
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Masks, N95 Respirators, KN95 Respirators, Elastomeric Respirators, Powered Air-Purifying Respirators Application: Medical Settings, Industrial Safety, Construction, Pharmaceutical Manufacturing, Food Processing End User: Hospitals, Fire Departments, Laboratories, Dental Clinics, Emergency Response Teams Distribution Channel: Online Retailers, Pharmacies, Medical Wholesalers, Direct Hospital Supply, Specialty Safety Stores |
| Companies Covered | 3M Company, Honeywell International Inc., Kimberly-Clark Corporation, Ansell Ltd., Cardinal Health, Medline Industries, DuPont, Owens & Minor, Prestige Ameritech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Mask and Respirators Market Shifts & Advancements
Active filtration science is reshaping competitive positioning across medical and industrial channels, with material breakthroughs and regulatory recalibration converging to redefine product hierarchies and procurement criteria.
Electrospun nanofiber membranes are achieving sub-micron filtration efficiency at reduced breathing resistance. Pharmaceutical cleanroom operators in Germany and Switzerland are specifying these materials for extended-wear applications. Nanofiber integration is electrifying the premium tier, compressing the performance gap between disposable N95s and powered air-purifying systems.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating oil-repellent treatments from European-market respirators. Manufacturers are reformulating outer layers with silicone-based alternatives or eliminating repellency altogether. The industrial segment is absorbing the largest compliance burden, with construction buyers accepting reduced splash protection in exchange for regulatory continuity.
Subscription-based inventory management is replacing spot purchasing for large hospital networks. Third-party logistics providers now hold title to mask stockpiles until point-of-use consumption, transferring carrying cost and obsolescence risk from providers to distributors. This model is most visible in US integrated delivery networks with centralized supply chain governance.
Global Surgical Mask and Respirators Market Segmentation
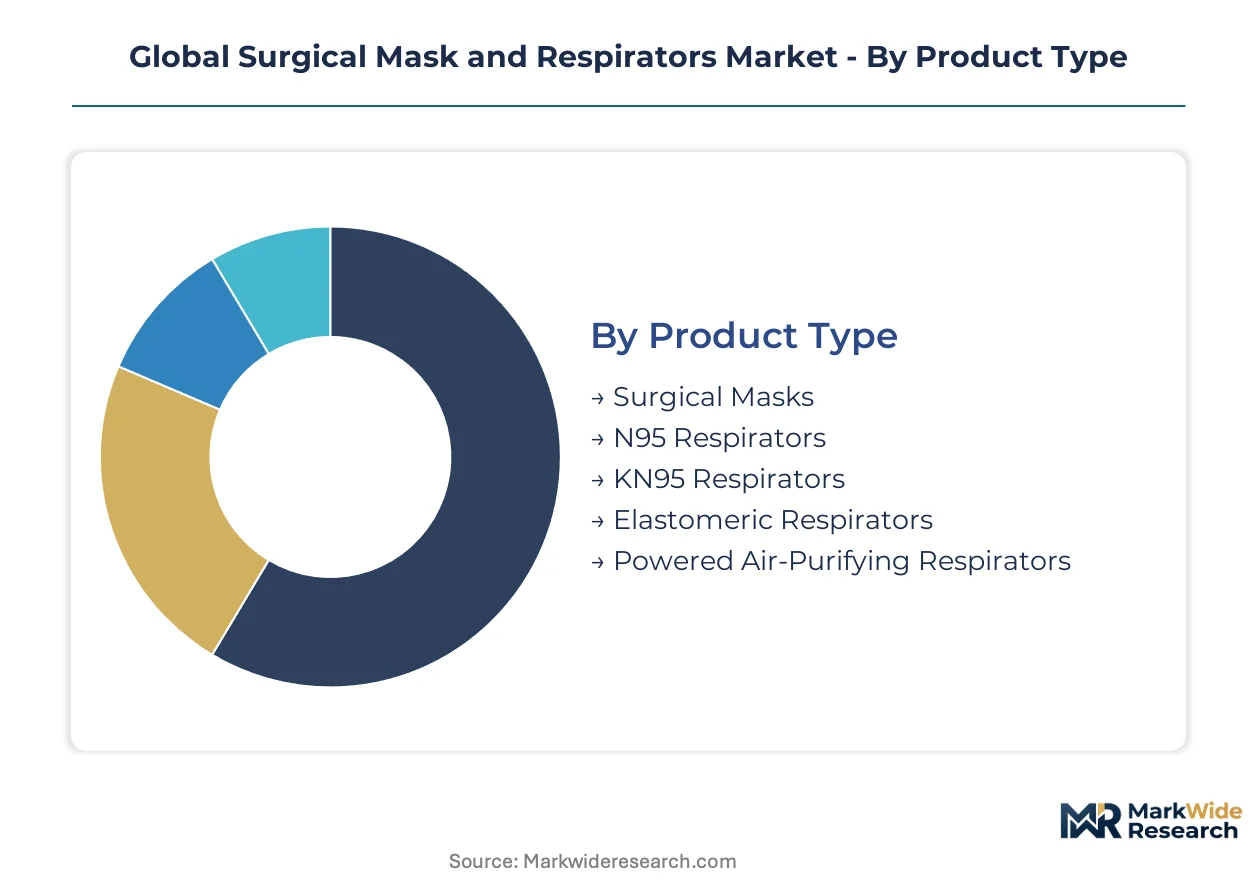
Product architecture in respiratory protection spans disposable barriers to powered systems, with each tier commanding distinct procurement workflows and margin structures. Segmentation clarity enables manufacturers to align R&D cycles with certification pathways and end-user specification clusters.
Product Type:
Customization intensity ranges from commodity disposables to engineered life-support systems, with filtration media sophistication determining price architecture and regulatory burden.
- Surgical Masks:Three-ply nonwoven polypropylene construction with melt-blown filtration cores serves routine medical procedures and general barrier protection. Hospital procurement in Delhi, Mumbai, and Bangalore drives volume concentration as India's tier-1 ICU capacity expands under formal quality mandates.
- N95 Respirators:Cup-shaped or flat-fold designs with electrostatically charged melt-blown media achieve 95% particle filtration at 0.3 microns. US hospital stockpile mandates under NIOSH certification pull demand toward domestic manufacturers with active approval numbers, compressing import viability.
- KN95 Respirators:Chinese-standard equivalents with ear-loop designs and GB 2626-2019 compliance serve price-sensitive industrial buyers.
- Elastomeric Respirators:Reusable silicone or thermoplastic elastomer facepieces with cartridge filtration target construction and chemical processing sectors pivoting toward washable platforms.
- Powered Air-Purifying Respirators:Battery-driven blower units with HEPA integration command pharmaceutical cleanroom specifications where contamination control standards are most stringent.
Leading the category by volume: Surgical Masks. Expanding most quickly: Powered Air-Purifying Respirators.
Application:
End-use concentration shapes certification requirements, with medical and pharmaceutical channels demanding the most stringent conformity assessments.
- Medical Settings:General ward and surgical suite deployment requires FDA or CE-marked devices with biocompatibility testing. EU MDR transition friction extends approval timelines for new entrants, favoring incumbents with established notified body relationships.
- Industrial Safety:Manufacturing and chemical plant protocols specify NIOSH-certified respirators for particulate and vapor exposure. REACH restrictions on PFAS oil-repellent treatments force formulation changes, with construction buyers accepting reduced splash protection.
- Construction:Silica dust and asbestos abatement drives respirator specification, with reusable elastomeric platforms gaining share against disposables.
- Pharmaceutical Manufacturing:Sterile drug production cleanrooms in Germany and Switzerland specify powered air-purifying systems with integrated HEPA and active carbon filtration.
- Food Processing:Hairnet-compatible surgical masks with metal-detectable nose bridges serve hygiene protocols in meat and dairy operations.
Dominating procurement value: Pharmaceutical Manufacturing. Steepest specification climb: Industrial Safety.
End User:
Customer type determines contract structure, from centralized hospital supply agreements to fragmented emergency responder purchasing.
- Hospitals:Integrated delivery networks in the United States consolidate purchasing through third-party logistics providers holding title to stockpiles until point-of-use consumption.
- Fire Departments:SCBA-compatible respirator systems require NFPA 1981 certification for structural firefighting and technical rescue.
- Laboratories:BSL-2 and BSL-3 containment facilities specify fit-tested N95 or P100 respirators with qualitative seal verification protocols.
- Dental Clinics:Small-practice buyers favor online retail channels with price transparency and subscription replenishment models.
- Emergency Response Teams:Pandemic stockpile and disaster preparedness procurement runs through federal and state health departments with surge capacity requirements.
Capturing largest contract value: Hospitals. Showing fastest channel shift: Dental Clinics.
Distribution Channel:
Channel selection reflects buyer scale and specification complexity, from automated hospital EDI to consumer self-service.
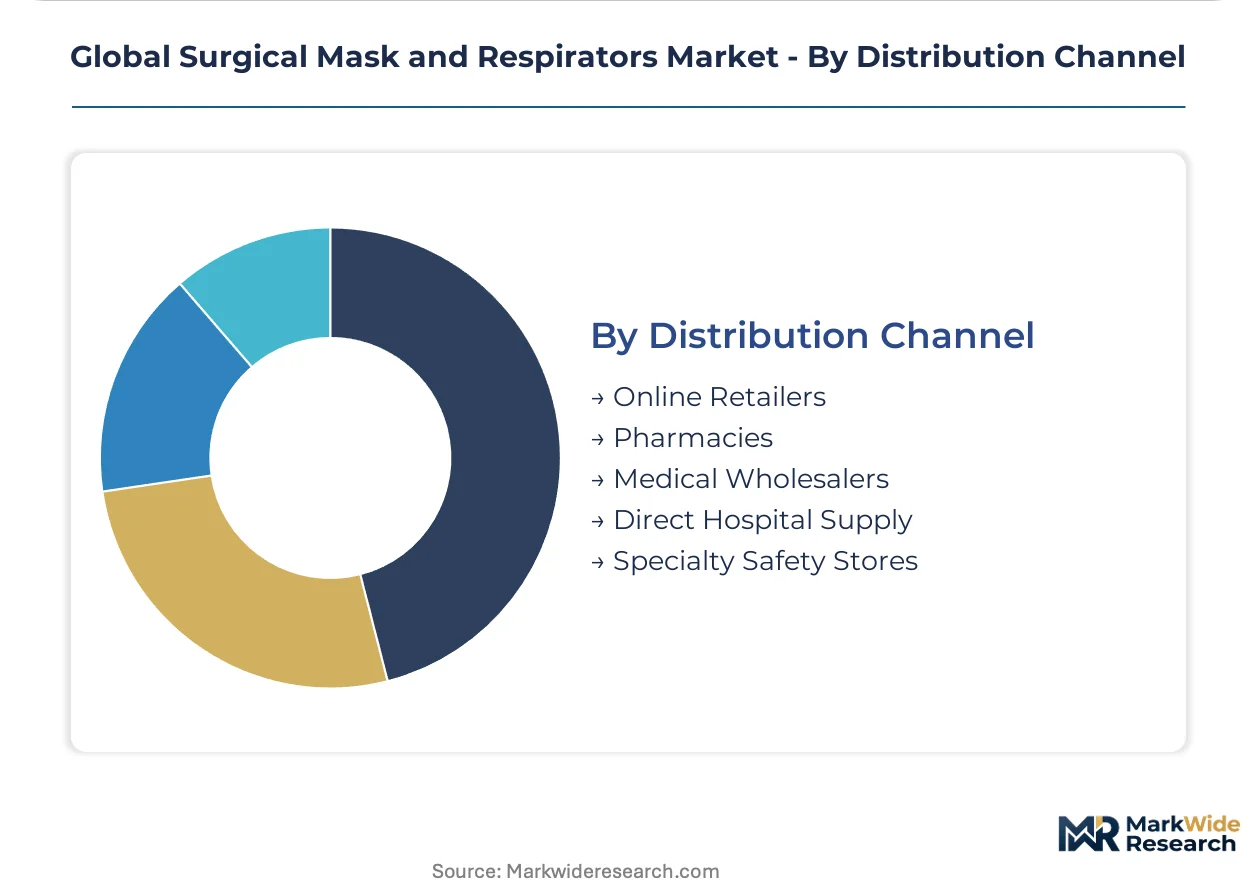
- Online Retailers:Amazon Business and specialized PPE platforms capture dental clinics and small industrial buyers with transparent pricing and rapid replenishment.
- Pharmacies:CVS, Walgreens, and Boots serve consumer and small-practice surgical mask demand with immediate availability.
- Medical Wholesalers:McKesson, Cardinal Health, and regional distributors manage hospital system contracts with customized ERP integration and consignment inventory.
- Direct Hospital Supply:Manufacturer-direct agreements with GPO-negotiated pricing capture stable recurring revenue from large health systems.
- Specialty Safety Stores:Grainger and regional industrial distributors serve construction and manufacturing with technical specification support and fit testing services.
Holding greatest volume concentration: Medical Wholesalers. Disintermediating fastest: Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Delhi, Mumbai, and Bangalore concentrate India's surgical mask procurement as tier-1 hospital networks scale ICU capacity under formal quality mandates. Hospital procurement departments in the United States are expanding stockpile mandates while the European Union Medical Device Regulation tightens conformity assessment pathways.
United States
NIOSH certification mandates pull hospital system volume toward domestic manufacturers with active approval numbers. The FDA governs market access for medical-grade respirators. Boston and New York procurement clusters drive subscription-based inventory management through third-party logistics providers.
Germany
Pharmaceutical cleanroom operators in Frankfurt and Basel-adjacent regions specify powered air-purifying respirators with HEPA integration. REACH restrictions on PFAS oil-repellent treatments force formulation changes for industrial buyers. The EMA and ECHA jointly recalibrate procurement criteria toward lower-carbon PPE under EU Green Deal alignment.
China
GB 2626-2019 compliance underpins KN95 production for price-sensitive industrial export channels. The NMPA and MIIT converge standards toward international filtration benchmarks. Zhejiang and Guangdong manufacturing clusters supply melt-blown polypropylene media to global finished goods producers.
India
CDSCO and BIS standards accelerate formal quality upgrading in domestic production. Delhi-NCR hospital networks scale ICU capacity with tier-1 procurement clusters demanding certified surgical masks. Mumbai and Bangalore metropolitan health systems concentrate specification-grade volume.
Brazil
ANVISA regulatory upgrading creates entry windows for manufacturers with established ISO 13485 quality systems. São Paulo and Rio de Janeiro health departments drive federal and state pandemic stockpile procurement. In-country registration capabilities determine market access for international suppliers.
Global Surgical Mask and Respirators Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with filtration science portfolios. NIOSH-certified domestic manufacturers capture US hospital stockpile volume. Three archetypes dominate: diversified industrials with materials science depth, medical supply specialists with hospital GPO relationships, and regional fabricators with cost-optimized KN95 production. M&A activity concentrates in distribution consolidation and electrostatic charging technology licensing.
Among diversified conglomerates, 3M Company and Honeywell International Inc. exemplify the premium-tier positioning archetype through filtration science depth and industrial safety channel anchoring. Kimberly-Clark Corporation occupies a position within the medical supply specialist tier, leveraging hospital system relationships and direct procurement contract structures.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| Kimberly-Clark Corporation |
| Ansell Ltd. |
| Cardinal Health |
| Medline Industries |
| DuPont |
| Owens & Minor |
| Prestige Ameritech |
| Others |
Supply & Pricing Matrix
US hospital procurement departments with expanded NIOSH stockpile mandates anchor pricing power toward certified domestic manufacturers, compressing import viability and sustaining premium tiers for N95 respirators against uncertified alternatives.
Pricing Analysis
Certification-grade pricing anchors value to NIOSH approval status and EU MDR conformity tiers. Three-tier pricing structure across premium NIOSH-certified, standard CE-marked, and economy KN95 tiers separates hospital systems from industrial buyers and price-sensitive dental clinics. Pricing pressure stems from reusable elastomeric substitution eroding disposable N95 volume in construction channels. Dental clinics exhibit highest price sensitivity through online retail channels, while pharmaceutical cleanroom operators show lowest sensitivity for powered air-purifying systems.
Supply Chain Analysis
Single-source vulnerability sits with Asian petrochemical converters supplying melt-blown polypropylene filtration media. Finished goods manufacturing draws from China, India, and domestic US facilities for NIOSH-certified production. Raw material dependencies center on polypropylene resin, electrostatic charging equipment, and silicone elastomer for reusable facepieces. Tariff exposure on Chinese-sourced media concentrates risk for non-vertically integrated assemblers. Distribution runs through medical wholesalers with hospital EDI integration and third-party logistics consignment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation's stricter notified body requirements create a cost-of-compliance moat favoring incumbents with established CE marking pathways and compressing margin recovery windows for unprepared entrants.
For Market Incumbents: Anticipate elastomeric substitution threats in industrial channels by deepening backward integration into melt-blown media production and accelerating biodegradable nonwoven R&D to capture EU Green Deal procurement criteria. Reinforce hospital GPO relationships through subscription-based inventory management with third-party logistics providers holding title to stockpiles until point-of-use consumption. For New Entrants and Emerging Players: Enter via Brazil's ANVISA formalization window by establishing ISO 13485 quality systems and in-country registration capabilities before regulatory upgrading closes access. Target price-transparent dental clinic procurement through direct-to-practice subscription models disintermediating traditional distribution, leveraging e-commerce channel penetration for rapid scale without legacy ERP integration burdens. For Investors and Strategic Acquirers: The window for entry favors electrostatic charging technology specialists and regional distributors with hospital system relationships. Long-term viability hinges on filtration science depth rather than commodity assembly capacity. Watch NIOSH certification backlog duration as the inflection signal for domestic manufacturing capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| NIOSH Certification Investment | Unlocks US hospital stockpile procurement through FDA-cleared domestic production pathways. |
| Biodegradable Nonwoven Development | Aligns product portfolios with EU Green Deal lower-carbon PPE procurement criteria. |
| Hospital System Partnership | Secures recurring revenue through GPO-negotiated direct supply contracts with automated reordering. |
| Electrospun Nanofiber Integration | Captures pharmaceutical cleanroom premium tier with sub-micron filtration at reduced breathing resistance. |
| Third-Party Logistics Consignment | Transfers carrying cost and obsolescence risk from providers to distributors in integrated delivery networks. |
Research Methodology
Multi-period observation of NIOSH approval timelines, EU MDR transition friction, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with hospital supply chain directors, filtration media engineers, GPO contracts managers, and industrial safety procurement leads. Secondary validation drew from FDA 510(k) filings, EMA medical device databases, NIOSH certified equipment lists, and hospital procurement database aggregators. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, end user, and distribution channel segments.
Input-output matrices mapped melt-blown polypropylene feedstock availability to finished goods capacity across the projection horizon, with segmentation dimensions spanning certification tier, end-use vertical, and regional regulatory cluster. CAGRs derived from regression analysis against hospital infrastructure investment cycles and pharmaceutical cleanroom expansion trajectories. Industry-specific forecast inputs included NIOSH approval queue depth and REACH restriction implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pandemic surge demand scenarios and trade policy shifts affecting Asian filtration media supply. Forecasts reflect documented assumptions regarding regulatory timeline adherence and hospital sustainability scorecard adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Spill Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Latin America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
US Negative Pressure Escape Masks Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Personal Protective Equipment Kit Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Strobe Beacon Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market