
 Global Polypropylene Catalyst Market | 2026-2036
Global Polypropylene Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polypropylene Catalyst Market Foresight
Market Context
The polypropylene catalyst trade is restructuring around a widening split between premium metallocene grades and commodity Ziegler-Natta output. LyondellBasell Industries leverages its proprietary multizone circulating reactor technology to dominate high-margin specialty resin contracts. Clariant AG sustains a differentiated position through advanced donor chemistry for controlled tacticity. Mitsui Chemicals, Inc. anchors Asian supply chains with integrated catalyst-polymer production in Japan and Thailand.
Technical Profile and Segment Dynamics
A polypropylene catalyst is a stereospecific organometallic compound, typically titanium-based with magnesium chloride supports and electron donors, that initiates the polymerization of propylene monomer into isotactic polypropylene with controlled molecular weight distribution and melt flow index. Its primary industrial purpose is to enable gas phase and slurry processes that yield resins for injection molding, biaxially oriented film, and fiber applications. Metallocene catalysts command premium positioning due to narrow polydispersity and superior optical properties in packaging films, while Ziegler-Natta systems retain volume leadership across construction materials and commodity consumer goods where cost efficiency outweighs performance differentiation. Gas phase polymerization technology leads capacity additions globally because it eliminates hydrocarbon diluent recovery and reduces capital intensity versus slurry alternatives.
Regulatory Environment and Strategic Outlook
EPA emissions standards in the United States, REACH chemical registration requirements in Europe, and China's GB standards for volatile organic compound limits collectively tighten specifications for catalyst residue levels and polymer extractables. These frameworks force catalyst producers to reformulate activator systems and validate lower-residue performance across multiple jurisdictions. Stakeholders must monitor regulatory divergence between EU Green Deal chemical sustainability targets and divergent national implementation timelines to avoid stranded formulation investments.
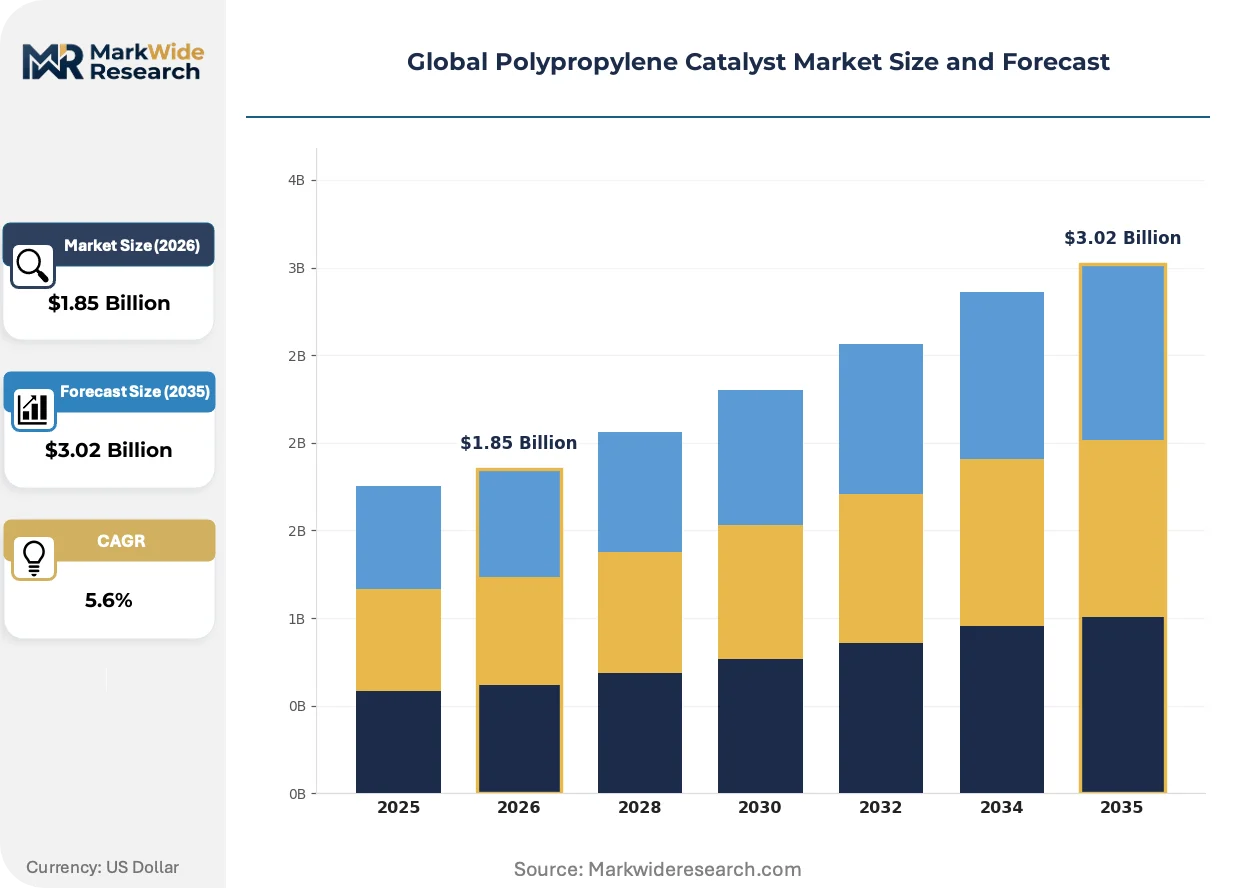
Market Dynamics
Metallocene catalyst systems are compressing margins for commodity Ziegler-Natta producers while China's dual carbon goals and Saudi Arabia's petrochemical corridor expansion reshape production geography. This bifurcation between premium and standard grades defines competitive positioning across the forecast window.
Growth Catalysts
- Lightweight automotive mandates:Component manufacturers in Germany and Japan are expanding catalyst orders for interior parts that reduce vehicle weight and improve fuel efficiency.
- China's dual carbon goals:Stricter MEE emissions rules are pushing domestic producers toward higher-efficiency metallocene systems with lower residue profiles.
- Film packaging premiumization:Biaxially oriented polypropylene demand for optical clarity in food packaging is pulling narrow-polydispersity catalyst adoption.
Market Restraints
- Titanium feedstock volatility:Sponge titanium prices fluctuate with aerospace demand cycles, compressing catalyst producer margins unpredictably.
- Donor chemistry concentration:Advanced electron donor supply concentrates among specialty chemical producers in Switzerland and Germany, creating single-source vulnerability.
- REACH registration friction:ECHA requirements for new organometallic activators extend validation timelines by 18-24 months versus legacy formulations.
Strategic Opportunities
- India's polymer capacity buildout:Reliance Industries and Indian Oil Corporation are expanding propylene derivative complexes along the Gujarat coast, creating catalyst demand without established supplier relationships.
- Chemical recycling integration:Pyrolysis-based polypropylene recovery requires reformulated catalyst tolerant to trace oxygen contamination in recycled feedstock.
- EU Green Deal tailwinds:CSRD disclosure requirements favor catalyst systems with verified lifecycle carbon footprints, rewarding early certifiers.
Industry Challenges
- Organometallic synthesis expertise:The specialized skill set for air-sensitive titanium-magnesium chloride complex preparation limits qualified engineering hires.
- Reactor retrofit capex:Converting slurry-phase assets to gas-phase metallocene compatibility requires $40-60 million per train at existing petrochemical sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polypropylene Catalyst Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.02 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ziegler-Natta Catalysts, Metallocene Catalysts, Chromium Catalysts, Phillips Catalysts Application: Packaging Films, Automotive Components, Construction Materials, Consumer Goods End User Industry: Plastic Manufacturers, Chemical Producers, Textile Fabricators, Household Appliance Makers Technology: Gas Phase Polymerization, Slurry Polymerization, Bulk Polymerization, Solution Polymerization |
| Companies Covered | LyondellBasell Industries, W. R. Grace & Co., Clariant AG, Mitsui Chemicals, Inc., BASF SE, INEOS, China Petrochemical Corporation, Sumitomo Chemical Co., Ltd., TOHO Titanium Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polypropylene Catalyst Market Shifts & Advancements
Digital process control and modular reactor design are compressing catalyst development cycles while regulatory pressure on polymer extractables forces formulation transparency. These forces are converging to reward integrated catalyst-polymer producers over standalone suppliers.
Single-site metallocene catalysts with constrained-geometry architecture are overtaking conventional Ziegler-Natta systems in packaging film applications. European and Japanese converters are adopting these systems at twice the rate of North American counterparts. The technology is overtaking commodity resin pricing benchmarks by enabling downgauging that reduces material usage without performance sacrifice.
REACH authorization requirements for boron-based activators are tightening residue specifications across European polymer imports. ECHA's 2024 updated guidance on substance evaluation extends compliance documentation for catalyst producers selling into EU markets. Asian exporters are responding by reformulating with aluminum-based co-catalysts that face lighter regulatory scrutiny.
Direct catalyst supply contracts between producers and integrated petrochemical operators are displacing distributor-mediated procurement in the Middle East and Southeast Asia. National oil companies in Saudi Arabia and Thailand are consolidating vendor panels to three approved suppliers per technology type. This concentration is most visible in Jubail Industrial City, where SABIC-affiliated ventures now source 70 percent of catalyst volumes through sole-source agreements.
Global Polypropylene Catalyst Market Segmentation
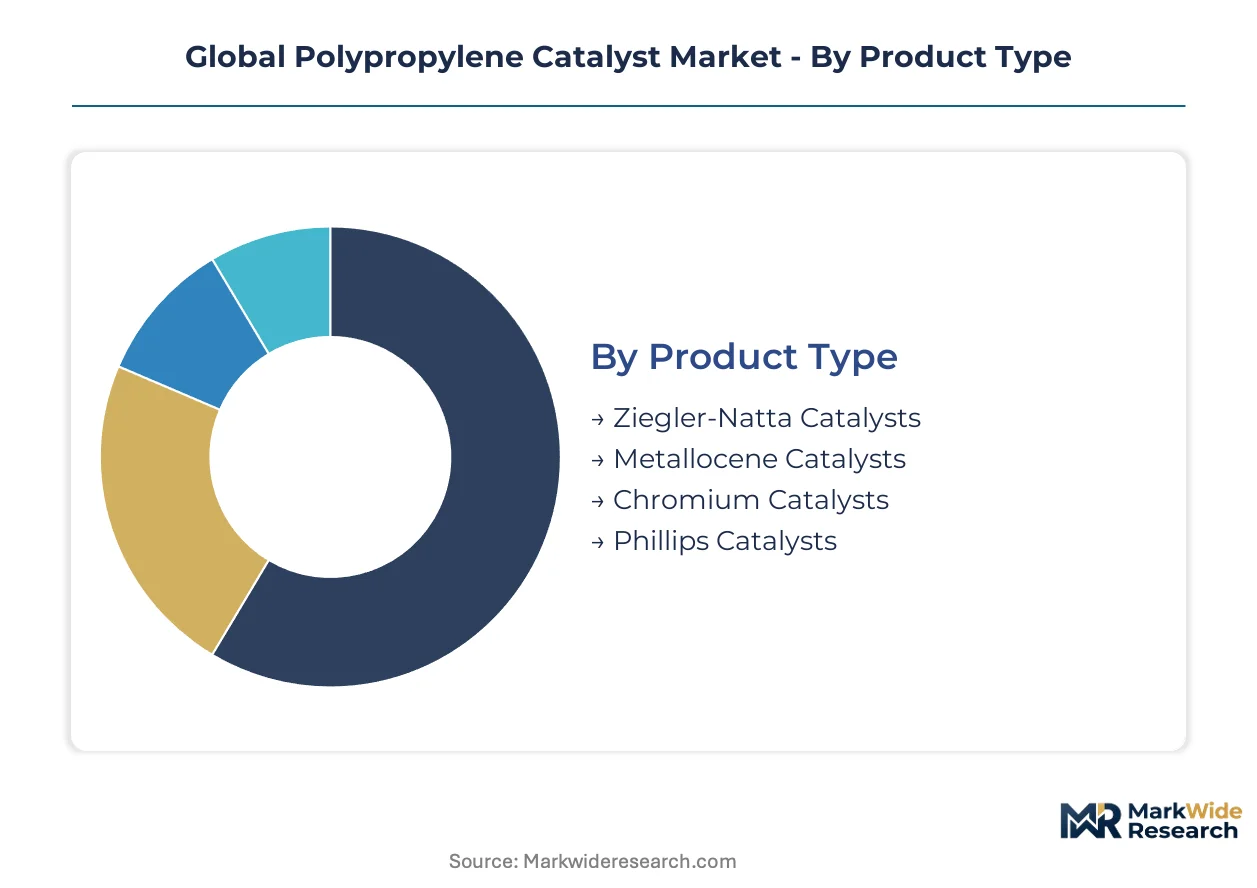
Catalyst selection in polypropylene production determines reactor efficiency, resin grade capabilities, and regulatory compliance profiles. Segment boundaries reflect divergent technical requirements across automotive lightweighting mandates, China's MEE emissions enforcement, and film packaging optical clarity standards.
Product Type:
Customization intensity varies from commodity Ziegler-Natta formulations to precision-engineered metallocene architectures with constrained-geometry active sites.
- Ziegler-Natta Catalysts:Titanium-magnesium chloride complexes with alkyl aluminum co-catalysts dominate commodity resin production for construction and consumer goods. Demand concentrates in Saudi Arabia's Jubail Industrial City where SABIC-affiliated ventures prioritize cost-efficient slurry-phase output for regional construction booms.
- Metallocene Catalysts:Single-site organometallic systems with narrow polydispersity enable downgauged packaging films and automotive interior components. German and Japanese converters adopt these systems at accelerated rates to meet lightweighting mandates and EU Green Deal carbon disclosure requirements.
- Chromium Catalysts:Phillips-type silica-supported systems serve high-density polyethylene crossover applications with limited polypropylene deployment.
- Phillips Catalysts:Chromium oxide on silica carriers find niche use in specialty copolymer grades requiring broad molecular weight distribution.
Most installed capacity flows through Ziegler-Natta systems. Expansion is steepest in metallocene catalysts.
Application:
Volume distribution tracks end-use durability requirements versus optical performance premiums across downstream converter networks.
- Packaging Films:Biaxially oriented polypropylene for food contact applications demands narrow polydispersity metallocene catalysts with low extractable profiles. European REACH compliance on boron-based activators is accelerating aluminum co-catalyst reformulation among Asian exporters.
- Automotive Components:Interior trim and under-hood applications require high melt flow index resins from Ziegler-Natta systems with controlled isotacticity. Japanese and German component manufacturers are expanding catalyst orders to meet corporate fleet efficiency targets.
- Construction Materials:Pipe, sheet, and injection-molded fittings utilize commodity-grade catalysts with broad processing windows.
- Consumer Goods:Durable household articles and disposable products balance cost optimization with adequate mechanical properties.
Film packaging commands the highest catalyst premiums per kilogram. Automotive applications are expanding most quickly.
End User Industry:
Procurement sophistication divides between integrated petrochemical operators with captive catalyst-polymer production and merchant resin purchasers.
- Plastic Manufacturers:Integrated polypropylene producers in Thailand and Saudi Arabia consolidate vendor panels to three approved suppliers per technology type, displacing distributor-mediated procurement.
- Chemical Producers:Diversified petrochemical operators leverage multizone circulating reactor technology for specialty resin contracts with narrow specification windows.
- Textile Fabricators:Fiber-grade polypropylene for nonwoven applications requires specific melt rheology controlled through donor chemistry selection.
- Household Appliance Makers:White goods manufacturers source compounded resins with pre-specified catalyst residue limits for indoor air quality compliance.
Plastic manufacturers absorb the majority of catalyst volumes. Chemical producers are gaining share fastest through backward integration into resin production.
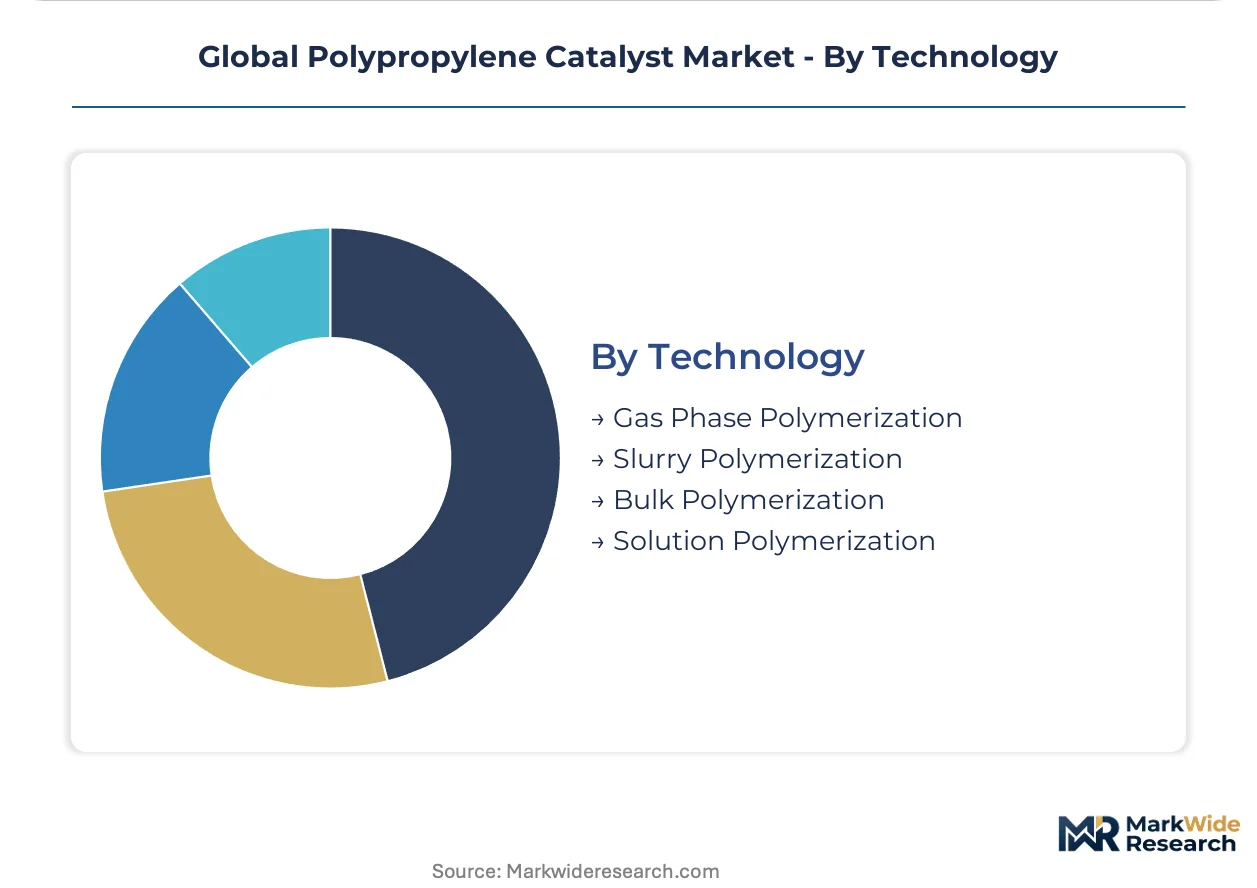
Technology:
Capital intensity and operating economics separate diluent-free gas phase systems from solvent-dependent alternatives.
- Gas Phase Polymerization:Fluidized bed reactors eliminate hydrocarbon diluent recovery, reducing capital intensity and enabling rapid grade transitions. China's dual carbon goals favor this technology for lower energy intensity versus slurry alternatives.
- Slurry Polymerization:Diluent-based loop reactors retain volume leadership in legacy assets producing commodity homopolymers and random copolymers.
- Bulk Polymerization:Liquid propylene monomer as sole diluent suits medium-scale operations with simplified product slate requirements.
- Solution Polymerization:Homogeneous catalysis in solvent media serves specialty elastomeric copolymers with limited commercial scale.
Most new capacity additions deploy gas phase technology. Slurry polymerization maintains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized organometallic synthesis expertise clusters in Germany's Ruhr industrial belt and Japan's Chubu region, anchoring catalyst formulation capabilities that supply polymer producers across three continents. These talent concentrations shape regional competitive dynamics more than raw material proximity.
China
Domestic propylene derivative expansions along the Yangtze River Delta and Bohai Rim are absorbing metallocene catalyst volumes at accelerated rates. MEE emissions enforcement under dual carbon goals is disqualifying legacy Ziegler-Natta formulations with higher residue profiles. Zhejiang and Jiangsu provinces host the majority of catalyst-polymer integration projects commissioned since 2023.
Saudi Arabia
SABIC-affiliated ventures in Jubail Industrial City now source catalyst through sole-source agreements covering 70 percent of procurement volumes. The country's national oil company consolidation of vendor panels to three approved suppliers per technology type is displacing distributor networks. Eastern Province petrochemical corridors are expanding gas-phase polypropylene capacity with captive catalyst supply arrangements.
Germany
Ruhr-based chemical complexes maintain Europe's deepest pool of titanium-magnesium chloride synthesis engineers. REACH authorization timelines for boron-based activators extend 18-24 months versus legacy formulations, favoring incumbent producers with established dossiers. Bavarian automotive component manufacturers are expanding catalyst orders for lightweight interior trim meeting corporate fleet efficiency targets.
United States
Gulf Coast propylene derivative complexes in Texas and Louisiana are retrofitting slurry-phase assets for gas-phase metallocene compatibility at $40-60 million per train. EPA emissions standards on volatile organic compound limits tighten catalyst residue specifications for polymer extractables. Houston's catalyst formulation specialists serve integrated petrochemical operators with multizone circulating reactor technology.
Japan
Chubu region catalyst producers anchor Asian supply chains through integrated catalyst-polymer production in Nagoya and Yokkaichi. METI industrial policy supports domestic metallocene development to preserve specialty resin capabilities against Chinese cost competition. Automotive lightweighting mandates from Tokyo-based OEMs are pulling narrow-polydispersity catalyst adoption for interior components.
Global Polypropylene Catalyst Market Competitive Landscape
Top-tier vendors anchor proprietary multizone circulating reactor technology and advanced donor chemistry, while commodity formulation specialists compete on titanium feedstock sourcing and regional logistics. The vendor base stratifies across integrated petrochemical operators with captive catalyst production, standalone catalyst houses with formulation IP, and regional compounders serving merchant resin markets. Two dominant competitive moves are consolidating: direct supply contracts displacing distributor procurement in the Middle East and Southeast Asia, and reactor retrofit partnerships that lock in catalyst supply for gas-phase conversions.
Within the integrated technology tier, LyondellBasell Industries and Clariant AG occupy positions defined by reactor system integration and electron donor specialization respectively. Mitsui Chemicals, Inc. exemplifies the Asia-Pacific catalyst-polymer integration model with production assets spanning Japan and Thailand. These three entities represent distinct strategic archetypes—reactor technology licensor, donor chemistry specialist, and integrated regional producer—that structure competitive positioning across premium and standard grade segments.
| Leading Market Players |
|---|
| LyondellBasell Industries |
| W. R. Grace & Co. |
| Clariant AG |
| Mitsui Chemicals, Inc. |
| BASF SE |
| INEOS |
| China Petrochemical Corporation |
| Sumitomo Chemical Co., Ltd. |
| TOHO Titanium Co., Ltd. |
| Others |
Supply & Pricing Matrix
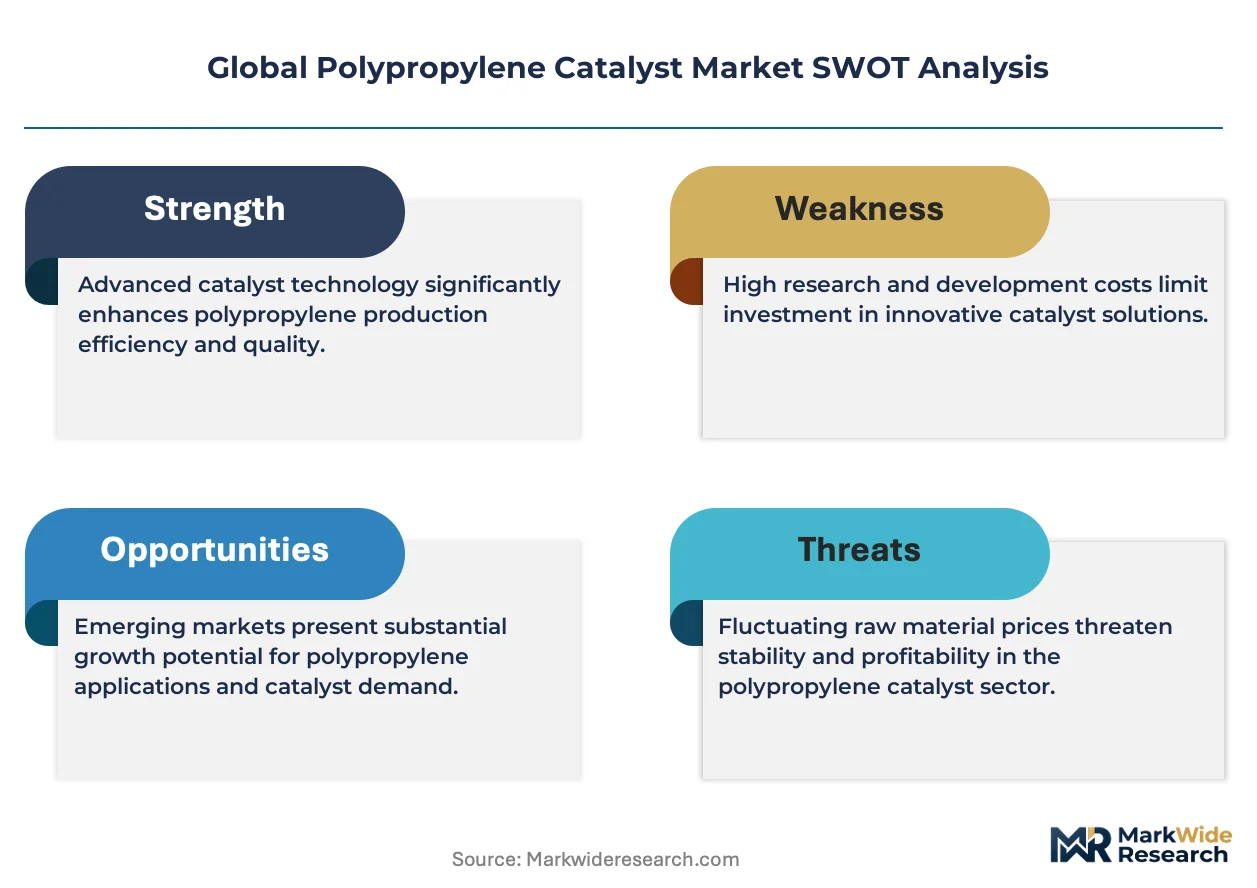
Sponge titanium price volatility cascades through catalyst manufacturing into three distinct pricing tiers that separate integrated petrochemical operators from merchant resin purchasers. Cost compression in commodity Ziegler-Natta formulations intensifies as aerospace demand cycles squeeze titanium feedstock margins, while metallocene premiums hold firm on donor chemistry scarcity.
Pricing Analysis
Technology-licensor bundling versus standalone catalyst supply defines the dominant pricing split. Three-tier pricing structure across metallocene premium, Ziegler-Natta standard, and economy-grade bulk separates reactor-integrated contracts from spot-market transactions. Price differentiation hinges on electron donor sophistication and REACH-compliant residue certification. Margins are tightening in commodity grades due to titanium sponge cost pass-through limitations. Merchant resin purchasers exhibit highest price sensitivity, while SABIC-affiliated ventures in Jubail absorb premiums for sole-source security.
Supply Chain Analysis
China's dual carbon goals and India's PLI scheme for petrochemicals are reshaping sourcing patterns toward domestic-content compliance. Titanium sponge concentrates in Japan and China, while advanced electron donor synthesis clusters in Switzerland and Germany. Catalyst production draws from magnesium chloride feedstocks anchored in Israel and Russia. Single-source vulnerability in alkyl aluminum co-catalyst supply creates structural risk. Distribution runs through direct supply contracts displacing distributor networks in Saudi Arabia and Thailand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in metallocene catalyst tiers as China's MEE emissions enforcement disqualifies legacy formulations. Cost-down drivers in gas-phase reactor retrofits unlock premium-grade penetration for integrated operators.
For Market Incumbents: Anticipate margin compression in commodity Ziegler-Natta grades as Chinese domestic producers achieve catalyst-polymer integration. Lock in sole-source agreements with national oil companies in Saudi Arabia and Thailand before vendor panel consolidation completes. Deepen backward integration into titanium sponge sourcing to offset aerospace demand cycle volatility. Prioritize REACH dossier maintenance for boron-based activators to preserve European market access against aluminum co-catalyst substitution.
For New Entrants and Emerging Players: Capture white-space in India's Gujarat coast polymer capacity buildout where Reliance Industries and Indian Oil Corporation lack established catalyst supplier relationships. Target chemical recycling integration opportunities requiring oxygen-tolerant reformulated catalysts. Penetrate through pyrolysis-feedstock compatibility testing partnerships with emerging European recyclers. Avoid direct confrontation with LyondellBasell's multizone circulating reactor licensing dominance in mature markets.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated catalyst-polymer producers possessing captive gas-phase technology and established donor chemistry IP. Long-term viability favors assets with demonstrated CSRD carbon footprint certification and sole-source contracts with Middle Eastern national oil companies. Monitor ECHA substance evaluation timelines as inflection indicator for boron-based activator authorization risk and aluminum co-catalyst substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Retrofit Partnership | Gas-phase conversion contracts lock in catalyst supply at Jubail Industrial City complexes. |
| Backward Integration into Titanium Sponge | Captive feedstock sourcing insulates margins from aerospace demand cycle volatility. |
| REACH Dossier Investment | Established boron-based activator authorization defends European market access against substitution. |
| CSRD Carbon Certification | Verified lifecycle footprints attract EU Green Deal-aligned procurement from German automotive OEMs. |
| Chemical Recycling Compatibility Program | Oxygen-tolerant formulations capture pyrolysis-feedstock demand from European packaging converters. |
Research Methodology
Bottom-up polymerization technology modeling reconciled against top-down catalyst production tracking forms the analytical core of this study. Primary interviews with plant managers at integrated petrochemical operators, procurement leads at downstream automotive component manufacturers, distribution channel partners in Middle Eastern industrial corridors, and technical R&D directors at donor chemistry specialists combined with secondary validation. Secondary sources encompass customs and trade data from major polypropylene exporting jurisdictions, SEC 10-K filings of diversified chemical producers, American Chemistry Council and Cefic industry reports, and ECHA substance evaluation databases.
Historical trendline analysis of capacity additions by polymerization technology type informs the projection framework. Segmentation dimensions modeled span catalyst architecture, end-use application, reactor technology configuration, and regional production hub characteristics. CAGRs derive from regression analysis of installed capacity trajectories and technology substitution elasticities across the projection horizon. Forecast inputs incorporate MEE emissions enforcement intensity in China, REACH authorization timelines for organometallic activators, and Saudi Aramco vendor panel consolidation schedules.
Titanium sponge price volatility, ECHA regulatory divergence from national implementation timelines, and chemical recycling feedstock quality variability are the dominant revision risks to the analytical envelope. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Polyurethane Catalysts Market
Catalysts
Polyolefin Catalyst Market
Catalysts
North America Refining Catalysts Market
Catalysts
Heavy Oil Cracking Catalyst Market
Catalysts
Industrial Catalytic Converters Market
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Organic Catalyst Market
Catalysts
Refinery Catalyst Market
Catalysts
Global Catalyst Market
Catalysts
Catalyst Regeneration Market
Catalysts
Global VOC Catalysts Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
North America Zeolite Market
Catalysts
FCC Catalyst Additive Market
Catalysts
Petrochemical Catalyst Market
Catalysts
Catalyst Handling Services Market