
 Global Catalyst Market | 2026-2036
Global Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Global Catalyst Market Analysis
Chinese petrochemical producers is broadening zeolite catalyst output for methanol-to-olefins plants. BASF SE leverages its Ludwigshafen integrated site to sustain rare-earth catalyst supply chains for automotive exhaust applications. Johnson Matthey Plc anchors hydrogen production catalyst demand through its differentiated membrane electrode assembly technology for electrolyzers.
A catalyst is a substance that accelerates chemical reactions without permanent consumption, typically structured as supported metal nanoparticles on alumina, silica, or zeolite carriers with surface areas exceeding 100 m²/g. Its primary industrial purpose is to enable selective conversion of feedstocks into higher-value products at reduced temperature and pressure. Heterogeneous catalysts occupy the dominant share of refining and petrochemical value chains due to their separability and thermal stability. Biocatalysts represent the fastest-expanding category as pharmaceutical manufacturers adopt enzymatic routes to replace solvent-intensive chemical synthesis.
EPA emission regulations and the EU Green Deal's carbon-border adjustment mechanism are forcing catalyst producers to certify lifecycle carbon intensity for exported materials. China's Ministry of Ecology and Environment enforces stricter volatile organic compound limits that elevate demand for low-temperature oxidation catalysts. REACH compliance in Europe adds formulation disclosure burdens that reshape competitive access for specialty catalyst suppliers. Stakeholders must monitor hydrogen economy policy signals to calibrate capital allocation between gray, blue, and green hydrogen production catalyst portfolios.
Market Dynamics
Refinery operators in India and China are expanding fluid catalytic cracking capacity to process heavier crude slates, forcing catalyst suppliers to reformulate zeolite structures for metal tolerance and thermal stability under more severe operating conditions.
Growth Catalysts
- EPA Tier 4 and Euro VII emission standards:These regulations tighten automotive catalyst specifications for nitrogen oxide and particulate matter reduction, mandating higher platinum group metal loadings and advanced washcoat formulations in diesel aftertreatment systems.
- China's coastal petrochemical clusters:Concentrated demand from methanol-to-olefins plants and integrated refinery-petrochemical complexes drives zeolite catalyst consumption for light olefin production from coal-derived feedstocks.
- Hydrogen electrolyzer deployment:Proton exchange membrane and alkaline electrolyzer manufacturing is accelerating demand for iridium, platinum, and nickel-based catalyst coatings in membrane electrode assemblies.
Market Restraints
- Rare-earth supply concentration:China controls over 80% of global rare-earth processing capacity, creating vulnerability for automotive exhaust catalyst producers dependent on cerium and lanthanum for oxygen storage components.
- Platinum group metal price volatility:Rhodium and palladium price spikes increase working capital requirements and compress margins for emission catalyst formulators locked into long-term automotive supply contracts.
- REACH formulation disclosure:ECHA registration requirements force proprietary catalyst compositions into public chemical safety dossiers, eroding intellectual property protection for specialty catalyst developers serving European pharmaceutical and fine chemical markets.
Strategic Opportunities
- India's refinery expansion corridor:Reliance Industries and Indian Oil Corporation are adding 1.5 million barrels per day of new crude processing capacity by 2030, creating demand for resid upgrading and hydroprocessing catalysts tailored to high-sulfur Middle Eastern crudes.
- Biocatalytic pharmaceutical synthesis:Enzymatic routes for active pharmaceutical ingredient manufacturing are displacing solvent-heavy chemical processes, opening demand for immobilized lipase and transaminase catalyst systems in contract manufacturing organizations.
- EU Green Deal carbon-border adjustment:The mechanism rewards catalyst producers certifying low-lifecycle-carbon production methods, favoring European manufacturers with renewable energy-integrated synthesis routes over import-dependent competitors.
Industry Challenges
- Catalyst characterization expertise shortage:Advanced electron microscopy and operando spectroscopy skills required for next-generation single-atom catalyst development are concentrated in a handful of academic and national laboratory centers, constraining R&D throughput.
- Extended automotive validation timelines:New emission catalyst formulations require 24-36 months of engine durability testing and on-road verification before OEM qualification, compressing product lifecycle returns before regulatory standards refresh.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Catalyst Market |
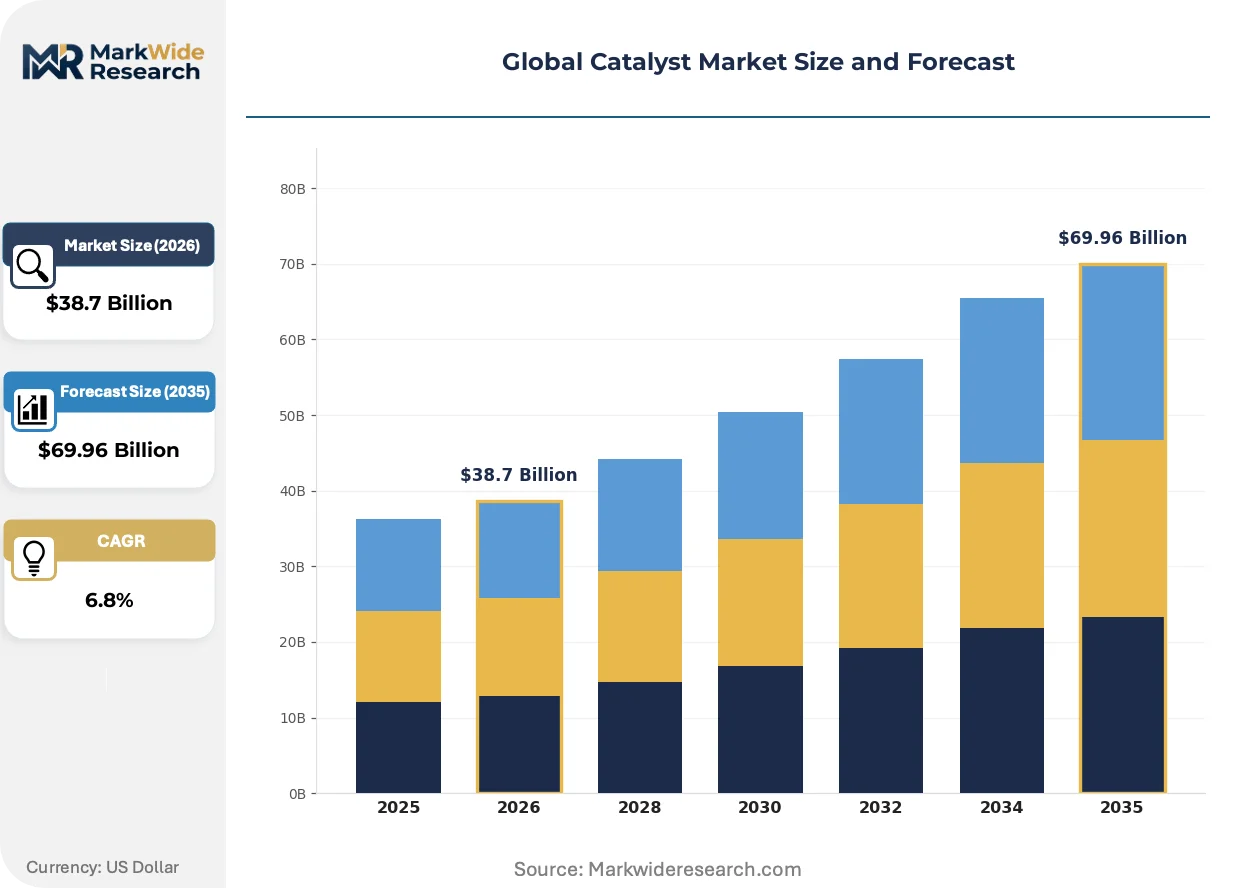
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heterogeneous Catalysts, Homogeneous Catalysts, Biocatalysts, Specialty Catalysts Application: Refining, Petrochemicals, Chemical Synthesis, Environmental End User: Oil & Gas, Chemicals, Automotive, Pharmaceuticals Technology: Fixed Bed, Fluidized Bed, Batch, Continuous |
| Companies Covered | BASF SE, Johnson Matthey Plc, Clariant AG, Honeywell UOP, Evonik Industries AG, Albemarle Corporation, W. R. Grace & Co., Axens, Haldor Topsoe A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Catalyst Market Emerging Trajectories
Digital process control and materials informatics are compressing catalyst development cycles, while regulatory carbon accounting and end-use electrification are redirecting R&D investment toward hydrogen and bio-based chemical production chemistries.
Single-atom catalysis is automating active site efficiency optimization by isolating individual metal atoms on nitrogen-doped carbon supports, eliminating particle sintering and metal leaching that plague conventional nanoparticle systems. BASF and Johnson Matthey are scaling these materials for selective hydrogenation in pharmaceutical intermediate production. The technology is automating yield improvements that previously required iterative batch screening, collapsing development timelines from years to months.
REACH authorization and restriction procedures are forcing substitution of cobalt and nickel catalysts in polyester polyol manufacturing, with ECHA designating these metals as substances of very high concern based on reproductive toxicity and carcinogenicity classifications. European polyurethane producers are accelerating adoption of bismuth and zirconium-based alternatives, though activity penalties require higher catalyst loadings and modified reactor designs.
Integrated service contracts are bundling catalyst supply with reactor monitoring and performance guarantees, displacing traditional procurement of discrete catalyst loads with per-ton-product pricing models. This restructuring concentrates purchasing power among multinational refiners with sufficient scale to negotiate long-term partnerships. The shift is most visible in the US Gulf Coast, where ExxonMobil and Chevron have consolidated catalyst supply relationships across multiple refinery sites.
Global Catalyst Market Segmentation
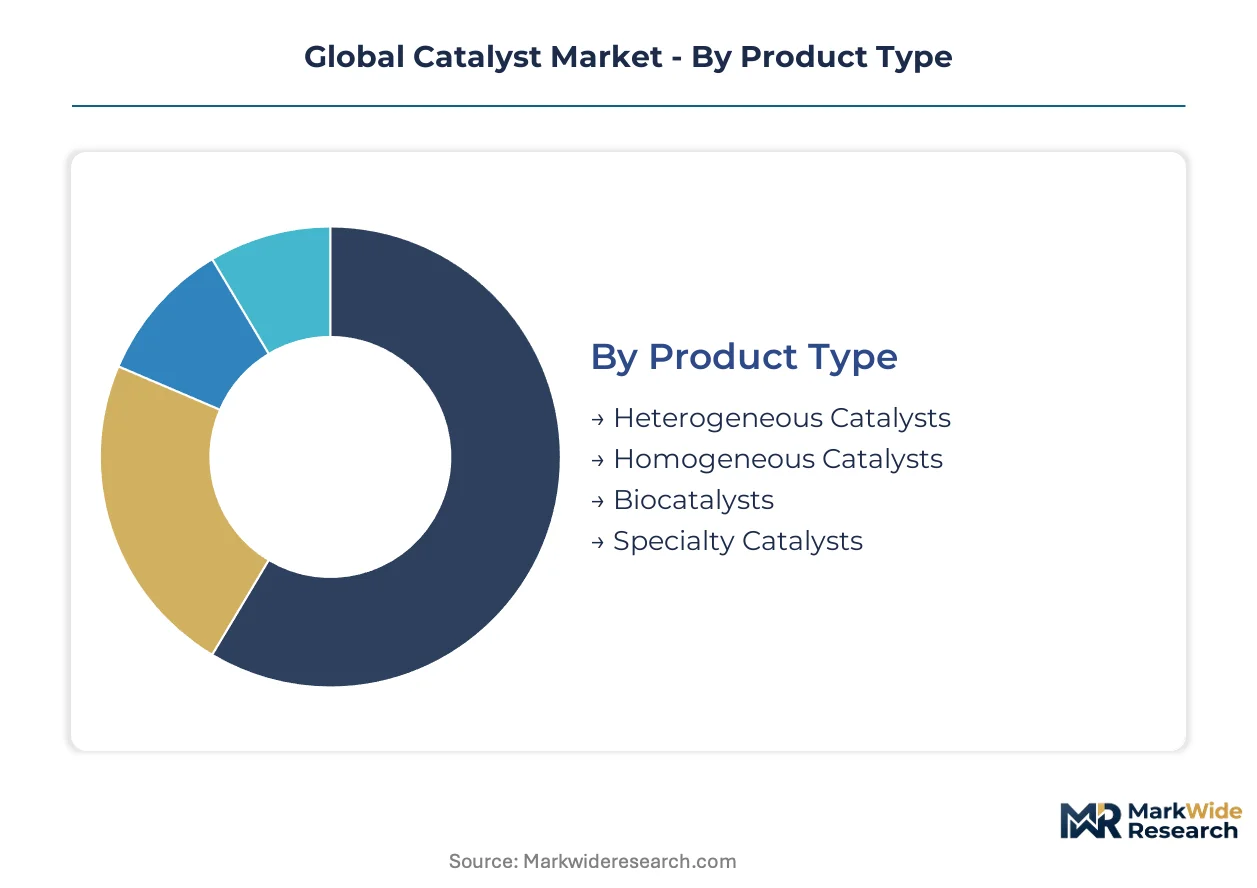
Catalyst procurement decisions pivot on reactor compatibility, feedstock chemistry, and regulatory compliance requirements. Buyers evaluate thermal stability, metal loading efficiency, and regeneration cycles against total cost of ownership metrics. The segmentation below maps how these technical and commercial factors distribute demand across product architectures and operational configurations.
Product Type:
Refinery operators and chemical manufacturers select catalyst formats based on separability economics, thermal tolerance thresholds, and intellectual property access to proprietary formulations.
- Heterogeneous Catalysts:Solid-phase systems with supported metal nanoparticles on alumina, silica, or zeolite carriers enable facile separation from product streams. Demand concentrates in India's expanding FCC units and US Gulf Coast resid upgraders, where thermal stability under metal-contaminated heavy crude processing determines supplier selection.
- Biocatalysts:Immobilized enzymes and whole-cell systems operate under mild temperature and pressure conditions with exceptional stereoselectivity. Pharmaceutical contract manufacturers in Switzerland and Ireland are displacing solvent-intensive chemical routes, driven by EMA sustainability guidelines and FDA green chemistry incentives.
- Homogeneous Catalysts:Soluble metal complexes in liquid phase offer uniform active site accessibility for precision polymerization and fine chemical synthesis.
- Specialty Catalysts:Custom-formulated systems address proprietary process chemistry with dedicated technical service support and performance guarantees.
Volume sits with heterogeneous systems; growth tilts toward biocatalysts.
Application:
End-use chemistry dictates catalyst specification, with conversion selectivity and coke formation resistance varying sharply across feedstock molecular structures.
- Refining:Hydroprocessing and fluid catalytic cracking catalysts handle sulfur removal, resid conversion, and octane enhancement across crude distillation complexes. China's coastal petrochemical clusters and India's Reliance Jamnagar refinery drive formulation demand for heavier, higher-metal crude slates.
- Environmental:Automotive exhaust aftertreatment and stationary source emission control deploy platinum group metal washcoats on ceramic honeycomb substrates. EPA Tier 4 and Euro VII standards mandate higher nitrogen oxide conversion efficiency, elevating palladium and rhodium loadings in diesel oxidation and selective catalytic reduction systems.
- Petrochemicals:Zeolite-based systems convert methanol to light olefins and catalytically crack naphtha for polymer-grade ethylene and propylene production.
- Chemical Synthesis:Hydrogenation, oxidation, and polymerization catalysts enable ammonia, methanol, and specialty chemical manufacturing.
Refining commands installed base; environmental applications expand most quickly.
End User:
Customer scale and integration depth determine procurement modality, with integrated majors negotiating multi-site supply contracts versus spot purchasing by merchant operators.
- Oil & Gas:Supermajors and national oil companies specify catalyst performance against crude assay variability and coke tolerance benchmarks. Saudi Aramco and ExxonMobil anchor hydroprocessing demand through long-term technical service agreements spanning multiple refinery sites.
- Automotive:OEMs and tier-one aftertreatment suppliers validate emission catalyst durability across 150,000-mile regulatory test cycles. Johnson Matthey and BASF supply membrane electrode assemblies for proton exchange membrane electrolyzers as hydrogen mobility infrastructure scales.
- Chemicals:Commodity and specialty chemical producers optimize catalyst productivity against feedstock flexibility and byproduct minimization targets.
- Pharmaceuticals:API manufacturers adopt enzymatic routes to satisfy EMA and FDA process mass intensity reduction mandates.
Oil and gas dominates procurement volume; pharmaceutical applications gain share fastest.
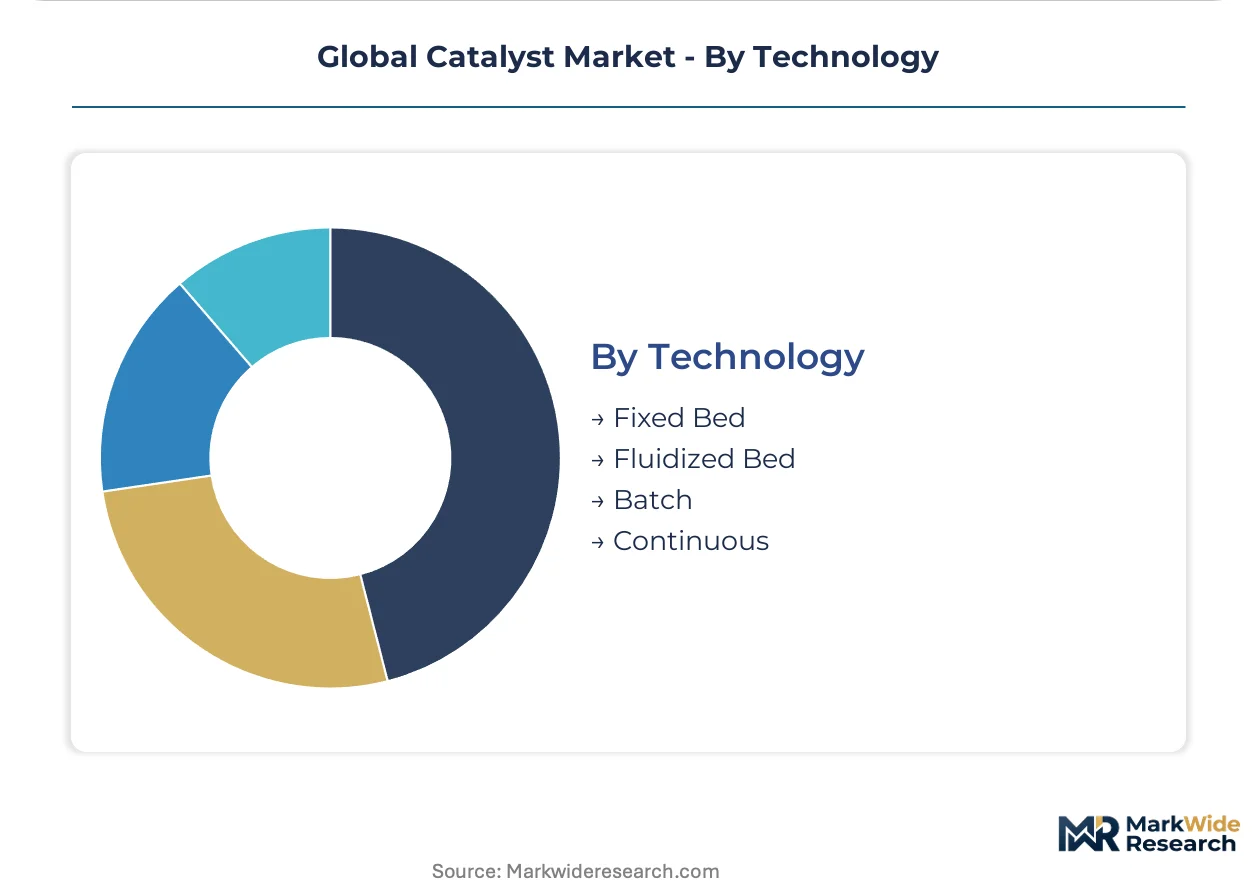
Technology:
Reactor configuration selection balances capital intensity, heat transfer efficiency, and catalyst replacement logistics against process throughput requirements.
- Fixed Bed:Stationary catalyst pellets in tubular or adiabatic reactors enable continuous operation with predictable pressure drop profiles. Hydrotreating units in the US Gulf Coast and hydrocracking trains in China's Sinopec complexes favor this architecture for high-pressure hydrogen service.
- Fluidized Bed:Suspended catalyst particles in upward-flowing gas or liquid streams deliver superior heat transfer and continuous regeneration capability. FCC units in India's expanding refineries and China's coal-to-olefins plants exploit this configuration for exothermic cracking reactions and rapid catalyst replacement.
- Batch:Discrete catalyst charges in stirred tank or loop reactors accommodate low-volume, high-value pharmaceutical and fine chemical synthesis.
- Continuous:Steady-state operation with catalyst recirculation or fixed-bed swing reactors maximizes capacity utilization in large-scale commodity chemical production.
Fixed bed holds installed capacity leadership; fluidized bed captures incremental investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth processing concentration in China's Inner Mongolia and Jiangxi provinces anchors global automotive catalyst supply chains. Platinum group metal refining in South Africa's Bushveld Complex and Russia's Norilsk region shapes raw material flows. Coastal petrochemical clusters in East Asia and the US Gulf Coast concentrate formulation demand.
China
Coal-to-olefins plants in Ningxia and Shaanxi provinces drive zeolite catalyst consumption for methanol conversion. The Ministry of Ecology and Environment enforces stricter volatile organic compound limits that elevate demand for low-temperature oxidation systems. The Yangtze River Delta petrochemical corridor, spanning Shanghai and Jiangsu, hosts integrated refinery-petrochemical complexes expanding fluid catalytic cracking capacity.
United States
Hydrogen electrolyzer manufacturing in Texas and California accelerates demand for iridium and platinum-based membrane electrode assemblies. EPA Tier 4 emission standards mandate higher nitrogen oxide conversion efficiency in diesel aftertreatment systems. The US Gulf Coast refining corridor, centered on Houston and Port Arthur, consolidates catalyst supply relationships across multiple ExxonMobil and Chevron sites.
Germany
Pharmaceutical contract manufacturers in Switzerland and Ireland displace solvent-heavy chemical routes with enzymatic synthesis. REACH authorization procedures force substitution of cobalt and nickel catalysts in polyester polyol manufacturing. The Ludwigshafen chemical complex anchors rare-earth catalyst supply chains for automotive exhaust applications through BASF's integrated site operations.
India
Reliance Industries and Indian Oil Corporation are adding resid upgrading and hydroprocessing capacity for high-sulfur Middle Eastern crudes. The Petroleum and Natural Gas Regulatory Board mandates cleaner fuel specifications that tighten catalyst performance requirements. The Jamnagar refinery complex in Gujarat and expanding Kochi facilities drive formulation demand for metal-tolerant zeolite structures.
Saudi Arabia
Saudi Aramco anchors hydroprocessing demand through long-term technical service agreements spanning multiple refinery sites. The Saudi Food and Drug Authority and national environmental regulators enforce emission standards that elevate catalyst specifications. The Eastern Province industrial cluster, centered on Jubail and Yanbu, concentrates resid upgrading capacity for heavier crude slates.
Global Catalyst Market Vendor Landscape
Global majors compete with regional champions across formulation expertise and raw material access. The market structures around integrated chemical conglomerates with captive rare-earth processing, specialized catalyst formulators with proprietary zeolite synthesis, and regional service providers with refinery technical partnerships. Three archetypes dominate: diversified materials giants with vertical control over precious metal supply, technology licensors with patented reactor-catalyst packages, and niche specialists in single-atom or biocatalytic systems. Competitive moves concentrate on long-term integrated service contracts bundling catalyst supply with performance guarantees, and geographic expansion through licensing partnerships in India's refinery expansion corridor.
Within the diversified materials tier, BASF SE and Johnson Matthey Plc occupy positions exemplifying integrated supply chain control. BASF's Ludwigshafen operations represent captive rare-earth catalyst production for automotive applications. Johnson Matthey anchors hydrogen economy positioning through membrane electrode assembly technology. Clariant AG sits within the specialty formulation archetype, reflecting Swiss-based precision chemical manufacturing. These three entities collectively illustrate how geographic concentration of raw material processing and end-use demand shapes competitive positioning without requiring specific product or financial disclosures.
| Leading Market Players |
|---|
| BASF SE |
| Johnson Matthey Plc |
| Clariant AG |
| Honeywell UOP |
| Evonik Industries AG |
| Albemarle Corporation |
| W. R. Grace & Co. |
| Axens |
| Haldor Topsoe A/S |
| Others |
Supply Flow & Price Mechanics
Integrated refinery operators in the US Gulf Coast and China's coastal petrochemical clusters negotiate multi-year performance contracts that bundle catalyst supply with technical service guarantees, displacing spot purchasing and compressing margins for suppliers locked into fixed-price formulations.
Pricing Analysis
Warranty and regeneration service bundling separates premium catalyst suppliers from commodity competitors, with integrated contracts covering spent catalyst recovery and metal reclamation. Three-tier pricing structure across premium, standard, and economy levels reflects platinum group metal loading density and zeolite crystallinity grades. Pricing pressure stems from rare-earth oxide cost volatility and automotive OEMs demanding longer durability guarantees. Merchant refiners in India exhibit highest price sensitivity due to working capital constraints, while Saudi Aramco's technical service agreements anchor premium tier stability.
Supply Chain Analysis
Ocean freight rates from South Africa's Bushveld Complex and Russia's Norilsk region to European formulation plants constitute a significant landed cost component for platinum group metals. Catalyst manufacturing draws from Chinese rare-earth processing in Inner Mongolia, South African platinum refining, and German chemical synthesis expertise. Single-source vulnerability concentrates in cerium and lanthanum oxide supply from China's Jiangxi province. Distribution runs through regional blending facilities proximate to the US Gulf Coast, Rotterdam Antwerp corridor, and Singapore hub.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH authorization procedures and EPA Tier 4 certification requirements erect substantial barrier-to-entry moats favoring incumbents with established regulatory dossiers and validated formulation libraries.
For Market Incumbents: Anchor hydrogen economy positioning through membrane electrode assembly technology partnerships as electrolyzer manufacturing scales in Texas and California. Deepen captive rare-earth oxide supply relationships to offset China's processing concentration risk. Defend against single-atom catalyst specialists by accelerating pharmaceutical intermediate application development. For New Entrants and Emerging Players: Digital materials informatics platforms offer lower-cost entry routes for catalyst discovery, collapsing traditional iterative screening timelines. Target India's refinery expansion corridor where Reliance Industries and Indian Oil Corporation seek metal-tolerant zeolite alternatives for high-sulfur crude processing. Pursue enzymatic biocatalyst partnerships with Swiss and Irish pharmaceutical contract manufacturers facing EMA sustainability mandates. For Investors and Strategic Acquirers: The window for entry favors specialty formulators with proprietary single-atom or biocatalytic intellectual property positions. Long-term viability centers on hydrogen production and pharmaceutical synthesis applications as refining demand plateaus. Monitor EPA emission standard refresh timelines and EU carbon-border adjustment implementation as inflection indicators for portfolio reallocation between gray, blue, and green hydrogen catalyst exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Oxide Processing | BASF's Ludwigshafen operations demonstrate captive supply security against China's export restrictions. |
| Long-term Technical Service Agreement | Saudi Aramco's multi-site contracts span Jubail and Yanbu resid upgrading capacity. |
| Green Manufacturing Certification | EU Green Deal carbon-border adjustment rewards renewable energy-integrated catalyst synthesis routes. |
| Joint Venture in Hydrogen Electrolyzer Components | Johnson Matthey anchors demand through differentiated membrane electrode assembly technology. |
| Capacity Expansion in Coal-to-Olefins Catalysts | Ningxia and Shaanxi province methanol-to-olefins plants drive zeolite consumption growth. |
Methodological Framework
Independent corroboration across refinery procurement directors, pharmaceutical process development leads, and automotive aftertreatment engineers underwrites the qualitative findings. Primary interviews with hydroprocessing unit managers, FCC operations specialists, and catalyst technical service representatives combined with secondary validation from SEC filings, customs trade data, and EPA emission certification databases. Bottom-up capacity and consumption estimates triangulate against top-down industry association aggregates from ACC and Cefic.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions span catalyst type, application chemistry, reactor technology, and regional production hub concentration. CAGRs derive from fitted trend extrapolation moderated by capacity build-out announcements and regulatory implementation schedules. Industry-specific inputs include crude slate heaviness indices, platinum group metal price volatility bands, and hydrogen electrolyzer deployment pipelines.
The model holds under stable rare-earth export policy and sustained emission regulation enforcement; deviation in geopolitical trade restrictions or accelerated electrification adoption would shift demand trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Environmental Catalysts Market
Catalysts
Solid Acid Catalysts Market
Catalysts
CO2 Reforming Catalysts Market
Catalysts
Residue Hydrodesulphurization Catalyst Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Sulfur Guard Catalyst Market
Catalysts
Photocatalyst Market
Catalysts
Catalyst for Hydrogen Production from Water Electrolysis Market
Catalysts
Global Polypropylene Catalyst Market
Catalysts
Asia-Pacific Refining Catalysts Market
Catalysts
Global Light Powered Catalyst Market
Catalysts
Platinum-Based Catalysts Market
Catalysts
Emission Control Catalyst for Marine Market
Catalysts
Europe PGM Catalyst Market
Catalysts
Refining Catalysts Market
Catalysts
Platinum and Palladium Carbon Catalyst Market