
 Bio-Based Polyvinyl Chloride Market | 2026-2036
Bio-Based Polyvinyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Polyvinyl Chloride Market Outlook
The EU Green Deal's plastics transition targets is shifting procurement criteria across European construction and automotive supply chains. INOVYN leverages its integrated chlor-alkali footprint to secure ethylene feedstock flexibility for bio-based vinyl chloride monomer production. BASF SE anchors its position through polymerization catalyst R&D aimed at maintaining processability with renewable-derived monomer inputs. Neste competes by supplying renewable naphtha streams that crack into bio-ethylene for PVC synthesis.
Bio-based polyvinyl chloride substitutes fossil-derived ethylene with renewable feedstock sources such as bio-naphtha or bio-ethanol, yielding a polymer with identical chlorine content but reduced cradle-to-gate carbon intensity. Flexible PVC commands the largest application share due to its dominance in wire insulation, flooring, and medical tubing where plasticizer compatibility remains critical. Rigid PVC sustains structural demand in construction piping and window profiles where dimensional stability and fire resistance specifications are non-negotiable. The automotive segment represents the fastest-growing application as interior trim and underbody coating specifications tighten around lifecycle emissions accounting.
REACH compliance in Europe mandates registration and hazard communication for bio-based monomer variants entering existing polymer supply chains. The EPA's renewable fuel standard pathways and state-level low-carbon fuel programs in California create indirect incentives for bio-ethylene producers serving PVC manufacturers. FDA biocompatibility requirements govern medical-grade flexible PVC formulations regardless of feedstock origin. Stakeholders must monitor how certification schemes for mass-balance accounting evolve to prevent greenwashing liabilities while securing premium offtake agreements.
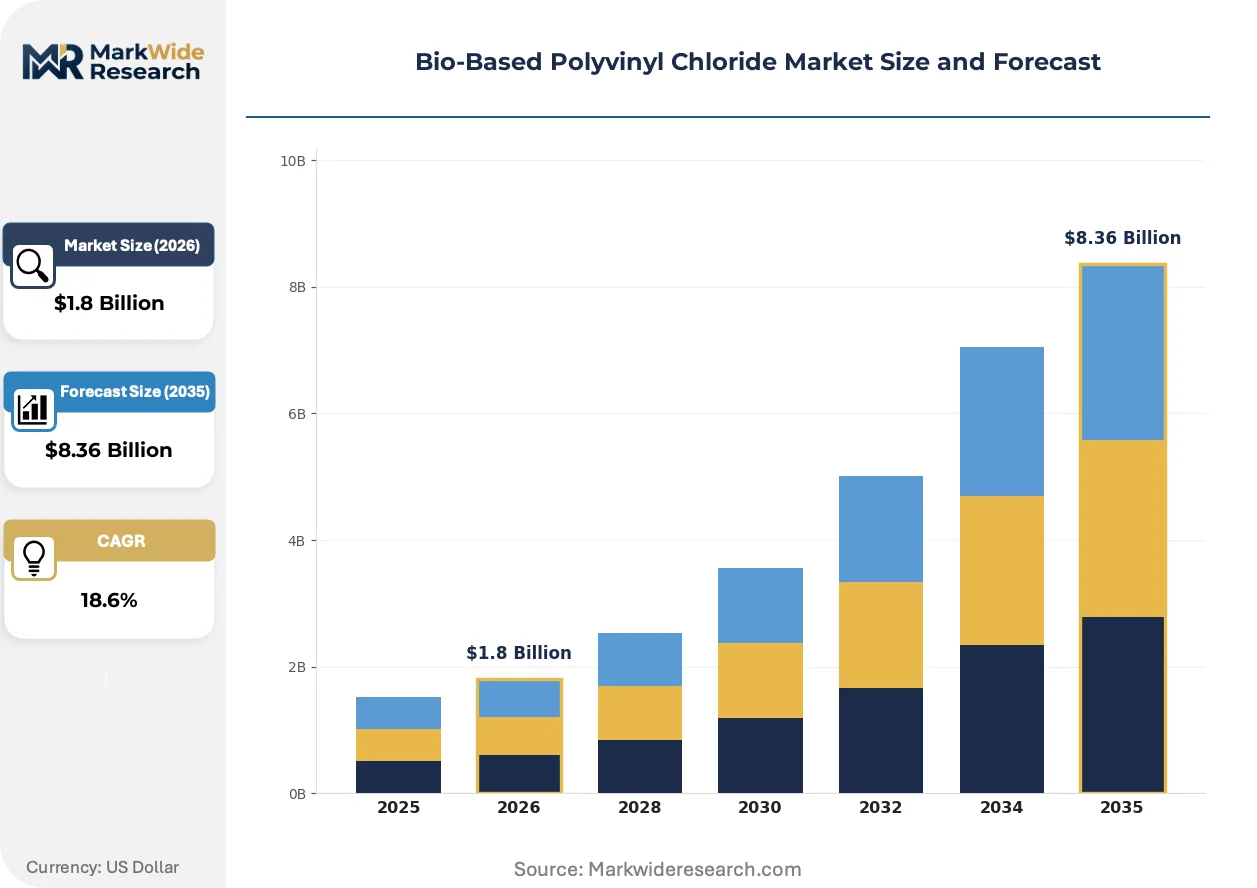
Market Dynamics
The EU Green Deal's binding plastics transition targets are forcing feedstock substitution decisions across European vinyl chloride monomer supply chains, compressing the timeline for renewable ethylene integration.
Growth Catalysts
- EU Green Deal mandates:The EU's plastics transition framework imposes cradle-to-gate emissions caps that favor bio-based vinyl chloride monomer in construction and automotive procurement.
- Automotive scope-three accounting:OEMs in Germany and the United States are embedding lifecycle emissions criteria into interior trim and underbody coating specifications.
- Mass-balance certification schemes:ISCC PLUS and RSB chain-of-custody standards enable premium pricing for bio-attributed PVC without segregated production lines.
Market Restraints
- Bio-ethylene feedstock scarcity:Renewable naphtha and bio-ethanol supply concentrates among a limited set of European and North American refiners, creating input bottlenecks.
- Chlorine process lock-in:Existing chlor-alkali infrastructure ties vinyl chloride production to specific coastal industrial clusters with legacy permits.
- Performance equivalence verification:REACH registration requirements for bio-based monomer variants impose testing costs that fossil-derived equivalents avoid.
Strategic Opportunities
- Medical-grade flexible PVC:FDA biocompatibility pathways for bio-based formulations open premium tubing and blood bag markets with stringent purity requirements.
- California LCFS integration:The state's Low Carbon Fuel Standard creates indirect credit value for bio-ethylene producers serving West Coast PVC manufacturers.
- Building certification alignment:LEED and BREEAM point systems for embodied carbon are pulling bio-based PVC into green building specifications across German construction.
Industry Challenges
- Polymerization catalyst adaptation:Maintaining processability with renewable-derived monomers demands R&D coordination between catalyst suppliers and resin producers.
- Mass-balance audit complexity:Preventing greenwashing liability requires real-time tracking systems that many compounders lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Polyvinyl Chloride Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible PVC, Rigid PVC, Foamed PVC, Plasticized PVC Application: Construction, Automotive, Electrical, Packaging End User: Manufacturers, Retailers, Wholesalers, Construction Firms Distribution Channel: Direct Sales, Online Sales, Distributors, Retail Stores |
| Companies Covered | Sylvin Technologies, Inc., Neste, INOVYN, LG Chem, Vynova Group, Bio-Tec Environmental, LLC, INEOS, BASF SE, ENSO Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Polyvinyl Chloride Market Strategic Shifts
Feedstock molecular verification technologies and regulatory mass-balance frameworks are converging to reshape how bio-attribution claims are validated and monetized across PVC value chains.
Advanced isotopic fingerprinting for bio-ethylene verification is expanding into contract enforcement mechanisms. German automotive suppliers now require third-party molecular certification for interior trim materials. This technology is expanding into dispute resolution between compounders and their OEM customers, replacing paper-based chain-of-custody documentation with analytical proof.
REACH registration deadlines for bio-based monomer variants are compressing formulation approval timelines. ECHA hazard communication requirements now cover renewable-derived vinyl chloride monomer entering existing polymer supply chains. European medical device manufacturers are responding by pre-qualifying dual-feedstock resin suppliers to avoid registration gaps.
Long-term offtake contracting for bio-naphtha streams is displacing spot market purchasing among PVC producers. Compounders in the United States are locking in five-year supply agreements with renewable feedstock refiners to secure volume certainty. This pattern is most visible in automotive interior applications where OEMs demand supply chain transparency for scope-three emissions reporting.
Bio-Based Polyvinyl Chloride Market Segmentation
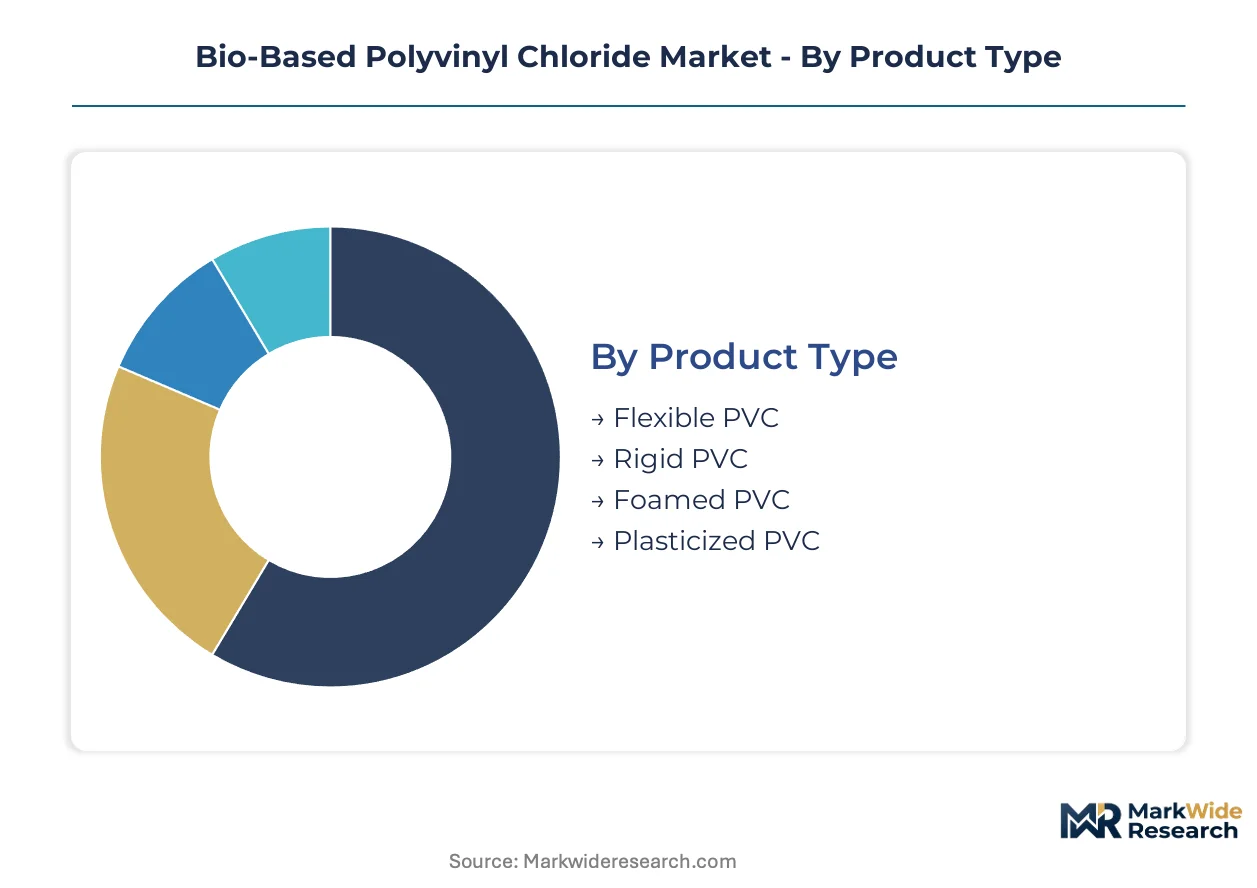
Bio-based PVC segmentation reveals how feedstock substitution penetrates differently across material formulations and procurement channels. Each category carries distinct certification requirements and margin structures that shape supplier prioritization.
Product Type:
Standalone formulations dominate high-volume construction applications, while embedded specialty grades command premium positioning in regulated end-uses.
- Flexible PVC:Plasticizer-loaded formulations with 30-50% additive content by weight. Wire insulation demand concentrates in German automotive harness production driven by OEM scope-three accounting mandates. Medical tubing applications in the United States require FDA biocompatibility validation regardless of bio-feedstock origin.
- Rigid PVC:Unplasticized polymer with high dimensional stability and fire resistance. Window profile and piping specifications across German construction firms prioritize embodied carbon metrics under EU Green Deal procurement guidelines. REACH registration for bio-based monomer variants adds compliance overhead that fossil-derived equivalents bypass.
- Foamed PVC:Cellular structure with density reduction for signage and display applications. Building interior projects in California specify mass-balance certified foamed boards for LEED point accumulation.
- Plasticized PVC:Mid-range flexibility grades for flooring and coated fabrics. Flooring manufacturers in the United States lock long-term offtake contracts with renewable naphtha suppliers to secure volume certainty.
Flexible PVC leads volumes today; foamed PVC is gaining share fastest in display and exhibition applications.
Application:
Cost-tier stratification separates commodity construction procurement from premium automotive and medical specifications.
- Construction:Piping, siding, and window profiles constitute the foundational demand base. German construction firms scale bio-based PVC procurement to meet BREEAM and LEED certification thresholds.
- Automotive:Interior trim, underbody coatings, and wire harness insulation. OEMs in Germany and the United States embed lifecycle emissions criteria into supplier scorecards, accelerating bio-attributed resin qualification.
- Electrical:Cable jacketing and conduit systems. ISCC PLUS mass-balance certification enables premium pricing without segregated production lines.
- Packaging:Blister packs and thermoformed containers. Pharmaceutical packaging in Europe faces ECHA hazard communication requirements for renewable-derived monomer variants.
Construction anchors volume; automotive climbs the fastest on scope-three emissions accounting pressure.
End User:
Customer-type concentration determines whether procurement flows through specification-driven direct channels or price-sensitive intermediated routes.
- Manufacturers:Compounders and processors with formulation control. Automotive suppliers in Germany require third-party molecular certification for interior trim materials, replacing paper-based chain-of-custody documentation.
- Retailers:Big-box and specialty building material distributors. California retailers stock mass-balance certified rigid PVC to capture green building renovation demand.
- Wholesalers:Regional distributors serving contractor networks. Wholesalers in the United States face audit complexity for mass-balance tracking systems that many lack.
- Construction Firms:Direct procurement by large developers and general contractors. German construction firms pre-qualify dual-feedstock resin suppliers to avoid REACH registration gaps.
Manufacturers lead procurement value; construction firms are expanding fastest through direct sourcing mandates.
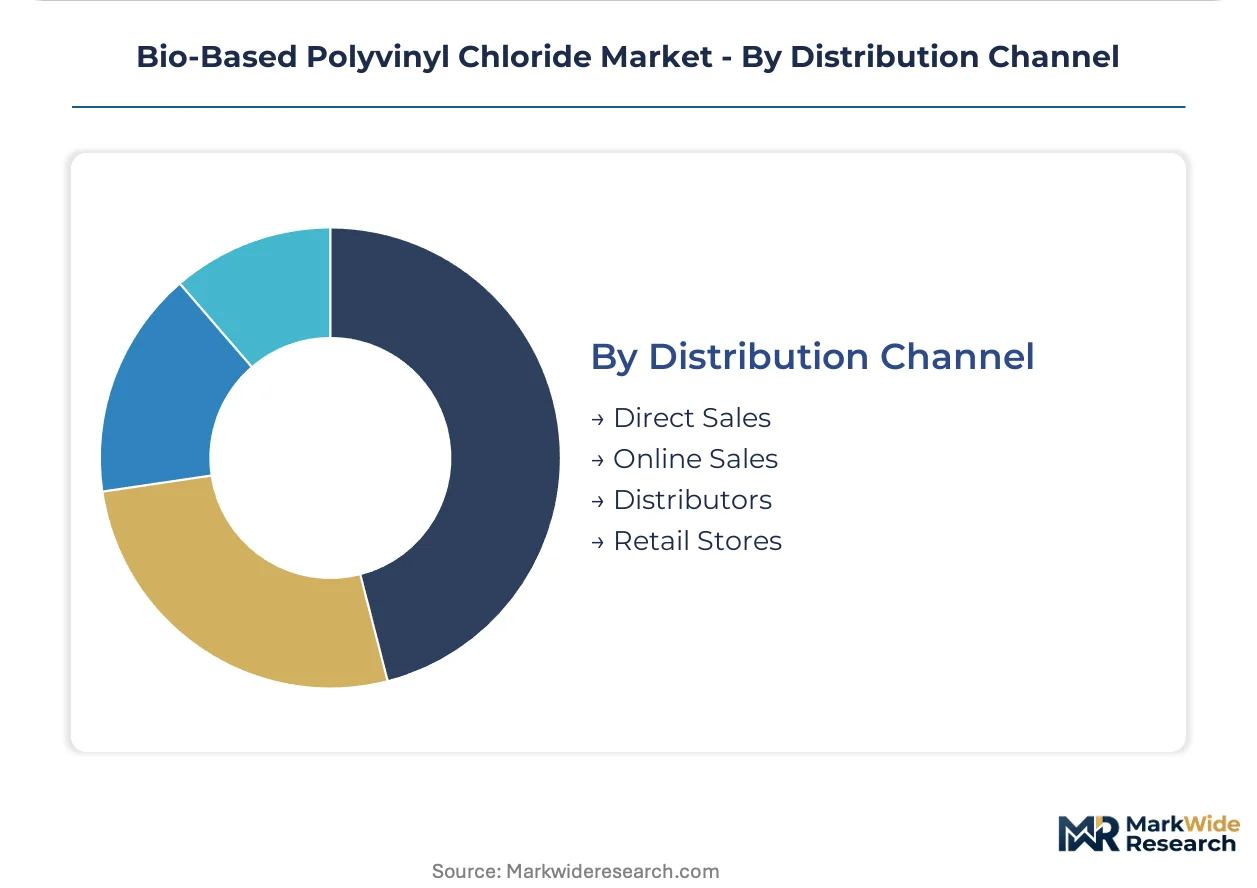
Distribution Channel:
Supply concentration varies from captive direct relationships to fragmented retail access, shaping price realization and certification transparency.
- Direct Sales:Long-term contracts between resin producers and compounders. Five-year supply agreements with renewable feedstock refiners secure volume certainty for automotive interior applications.
- Online Sales:E-commerce platforms for standard grades and small-lot specialty formulations. Online channels in the United States serve independent fabricators seeking ISCC PLUS certified material without minimum order constraints.
- Distributors:Regional and national intermediaries with technical support capabilities. Distributors in Germany coordinate REACH registration documentation for bio-based monomer variants entering existing polymer supply chains.
- Retail Stores:Physical building material outlets for contractor walk-up demand. Retail availability of bio-attributed PVC remains limited to premium-tier positioning in urban California markets.
Direct sales dominate value capture; online channels show steepest expansion trajectory among independent processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale vinyl chloride production in the early 20th century, establishing the chemical engineering foundations that now anchor European bio-based PVC development. This historical concentration of chlor-alkali expertise shapes where feedstock substitution investments flow today.
Germany
Automotive wire harness and interior trim specifications from BMW and Volkswagen compress supplier qualification timelines for bio-attributed resins. The EU Green Deal's binding plastics transition targets force construction procurement toward cradle-to-gate emissions accounting. The Cologne-Leverkusen chemical corridor hosts integrated chlor-alkali facilities now trialing renewable naphtha feeds.
United States
California's Low Carbon Fuel Standard generates credit value for bio-ethylene producers serving West Coast PVC compounders. EPA renewable fuel standard pathways create indirect incentives for bio-based monomer production. The Gulf Coast petrochemical cluster near Houston experiments with mass-balance certification for export-oriented rigid PVC piping.
Netherlands
Rotterdam's biofuel refining hub supplies renewable naphtha streams cracking into bio-ethylene for PVC synthesis. ISCC PLUS chain-of-custody standards enable premium pricing without segregated production lines. The Port of Rotterdam industrial zone anchors long-term offtake contracting between feedstock refiners and resin producers.
China
Dual carbon goals under the 14th Five-Year Plan accelerate pilot projects for bio-based vinyl chloride monomer in coastal chemical parks. The national petroleum and chemical planning institute evaluates mass-balance frameworks for import substitution. The Yangtze River Delta near Shanghai concentrates rigid PVC extrusion capacity now sourcing trial bio-ethylene batches.
Belgium
Antwerp's chlor-alkali infrastructure ties vinyl chloride production to legacy coastal permits with high environmental compliance costs. REACH registration deadlines for bio-based monomer variants compress formulation approval timelines for medical-grade flexible PVC. The Port of Antwerp-Bruges chemical cluster coordinates ECHA hazard communication documentation for renewable-derived resin imports.
Bio-Based Polyvinyl Chloride Market Competitive Environment
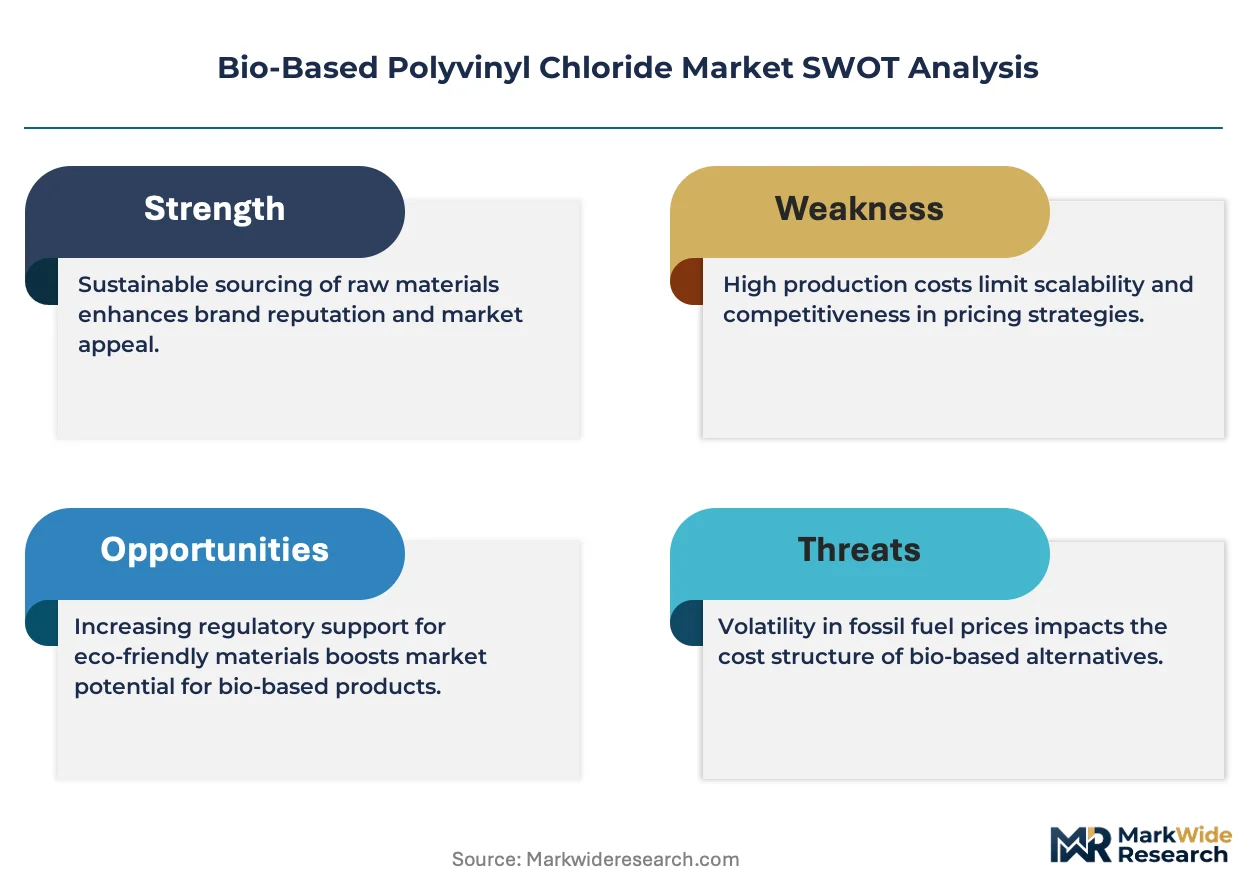
Capital-heavy chlor-alkali producers compete with asset-light compounders and specialty formulators across differentiated value chain positions. The market structure consolidates around integrated petrochemical groups with captive ethylene supply, while independent compounders fragment across application-specific niches. Three archetypes dominate: upstream feedstock suppliers controlling renewable naphtha streams, integrated resin producers with polymerization catalyst R&D capabilities, and downstream compounders with FDA biocompatibility certifications. Capacity expansion and strategic partnerships for mass-balance certification represent the dominant competitive moves.
Among European integrated producers, INOVYN and Vynova Group exemplify the upstream-resin archetype with coastal chlor-alkali footprints. BASF SE anchors the catalyst-specialist position through polymerization R&D coordination. Neste represents the pure-play feedstock supplier model, supplying renewable naphtha streams that crack into bio-ethylene for PVC synthesis.
| Leading Market Players |
|---|
| Sylvin Technologies, Inc. |
| Neste |
| INOVYN |
| LG Chem |
| Vynova Group |
| Bio-Tec Environmental, LLC |
| INEOS |
| BASF SE |
| ENSO Plastics |
| Others |
Value Chain & Pricing Dynamics
ISCC PLUS mass-balance certification creates a three-tier pricing structure across premium, standard, and economy levels that separates German automotive suppliers from California construction distributors from spot-market compounders. This stratification manifests in supply chain configurations where certified resin flows through direct long-term contracts while uncertified material channels through distributors with fragmented audit capabilities.
Pricing Analysis
Contract-based long-term offtake dominates bio-based PVC procurement, with price differentiation driven by certification grade and volume scale. Premium pricing attaches to ISCC PLUS and RSB chain-of-custody documentation that German OEMs require for scope-three emissions reporting. Cost compression in standard-grade rigid PVC intensifies because REACH registration overhead for bio-based monomer variants adds fixed compliance costs that fossil-derived equivalents bypass. Construction firms in Germany show least price sensitivity due to BREEAM point accumulation requirements, while United States wholesalers face greatest margin pressure from audit system investments they lack.
Supply Chain Analysis
Dual-sourcing requirements from BMW and Volkswagen compounders mandate pre-qualified backup suppliers for bio-attributed resins, forcing redundant feedstock agreements. Geographic supply concentration centers on Germany, the Netherlands, and the United States, with Rotterdam's renewable naphtha refiners and the Cologne-Leverkusen chemical corridor anchoring upstream capacity. Raw material dependencies rest on bio-naphtha streams, bio-ethanol feedstocks, and chlor-alkali chlorine supply. Single-source vulnerability runs through limited renewable naphtha refiners concentrated in European coastal hubs. Distribution runs through direct sales channels for automotive interior applications and regional distributors serving German construction networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's binding plastics transition targets compound regulatory demand into procurement mandates that reshape competitive positioning across construction and automotive supply chains.
For Market Incumbents: Anchor market position through captive bio-naphtha supply agreements that lock out emerging compounders facing feedstock scarcity. Invest in polymerization catalyst R&D coordination with BASF SE to maintain processability equivalence as renewable-derived monomer ratios climb. Defend against specialty formulators with FDA biocompatibility certifications by accelerating medical-grade flexible PVC qualification timelines. For New Entrants and Emerging Players: Automotive Tier 2 suppliers in the United States represent the most penetrable channel partner type for bio-attributed resin qualification without legacy chlor-alkali infrastructure burdens. Target California LCFS credit aggregation as a go-to-market angle, creating indirect value capture for West Coast compounders serving green building renovation demand. White-space exists in online sales channels for independent fabricators seeking ISCC PLUS certified material without minimum order constraints. For Investors and Strategic Acquirers: Consolidation pressure builds where mass-balance audit complexity exceeds compounder technical capabilities, creating acquisition targets among regional distributors with fragmented tracking systems. Long-term viability over the next decade hinges on feedstock security rather than polymerization scale, favoring targets with locked renewable naphtha offtake. Watch for ECHA hazard communication deadline compression as the signal indicating formulation approval bottlenecks that reshape supplier qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstock | Captive bio-naphtha supply secures volume certainty against Rotterdam refiner concentration. |
| Mass-Balance Certification Investment | ISCC PLUS documentation enables German automotive premium pricing without segregated production lines. |
| Medical-Grade Formulation Qualification | FDA biocompatibility pathways open premium tubing markets with stringent purity requirements. |
| Long-Term Supply Agreement Structuring | Five-year contracts with renewable refiners match OEM scope-three reporting timelines. |
| Polymerization Catalyst R&D Partnership | BASF SE coordination maintains processability as renewable monomer ratios increase. |
Study Parameters
Direct dialogue with chlor-alkali plant managers, automotive procurement leads at German OEMs, distribution channel partners, and technical R&D directors at catalyst suppliers grounded qualitative assessment. Secondary validation drew from ECHA REACH registration databases, EU Green Deal implementation documents, SEC 10-K filings of listed chemical producers, and customs trade data tracking bio-ethylene imports. Bottom-up resin production estimates and top-down construction and automotive demand projections were triangulated to cross-verify volume assumptions.
Bottom-up modeling of vinyl chloride monomer capacity by feedstock type was reconciled against top-down end-use demand segmentation across flexible, rigid, and foamed PVC grades. The analytical framework spans product type, application, end user, and distribution channel dimensions across the analysis window. CAGRs were derived from regression analysis of historical substitution rates and policy implementation timelines. Key inputs included EU Green Deal plastics transition target enforcement schedules and California LCFS credit value trajectories.
Revisions become necessary when bio-ethylene feedstock scarcity intensifies beyond current refiner expansion plans or when ECHA accelerates hazard communication deadlines for renewable-derived monomers. Deviation in German automotive OEM scope-three accounting stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyimides Market
Polymers & Resins
EVA Foam Market
Polymers & Resins
Linear Low Density Polyethylene Lldpe Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
Molding and Trim Materials Market
Polymers & Resins
Middle East Polymer Market
Polymers & Resins
PE Resins Market
Polymers & Resins
UV Stabilized Thermoplastic Elastomer for Automotive Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market
Polymers & Resins
Sugar Polymers Market
Polymers & Resins
United States Polymer Emulsion Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Antiviral Polymers for Packaging Market
Polymers & Resins
United Kingdom Engineering Plastics Market
Polymers & Resins
Sodium Polyacrylate Market
Polymers & Resins
Brazil Engineering Plastics Market