
 Indonesia Plastic Food Tray Market | 2026-2036
Indonesia Plastic Food Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Plastic Food Tray Market Foresight
Multi-source procurement among Indonesian food manufacturers is broadening as buyers diversify away from single-mold suppliers. PT Solusi Prima Packaging leverages domestic resin partnerships to sustain cost-competitive polypropylene tray output. Amcor PLC anchors premium PET tray supply through its regional Southeast Asian manufacturing footprint. PT Dynapak Asia differentiates via integrated thermoforming and printing capabilities serving quick-service chains.
Indonesia plastic food trays are thermoformed or injection-molded containers, typically manufactured from polypropylene, polystyrene, or PET resin in thicknesses ranging from 0.3 mm to 1.2 mm, designed to contain, display, and protect prepared or raw food items during distribution and retail sale. The primary commercial purpose centers on extending shelf visibility and hygienic handling across food service, retail, and catering channels. Single compartment trays dominate volume due to standardized quick-service packaging requirements, while biodegradable variants represent the fastest-expanding material segment as BPI and OK Compost certifications gain traction among export-oriented processors. Polypropylene occupies the largest material share given its microwave stability and broad recycling infrastructure acceptance across Indonesian cities.
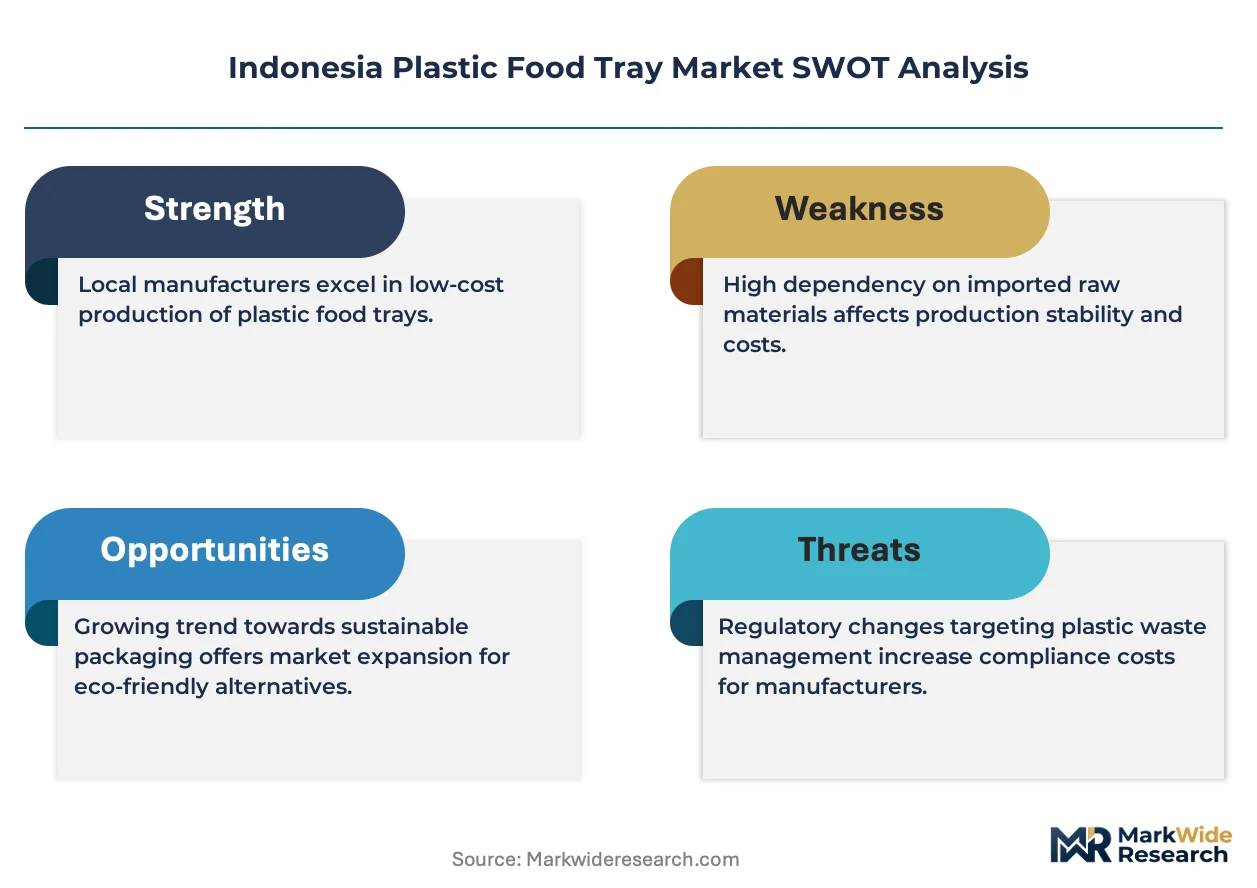
BIS-equivalent Indonesian National Standards and the Ministry of Environment and Forestry's waste reduction roadmaps shape food-contact compliance and recycled content thresholds for domestic tray producers. The National Plastic Action Partnership coordinates with provincial governors to implement extended producer responsibility frameworks across Java, Bali, and Sulawesi. Stakeholders must monitor evolving biodegradable certification requirements and regional waste bank integration mandates that will determine which material platforms retain market access.
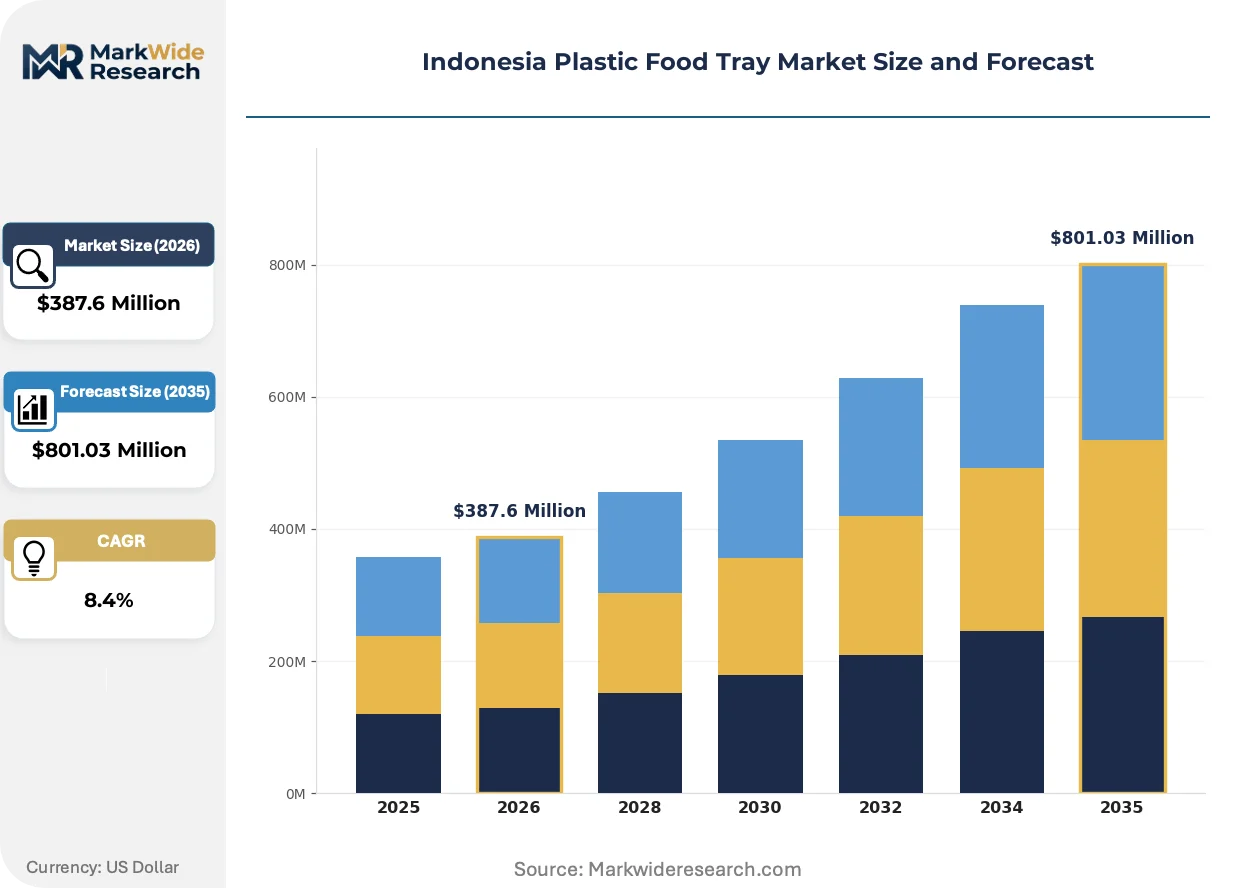
Market Dynamics
Indonesia's plastic food tray sector faces structural compression from the Ministry of Environment and Forestry's waste reduction roadmaps, which mandate recycled content thresholds and extended producer responsibility frameworks across Java, Bali, and Sulawesi.
Growth Catalysts
- Cloud kitchen proliferation:Quick-service restaurants and delivery-only kitchens across Greater Jakarta and Surabaya are expanding standardized tray procurement for meal kit packaging.
- Regulatory tailwinds:The National Plastic Action Partnership coordinates provincial EPR implementation, creating compliant market access for certified producers.
- Export certification demand:BPI and OK Compost standards gain traction among processors supplying EU and Japanese food importers.
Market Restraints
- Resin price volatility:Polypropylene feedstock costs fluctuate with naphtha cracking margins and import dependency on Singapore and South Korean suppliers.
- Technical limitation:Food-grade recycled PET flake supply remains insufficient for mass-scale tray production meeting BIS-equivalent Indonesian National Standards.
- Substitution threat:Molded fiber and bagasse alternatives capture premium quick-service contracts from sustainability-focused chains.
Strategic Opportunities
- Underpenetrated geography:Sulawesi and Kalimantan food processing corridors lack local thermoforming capacity, creating import substitution potential.
- Regulatory tailwind:Waste bank integration mandates in provincial regulations reward tray designs compatible with Indonesia's informal collection infrastructure.
- Technology convergence:In-mold labeling and barrier coating technologies enable premium ready-meal tray formats for modern retail channels.
Industry Challenges
- Certification timeline compression:Biodegradable tray variants require simultaneous BPI, OK Compost, and national food-contact approvals, extending product launch cycles.
- Capex intensity:Multi-layer extrusion and thermoforming lines for barrier-enhanced polypropylene demand significant upfront investment relative to commodity tray equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Plastic Food Tray Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Compartment, Multi-Compartment, Collapsible, Biodegradable Material: Polypropylene, Polystyrene, PVC, PET End User: Food Service, Retail, Catering, Household Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesalers |
| Companies Covered | PT Vacpack Indonesia, PT Solusi Prima Packaging, Amcor PLC, PT Dynapack Asia, PT Indopoly Swakarsa Industry, Sonoco Products Company, PT Gosyen Pacific Sukses Makmur, PT Amandina Bumi Nusantara, PT Thermopak Karya Indonesia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Plastic Food Tray Market Shifts & Advancements
Material science advances and regulatory compliance requirements are restructuring Indonesia's plastic food tray competitive landscape, favoring producers with integrated certification capabilities and domestic resin partnerships.
Barrier-coated polypropylene is integrating oxygen and moisture resistance into standard thermoformed trays without multi-layer coextrusion complexity. Ready-meal processors in Greater Jakarta are adopting these formats for chilled distribution to modern retail. The technology is integrating mid-tier producers into premium contract manufacturing previously dominated by regional multinationals.
Extended producer responsibility mandates from the Ministry of Environment and Forestry are compelling tray producers to fund waste bank collection systems proportionate to market share. This obligation is compressing margins for non-integrated molders while rewarding producers with captive recycling partnerships. Quick-service chains are responding by consolidating procurement among EPR-compliant suppliers.
Consolidated procurement contracts are displacing fragmented spot purchasing among Indonesian food manufacturers. Large quick-service chains now mandate annual volume commitments with penalty clauses for non-performance. This behavioral shift concentrates tray demand among five to seven dominant processors in Java's food manufacturing belt.
Indonesia Plastic Food Tray Market Segmentation
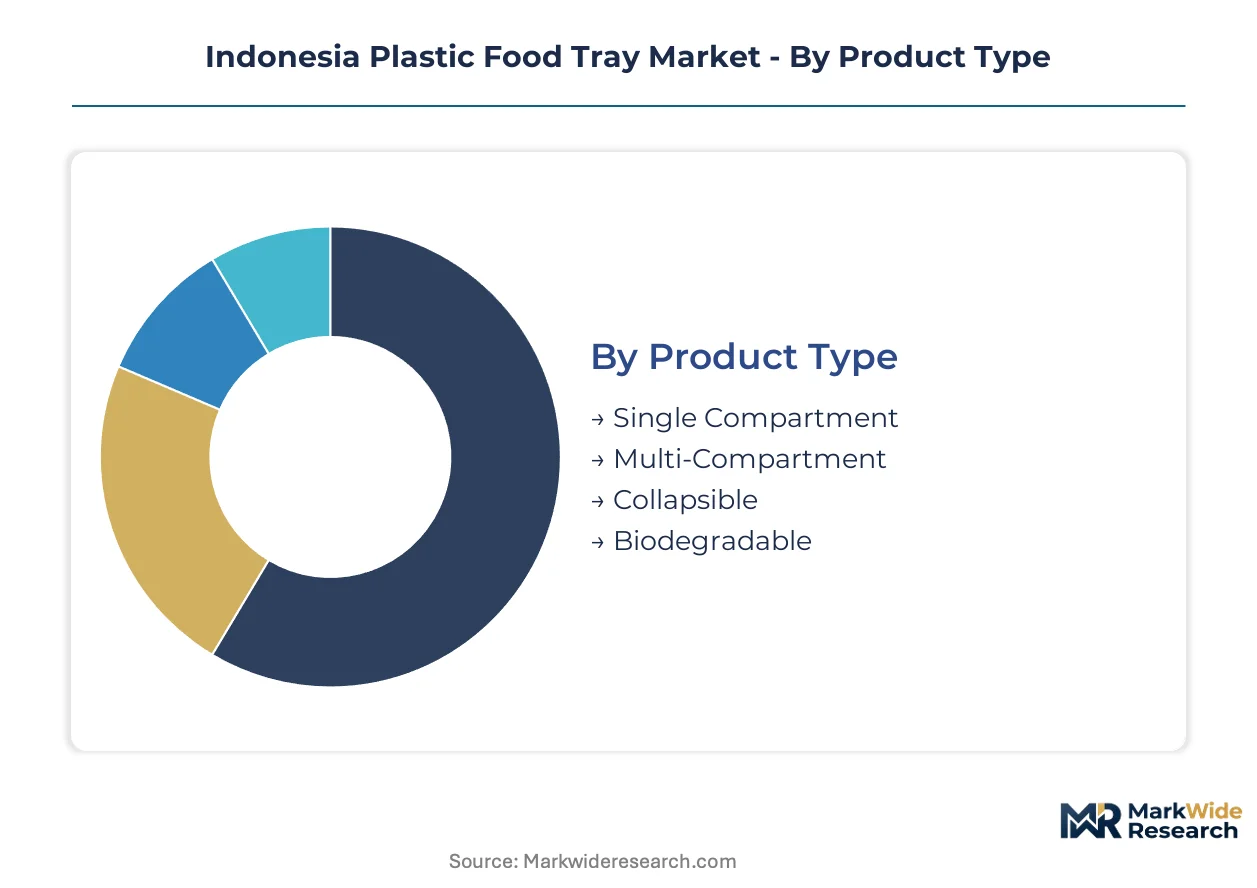
Indonesian plastic food tray procurement splits across four structural dimensions. Product geometry and material compliance determine unit economics for quick-service chains, while end-user channel dynamics reshape distribution infrastructure across Java and Sumatra.
Product Type:
Quick-service chains select tray geometry based on meal complexity and microwave compatibility requirements.
- Single Compartment:Standardized rectangular thermoformed containers dominate quick-service chicken and rice meal packaging across Greater Jakarta. Cloud kitchens in Surabaya's logistics corridor are consolidating procurement around this format for delivery-optimized portion control.
- Biodegradable:PLA and bagasse-composite trays carry BPI and OK Compost certifications required by export-oriented processors supplying EU and Japanese importers. The National Plastic Action Partnership's waste bank integration mandates are accelerating adoption among EPR-compliant suppliers.
- Multi-Compartment:Segmented designs separate proteins, starches, and sauces for premium ready-meal retail formats in modern trade channels.
- Collapsible:Space-efficient designs target catering and institutional food service with reduced storage footprint requirements.
Single compartment leads on scale; biodegradable leads on momentum.
Material:
Resin selection hinges on thermal performance, recycling infrastructure compatibility, and Ministry of Environment compliance thresholds.
- Polypropylene:Homopolymer and random copolymer grades provide microwave stability across minus twenty to one hundred twenty degrees Celsius, supporting Indonesia's dominant quick-service reheating protocols. Domestic resin partnerships with Chandra Asri and Polytama Propindo sustain cost-competitive supply for Java-based thermoformers.
- PET:Amorphous and crystalline grades deliver clarity for premium chilled ready-meal visibility in modern retail. Food-grade recycled flake supply constraints limit mass-scale production meeting BIS-equivalent Indonesian National Standards.
- Polystyrene:General-purpose and high-impact grades serve cost-sensitive institutional catering with limited heat-resistance requirements.
- PVC:Rigid formulations persist in specific barrier applications despite environmental scrutiny under Ministry of Environment roadmaps.
Polypropylene commands volume concentration; PET climbs fastest on premium channel expansion.
End User:
Channel-specific hygiene protocols and volume scale determine tray specification and procurement contract structure.
- Food Service:Quick-service restaurants and cloud kitchens across Greater Jakarta and Surabaya drive standardized polypropylene procurement with annual volume commitments and penalty clauses for non-performance.
- Retail:Modern trade channels in Jakarta's food processing corridor demand barrier-coated and in-mold labeled formats for chilled distribution shelf visibility.
- Catering:Institutional and event-based food service requires stackable, nestable designs with bulk logistics optimization.
- Household:Consumer-direct purchases through supermarkets and convenience stores favor multi-pack configurations with resealable features.
Food service dominates absolute volume; retail gains share fastest on modern trade penetration.
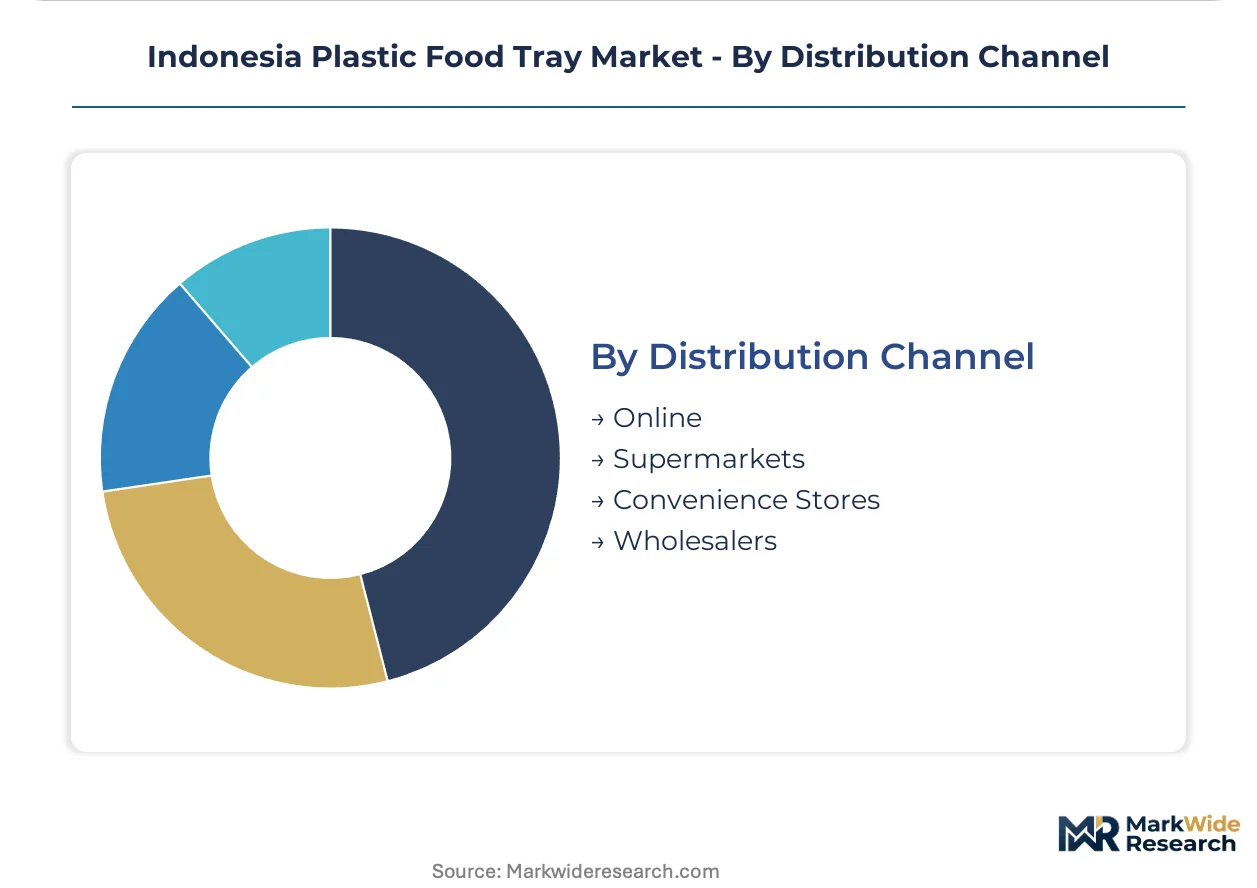
Distribution Channel:
Channel selection reflects buyer scale, geographic coverage requirements, and inventory turnover velocity.
- Wholesalers:Distributor networks across Java's food manufacturing belt aggregate fragmented quick-service demand into consolidated tray procurement pools. Surabaya's logistics hub serves as the primary consolidation point for eastern Indonesia distribution.
- Online:B2B platforms and direct manufacturer portals are displacing spot purchasing among mid-tier food processors in Sulawesi and Kalimantan underpenetrated by traditional distribution.
- Supermarkets:Modern retail chains in Greater Jakarta stock consumer-format tray multi-packs with household resealable specifications.
- Convenience Stores:Alfamart and Indomaret networks carry impulse-purchase single-unit formats for immediate-use household demand.
Wholesalers anchor volume concentration; online expands most quickly on geographic coverage gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Jakarta's food processing corridor concentrates Indonesia's plastic food tray demand, with Surabaya's logistics hub serving as the eastern distribution anchor. The Ministry of Environment and Forestry's waste reduction roadmaps are tightening compliance requirements across Java, Bali, and Sulawesi. Provincial EPR frameworks are reshaping where certified producers retain market access.
Java
Quick-service restaurants and cloud kitchens across Greater Jakarta and Bandung drive standardized polypropylene procurement with annual volume commitments. The National Plastic Action Partnership coordinates provincial waste bank integration mandates that reward EPR-compliant suppliers. Bekasi's manufacturing belt hosts captive thermoforming capacity serving KFC, McDonald's, and local chicken chains with microwave-stable tray formats.
Sumatra
Medan's palm oil processing corridor and Palembang's logistics nodes generate institutional catering demand for stackable, nestable tray designs. The Ministry of Environment and Forestry's recycled content thresholds apply uniformly across Sumatra's provincial jurisdictions. Batam's free trade zone imports premium PET tray formats for electronics industry canteens and export-oriented food processors.
Sulawesi
Makassar's emerging food processing corridor lacks local thermoforming capacity, creating import substitution potential for Java-based producers. Provincial governors implement extended producer responsibility frameworks with waste bank collection mandates proportionate to market share. Kendari's nickel processing workforce canteens drive bulk institutional procurement of cost-sensitive polystyrene formats.
Kalimantan
Balikpapan's oil and gas industry catering and Samarinda's mining workforce food service sustain demand for durable, reusable tray systems. The National Plastic Action Partnership's coordination with East Kalimantan's provincial administration lags Java's implementation timeline. Pontianak's border trade position enables Malaysian tray imports competing on price against domestic Java suppliers.
Bali
Tourism-dependent food service in Denpasar and Ubud is accelerating biodegradable tray adoption under provincial sustainability branding initiatives. The Ministry of Environment and Forestry's waste reduction roadmaps target Bali for early EPR implementation given its high-profile waste management challenges. Local processors pursue BPI and OK Compost certifications to supply international hotel chains with compostable meal packaging.
Indonesia Plastic Food Tray Market Competitive Landscape
Global majors compete with regional champions across certification capabilities and domestic resin partnerships. The vendor base structures around three tiers: multinational converters with Southeast Asian manufacturing footprints, integrated Indonesian processors with captive recycling partnerships, and commodity thermoformers serving spot-market institutional demand. Strategic differentiation centers on EPR compliance infrastructure and barrier coating technology licensing. Consolidated procurement contracts with penalty clauses are displacing fragmented spot purchasing among quick-service chains.
Within the integrated domestic tier, PT Solusi Prima Packaging and PT Dynapack Asia exemplify producers leveraging domestic resin partnerships and thermoforming-printing integration to secure chain restaurant contracts. Amcor PLC occupies a position among global converters anchoring premium PET supply through regional Southeast Asian manufacturing. PT Indopoly Swakarsa Industry represents the scale-driven commodity segment serving institutional catering and bulk logistics channels.
| Leading Market Players |
|---|
| PT Vacpack Indonesia |
| PT Solusi Prima Packaging |
| Amcor PLC |
| PT Dynapack Asia |
| PT Indopoly Swakarsa Industry |
| Sonoco Products Company |
| PT Gosyen Pacific Sukses Makmur |
| PT Amandina Bumi Nusantara |
| PT Thermopak Karya Indonesia |
| Others |
Supply & Pricing Matrix
Consolidated procurement contracts with penalty clauses among Greater Jakarta quick-service chains are compressing supplier margins and forcing thermoformers to absorb resin volatility or lose annual volume commitments. This buyer concentration is reshaping how Java-based producers structure pricing tiers and manage polypropylene feedstock exposure.
Pricing Analysis
Polypropylene naphtha-cracking margins from Singapore and South Korean suppliers pass through directly to tray unit economics, with domestic resin partnerships offering partial hedging. Three-tier pricing structure across premium barrier-coated, standard microwave-stable, and economy polystyrene levels separates EPR-compliant suppliers from commodity molders. Pricing pressure stems from waste bank integration mandates compressing margins for non-integrated producers. Quick-service chains demonstrate highest price sensitivity via consolidated annual tenders, while export-oriented processors accept premium tiers for BPI certification.
Supply Chain Analysis
Freight costs from Singapore and South Korean resin terminals to Java's thermoforming belt represent a structural cost layer that Sulawesi and Kalimantan buyers cannot escape without local capacity. Supply concentrates in Indonesia's domestic resin partnerships with Chandra Asri, regional Southeast Asian PET imports, and spot naphtha-derived polypropylene. Raw material dependencies center on propylene monomer, food-grade recycled PET flake, and thermoforming equipment components. Single-source vulnerability runs through Singapore-Jakarta shipping lanes. Distribution runs through Surabaya's logistics hub serving eastern Indonesia consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's plastic food tray market operates as a regulatory compounder where Ministry of Environment and Forestry waste reduction roadmaps are tightening compliance thresholds faster than supply can adapt. Extended producer responsibility implementation across Java, Bali, and Sulawesi is creating demand acceleration for certified producers with captive recycling infrastructure.
For Market Incumbents: Deploy barrier coating technology licensing to defend premium ready-meal contracts against regional multinational encroachment. Secure backward integration into domestic resin partnerships with Chandra Asri or Polytama Propindo to hedge naphtha import exposure. Consolidate waste bank collection infrastructure proportionate to market share before provincial EPR mandates harden.
For New Entrants and Emerging Players: Begin with Sulawesi and Kalimantan food processing corridors where local thermoforming capacity gaps create import substitution potential. Target Makassar's emerging processing belt with standardized polypropylene formats for institutional catering. Pursue BPI and OK Compost certification early to access EU and Japanese export channels before compliance timelines compress.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated Indonesian processors combining domestic resin partnerships with captive recycling and thermoforming-printing capabilities. Long-term viability favors EPR-compliant suppliers with waste bank infrastructure locked in across multiple provincial jurisdictions. Watch National Plastic Action Partnership coordination intensity with provincial governors as the inflection signal for compliance-driven consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Resin Supply | Chandra Asri partnerships reduce naphtha import exposure for Java thermoformers. |
| Barrier Coating Technology Licensing | Enables mid-tier producers to access premium ready-meal retail contracts. |
| Waste Bank Infrastructure Buildout | Ministry of Environment EPR mandates reward proportional collection system investment. |
| BPI and OK Compost Certification Investment | Unlocks EU and Japanese export channels for biodegradable tray variants. |
| Geographic Expansion to Sulawesi and Kalimantan | Import substitution potential in underpenetrated food processing corridors. |
Research Methodology
Multiple input streams — primary interviews with thermoforming plant managers, quick-service procurement leads, and Ministry of Environment regulatory officers; secondary validation through Indonesian National Standards documentation, customs trade data, and National Plastic Action Partnership coordination records; plus bottom-up and top-down triangulation — were reconciled to construct segment-level demand estimates.
Data-stream reconciliation across product geometry, material compliance thresholds, end-user channel dynamics, and provincial EPR implementation timelines anchored the analytical framework over the projection horizon. CAGRs were derived from volume-weighted segment trajectories incorporating cloud kitchen proliferation rates, recycled content mandate phase-in schedules, and export certification adoption curves.
Several conditions sit outside the modeled scope, including abrupt resin price shocks exceeding historical naphtha volatility bands, accelerated biodegradable material substitution beyond BPI adoption curves, and provincial EPR enforcement variance across Indonesia's archipelago governance structure. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic-Based Egg Packaging Market
Plastic Packaging
Plastic Sterilization Trays Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Indonesia Plastic Packaging Market
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market
Plastic Packaging
North America Single-Use Plastic Packaging Market
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Thermoformed Plastic Trays Market
Plastic Packaging
Europe Blow Molded Plastic Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
Blow Molded Plastics Market
Plastic Packaging
Plastic Ready Meal Trays Market